
 Forklift Battery Charger Market | 2026-2036
Forklift Battery Charger Market Size, Share, and Industry Trends Forecast 2026-2036
Forklift Battery Charger Market Foresight
Chinese charger manufacturing capacity is decoupling from European assembly demand as regional supply chains harden. Exide Technologies leverages its integrated battery-charger ecosystem to dominate North American aftermarket service. Fronius International GmbH sustains premium positioning through welding-to-charging technology cross-pollination. Delta-Q Technologies specializes in compact onboard charger architectures for electric forklift OEMs.
A forklift battery charger is an electrical power conversion device that transforms grid alternating current into direct current at voltages typically spanning 24V to 80V, with output currents calibrated to specific battery chemistries and thermal profiles. Its primary industrial purpose is to restore energy storage capacity in motive power batteries while minimizing downtime, electrolyte degradation, and thermal runaway risk in multi-shift warehouse and manufacturing environments. Fast charger deployment is accelerating in third-party logistics operations where two-shift and three-shift models compress available charging windows. Lithium-ion technology segments command margin concentration due to precision charging protocols and battery management system integration requirements. Lead acid charger demand remains structurally embedded in wholesale distribution and heavy equipment rental fleets where capital replacement cycles extend across seven to ten years.
OSHA electrical safety standards and EPA stationary source emissions frameworks directly shape charger installation specifications and facility compliance costs in the United States. CE marking under EU machinery directives and REACH substance restrictions govern product market access across European member states, with ECHA scrutiny intensifying on power electronics solder and coating chemistries. Stakeholders must monitor how IEC 62485 safety standards for secondary batteries and chargers evolve to accommodate solid-state and zinc-air chemistry interfaces.
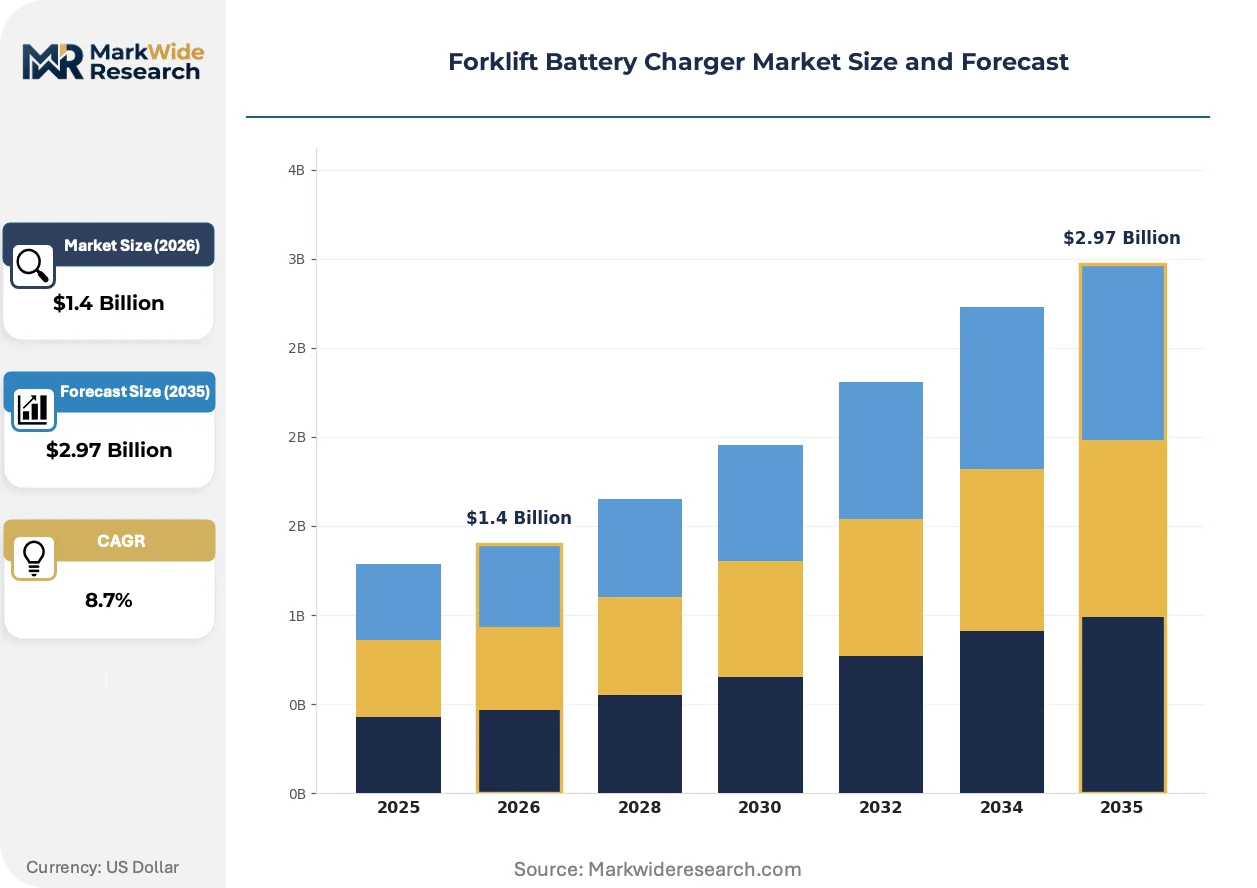
Market Dynamics
Fleet electrification mandates are compressing charger deployment timelines across third-party logistics and manufacturing operations, forcing infrastructure decisions ahead of full battery fleet turnover.
Growth Catalysts
- OSHA electrical safety mandates:Workplace safety standards for material handling equipment are mandating charger installation protocols that accelerate replacement of legacy unregulated systems in United States distribution centers.
- Lithium-ion precision protocols:Battery management system integration requirements for motive power applications are creating specialized charger demand segments with higher technical barriers to entry.
- German intralogistics investment:Industrial automation spending in Baden-Württemberg and Bavaria manufacturing clusters is sustaining premium charger procurement volumes despite broader European industrial headwinds.
Market Restraints
- Copper and silicon carbide input volatility:Power semiconductor and magnetics material costs are creating margin compression for charger manufacturers without captive component supply.
- Chinese manufacturing concentration:Regional supply chain hardening is decoupling Asian production capacity from European assembly demand, creating availability friction for just-in-time procurement models.
- Lead-acid capital lock-in:Seven-to-ten year replacement cycles in wholesale distribution fleets are structurally embedding legacy charger architectures and delaying lithium-ion infrastructure conversion.
Strategic Opportunities
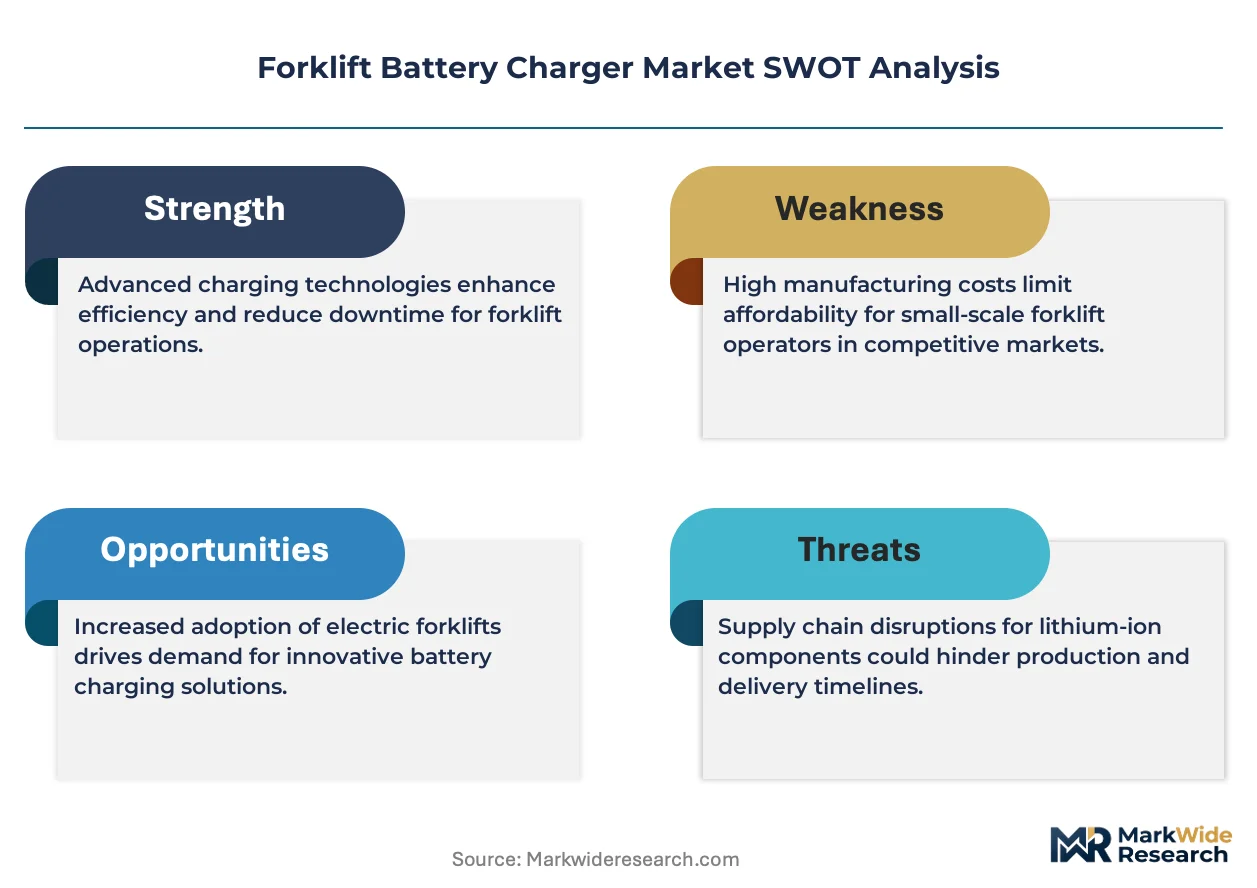
- Fast-charger white space in multi-shift operations:Two-shift and three-shift compression models in United States third-party logistics are creating demand for opportunity charging systems that bypass traditional battery swap workflows.
- Onboard compact architectures:Electric forklift OEM integration partnerships for space-constrained industrial vehicle designs are opening charger specification influence at the platform development stage.
- CE marking under EU machinery directives:REACH substance restrictions on power electronics solder and coating chemistries are creating compliance-based differentiation for European-certified manufacturers.
Industry Challenges
- IEC 62485 safety standard evolution:Secondary battery and charger interface specifications for emerging solid-state and zinc-air chemistries are creating certification timeline uncertainty for product roadmaps.
- Thermal runaway mitigation engineering:Multi-shift warehouse environments require charger architectures that manage electrolyte degradation risks across variable duty cycles without supervised intervention.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Forklift Battery Charger Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fast Charger, Slow Charger, Modular Charger, Onboard Charger, Offboard Charger Technology: Lead Acid, Lithium-Ion, Nickel-Metal Hydride, Solid State, Zinc-Air Application: Warehouse Operations, Manufacturing Plants, Logistics Centers, Maritime Yards, Construction Sites End User: Third-Party Logistics, Wholesale Distribution, Retail Fulfillment, Heavy Equipment Rental, Port Authorities |
| Companies Covered | Exide Technologies, ElCon Chargers, Delta-Q Technologies, Advanced Charging Technologies, PosiCharge, Jungheinrich AG, Fronius International GmbH, Power Designers, Crown Equipment Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Forklift Battery Charger Market Shifts & Advancements
Intelligent charging algorithms and embedded diagnostics are displacing passive timer-based systems across motive power applications, compressing the technical differentiation window between established and emerging suppliers.
Adaptive charging software with real-time impedance monitoring is automating current modulation decisions previously requiring manual technician intervention. Third-party logistics operators in high-throughput distribution hubs are adopting these systems at twelve-to-eighteen month refresh cycles. The technology is automating battery state-of-health prediction and compressing warranty claim exposure for fleet operators managing heterogeneous battery ages.
EPA stationary source emissions frameworks are tightening facility-level compliance specifications for charger installation and electrical infrastructure upgrades. Industrial facilities in California and Texas manufacturing corridors are absorbing incremental capital costs for ventilation and electrical isolation systems. Heavy equipment rental fleets with national footprints are standardizing on EPA-compliant charger architectures to simplify cross-state deployment logistics.
Service contract unbundling is separating charger hardware procurement from aftermarket maintenance agreements. Wholesale distribution buyers are negotiating direct OEM relationships for replacement units while sourcing technical service through independent electrical contractors. This pattern is most visible in Midwest United States manufacturing belts where legacy distributor relationships face price transparency pressure from direct digital channels.
Forklift Battery Charger Market Segmentation
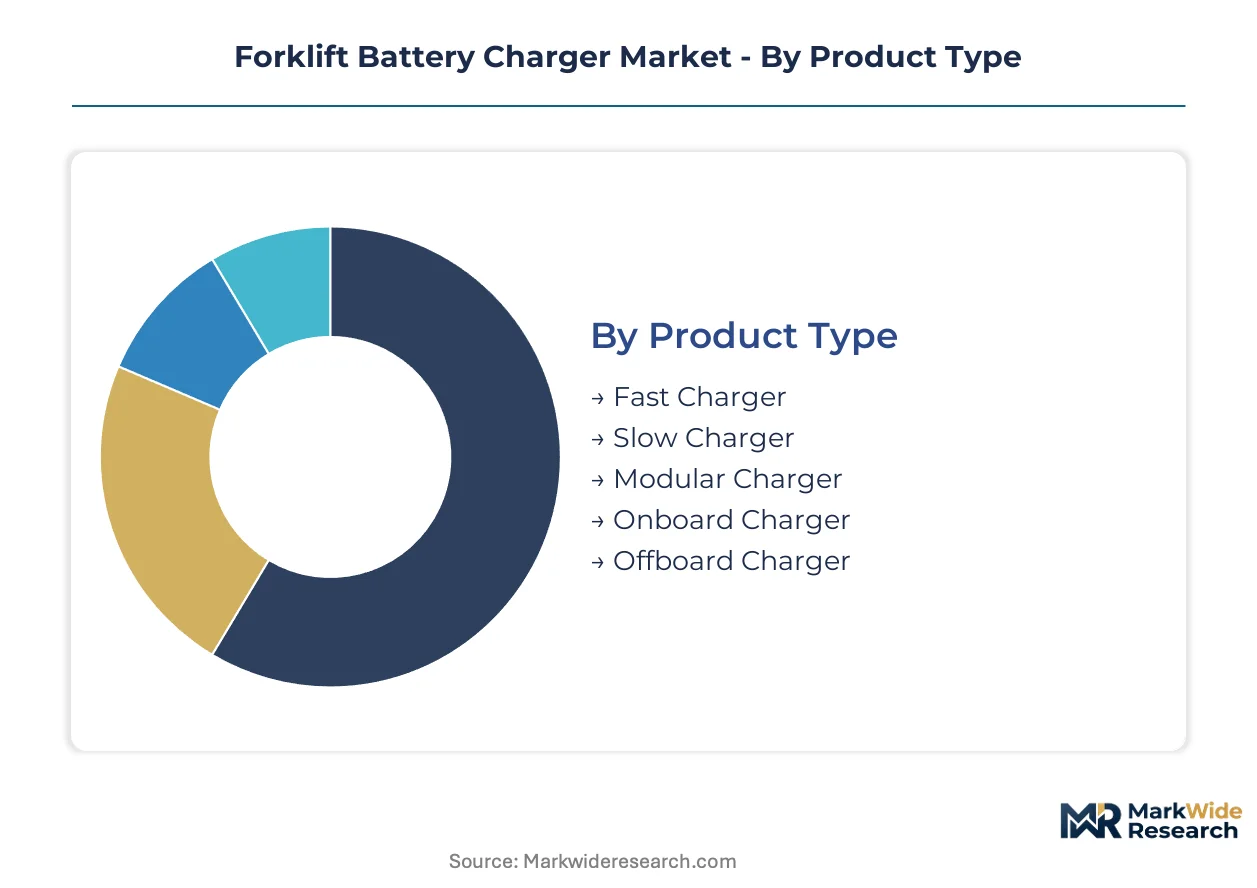
Charger specification diversity reflects the tension between standardized fleet procurement and site-specific power infrastructure constraints. Segmentation reveals where technical customization commands premium positioning versus where commodity architectures dominate procurement decisions.
Product Type:
Standardization pressure intensifies as fleet operators consolidate procurement specifications, yet installation environments demand customized power delivery profiles and mounting configurations.
- Fast Charger:High-amperage output systems compress charging windows to 15-30 minutes for opportunity charging during shift breaks. Demand concentrates in United States third-party logistics hubs where two-shift compression eliminates traditional battery swap workflows. OSHA electrical isolation mandates are accelerating replacement of legacy unregulated fast-charging installations.
- Slow Charger:Extended-duration systems deliver 6-8 hour full charge cycles optimized for overnight fleet parking. Wholesale distribution operations in Germany's Baden-Württemberg manufacturing belt favor these architectures for their thermal stability and minimal battery degradation over seven-to-ten year capital cycles.
- Modular Charger:Scalable rack-mounted configurations allow capacity expansion without full system replacement. Port authorities in Hamburg and Rotterdam deploy these for phased electrification of container handling fleets.
- Onboard Charger:Space-constrained integration directly into electric forklift platforms eliminates external charging infrastructure. OEM specification influence at the vehicle development stage creates technical barrier differentiation.
- Offboard Charger:Stationary rack systems serve centralized fleet depots with standardized voltage outputs. Heavy equipment rental fleets standardize on these architectures for cross-state deployment compatibility.
Most installed capacity flows through Slow Charger architectures. Expansion is steepest in Fast Charger systems.
Technology:
Margin concentration tracks chemistry-specific precision requirements, with battery management system integration complexity creating tiered competitive positioning.
- Lead Acid:Established flooded and sealed battery chemistries require temperature-compensated charging curves and electrolyte monitoring. Wholesale distribution and rental fleet capital lock-in sustains structural demand despite efficiency disadvantages.
- Lithium-Ion:NMC and LFP cell formats demand milliamp-level current precision and active thermal management integration. Precision protocol requirements create specialized charger segments with elevated technical barriers to entry.
- Nickel-Metal Hydride:Legacy chemistry persists in niche applications requiring memory-effect mitigation charging profiles. Japanese manufacturing facilities maintain limited procurement volumes for specialized material handling equipment.
- Solid State:Emerging ceramic electrolyte interfaces require voltage protocol adaptation ahead of commercial volume deployment. IEC 62485 standard evolution timeline uncertainty constrains product roadmap commitments.
- Zinc-Air:Metal-air chemistry charging mechanisms involve electrolyte regeneration rather than direct electron transfer. ECHA scrutiny on power electronics solder chemistries affects charger design for experimental pilot programs.
Lead Acid technology retains the largest installed base. Lithium-Ion represents the fastest-growing trajectory.
Application:
Site-specific duty cycle intensity and shift compression patterns determine charger specification tiering across industrial environments.
- Warehouse Operations:High-rack distribution centers with 24/7 fulfillment schedules demand opportunity charging infrastructure. California and Texas logistics corridors absorb incremental capital costs for EPA-compliant electrical isolation systems.
- Manufacturing Plants:Just-in-time production lines synchronize charging windows with shift schedules. Bavarian automotive supplier clusters sustain premium charger procurement despite broader European industrial headwinds.
- Logistics Centers:Cross-dock facilities with high equipment utilization rates prioritize fast-charger deployment to minimize battery inventory. Third-party logistics operators refresh charging infrastructure at twelve-to-eighteen month cycles.
- Maritime Yards:Corrosive coastal environments require sealed NEMA-rated charger enclosures. Port authorities in Long Beach and Savannah specify salt-spray-resistant architectures for container handling electrification.
- Construction Sites:Temporary power availability and mobile equipment patterns favor portable charger configurations. Rental fleet standardization simplifies deployment logistics across state regulatory variations.
Warehouse Operations absorb the majority of current installations. Logistics Centers are gaining share fastest.
End User:
Procurement authority centralization versus distributed site management creates divergent specification and service contract structures.
- Third-Party Logistics:National operators with multi-facility footprints standardize on fast-charger architectures to enable labor model flexibility. Service contract unbundling separates hardware procurement from independent electrical contractor maintenance agreements.
- Wholesale Distribution:Capital replacement cycles extending seven-to-ten years structurally embed legacy charger architectures. Midwest United States manufacturing belts face price transparency pressure from direct digital channels.
- Retail Fulfillment:E-commerce volume volatility demands scalable charging infrastructure with rapid capacity modulation. Intelligent charging algorithms with real-time impedance monitoring automate battery state-of-health prediction.
- Heavy Equipment Rental:National footprint operators prioritize EPA-compliant standardization for cross-state deployment. Stationary source emissions frameworks tighten facility-level compliance specifications.
- Port Authorities:Public procurement processes with extended evaluation timelines favor established CE-marked European suppliers. REACH substance restrictions on power electronics solder create compliance-based differentiation.
Wholesale Distribution maintains the largest installed base. Third-Party Logistics shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as manufacturers migrate toward jurisdictions with streamlined compliance frameworks. Cost-of-compliance gaps between REACH-heavy European enforcement and EPA-aligned North American standards are accelerating facility relocation decisions.
United States
OSHA electrical safety mandates and EPA stationary source emissions frameworks are tightening facility-level charger installation specifications. Third-party logistics operators in California and Texas logistics corridors absorb incremental capital costs for ventilation and electrical isolation systems. Midwest manufacturing belts face price transparency pressure as wholesale distribution buyers negotiate direct OEM relationships.
Germany
CE marking under EU machinery directives and ECHA scrutiny on power electronics solder chemistries govern product market access. Industrial automation spending in Baden-Württemberg and Bavaria manufacturing clusters sustains premium charger procurement volumes. REACH substance restrictions create compliance-based differentiation for European-certified manufacturers.
China
Manufacturing capacity is decoupling from European assembly demand as regional supply chains harden under dual carbon goals and MIIT industrial policy. GB standards and SAMR market supervision frameworks shape domestic product specifications. Yangtze River Delta production clusters face availability friction for just-in-time European procurement models.
Japan
METI energy efficiency standards and JIS technical specifications drive charger performance benchmarking for motive power applications. Legacy nickel-metal hydride chemistry persists in specialized material handling equipment at manufacturing facilities. Kansai industrial corridors maintain limited procurement volumes for niche battery formats.
Netherlands
Port authorities in Rotterdam deploy modular charger configurations for phased electrification of container handling fleets. EU Green Deal alignment pressures accelerate infrastructure investment timelines. Randstad logistics hubs concentrate demand for scalable charging architectures serving multi-shift warehouse operations.
Forklift Battery Charger Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue onboard integration partnerships with electric forklift OEMs. The vendor base separates into welding-technology cross-pollinators, integrated battery-charger ecosystem operators, and compact architecture specialists. Three archetypes dominate: diversified industrial conglomerates with captive motive power divisions, pure-play charging equipment fabricators, and battery manufacturers extending into adjacent power conversion. Strategic moves concentrate on M&A for regional compliance certification and capacity expansion near port logistics clusters.
Among integrated ecosystem operators, Exide Technologies anchors the North American aftermarket service tier through its battery-charger combined presence. Fronius International GmbH exemplifies the welding-to-charging technology cross-pollination archetype within European premium positioning. Delta-Q Technologies occupies the compact onboard charger specialization vector for electric forklift OEM integration partnerships.
| Leading Market Players |
|---|
| Exide Technologies |
| ElCon Chargers |
| Delta-Q Technologies |
| Advanced Charging Technologies |
| PosiCharge |
| Jungheinrich AG |
| Fronius International GmbH |
| Power Designers |
| Crown Equipment Corporation |
| Others |
Supply & Pricing Matrix
Lithium-ion battery management system integration is simultaneously elevating charger precision requirements and concentrating production among suppliers with captive semiconductor capabilities. This technology shift compresses margins for legacy lead-acid charger producers while rewarding manufacturers with in-house power electronics expertise.
Pricing Analysis
Distributor margins in the forklift battery charger market compress pricing transparency for wholesale distribution buyers negotiating direct OEM relationships. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with CE-marked and UL-listed units commanding substantial premiums over unregulated alternatives. Pricing pressure stems from copper and silicon carbide input volatility eroding manufacturer margins without captive component supply. Third-party logistics operators exhibit lowest price sensitivity due to fast-charger deployment timelines compressing procurement evaluation cycles, while heavy equipment rental fleets prioritize cross-state deployment compatibility over unit cost.
Supply Chain Analysis
Power semiconductor supply rests on Taiwanese foundry capacity and Chinese rare earth processing infrastructure for magnetics components. Raw material dependencies center on copper winding stock, silicon carbide wafers, and epoxy resin systems for thermal management enclosures. Single-source vulnerability concentrates in advanced MOSFET and IGBT modules where European and North American assembly operations draw from limited qualified suppliers. Distribution runs through regional electrical distributors serving industrial maintenance channels, with direct OEM partnerships bypassing traditional wholesale tiers for onboard charger architectures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The forklift battery charger market offers margin expansion through lithium-ion precision protocol specialization and fast-charger premium positioning. Cost compression in legacy lead-acid segments accelerates tier consolidation.
For Market Incumbents: Cement aftermarket service lock-in through integrated battery-charger ecosystem offerings that complicate disintermediation by independent electrical contractors. Extend backward integration into power semiconductor sourcing to defend margin position against silicon carbide input volatility. Prioritize IEC 62485 certification investment ahead of solid-state chemistry commercialization to capture emerging protocol standards. For New Entrants and Emerging Players: Begin with onboard compact charger architectures for electric forklift OEM specification influence at platform development stages. Target third-party logistics fast-charger white space in California and Texas logistics corridors where two-shift compression eliminates traditional battery swap workflows. Pursue direct digital channel penetration in Midwest wholesale distribution belts facing price transparency pressure from legacy distributor relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play charging equipment fabricators without integrated battery manufacturing or welding-technology cross-pollination. Long-term viability favors acquisition targets with CE marking compliance and REACH substance restriction adherence for European market access. Monitor ECHA scrutiny intensity on power electronics solder chemistries as inflection indicator for compliance-based competitive differentiation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Power Semiconductors | Captive silicon carbide sourcing insulates margins from Taiwan foundry concentration risk. |
| Fast-Charger Certification Investment | OSHA electrical isolation compliance accelerates replacement of legacy unregulated installations. |
| OEM Platform Integration Partnership | Onboard charger specification influence at vehicle development stage creates technical barriers. |
| European CE Marking Pathway | REACH substance restriction adherence creates compliance-based differentiation against Asian imports. |
| Aftermarket Service Unbundling | Direct hardware procurement relationships bypass legacy distributor markups in wholesale distribution. |
Research Methodology
Multiple input streams — OEM procurement director interviews, aftermarket service head discussions, and regulatory affairs lead consultations — were reconciled against customs trade data, SEC equipment manufacturer filings, and OSHA compliance documentation. Secondary validation drew from ECHA substance restriction databases, EPA stationary source emissions frameworks, and IEC technical committee proceedings. Bottom-up installation volume estimates and top-down industrial capital expenditure patterns were triangulated to anchor market sizing.
Data-stream reconciliation across product type, battery chemistry, end-user procurement authority, and regional regulatory cluster dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth trajectory modeling incorporating fleet electrification mandate timelines and lithium-ion conversion rate assumptions. Charger specification evolution and power semiconductor supply availability served as industry-specific forecast sensitivity inputs.
Several conditions sit outside the modeled scope, including speculative solid-state and zinc-air chemistry commercialization timelines, abrupt tariff restructuring affecting Chinese manufacturing access, and unforeseen IEC 62485 standard revision scope. Forecasts reflect documented assumptions regarding OSHA enforcement intensity and EPA emissions framework stability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Global Lithium Titanate (LTO) Batteries Market
Batteries
Global Industrial Lead Acid Battery Market
Batteries
Asia-Pacific Rechargeable Battery Market
Batteries
AAA Battery Market
Batteries
Molten Salt Battery Market
Batteries
Middle East and Africa SLI Battery Market
Batteries
Flow Battery Market
Batteries
East Africa Battery Market
Batteries
Aluminum Based Battery Market
Batteries
Battery Swapping Market
Batteries
Bio Based Battery Market
Batteries
South Asia Battery Market
Batteries
Global Automotive Lead Acid Batteries Market
Batteries
Iron Flow Battery Market
Batteries
Battery Simulator Market
Batteries
Netherlands Rechargeable Battery Market