
 Global Coke Oven Batteries Market | 2026-2036
Global Coke Oven Batteries Market Size, Share, and Industry Trends Forecast 2026-2036
Global Coke Oven Batteries Market Intelligence
The substitution of conventional fireclay refractories with high-purity silica bricks is rebalancing the lifetime economics of coke oven battery construction and maintenance. This shift favors suppliers with advanced material science capabilities. Thyssenkrupp AG leverages its integrated engineering and construction expertise to deliver turnkey plants. Paul Wurth specializes in designing high-efficiency coke oven components and systems that improve energy recovery.
A coke oven battery is an array of chambers used to carbonize coal at temperatures exceeding 1,100°C without combustion, producing metallurgical coke. Its primary industrial purpose is to supply high-carbon fuel and reducing agents for blast furnaces in integrated steel mills. By-product recovery technology dominates the installed base, capturing valuable chemicals and gas for other processes. Steel manufacturing remains the principal application, consuming the vast majority of metallurgical coke produced globally.
Stringent air quality standards from regulators like the US EPA and China's MEE mandate advanced emission control systems on new and existing batteries. In Europe, the EU Green Deal's focus on industrial decarbonization pressures operators to improve energy efficiency and explore alternative technologies. Stakeholders must now decide how to allocate capital between retrofitting legacy assets for compliance and investing in next-generation, lower-emission cokemaking technologies.
Market Dynamics
The central structural force shaping the coke oven battery market is the global steel industry's response to decarbonization mandates. Environmental regulations from authorities like China's MEE are compelling a shift toward higher-efficiency technologies and cleaner production clusters.
Growth Catalysts
- Steel Capacity Expansion:Surging steel production targets in India are creating sustained demand for new, large-scale coke oven batteries to feed an expanding fleet of blast furnaces.
- Regulatory Modernization Mandates:China's dual carbon goals and associated environmental policies are forcing the closure of older, inefficient coke plants, thereby stimulating investment in modern replacement capacity with superior emission controls.
- Advanced Refractory Materials:The adoption of high-purity silica bricks over traditional fireclay extends battery lifespan and improves thermal efficiency, making new construction and major rebuilds more economically attractive for operators.
Market Restraints
- High Capital Investment:The immense upfront cost required to construct a new coke oven battery or to execute a comprehensive rebuild of an existing one acts as a significant barrier to entry and investment.
- Alternative Ironmaking Technologies:Long-term development of hydrogen-based direct reduced iron (H-DRI) and other low-carbon steelmaking processes presents a fundamental substitution threat to the coke-dependent blast furnace route.
- Stringent Emission Standards:Complying with rigorous air quality regulations, such as those from the US EPA, imposes substantial operational costs for monitoring and abatement, restraining the profitability of legacy assets.
Strategic Opportunities
- Next-Generation Cokemaking:Investing in the development and commercialization of innovative, lower-emission technologies, such as non-recovery or advanced heat-recovery systems, offers a path to meet future environmental standards.
- Modernization and Retrofitting Services:A significant market exists for specialized engineering services focused on upgrading existing batteries with modern automation, emission controls, and energy recovery systems to extend asset life.
- By-Product Value Enhancement:Developing more sophisticated by-product recovery plants that can capture and refine a wider array of valuable chemicals provides an ancillary revenue stream and improves overall plant economics.
Industry Challenges
- Capital Allocation Dilemma:Steel producers face a critical strategic challenge in deciding whether to allocate capital toward retrofitting existing coke batteries for compliance or to invest in next-generation, but less proven, technologies.
- Specialized Skill Shortages:The industry confronts a scarcity of engineers and technicians with the requisite expertise in modern coke oven design, refractory engineering, and advanced environmental control systems.
- Legacy System Integration:Integrating new digital control systems and emission abatement equipment with aging mechanical and structural components in existing coke plants presents significant technical and operational complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Coke Oven Batteries Market |
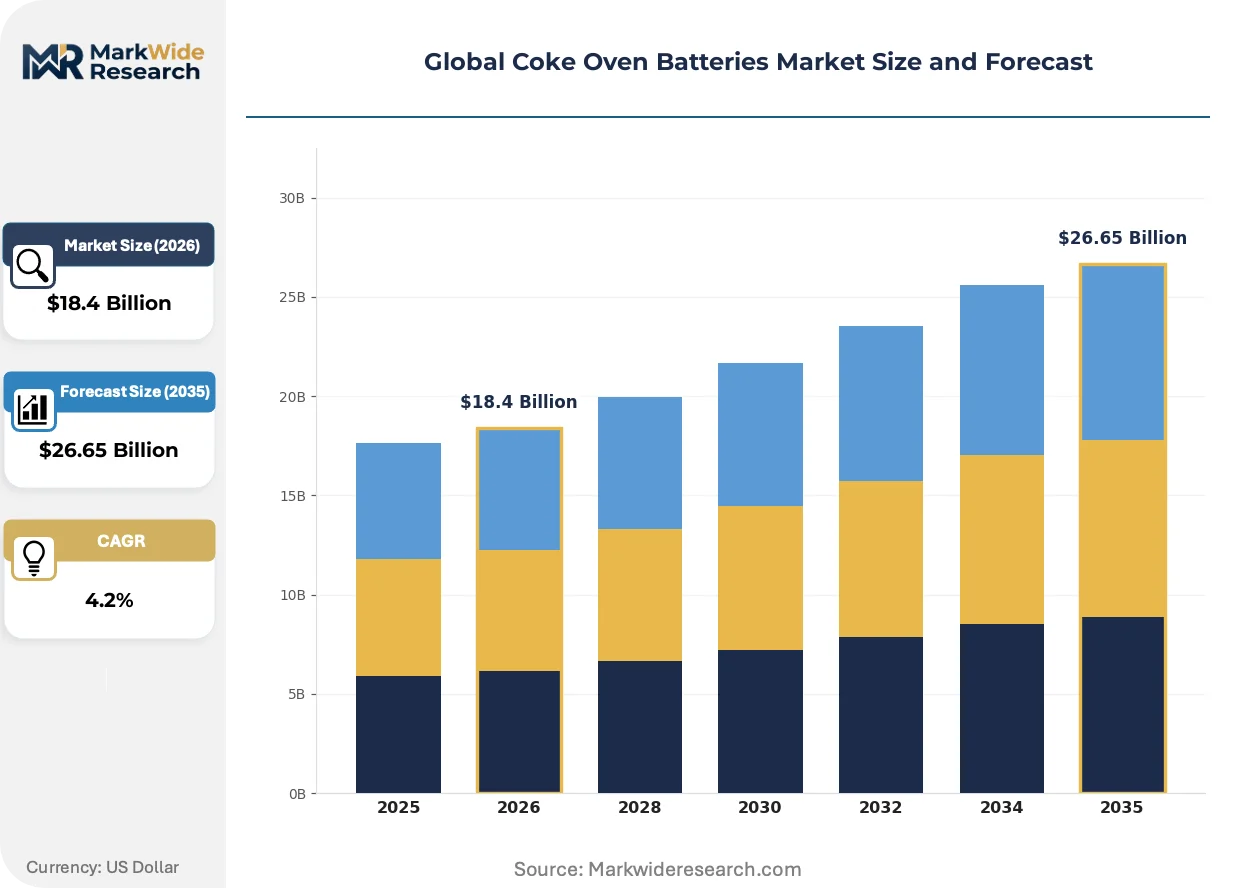
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $26.65 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: By-product Recovery, Heat Recovery, Industrial Grade, Carbonization, Semi-coke Production Technology: Byproduct Coke Oven, Stamp Charging, Non-recovery, Beehive Oven, Bunker Oven Application: Steel Manufacturing, Foundries, Chemical Synthesis, Power Generation, Metallurgical Processing End User: Steel Manufacturers, Foundry Units, Chemical Plants, Power Producers, Metallurgical Facilities |
| Companies Covered | Paul Wurth, Thyssenkrupp AG, GIPROKOKS, Graycor International Inc., Heavy Engineering Corporation Ltd., ArcelorMittal, POSCO, Danieli Corus, Ingeteam Power Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Coke Oven Batteries Market Strategic Shifts & Innovations
Operational imperatives now center on balancing stringent environmental compliance with the economic need for higher thermal efficiency and longer asset lifespans. This dynamic is driving innovation in material science, process control, and plant design to meet the dual demands of regulators and steel producers.
Advanced refractory materials, particularly high-purity silica bricks, provide superior thermal conductivity and resistance to chemical corrosion at extreme temperatures. Steel manufacturers in India and China are specifying these materials for new battery constructions and major rebuilds to maximize operational uptime. The adoption of these superior materials is consolidating the competitive landscape around suppliers with deep material science and engineering capabilities.
European Union climate policy, notably the EU Green Deal, is forcing a strategic reevaluation of industrial carbon footprints. This framework pressures steelmakers to significantly improve the energy efficiency of cokemaking operations or invest in alternative iron production technologies to meet decarbonization targets. Operators of older, less efficient batteries across the continent are most affected, facing difficult decisions on capital-intensive retrofits versus accelerated plant closures.
Demand patterns show a clear preference for integrated, turnkey plant solutions over piecemeal component procurement. This shift disrupts the traditional model where steel producers managed multiple contractors for design, equipment supply, and construction. The turnkey approach is most prominent in large-scale greenfield projects in Asia, where single-point accountability for project timelines and performance guarantees is a critical factor for investors.
Global Coke Oven Batteries Market Segmentation
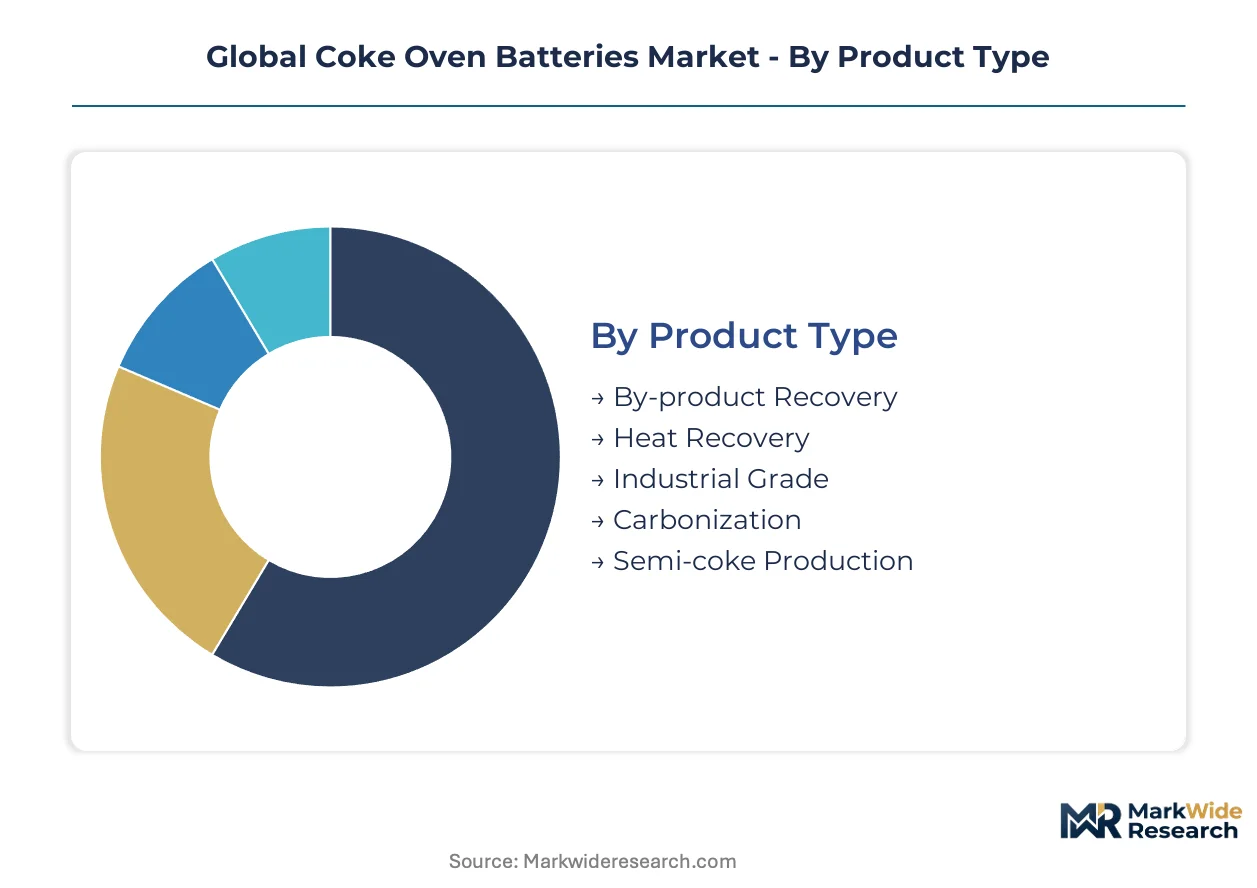
The global coke oven batteries market segments reflect distinct operational profiles and investment requirements within the steel and related industries. Understanding these differentiations is critical for stakeholders assessing capital expenditure and long-term strategic positioning. Each segment addresses specific industrial needs for metallurgical coke production or chemical recovery processes.
Product Type:
The capital intensity of coke oven battery installations varies significantly across product types, with large-scale by-product recovery systems demanding the highest upfront investment.
- By-product Recovery:These batteries carbonize coal to produce coke while capturing valuable gases and chemicals like tar, ammonia, and light oil. Demand concentrates in integrated steel mills in India and China, driven by the economic value of recovered chemicals and energy.
- Heat Recovery:These systems capture waste heat from the coking process for power generation or other industrial uses, prioritizing energy efficiency over chemical recovery. Investment increases in Europe due to EU Green Deal mandates for industrial decarbonization.
- Industrial Grade:These batteries produce coke primarily for non-metallurgical applications, including various industrial processes requiring carbon.
- Carbonization:This segment focuses on the fundamental process of converting coal into coke through high-temperature heating in oxygen-limited environments.
- Semi-coke Production:These facilities produce a lower-quality coke, often used as a reducing agent in ferroalloy production or as a fuel.
Most installed capacity flows through By-product Recovery systems. Expansion is steepest in Heat Recovery technologies.
Technology:
Technological choices in cokemaking are increasingly influenced by environmental regulations and the need for higher energy efficiency.
- Byproduct Coke Oven:These conventional ovens are designed to recover valuable chemical byproducts alongside metallurgical coke. Demand remains strong in steel-producing regions like India due to established infrastructure and economic returns from by-product sales.
- Non-recovery:These ovens operate without by-product recovery, instead incinerating coking gases to generate heat, offering a simpler design and lower emissions profile. Investment is growing in regions with stringent air quality standards, such as the US and parts of China.
- Stamp Charging:This method involves compacting coal charges before loading, improving coke quality and increasing oven productivity.
- Beehive Oven:These older, less efficient ovens are characterized by their simple design and lack of by-product recovery or emission controls.
- Bunker Oven:These ovens represent an older, less common coking technology, typically with limited environmental controls and lower efficiency.
Byproduct Coke Oven technology holds the largest share of operational capacity. Non-recovery technology drives innovation in emission reduction.
Application:
Demand for coke oven batteries is overwhelmingly concentrated in applications requiring high-carbon fuel and reducing agents.
- Steel Manufacturing:This application consumes the vast majority of metallurgical coke produced globally, serving as a critical input for blast furnaces in integrated steel mills. Demand surges in India and China, reflecting significant steel capacity expansion.
- Metallurgical Processing:This broad application includes the use of coke as a reducing agent or fuel in processes beyond primary steelmaking, such as ferroalloy production and non-ferrous metal smelting. Growth occurs in specialized industrial clusters across Asia.
- Foundries:Foundries utilize coke as a fuel and carbon source in cupola furnaces for casting various metal products.
- Chemical Synthesis:Coke oven by-products, rather than coke itself, are crucial feedstocks for synthesizing various industrial chemicals and plastics.
- Power Generation:Coke oven gas, a by-product of coke production, is combusted to generate electricity, improving the energy efficiency of integrated plants.
Steel Manufacturing generates the dominant revenue share for coke oven battery operators. Metallurgical Processing shows consistent demand from diverse industrial needs.
End User:
The end-user landscape for coke oven batteries is defined by large industrial entities with substantial capital investment capabilities.
- Steel Manufacturers:These companies operate integrated steel mills, relying on coke oven batteries to produce metallurgical coke essential for blast furnace operations. Major investments originate from large steel groups in China and India, driven by production targets.
- Chemical Plants:While not primary coke consumers, these facilities utilize the valuable by-products recovered from coke oven batteries as feedstocks for chemical synthesis. Demand for by-product recovery systems is influenced by petrochemical market dynamics.
- Foundry Units:These industrial facilities purchase coke for use in cupola furnaces to melt and cast metals for various components.
- Power Producers:Some power generation companies or integrated industrial complexes utilize coke oven gas as a fuel source for electricity production.
- Metallurgical Facilities:This segment encompasses diverse operations, including ferroalloy producers and non-ferrous metal smelters, which use coke as a reducing agent.
Steel Manufacturers represent the core strategic segment for coke oven battery suppliers. Chemical Plants prioritize the efficiency of by-product recovery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial clusters in India and China are anchoring the global demand for new coke oven batteries, driven by robust steel production targets. Environmental regulations across various regions also compel significant investment in modern, efficient capacity. This reconfigures capital allocation decisions for steel manufacturers worldwide.
China
China's dual carbon goals are compelling investment in modern coke oven technologies to replace older, inefficient plants. The Ministry of Ecology and Environment (MEE) mandates stringent emission controls for new and retrofitted facilities. Steel-intensive regions like Hebei and the Yangtze River Delta are seeing concentrated investment in advanced cokemaking.
India
Surging steel production targets in India drive consistent demand for large-scale coke oven batteries. The PLI scheme supports domestic manufacturing capabilities, including for steel and its inputs. Major steel hubs in Odisha and Chhattisgarh are expanding their coking capacity to feed blast furnaces.
United States
The US EPA's stringent air quality standards necessitate significant upgrades for existing coke oven batteries. Operators are focusing on modernizing legacy assets to improve environmental performance and extend operational lifespans. The Great Lakes region, historically a steelmaking center, requires continuous investment in emission control systems.
Germany
Decarbonization mandates under the EU Green Deal pressure German steelmakers to enhance energy efficiency in cokemaking. The European Chemicals Agency (ECHA) influences by-product recovery standards and chemical safety. The industrial Ruhr Valley region is exploring advanced heat recovery systems and alternative ironmaking technologies.
Japan
Stable steel production in Japan drives demand for highly efficient and long-lasting coke oven batteries. The Ministry of Economy, Trade and Industry (METI) promotes energy efficiency targets for heavy industry. Integrated steel mills in the Kanto region and along the Setouchi Inland Sea prioritize technological upgrades for operational stability.
Global Coke Oven Batteries Market Key Industry Players
Global majors compete with regional champions across integrated engineering and specialized component supply within the coke oven batteries market. The market exhibits a tiered structure, with large industrial conglomerates offering comprehensive turnkey solutions alongside specialized engineering firms providing advanced material science and system designs. Key strategic archetypes include integrated plant builders, refractory material specialists, and advanced emission control system providers. Strategic partnerships for technology transfer and capacity expansion are dominant competitive moves.
Integrated plant builders, such as Germany-based Thyssenkrupp AG, exemplify the capability to deliver full-scale cokemaking facilities, leveraging extensive engineering and construction expertise. Paul Wurth, a Luxembourgish company, represents specialized engineering expertise in high-efficiency coke oven components and advanced energy recovery systems, catering to efficiency-driven operators. Steel manufacturing giants like ArcelorMittal often operate their own captive coke oven batteries, influencing demand for upgrades and maintenance services, and demonstrating the end-user perspective on technology adoption.
| Leading Market Players |
|---|
| Paul Wurth |
| Thyssenkrupp AG |
| GIPROKOKS |
| Graycor International Inc. |
| Heavy Engineering Corporation Ltd. |
| ArcelorMittal |
| POSCO |
| Danieli Corus |
| Ingeteam Power Technology |
| Others |
Cost & Logistics Intelligence
Vertical integration by major steel manufacturers anchors both the supply position of metallurgical coke and the pricing power for coke oven battery construction services. This model allows large producers to secure essential inputs while influencing technology adoption and investment cycles.
Pricing Analysis
Input-cost pass-through for critical raw materials, such as high-purity silica and specialized engineering components, significantly influences project pricing for new coke oven batteries and major rebuilds. Project-based pricing dominates large-scale installations, reflecting the unique engineering and construction requirements of each site. Price differentiation stems from the inclusion of advanced emission control systems and the integration of energy recovery technologies. Upward pricing pressure also stems from stringent environmental regulations mandating costly compliance features. Steel manufacturers, while sensitive to overall capital expenditure, prioritize long-term operational efficiency and regulatory adherence over absolute lowest cost.
Supply Chain Analysis
Direct sales channels from integrated plant builders and specialized component suppliers handle the procurement of coke oven battery systems for global steel manufacturers. Supply concentration for advanced refractory materials and complex engineering services centers in countries like China, Germany, and Japan. Raw material dependencies include high-purity silica, specialized alloys for high-temperature applications, and advanced automation components. Geopolitical instability and trade restrictions affecting critical material access represent a significant supply chain risk. Distribution runs primarily through direct contracts between technology providers and large industrial end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a margin-expansion story, driven by the premium pricing associated with advanced refractory materials and next-generation, lower-emission cokemaking technologies.
For Market Incumbents:Hedge against the long-term threat of hydrogen-based direct reduced iron (H-DRI) by investing in R&D for next-generation, lower-emission cokemaking technologies and advanced heat recovery systems. Consolidate market share in engineering and construction services by offering comprehensive turnkey solutions that integrate advanced material science capabilities. Focus on strategic partnerships with refractory material specialists to secure supply and maintain a technological edge. The increasing regulatory burden from authorities like China's MEE demands continuous innovation in emission control systems.
For New Entrants and Emerging Players:Specialized technical consultancy services for retrofitting legacy assets represent a significant white-space opportunity, particularly in regions like the US where existing batteries require substantial upgrades for EPA compliance. Target the modernization and maintenance segment for older coke oven batteries, focusing on energy efficiency improvements and advanced emission controls. A direct technical sales approach, emphasizing specialized engineering expertise and rapid deployment capabilities, offers a viable go-to-market angle for these niche services.
For Investors and Strategic Acquirers:Roll-up economics work for specialized engineering firms and advanced material producers because the industry is consolidating around integrated solutions and high-performance components. The long-term viability of the coke oven battery market remains strong for the next decade, anchored by continued global steel demand and the capital-intensive nature of blast furnace steelmaking. Target specialized firms offering advanced refractory materials, next-generation emission control systems, or innovative heat recovery technologies. The sustained investment in new capacity by steel manufacturers in India and China is a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in India | Supports surging steel production targets and feeds an expanding fleet of blast furnaces. |
| Green Manufacturing Transition | Addresses EU Green Deal mandates for industrial decarbonization and energy efficiency improvements. |
| Long-term Refractory Supply Agreements | Secures critical high-purity silica materials for new constructions and major rebuilds. |
| Joint Ventures for Technology Transfer | Accelerates the adoption of advanced cokemaking processes and emission control systems. |
| Product Launch of Non-recovery Ovens | Meets stringent air quality standards with a simpler design and lower emissions profile. |
Research Approach
Bottom-up steel manufacturing end-use modeling reconciled against top-down coke oven battery builder tracking forms the analytical core of this study. Primary research involved in-depth interviews with steel executives, engineering firm R&D leads, refractory material scientists, and environmental regulators to gather qualitative insights. Secondary validation drew from industry association reports, government environmental agency publications, company annual reports, and specialized trade journals.
Historical trendline analysis of global coke production and investment patterns informs the market forecast across the analysis window. Segmentation dimensions modeled include product type, technology, application, end user, and regional regulatory frameworks. Compound annual growth rates were derived through statistical regression analysis and expert consensus. Industry-specific forecast inputs include projected steel production volumes in key regions and regulatory compliance timelines.
Geopolitical shifts impacting steel demand, accelerated adoption of H-DRI, and unforeseen changes in environmental enforcement are the dominant revision risks for market projections. Forecasts reflect assumptions regarding technological evolution and economic stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Japan Rechargeable Battery Market
Batteries
Modular Battery Market
Batteries
Power Battery Sealant Market
Batteries
Atomic Battery Market
Batteries
Absorbed Glass Mat (AGM) Separator Batteries Market
Batteries
South America Primary Battery Market
Batteries
Printable Battery Market
Batteries
Alkaline Battery Market
Batteries
Rechargeable Battery Market
Batteries
Europe SLI Battery Market
Batteries
United Kingdom Electric Vehicle Battery Electrolyte Market
Batteries
Smart Battery Market
Batteries
Breathing Battery Market
Batteries
Battery Pack for Marine Hybrid and Full Electric Propulsion Market
Batteries
Elastic Battery Binders Market
Batteries
Battery Cases Market