
 Battery Plate Market | 2026-2036
Battery Plate Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Plate Market Analysis
High-purity lead-calcium-tin alloy specifications is rotating demand away from conventional antimonial grids across the Battery Plate Market. EnerSys leverages its captive smelting network to secure refined lead feedstock. Exide Technologies anchors North American aftermarket supply through dense distributor relationships. GS Yuasa dominates cylindrical plate production for Japanese OEM starter battery programs.
A battery plate is an electroconductive grid or foil substrate, typically cast from lead alloys or coated copper, that holds active material paste and serves as the current collector in electrochemical cells. Grids range from 0.8 mm to 3.5 mm in thickness depending on cycle-life requirements, with expanded metal and stamped strip processes replacing gravity casting in high-volume lines. Lead-Acid plates retain the largest installed base but face margin compression from environmental compliance costs. Lithium-Ion plate architectures, particularly aluminum foil anode substrates and copper cathode foils, are capturing the fastest growth as cell manufacturers scale cylindrical and prismatic formats. Automotive applications consume the majority of finished plate tonnage, though Renewable Energy storage systems are shifting procurement toward thicker, corrosion-resistant designs for extended calendar life.
EPA lead emission standards and OSHA workplace exposure limits govern US plate casting operations, while REACH and RoHS constrain cadmium and hexavalent chromium use in European supply chains. India's BIS certification mandates grid alloy composition disclosure for domestic battery assembly. Stakeholders must monitor how China's SAMR enforces GB standards on recycled lead content as circular material quotas tighten across Asian supply bases.
Market Dynamics
Electric vehicle manufacturers are consolidating procurement around advanced plate architectures while China's NMPA purity mandates and dual carbon goals force alloy specification upgrades across Asian supply bases.
Growth Catalysts
- Automotive electrification:EV battery programs require high-surface-area foils and corrosion-resistant substrates, pulling capacity expansion in Jiangsu and Guangdong manufacturing clusters.
- REACH substance restrictions:European RoHS and REACH constraints on cadmium and hexavalent chromium accelerate lead-calcium-tin alloy substitution for antimonial grid formulations.
- Expanded metal processing:Stamped strip and continuous casting methods replace gravity casting, reducing material waste and enabling thinner 0.8 mm grid profiles for cycle-intensive applications.
Market Restraints
- Refined lead price volatility:Smelter capacity concentration and scrap supply disruptions transmit directly to plate casting cost structures.
- Environmental compliance burden:EPA lead emission standards and OSHA workplace exposure limits require continuous abatement investment at US casting facilities.
- Lithium-ion substrate substitution:Aluminum anode foils and copper cathode foils capture cylindrical and prismatic cell architectures, compressing lead-acid plate growth in portable and motive power segments.
Strategic Opportunities
- Renewable energy storage procurement:Grid-scale battery installations favor thicker corrosion-resistant plate designs for 20-year calendar life specifications.
- India BIS certification alignment:Domestic grid alloy composition disclosure mandates create localized supply advantages for certified producers.
- Recycled lead circular quotas:China's SAMR enforcement of GB standards on secondary lead content rewards integrated smelter-caster operations with qualified scrap streams.
Industry Challenges
- Metallurgical talent scarcity:Lead-calcium-tin alloy formulation expertise concentrates among aging technical workforces in mature manufacturing regions.
- Casting equipment capex cycles:Continuous expansion line upgrades demand capital commitments amid uncertain lead-acid demand trajectories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Plate Market |
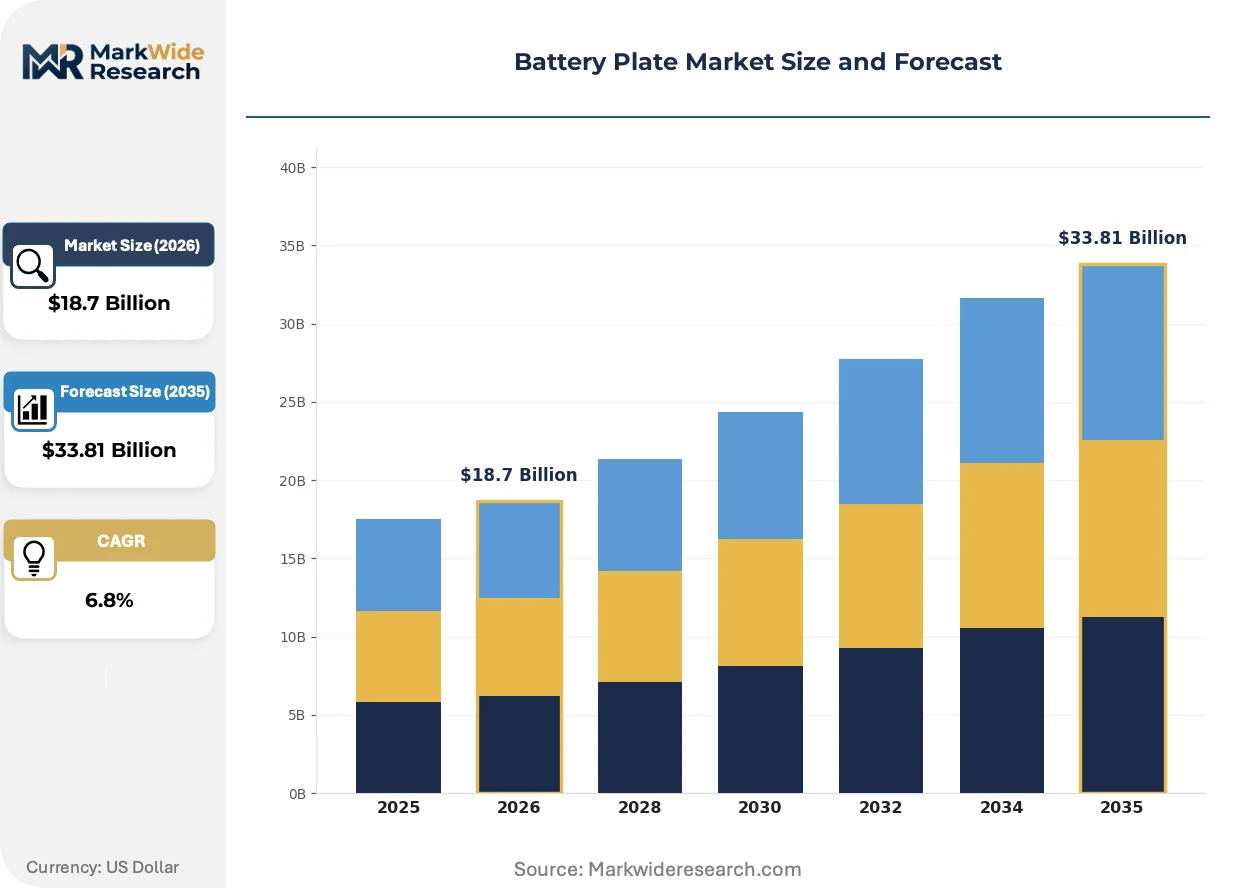
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead-Acid, Lithium-Ion, Nickel-Cadmium, AGM Application: Automotive, Telecommunications, Renewable Energy, Consumer Electronics End User: OEMs, Aftermarket Suppliers, Commercial, Industrial Manufacturing Stage: Raw Material Sourcing, Component Assembly, Final Testing, Quality Assurance |
| Companies Covered | EnerSys, Exide Technologies, GS Yuasa, Johnson Controls, East Penn Manufacturing, Amara Raja Batteries, Crown Battery, Microvast Holding, Toshiba Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Plate Market Emerging Trajectories
Plate manufacturing is pivoting from legacy gravity casting toward continuous processes and alternative substrates, driven by end-use performance specifications and regulatory substance bans.
Continuous expansion and stamped strip processing is supplanting gravity casting in high-volume lead-acid plate lines. Automotive OEM starter battery programs now specify 0.8 mm to 1.2 mm thickness tolerances that gravity methods cannot reliably achieve. This process transition compresses scrap rates and enables thinner grid geometries for improved power density.
China's GB standards on recycled lead content are tightening material traceability requirements across Asian supply chains. SAMR enforcement of circular material quotas forces casters to document secondary lead sourcing or face market exclusion. European battery assemblers importing Chinese plates must now verify alloy certificates against MEE environmental compliance records.
Long-term service contracts with performance guarantees are displacing spot purchasing in grid-scale energy storage procurement. Developers in utility-scale solar-plus-storage projects now require 15-year plate corrosion warranties backed by manufacturer balance sheet commitments. This contracting shift concentrates plate supply among vertically integrated producers with captive smelting and extended testing capabilities.
Battery Plate Market Segmentation
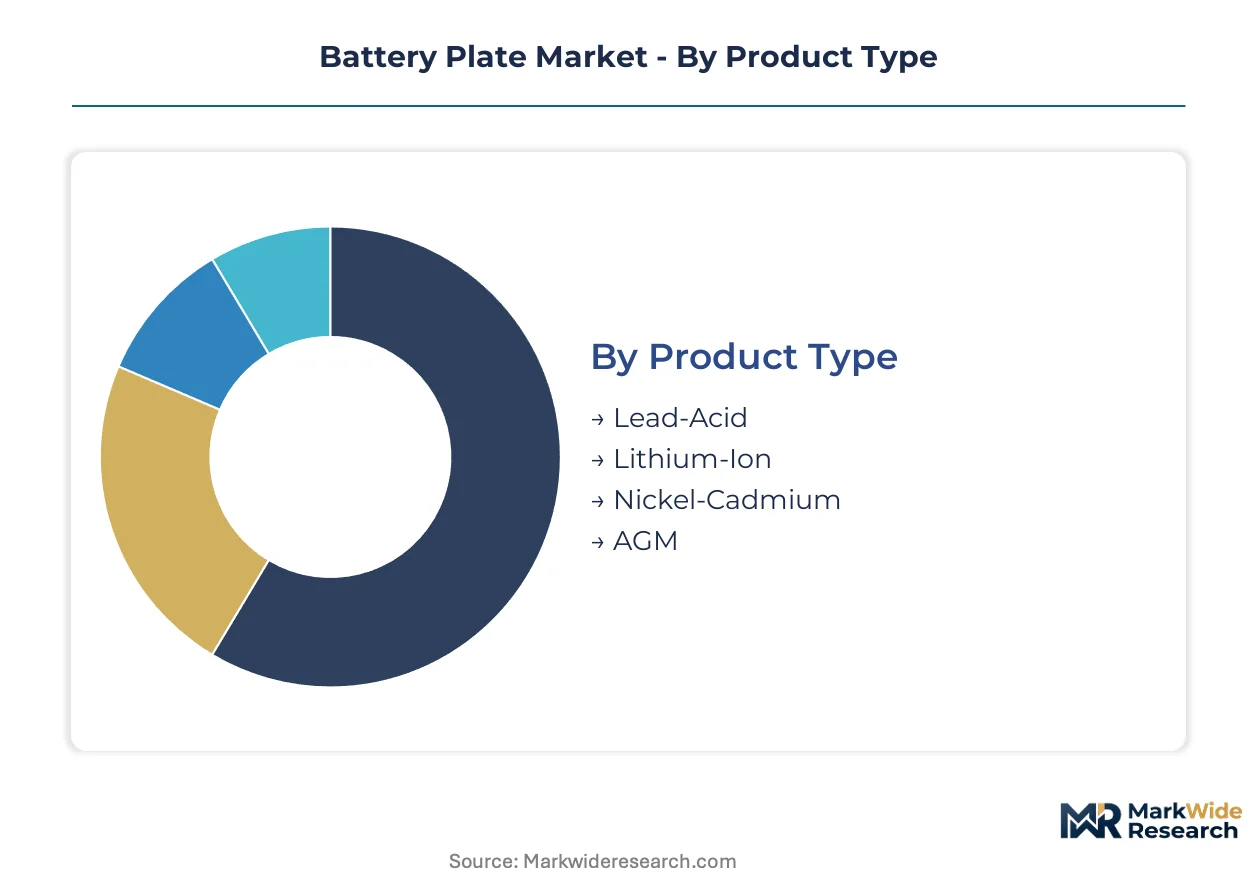
Battery plate procurement channels diverge sharply by electrochemistry and end-use durability requirements. OEMs negotiate direct casting contracts for automotive programs, while aftermarket distributors stock standardized grid geometries for replacement demand.
Product Type:
Channel mix splits between captive foundry supply for lead-acid volumes and foil converter networks for lithium-ion cell producers.
- Lead-Acid:Cast lead-calcium-tin grids dominate automotive starter battery supply through direct OEM contracts. China's Jiangsu cluster ships antimonial replacements to Southeast Asian aftermarket distributors facing REACH substance restrictions.
- Lithium-Ion:Aluminum anode foils and copper cathode substrates flow through Japanese and South Korean foil rolling mills into cylindrical cell lines. Cell manufacturers in Guangdong specify 6-20 micron thickness tolerances for prismatic formats.
- Nickel-Cadmium:Sintered nickel plaque substrates serve aviation and rail backup power through specialized aerospace distributors.
- AGM:Absorbent glass mat separators integrate with compressed lead plates in premium automotive and marine channels.
By volume, Lead-Acid leads. By growth pace, Lithium-Ion is climbing the fastest.
Application:
Cost tier stratification separates commodity automotive volumes from premium renewable energy specifications demanding extended corrosion warranties.
- Automotive:OEM starter battery programs specify 0.8-1.2 mm grid thickness through continuous casting contracts. Japanese OEMs anchor cylindrical plate demand through GS Yuasa supply agreements.
- Telecommunications:Stationary backup installations in India source BIS-certified lead-calcium grids through domestic assemblers.
- Renewable Energy:Grid-scale developers procure thicker corrosion-resistant designs with 15-year performance guarantees. Utility-scale solar-plus-storage projects in China require SAMR-compliant alloy certificates.
- Consumer Electronics:Portable power banks and UPS units drive thin-foil lithium-ion substrate demand through electronics manufacturing services.
Automotive commands the heaviest tonnage. Renewable Energy carries the steepest specification premiums.
End User:
Customer type determines contract structure, with OEMs locking multi-year casting capacity and aftermarket suppliers trading spot grid inventories.
- OEMs:Vehicle manufacturers consolidate procurement around advanced plate architectures with captive smelter integration. EnerSys leverages refined lead feedstock security for long-term supply commitments.
- Aftermarket Suppliers:Dense distributor relationships anchor North American replacement demand through Exide Technologies' channel network.
- Commercial:Fleet operators and data centers negotiate service contracts with performance guarantees rather than spot purchasing.
- Industrial:Material handling and motive power segments face lithium-ion substrate substitution in forklift and mining equipment.
OEMs dominate contract value. Aftermarket Suppliers handle the widest SKU proliferation.
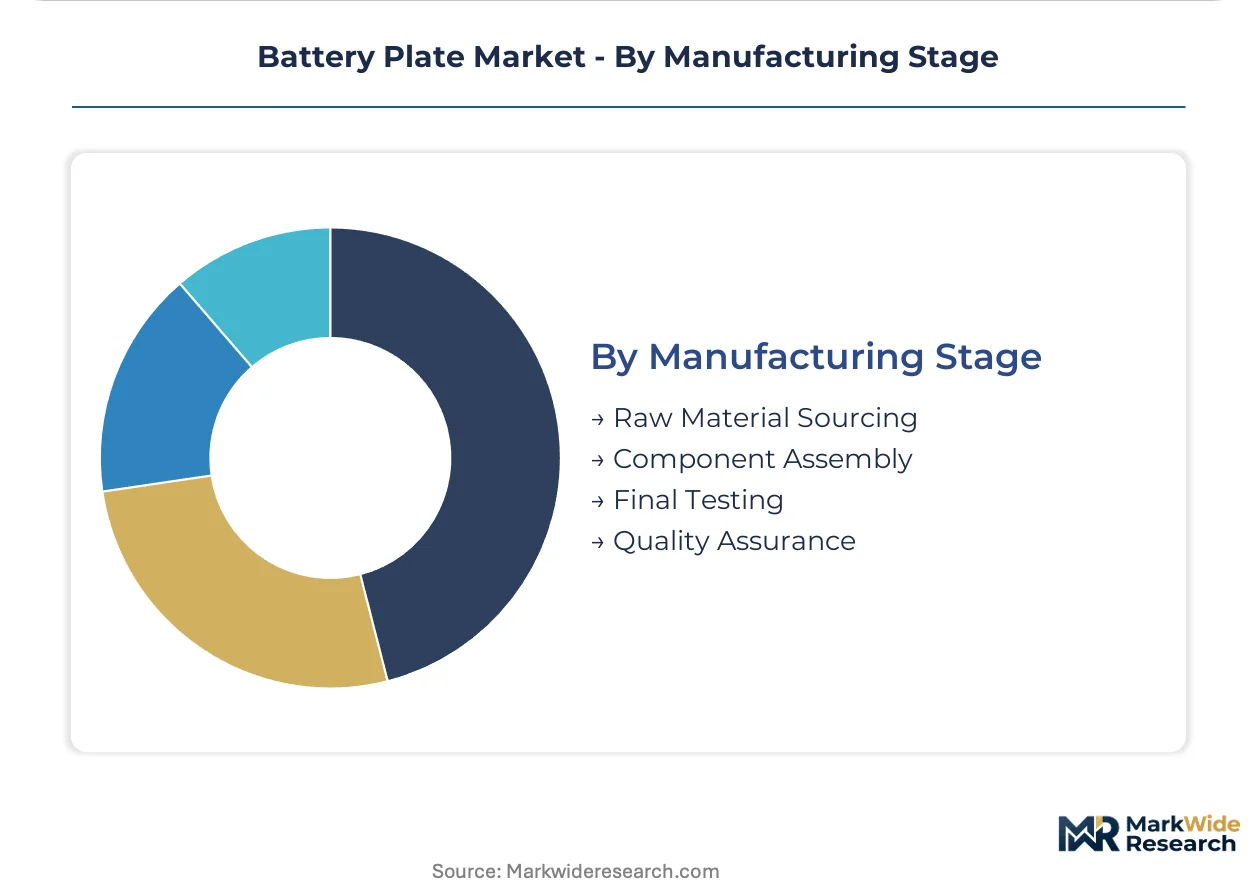
Manufacturing Stage:
Supply concentration varies by process step, with raw material sourcing consolidating around integrated smelters and quality assurance fragmenting across third-party labs.
- Raw Material Sourcing:Refined lead price volatility transmits directly to plate casting economics. China's SAMR enforcement of GB standards on recycled content rewards qualified scrap stream documentation.
- Component Assembly:Continuous expansion lines in Guangdong replace gravity casting for high-volume automotive programs.
- Final Testing:Cycle-life verification and corrosion resistance validation occur at caster facilities or captive OEM labs.
- Quality Assurance:Third-party certification against EPA emission standards and OSHA exposure limits governs US facility access.
Raw Material Sourcing absorbs the greatest margin risk. Quality Assurance carries the highest compliance burden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics shape regional plate procurement, with Asian manufacturing clusters supplying lead-acid grids to European assemblers while North American producers focus on captive automotive programs. Currency fluctuations and alloy certification requirements increasingly determine cross-border sourcing decisions.
China
Jiangsu and Guangdong manufacturing clusters ship antimonial replacement grids to Southeast Asian aftermarket channels. SAMR enforcement of GB standards on recycled lead content forces casters to document secondary sourcing or face exclusion from state-backed procurement. NMPA purity mandates and dual carbon goals are tightening active material specifications across domestic EV battery programs.
United States
EPA lead emission standards and OSHA workplace exposure limits govern plate casting operations concentrated in industrial Midwest states. Refined lead price volatility from smelter capacity concentration transmits directly to domestic cost structures. Dense distributor relationships anchor aftermarket supply through regional battery assembly networks serving automotive replacement demand.
Germany
REACH substance restrictions and RoHS constraints on cadmium accelerate lead-calcium-tin alloy substitution for conventional grid formulations. European battery assemblers importing Asian plates must verify alloy certificates against MEE environmental compliance records. Industrial motive power segments face lithium-ion substrate substitution in material handling equipment procurement.
India
BIS certification mandates grid alloy composition disclosure for domestic battery assembly, creating localized supply advantages for certified producers. Stationary backup installations in telecommunications source lead-calcium grids through domestic assemblers meeting national standards. Maharashtra and Gujarat industrial corridors concentrate plate fabrication capacity for regional automotive OEM programs.
Japan
METI industrial policy supports cylindrical plate production for domestic OEM starter battery programs through established supply agreements. JIS standards govern grid thickness tolerances and alloy specifications for automotive applications. Kansai and Chubu manufacturing regions maintain specialized casting expertise for premium battery architectures.
Battery Plate Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and technology licensing dimensions. The vendor base stratifies between integrated smelter-casters with captive lead supply and independent fabricators purchasing refined feedstock on spot markets. Three archetypes dominate: vertically integrated battery manufacturers, standalone plate specialists, and diversified industrial conglomerates with materials divisions. Competitive moves center on continuous casting line upgrades and long-term service contracts with performance guarantees for grid-scale energy storage developers.
Within the integrated battery manufacturer tier, EnerSys leverages captive smelting networks to secure refined lead feedstock, while Exide Technologies anchors North American aftermarket channels through established distributor relationships. GS Yuasa occupies a position exemplifying cylindrical plate specialization for Japanese OEM programs. These three represent distinct geographic and structural approaches to plate supply security.
| Leading Market Players |
|---|
| EnerSys |
| Exide Technologies |
| GS Yuasa |
| Johnson Controls |
| East Penn Manufacturing |
| Amara Raja Batteries |
| Crown Battery |
| Microvast Holding |
| Toshiba Corporation |
| Others |
Supply Flow & Price Mechanics
Ninety-day refined lead inventory cycles at Jiangsu casting facilities concentrate pricing power among integrated smelter-casters while spot-market buyers absorb volatility from scrap supply disruptions. This lead-time compression ties contract premiums directly to SAMR-certified secondary material documentation.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with volume-scale discounts and BIS certification tiers separating premium from standard supply. Price differentiation stems from captive smelter integration and corrosion warranty duration. Cost compression in antimonial replacement grades is intensifying because REACH substance restrictions force alloy reformulation. Aftermarket distributors exhibit highest price sensitivity; utility-scale developers with 15-year performance guarantees show lowest.
Supply Chain Analysis
Strait of Malacca transit underwrites refined lead flows from Australian concentrate to Chinese smelters. Supply concentrates in China, South Korea, and Japan for lithium-ion foil rolling; India and Germany for lead-acid grid casting. Raw material dependencies include LME-grade refined lead, copper cathode, and aluminum ingot. Single-source vulnerability concentrates in Jiangsu cluster expansion lines. Distribution runs through direct OEM contracts for automotive volumes and dense distributor networks for aftermarket replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Battery Plate Market functions as a defensive-moat arena where regulatory entrenchment through alloy certification standards creates durable switching costs for qualified producers.
For Market Incumbents: Consolidate captive smelter capacity in Guangdong to secure SAMR-compliant scrap streams against lithium-ion substrate substitution. Deepen backward integration into secondary lead refining to defend margin position from LME price volatility. Lock long-term service contracts with 15-year corrosion warranties to bind utility-scale developers. For New Entrants and Emerging Players: Anchor in India's BIS-certified domestic assembly channel where localized alloy disclosure mandates favor new certified producers. Target telecommunications stationary backup installations with lead-calcium grid supply. Pursue joint venture structures with established Jiangsu casters to bypass metallurgical talent scarcity. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across continuous expansion line upgrades. Five-to-ten year viability favors integrated smelter-casters with qualified scrap documentation over independent fabricators. Watch SAMR enforcement intensity as inflection signal for circular quota compliance costs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Secondary Lead Refining | Captive scrap stream documentation satisfies China's SAMR circular material quotas. |
| Continuous Expansion Line Upgrade | Thinner 0.8 mm grid tolerances meet Japanese OEM starter battery specifications. |
| Long-term Service Contract with Performance Guarantee | 15-year corrosion warranties align with utility-scale solar-plus-storage procurement. |
| BIS Certification Investment | Domestic alloy disclosure compliance opens Indian telecommunications backup channels. |
| Joint Venture with Established Caster | Technology transfer agreements bypass metallurgical talent scarcity in lead-calcium-tin formulation. |
Methodological Framework
A spread of perspectives from lead smelter operations managers, OEM battery procurement leads, grid casting technical directors, and renewable energy EPC contractors converged on the working assumptions. Secondary validation drew from EPA emission compliance filings, China's MEE environmental records, BIS certification registries, and SEC 10-K disclosures from listed battery manufacturers. Bottom-up plate volume estimates triangulated against top-down electrochemical cell production forecasts.
Segmentation dimensions modeled span product type (lead-acid, lithium-ion, nickel-cadmium, AGM), application (automotive, telecommunications, renewable energy, consumer electronics), end user (OEMs, aftermarket suppliers, commercial, industrial), and manufacturing stage. CAGRs derived from regression analysis of historical capacity expansion announcements against regulatory enforcement timelines. Forecast inputs incorporated SAMR quota implementation schedules and NMPA purity mandate phase-ins.
Material uncertainties — refined lead price volatility, scrap supply disruptions, and lithium-ion substitution acceleration — sit outside the modeled envelope. Forecasts reflect assumptions about continuous casting adoption rates and certification compliance timelines. Practitioners should keep alternative scenarios live as China's dual carbon policy enforcement evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Elastic Battery Binders Market
Batteries
South America Micro Battery Market
Batteries
Asia Power Tool Batteries Market
Batteries
Non-Rechargeable Battery Market
Batteries
South Africa Battery Market
Batteries
Utility Battery Market
Batteries
Iron Flow Battery Market
Batteries
Smart Battery Charger Market
Batteries
North Africa Battery Market
Batteries
United States SLI Battery Market
Batteries
Europe SLI Battery Market
Batteries
Carbon Foam Battery Market
Batteries
Europe Industrial Battery Market
Batteries
Battery Wash System Market
Batteries
Sodium Nickel Chloride Battery Market
Batteries
South America Battery Cell Market