
 Aircraft Turn Coordinator Market | 2026-2036
Aircraft Turn Coordinator Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Turn Coordinator Market Analysis
TSO-certified digital specifications is bifurcating the competitive landscape between legacy analog suppliers and modern avionics houses. Honeywell International Inc. leverages its integrated flight deck portfolio to bundle turn coordinators with larger system sales. L3Harris Technologies, Inc. sustains defense-grade gyroscopic production lines that anchor military retrofit contracts. Garmin Ltd. dominates the general aviation channel through direct-to-consumer distribution and certified aftermarket units.
An aircraft turn coordinator is a flight instrument that indicates the rate of turn and quality of coordination using an electrically or pneumatically driven gyroscope, typically displaying roll rate via a miniature aircraft symbol against a calibrated dial. It serves as a critical reference for pilots during instrument flight rules operations, preventing hazardous uncoordinated turns that lead to stalls or spins. Digital turn coordinators are capturing margin pools as operators replace vacuum-driven systems with solid-state electronic sensors that eliminate maintenance-intensive gyroscopic components. The flight schools end-user segment is expanding fastest as training fleets modernize to meet FAA instrument rating requirements with reliable, low-drift instrumentation.
FAA Technical Standard Orders govern airworthiness certification for turn coordinators installed in US-registered aircraft, while EASA CS-SC001 sets equivalent standards across European member states. The EPA's phase-out of mercury-containing instruments indirectly accelerates electronic sensor adoption by restricting legacy gyroscopic technologies. Stakeholders must monitor evolving FAA mandates for automatic dependent surveillance-broadcast integration, which will determine whether standalone turn coordinators persist or become absorbed into unified attitude reference units.
Market Dynamics
TSO-certified digital specifications are bifurcating the competitive landscape between legacy analog suppliers and modern avionics houses, forcing established manufacturers to recertify product lines while creating entry points for solid-state sensor specialists.
Growth Catalysts
- FAA airworthiness directives:Mandates requiring instrument modernization in US-registered aircraft are accelerating replacement cycles for vacuum-driven systems.
- Flight school certification requirements:Training fleets are modernizing instrumentation to meet FAA instrument rating standards, expanding procurement of reliable, low-drift units.
- Solid-state MEMS sensors:Elimination of maintenance-intensive gyroscopic components is reducing total cost of ownership for commercial operators.
Market Restraints
- Avionics-grade semiconductor supply:Concentrated fabrication capacity in East Asia creates vulnerability for sensor-integrated units during supply disruptions.
- Dual certification requirements:FAA TSO-C4c and EASA CS-SC001 compliance adds development overhead for products targeting transatlantic fleets.
- Attitude reference unit integration:Unified glass cockpit systems threaten standalone turn coordinator demand as manufacturers bundle functionality.
Strategic Opportunities
- ADS-B mandate preparation:FAA requirements for automatic dependent surveillance-broadcast integration may preserve standalone instrument demand if certification pathways favor discrete units.
- Mercury instrument phase-out:EPA restrictions on mercury-containing gyroscopic technologies are accelerating electronic sensor adoption among legacy fleet operators.
- Direct-to-consumer channels:Experimental and light-sport aircraft builders are purchasing certified aftermarket units through online distribution, bypassing traditional avionics shops.
Industry Challenges
- Gyroscopic engineering expertise:The transition from mechanical to solid-state sensing has created a talent gap in MEMS calibration and drift compensation.
- Legacy airframe integration:Retrofit installations require custom mounting adaptations and electrical system upgrades that extend installation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Turn Coordinator Market |
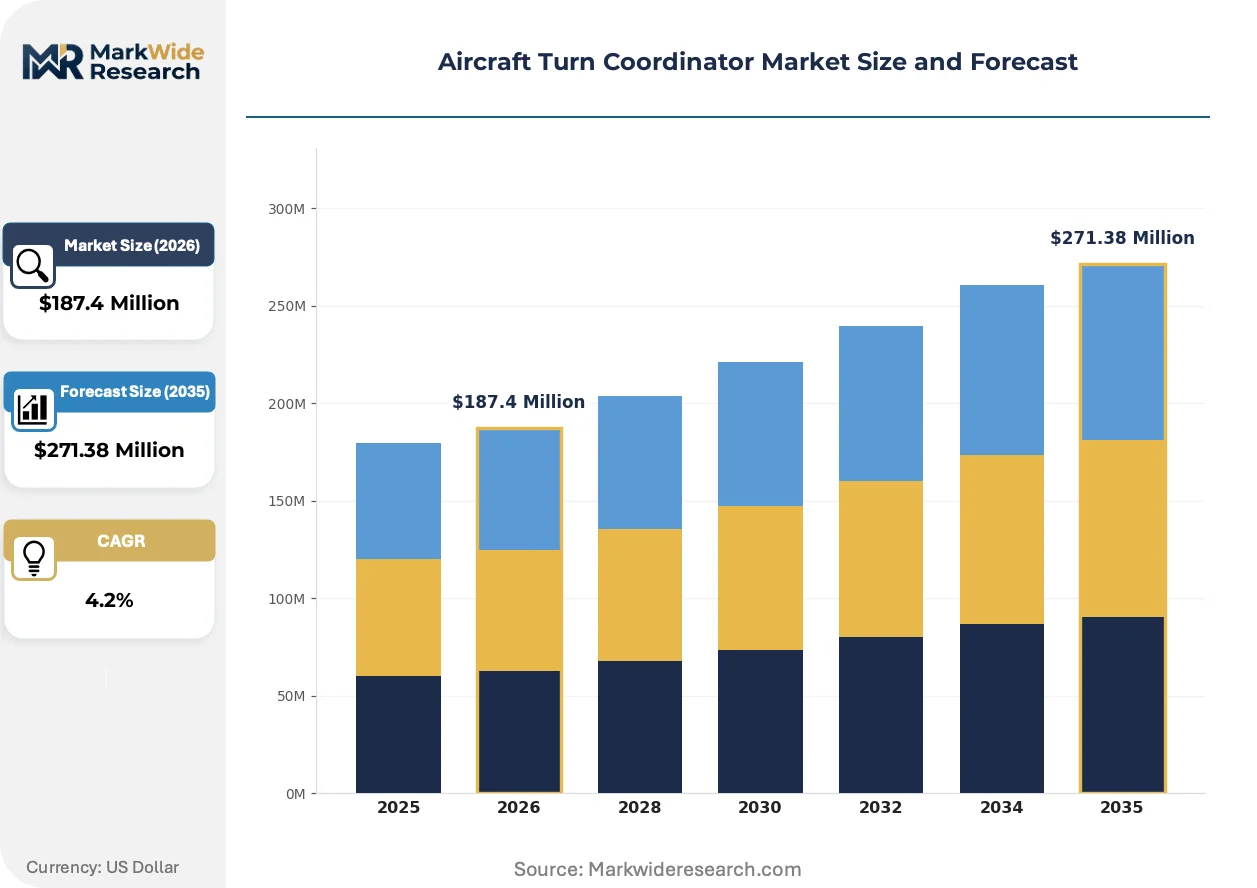
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $271.38 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Turn Coordinators, Digital Turn Coordinators, Multi-Function Displays, Integrated Flight Instrumentation End User: Commercial Aviation, Military Aviation, Private Jets, Flight Schools Technology: Gyroscopic Technology, MEMS Technology, Inertial Navigation, Electronic Sensors Installation Type: Fixed Wing Aircraft, Rotary Wing Aircraft, UAVs, Simulator Systems |
| Companies Covered | L3Harris Technologies, Inc., Kelly Manufacturing Co., Honeywell International Inc., Aircraft Spruce, Radiant Technology, Garmin Ltd., Mid-Continent Instrument Co., Inc., Tokyo Aircraft Instrument Co., Ltd., Collins Aerospace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Turn Coordinator Market Emerging Trajectories
Digital sensor architectures are compressing form factors while expanding functionality, creating divergence between premium integrated flight decks and cost-optimized standalone instruments for the retrofit market.
MEMS-based angular rate sensors are replacing traditional spinning mass gyroscopes in turn coordinator designs. Flight schools and charter operators are adopting these units fastest due to reduced calibration intervals. Solid-state electronics is miniaturizing instrument packages to fit legacy panel cutouts without structural airframe modification.
EPA regulations phasing out mercury-containing instruments are indirectly mandating electronic sensor adoption across the US general aviation fleet. This regulatory pressure eliminates maintenance-intensive vacuum systems from new installations. Aging aircraft owners in the United States are responding by prioritizing TSO-certified digital replacements during scheduled avionics upgrades.
Buyer purchasing patterns are fragmenting across direct manufacturer sales, traditional avionics distributors, and online aftermarket channels. Experimental aircraft builders and owner-operators increasingly source certified units through e-commerce platforms that bypass dealer networks. This channel shift is most pronounced in the United States, where Part 91 operators face fewer installation restrictions than commercial carriers.
Aircraft Turn Coordinator Market Segmentation
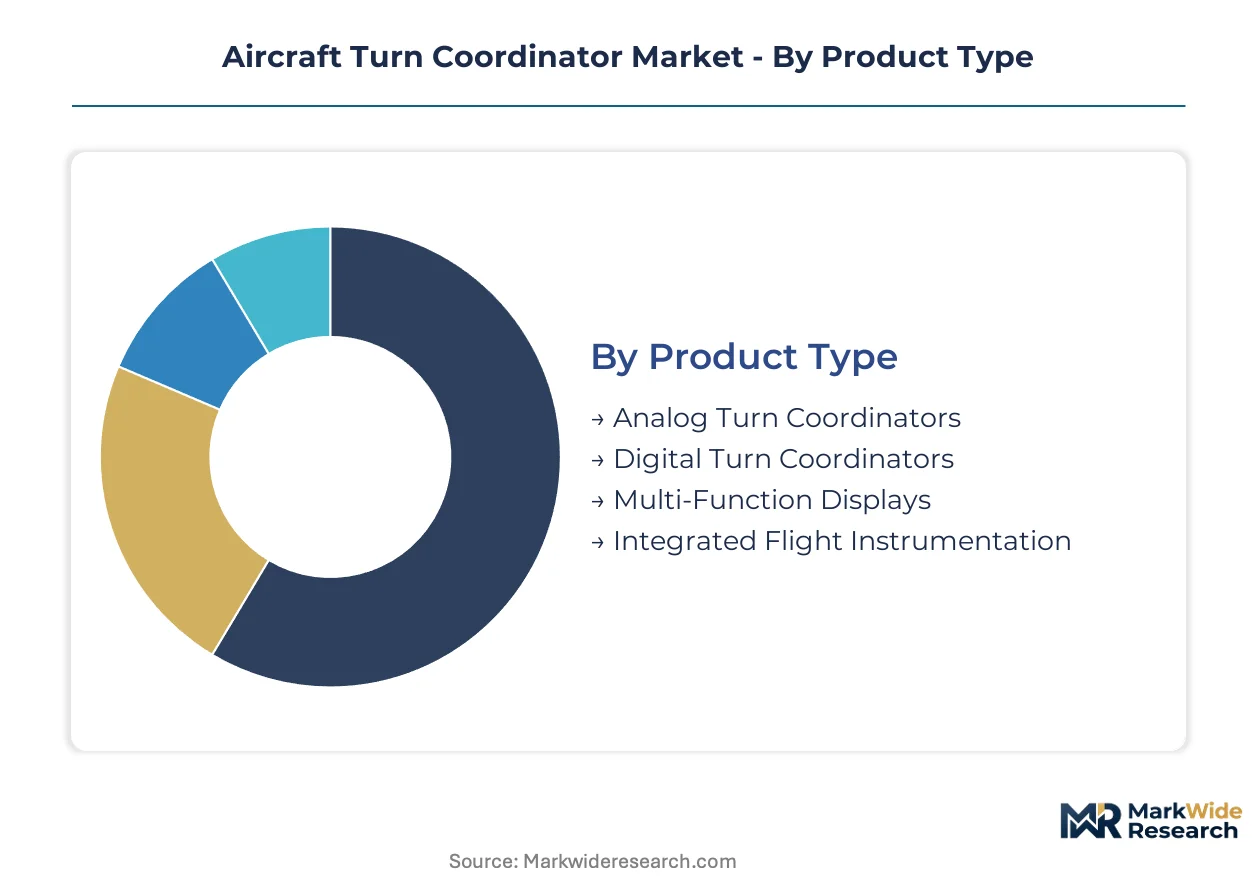
Segmentation in the Aircraft Turn Coordinator Market reveals how procurement patterns split between legacy fleet retrofits and new aircraft production lines. Understanding these divisions helps suppliers align certification strategies with distinct buyer requirements across aviation sectors.
Product Type:
Analog units dominate domestic US retrofit demand from aging general aviation fleets, while digital specifications drive export sales to modernizing operators in Germany, France, and Australia.
- Analog Turn Coordinators:Vacuum-driven gyroscopic instruments with mechanical spinning mass sensors remain specified for legacy aircraft lacking electrical system capacity. Demand concentrates in US-based Part 91 owner-operators facing FAA airworthiness directive deadlines for instrument replacement.
- Digital Turn Coordinators:Solid-state electronic units employing MEMS angular rate sensors eliminate maintenance-intensive gyroscopic components. Flight schools across Texas, Florida, and California are standardizing on these units to reduce calibration intervals and meet FAA instrument rating requirements.
- Multi-Function Displays:Combined instruments integrating turn coordination with attitude reference data.
- Integrated Flight Instrumentation:Fully unified glass cockpit systems absorbing turn coordinator functionality into broader avionics suites.
Analog turn coordinators hold the largest share; momentum sits with digital specifications.
End User:
Cost tiers separate military-grade precision requirements from price-sensitive flight school procurement, with commercial aviation occupying the middle ground on total cost of ownership calculations.
- Commercial Aviation:Regional airlines and charter operators specify TSO-certified digital units with reduced mean time between failures. These buyers prioritize lifecycle cost over acquisition price, driving demand for solid-state MEMS configurations in scheduled service fleets.
- Military Aviation:Defense operators require hardened gyroscopic instruments meeting MIL-STD environmental specifications. Procurement runs through defense-grade production lines with extended qualification timelines and captive supply arrangements.
- Private Jets:Owner-operators and corporate flight departments selecting instruments for cabin-class turbine aircraft.
- Flight Schools:Training fleet operators modernizing instrumentation to satisfy FAA practical test standards for instrument rating certification.
Commercial aviation generates the highest unit volumes; flight schools are climbing the fastest.
Technology:
Application requirements dictate sensor selection, with inertial navigation commanding premium positioning while electronic sensors capture retrofit volume.
- Gyroscopic Technology:Traditional spinning mass instruments using electrically or pneumatically driven rotors to detect angular rate. Remaining demand comes from operators of vintage aircraft preserving original panel configurations for historical authenticity.
- MEMS Technology:Microelectromechanical systems employing silicon-based vibrating structures to measure rotational acceleration. Charter operators in the US Southwest are adopting these units fastest due to reduced drift characteristics in high-temperature operating environments.
- Inertial Navigation:Ring laser and fiber-optic gyroscopes integrated with accelerometers for high-precision attitude reference.
- Electronic Sensors:Solid-state angular rate sensors without moving parts, suitable for light-sport and experimental aircraft categories.
Gyroscopic technology retains installed base dominance; MEMS specifications are gaining share fastest.
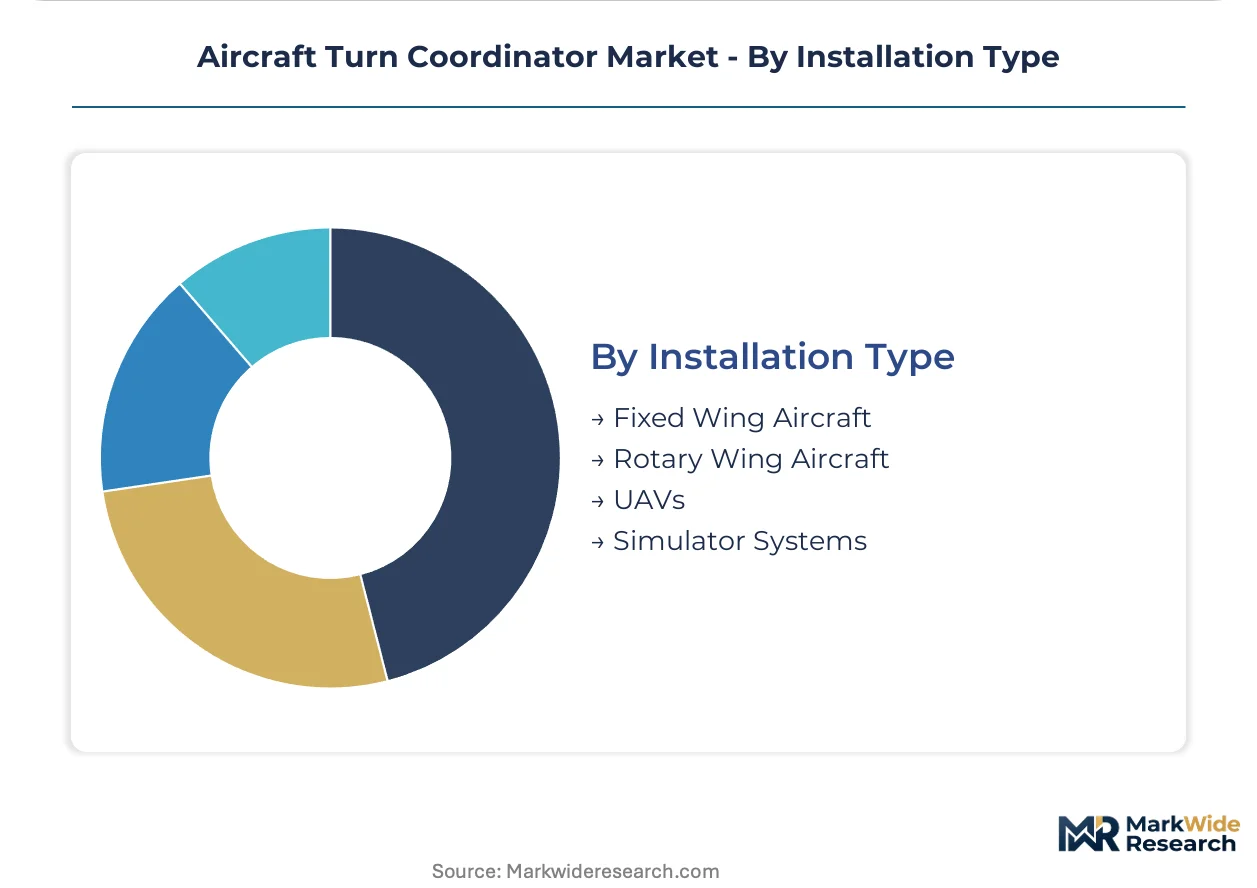
Installation Type:
Customer type fragmentation separates OEM line-fit requirements from aftermarket retrofit complexity, with UAVs introducing novel form factor constraints.
- Fixed Wing Aircraft:Conventional panel-mounted instruments designed for standard 3-inch instrument cutouts in general aviation aircraft. The US-based fleet of Cessna, Piper, and Beechcraft single-engine pistons drives replacement demand as these airframes exceed forty years of service.
- Rotary Wing Aircraft:Helicopter-specific units with enhanced vibration isolation and 360-degree display readability. Emergency medical services operators in California and Texas are upgrading fleets with digital replacements for vacuum-driven legacy instruments.
- UAVs:Miniaturized solid-state sensors for unmanned aircraft systems with severe weight and power constraints.
- Simulator Systems:Replica instruments for flight training devices requiring visual fidelity without airworthiness certification.
Fixed wing installations command the largest share; rotary wing upgrades show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Avionics manufacturing clusters concentrate in the United States, where FAA certification requirements and the world's largest general aviation fleet create concentrated procurement demand. Suppliers align regional strategies with distinct regulatory pathways and fleet modernization cycles across key aviation markets.
United States
Texas and Florida flight schools are standardizing on digital turn coordinators to meet FAA instrument rating practical test standards. The FAA's airworthiness directives mandating vacuum system replacements are accelerating retrofit cycles across the aging Cessna and Piper fleet. Wichita's aviation manufacturing corridor hosts integrated avionics houses bundling turn coordinators with larger flight deck systems.
Germany
Commercial operators across Bavaria and North Rhine-Westphalia specify EASA CS-SC001 certified digital units with reduced calibration intervals for scheduled service fleets. The country's national aviation regulator enforces stringent environmental standards that restrict mercury-containing instrument installations. Stuttgart's precision engineering cluster supplies MEMS sensor components to avionics integrators serving the European retrofit market.
France
Charter operators in the Île-de-France region prioritize solid-state electronic sensors to minimize maintenance downtime in high-utilization aircraft. ANSM and EASA coordinate on instrument airworthiness certification timelines that affect transatlantic fleet harmonization. Toulouse's aerospace manufacturing ecosystem includes suppliers producing gyroscopic components for defense-grade turn coordinator applications.
Australia
Flight training organizations in Queensland and Victoria are modernizing instrumentation to comply with CASA instrument rating requirements. The country's civil aviation safety authority mandates equipment standards equivalent to FAA TSO specifications for imported avionics. Sydney's avionics distribution channels service the Pacific region's general aviation retrofit demand.
Japan
Tokyo Aircraft Instrument anchors domestic production of precision gyroscopic instruments for regional airline and military applications. METI coordinates industrial policy supporting avionics component manufacturing for export markets. Nagoya's aerospace manufacturing corridor supplies sensor technologies integrated into next-generation flight instrumentation.
Aircraft Turn Coordinator Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the bifurcated analog-digital product spectrum. The market structure separates legacy gyroscopic instrument specialists from solid-state MEMS sensor houses, with mid-tier avionics distributors occupying intermediate positions. Three archetypes dominate: integrated flight deck manufacturers bundling turn coordinators with larger system sales, standalone instrument specialists serving the retrofit channel, and defense-grade precision gyroscope producers. Competitive moves center on FAA TSO recertification investments and direct-to-consumer distribution channel development.
Among US-based avionics houses, Honeywell International Inc. and Garmin Ltd. exemplify the integrated systems archetype, while L3Harris Technologies, Inc. occupies a position within defense-grade precision instrumentation. Tokyo Aircraft Instrument Co., Ltd. represents specialized gyroscopic manufacturing expertise concentrated in Japanese industrial clusters. These three companies anchor distinct competitive vectors that structure procurement alternatives across military, commercial, and general aviation end-user segments.
| Leading Market Players |
|---|
| L3Harris Technologies, Inc. |
| Kelly Manufacturing Co. |
| Honeywell International Inc. |
| Aircraft Spruce |
| Radiant Technology |
| Garmin Ltd. |
| Mid-Continent Instrument Co., Inc. |
| Tokyo Aircraft Instrument Co., Ltd. |
| Collins Aerospace |
| Others |
Supply Flow & Price Mechanics
TSO-C4c certification scale economies concentrate production among avionics houses with dedicated FAA approval staff, compressing price floors for analog retrofits while elevating entry costs for solid-state entrants. This concentration reinforces supplier power over flight schools and Part 91 operators facing directive-driven replacement deadlines.
Pricing Analysis
FAA TSO-C4c dictates the pricing tier structure across the retrofit channel, separating vacuum-driven analog units from MEMS-based digital specifications. Three-tier pricing stratifies across integrated flight deck bundles, standalone certified instruments, and experimental-category alternatives. Cost compression in the analog tier stems from shrinking gyroscopic component suppliers exiting the EPA-regulated mercury instrument segment. Flight schools exhibit highest price sensitivity due to fleet-scale procurement volumes, while corporate operators prioritize reduced calibration intervals over acquisition cost.
Supply Chain Analysis
Avionics-grade semiconductor inventory cycles stretch lead times for MEMS sensor-integrated units during East Asian fabrication disruptions. Component sourcing draws from Taiwan for silicon wafer processing, Japan for precision gyroscopic elements, and the United States for final assembly and TSO certification. Single-source vulnerability concentrates in MEMS die fabrication, where limited qualified suppliers anchor sensor production. Distribution runs through traditional avionics shops, direct manufacturer channels, and emerging e-commerce platforms serving experimental builders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as FAA airworthiness directives force instrument modernization across the aging general aviation fleet, creating directive-driven replacement demand independent of discretionary upgrade cycles.
For Market Incumbents: Secure TSO-C4c recertification for solid-state product lines before EPA mercury instrument deadlines eliminate analog revenue streams. Backward integration into MEMS sensor sourcing reduces exposure to East Asian semiconductor supply disruptions. Channel control through direct-to-consumer platforms defends against distributor disintermediation in the experimental aircraft segment. For New Entrants and Emerging Players: Anchor in the flight school retrofit segment, where fleet-scale procurement and FAA instrument rating requirements create predictable demand without OEM line-fit qualification barriers. Texas and Florida training organizations represent the most penetrable geography due to concentrated fleet density and standardized panel configurations. A go-to-market angle emphasizing reduced calibration intervals and lower total cost of ownership differentiates against legacy analog suppliers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated flight deck manufacturers bundling turn coordinators with larger avionics suite sales. Long-term viability favors suppliers with established FAA certification infrastructure and MEMS calibration expertise rather than mechanical gyroscope legacy assets. The signal to watch is EASA-FAA harmonization on CS-SC001 and TSO-C4c alignment, which would consolidate procurement standards and favor transatlantic-certified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| TSO-C4c Digital Recertification | Preserves market access as EPA mercury restrictions eliminate analog alternatives. |
| MEMS Sensor Backward Integration | Reduces supply vulnerability to East Asian semiconductor fabrication disruptions. |
| Direct-to-Consumer Channel Development | Captures experimental and light-sport aircraft builders bypassing traditional avionics shops. |
| Flight School Fleet Partnerships | Locks in recurring procurement from training organizations modernizing for FAA instrument rating compliance. |
| EASA-FAA Harmonization Investment | Enables single-certification access to transatlantic retrofit demand from European general aviation operators. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with avionics procurement managers at flight schools, maintenance directors at charter operators, certification engineers at FAA-approved manufacturing facilities, and distribution channel partners at regional avionics shops. Secondary validation drew from FAA TSO certification databases, EPA regulatory filings on mercury instrument phase-outs, EASA CS-SC001 documentation, and customs records of avionics component trade flows. Bottom-up fleet replacement modeling triangulated against top-down market sizing from installed base estimates and directive compliance timelines.
Across the analysis window, forecasts employed a segmented growth accounting framework disaggregating analog versus digital product trajectories, fixed-wing versus rotary-wing installation types, and commercial aviation versus flight school end-user demand. CAGRs were derived from replacement cycle acceleration under FAA airworthiness directives and MEMS sensor penetration curves calibrated to EPA regulatory enforcement intensity. Industry-specific inputs included gyroscopic component supplier exit rates and flight school enrollment trends driving training fleet modernization.
Material uncertainties — regulatory delay in EPA mercury instrument enforcement, EASA-FAA certification standard divergence, and semiconductor supply disruption severity — sit outside the modeled envelope. Forecasts reflect documented assumptions about directive compliance timelines and technology substitution elasticities. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Navigation and Communication
Airborne High Frequency Radio Market
Aircraft Navigation and Communication
Air Traffic Management Market
Aircraft Navigation and Communication
5G in Aviation Market
Aircraft Navigation and Communication
Asia-Pacific VHF Air-Ground Communication Stations Market
Aircraft Navigation and Communication
Air-Based Tactical Data Link Market
Aircraft Navigation and Communication
Global Air Traffic Control Equipment Market
Aircraft Navigation and Communication
Ground to Air on-Board Connectivity Market
Aircraft Navigation and Communication
Ultra Short Base Line Positioning System Market
Aircraft Navigation and Communication
Aviation Weather Radar Market
Aircraft Navigation and Communication
Airborne Radars Market
Aircraft Navigation and Communication
GPS and GNSS Receivers in Aviation Market
Aircraft Navigation and Communication
Air Traffic Control Market
Aircraft Navigation and Communication
Automatic Dependent Surveillance-Broadcast (ADS-B) Market
Aircraft Navigation and Communication
Digital Radiosonde Market
Aircraft Navigation and Communication
In Flight Connectivity Market
Aircraft Navigation and Communication
Global Flight Navigation System Market