
 Air Traffic Management Market | 2026-2036
Air Traffic Management Market Size, Share, and Industry Trends Forecast 2026-2036
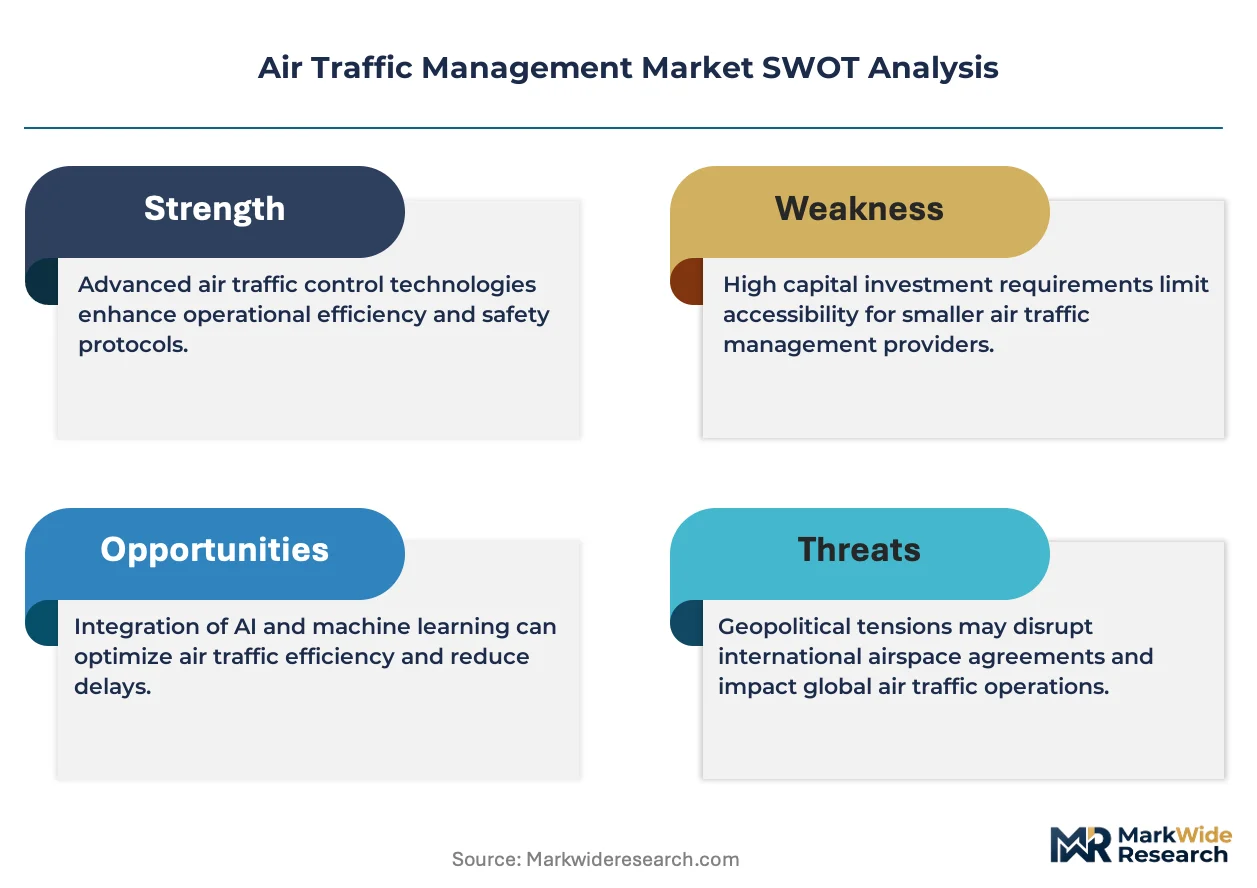
Air Traffic Management Market Analysis
Defense and civilian airport integration is realigning procurement priorities across the ATM sector. Thales Group leverages its dual-use surveillance portfolio to anchor European modernization programs while competing for Asia-Pacific digital tower contracts. RTX Corporation sustains long-term service relationships with the FAA and Pentagon through integrated communication-navigation systems. L3Harris Technologies specializes in remote tower and airport surface detection technologies, occupying a niche that differentiates it from full-platform rivals.
Air traffic management encompasses the ground-based and airborne systems that monitor, communicate with, and direct aircraft through controlled airspace using radar, ADS-B transponders, and VHF data links operating at 1030/1090 MHz. Its primary purpose is maintaining safe separation minima while optimizing route efficiency and fuel consumption across congested corridors. Surveillance Systems dominate capital expenditure as Mode S and multilateration upgrades replace aging primary radar, while Automation Systems represent the fastest-expanding margin pool as artificial intelligence-enabled conflict detection tools gain certification traction. Communication Systems remain mature with steady replacement cycles, though satellite-based VDL Mode 4 adoption is accelerating in oceanic airspace.
The FAA's NextGen roadmap and EUROCONTROL's Single European Sky ATM Research framework shape certification timelines and interoperability standards that vendors must satisfy for market access. EASA's cyber-resilience requirements for safety-critical aviation systems are forcing hardware and software suppliers to rearchitect product development pipelines. Stakeholders must monitor how China's civil aviation regulator harmonizes domestic GB standards with ICAO protocols as Beijing expands its ATM export footprint across Belt and Road aviation markets.
Market Dynamics
The FAA's NextGen mandate and EUROCONTROL's SESAR framework are forcing simultaneous upgrades across surveillance, communication, and automation layers, compressing procurement cycles while expanding vendor qualification requirements.
Growth Catalysts
- NextGen Infrastructure Mandate:The FAA's performance-based navigation requirements are accelerating ADS-B ground station deployments across congested US corridors, pulling demand for integrated surveillance platforms.
- Remote Tower Proliferation:Military-civilian airfield consolidation in Germany and Scandinavia is generating procurement volumes for camera-based surveillance and digital tower automation systems.
- GB Standard Harmonization:China's civil aviation regulator is aligning domestic certification protocols with ICAO Annex 10, enabling export-ready ATM system manufacturers to access Belt and Road aviation markets.
Market Restraints
- Long-Cycle Certification Friction:EASA's cyber-resilience requirements for safety-critical systems are extending hardware and software validation timelines by 18-24 months, freezing development roadmaps.
- Concentrated Sensor Supply:Precision radar components and specialized semiconductors for Mode S transponders rely on a limited supplier base concentrated in Germany and Japan, creating vulnerability to export control disruptions.
- Legacy System Interlock:Existing primary radar installations with 25-30 year service lives create technical debt that resists modular replacement, forcing parallel system operation and elevated maintenance overhead.
Strategic Opportunities
- AI-Enabled Conflict Detection:Machine learning algorithms for trajectory prediction and separation assurance are integrating with existing automation platforms, opening software-centric revenue streams beyond hardware replacement cycles.
- Oceanic Satellite Communications:VDL Mode 4 adoption over satellite links is creating demand for airborne and ground-based data link infrastructure in transatlantic and transpacific corridors where radar coverage terminates.
- Urban Air Mobility Integration:Low-altitude drone traffic management systems are emerging as a discrete procurement category as civil aviation authorities in the United States and United Arab Emirates establish regulatory frameworks for eVTOL operations.
Industry Challenges
- Systems Engineering Talent Scarcity:The intersection of radar physics, real-time software architecture, and aviation safety certification requires specialized expertise that outpaces university pipeline output.
- Multi-Stakeholder Coordination Complexity:ATM modernization demands synchronized deployment across military, commercial, and general aviation operators with divergent operational priorities and procurement timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Traffic Management Market |
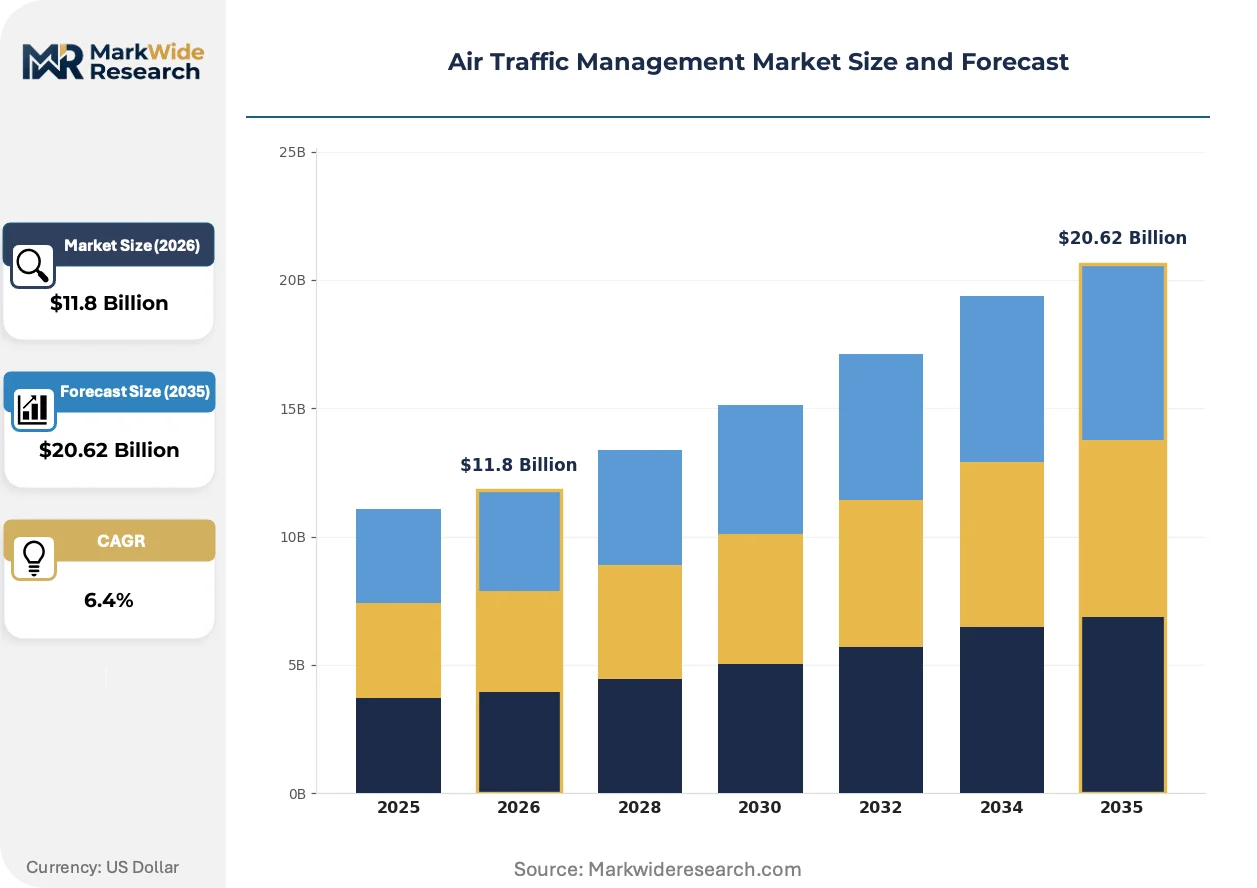
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Surveillance Systems, Communication Systems, Navigation Systems, Automation Systems Service Type: Consulting, Software Development, Hardware Provisioning, Training Services End User: Airports, Airlines, Government Agencies, Air Traffic Control Centers Application: Flight Planning, Airspace Management, Incident Management, Data Sharing |
| Companies Covered | Thales Group, RTX Corporation, L3Harris Technologies, Inc., Honeywell International Inc., Indra Sistemas, S.A., Raytheon Technologies Corporation, Northrop Grumman Corporation, BAE Systems plc, Frequentis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Traffic Management Market Emerging Trajectories
Digital infrastructure is displacing analog surveillance architectures while artificial intelligence migrates from experimental to certified operational status, restructuring vendor competitive advantages around software integration capabilities rather than hardware manufacturing scale.
Multilateration systems are integrating with Mode S secondary radar to create hybrid surveillance networks that reduce dependency on expensive primary radar installations while maintaining redundancy for safety-critical airspace. European ANSPs in Germany and the United Kingdom are deploying these configurations at regional airports with moderate traffic density. The structural consequence is compressing capital expenditure per surveillance node by 40-60 percent compared to conventional radar replacement.
EUROCONTROL's SESAR 3 Joint Undertaking is mandating interoperability standards that force legacy system obsolescence while creating certification pathways for new entrants. The industrial consequence is fragmenting procurement authority from national regulators to centralized EU bodies, consolidating vendor qualification requirements. ATM system manufacturers serving European markets are responding by establishing dedicated SESAR compliance engineering centers in Brussels and Toulouse.
Air navigation service providers are unbundling long-term service contracts from initial system procurement, separating hardware acquisition from software maintenance and air traffic controller training. This shift is disrupting traditional vendor lock-in models and enabling competitive re-bidding of service components at mid-contract intervals. The United States and Australia exhibit the most advanced adoption of this disaggregated procurement structure, with the FAA's System Engineering Services contracts establishing the template.
Air Traffic Management Market Segmentation
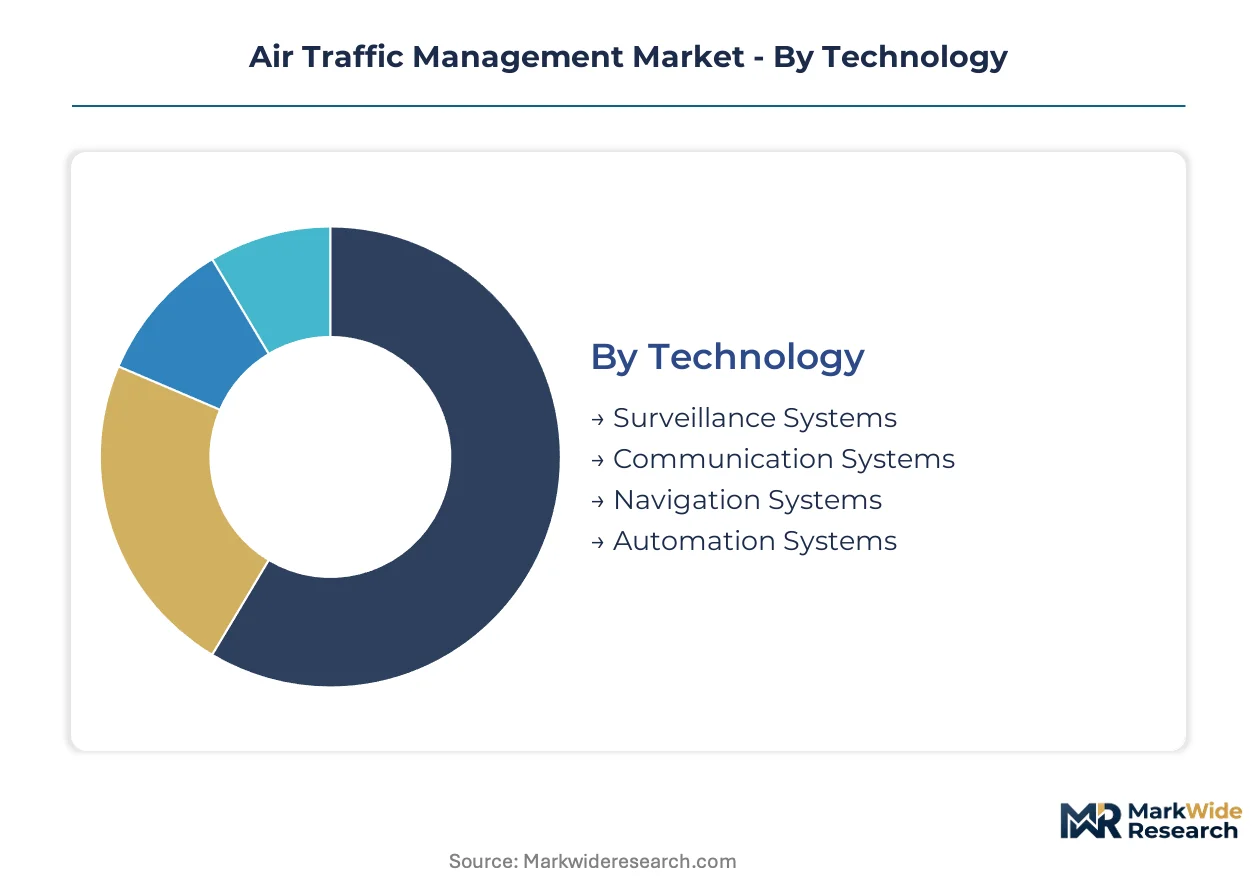
ATM procurement patterns diverge sharply across technology layers and service models, with certification requirements from the FAA, EASA, and China's CAAC dictating vendor qualification timelines. Segmentation reveals where capital concentrates versus where margin pools are expanding fastest.
Technology:
EASA's cyber-resilience requirements and FAA NextGen interoperability standards impose distinct validation burdens on each technology layer, with surveillance and automation systems facing the longest certification cycles.
- Surveillance Systems:Mode S secondary radar and multilateration networks form the backbone of ground-based aircraft tracking, replacing aging primary radar installations. Demand concentrates in Germany and the United States where ANSPs modernize congested corridor coverage under NextGen and SESAR mandates. EASA's hardware validation timelines extend 18-24 months for new sensor deployments.
- Automation Systems:AI-enabled conflict detection and trajectory prediction software integrate with existing controller workstations. Airlines and ANSPs in China and the United States drive adoption as fuel optimization pressures intensify. Certification pathways remain fluid as regulators adapt safety frameworks for machine-learning decision support.
- Communication Systems:VHF ground stations and satellite-based VDL Mode 4 data links serve oceanic and remote airspace where radar coverage terminates.
- Navigation Systems:Ground-based augmentation systems and GNSS integrity monitoring support performance-based navigation approaches.
Surveillance Systems sit at the top of the volume ranking, with Automation Systems climbing the fastest.
Service Type:
Procurement disaggregation is separating hardware acquisition from long-term service commitments, reshaping contract structures across mature and emerging aviation markets.
- Software Development:Custom automation platforms and middleware integration for ANSP-specific workflows. Germany and Australia lead in competitive re-bidding of software maintenance contracts at mid-cycle intervals.
- Hardware Provisioning:Radar arrays, transponders, and ground station infrastructure with 15-25 year service lives. Supply concentrates among German and Japanese precision sensor manufacturers vulnerable to export control disruptions.
- Consulting:System integration and SESAR compliance engineering for European modernization programs.
- Training Services:Controller certification for digital tower and remote surveillance operations.
Hardware Provisioning dominates contract value, though Software Development is gaining share fastest as AI-enabled tools proliferate.
End User:
Military-civilian airfield consolidation and commercial fleet expansion are diverging procurement priorities across user categories.
- Air Traffic Control Centers:National ANSPs in the United States, Germany, and China deploy integrated surveillance-communication-automation stacks. FAA System Engineering Services contracts and EUROCONTROL's centralized procurement fragment traditional vendor lock-in models.
- Airports:Regional facilities in Scandinavia and Germany adopt camera-based remote towers to consolidate military-civilian operations. Capital expenditure per surveillance node compresses 40-60 percent versus conventional radar.
- Government Agencies:Defense and homeland security coordination requirements for dual-use airspace management.
- Airlines:Flight deck connectivity and operational control center integration for fleet-wide trajectory optimization.
Air Traffic Control Centers anchor procurement volume, while Airports represent the steepest expansion trajectory as remote tower adoption accelerates.
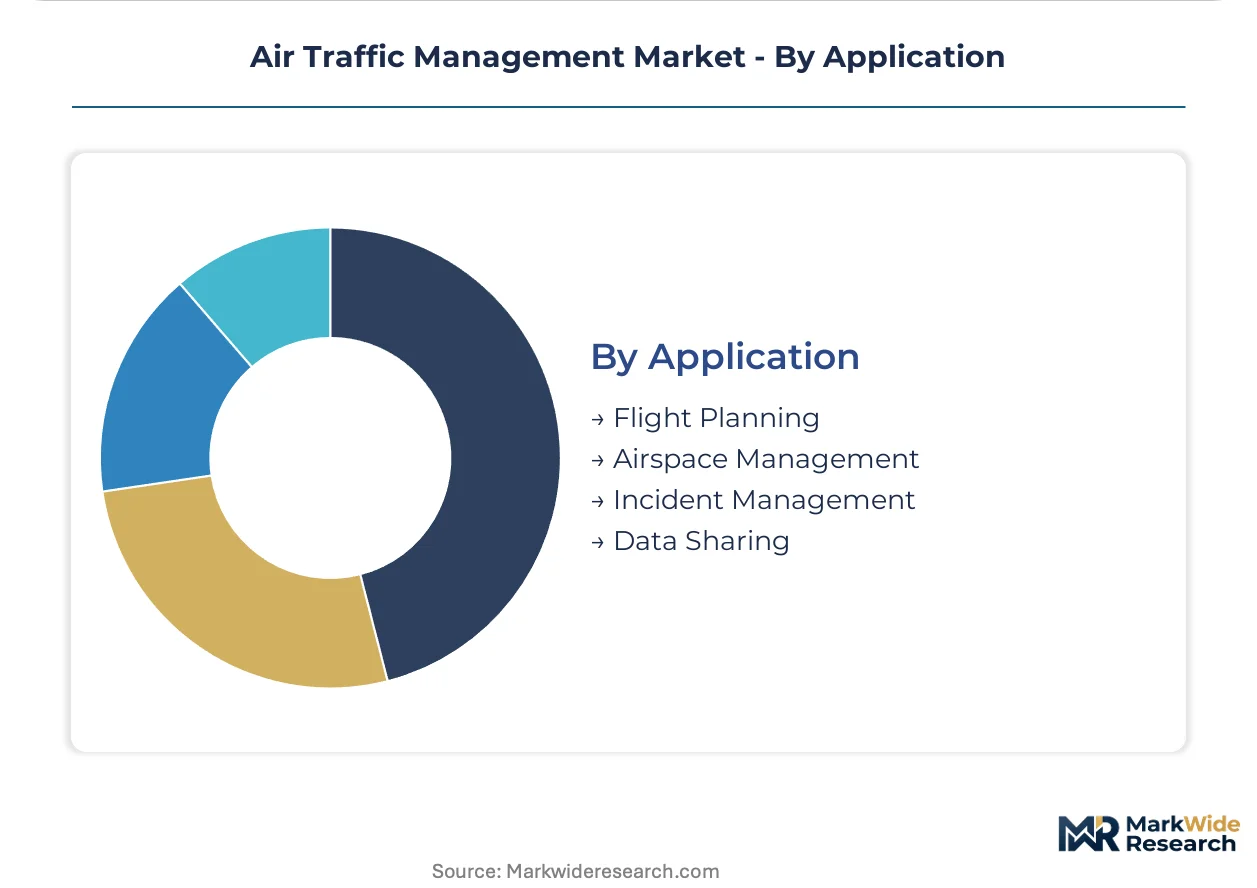
Application:
Functional requirements map directly to regulatory mandates, with data interoperability standards forcing architectural decisions across deployment architectures.
- Airspace Management:Sectorization, flow management, and dynamic route optimization across congested corridors. EUROCONTROL's SESAR 3 Joint Undertaking mandates interoperability standards that accelerate legacy obsolescence in European markets.
- Flight Planning:Pre-departure trajectory optimization and continuous descent approach programming. China's CAAC alignment with ICAO Annex 10 enables domestic manufacturers to export across Belt and Road aviation markets.
- Incident Management:Emergency response coordination and weather deviation protocols.
- Data Sharing:SWIM-compliant information exchange between ANSPs, airlines, and airports.
Airspace Management commands the largest installed base, with Flight Planning expanding most quickly as performance-based navigation mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping procurement flows as vendors relocate engineering centers to jurisdictions with streamlined certification pathways. The FAA's NextGen mandate and EASA's cyber-resilience requirements create divergent compliance cost structures that influence where ATM system development concentrates.
United States
The FAA's System Engineering Services contracts and NextGen infrastructure rollout drive sustained procurement volume for integrated surveillance-communication platforms. Performance-based navigation requirements accelerate ADS-B ground station deployments across congested corridors. Engineering activity clusters around Washington DC metro and Dallas-Fort Worth, where ANSP modernization programs and defense-civilian coordination requirements intersect.
Germany
Military-civilian airfield consolidation and SESAR 3 Joint Undertaking compliance generate demand for remote tower and digital surveillance systems. EASA's hardware validation timelines extend development cycles for new sensor deployments. Industrial concentration centers on Munich and Hamburg, where ANSPs deploy hybrid multilateration-Mode S networks at regional airports to compress capital expenditure per surveillance node.
China
CAAC alignment of domestic GB standards with ICAO Annex 10 enables export-ready manufacturers to access Belt and Road aviation markets. Commercial fleet expansion and airspace congestion in eastern corridors pull investment in automation and surveillance infrastructure. Development activity concentrates in Beijing and Shanghai, where state-owned aviation enterprises coordinate ATM system integration for domestic and export programs.
United Kingdom
NATS modernization programs and post-Brexit regulatory autonomy create distinct certification requirements for ATM system vendors. Remote tower adoption at regional airports reduces dependency on conventional radar replacement. Engineering clusters in London and Southampton focus on SESAR interoperability compliance and digital tower automation for European and Commonwealth export markets.
Australia
Airservices Australia's procurement disaggregation models separate hardware acquisition from long-term service contracts, establishing templates competitive rebidding structures. Vast oceanic airspace drives satellite-based VDL Mode 4 adoption for trans-Pacific corridor coverage. System integration activity concentrates in Melbourne and Brisbane, where ANSPs pioneer competitive service contract structures that disrupt traditional vendor lock-in models.
Air Traffic Management Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-platform integrators commanding surveillance-automation stacks while niche players capture remote tower and surface detection niches. The vendor base organizes around three strategic archetypes: dual-use defense contractors leveraging military-civilian synergies, pure-play ATM specialists with SESAR compliance depth, and diversified aerospace conglomerates with integrated communication-navigation portfolios. Consolidation pressure intensifies as procurement disaggregation forces vendors to defend service revenue streams separately from hardware margins, while technology licensing partnerships proliferate to address systems engineering talent scarcity.
Among European dual-use specialists, Thales Group and Indra Sistemas occupy positions that exemplify the defense-civilian integration archetype, anchoring SESAR modernization programs through surveillance portfolio breadth. RTX Corporation and L3Harris Technologies represent the integrated systems tier, with the former sustaining long-term service relationships with the FAA and the latter specializing in remote tower technologies that differentiate from full-platform rivals. These three companies illustrate how competitive positioning stratifies between comprehensive platform coverage and targeted specialization.
| Leading Market Players |
|---|
| Thales Group |
| RTX Corporation |
| L3Harris Technologies, Inc. |
| Honeywell International Inc. |
| Indra Sistemas, S.A. |
| Raytheon Technologies Corporation |
| Northrop Grumman Corporation |
| BAE Systems plc |
| Frequentis AG |
| Others |
Supply Flow & Price Mechanics
National ANSP procurement programs in the United States, Germany, and China anchor contract structures around long-term service bundling rather than transactional hardware sales, compressing upfront margins while extending revenue visibility across 15-25 year system lifecycles. This buyer concentration forces vendors to absorb certification and cyber-resilience compliance costs within fixed-price frameworks.
Pricing Analysis
Direct-to-ANSP contracting with minimal distributor markup dominates the channel structure, though systems integrators capture 8-12 percent margin layers for SESAR compliance engineering and installation supervision. Pricing stratifies across FAA-certified, EASA-certified, and CAAC-aligned tiers, with dual-use defense contractors commanding premiums for military-civilian interoperability. Cost compression in remote tower deployments is intensifying because camera-based surveillance achieves 40-60 percent capital expenditure reduction versus conventional radar. Regional airports in Scandinavia and Germany exhibit the highest price sensitivity due to constrained municipal budgets, while Pentagon and FAA System Engineering Services contracts demonstrate lowest sensitivity given mission-critical requirements.
Supply Chain Analysis
Regional distribution centers in Brussels and Toulouse coordinate component flows for European SESAR compliance programs, with satellite engineering clusters in Washington DC and Beijing managing Americas and Asia-Pacific deployments. Precision radar components and Mode S transponder semiconductors draw from concentrated manufacturing bases in Germany and Japan, creating single-source vulnerability for specialized sensor arrays. Supply chain risk centers on export control disruptions for dual-use surveillance technologies subject to ITAR and EU dual-use regulations. Distribution runs through ANSP-direct procurement with long-term service contracts unbundled from initial hardware acquisition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Air Traffic Management Market functions as a stable compounder sustained by regulatory mandates that force systematic infrastructure refresh cycles regardless of commercial aviation cyclicality. FAA NextGen and EUROCONTROL SESAR frameworks ensure predictable procurement pipelines across decades-long modernization roadmaps.
For Market Incumbents: Anchor service revenue streams through competitive re-bidding of software maintenance contracts at mid-cycle intervals, disrupting traditional vendor lock-in models that competitors exploit. Deepen backward integration into precision sensor manufacturing to mitigate single-source dependencies on German and Japanese semiconductor suppliers. Invest in SESAR 3 Joint Undertaking compliance engineering centers in Brussels and Toulouse to defend European market access against emerging pure-play automation specialists. For New Entrants and Emerging Players: AI-enabled conflict detection algorithms offer the most penetrable wedge for software-centric entrants lacking radar manufacturing heritage. Target remote tower and airport surface detection niches where L3Harris Technologies has established differentiation templates but full-platform rivals underinvest. Pursue CAAC certification alignment for Belt and Road export markets where Chinese state-owned aviation enterprises seek cost-competitive alternatives to Western surveillance stacks. For Investors and Strategic Acquirers: Defense contractors with dual-use surveillance portfolios are the most active acquirer in this space, consolidating ATM specialists to capture military-civilian airfield consolidation opportunities. Long-term viability rests on 5-10 year service contract visibility rather than hardware replacement cyclicality. Monitor EASA cyber-resilience certification timelines as the critical inflection signal—vendors with validated hardware-software pipelines will capture disproportionate share as validation bottlenecks freeze competitor roadmaps.| Strategic Initiative | Industry Significance |
|---|---|
| SESAR Compliance Engineering Center Establishment | EUROCONTROL's centralized procurement authority fragments national vendor qualification requirements across European ANSPs. |
| AI-Enabled Conflict Detection Certification | FAA and EASA safety frameworks for machine-learning decision support remain fluid, creating first-mover certification advantages. |
| Remote Tower Technology Acquisition | German and Scandinavian military-civilian airfield consolidation generates procurement volumes for camera-based surveillance systems. |
| VDL Mode 4 Satellite Infrastructure Partnership | Oceanic airspace beyond radar coverage drives demand for transatlantic and transpacific data link deployments. |
| CAAC GB Standard Harmonization Investment | China's alignment with ICAO Annex 10 enables export-ready manufacturers to access Belt and Road aviation markets. |
Methodological Framework
Multiple input streams — primary interviews with ANSP procurement directors, FAA program managers, and EASA certification engineers; secondary validation against EUROCONTROL SESAR documentation, FAA NextGen budget justifications, and ICAO Annex 10 harmonization protocols; plus customs and trade data for precision sensor component flows — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured operational requirements from air traffic controllers, system integration specialists, and defense-civilian coordination officers across the United States, Germany, China, and Australia. Secondary sources included national aviation authority procurement databases, ANSP annual reports, and industry association technical standards filings.
Historical deployment trajectories were cross-referenced against panel input from ANSP modernization program directors to construct analytical frameworks across the projection horizon. Segmentation dimensions modeled encompass technology layer (surveillance, automation, communication, navigation), service type (software development, hardware provisioning, consulting, training), end user (air traffic control centers, airports, government agencies, airlines), and application (airspace management, flight planning, incident management, data sharing). CAGRs were derived from installed base replacement cycles, regulatory mandate deadlines, and fleet expansion projections. Industry-specific forecast inputs incorporated ADS-B ground station deployment schedules and remote tower adoption curves.
The model holds under stable regulatory mandate enforcement and sustained defense-civilian coordination requirements; deviation in export control regimes or certification timeline extensions would shift vendor competitive positioning and procurement pacing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Navigation and Communication
Aircraft Navigation Software Market
Aircraft Navigation and Communication
Helicopter Meteorological Software Market
Aircraft Navigation and Communication
Military Navigation Systems Market
Aircraft Navigation and Communication
Aircraft Communication System Market
Aircraft Navigation and Communication
In Flight Connectivity Market
Aircraft Navigation and Communication
Aviation Weather Radar Market
Aircraft Navigation and Communication
Connected Aircraft Market
Aircraft Navigation and Communication
Aircraft Turn Coordinator Market
Aircraft Navigation and Communication
Electronic Navigational Charts (ENC) Market
Aircraft Navigation and Communication
Automatic Dependent Surveillance-Broadcast (ADS-B) Market
Aircraft Navigation and Communication
Airborne Telemetry Market
Aircraft Navigation and Communication
Asia-Pacific Air Traffic Management Market
Aircraft Navigation and Communication
Global Aviation Mapping Software Market
Aircraft Navigation and Communication
Europe Inertial Systems Market
Aircraft Navigation and Communication
Airborne Situational Awareness Systems Market
Aircraft Navigation and Communication
5G in Aviation Market