
 Electronic Navigational Charts (ENC) Market | 2026-2036
Electronic Navigational Charts (ENC) Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Navigational Charts (ENC) Market Foresight
Leasing-based subscription models for ENC data licensing is rewriting capital requirements for fleet-wide digital chart compliance. Kongsberg Maritime leverages its integrated bridge systems to bundle ENC updates with bridge hardware contracts. Garmin competes through consumer-facing chartplotter ecosystems that extend into recreational ENC distribution. Jeppesen anchors professional aviation-grade data quality standards into its maritime chart offerings.
Electronic Navigational Charts are digital vector or raster representations of hydrographic information conforming to IHO S-57 and S-101 standards, designed for safe marine navigation through GPS-referenced bathymetric and obstacle data. Vector ENC dominates commercial shipping procurement due to scalable object-oriented query capabilities and automatic alert generation, while raster overlay retains utility in legacy ECDIS retrofit installations where hardware constraints persist. Commercial shipping application segments command the deepest margin pools through multi-year fleet licensing agreements, whereas recreational boating exhibits faster volume expansion through app-based distribution channels.
The International Hydrographic Organization sets ENC production and distribution standards that determine market access for chart providers, while national maritime regulators in major flag states enforce ECDIS carriage mandates that directly stimulate replacement demand. Port state control inspections under Paris MoU and Tokyo MoU frameworks create compliance-driven purchasing cycles that reduce sales cycle variability. Stakeholders must monitor the IHO S-100 framework transition timeline to assess whether early migration investments yield competitive differentiation or stranded data assets.
Market Dynamics
The Electronic Navigational Charts market is restructuring around the IHO S-100 framework transition, which forces chart providers to rebuild data architectures while maintaining backward compatibility with installed ECDIS bases.
Growth Catalysts
- IMO ECDIS Carriage Mandates:The International Maritime Organization's phased compliance deadlines for SOLAS vessels are compressing replacement cycles and forcing fleet-wide upgrades across commercial shipping operators.
- Port State Control Intensification:Tokyo MoU and Paris MoU inspection regimes in Singapore, Rotterdam, and Shanghai are elevating detention risks for non-compliant vessels, converting regulatory fear into procurement urgency.
- Container Traffic Concentration:East Asian hub ports handling transshipment volumes are driving concentrated demand for high-resolution ENC coverage and real-time update services.
Market Restraints
- Hydrographic Survey Input Constraints:Multibeam sonar vessel charter rates and skilled hydrographer scarcity are limiting raw data refresh frequencies for remote archipelagic routes.
- National Hydrographic Office Concentration:Primary ENC source data remains captive to government monopolies in coastal states, constraining private-sector value-add differentiation.
- Legacy Raster Dependency:Raster Chart Display Systems retain regulatory acceptance for specific vessel classes, slowing pure-vector ECDIS penetration in certain flag-state fleets.
Strategic Opportunities
- Autonomous Vessel Navigation:Maritime autonomous surface ships require machine-readable ENC formats with embedded semantic layers, opening premium data architecture contracts.
- Recreational App Distribution:Smartphone-based chartplotter applications are penetrating leisure boating segments previously unserved by professional ECDIS channels.
- S-100 Framework Early Migration:First-mover chart providers capturing IHO S-100 certification ahead of mandatory transition windows can lock in long-term fleet data contracts.
Industry Challenges
- Hydrographic Data Scientist Scarcity:The intersection of geospatial information systems expertise and maritime domain knowledge commands salary premiums that strain mid-tier provider margins.
- Cross-Flag Certification Complexity:Vessels operating under multiple flag-state registrations face divergent ECDIS type-approval requirements that fragment product development roadmaps.
- Legacy System Integration Friction:Bridge hardware refresh cycles decoupled from ENC data license renewals create misaligned procurement negotiations and revenue recognition challenges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Navigational Charts (ENC) Market |
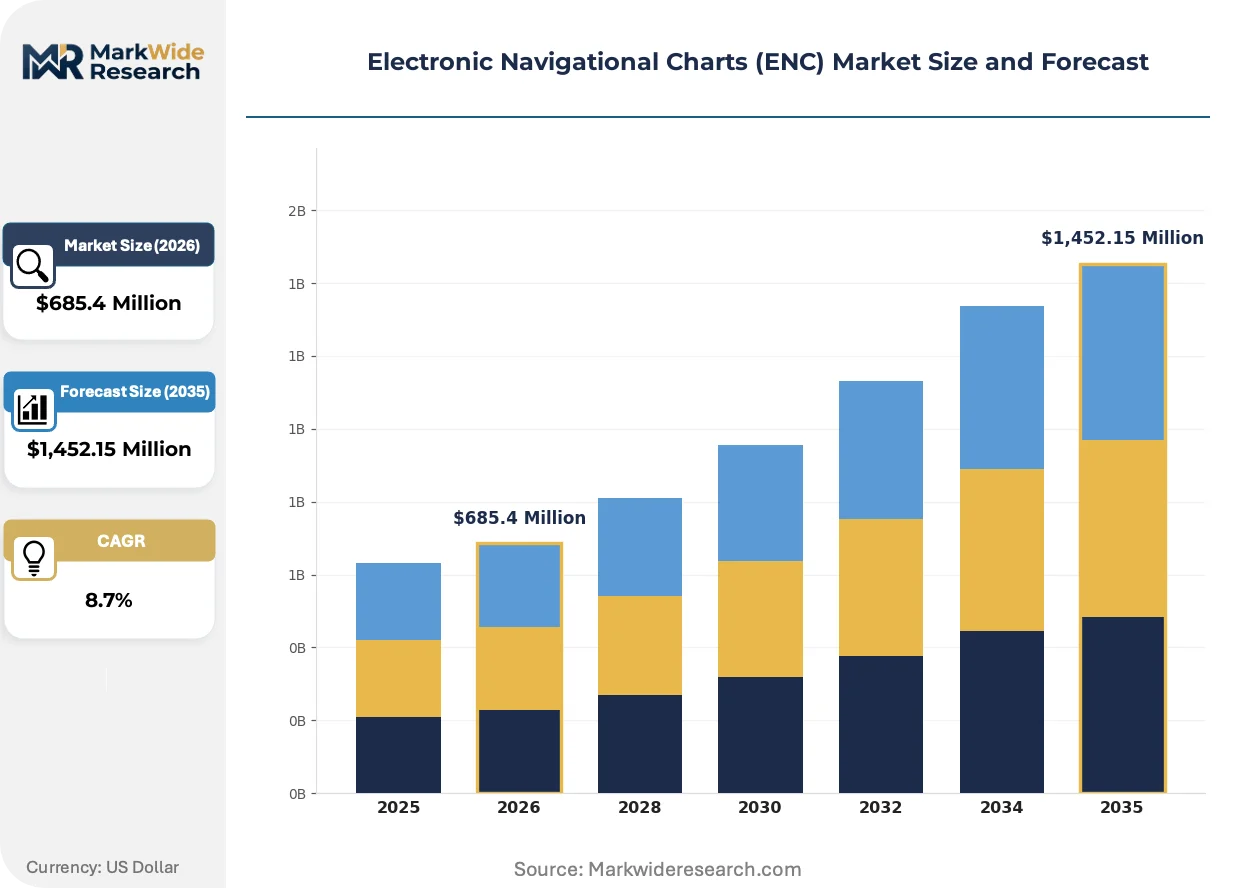
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raster ENC, Vector ENC, Hybrid ENC, Raster Overlay, Digital Paper Chart Technology: GPS Integration, AIS Support, Radar Overlay, Automatic Positioning, Real-Time Updates Application: Commercial Shipping, Offshore Operations, Coastal Navigation, Research Vessels, Recreational Boating End User: Ship Operators, Marine Surveyors, Defense Agencies, Environmental Monitoring, Port Authorities |
| Companies Covered | Kongsberg Maritime, Garmin, Navionics, ChartCo, OceanWise, Jeppesen, Furuno Electric, Wärtsilä Corporation, C-MAP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Navigational Charts (ENC) Market Shifts & Advancements
Three intersecting forces are compressing the Electronic Navigational Charts value chain: real-time data architectures, regulatory framework migration, and procurement model unbundling.
Cloud-native ENC distribution infrastructure is digitizing the update delivery mechanism that historically relied on physical media exchange or satellite broadcast windows. Major container lines operating Singapore-anchored fleets are adopting continuous synchronization protocols that push chart corrections within hours of hydrographic office publication. This compression of the update cycle is digitizing competitive differentiation away from static coverage breadth toward dynamic data freshness guarantees.
EU Maritime Spatial Planning Directive implementation is mandating interoperable marine data layers that extend beyond traditional bathymetric ENC content to include seabed substrate and ecological sensitivity overlays. North Sea and Baltic route operators face new compliance obligations that require enhanced ENC products with integrated environmental data streams. Commercial shipping segments transiting Rotterdam and Hamburg corridors are responding by specifying S-100-compatible systems in newbuild vessel contracts.
Fleet managers are unbundling ENC procurement from integrated bridge system packages, creating standalone data licensing negotiations that pit specialized chart providers against hardware OEM captive offerings. Container shipping lines with centralized technical management functions are consolidating ENC purchasing across vessel pools to extract volume-based pricing concessions. This behavioral shift is most visible among Asia-Pacific headquartered operators managing mixed-flag fleets from Singapore and Hong Kong technical hubs.
Electronic Navigational Charts (ENC) Market Segmentation
ENC procurement patterns diverge sharply across vessel classes and operational profiles. Fleet managers weight update frequency against hardware compatibility when selecting product formats. Defense and environmental end users impose distinct certification requirements that fragment supplier positioning.
Product Type:
Cost tier differentiation separates professional ECDIS-grade formats from legacy-compatible alternatives and emerging hybrid architectures.
- Vector ENC:Object-oriented data structures enable scalable query functions and automatic alert generation for obstacle proximity. Commercial shipping lines operating Singapore and Rotterdam corridors specify vector formats for fleet-wide ECDIS compliance under IMO carriage mandates.
- Raster ENC:Pixel-based chart images mirror traditional paper chart appearances for bridge crew familiarity. Legacy vessel retrofits in flag states with extended compliance windows sustain demand where hardware constraints block full vector migration.
- Hybrid ENC:Dual-layer architectures combine vector query capabilities with raster visual reference for transitional ECDIS installations.
- Raster Overlay:Supplementary display layer superimposes raster detail atop primary vector bases for situational awareness enhancement.
- Digital Paper Chart:Static PDF-equivalent outputs serve backup navigation requirements without dynamic positioning integration.
Vector ENC commands the established base. The steepest expansion runs through Hybrid ENC as fleet operators navigate S-100 framework transitions.
Technology:
Functional integration depth determines pricing tiers and hardware bundling negotiations across bridge system architectures.
- GPS Integration:Satellite positioning correlation with chart datum enables real-time vessel tracking against ENC waypoints. Container lines with Singapore-anchored technical management mandate GPS-referenced systems for transshipment route precision.
- Real-Time Updates:Continuous data synchronization protocols compress correction delivery from satellite broadcast cycles to hours. Major operators transiting Shanghai and Busan corridors specify real-time capability for high-traffic waterway safety management.
- AIS Support:Automatic Identification System overlay correlates vessel traffic data with ENC obstacle layers.
- Radar Overlay:Sensor fusion projects radar returns onto chart displays for collision avoidance verification.
- Automatic Positioning:Dead reckoning algorithms maintain track continuity during GPS signal degradation.
GPS Integration anchors current procurement specifications. Real-Time Updates are climbing the fastest as cloud distribution infrastructure matures.
Application:
Operational intensity and regulatory exposure create divergent margin structures across vessel deployment categories.
- Commercial Shipping:SOLAS-regulated cargo and passenger vessels drive mandatory ECDIS replacement cycles through IMO compliance deadlines. Multi-year fleet licensing agreements with Asia-Pacific headquartered operators concentrate revenue in this segment.
- Recreational Boating:Leisure craft operators access ENC through smartphone chartplotter applications at price points below professional ECDIS channels. Mediterranean and Caribbean charter fleets are gaining share fastest through app-based distribution.
- Offshore Operations:Oil and gas platform supply vessels require high-resolution bathymetry for dynamic positioning operations.
- Coastal Navigation:Short-sea shipping and pilotage services demand frequent update cycles for near-shore hazard management.
- Research Vessels:Scientific expedition operators specify customizable data layers beyond standard ENC content.
Commercial Shipping retains volume concentration. Recreational Boating shows the steepest expansion trajectory as consumer-facing platforms democratize access.
End User:
Procurement authority centralization versus fragmentation shapes contract negotiation dynamics and sales cycle duration.
- Ship Operators:Technical departments at container lines and bulk carriers consolidate ENC purchasing across mixed-flag fleets. Singapore and Hong Kong headquartered managers extract volume pricing through centralized technical management functions.
- Port Authorities:Harbor master offices specify ENC coverage standards for pilotage services and vessel traffic management. Rotterdam and Hamburg port authorities are mandating S-100-compatible systems for newbuild vessel calls.
- Defense Agencies:Naval hydrographic offices impose security-cleared data handling and encrypted distribution protocols.
- Marine Surveyors:Independent certification bodies require ENC access for vessel condition and compliance auditing.
- Environmental Monitoring:Regulatory agencies overlay ENC bathymetry with ecological sensitivity data for maritime spatial planning.
Ship Operators dominate contract value. Port Authorities are gaining share fastest as EU Maritime Spatial Planning Directive implementation expands their data specification authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
IMO ECDIS carriage mandates and port state control intensification are redrawing procurement patterns across coastal economies. Flag-state enforcement windows and transshipment traffic volumes determine where ENC providers concentrate licensing negotiations.
Singapore
Container traffic through the Port of Singapore exceeds 37 million TEU annually, creating concentrated demand for real-time ENC updates. The Maritime and Port Authority enforces strict ECDIS compliance during vessel inspections, elevating detention risks for non-compliant operators. Technical management hubs clustered around Tanjong Pagar coordinate fleet-wide ENC licensing for Asia-Pacific headquartered container lines.
Netherlands
Rotterdam's status as Europe's largest port drives mandatory S-100 framework adoption for vessels calling Dutch terminals. The EU Maritime Spatial Planning Directive requires integrated environmental data layers in ENC products for North Sea route operators. Maritime service providers concentrated in the Rotterdam-Rijnmond corridor are consolidating ENC procurement across short-sea shipping fleets.
Japan
The Ministry of Land, Infrastructure, Transport and Tourism mandates ECDIS carriage for domestic coastal vessels under revised maritime safety regulations. Tokyo MoU port state control inspections in Yokohama and Kobe elevate compliance urgency for regional operators. Hydrographic Office data production in Tsukuba supplies raw ENC source material for East Asian distribution networks.
United States
The US Coast Guard enforces ECDIS compliance through Port State Control examinations in Los Angeles, Long Beach, and Houston. NOAA's Office of Coast Survey maintains primary ENC source data authority, constraining private-sector value-add differentiation. Maritime technology clusters in Seattle and Norfolk host bridge system integrators bundling ENC updates with hardware contracts.
Germany
The Federal Maritime and Hydrographic Agency enforces S-100 migration timelines for vessels registered under German flag. Hamburg and Bremen port authorities specify high-resolution ENC coverage standards for Elbe River pilotage services. Ship operators concentrated in the Northern German maritime corridor are unbundling ENC procurement from integrated bridge packages.
Electronic Navigational Charts (ENC) Market Competitive Landscape
On the supply side, the industry is consolidating around integrated bridge system OEMs and specialized chart data providers. Tiered competitive positioning separates hardware-bundled offerings from standalone data licensing specialists. Strategic archetypes include full-stack bridge integrators, pure-play ENC data specialists, and consumer-facing recreational chart distributors. Dominant competitive moves encompass S-100 framework early certification capture and fleet-wide multi-year licensing consolidation.
Among Nordic integrated system providers, Kongsberg Maritime and Wärtsilä Corporation exemplify the hardware-anchored archetype leveraging bridge equipment contracts to bundle ENC update services. Garmin occupies a distinct position within consumer-facing recreational distribution, extending smartphone chartplotter ecosystems into leisure boating segments previously unserved by professional ECDIS channels. Jeppesen represents the aviation-grade data quality standard-bearer migrating professional certification rigor into maritime chart offerings.
| Leading Market Players |
|---|
| Kongsberg Maritime |
| Garmin |
| Navionics |
| ChartCo |
| OceanWise |
| Jeppesen |
| Furuno Electric |
| Wärtsilä Corporation |
| C-MAP |
| Others |
Supply & Pricing Matrix
Overcapacity in multibeam sonar vessel fleets across the North Sea and Baltic corridors is compressing hydrographic survey charter rates, forcing ENC providers to absorb data acquisition cost volatility while maintaining subscription pricing discipline for fleet customers.
Pricing Analysis
Certification level creates the primary spread between professional ECDIS-grade and recreational chartplotter tiers. Three-tier pricing structure across premium, standard, and economy levels segments by update frequency, coverage resolution, and hardware integration depth. Cost compression in the recreational tier is intensifying because smartphone app distribution eliminates hardware bundling premiums. Commercial shipping lines exhibit the lowest price sensitivity due to detention risk exposure under Tokyo MoU and Paris MoU regimes.
Supply Chain Analysis
Raw hydrographic data feeds from government monopolies in the United Kingdom, Norway, and Japan constrain private-sector differentiation. Multibeam sonar surveys, satellite-derived bathymetry, and crowd-sourced depth soundings constitute the input base. Single-source vulnerability runs through national hydrographic office licensing terms that can abruptly restrict redistribution rights. Distribution runs through cloud-native synchronization protocols replacing physical media exchange.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open-source chartplotter alternatives and crowd-sourced bathymetry platforms threaten to commoditize recreational ENC tiers, forcing incumbents to defend professional-grade certification moats.
For Market Incumbents: Entrench S-100 framework certification leadership through early IHO compliance investment ahead of mandatory transition windows. Lock in multi-year fleet licensing with Asia-Pacific technical management hubs in Singapore and Hong Kong. Capture backward integration into real-time update infrastructure to neutralize cloud-native distribution entrants. For New Entrants and Emerging Players: Pursue recreational boating white-space through smartphone-native chartplotter applications with offline functionality for Mediterranean and Caribbean charter fleets. Target coastal navigation segments underserved by professional ECDIS channels. Lead with app store distribution partnerships that bypass hardware OEM gatekeepers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native ENC distribution as server infrastructure replaces physical media replication. Favor acquisition targets with IHO S-100 certification progress and established national hydrographic office data licensing relationships. Monitor Tokyo MoU and Paris MoU detention statistics as compliance urgency inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| S-100 Framework Early Certification | IHO compliance ahead of mandatory windows locks in fleet contract renewals. |
| Cloud-Native Distribution Infrastructure | Continuous synchronization protocols compress update cycles from weeks to hours. |
| National Hydrographic Office Licensing | Exclusive data partnerships with UKHO or NOAA constrain competitor coverage breadth. |
| Recreational App Store Distribution | Consumer-facing platforms penetrate leisure segments below ECDIS price floors. |
| Real-Time Update Service Tier | Premium subscriptions for Singapore and Rotterdam corridor operators deepen retention. |
Research Methodology
Operator-level perspectives from fleet technical managers, bridge system integrators, hydrographic office licensing directors, and port state control inspectors anchored the qualitative base. Primary interviews combined with secondary validation against IHO S-57 and S-101 standards documentation, IMO SOLAS carriage mandate texts, and Tokyo MoU annual detention reports. Bottom-up vessel fleet segmentation triangulated against top-down hydrographic office production capacity estimates.
Scenario-bracketing framed low, base, and high cases across the projection horizon without year-specific anchors. Segmentation dimensions modeled include product format, application vessel class, technology integration depth, and regional flag-state enforcement intensity. CAGRs derived from fleet replacement cycle analysis against ECDIS compliance deadline phasing. Forecast inputs incorporated multibeam sonar vessel charter rate trajectories and container traffic volume projections through East Asian hub ports.
Sensitivities concentrate around IHO S-100 transition timeline acceleration, national hydrographic office licensing term changes, and autonomous vessel regulatory framework emergence. Forecasts reflect documented assumptions on fleet compliance behavior and hardware refresh coupling. Cross-checking against Lloyd's List vessel inspection detention databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Navigation and Communication
Military Navigation Systems Market
Aircraft Navigation and Communication
Connected Aircraft Market
Aircraft Navigation and Communication
Digital Radiosonde Market
Aircraft Navigation and Communication
Ground to Air on-Board Connectivity Market
Aircraft Navigation and Communication
Asia-Pacific VHF Air-Ground Communication Stations Market
Aircraft Navigation and Communication
Airborne High Frequency Radio Market
Aircraft Navigation and Communication
Europe Air Traffic Management Market
Aircraft Navigation and Communication
Global Flight Navigation System Market
Aircraft Navigation and Communication
Airborne Telemetry Market
Aircraft Navigation and Communication
Aircraft Communication System Market
Aircraft Navigation and Communication
Middle-East and Africa Air Traffic Management Market
Aircraft Navigation and Communication
Air Traffic Management Software Market
Aircraft Navigation and Communication
Helicopter Meteorological Software Market
Aircraft Navigation and Communication
GPS and GNSS Receivers in Aviation Market
Aircraft Navigation and Communication
America Air Traffic Management Market
Aircraft Navigation and Communication
Global Air Traffic Control Equipment Market