
 Military Navigation Systems Market | 2026-2036
Military Navigation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Military Navigation Systems Market Foresight
A widening capability gap between prime contractors and mid-tier suppliers is unwinding traditional procurement hierarchies in military navigation. Northrop Grumman Corporation leverages its satellite payload heritage to dominate GPS III follow-on contracts. Safran SA anchors European sovereign PNT programs through hybrid inertial-satellite architectures.
Military navigation systems integrate gyroscopes, accelerometers, and radio-frequency receivers to compute position, velocity, and attitude under contested electromagnetic conditions, typically achieving circular error probabilities below ten meters even with degraded satellite access. Inertial Technology leads product type revenue due to submarine and strategic aircraft reliance on self-contained guidance, while Hybrid Systems represent the fastest-expanding technology segment as operators demand seamless failover between satellite and terrestrial references. Aircraft Navigation applications command premium pricing because fighter and bomber platforms require certified anti-jam waveform processing.
The U.S. Department of Defense mandates PNT resilience standards that compel vendors to demonstrate multi-constellation reception and alternative navigation readiness, while the EU's MDR and CE marking frameworks shape transatlantic component interoperability for NATO-interoperable systems. The FAA and EASA jointly influence military-civil dual-use certification pathways for transport and tanker platforms. Stakeholders must monitor evolving electronic warfare threats to decide between open-architecture upgrade investments and platform-specific proprietary solutions.
Market Dynamics
Assured positioning, navigation, and timing resilience mandates are restructuring contractor obligations across defense procurement, forcing vendors to demonstrate multi-constellation reception and alternative navigation readiness under contested electromagnetic conditions.
Growth Catalysts
- U.S. DoD PNT Resilience Directives:Congressional defense appropriations prioritize anti-jam capabilities across joint force operations, compelling platform upgrades for fighter and bomber fleets.
- Submarine Self-Contained Guidance:Inertial technology demand accelerates as strategic underwater platforms require navigation independence from satellite signals.
- NATO Interoperability Standards:Member state procurement of jam-resistant suites for aerial and maritime platforms drives harmonized certification pathways.
Market Restraints
- Strategic Material Concentration:Precision gyroscope manufacturing depends on rare earth element processing concentrated in limited supplier geographies.
- Dual-Use Export Controls:ITAR and EAR regulations create licensing friction for component transfers between allied defense programs.
- Technical Limitation:Atomic clock miniaturization for tactical platforms remains constrained by power consumption and thermal stability thresholds.
Strategic Opportunities
- Quantum Sensing Convergence:Cold atom interferometry integration with traditional inertial systems opens navigation accuracy improvements for strategic aircraft.
- EU MDR Certification Pathways:CE marking frameworks for military-civil dual-use components streamline transatlantic component flows.
- Unmanned Platform Expansion:Autonomous swarming vehicles require distributed navigation architectures absent legacy centralized GPS dependence.
Industry Challenges
- Specialized Workforce Scarcity:RF waveform engineering and inertial sensor calibration expertise pools remain shallow relative to program demands.
- Platform Integration Complexity:Retrofitting open-architecture navigation suites into fielded aircraft with proprietary legacy systems extends deployment timelines.
- Certification Timeline Compression:FAA and EASA joint military-civil certification requirements for tanker and transport platforms strain validation resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Navigation Systems Market |
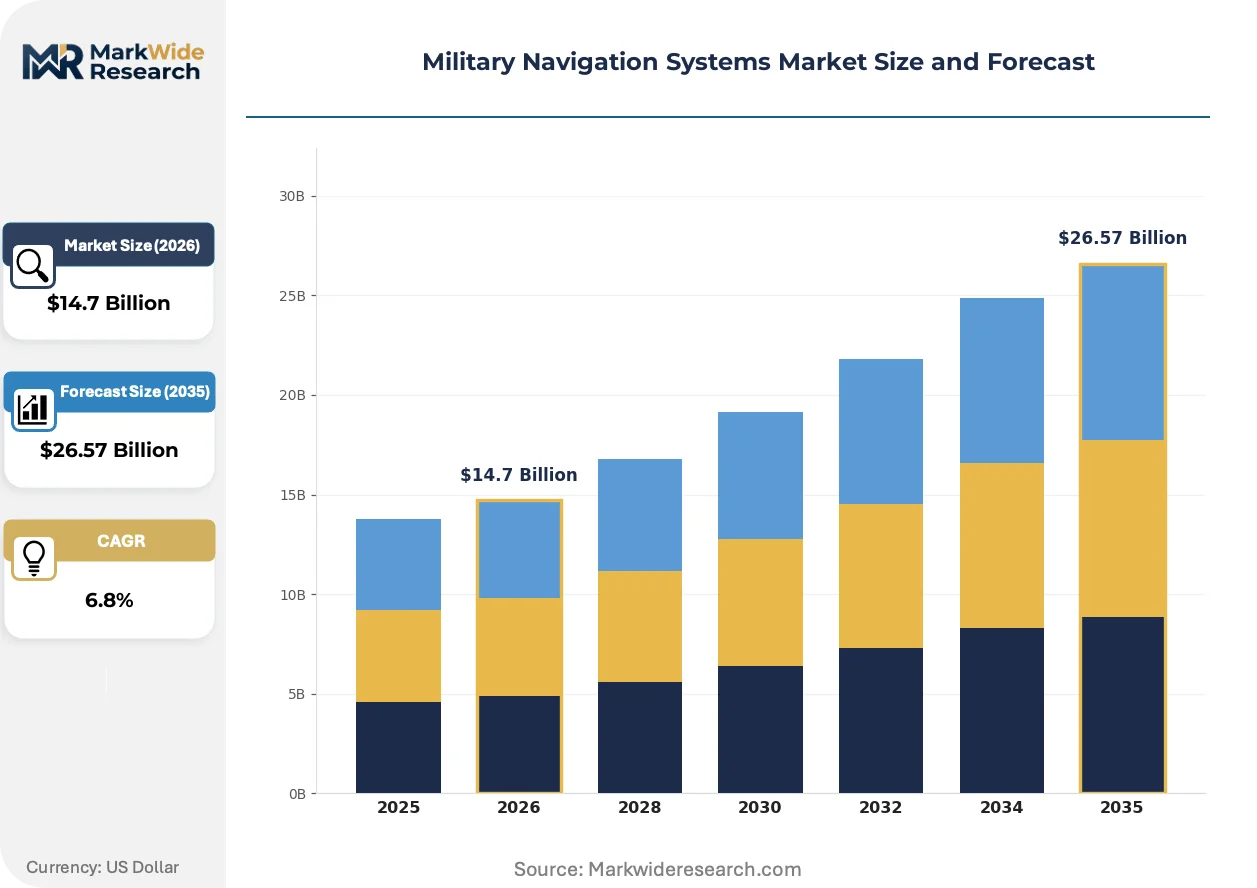
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: GPS, INS, GNSS, Terrestrial Navigation Technology: Inertial Technology, Satellite Communication, Radio Navigation, Hybrid Systems End User: Defense Forces, Aerospace Manufacturers, Government Agencies, Contractors Application: Aircraft Navigation, Naval Systems, Ground Vehicles, Drones |
| Companies Covered | Northrop Grumman Corporation, Honeywell International Inc., Safran SA, Thales Group, RTX Corporation, BAE Systems, L3Harris Technologies, Lockheed Martin Corporation, Elbit Systems Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Navigation Systems Market Shifts & Advancements
Navigation technology development is splitting between sovereign capability preservation and coalition interoperability, with electromagnetic contestedness driving hardware and software architecture decisions simultaneously.
Hybrid inertial-satellite architectures are bifurcating procurement strategies across major defense programs. Submarine and strategic bomber operators demand pure inertial solutions for signal-denied environments, while tactical aircraft programs pursue seamless failover between GPS, Galileo, and terrestrial references. This technological divergence is compressing vendor specialization, with primes forced to maintain dual competency streams or accept subcontractor dependence.
The EU's MDR and CE marking frameworks are reshaping component certification requirements for NATO-interoperable systems. Manufacturers must now demonstrate electromagnetic compatibility and safety documentation previously reserved for civil aviation applications. European sovereign PNT programs are responding by embedding hybrid architectures that satisfy both military resilience standards and civilian regulatory pathways.
Defense procurement offices are consolidating vendor relationships around platform-specific performance guarantees rather than component specifications. Long-term availability contracts with fixed pricing for navigation suites are displacing transactional spare part purchasing in fighter and maritime programs. This behavioral shift is most pronounced in United States Navy and Royal Navy surface vessel programs, where through-life support obligations now dominate source selection criteria.
Military Navigation Systems Market Segmentation
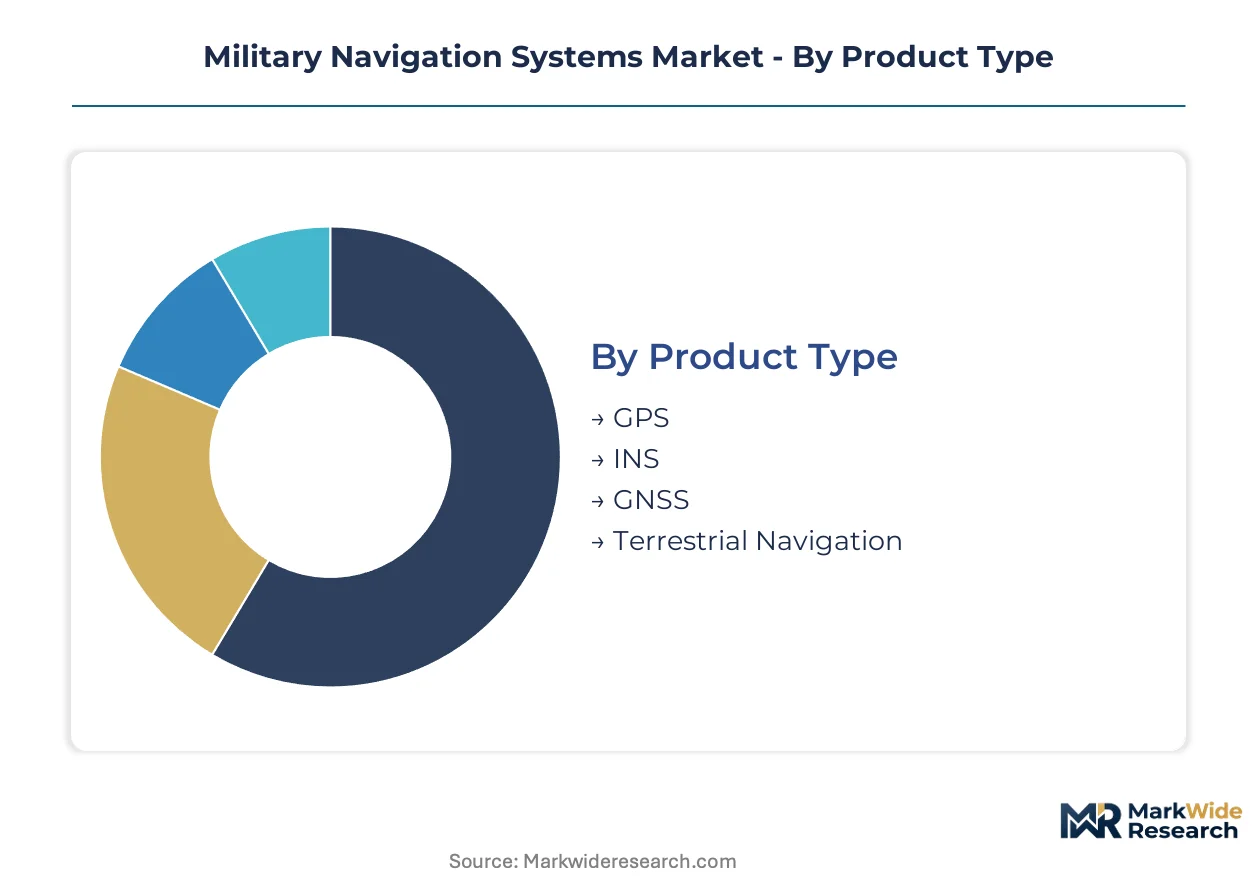
Segmentation in military navigation systems reveals how procurement hierarchies allocate budget across signal-dependent and signal-denied operational domains. Regulatory mandates from the FAA, EASA, and national defense ministries create divergent certification burdens that reshape vendor specialization and platform integration timelines.
Product Type:
FAA and EASA certification pathways differentiate airworthiness requirements across signal architectures, with civil-military dual-use platforms facing compounded validation protocols.
- GPS:Satellite-dependent positioning using encrypted military waveforms with anti-spoofing authentication. Demand concentrates in U.S. fighter and bomber fleets where congressional appropriations mandate GPS modernization and jam-resistant receiver upgrades.
- INS:Self-contained inertial navigation using gyroscopes and accelerometers without external signal dependence. Submarine and strategic aircraft programs in the United States and France drive procurement as operators require navigation continuity under complete electromagnetic denial.
- GNSS:Multi-constellation reception encompassing GPS, Galileo, and allied satellite networks.
- Terrestrial Navigation:Ground-based radio beacon and terrain-reference systems for backup positioning.
INS handles the majority of throughput in contested environments; Hybrid Systems (spanning GPS/INS integration) is the fastest mover on share as operators demand seamless failover capabilities.
Technology:
Cost tier differentiation separates strategic platform investments from tactical system upgrades, with pure inertial solutions commanding premium pricing against hybrid alternatives.
- Inertial Technology:Ring laser gyroscopes and fiber-optic gyroscopes providing drift-compensated position fixes. Nuclear submarine programs in the United States, United Kingdom, and France anchor demand as these platforms require absolute signal independence for months-long patrols.
- Hybrid Systems:Integrated architectures combining inertial cores with satellite and terrestrial references. NATO aerial refueling and transport programs across Germany, Italy, and Spain are expanding procurement as operators seek certified failover between GPS and Galileo constellations.
- Satellite Communication:Dedicated military satellite uplinks for position verification and timing distribution.
- Radio Navigation:Legacy VOR, TACAN, and emerging eLORAN ground-based systems.
Inertial Technology captures the highest absolute spending per unit; Hybrid Systems is climbing the fastest as platform retrofits accelerate across allied air forces.
End User:
Customer type determines contracting vehicle structures, with defense forces employing sole-source awards while aerospace manufacturers navigate competitive bidding for subsystem integration.
- Defense Forces:Uniformed services operating platforms and directing navigation suite specifications. The U.S. Department of Defense and allied NATO ministries dominate procurement volume through multi-year availability contracts.
- Aerospace Manufacturers:Prime contractors integrating navigation systems into airframes and maritime hulls. Boeing, Airbus Defence and Space, and Dassault Aviation specify subsystem performance tiers for fighter, transport, and tanker programs.
- Government Agencies:National laboratories and test ranges validating navigation performance standards.
- Contractors:System integrators and maintenance providers executing through-life support obligations.
Defense Forces account for the dominant procurement volume; Aerospace Manufacturers are gaining contractual share as platform OEMs consolidate subsystem vendor relationships.
Application:
Application-specific electromagnetic threat profiles drive hardware architecture decisions, with aerial platforms facing jamming exposure while naval systems prioritize signal denial endurance.
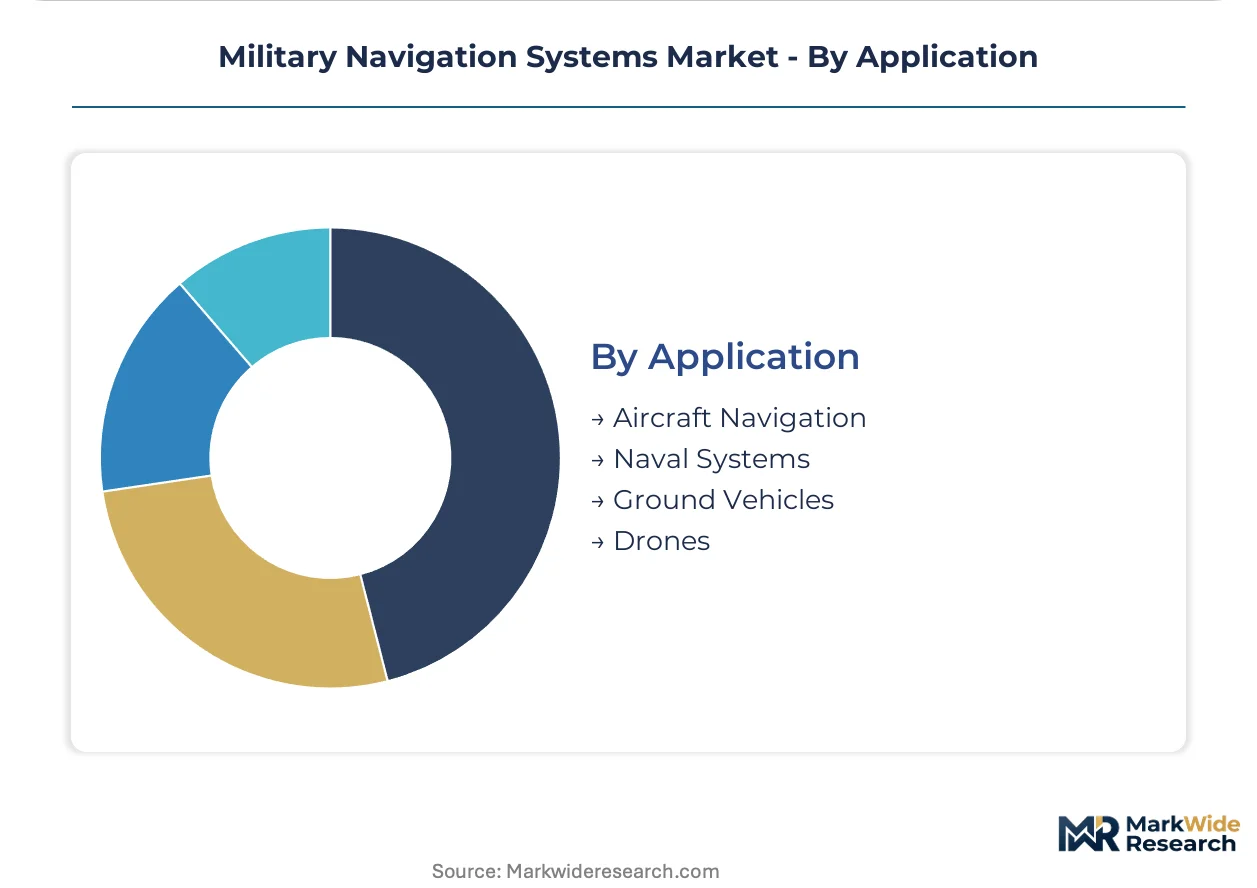
- Aircraft Navigation:Certified anti-jam waveform processing for fighter, bomber, and transport platforms. U.S. Air Force and Navy programs are expanding procurement as the Department of Defense mandates PNT resilience upgrades across tactical aviation fleets.
- Naval Systems:Submarine inertial suites and surface vessel integrated bridge systems. The Royal Navy and French Navy are accelerating procurement of pure inertial solutions for ballistic missile submarine guidance.
- Ground Vehicles:Armored platform navigation with GPS-denied backup modes.
- Drones:Unmanned aerial system navigation with size-weight-power constraints.
Aircraft Navigation commands premium pricing per unit; Drones is expanding most quickly as autonomous swarming architectures proliferate across reconnaissance and strike missions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement elasticity varies sharply across NATO member states, with congressional appropriations in the United States absorbing premium pricing for assured PNT capabilities while allied European ministries prioritize cost-efficient hybrid architectures under constrained national budgets.
United States
The Department of Defense drives absolute procurement volume through multi-year availability contracts for fighter and bomber fleet upgrades. FAA and DoD joint certification mandates for military-civil dual-use tanker platforms compress validation timelines. Defense contractors in the Greater Washington corridor concentrate GPS modernization engineering and anti-jam waveform development for tactical aviation programs.
France
Strategic submarine programs anchor pure inertial navigation demand as the French Navy requires signal-independent guidance for months-long ballistic missile patrols. EU MDR and CE marking frameworks reshape component certification for NATO-interoperable systems. Safran SA and Thales Group anchor sovereign PNT development clusters in the Paris-Saclay innovation belt, embedding hybrid architectures for dual-use compliance.
United Kingdom
The Royal Navy accelerates procurement of self-contained inertial suites for Vanguard-class submarine replacement programs. Ministry of Defence PNT resilience directives align with NATO standardization protocols for maritime platform interoperability. BAE Systems and specialist sensor houses concentrate manufacturing and integration capabilities across the Bristol-Southwest England defense corridor.
Germany
Luftwaffe aerial refueling and transport programs expand hybrid system procurement as operators seek certified failover between GPS and Galileo constellations. Bundeswehr interoperability requirements with allied NATO forces drive harmonized certification investments. Aerospace subsystem suppliers cluster in Bavaria and Baden-Württemberg, executing through-life support obligations for Eurofighter and A400M navigation suites.
Israel
Elbit Systems and defense electronics specialists develop compact navigation architectures for unmanned aerial systems facing contested electromagnetic environments. Israeli Defense Forces procurement prioritizes distributed navigation for autonomous swarming reconnaissance platforms. Tel Aviv-Haifa technology corridors concentrate RF waveform engineering and inertial sensor calibration expertise for tactical drone programs.
Military Navigation Systems Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in military navigation systems, with prime contractors controlling satellite payload heritage and inertial core manufacturing while mid-tier vendors concentrate on subsystem integration and through-life support. The vendor landscape splits between sovereign capability preservation and coalition interoperability strategies. Three archetypes dominate: satellite payload specialists leveraging GPS heritage, European hybrid architecture providers serving NATO standardization mandates, and diversified defense primes bundling navigation within platform-wide system integration. Competitive positioning hardens around long-term availability contracts with fixed pricing and open-architecture upgrade commitments.
Within the satellite payload specialist tier, Northrop Grumman Corporation and Lockheed Martin Corporation exemplify integrated leaders with heritage in GPS III follow-on programs and military satellite navigation infrastructure. Safran SA occupies a distinct position anchoring European sovereign PNT development through hybrid inertial-satellite architectures compliant with EU regulatory frameworks. RTX Corporation and Honeywell International Inc. represent diversified primes bundling navigation subsystems within broader aerospace and defense portfolios, competing on platform-wide integration scale rather than navigation-specific specialization.
| Leading Market Players |
|---|
| Northrop Grumman Corporation |
| Honeywell International Inc. |
| Safran SA |
| Thales Group |
| RTX Corporation |
| BAE Systems |
| L3Harris Technologies |
| Lockheed Martin Corporation |
| Elbit Systems Ltd. |
| Others |
Supply & Pricing Matrix
Capacity utilization at precision gyroscope foundries in the United States and France shapes both supply concentration and price floors for military navigation suites, with dedicated defense production lines commanding premium allocations over dual-use manufacturing.
Pricing Analysis
After-sales service contracts and long-term availability agreements drive lifetime value for prime contractors, displacing transactional spare part purchasing in fighter and maritime programs. Three-tier pricing structure across certified military-grade, dual-use commercial-grade, and developmental prototype levels reflects FAA and EASA certification burdens. Pricing pressure stems from congressional defense appropriations prioritizing fixed-price multi-year awards over cost-plus development contracts. Aerospace manufacturers exhibit highest price sensitivity as platform OEMs consolidate subsystem vendor relationships, while defense forces absorb premium pricing for assured PNT resilience.
Supply Chain Analysis
The United States and France anchor precision gyroscope manufacturing, with ring laser gyroscope production concentrated in dedicated defense corridors around the Greater Washington area and Paris-Saclay innovation belt. Rare earth element processing for gyroscope substrates draws from limited supplier geographies, creating single-source vulnerability for strategic material feedstocks. Distribution runs through defense prime contractors executing through-life support obligations rather than component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Military navigation systems face substitution pressure from quantum sensing architectures, requiring incumbents to defend against cold atom interferometry displacement while navigating long platform certification cycles.
For Market Incumbents: Secure multi-constellation receiver certification ahead of PNT resilience mandate deadlines, locking in platform upgrade contracts before quantum alternatives mature. Anchor backward integration into rare earth element processing to mitigate supply concentration risk from geopolitical disruption. Prioritize open-architecture upgrade commitments in long-term availability contracts to forestall modular competitor entry. For New Entrants and Emerging Players: Anchor in unmanned aerial system navigation subsystems, where size-weight-power constraints and distributed architectures favor specialized vendors over bundled prime offerings. Target Israeli and German drone program procurement offices with compact RF waveform engineering capabilities absent from legacy inertial specialists. Pursue direct subsystem integration contracts with aerospace manufacturers consolidating vendor relationships for autonomous swarming platforms. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors hybrid architecture specialists bridging inertial and satellite competencies, as pure-play GPS incumbents face multi-constellation reception mandates. Five-to-ten year viability hinges on quantum sensing convergence readiness, with acquisition targets screening for cold atom interferometry R&D partnerships or national laboratory collaboration histories. Monitor FAA-EASA joint certification timeline compression as inflection indicator for validation resource scarcity and specialist engineering premium expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Constellation Receiver Certification | Demonstrates PNT resilience compliance for U.S. DoD platform upgrade contracts. |
| Backward Integration into Rare Earth Processing | Mitigates strategic material concentration risk from limited supplier geographies. |
| Open-Architecture Navigation Suite Development | Enables seamless retrofit into fielded aircraft with proprietary legacy systems. |
| Quantum Sensing R&D Partnership | Positions for cold atom interferometry integration with traditional inertial cores. |
| Long-Term Availability Contract Negotiation | Locks in through-life support revenue with fixed pricing for fighter and maritime programs. |
Research Methodology
A standing panel of program managers at defense procurement offices, navigation subsystem engineers at prime contractors, RF waveform specialists at mid-tier suppliers, and inertial sensor calibration technicians provided ongoing calibration across primary fieldwork and secondary validation. Defense budget appropriation databases, FAA certification filings, EASA military-civil dual-use documentation, congressional research service reports, and NATO standardization protocol releases anchored secondary source triangulation. Bottom-up platform procurement tracking and top-down defense expenditure allocation modeling were reconciled through iterative stakeholder review.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window, with segmentation modeled by product type, technology architecture, end-user contracting vehicle, and application-specific electromagnetic threat profile. CAGRs were derived from weighted platform replacement schedules and modernization directive implementation timelines, incorporating submarine patrol cycle durations, fighter fleet upgrade phasing, and unmanned platform proliferation curves as industry-specific forecast inputs.
Underlying assumptions cover sustained congressional defense appropriations prioritizing assured PNT capabilities, with deviation risk concentrated in quantum sensing technology maturation acceleration and rare earth supply chain geopolitical disruption. Forecasts reflect documented conditions with revision triggers tied to regulatory mandate expansion or alternative navigation technology breakthrough demonstration. Recalibration cycles align with material shifts in DoD PNT resilience directive implementation and FAA-EASA joint certification protocol updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Navigation and Communication
Middle-East and Africa Air Traffic Management Market
Aircraft Navigation and Communication
Global Drone Navigation System Market
Aircraft Navigation and Communication
Global Air Traffic Control Equipment Market
Aircraft Navigation and Communication
America Air Traffic Management Market
Aircraft Navigation and Communication
Airborne Situational Awareness Systems Market
Aircraft Navigation and Communication
Asia-Pacific VHF Air-Ground Communication Stations Market
Aircraft Navigation and Communication
GPS and GNSS Receivers in Aviation Market
Aircraft Navigation and Communication
Aircraft Turn Coordinator Market
Aircraft Navigation and Communication
Digital Radiosonde Market
Aircraft Navigation and Communication
Global Flight Navigation System Market
Aircraft Navigation and Communication
In Flight Connectivity Market
Aircraft Navigation and Communication
Europe Inertial Systems Market
Aircraft Navigation and Communication
Helicopter Meteorological Software Market
Aircraft Navigation and Communication
Automatic Dependent Surveillance-Broadcast (ADS-B) Market
Aircraft Navigation and Communication
Aircraft Navigation System Market
Aircraft Navigation and Communication
Ground to Air on-Board Connectivity Market