
 Asia-Pacific Air Traffic Management Market | 2026-2036
Asia-Pacific Air Traffic Management Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Air Traffic Management Market Outlook
ICAO's Global Air Navigation Plan is realigning certification requirements across the Asia-Pacific, forcing suppliers to absorb heavier validation costs before contract eligibility. Thales Group leverages its surveillance radar installed base to sustain recurring service revenue across Australian and Indian terminals. Saab AB anchors digital tower deployments in secondary airports where capital budgets constrain full infrastructure builds. L3Harris Technologies competes on software-defined radio architectures that reduce hardware swap cycles for military end users.
Air traffic management encompasses the integrated systems coordinating aircraft movement from gate to gate through surveillance, communication, navigation, and automation layers, typically operating on 1030/1090 MHz transponder frequencies and VHF voice channels. Ground-based systems dominate capital expenditure as nations replace aging primary surveillance radars with multilateration and ADS-B networks. Software solutions represent the fastest-expanding margin pool, particularly automation platforms enabling trajectory-based operations and remote tower functionality. Services absorb growing share as public-private partnerships shift operational risk to vendors across Indonesia, the Philippines, and Vietnam.
Japan's MLIT and Australia's CASA enforce divergent certification timelines for ADS-B OUT mandates, fragmenting supplier compliance roadmaps. India's DGCA and China's CAAC impose local content requirements that constrain pure foreign system sales without joint venture structures. Stakeholders must monitor how cross-border airspace liberalization between ASEAN members reshapes procurement centralization versus national sovereignty in system selection.
Market Dynamics
ICAO performance-based navigation mandates are forcing wholesale replacement of ground-based surveillance infrastructure across Southeast Asian airspace corridors, compressing supplier certification timelines and fragmenting procurement authority between national regulators and centralized ASEAN bodies.
Growth Catalysts
- BeiDou-3 Satellite Constellation:China's completed navigation network enables precision approach procedures at Beijing Daxing and Shanghai Pudong without foreign GNSS dependency.
- Remote Tower Technology:Secondary airports in Indonesia and the Philippines deploy digital tower platforms to bypass full infrastructure builds.
- ADS-B OUT Mandates:Japan's MLIT and Australia's CASA enforcement timelines accelerate transponder upgrade cycles across commercial fleets.
Market Restraints
- Validation Cost Burden:ICAO's Global Air Navigation Plan forces suppliers to absorb heavier certification expenses before contract eligibility.
- Local Content Requirements:India's DGCA and China's CAAC joint venture structures constrain pure foreign system sales without domestic partnership.
- Legacy Radar Replacement Cycles:Multilateration and ADS-B networks require coordinated ground infrastructure swaps that strain capital budgets.
Strategic Opportunities
- Trajectory-Based Operations:Automation platforms enabling 4D flight path management create software margin expansion in Australian and Indian terminals.
- Public-Private Partnerships:Indonesia, the Philippines, and Vietnam shift operational risk to vendors through service-based contracts.
- Cross-Border Liberalization:ASEAN airspace integration reshapes procurement centralization versus national sovereignty in system selection.
Industry Challenges
- Certification Timeline Fragmentation:Divergent ADS-B OUT deadlines between Japan's MLIT and Australia's CASA complicate supplier compliance roadmaps.
- Interoperability Complexity:Ground-based augmentation systems must integrate with legacy primary surveillance radar networks during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Air Traffic Management Market |
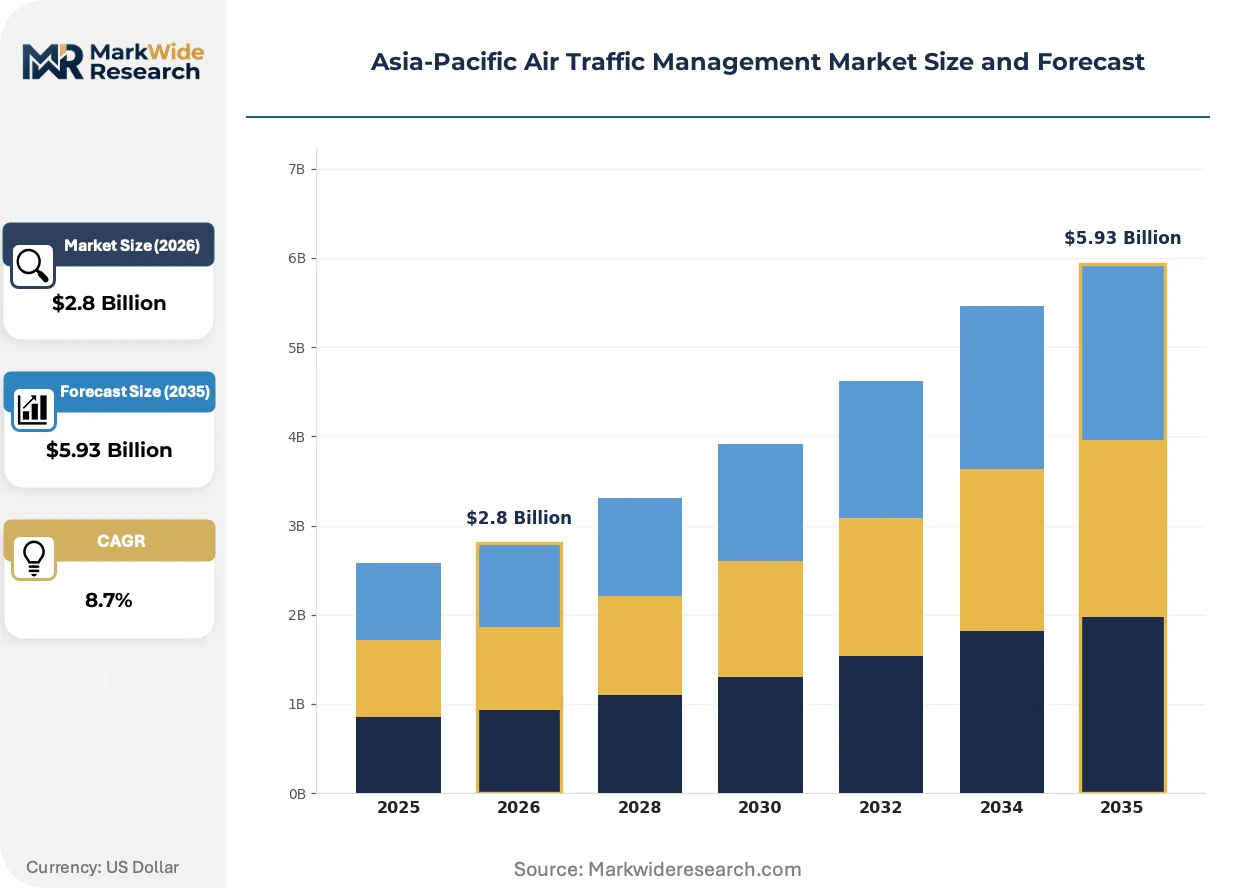
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Airborne Systems, Ground-Based Systems, Software Solutions, Services Technology: Surveillance, Communication, Navigation, Automation End User: Airlines, Airports, Government Agencies, Military Deployment: Cloud-Based, On-Premise, Hybrid, Edge Computing |
| Companies Covered | L3Harris Technologies, Saab AB, Thales Group, Leidos Holdings, Honeywell International, RTX Corporation, Leonardo, SITA, Indra Sistemas, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Air Traffic Management Market Strategic Shifts
Software-defined architectures are displacing hardware-centric ATM systems, compressing upgrade cycles and enabling remote functionality that reduces physical infrastructure dependency across the region's fragmented airport landscape.
Multilateration networks are unifying surveillance coverage across Indonesia's archipelagic airspace. Secondary airports in remote provinces adopt these systems to bypass expensive primary radar installations. The technology is unifying air traffic visibility where terrain and distance previously created dangerous gaps.
ICAO's Global Air Navigation Plan is realigning certification requirements across the Asia-Pacific. Suppliers face heavier validation costs before achieving contract eligibility for national procurement programs. Australian and Indian terminal operators respond by bundling service contracts with initial system purchases.
Airlines now specify software-upgradeable transponder architectures in fleet renewal tenders. Hardware swap cycles compress from decade-long intervals to modular firmware updates. This specification pattern concentrates in Southeast Asian low-cost carriers managing narrowbody fleet standardization.
Asia-Pacific Air Traffic Management Market Segmentation
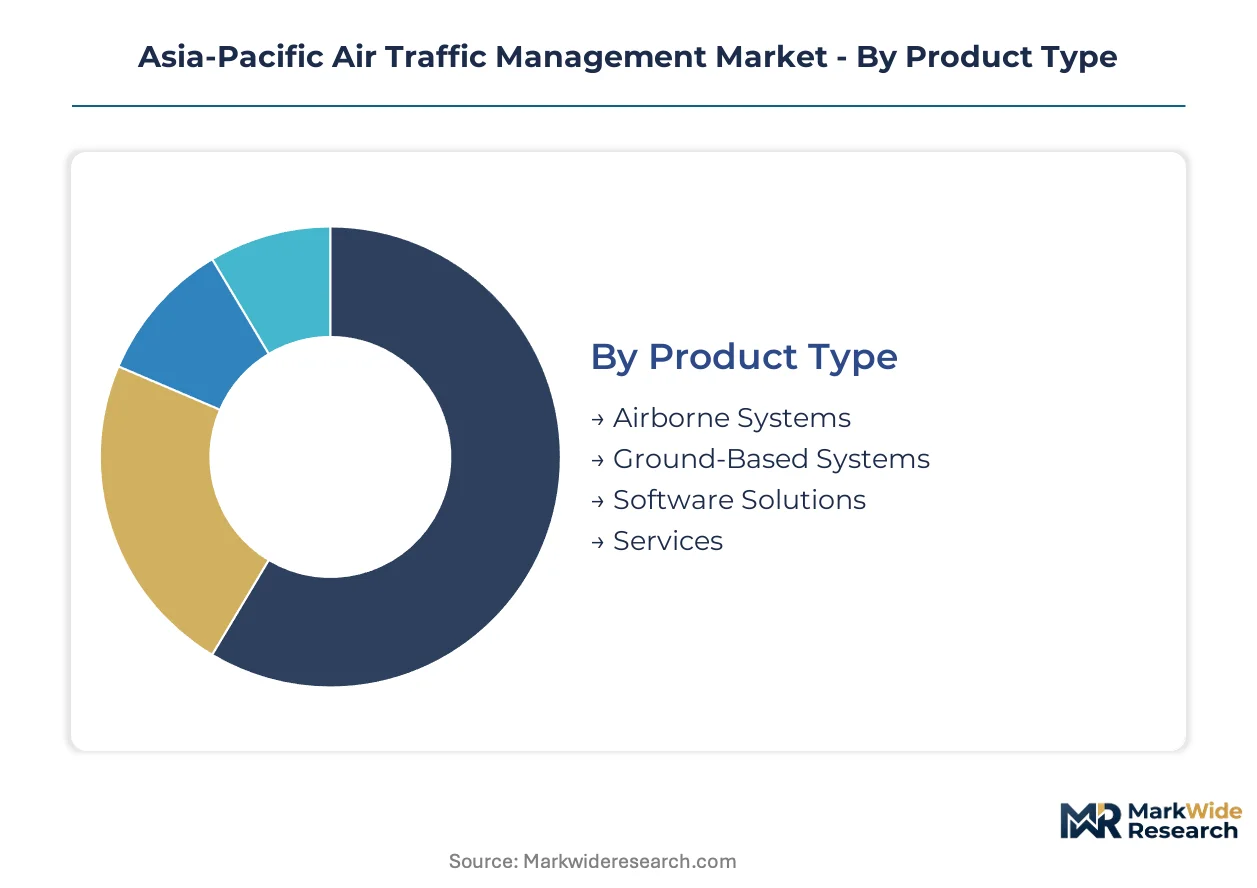
Segmentation in Asia-Pacific air traffic management reveals where capital flows concentrate versus where margins expand fastest. Procurement patterns diverge sharply between infrastructure-heavy ground installations and recurring-revenue service models.
Product Type:
Ground-Based Systems demand the heaviest upfront capital deployment, with primary surveillance radar replacements and multilateration networks requiring decade-long amortization cycles across national budgets.
- Ground-Based Systems:Multilateration networks and ADS-B ground stations coordinate aircraft positioning across Indonesia's archipelagic corridors. Australia's CASA and India's DGCA drive procurement for remote airspace coverage where terrain blocks traditional radar. These installations lock suppliers into 15-20 year maintenance contracts.
- Services:Public-private partnerships in the Philippines and Vietnam shift operational risk to vendors through performance-based contracts. Airlines at Jakarta Soekarno-Hatta and Manila Ninoy Aquino outsource tower operations to avoid civil service staffing constraints.
- Airborne Systems:Transponder upgrades for Japan's MLIT ADS-B OUT mandate concentrate at ANA and JAL maintenance facilities.
- Software Solutions:Trajectory-based operations platforms enable 4D flight path management at Beijing Daxing and Shanghai Pudong.
Ground-Based Systems absorb the bulk of installed capacity; Services is expanding most quickly as procurement shifts toward operational expenditure models.
Technology:
Application context determines which technology layer captures budget priority — surveillance dominates greenfield installations while automation penetrates established hubs seeking efficiency gains.
- Surveillance:ADS-B OUT mandates from Japan's MLIT and Australia's CASA force fleet-wide transponder replacements. Secondary surveillance radar upgrades at Bangkok Suvarnabhumi and Singapore Changi integrate multilateration for redundancy.
- Automation:Digital tower platforms enable remote air traffic control from centralized facilities, bypassing full infrastructure builds at secondary Indonesian and Philippine airports. Controllers manage multiple aerodromes from single locations.
- Communication:VHF ground stations and CPDLC data links coordinate oceanic handoffs across the South China Sea corridor.
- Navigation:BeiDou-3 augmentation at Chinese hubs reduces foreign GNSS dependency for precision approaches.
Surveillance claims the largest installed base; Automation is climbing the fastest as remote tower deployments multiply.
End User:
Customer type shapes contract structure — government agencies favor capital-intensive procurement while airlines prioritize upgradeable architectures that compress hardware refresh cycles.
- Airports:Hub operators at Beijing Daxing and Singapore Changi bundle surveillance, navigation, and automation into integrated procurement packages. Ground infrastructure modernization absorbs the majority of national ATM budgets across the region.
- Airlines:Southeast Asian low-cost carriers specify software-upgradeable transponder architectures in fleet tenders. Narrowbody standardization at AirAsia and Lion Air drives volume discounts on ADS-B OUT installations.
- Government Agencies:Civil aviation authorities in Indonesia and Vietnam manage fragmented archipelagic airspace through centralized procurement of multilateration networks.
- Military:Software-defined radio architectures reduce hardware swap cycles for dual-use military-civilian coordination.
Airports command the dominant share of capital deployment; Airlines are gaining share fastest as mandates accelerate fleet retrofit cycles.
Deployment:
Architecture choice reflects data sovereignty concerns and latency requirements — edge computing penetrates remote installations while cloud models concentrate at major hubs with redundant connectivity.
- On-Premise:Legacy primary surveillance radar installations at established hubs like Tokyo Haneda and Sydney Kingsford Smith remain physically isolated for cybersecurity compliance. Australia's CASA enforces air-gapped automation systems for critical safety functions.
- Edge Computing:Remote tower deployments in Indonesian Papua and Philippine Mindanao process surveillance data locally to overcome satellite bandwidth constraints. Real-time positioning cannot tolerate cloud latency.
- Hybrid:Major Chinese hubs partition sensitive navigation functions on-premise while offloading analytics to cloud infrastructure.
- Cloud-Based:Flight data analysis and predictive maintenance platforms at Singapore Changi leverage centralized processing for non-safety-critical applications.
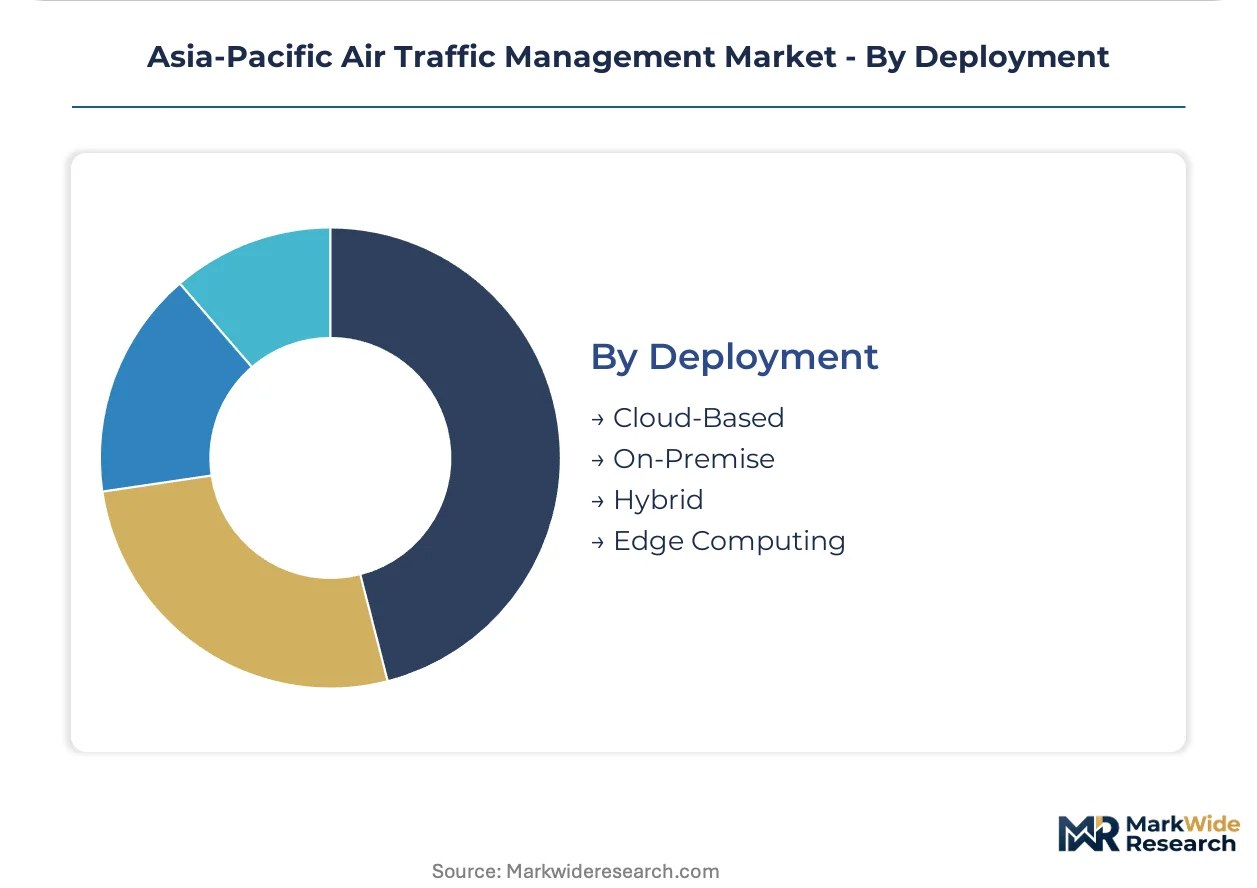
On-Premise retains the largest installed footprint; Edge Computing is gaining traction fastest where connectivity gaps constrain cloud alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Hainan Free Trade Port and Malaysia's Iskandar Malaysia special economic zone concentrate foreign direct investment in aviation infrastructure, drawing system integrators into clustered procurement corridors across the Asia-Pacific.
China
Beijing Daxing and Shanghai Pudong deploy BeiDou-3 augmentation for precision approaches without foreign GNSS dependency. CAAC local content rules require joint venture structures for foreign system sales. The Yangtze River Delta anchors domestic ATM manufacturing clusters serving hub modernization programs.
Japan
ANA and JAL maintenance facilities concentrate ADS-B OUT transponder upgrades for MLIT fleet mandates. Tokyo Haneda retains air-gapped automation systems for cybersecurity compliance. Kansai's Osaka hub integrates multilateration redundancy into secondary surveillance radar networks.
Australia
CASA enforcement timelines accelerate commercial fleet retrofit cycles across Qantas and Virgin Australia operations. Sydney Kingsford Smith maintains physically isolated legacy radar installations. Remote tower deployments in Western Australia process surveillance data locally to overcome satellite bandwidth constraints.
Indonesia
Archipelagic airspace fragmentation drives centralized procurement of multilateration networks through DGCA coordination. Jakarta Soekarno-Hatta outsources tower operations to bypass civil service staffing constraints. Papua provinces adopt edge-computing remote towers where connectivity gaps constrain cloud alternatives.
India
DGCA local content requirements constrain pure foreign sales without domestic partnership structures. Delhi-Indira Gandhi and Mumbai Chhatrapati Shivaji bundle surveillance and automation into integrated procurement packages. Bangalore's technology corridor hosts joint venture engineering centers for system localization.
Asia-Pacific Air Traffic Management Market Competitive Environment
European system integrators anchor one tier; North American defense-electronics specialists hold contract positions in dual-use military-civilian coordination. Supplier concentration remains moderate with eight to ten credible bidders for major hub installations. Three archetypes dominate: full-stack platform vendors, component specialists in surveillance or automation, and service-anchored operators capturing public-private partnership risk. Competitive moves center on joint venture formation for local content compliance and recurring service contract bundling to extend revenue duration.
Within the full-stack platform tier, Thales Group and Saab AB exemplify integrated system vendors. Thales leverages surveillance radar installed bases to sustain recurring service revenue across Australian and Indian terminals. Saab anchors digital tower deployments in secondary airports where capital budgets constrain full infrastructure builds. L3Harris Technologies occupies a position among North American specialists competing on software-defined architectures.
| Leading Market Players |
|---|
| L3Harris Technologies |
| Saab AB |
| Thales Group |
| Leidos Holdings |
| Honeywell International |
| RTX Corporation |
| Leonardo |
| SITA |
| Indra Sistemas |
| Others |
Value Chain & Pricing Dynamics
Japan's MLIT and Australia's CASA divergent ADS-B OUT certification timelines compress procurement windows, forcing suppliers to absorb validation costs upfront and recoup through premium service bundling rather than hardware margins.
Pricing Analysis
Short lead-time premiums dominate contract structures, with Indonesia and Vietnam civil aviation authorities paying 15-25% markups for accelerated multilateration network deployment to meet ICAO compliance deadlines. Project-based pricing with performance milestones anchors ground-system procurement, while software solutions migrate toward subscription tiers tied to traffic volume. Price differentiation rests on certification grade—ICAO-compliant systems command substantial premiums over baseline configurations. Cost compression in airborne transponder segments intensifies as Southeast Asian low-cost carriers standardize narrowbody fleets and extract volume discounts. Airlines remain most price-sensitive, prioritizing upgradeable architectures that extend hardware lifecycles; government agencies accept higher upfront capital outlays for sovereign airspace control.
Supply Chain Analysis
Refurbishment flows for legacy primary surveillance radar components create secondary supply channels, with Australian and Indian terminals sourcing remanufactured parts during transition periods to multilateration networks. Manufacturing concentrates in China, France, and Sweden, with CAAC local content rules and DGCA joint venture mandates forcing foreign vendors to domesticate final assembly. Critical dependencies include gallium nitride semiconductors for radar transmitters, precision optics for optical landing systems, and specialized aluminum alloys for antenna structures. Single-source vulnerability in BeiDou-3 augmentation chipsets exposes Chinese hub deployments to geopolitical supply disruption. Distribution runs through system integrators with established civil aviation authority relationships, bypassing direct OEM sales for major infrastructure contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Control over software-defined radio architectures and trajectory-based operations platforms determines who captures recurring service revenue as procurement shifts toward operational expenditure models.
For Market Incumbents: To counter software-defined architecture disruption from North American defense-electronics specialists, Thales Group and Saab AB should deepen backward integration into surveillance radar component manufacturing and lock in 15-20 year maintenance contracts through bundled service offerings at Australian and Indian terminals. Certification investment in multiple national regulator frameworks—simultaneously pursuing CAAC, DGCA, and CASA approvals—creates switching costs that protect installed bases. For New Entrants and Emerging Players: The gap between premium full-stack platform pricing and economy-tier component supply opens entry paths for remote tower automation specialists targeting Indonesian and Philippine secondary airports where capital budgets exclude infrastructure-heavy builds. White-space concentration sits in edge-computing surveillance processing for Papua and Mindanao connectivity-constrained provinces. Go-to-market leverage rests on public-private partnership risk-sharing structures that shift operational staffing burdens from civil aviation authorities to vendors. For Investors and Strategic Acquirers: The window for entry favors mid-cap automation software vendors with proven trajectory-based operations deployments. Long-term viability hinges on recurring revenue duration rather than one-time system sales, making service-contract anchored targets preferable to hardware-centric assets. Monitor ASEAN airspace liberalization negotiations as the inflection signal—cross-border integration would consolidate procurement authority and eliminate fragmented national vendor lists, compressing competitive sets to full-stack platform holders.| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture Formation | CAAC and DGCA local content rules mandate domestic partnership structures for foreign system eligibility. |
| Service Contract Bundling | 15-20 year maintenance agreements at Jakarta Soekarno-Hatta and Manila Ninoy Aquino extend revenue duration. |
| Software-Defined Architecture Migration | Modular firmware updates compress hardware swap cycles for ANA and JAL fleet standardization. |
| Remote Tower Deployment | Digital platforms bypass full infrastructure builds at secondary Indonesian and Philippine airports. |
| Certification Multi-Homing | Simultaneous MLIT, CASA, and CAAC approvals create regulatory moats against single-market competitors. |
Study Parameters
Document review covered ICAO regulatory filings, national civil aviation authority procurement records, and airline fleet modernization disclosures, complemented by interviews with air traffic control system engineers, airport operations directors, civil aviation authority procurement leads, and defense-electronics vendor program managers. Secondary validation drew from customs trade databases, SEC 10-K segment disclosures, and satellite navigation constellation deployment reports. Bottom-up unit economics for transponder installations and ground station deployments were triangulated against top-down national budget allocations for ATM infrastructure.
Historical spending patterns across surveillance, automation, and communication technology layers were cross-referenced against expert panel assessments of mandate enforcement timelines. Segmentation modeling incorporated product type, technology layer, end-user archetype, and deployment architecture dimensions. CAGRs were derived from regression analysis of capital expenditure trajectories and fleet retrofit cycle data, with trajectory-based operations software margins and public-private partnership penetration rates serving as key forecast inputs.
Inputs from ICAO and national regulator documentation were available through the study window; gaps in real-time procurement pipeline visibility and classified military-civilian coordination budgets introduce uncertainty bands around dual-use segment projections. Forecasts reflect documented mandate schedules and announced fleet modernization programs, with revision triggers including ASEAN airspace liberalization treaty ratification, BeiDou-3 augmentation export licensing changes, and ADS-B OUT deadline extensions. Practitioners should monitor cross-border procurement centralization negotiations and satellite navigation constellation interoperability agreements for early signals of competitive structure shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Navigation and Communication
Asia-Pacific VHF Air-Ground Communication Stations Market
Aircraft Navigation and Communication
5G in Aviation Market
Aircraft Navigation and Communication
Digital Radiosonde Market
Aircraft Navigation and Communication
Air Traffic Control Market
Aircraft Navigation and Communication
Aircraft Navigation System Market
Aircraft Navigation and Communication
Aircraft Navigation Software Market
Aircraft Navigation and Communication
Ultra Short Base Line Positioning System Market
Aircraft Navigation and Communication
Global Air Traffic Control Equipment Market
Aircraft Navigation and Communication
In Flight Connectivity Market
Aircraft Navigation and Communication
Aircraft Communication System Market
Aircraft Navigation and Communication
Aircraft Turn Coordinator Market
Aircraft Navigation and Communication
America Air Traffic Management Market
Aircraft Navigation and Communication
Military Navigation Systems Market
Aircraft Navigation and Communication
Global Flight Navigation System Market
Aircraft Navigation and Communication
Helicopter Meteorological Software Market
Aircraft Navigation and Communication
Europe Air Traffic Management Market