
 Airspace and Procedure Design Market | 2026-2036
Airspace and Procedure Design Market Size, Share, and Industry Trends Forecast 2026-2036
Airspace and Procedure Design Market Insights
The EU Green Deal aviation sustainability targets is repositioning airspace design priorities toward fuel-efficient routing and noise-optimized procedures. THALES leverages its simulation software portfolio to anchor European modernization programs. Honeywell International Inc. sustains technology leadership through integrated flight safety assessment platforms. Saab AB competes in military procedure development with specialized risk assessment models for defense applications.
Airspace and Procedure Design encompasses the engineering discipline of structuring aerial corridors, instrument flight procedures, and terminal area configurations using defined geometric parameters, obstacle clearance surfaces, and performance-based navigation specifications. The field applies computational fluid dynamics and terrain database modeling to ensure safe aircraft separation while optimizing fuel burn and environmental exposure. Procedure Development commands the largest service type revenue pool as legacy waypoint systems require continuous recalibration for satellite-based navigation. Simulation Software represents the fastest-expanding technology segment as virtual validation reduces physical flight inspection costs. Air Navigation Service Providers remain the dominant client type due to their statutory obligation to maintain certified instrument procedures.
The FAA mandates performance-based navigation standards under NextGen, while EASA enforces European Single Sky interoperability regulations that force cross-border procedure harmonization. ICAO's Global Air Navigation Plan creates compliance deadlines that shape national procurement schedules and technology vendor qualification requirements. Stakeholders must monitor how urban air mobility corridors and unmanned aircraft system integration will force fundamental restructuring of legacy airspace architecture and procedure design methodologies.
Market Dynamics
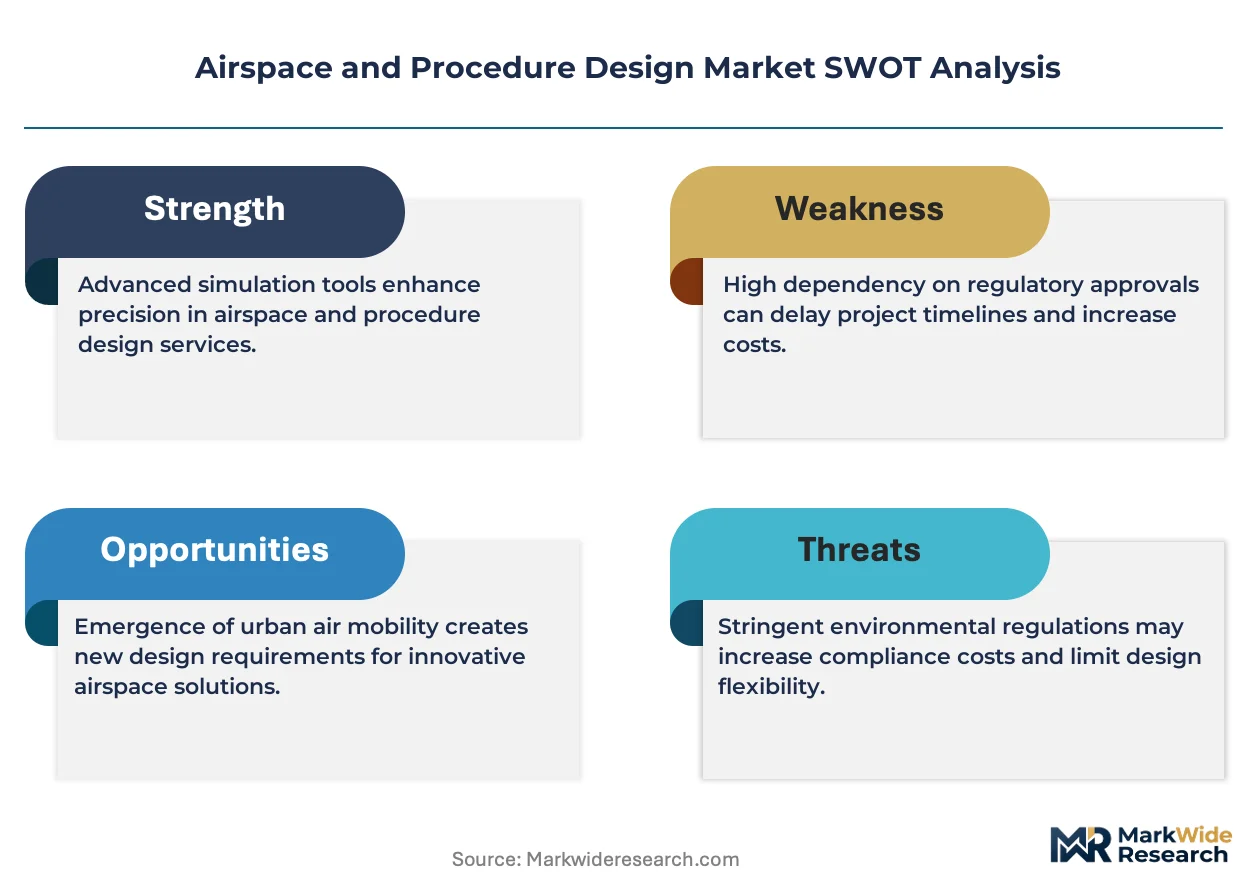
Performance-based navigation mandates are forcing wholesale replacement of legacy waypoint systems, compressing procurement cycles for Air Navigation Service Providers and mandating satellite-dependent infrastructure upgrades across civilian and military installations.
Growth Catalysts
- NextGen Modernization Mandate:The FAA's performance-based navigation standards require continuous recalibration of instrument flight procedures, creating sustained demand for procedure development services and simulation validation tools.
- Urban Air Mobility Corridors:Emerging unmanned aircraft system integration is forcing fundamental restructuring of terminal area configurations and low-altitude routing protocols in metropolitan clusters.
- EU Green Deal Aviation Targets:Fuel-efficient routing specifications and noise-optimized procedure requirements are accelerating adoption of computational fluid dynamics modeling for environmental exposure reduction.
Market Restraints
- Specialized Simulation Hardware Costs:High-fidelity terrain database modeling and computational fluid dynamics workstations require capital intensity that limits vendor entry and client upgrade frequency.
- Cross-Border Harmonization Friction:EASA's Single European Sky interoperability regulations create procedural misalignment with national military airspace reservations, complicating unified airspace architecture.
- Certified Personnel Scarcity:The shallow pool of ICAO-qualified procedure design specialists concentrates execution risk with established engineering consultancies and legacy ANSP engineering divisions.
Strategic Opportunities
- Unmanned Traffic Management Integration:U-space regulatory frameworks in Europe and equivalent FAA rulemaking are opening dedicated procedure design verticals for drone corridor segregation and vertiport approach modeling.
- Virtual Validation Adoption:Digital twin environments for flight procedure testing are reducing physical flight inspection requirements, creating subscription-based software revenue streams.
- Military-Civilian Interface Standards:NATO-aligned nations are harmonizing classified and civilian airspace boundaries, requiring specialized risk assessment protocols for dual-use terminal areas.
Industry Challenges
- Legacy System Integration Complexity:Ground-based navigation aid decommissioning must maintain backward compatibility for non-equipped aircraft, extending dual-system maintenance burdens.
- ICAO Compliance Timeline Compression:Global Air Navigation Plan deadlines are forcing parallel procedure development tracks that strain engineering capacity and certification queue management.
- Obstacle Database Currency:Terrain and man-made structure surveillance requires continuous survey investment to maintain certified instrument procedure validity.
Report Scope
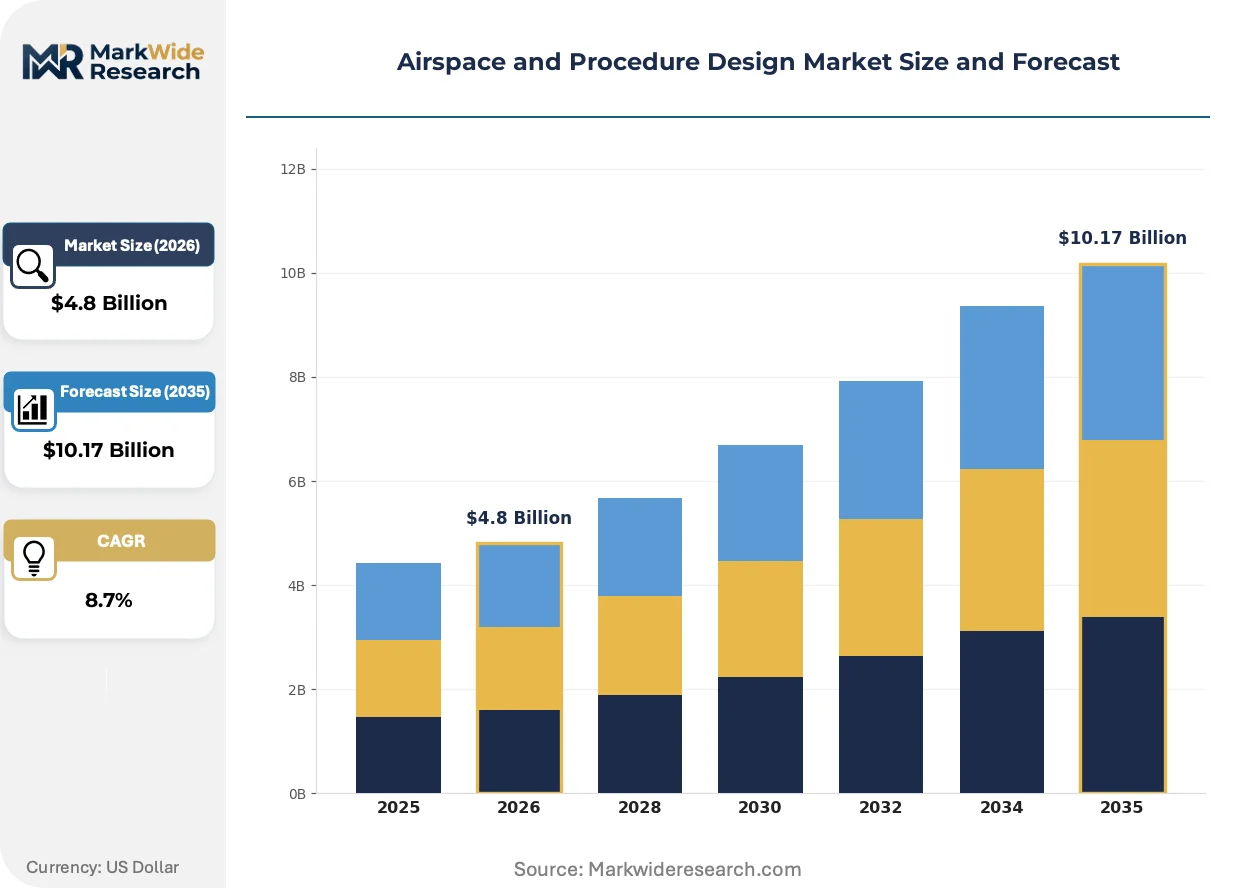
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airspace and Procedure Design Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Airspace Management, Procedure Development, Flight Safety Assessment, Compliance Verification Client Type: Air Navigation Service Providers, Airlines, Airports, Government Agencies Technology: 3D Visualization, Simulation Software, Data Analytics Tools, Risk Assessment Models End User: Commercial Aviation, Military Operations, General Aviation, Private Pilots |
| Companies Covered | Honeywell International Inc., THALES, Northrop Grumman Corporation, Indra Sistemas S.A., Adacel Technologies Limited, Leonardo S.p.A., Frequentis AG, L3Harris Technologies, Inc., Saab AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airspace and Procedure Design Market Trends and Innovations
Computational methods are displacing manual flight inspection protocols while regulatory mandates accelerate technology refresh cycles across civilian and defense procurement channels.
Artificial intelligence-based trajectory optimization is automating the generation of fuel-efficient routing algorithms and noise-abatement departure procedures. Major Air Navigation Service Providers in the United States and Germany are deploying machine learning platforms to compress procedure design iteration cycles from months to weeks. This automation is reducing engineering headcount requirements for standard terminal arrival route development while elevating demand for AI model validation specialists.
Europe's Single European Sky initiative is mandating cross-border procedure harmonization that overrides national airspace sovereignty conventions. The regulation forces ANSPs in France, Germany, and the Benelux corridor to consolidate previously independent terminal area designs into unified functional airspace blocks. Military airspace reservation protocols represent the primary friction point, requiring negotiated civil-military interface standards that delay implementation timelines.
After-sales service unbundling is fragmenting traditional engineering procurement into discrete validation, certification, and software licensing components. ANSPs in the United Kingdom and Nordic countries are separating simulation software subscriptions from procedure design consulting, creating price transparency that pressures bundled service margins. This disintermediation favors specialized software vendors with recurring revenue models over full-service engineering consultancies dependent on project-based contracting.
Airspace and Procedure Design Market Segmentation
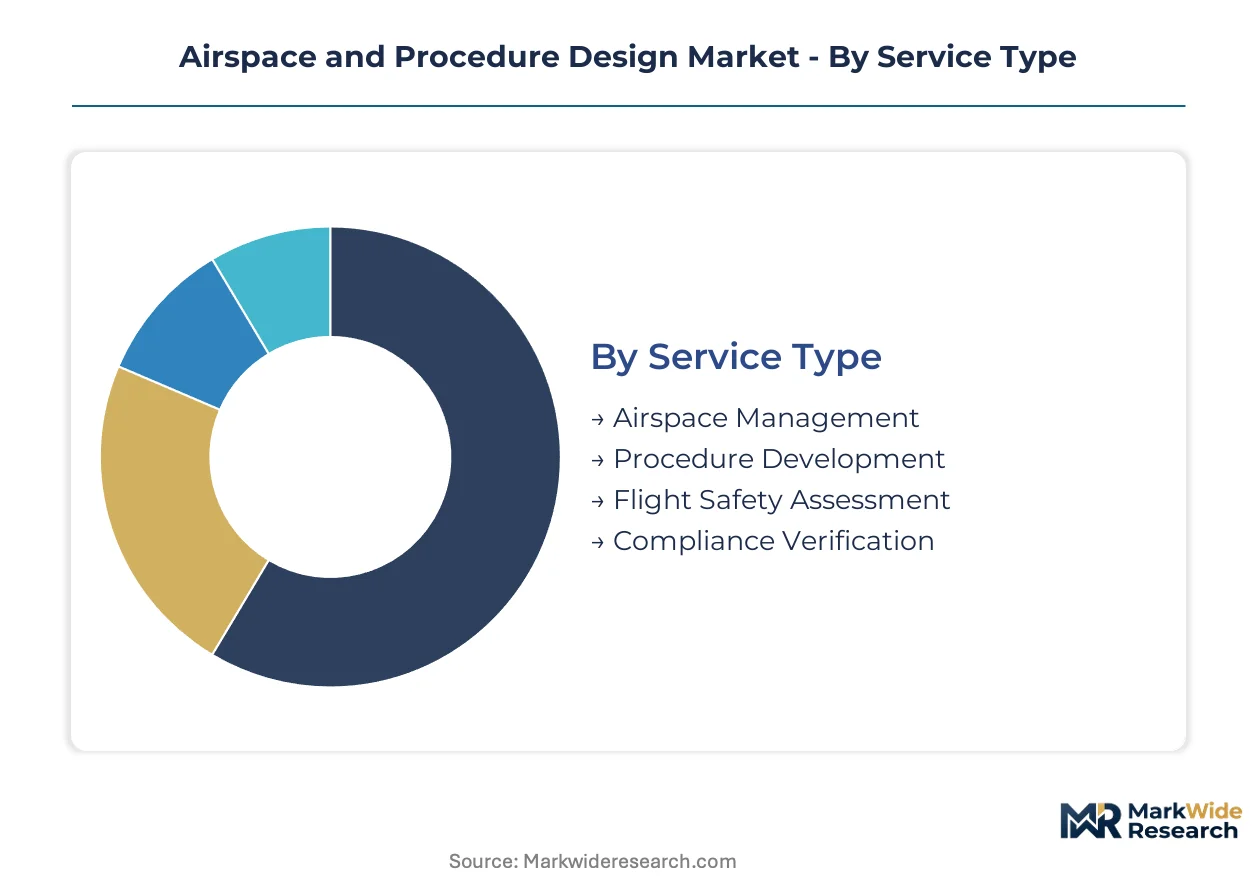
Airspace and Procedure Design procurement fragments across service modalities, client capabilities, and technology maturity tiers. Each segmentation axis reveals distinct margin structures and vendor qualification thresholds that shape competitive positioning.
Service Type:
Customization intensity varies sharply across this category, from standardized compliance audits to bespoke military procedure architectures requiring classified clearance protocols.
- Procedure Development:Engineering of instrument flight procedures, terminal area configurations, and performance-based navigation specifications using obstacle clearance surfaces and terrain database modeling. Demand concentrates with Air Navigation Service Providers in the United States and Germany as FAA NextGen and EASA Single European Sky mandates force continuous recalibration of legacy waypoint systems for satellite-based navigation.
- Airspace Management:Structuring of aerial corridors, sector boundaries, and traffic flow patterns to ensure safe aircraft separation while optimizing fuel burn. Military operations across NATO-aligned nations are expanding adoption of advanced flight procedure systems, creating specialized demand for dual-use terminal area designs.
- Flight Safety Assessment:Risk evaluation protocols for approach and departure procedures using computational fluid dynamics and terrain surveillance data.
- Compliance Verification:Certification audits against ICAO Global Air Navigation Plan standards and national aviation regulator requirements.
Most installed capacity flows through Procedure Development. Expansion is steepest in Airspace Management as urban air mobility corridors force restructuring of low-altitude routing protocols.
Client Type:
Procurement authority concentrates with statutory service providers, while commercial operators represent discretionary spend tiers with divergent vendor selection criteria.
- Air Navigation Service Providers:Statutory obligation to maintain certified instrument procedures creates sustained procurement volume. ANSPs in the United Kingdom and Nordic countries are unbundling after-sales service into discrete validation, certification, and software licensing components.
- Government Agencies:Defense modernization programs and national security airspace reservations generate classified procedure development contracts with specialized risk assessment protocols.
- Airlines:Fuel-efficient routing specifications and noise-optimized procedure requirements drive demand for computational fluid dynamics modeling.
- Airports:Terminal area configuration upgrades and vertiport approach modeling for unmanned traffic management integration.
Revenue concentration sits with Air Navigation Service Providers. Government Agencies are gaining share fastest as military-civilian interface standardization accelerates.
Technology:
Capital intensity and personnel requirements create tiered adoption barriers, separating ANSPs with dedicated simulation infrastructure from clients relying on vendor-hosted platforms.
- Simulation Software:Virtual validation environments for flight procedure testing that reduce physical flight inspection costs. Digital twin adoption is creating subscription-based revenue streams as ANSPs separate software subscriptions from consulting engagements.
- 3D Visualization:Terrain database rendering and obstacle clearance surface modeling for procedure design iteration.
- Risk Assessment Models:Specialized protocols for defense applications and dual-use terminal areas requiring civil-military interface standards.
- Data Analytics Tools:Machine learning platforms for fuel-efficient routing algorithm generation and noise-abatement departure procedure optimization.
Deployment scale favors Simulation Software. Technology refresh cycles are compressing fastest around Data Analytics Tools as artificial intelligence automates standard terminal arrival route development.
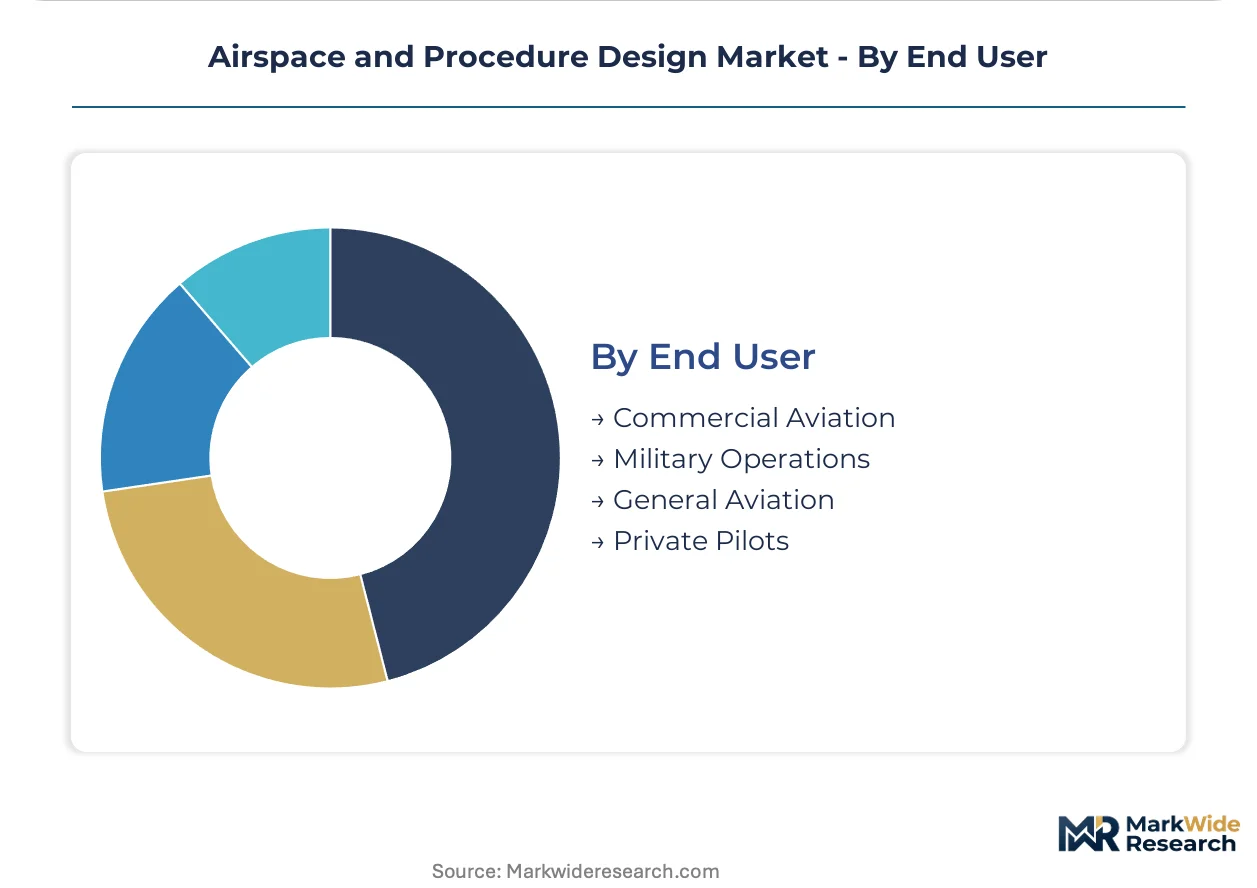
End User:
Operational tempo and regulatory exposure determine service tier procurement, from high-frequency commercial corridors to sporadic general aviation requirements.
- Commercial Aviation:Dense air traffic corridors in metropolitan clusters drive continuous procedure recalibration for performance-based navigation compliance.
- Military Operations:Classified airspace boundaries and specialized risk assessment models for defense applications across NATO-aligned nations.
- General Aviation:Non-equipped aircraft requirements extend dual-system maintenance burdens as ground-based navigation aids face decommissioning.
- Private Pilots:Minimal procurement footprint with reliance on standardized published procedures rather than custom design services.
Volume leadership belongs to Commercial Aviation. Military Operations are expanding most quickly as NATO nations harmonize classified and civilian airspace architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The airspace and procedure design discipline traces its modern lineage to post-war instrument flight standardization efforts in the United States, where dense transcontinental corridors first demanded systematic terminal area engineering and obstacle clearance modeling.
United States
FAA NextGen mandates drive continuous recalibration of legacy waypoint systems for satellite-based navigation across the National Airspace System. The FAA's performance-based navigation standards compress procurement cycles for Air Navigation Service Providers and defense installations alike. Dallas-Fort Worth and Atlanta metropolitan clusters concentrate engineering demand as urban air mobility corridors force restructuring of low-altitude routing protocols.
Germany
EASA Single European Sky interoperability regulations override national airspace sovereignty conventions and force cross-border procedure harmonization with France and Benelux neighbors. The EU Green Deal aviation sustainability targets accelerate adoption of computational fluid dynamics modeling for fuel-efficient routing in German terminal areas. Frankfurt and Munich airport complexes anchor engineering procurement as ANSPs consolidate previously independent terminal designs into unified functional airspace blocks.
United Kingdom
Post-Brexit regulatory divergence from EASA frameworks creates parallel certification requirements for instrument flight procedures serving London airspace. The country's national aviation regulator maintains distinct compliance verification protocols that strain engineering capacity and certification queue management. NATS engineering divisions in Swanwick and Prestwick concentrate procedure development expertise while unbundling after-sales service into discrete validation and software licensing components.
France
Military-civilian interface standardization across NATO-aligned airspace generates specialized demand for dual-use terminal area designs and classified risk assessment protocols. The EU Green Deal noise-optimized procedure requirements reshape departure routing from Paris Charles de Gaulle and Orly airports. THALES leverages its simulation software portfolio to anchor European modernization programs while competing for military procedure development contracts.
United Arab Emirates
Strategic positioning as a global aviation hub drives investment in advanced flight procedure systems for Dubai and Abu Dhabi metropolitan corridors. The country's civil aviation authority pursues ICAO Global Air Navigation Plan compliance deadlines that shape national procurement schedules and technology vendor qualification requirements. Dubai South and Al Maktoum International anchor unmanned traffic management integration efforts as U-space regulatory frameworks open dedicated procedure design verticals for drone corridor segregation.
Airspace and Procedure Design Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification complexity and defense clearance protocols. Engineering consultancies with ICAO-qualified procedure design specialists command pricing power over software-only vendors lacking validation authority. Three archetypes dominate: integrated aerospace conglomerates with simulation software portfolios, specialized defense contractors with classified risk assessment capabilities, and unbundled software vendors pursuing subscription-based recurring revenue models. Competitive dynamics center on strategic partnerships with Air Navigation Service Providers and technology licensing arrangements that embed vendors within multi-year modernization programs.
Within the integrated systems tier, Honeywell International Inc. and THALES exemplify archetypes combining hardware certification authority with simulation validation platforms. Saab AB occupies a position among defense-specialized contractors developing military-civilian interface standards for NATO-aligned nations. These three anchors demonstrate how geographic origin and corporate structure shape competitive positioning: Honeywell International Inc. as a US-based aerospace conglomerate, THALES as a French S.A. with European regulatory embeddedness, and Saab AB as a Swedish specialist in dual-use terminal area architectures.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| THALES |
| Northrop Grumman Corporation |
| Indra Sistemas S.A. |
| Adacel Technologies Limited |
| Leonardo S.p.A. |
| Frequentis AG |
| L3Harris Technologies, Inc. |
| Saab AB |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal aviation sustainability targets gate qualified supply and premium-tier pricing access by mandating computational fluid dynamics modeling capabilities that only certified engineering consultancies possess. ANSPs seeking fuel-efficient routing specifications must pay subscription premiums for simulation software with environmental exposure reduction modules, while vendors lacking ICAO-qualified procedure design specialists face exclusion from high-margin procedure development contracts.
Pricing Analysis
Project-based consulting fees layered with recurring simulation software subscriptions dominate revenue capture across Air Navigation Service Providers. Price differentiation rests on ICAO certification tier and after-sales service bundling, with full-service engineering consultancies commanding premiums over unbundled software vendors. Cost compression in standard terminal arrival route development is intensifying because artificial intelligence automation reduces engineering headcount requirements. Government agencies with classified defense contracts exhibit lowest price sensitivity, while regional airports pursuing vertiport approach modeling show highest sensitivity to upfront licensing costs.
Supply Chain Analysis
Single-source vulnerability sits with high-fidelity terrain database providers concentrated in the United States, Germany, and France. Raw material dependencies include computational fluid dynamics workstations, satellite navigation augmentation systems, and continuous obstacle survey data feeds. Supply chain risk centers on regulatory restriction as EASA Single European Sky interoperability regulations override national airspace sovereignty conventions and complicate cross-border vendor qualification. Distribution runs through direct procurement relationships between ANSP engineering divisions and integrated aerospace conglomerates, with subscription-based software licensing gaining share in Nordic countries and the United Kingdom.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Airspace and Procedure Design represents a late-cycle quality story as FAA NextGen and EASA mandates shift procurement toward premium-tier simulation validation platforms with AI-powered trajectory optimization. Buyers now prioritize vendors with ICAO-qualified specialists over commodity software providers.
For Market Incumbents: Anticipate margin erosion from unbundled software vendors by embedding subscription-based digital twin environments within multi-year ANSP modernization programs. Consolidate engineering capacity through selective acquisition of specialized risk assessment modeling firms serving NATO defense applications. Certification queue management capabilities differentiate premium-tier positioning as Global Air Navigation Plan deadlines compress delivery timelines. For New Entrants and Emerging Players: Enter via unmanned traffic management integration verticals in Dubai and Abu Dhabi metropolitan corridors, where U-space regulatory frameworks create dedicated procedure design white space for drone corridor segregation. Target airport authorities in the United Arab Emirates and Nordic countries pursuing vertiport approach modeling with limited incumbent presence. Lead with machine learning platform demonstrations that compress procedure design iteration cycles from months to weeks. For Investors and Strategic Acquirers: Valuations sit cheapest among unbundled software vendors lacking ICAO validation authority but possessing recurring revenue models and AI model development capabilities. Long-term viability favors vendors with embedded positions in FAA NextGen or EASA Single European Sky modernization programs. Watch civil-military interface standardization progress across NATO-aligned nations as the inflection signal for defense-specialized procedure development demand.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Powered Trajectory Optimization Platform | Machine learning automation compresses terminal arrival route development cycles for ANSPs in Germany and the United States. |
| U-Space Regulatory Compliance Certification | European drone corridor segregation mandates open dedicated procedure design verticals for unmanned traffic management vendors. |
| Military-Civilian Interface Standardization | NATO airspace harmonization protocols generate classified contracts for dual-use terminal area risk assessment specialists. |
| Digital Twin Environment Deployment | Virtual validation adoption reduces physical flight inspection costs and creates subscription-based recurring revenue streams. |
| Cross-Border Procedure Harmonization Partnership | EASA functional airspace block consolidation forces ANSP collaboration across France, Germany, and Benelux corridors. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with air navigation service provider engineering directors, ICAO-qualified procedure design specialists, military airspace reservation officers, and simulation software procurement leads with secondary validation against FAA NextGen implementation reports, EASA Single European Sky regulatory filings, ICAO Global Air Navigation Plan documentation, and ANSP capital expenditure disclosures. Bottom-up service-type demand modeling and top-down regional procurement aggregation were cross-referenced for triangulation.
Historical reference periods anchored the projection horizon through documented technology refresh cycles and regulatory compliance deadline clustering. Segmentation dimensions modeled include service type, client capability tier, technology maturity level, and end-user operational tempo. CAGRs were derived from fitted growth curves calibrated to procurement volume indicators and vendor revenue recognition patterns. Forecast inputs incorporated urban air mobility corridor deployment timelines and unmanned traffic management regulatory finalization schedules.
Inputs from ANSP procurement officers and defense airspace planners were available through the study window; gaps in classified military procedure development contract disclosure introduce uncertainty bands around the defense segment sizing. Forecasts reflect documented assumptions regarding FAA and EASA mandate adherence rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Navigation and Communication
America Air Traffic Management Market
Aircraft Navigation and Communication
5G Adoption Analysis in Aviation Market
Aircraft Navigation and Communication
Global Aircraft Antenna Market
Aircraft Navigation and Communication
Asia-Pacific Air Traffic Management Market
Aircraft Navigation and Communication
Aircraft Turn Coordinator Market
Aircraft Navigation and Communication
Air Traffic Management Market
Aircraft Navigation and Communication
Global Flight Navigation System Market
Aircraft Navigation and Communication
Airborne Telemetry Market
Aircraft Navigation and Communication
Connected Aircraft Market
Aircraft Navigation and Communication
Global Aviation Mapping Software Market
Aircraft Navigation and Communication
Helicopter Meteorological Software Market
Aircraft Navigation and Communication
Global Drone Navigation System Market
Aircraft Navigation and Communication
Ground to Air on-Board Connectivity Market
Aircraft Navigation and Communication
Aviation Weather Radar Market
Aircraft Navigation and Communication
Aircraft Communication System Market
Aircraft Navigation and Communication
Europe Air Traffic Management Market