
 Aluminum Welding Market | 2026-2036
Aluminum Welding Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Welding Market Analysis
The divergence between premium precision welding systems and commodity filler metal supply is broadening. ESAB leverages its R&D intensity across automated MIG solutions for automotive OEMs. The Lincoln Electric Company anchors North American distribution through vertical integration into filler wire production. Fronius differentiates via laser welding technology leadership for thin-gauge aluminum fabrication.
Aluminum welding encompasses the fusion joining of aluminum alloys using heat, pressure, or both, typically requiring specialized filler metals with silicon or magnesium additions to mitigate solidification cracking in the 6000-series and 7000-series alloys most common to structural applications. Its primary industrial purpose centers on producing lightweight, corrosion-resistant joints for transportation and infrastructure systems where steel's mass penalty is unacceptable. Filler Wire commands the largest product type position due to recurring consumable demand across repair and manufacturing cycles, while Laser Welding represents the fastest-growing technology segment as EV battery tray and aerospace panel applications demand minimal heat-affected zones. The Equipment category carries concentrated margin pools where system integrators bundle power sources with process control software.
EMA's Medical Device Regulation and REACH substance restrictions shape consumable composition standards across European supply chains, while the EPA and OSHA govern fume exposure limits and workplace ventilation requirements in US fabrication facilities. China's GB standards and SAMR certification protocols control market access for imported welding power sources. Stakeholders must monitor how evolving carbon border adjustment mechanisms recalibrate sourcing economics between domestic filler wire production and Asian supply routes.
Market Dynamics
The transition from traditional MIG processes to laser-hybrid systems is compressing equipment replacement cycles across automotive and aerospace fabrication lines. Tier-1 suppliers now demand sub-millimeter heat-affected zone control for EV battery enclosures, forcing capital redeployment toward precision power sources with integrated process monitoring.
Growth Catalysts
- EU Green Deal carbon border adjustments:Domestic filler wire production in Germany and France gains cost parity against Asian imports as CBAM phase-in tightens. Shipyards and automotive OEMs accelerate local sourcing audits.
- 6000-series alloy penetration in EV architectures:Battery tray and motor housing designs specify aluminum extrusion welding at scale. OEMs in Stuttgart and Wolfsburg expand automated cell deployment.
- Laser welding technology maturation:Fiber laser costs per watt decline while beam quality improves. Aerospace panel fabricators in Hamburg adopt single-mode systems for thin-gauge stringer-to-skin joints.
Market Restraints
- Argon shielding gas cost volatility:Energy-intensive cryogenic separation exposes European fabricators to natural gas price swings. Smaller job shops in Poland and Czechia face margin compression.
- Chinese power source import dependency:SAMR certification timelines extend 8-14 months for non-domestic suppliers. German system integrators face project delays when sourcing from Shenzhen clusters.
- Solidification cracking in 7000-series alloys:High-strength aerospace grades require exotic filler formulations with scandium or zirconium. Limited qualified wire suppliers concentrate supply risk.
Strategic Opportunities
- India automotive welding infrastructure:PLI scheme incentives for EV manufacturing attract aluminum-intensive platform investments. Domestic equipment distributors in Pune and Chennai expand service networks.
- Remote process monitoring via industrial IoT:Cloud-based arc data analytics enable predictive maintenance contracts. Dutch shipbuilders in Rotterdam pilot subscription-based uptime guarantees.
- Scandium-modified filler wire qualification:EASA and FAA certification pathways for next-generation aerospace alloys create first-mover advantages. Specialized wire producers in Austria advance metallurgical partnerships.
Industry Challenges
- Welding engineer certification bottlenecks:IIW and EWF diploma programs face 18-month backlogs in Central Europe. Automotive OEMs in Munich compete for qualified laser-hybrid operators.
- Legacy equipment integration complexity:Retrofitting 1990s-era power sources with modern bus architecture requires custom interface development. Job shops in Northern Italy defer automation investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Welding Market |
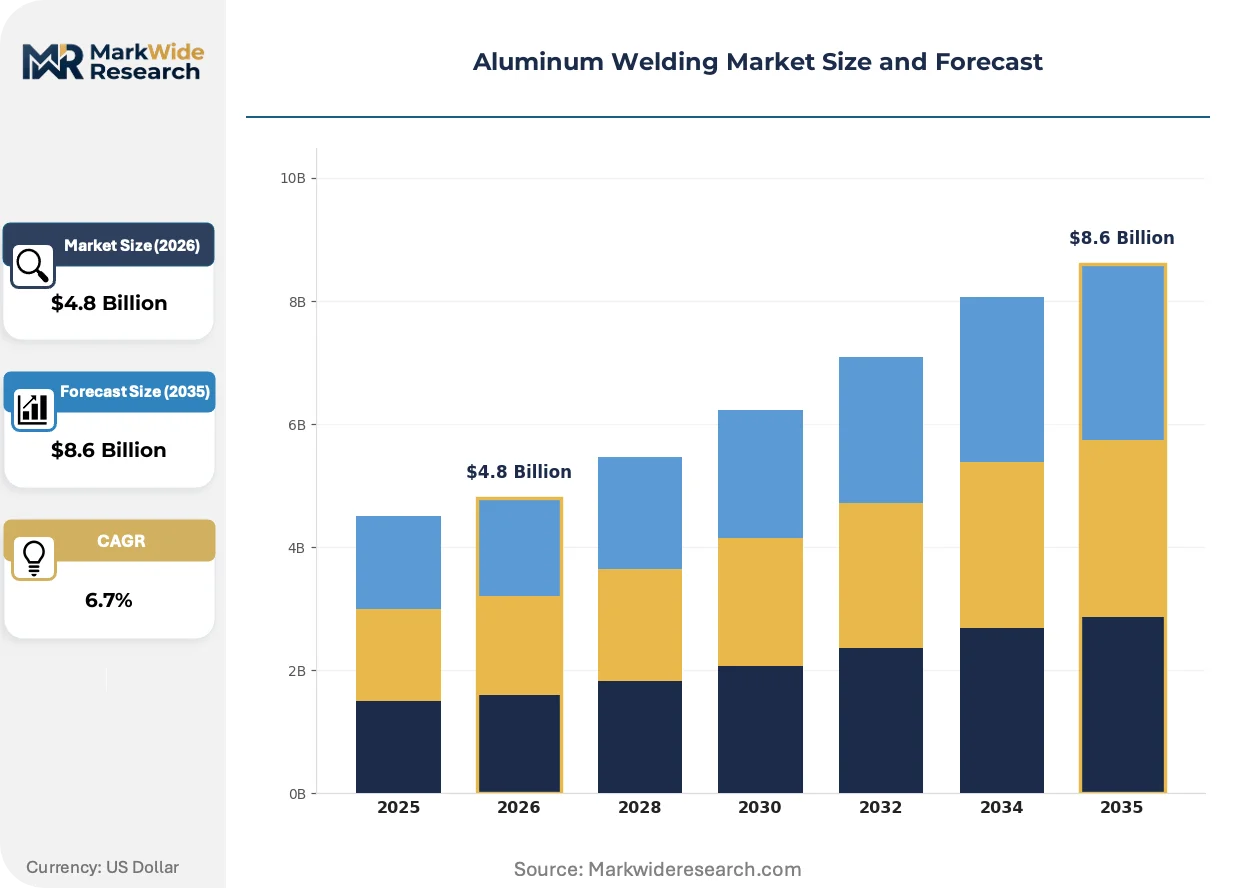
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filler Wire, Welding Rods, Shielding Gas, Equipment Technology: MIG Welding, TIG Welding, Laser Welding, Resistance Welding End User: Aerospace, Automotive OEMs, Construction, Marine Application: Fabrication, Repair, Manufacturing, Assembly |
| Companies Covered | The Lincoln Electric Company, ESAB, Hilarius Haarlem Holland B.V., EWM GmbH, Hermann Fliess and Co. GmbH, Drahtwerk ELISENTAL W. Erdmann GmbH & Co., Air Liquide, Miller Electric, Fronius, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Welding Market Emerging Trajectories
Process control digitization and beam source commodification are collapsing the traditional boundary between equipment tiers. Fabricators now specify performance outcomes rather than brand names, while consumable metallurgy advances unlock previously unweldable alloy combinations.
Hybrid laser-arc welding is rewriting productivity benchmarks for thick-section aluminum fabrication. Shipbuilders in South Korea adopt 10-kW fiber laser-GMAW systems for cruise vessel superstructure panels. The technology enables single-pass 12-mm penetration at speeds triple conventional MIG, compressing yard throughput timelines and reducing distortion-related rework.
REACH substance restriction expansions are forcing filler metal reformulation across European supply chains. ECHA scrutiny of chromium and nickel compounds in flux-cored wires drives R&D toward silicon-magnesium-boron systems. Swedish equipment OEMs in Gothenburg accelerate qualification programs for chrome-free consumables ahead of 2026 sunset dates.
Buyer consolidation among automotive Tier-1s is concentrating procurement leverage against fragmented equipment vendors. Magna and Benteler now mandate five-year total cost-of-ownership contracts with guaranteed uptime clauses. German power source manufacturers respond with embedded predictive analytics and remote diagnostic subscriptions rather than discrete hardware sales.
Aluminum Welding Market Segmentation
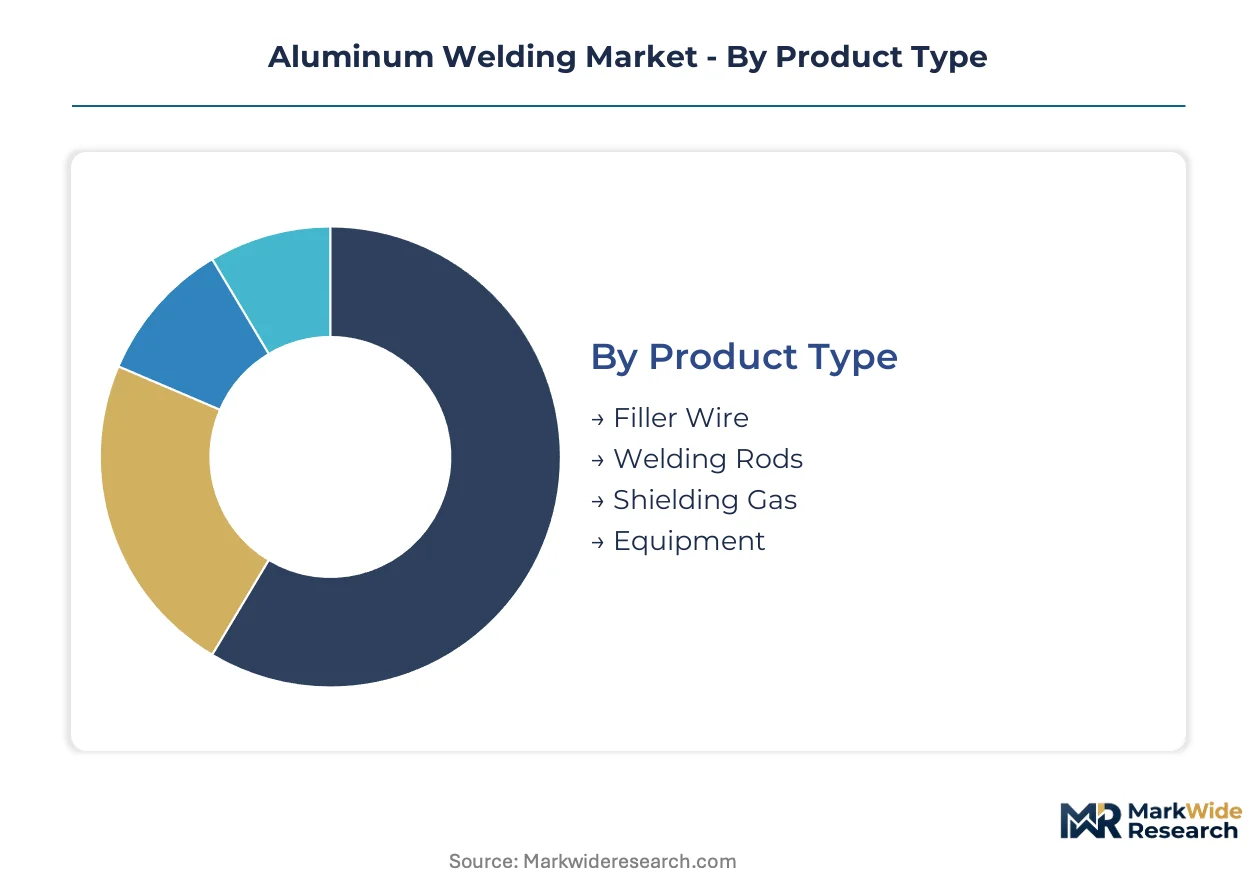
Aluminum welding market segmentation reveals distinct margin architectures across consumables versus capital equipment. Procurement patterns diverge sharply between recurring filler metal purchases and long-cycle power source investments.
Product Type:
Standardization dominates filler metals while equipment demands heavy customization for automated production lines.
- Filler Wire:Continuous-feed aluminum alloys with silicon or magnesium additions to control solidification cracking in 6000-series and 7000-series joints. Automotive OEMs in Stuttgart and Wolfsburg drive volume through automated MIG cells for battery tray welding, with recurring consumable demand creating annuity-like revenue streams for qualified suppliers.
- Equipment:Power sources, wire feeders, and robotic integration modules requiring process control software customization. Shipyards in Hamburg specify multi-process systems with integrated arc monitoring, where system integrators bundle hardware with predictive maintenance subscriptions to secure multi-year contracts.
- Welding Rods:Manual electrode products for field repair and maintenance applications. Maintenance crews at aerospace MRO facilities in Toulouse favor portable stick welding for airframe patch repairs.
- Shielding Gas:High-purity argon and helium blends for oxide disruption and arc stability. European fabricators face cost pressure from energy-intensive cryogenic separation tied to natural gas price volatility.
Most installed capacity flows through Filler Wire. Expansion is steepest in Equipment.
Technology:
Maturity gradients separate established arc processes from emerging laser systems with distinct learning curve requirements.
- MIG Welding:Gas metal arc processes using continuous wire feed and external shielding gas. Automotive OEMs in Munich deploy pulsed MIG variants for thin-gauge extrusion welding in EV architectures, balancing deposition rates against heat input control.
- Laser Welding:Fiber laser beam fusion with minimal heat-affected zones for precision applications. Aerospace panel fabricators in Hamburg adopt single-mode systems for stringer-to-skin joints, where sub-millimeter distortion tolerance justifies capital intensity.
- TIG Welding:Tungsten inert gas processes offering manual control for complex geometries. Custom fabrication shops in Northern Italy retain TIG for prototype development and low-volume architectural work.
- Resistance Welding:Electric current and pressure joining for spot-weldable aluminum grades. Tier-1 suppliers in South Korea apply servo-controlled resistance welding for door panel assembly on mixed-material vehicle platforms.
Process selection concentrates in MIG Welding for throughput. Laser Welding gains share fastest in battery enclosure and aerospace applications.
End User:
Certification stringency and volume scale create divergent supplier relationship models across end-use verticals.
- Automotive OEMs:High-volume automated production with strict process qualification requirements. OEMs in Stuttgart mandate five-year total cost-of-ownership contracts with guaranteed uptime clauses, shifting procurement from hardware sales to performance-based service agreements.
- Aerospace:Material traceability and welder certification standards per EASA and FAA protocols. Airframe manufacturers in Toulouse and Hamburg require qualified filler wire suppliers with scandium-modified formulations for next-generation 7000-series alloys.
- Marine:Thick-section fabrication for superstructure and hull applications. Shipbuilders in South Korea deploy hybrid laser-arc systems for cruise vessel panels, prioritizing single-pass penetration and distortion reduction.
- Construction:Field welding for infrastructure and architectural metalwork. Bridge contractors in France specify weather-resistant aluminum alloys with on-site TIG repair capability.
Procurement volume concentrates with Automotive OEMs. Aerospace commands the steepest qualification barriers.
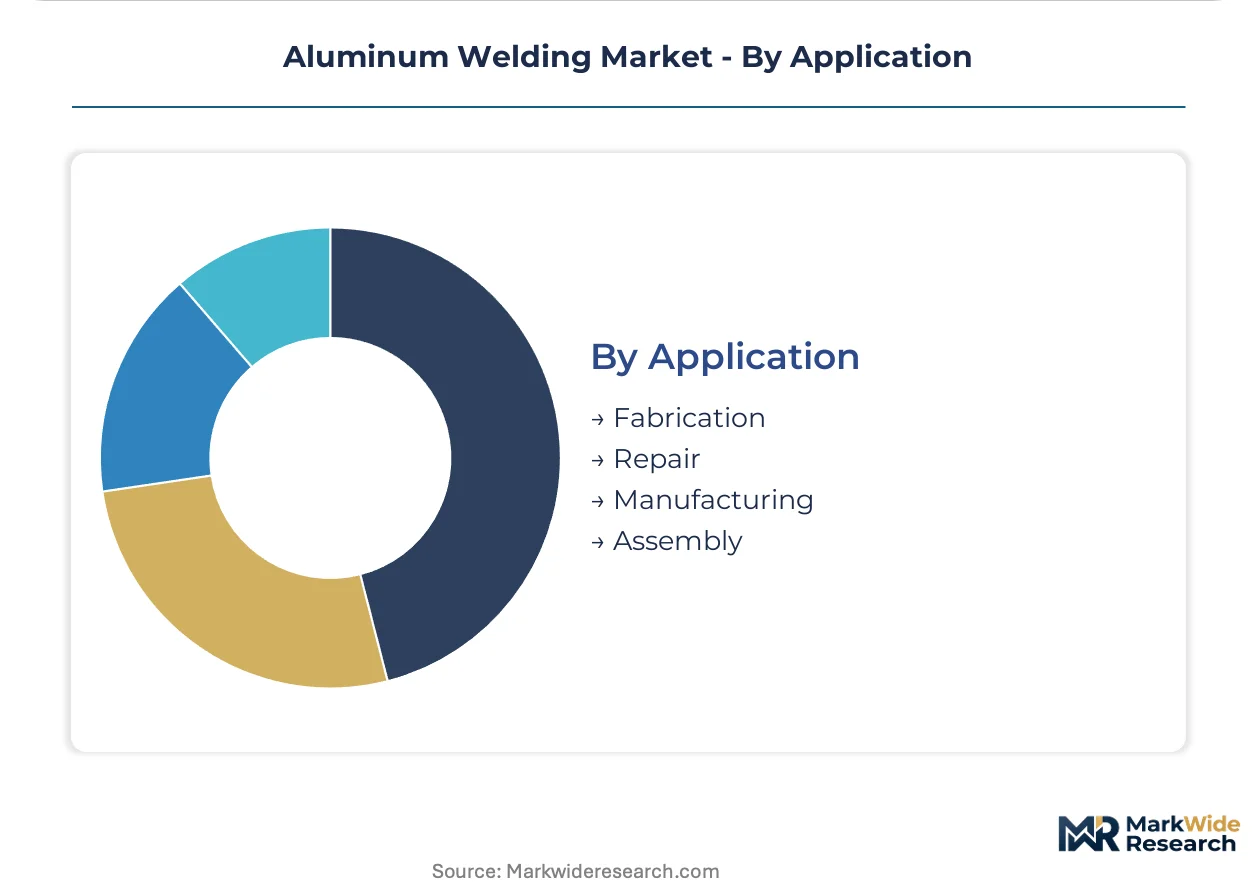
Application:
Lifecycle position determines equipment configuration and consumable specification intensity.
- Manufacturing:Original production welding with qualified processes and statistical process control. Battery tray manufacturers in Germany run automated cells with integrated vision systems for seam tracking and quality documentation.
- Repair:Field and depot maintenance requiring portable equipment and flexible procedures. Aerospace MRO stations in Hamburg perform skin panel repairs with manual TIG and qualified filler wire lots.
- Fabrication:Custom component production for structural and architectural applications. Specialty shops in Gothenburg produce aluminum facade elements with pulsed MIG for cosmetic surface quality.
- Assembly:Joining of pre-fabricated subcomponents into final systems. Automotive Tier-1s in Wolfsburg integrate resistance spot welding into mixed-material body-in-white lines.
Process standardization is highest in Manufacturing. Repair applications retain the most manual process diversity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified welding engineers in Stuttgart, Wolfsburg, and Hamburg anchor Europe's aluminum fabrication workforce, while South Korean shipyards and Chinese power electronics clusters concentrate technical talent pools in Asia.
Germany
Automotive OEMs in Stuttgart and Wolfsburg deploy automated MIG cells for EV battery tray welding at scale. The EU Green Deal carbon border adjustment mechanism tightens sourcing economics for filler wire imports. Shipyards in Hamburg adopt hybrid laser-arc systems for cruise vessel superstructure fabrication.
United States
Aerospace manufacturers in Seattle and Wichita expand aluminum welding for lightweight airframe structures to improve fuel efficiency. The EPA and OSHA govern fume exposure limits and workplace ventilation requirements in fabrication facilities. Automotive Tier-1s in Michigan integrate resistance spot welding into mixed-material body-in-white production lines.
China
Power source manufacturers in Shenzhen face extended SAMR certification timelines of 8-14 months for non-domestic suppliers. GB standards and MIIT protocols control market access for imported welding equipment. EV battery enclosure fabricators in the Yangtze River Delta region accelerate automated cell deployment.
South Korea
Shipbuilders in Ulsan and Busan deploy 10-kW fiber laser-GMAW systems for cruise vessel superstructure panels. The Ministry of Trade, Industry and Energy supports advanced manufacturing technology adoption through targeted industrial policy. Battery tray suppliers in the Seoul Capital Area expand welding capacity for export-oriented EV platform contracts.
India
PLI scheme incentives for EV manufacturing attract aluminum-intensive platform investments to Pune and Chennai. BIS standards govern welding consumable quality certification for domestic procurement. Domestic equipment distributors in Tamil Nadu and Maharashtra expand service networks to support automotive OEM localization.
Aluminum Welding Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the aluminum welding equipment and consumables landscape. The vendor base separates into integrated system bundlers, specialized consumable formulators, and regional power source assemblers. Three strategic archetypes dominate: full-stack automation integrators, captive filler wire producers, and precision beam source specialists. Competitive moves concentrate on backward integration into consumable production and predictive maintenance subscription bundling.
Among European-based fabricators, ESAB exemplifies the automation-integrator archetype through its R&D intensity across automotive OEM solutions. The Lincoln Electric Company anchors North American market presence with captive supply of filler wire production. Fronius occupies a position within the precision-tier segment, representing laser welding technology leadership for thin-gauge fabrication applications.
| Leading Market Players |
|---|
| The Lincoln Electric Company |
| ESAB |
| Hilarius Haarlem Holland B.V. |
| EWM GmbH |
| Hermann Fliess and Co. GmbH |
| Drahtwerk ELISENTAL W. Erdmann GmbH & Co. |
| Air Liquide |
| Miller Electric |
| Fronius |
| Others |
Supply Flow & Price Mechanics
Premium-laser-system versus commodity-arc-equipment divergence splits procurement budgets and supplier relationships across automotive and aerospace fabrication lines. German OEMs in Stuttgart bundle five-year predictive maintenance subscriptions with power source purchases, while Polish job shops transact filler wire on spot markets exposed to argon cost volatility.
Pricing Analysis
Bundled service contracts versus unbundled hardware sales define the dominant pricing split. Subscription-based uptime guarantees with remote diagnostics command premium positioning against transactional equipment sales. Price differentiation rests on certification grade and automation integration depth. Cost compression in standard MIG systems intensifies as Chinese power sources penetrate European distribution. Tier-1 automotive buyers exhibit lowest price sensitivity due to qualification switching costs, while independent fabricators in Czechia and Northern Italy face acute margin pressure.
Supply Chain Analysis
Dual-sourcing mandates from Hamburg shipyards and Toulouse aerospace manufacturers force qualification of redundant filler wire suppliers across Austria and Germany. Supply concentration centers on Germany, China, and South Korea for equipment final assembly. Raw material dependencies span high-purity aluminum billet, scandium alloying additions, and cryogenic argon separation capacity. Single-source vulnerability concentrates in qualified scandium-modified wire formulations for 7000-series aerospace grades. Distribution runs through system integrators bundling hardware with process software and consumable supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aluminum welding market compounds steadily as EV platform aluminum intensity rises across automotive production cycles. Lightweighting mandates and carbon border adjustments cement structural demand for precision joining solutions.
For Market Incumbents: Lock in long-term consumable supply contracts with Stuttgart and Wolfsburg OEMs before CBAM phase-in completes. Defend against emerging laser-system specialists by embedding predictive analytics subscriptions that raise switching costs. Prioritize backward integration into scandium-modified wire production to capture aerospace qualification premiums.
For New Entrants and Emerging Players: Specialized distributors in India's PLI-driven EV corridors offer the most penetrable channel entry point. Target Pune and Chennai automotive welding infrastructure buildouts where domestic service networks remain underdeveloped. Lead with portable repair-system offerings for aerospace MRO stations before expanding into qualified manufacturing cells.
For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented regional equipment assemblers lack software capabilities to meet Tier-1 subscription demands. Five-to-ten year viability favors consumable formulators with qualified aerospace wire portfolios over pure-play power source vendors. Monitor EASA scandium-alloy certification timelines as inflection signal for next-generation filler wire valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Filler Wire Production | Captive supply of qualified consumables locks in automotive OEM recurring revenue streams. |
| Predictive Maintenance Subscription Bundling | Remote arc analytics from Dutch shipbuilders pilot uptime guarantee contracts. |
| Laser-Hybrid System Qualification | Single-mode fiber adoption in Hamburg aerospace panel fabrication rewrites productivity benchmarks. |
| Scandium-Modified Wire Certification | EASA pathway completion creates first-mover metallurgical partnerships for 7000-series alloys. |
| India Service Network Expansion | Tamil Nadu and Maharashtra distributors support PLI-scheme EV platform localization. |
Methodological Framework
Direct dialogue with welding equipment procurement managers, automotive Tier-1 manufacturing engineers, aerospace quality assurance leads, and shipyard production planners grounded qualitative findings. Secondary validation drew from ECHA substance restriction filings, EU CBAM implementation guidance, SAMR certification databases, and SEC disclosures from listed welding equipment manufacturers. Bottom-up segment sizing triangulated against top-down industry production forecasts.
Segment-level projections across product type, technology, end user, and application dimensions fed analytical framework outputs throughout the forecast period. CAGRs derived from regression analysis against EV aluminum content trajectories and aerospace build rate assumptions. Industry-specific inputs incorporated laser source cost-per-watt decline curves and welder certification backlog data from IIW and EWF diploma programs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to argon price volatility and scandium supply concentration. Deviation in EU carbon border adjustment implementation pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Global Brazing Consumable Market
Metals
Aluminum Scrap Recycling Market
Metals
High Purity Aluminium Market
Metals
Metal Powder Market
Metals
Copper Azoles Market
Metals
Nickel Powder Plating Market
Metals
Zinc Plating Market
Metals
Anodized Titanium Market
Metals
Medium Carbon Steel Market
Metals
Bismuth Market
Metals
High Purity Lead Market
Metals
Global Superconducting Wire Market
Metals
North America Grain Oriented Electrical Steel Market
Metals
7075 T6 Aluminum Market
Metals
Zirconium Market
Metals
Aluminum Wire Market