
 Zinc Carbonate Market | 2026-2036
Zinc Carbonate Market Size, Share, and Industry Trends Forecast 2026-2036
Zinc Carbonate Market Outlook
Green synthesis pathways and solvent-free precipitation methods are rewriting production economics across the zinc carbonate supply chain. Shepherd Chemical leverages captive R&D infrastructure to sustain differentiated activated grades for pharmaceutical customers. Yanggu Zhongtian Zinc Industrial anchors Chinese supply through integrated zinc mining and refining operations. Bruggemann Chemical competes on European REACH certification depth, controlling access to formulated feed additive markets.
Zinc carbonate is a zinc salt of carbonic acid, typically produced via reaction of zinc sulfate with sodium carbonate or through direct carbonation of zinc oxide slurries, yielding a white crystalline powder with 56-58% zinc content used as a chemical intermediate, rubber activator, and nutritional supplement. The compound serves as a sulfur activator in rubber vulcanization and a zinc source in animal feed premixes and agricultural fertilizers. Activated zinc carbonate commands premium positioning in pharmaceutical and high-performance rubber applications where surface area and reactivity specifications drive formulation outcomes. Standard zinc carbonate dominates volume in agricultural fertilizer blending, while precipitated grades capture margin pools in specialty coatings and fine chemical synthesis.
EPA oversight of zinc-containing fertilizers and animal feed additives shapes product registration requirements and labeling standards in the United States. REACH registration and classification protocols under ECHA govern market access for European chemical distributors and downstream compounders. China's GB standards and MEE environmental discharge rules constrain small-scale producers, concentrating supply among integrated manufacturers. Stakeholders must monitor evolving pharmaceutical excipient monographs and veterinary feed directive harmonization to anticipate procurement specification shifts.
Market Dynamics
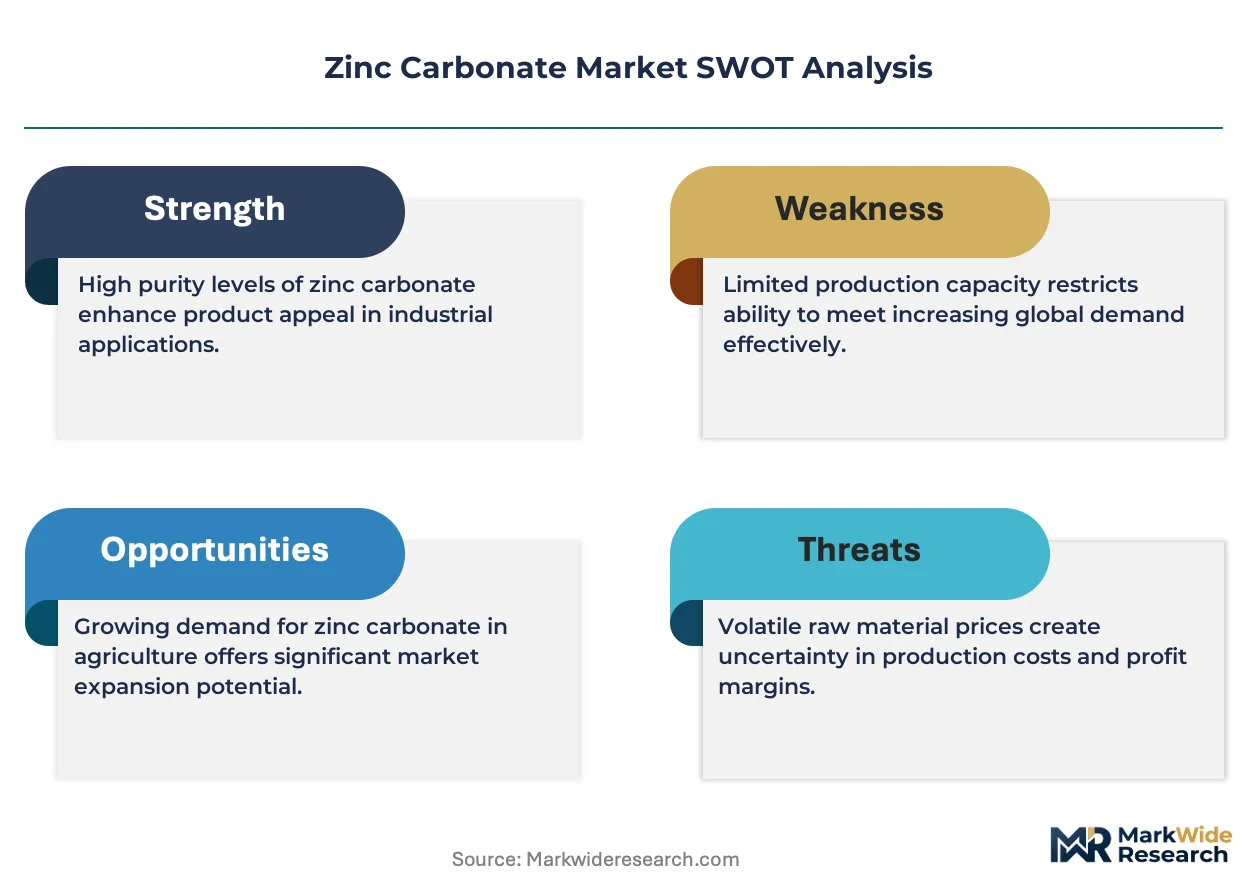
REACH registration deadlines and EPA fertilizer oversight are compressing supplier margins while concentrating procurement among certified producers capable of documenting full material provenance.
Growth Catalysts
- Pharmaceutical excipient tightening:Tablet manufacturers demand activated grades with documented surface area specifications, pulling supply toward pharmaceutical-certified producers.
- China's dual carbon goals:MEE environmental discharge rules are shuttering small-scale carbonate operations, consolidating volume among integrated zinc refiners with captive acid gas recovery.
- Rubber vulcanization chemistry:Sulfur activation requirements in tire manufacturing sustain baseline demand for high-reactivity carbonate grades across automotive supply chains.
Market Restraints
- Zinc concentrate volatility:Smelter treatment charges and mined ore grade decline transmit directly to carbonate input costs, squeezing precipitated grade margins.
- Substitution by zinc oxide:Direct oxide addition in some fertilizer and feed formulations bypasses carbonate intermediation, capping volume in commodity applications.
- REACH authorization bottlenecks:ECHA substance evaluation delays for zinc compounds extend registration timelines, freezing market access for non-compliant distributors.
Strategic Opportunities
- India feed premix formalization:FSSAI and BIS standards convergence is displacing informal zinc sources in poultry and cattle nutrition, opening certified carbonate penetration.
- Solvent-free precipitation:Carbonation of zinc oxide slurries without sodium carbonate intermediate is hybridizing production economics and waste profiles.
- Veterinary feed directive harmonization:EU and US regulatory alignment on trace mineral bioavailability is creating cross-border specification standards for pharmaceutical-grade material.
Industry Challenges
- Pharmaceutical monograph compliance:USP and EP excipient certification timelines stretch 18-24 months, blocking rapid market entry for new production capacity.
- Analytical capability gaps:Surface area and particle size distribution testing infrastructure is scarce outside integrated chemical majors, constraining quality differentiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zinc Carbonate Market |
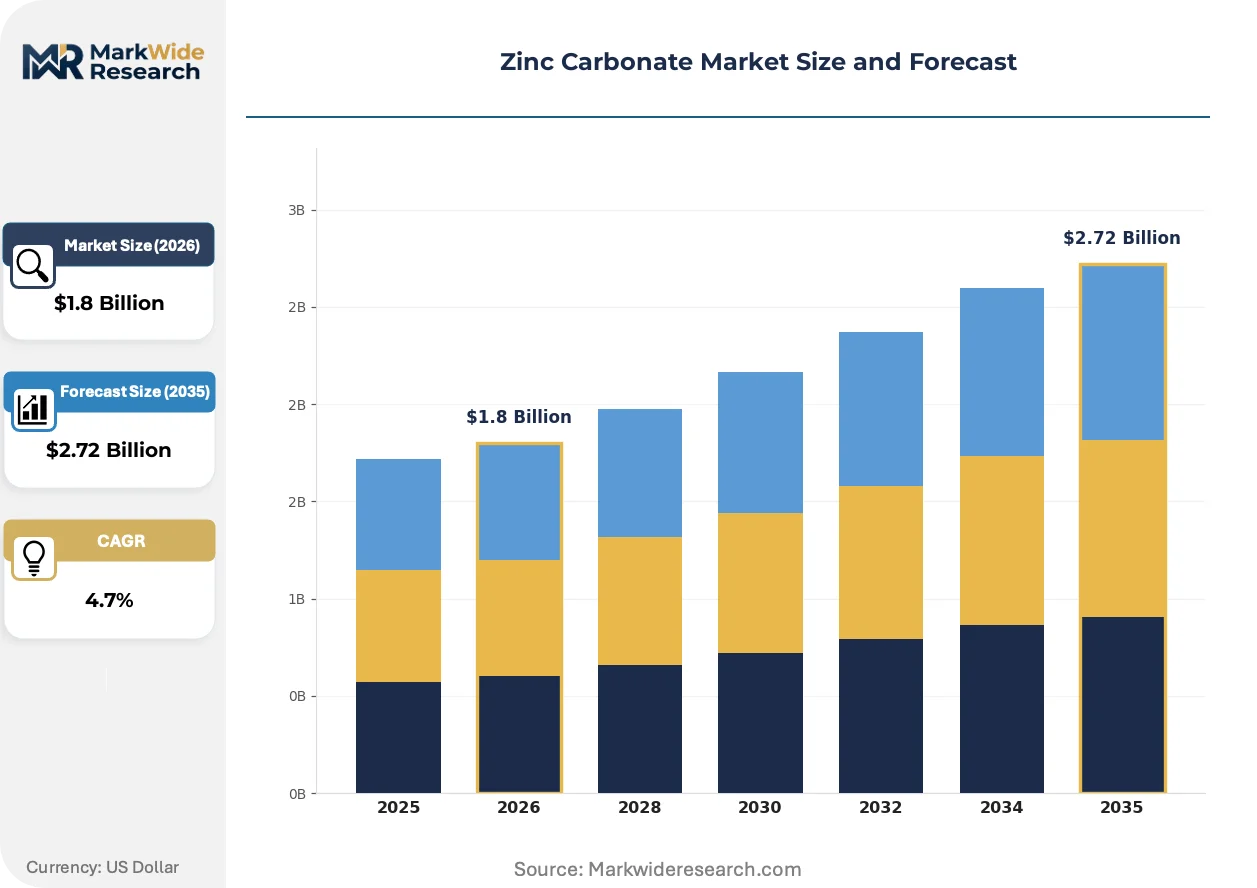
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Zinc Carbonate, Activated Zinc Carbonate, Precipitated Zinc Carbonate, Granular Zinc Carbonate End Use Industry: Pharmaceuticals, Agriculture, Chemicals, Plastics Application: Fertilizers, Animal Feed, Rubber Compounding, Coatings Packaging Type: Bags, Drums, Bulk, Pallets |
| Companies Covered | Bruggemann Chemical, Shepherd Chemical, TIB Chemicals, Yanggu Zhongtian Zinc Industrial, Pan-Continental Chemical, Seido Chemical Industry, Rubamin, Transpek-Silox, Global Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zinc Carbonate Market Strategic Shifts
Production chemistry and regulatory documentation requirements are restructuring competitive advantage toward integrated producers with captive analytical and certification infrastructure.
Continuous carbonation reactor design is hybridizing batch precipitation economics. Tire manufacturers and pharmaceutical formulators adopt these grades for tighter particle size distribution. The technology is compressing cost structures for mid-scale producers previously locked out of premium segments.
REACH SCIP database obligations and extended producer responsibility frameworks now govern zinc compound traceability. Downstream compounders must document full supply chain substance identity. Pharmaceutical and automotive rubber segments are responding by consolidating supplier panels to pre-registered, fully documented producers.
Specification-driven procurement now dominates pharmaceutical and high-performance rubber purchasing. Buyers unbundle spot market sourcing in favor of multi-year supply agreements with embedded certification maintenance. This pattern is most visible across EU and US pharmaceutical manufacturing clusters where excipient master file obligations create switching friction.
Zinc Carbonate Market Segmentation

Segmentation in zinc carbonate markets separates specification-driven pharmaceutical procurement from commodity agricultural offtake. Cycle times and margin profiles diverge sharply across these boundaries, reshaping supplier investment priorities and inventory strategies.
Product Type:
Activated grades turn inventory fastest through pharmaceutical channels, while standard material sits longer in agricultural distribution. Precipitated variants occupy intermediate velocity tiers tied to coatings seasonality.
- Standard Zinc Carbonate:Basic 56-58% zinc content powder produced via conventional sulfate-carbonate precipitation. Agricultural fertilizer blenders in China and India anchor volume, though substitution by direct zinc oxide addition caps pricing power in commodity feed applications.
- Activated Zinc Carbonate:Engineered for elevated surface area and reactivity through controlled precipitation parameters. Pharmaceutical tablet manufacturers and high-performance rubber compounders concentrate demand, with REACH and USP documentation requirements creating multi-year supplier lock-in.
- Precipitated Zinc Carbonate:Ultra-fine particle grades for specialty coatings and fine chemical synthesis.
- Granular Zinc Carbonate:Low-dust agglomerated form for automated feed handling systems.
Standard zinc carbonate dominates installed base. Activated zinc carbonate is where expansion concentrates.
End Use Industry:
Margin structures stratify sharply: pharmaceutical customers pay certification premiums, agricultural buyers negotiate on zinc unit economics, and chemical processors demand technical service depth.
- Pharmaceuticals:Excipient-grade material for tablet formulations and mineral supplements. US FDA and EMA pharmaceutical master file obligations stretch qualification timelines to 18-24 months, entrenching incumbent suppliers with documented batch histories.
- Agriculture:Zinc source in NPK fertilizer blends and animal feed premixes. India's FSSAI feed formalization and China's MEE environmental enforcement are displacing informal suppliers, consolidating certified carbonate penetration.
- Chemicals:Intermediate for zinc derivative synthesis and catalyst preparation.
- Plastics:Thermal stabilizer additive in PVC compounding.
Agriculture commands the volume base. Pharmaceuticals deliver the steepest expansion trajectory.
Application:
Application-level procurement splits between formulation integration depth and standalone mineral supplementation, with rubber chemistry demanding the tightest specification bandwidth.
- Fertilizers:Micronutrient correction in zinc-deficient soils. China's GB fertilizer standards and EPA fertilizer oversight in the United States govern product registration and labeling compliance.
- Animal Feed:Trace mineral premix for poultry, cattle, and swine nutrition. EU veterinary feed directive harmonization with US FDA guidelines is creating cross-border specification standards for bioavailability-tested material.
- Rubber Compounding:Sulfur activator in tire and industrial rubber vulcanization. Automotive supply chain qualification protocols favor producers with continuous carbonation reactor technology and documented particle size distribution control.
- Coatings:Corrosion inhibitor and pigment extender in protective paints.
Fertilizers anchor the installed demand base. Rubber compounding is where specification premiums expand fastest.
Packaging Type:
Packaging selection tracks customer scale and handling automation, with bulk formats compressing per-unit logistics cost for integrated compounders.
- Bags:25-50 kg multi-wall paper or woven polypropylene for mid-scale agricultural and chemical processors.
- Drums:Fiber or steel containment for pharmaceutical and coatings applications requiring moisture protection and lot traceability.
- Bulk:Pneumatic discharge for high-volume fertilizer blenders and feed mills with silo infrastructure.
- Pallets:Unitized load formats for automated warehouse handling in rubber and plastics manufacturing.
Bags dominate the installed base. Bulk formats are where logistics efficiency investments concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in zinc carbonate track the geographic distribution of integrated zinc refining and downstream rubber compounding capacity. Countries with captive zinc mining and smelting infrastructure dominate outbound shipments, while pharmaceutical and automotive manufacturing clusters drive inbound demand for certified grades.
China
Yanggu Zhongtian Zinc Industrial and downstream rubber compounders anchor regional consumption of standard and activated grades. MEE environmental discharge rules under the dual carbon goals are shuttering small-scale carbonate operations, consolidating supply among integrated refiners with captive acid gas recovery. The Shandong and Jiangsu provinces concentrate tire manufacturing demand.
United States
Pharmaceutical formulators in New Jersey and North Carolina drive demand for USP-certified activated grades with documented surface area specifications. EPA fertilizer oversight and state-level registration requirements shape product labeling standards for agricultural applications. The Southeast automotive corridor sustains rubber vulcanization demand through tire plants in South Carolina and Tennessee.
Germany
REACH registration depth controls market access for European chemical distributors and downstream compounders. Bruggemann Chemical leverages ECHA certification to supply formulated feed additive markets. The Rhine-Ruhr industrial cluster anchors specialty coatings demand, while Bavaria's automotive supply chain qualifies precipitated grades for tire manufacturing.
India
FSSAI and BIS standards convergence is displacing informal zinc sources in poultry and cattle nutrition, opening certified carbonate penetration. Gujarat and Maharashtra concentrate animal feed premix manufacturing. The country's fertilizer subsidy framework directs micronutrient procurement toward registered suppliers with documented zinc content verification.
Japan
METI industrial standards and PMDA pharmaceutical regulations govern excipient-grade material qualification. The Kansai rubber manufacturing belt around Osaka sustains demand for high-reactivity carbonate in precision tire compounding. Domestic producers focus on pharmaceutical and electronics-grade specialties, importing standard material for agricultural applications.
Zinc Carbonate Market Competitive Environment
On the supply side, the industry is consolidating around integrated zinc refiners with captive carbonate precipitation capacity and certified pharmaceutical-grade producers with documented batch histories. Three archetypes dominate: mining-integrated refiners controlling raw material input costs, specialty chemical houses with REACH and USP certification infrastructure, and regional compounders serving agricultural and feed markets. Capacity expansion and certification depth represent the dominant competitive moves, with producers investing in continuous carbonation reactor technology and excipient master file documentation.
Among integrated mining-chemical producers, Yanggu Zhongtian Zinc Industrial exemplifies the captive refiner archetype with upstream zinc smelting control. Shepherd Chemical and Bruggemann Chemical occupy positions within the certification-driven specialty tier, representing pharmaceutical and feed additive market access strategies respectively. These three anchors illustrate the structural divergence between volume-scale commodity supply and specification-premium specialty positioning.
| Leading Market Players |
|---|
| Bruggemann Chemical |
| Shepherd Chemical |
| TIB Chemicals |
| Yanggu Zhongtian Zinc Industrial |
| Pan-Continental Chemical |
| Seido Chemical Industry |
| Rubamin |
| Transpek-Silox |
| Global Chemical |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Shandong province carbonate precipitation facilities is compressing spot pricing for standard grades while simultaneously concentrating contract negotiations among integrated refiners with captive zinc oxide supply. This utilization imbalance rewards producers with backward integration into zinc smelting, as marginal operators absorb treatment charge volatility without pricing power.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across tire manufacturing and pharmaceutical formulator procurement. Pricing stratifies across pharmaceutical-certified, REACH-documented, and commodity agricultural tiers, with certification depth and surface area specifications commanding substantial premiums. Cost compression in standard grades is intensifying because Yanggu Zhongtian Zinc Industrial and similar integrated producers leverage captive raw material positions. Agricultural fertilizer blenders exhibit the highest price sensitivity, while pharmaceutical tablet manufacturers prioritize batch documentation over unit economics.
Supply Chain Analysis
Contract manufacturing concentration rests with Yanggu Zhongtian Zinc Industrial, Shepherd Chemical, and Bruggemann Chemical controlling precipitation capacity across China, the United States, and Germany. Raw material feeds draw from zinc concentrate smelters, sodium carbonate suppliers, and acid gas recovery systems. Single-source vulnerability concentrates around Shandong province environmental enforcement actions shuttering smaller competitors. Distribution runs through multi-wall bag and bulk pneumatic channels for agricultural compounders, with drum formats serving pharmaceutical lot traceability requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of continuous carbonation reactor engineering talent and USP excipient master file documentation expertise is concentrating competitive advantage among producers with decade-long batch histories. This capability gap widens as pharmaceutical qualification timelines extend.
For Market Incumbents: Entrench pharmaceutical supplier panels through embedded certification maintenance and multi-year supply agreements with automated reorder triggers. Add continuous carbonation capacity in Jiangsu province to capture tire manufacturer qualification protocols. Defend against zinc oxide substitution in fertilizer applications by demonstrating superior bioavailability metrics in feed premix trials.
For New Entrants and Emerging Players: India's Maharashtra and Gujarat feed premix markets present the most penetrable white-space opportunity as FSSAI formalization displaces informal zinc sources. Target solvent-free precipitation technology licensing to mid-scale agricultural compounders seeking waste profile improvements. Lead with veterinary feed directive harmonization compliance as the go-to-market angle for cross-border specification acceptance.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because REACH and USP documentation moats deepen with each registration cycle. Acquisition candidates should display integrated zinc refining positions or captive analytical infrastructure for surface area testing. Watch for ECHA substance evaluation delays as the signal indicating extended registration timelines and frozen market access for non-compliant distributors.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Zinc Smelting | Captive concentrate supply insulates Yanggu Zhongtian Zinc Industrial from treatment charge volatility. |
| Continuous Carbonation Reactor Deployment | Tighter particle size distribution qualifies producers for automotive tire manufacturer panels. |
| USP Excipient Master File Investment | Eighteen-month qualification timelines lock pharmaceutical formulators into documented supplier relationships. |
| Solvent-Free Precipitation Transition | Waste profile improvements align with MEE environmental discharge rules under dual carbon goals. |
| Long-Term Supply Agreement Structuring | Multi-year contracts with embedded certification maintenance reduce spot market exposure for REACH-registered grades. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across pharmaceutical tablet manufacturers, tire compounders, and fertilizer blenders. Primary interviews with plant managers, procurement leads at downstream OEMs, and technical R&D directors combined with secondary validation from customs trade data, SEC filings, and ECHA registration databases. Bottom-up capacity modeling and top-down demand aggregation triangulated volume estimates across the projection horizon.
Calibration against historical price realizations and capacity utilization rates informed the analytical framework. Segmentation dimensions modeled include grade tier, end-use industry, packaging format, and regional production hub. CAGRs derived from slope analysis of segment-specific demand curves incorporate zinc concentrate treatment charge trajectories and pharmaceutical excipient specification tightening as industry-specific forecast inputs.
Practitioners should monitor ECHA substance evaluation timelines and MEE environmental enforcement intensity for early signals of supply consolidation or registration bottlenecks. Forecasts reflect assumptions about regulatory continuity and concentrate grade availability. Quarterly review of smelter treatment charge movements and pharmaceutical master file submission rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Calcium Chloride Market
Bulk Chemicals
North America Sodium Chloride Market
Bulk Chemicals
Ceric Ammonium Nitrate Market
Bulk Chemicals
Methionine Market
Bulk Chemicals
North America Caustic Potash Market
Bulk Chemicals
Lithium Chloride Market
Bulk Chemicals
North America and Europe Palm Derivatives Market
Bulk Chemicals
Ground Calcium Carbonate Market
Bulk Chemicals
DL-Methionine Market
Bulk Chemicals
Phosphorus and Derivatives Market
Bulk Chemicals
Global Ammonium Chloride Market
Bulk Chemicals
Oman Sodium Hydroxide Market
Bulk Chemicals
Electronic Batio3 Powder Market
Bulk Chemicals
Calcium Bromide Market
Bulk Chemicals
Mexico Caustic Soda Market
Bulk Chemicals
Global Anthracite Market