
 Global Vinyl Chloride Monomer Market | 2026-2036
Global Vinyl Chloride Monomer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vinyl Chloride Monomer Market Intelligence
A shift from multi-source procurement toward dedicated, long-term supply agreements is restructuring the market's competitive dynamics. Major producers like Formosa Plastics Corporation leverage immense scale in downstream PVC manufacturing. Occidental Petroleum Corporation specializes in ethylene-based VCM production routes. Meanwhile, Westlake Chemical Corporation sustains its position through significant backward integration into ethylene feedstock.
Vinyl chloride monomer is a colorless organochloride gas, essential as the primary precursor for polyvinyl chloride (PVC). It is produced commercially through the thermal cracking of ethylene dichloride (EDC) at high temperatures. Within applications, Polyvinyl Chloride Production accounts for the vast majority of VCM consumption. The thermal cracking technology route remains dominant due to its established infrastructure and efficiency, although catalytic reaction methods are explored for potential energy savings.
The market operates under stringent environmental regulations. The US Environmental Protection Agency (EPA) enforces strict air emission limits for VCM facilities. In Europe, the substance is regulated under the ECHA's REACH framework. China's Ministry of Ecology and Environment (MEE) also imposes tight controls on production. Strategic planning for producers now depends on navigating feedstock volatility while meeting increasingly strict global emissions standards.
Market Dynamics
The central tension in the vinyl chloride monomer market is the conflict between cost-driven production, heavily reliant on volatile ethylene feedstock prices, and the increasing capital expenditure required to comply with stringent global air emission standards.
Growth Catalysts
- Infrastructure Expansion:Sustained investment in construction and public works, particularly in China and India, drives demand for PVC pipes, window profiles, and flooring, directly consuming VCM.
- Bio-Based Feedstocks:The development of bio-ethylene from renewable sources like sugarcane offers a pathway to produce VCM with a lower carbon footprint, appealing to sustainability-focused end markets.
- Medical Grade PVC:Growth in the healthcare sector increases the need for high-purity VCM to produce medical-grade PVC for applications like IV bags, tubing, and medical device components.
Market Restraints
- Feedstock Volatility:VCM production costs are directly tied to the price of ethylene and chlorine, whose markets are subject to significant price swings based on energy costs and geopolitical events.
- Regulatory Pressure:Strict air emission limits enforced by agencies like the US EPA and China's MEE require costly abatement technologies, adding to operational expenses and capital investment hurdles.
- Carcinogenicity Classification:VCM's classification as a known human carcinogen necessitates rigorous occupational safety protocols and limits its direct consumer applications, constraining market boundaries.
Strategic Opportunities
- Chemical Recycling:Developing advanced chemical recycling processes to break down post-consumer PVC waste back into VCM can create a circular economy and a new source of feedstock.
- Catalytic Process Innovation:Research into new catalytic reaction methods for EDC cracking promises lower energy consumption and higher selectivity compared to traditional thermal cracking, offering cost advantages.
- Emerging Economies:Urbanization and infrastructure development in Southeast Asian and African nations represent long-term growth frontiers for VCM demand as PVC consumption rises.
Industry Challenges
- Capital-Intensive Infrastructure:The construction of new, world-scale VCM and integrated PVC facilities requires massive upfront capital investment, creating high barriers to entry for non-integrated players.
- Hazardous Material Logistics:Transporting VCM, a toxic and flammable gas, involves specialized, costly logistics and adherence to stringent international transportation codes, complicating supply chains.
- Compliance Divergence:Producers must navigate a complex and often divergent web of environmental and safety regulations, such as the EU's REACH versus US EPA standards, for global market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vinyl Chloride Monomer Market |
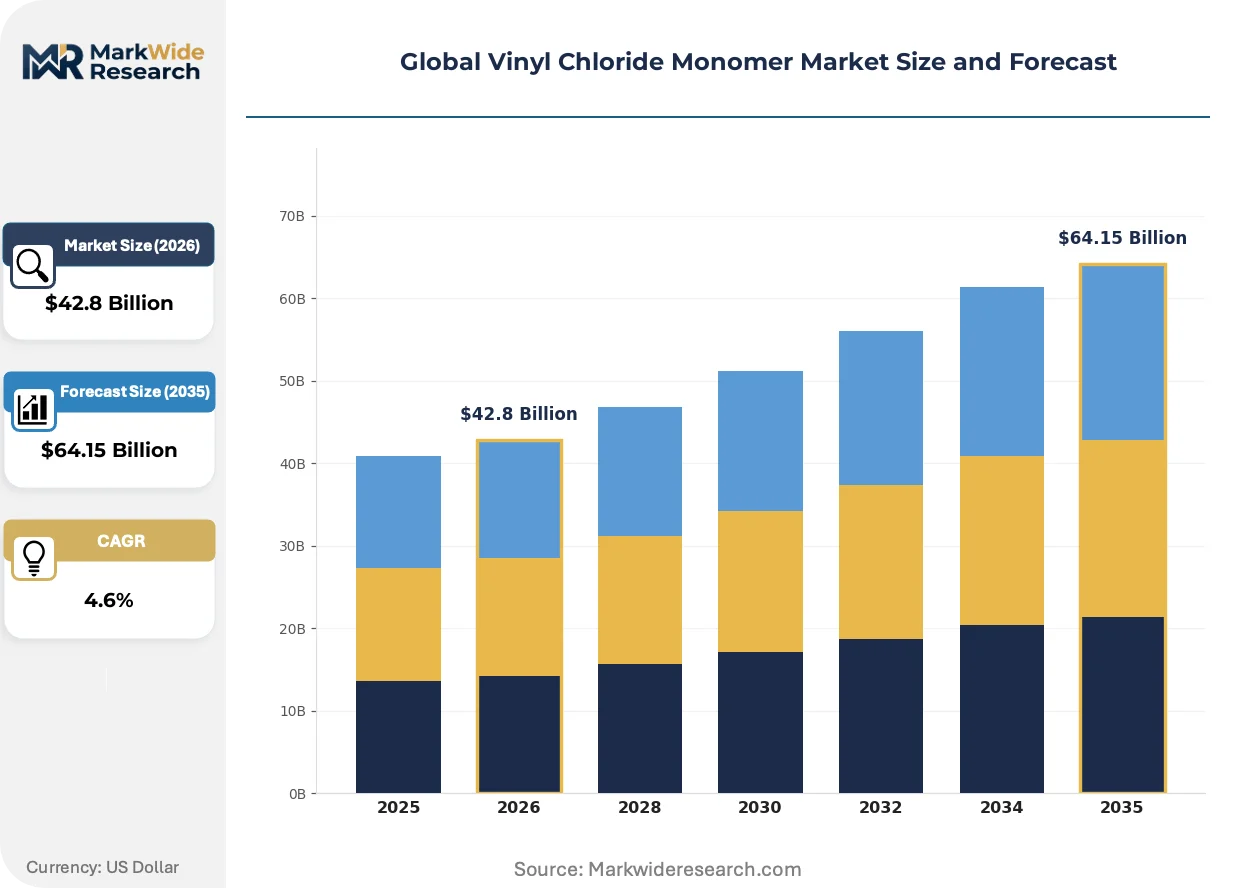
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $64.15 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid VCM, Gaseous VCM, Stabilized VCM, Purified VCM Technology: Thermal Cracking, Catalytic Reaction, Dehydrochlorination, Suspension Polymerization, Emulsion Polymerization Application: Polyvinyl Chloride Production, Synthetic Fiber, Adhesives Manufacturing, Coatings, Plasticizers End User Industry: Construction Materials, Electrical Components, Packaging Solutions, Automotive Suppliers, Textile Manufacturing |
| Companies Covered | Formosa Plastics Corporation, Occidental Petroleum Corporation, Dow, The Axiall Corporation, NOVA Chemicals, Mexichem, Olin Corporation, Tosoh Corporation, Westlake Chemical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vinyl Chloride Monomer Market Strategic Shifts & Innovations
The market's evolution is defined by a dual pursuit of operational efficiency and environmental sustainability. This push originates from both internal process optimization efforts and external pressures from regulators and downstream customers demanding greener supply chains.
Bio-ethylene, derived from sources like bio-ethanol, provides a renewable pathway to produce ethylene dichloride and VCM. PVC manufacturers serving the packaging and consumer goods sectors are driving initial adoption. This green feedstock route is expanding into specialty PVC applications where a certifiably lower carbon footprint commands a premium.
Europe's REACH framework, administered by the ECHA, mandates comprehensive safety data for chemicals like VCM. This regulation increases compliance burdens for producers and importers operating within the European Union. Downstream formulators of PVC compounds are most affected, as they must document the compliance of their entire upstream VCM supply.
A significant behavioral change involves large PVC converters moving away from spot-based VCM procurement. They are instead locking in multi-year supply contracts with major producers to ensure price stability and supply security. This trend is most pronounced in China, where supply continuity for large-scale infrastructure projects is a primary concern.
Global Vinyl Chloride Monomer Market Segmentation
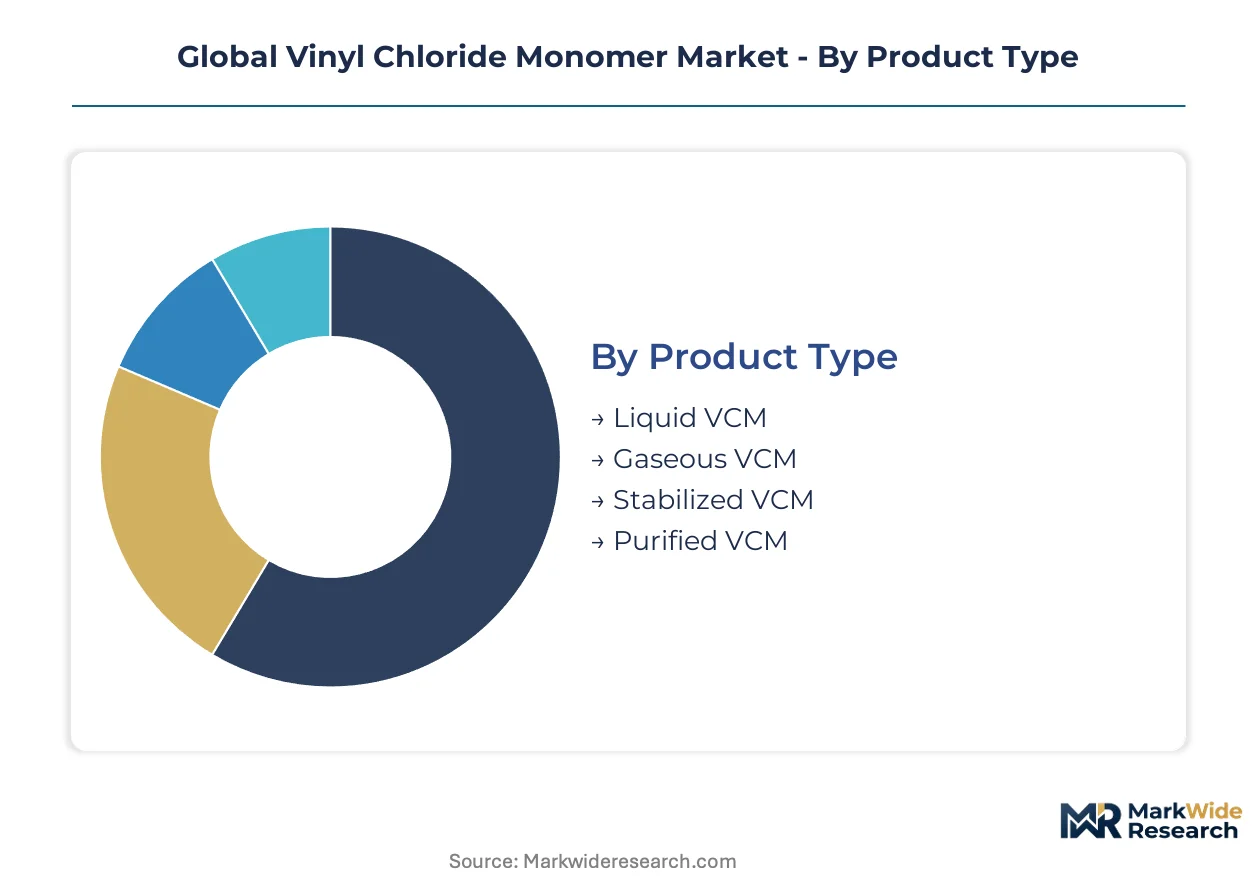
Market segmentation for vinyl chloride monomer clarifies the distinct forms, production methodologies, and downstream uses influencing overall demand. Understanding these categories helps producers align their operational strategies with specific market requirements, from bulk commodity supply to specialized niche applications.
Product Type:
Product type segmentation for vinyl chloride monomer reveals how different forms are either standalone commodities or integrated components within downstream chemical processes.
- Gaseous VCM:This is the primary commercial form of VCM, a colorless organochloride gas maintained under pressure for transport and storage. Its high purity and gaseous state are essential for direct polymerization into polyvinyl chloride, driving demand in China's extensive PVC manufacturing sector.
- Purified VCM:This segment involves VCM that undergoes additional purification steps to remove trace impurities, ensuring extremely high purity levels. Demand for purified VCM is expanding within specialized medical-grade PVC applications, particularly for sensitive healthcare devices in Europe and the United States.
- Liquid VCM:VCM can be stored and transported as a liquid under specific pressure and temperature conditions, offering logistical advantages for certain industrial users. This form facilitates easier handling for smaller batch processes or specific chemical synthesis routes.
- Stabilized VCM:This VCM variant contains inhibitors to prevent premature polymerization or degradation during extended storage and transport. Stabilized VCM ensures product integrity for long-distance shipments to diverse global markets.
Volume placements concentrate in Gaseous VCM; the faster expansion belongs to Purified VCM.
Technology:
Technology segmentation highlights the varying efficiency and capital intensity inherent in VCM production methods.
- Thermal Cracking:This established technology involves heating ethylene dichloride (EDC) to high temperatures, typically 450-550°C, to produce VCM and hydrogen chloride. Thermal cracking remains the backbone of global VCM production due to its proven reliability and large-scale operational efficiency, particularly in facilities across the United Gulf States.
- Catalytic Reaction:This emerging technology explores the use of catalysts to lower reaction temperatures and improve selectivity in EDC cracking, offering potential energy savings and reduced by-product formation. Research into catalytic processes is attracting investment from major chemical companies in Germany and Japan seeking greener production routes.
- Dehydrochlorination:This process converts 1,2-dichloroethane (EDC) directly to VCM by removing hydrogen chloride, often achieved through thermal cracking or catalytic methods. Dehydrochlorination is a core chemical transformation step in integrated VCM production plants.
- Suspension Polymerization:While not a VCM production technology, this refers to the primary method for polymerizing VCM into PVC resin, where VCM droplets are suspended in water. Suspension polymerization yields the most common type of PVC, used extensively in construction.
- Emulsion Polymerization:This method polymerizes VCM in an aqueous emulsion, producing fine PVC particles suitable for specific applications like coatings and pastes. Emulsion polymerization creates specialized PVC grades for flexible applications.
Thermal Cracking technology dominates current output, while Catalytic Reaction methods show the steepest expansion trajectory for future VCM production.
Application:
Application segmentation demonstrates the diverse end-use spectrum where VCM derivatives contribute to material properties and product functionality.
- Polyvinyl Chloride Production:VCM serves as the essential monomer for producing polyvinyl chloride (PVC), the world's third-most widely produced synthetic plastic polymer. This application consumes the vast majority of VCM output, supporting construction and infrastructure projects globally.
- Adhesives Manufacturing:VCM derivatives, particularly certain vinyl acetate copolymers, find use in specialized adhesive formulations requiring specific bonding properties and chemical resistance. This segment values VCM for its contribution to durable and high-performance adhesive products.
- Synthetic Fiber:While a smaller application, VCM-derived co-polymers are used in the production of certain synthetic fibers, enhancing properties like flame retardancy and chemical resistance. These fibers find niche applications in protective clothing and industrial textiles.
- Coatings:Vinyl chloride co-polymers are incorporated into various coating formulations, providing durability, weather resistance, and adhesion to different substrates. Coatings using VCM derivatives protect metal and concrete surfaces in industrial settings.
- Plasticizers:Although VCM is a monomer, its derivatives contribute to the production of plasticizers that enhance the flexibility and workability of PVC. Plasticizers are crucial for soft PVC products like electrical cable insulation and flooring.
Polyvinyl Chloride Production consumes the vast majority of VCM, but specialized applications like Adhesives Manufacturing are gaining share fastest.
End User Industry:
End user industry segmentation reflects the primary demand drivers for VCM, tied to infrastructure development and consumer product manufacturing.
- Construction Materials:This industry represents the largest end-user segment for VCM, primarily through its conversion into PVC for pipes, window frames, roofing, and flooring. Sustained infrastructure investment in countries like India and China fuels this demand.
- Electrical Components:PVC, derived from VCM, is extensively used in the electrical industry for wire and cable insulation due to its excellent dielectric properties and flame retardancy. Strict safety standards in the United States and Europe drive demand for high-performance PVC in this sector.
- Packaging Solutions:Rigid and flexible PVC films, bottles, and blister packaging utilize VCM-derived polymers, providing barrier properties and cost-effectiveness for various consumer goods. This application supports the food and pharmaceutical packaging markets.
- Automotive Suppliers:PVC finds applications in automotive interiors, underbody coatings, and wire harnesses, offering durability, sound dampening, and resistance to chemicals. The automotive sector in Germany and Japan employs PVC for lightweight and durable components.
- Textile Manufacturing:VCM derivatives are used in certain textile coatings and synthetic leather production, imparting waterproof properties and wear resistance. This segment serves specialized apparel and upholstery markets.
Construction Materials account for the largest VCM consumption, with Electrical Components exhibiting significant growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration for vinyl chloride monomer is primarily anchored in China, driven by its extensive industrial and infrastructure projects. This global market sees significant consumption across various developing and industrialized nations. Other key regions like India, the United States, and Europe also contribute substantially to overall VCM demand.
China
Infrastructure expansion and vast industrial projects drive substantial VCM demand for PVC manufacturing within China. The Ministry of Ecology and Environment (MEE) imposes stringent controls on VCM production emissions. The Yangtze River Delta region, a major industrial cluster, continues to expand its PVC production capabilities.
India
Sustained investment in construction and public works, alongside rapid urbanization, fuels India's VCM consumption for PVC applications. The Bureau of Indian Standards (BIS) sets quality benchmarks for PVC products, influencing VCM purity requirements. Gujarat's chemical hubs are significant centers for VCM processing and downstream PVC conversion.
United States
The United States exhibits strong demand for VCM, particularly for medical-grade PVC and electrical components. The US Environmental Protection Agency (EPA) enforces strict air emission limits for VCM facilities. The Gulf Coast states host a concentrated cluster of major VCM and integrated PVC manufacturing operations.
Germany
Germany's VCM demand stems from specialized PVC applications and ongoing research into greener production routes. The European Chemicals Agency (ECHA) regulates VCM under the comprehensive REACH framework. Chemical parks in North Rhine-Westphalia concentrate on advanced material development and process innovation for VCM derivatives.
Saudi Arabia
Saudi Arabia's market position involves large-scale thermal cracking operations supporting downstream petrochemical expansion. The nation's environmental standards are evolving for industrial emissions, impacting VCM production practices. Jubail Industrial City, a key industrial hub, contains major VCM production facilities for regional and global supply.
Global Vinyl Chloride Monomer Market Key Industry Players
Securing long-term supply agreements dominates the current landscape, restructuring competitive dynamics as major PVC converters seek price stability. The market features large-scale commodity producers, specialized technology providers, and integrated feedstock players. Key competitive moves include strategic backward integration and continuous capacity optimization to manage cost volatility.
Scale-driven players like Formosa Plastics Corporation leverage immense manufacturing capacity in downstream polyvinyl chloride production. Occidental Petroleum Corporation occupies a position specializing in ethylene-based VCM production routes. Meanwhile, Westlake Chemical Corporation exemplifies significant backward integration into ethylene feedstock, securing its upstream supply chain.
| Leading Market Players |
|---|
| Formosa Plastics Corporation |
| Occidental Petroleum Corporation |
| Dow |
| The Axiall Corporation |
| NOVA Chemicals |
| Mexichem |
| Olin Corporation |
| Tosoh Corporation |
| Westlake Chemical Corporation |
| Others |
Cost & Logistics Intelligence
The global ethylene price index, a key commodity benchmark, cascades through the vinyl chloride monomer supply chain, directly influencing production costs and subsequent pricing tiers for VCM. This volatility is a constant challenge for producers and downstream converters.
Pricing Analysis
Volume-based contracts dominate the VCM market, particularly for large-scale polyvinyl chloride converters, ensuring supply stability over margin maximization. Price differentiation stems from purity levels, especially for medical-grade VCM, and geographic delivery costs. Pricing softness reflects intense competition among commodity producers and the high capital costs associated with new capacity. Large PVC manufacturers are less price-sensitive due to long-term supply agreements, while smaller, spot-market buyers exhibit higher price sensitivity.
Supply Chain Analysis
Workforce availability, particularly for specialized chemical operations in China and the United States, impacts VCM production efficiency and localized supply. Geographic supply concentrates in China, the United States, and Saudi Arabia, reflecting established infrastructure and feedstock access. The VCM supply chain draws from ethylene and chlorine as primary raw materials. Hazardous material logistics for VCM transportation represent a significant structural risk. Distribution runs through direct sales channels to large, integrated PVC manufacturing facilities globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vinyl chloride monomer market is entering a consolidation phase, driven by the immense capital expenditure required for regulatory compliance, which forces out smaller, less integrated players.
For Market Incumbents:
Acquire advanced catalytic cracking technologies to reduce energy consumption and improve environmental footprints. Deepen backward integration into ethylene feedstock production to mitigate price volatility and secure supply. Invest in chemical recycling research for post-consumer PVC waste, creating a circular economy. This addresses the threat of increasingly strict global emissions standards and feedstock price fluctuations.
For New Entrants and Emerging Players:
Enter via niche applications, such as high-purity VCM for medical-grade PVC, leveraging sustainability credentials. Target emerging economies in Southeast Asia and Africa where infrastructure development drives PVC demand. A go-to-market angle focused on bio-based VCM offers a premium for sustainability-focused end markets. This strategy bypasses the capital-intensive commodity VCM production.
For Investors and Strategic Acquirers:
Distressed-cycle entries favor integrated producers in the United States and Saudi Arabia with strong feedstock positions. The long-term viability of VCM is anchored in sustained global demand for PVC in construction and infrastructure. Acquisition targets should include companies pioneering greener production routes or possessing significant backward integration. A signal to watch is the commercialization progress of bio-ethylene production for VCM.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Gulf States | Increases global VCM supply for growing Asian markets while leveraging cost-advantaged feedstock. |
| Backward Integration into Ethylene | Mitigates feedstock price volatility and enhances supply security for VCM producers. |
| Green Manufacturing Transition | Reduces environmental impact and meets stringent regulatory requirements for VCM facilities. |
| Long-term Supply Agreements | Ensures stable VCM procurement for major PVC converters, locking in prices. |
| Chemical Recycling Investment | Creates a circular economy for PVC, providing alternative VCM feedstock sources. |
Research Approach
Multi-period observation of VCM production volumes and feedstock price trends anchored the trend analysis, supplemented by interviews with plant managers, procurement leads at PVC converters, environmental compliance officers, and R&D directors. Secondary validation drew from customs/trade data, ACC/Cefic reports, EPA/ECHA regulatory documents, and company financial filings. This approach facilitated bottom-up and top-down triangulation.
The segment-weighting approach informed the market forecast across the analysis window, integrating various VCM product types, production technologies, end-user applications, and regional consumption patterns. CAGRs were derived from historical growth trends and expert projections regarding infrastructure spending and regulatory impacts. Key forecast inputs included ethylene feedstock prices and global construction material demand.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rapid geopolitical shifts or accelerated green technology adoption. Forecasts reflect assumptions regarding feedstock price stability and consistent regulatory enforcement. Material deviation in global energy prices or significant shifts in bio-based VCM commercialization warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Global Hydroiodic Acid (Hydriodic Acid) Market
Bulk Chemicals
Pivaloyl Chloride Market
Bulk Chemicals
Global Naphthalene Derivatives Market
Bulk Chemicals
Global Ammonium Sulphate Market
Bulk Chemicals
Global 2-Ethylhexanoic Acid Market
Bulk Chemicals
United States Fumaric Acid Market
Bulk Chemicals
Middle East Ammonia Market
Bulk Chemicals
Isoprene Monomer Market
Bulk Chemicals
Global Cyclopentane Market
Bulk Chemicals
Cresylic Acid Market
Bulk Chemicals
Stilbene Market
Bulk Chemicals
Global Sodium Chlorate Market
Bulk Chemicals
Global Pitch Coke Market
Bulk Chemicals
Asia-Pacific Ammonium Nitrate Market
Bulk Chemicals
Precipitated Fine Hydrate Market
Bulk Chemicals
Trona Market