
 Zinc L-Pidolate Market | 2026-2036
Zinc L-Pidolate Market Size, Share, and Industry Trends Forecast 2026-2036
Zinc L-Pidolate Market Analytics
USP monograph compliance for chelated mineral salts is rotating supplier eligibility, forcing smaller manufacturers to invest in analytical capabilities or exit. Dr. Paul Lohmann GmbH leverages its German pharmaceutical-grade certification to dominate European nutraceutical contracts. American Elements sustains North American demand through vertical integration from elemental zinc to finished chelate. Gonmisol Fine Ingredients specializes in custom granulation for tablet manufacturers seeking direct-compression compatibility.
Zinc L-pidolate is the zinc salt of L-pyroglutamic acid (L-pidolic acid), formed through chelation to yield a highly bioavailable mineral complex with documented absorption advantages over inorganic zinc salts such as oxide or sulfate. The compound serves primarily as an active ingredient in dietary supplements, fortified foods, and dermatological preparations where gastrointestinal tolerability and cellular uptake matter. Powder and granule formats lead volume due to their flexibility across blending operations in pharmaceutical and nutraceutical facilities. Pharmaceutical-grade capsules command premium positioning where endotoxin limits and batch-specific CoA documentation justify higher unit economics. Direct sales channels capture the largest margin pools by eliminating distributor markups for qualified institutional buyers with recurring formulation needs.
FDA oversight of dietary supplement cGMPs, USP verification programs, and EU REACH registration requirements collectively elevate barrier costs for new zinc L-pidolate suppliers seeking multi-regional market access. EFSA health claim evaluations for zinc-containing products further shape permissible marketing language and influence R&D investment priorities across European nutraceutical portfolios. Stakeholders must monitor evolving pharmacopeial monograph revisions and regional purity standard divergences to preserve formulation approvals and avoid supply discontinuities.
Market Dynamics
Pharmacopeial monograph tightening is compressing supplier eligibility for zinc L-pidolate, forcing manufacturers to choose between analytical capability investments and market exit. This structural filter is reshaping competitive positioning across European and North American nutraceutical supply chains.
Growth Catalysts
- EFSA health claim pathways:Zinc-specific approved claims in the European Union are accelerating R&D investment in bioavailable mineral formulations. Supplement manufacturers are reformulating portfolios to capture permitted marketing language.
- Direct-compression tablet demand:Pharmaceutical contract manufacturers in Germany and the United States are specifying custom-granulated zinc L-pidolate to reduce processing steps. This technical specification is pulling volume toward qualified suppliers.
- Gastrointestinal tolerability preference:Consumer switching from zinc oxide and sulfate toward chelated forms is concentrating procurement with bioavailability-certified producers. Dermatological and senior nutrition applications are leading this migration.
Market Restraints
- L-pyroglutamic acid supply concentration:Amino acid precursor production clusters in Chinese and Japanese chemical manufacturing zones. Geopolitical friction or logistics disruption threatens input cost stability.
- REACH registration cost burden:Small and mid-sized European compounders face five-figure euro expenditures for full substance dossier compliance. This cost structure is filtering marginal participants from the supplier base.
- Inorganic zinc price anchoring:Commodity zinc oxide and sulfate pricing caps willingness-to-pay for chelated alternatives in cost-sensitive supplement categories. Price-sensitive private-label brands maintain dual sourcing.
Strategic Opportunities
- Pediatric gummy and liquid formats:Palatability requirements in children's nutrition are opening formulation contracts for taste-masked zinc L-pidolate. European and North American brand owners are expanding SKU counts.
- CSRD-aligned sustainability reporting:Large nutraceutical buyers are adding carbon footprint and water intensity metrics to supplier scorecards. Early adopters with verified lifecycle data are capturing preferred vendor status.
- Clinical nutrition institutional contracts:Hospital and long-term care procurement in France and Switzerland is specifying pharmaceutical-grade mineral chelates for enteral feeding. This channel offers multi-year offtake security.
Industry Challenges
- USP monograph analytical capability gaps:Smaller manufacturers lack in-house inductively coupled plasma mass spectrometry for heavy metal verification. Third-party testing adds lead time and cost.
- Batch-specific CoA documentation complexity:Pharmaceutical and medical food buyers require endotoxin, microbial, and elemental purity data per lot. Legacy ERP systems struggle with automated certificate distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zinc L-Pidolate Market |
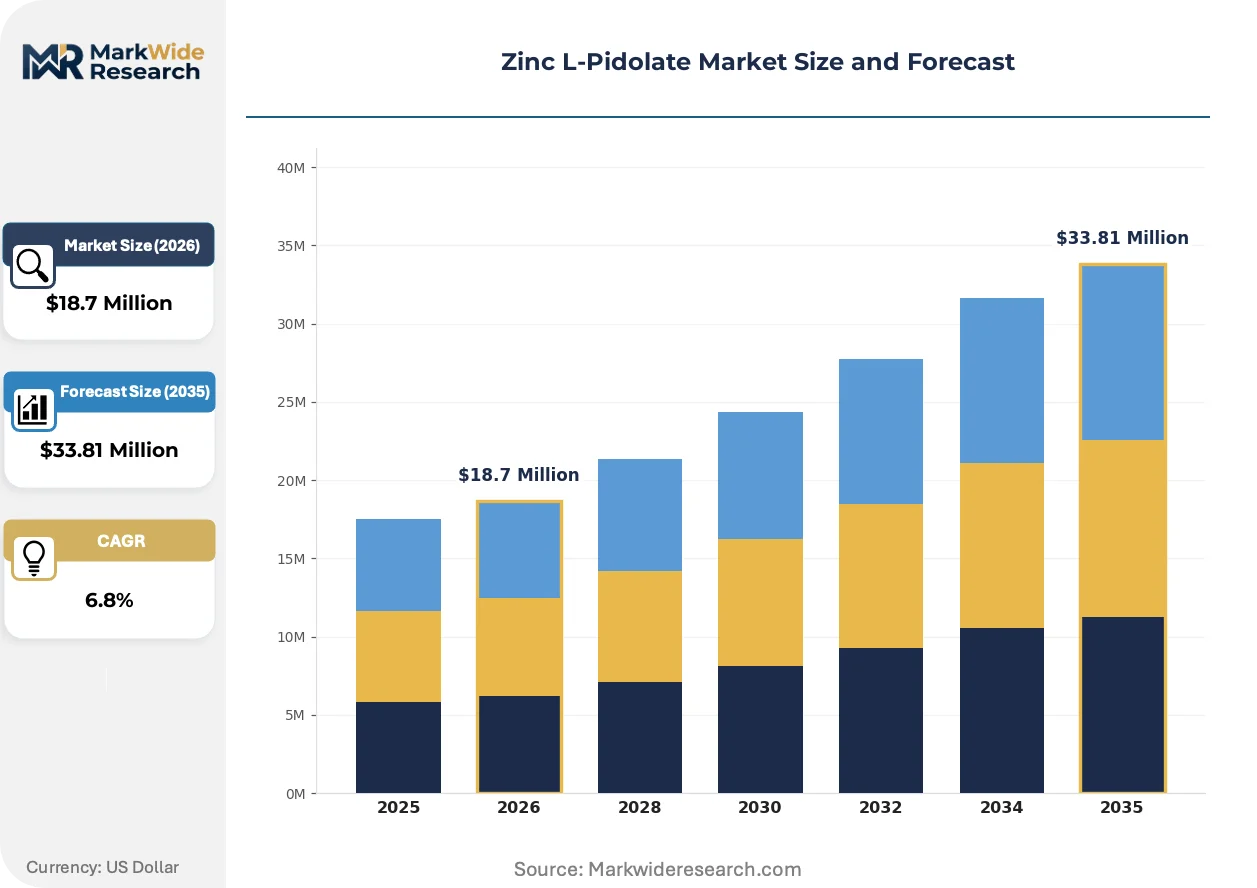
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $33.81 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Capsules, Tablets End User: Pharmaceuticals, Nutraceuticals, Cosmetics, Animal Feed Distribution Channel: Online Retail, Distributors, Direct Sales, Pharmacies Application: Dietary Supplements, Health Products, Skin Care, Fortified Foods |
| Companies Covered | Angene International Limited, Gonmisol Fine Ingredients, Changzhou Xiaqing Technological Co., Ltd., Dr. Paul Lohmann GmbH, Zinc Oxide LLC, American Elements, GHC Limited, Spectrum Chemical Manufacturing Corp., Santa Cruz Biotechnology, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zinc L-Pidolate Market Evolving Landscape
Continuous manufacturing technologies and real-time release testing are compressing quality assurance timelines for chelated mineral production. These process innovations are reshaping supplier capability requirements and buyer evaluation criteria.
Fluid-bed granulation with integrated PAT sensors is displacing conventional batch drying and offline testing in zinc L-pidolate finishing operations. Contract manufacturers serving North American tablet producers are adopting these systems to reduce hold times. The technology is compressing working capital requirements and enabling just-in-time raw material call-offs from compounders.
REACH Annex XVII updates for chelated metal salts are tightening impurity thresholds for nickel and cadmium co-extraction. European compounders must validate alternative synthesis routes or install additional purification stages. Pharmaceutical-grade applications in Germany and Switzerland are absorbing the compliance costs fastest, while feed-grade suppliers face margin compression.
Long-term offtake agreements with fixed-price escalators are replacing spot purchasing for qualified zinc L-pidolate volumes. North American dietary supplement brand owners with multi-SKU portfolios are consolidating supplier relationships to secure allocation. This behavioral shift is most visible among publicly traded nutraceutical companies with earnings visibility requirements and activist investor scrutiny.
Zinc L-Pidolate Market Segmentation
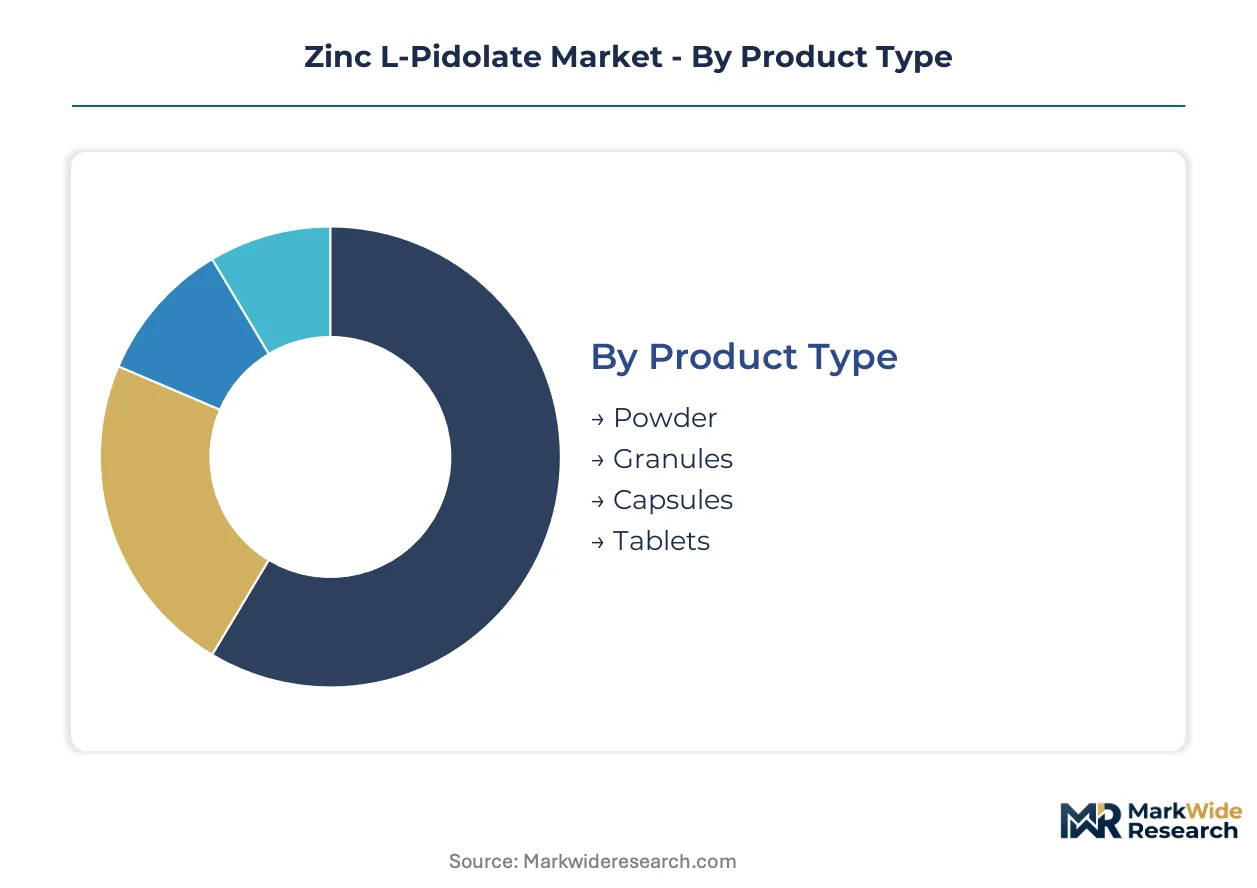
Zinc L-pidolate formulations vary sharply in bioavailability certification, processing requirements, and regulatory pathway. Segment boundaries determine supplier qualification tiers and margin capture potential across pharmaceutical and nutraceutical channels.
Product Type:
Domestic consumption in Germany and the United States favors pharmaceutical-grade powders and granules, while export-led demand from Southeast Asian contract manufacturers concentrates in uncoated bulk powders. Cost tier differentiation separates certified pharmaceutical grades from technical feed-grade alternatives.
- Powder:Fine-milled crystalline zinc L-pidolate serves as the foundational input for capsule filling and wet granulation operations. Nutraceutical blenders in the United States specify this format for maximum formulation flexibility. Powder captures the largest volume share due to its adaptability across dosage forms.
- Granules:Agglomerated particles engineered for direct-compression tablet manufacturing reduce processing steps and lubricant requirements. German contract manufacturers specify custom particle size distributions to match high-speed rotary press parameters. This format commands premium positioning where processing efficiency justifies unit cost premiums.
- Capsules:Pre-filled gelatin or HPMC shells containing measured zinc L-pidolate doses target consumer convenience segments. Finished capsule supply concentrates with pharmaceutical packagers serving North American retail pharmacy chains.
- Tablets:Compressed dosage forms incorporating binders and disintegrants dominate mass-market dietary supplement shelves. European private-label brands source these through Polish and Spanish contract manufacturing organizations.
Powder holds the largest share; momentum sits with granules as direct-compression adoption accelerates.
End User:
Application maturity varies: pharmaceutical and nutraceutical buyers demand batch-specific CoA documentation, while cosmetics and animal feed purchasers prioritize cost efficiency over analytical depth. Customer type determines qualification burden and contract duration.
- Pharmaceuticals:Finished drug manufacturers and medical food compounders require endotoxin-tested, USP-verified zinc L-pidolate with full elemental impurity profiling. Hospital procurement in France and Switzerland specifies this grade for enteral nutrition. This segment absorbs compliance costs fastest and maintains multi-year supplier relationships.
- Nutraceuticals:Dietary supplement brand owners in Germany and the United States drive volume through reformulation of zinc oxide portfolios toward chelated alternatives. EFSA health claim compliance shapes R&D investment priorities. This segment represents the steepest expansion trajectory as bioavailability marketing gains regulatory clarity.
- Cosmetics:Dermatological formulations leverage zinc L-pidolate for topical delivery where skin penetration and tolerability matter. Korean and French beauty manufacturers incorporate this chelate into anti-acne and barrier-repair products.
- Animal Feed:Livestock mineral premixers utilize feed-grade zinc L-pidolate for bioavailable zinc supplementation in poultry and swine nutrition. Price anchoring against inorganic zinc sulfate limits penetration in cost-sensitive markets.
Pharmaceuticals command the highest unit margins; nutraceuticals drive absolute volume expansion.
Distribution Channel:
Channel selection reflects buyer scale and technical capability: institutional purchasers with in-house quality labs prefer direct relationships, while smaller blenders rely on distributor technical support. Volume concentration shapes channel economics.
- Online Retail:E-commerce platforms serve small-scale nutraceutical startups and research institutions requiring sub-kilogram quantities. German and Dutch chemical marketplaces have expanded zinc L-pidolate SKU availability.
- Distributors:Regional chemical and ingredient distributors provide technical documentation, inventory management, and just-in-time delivery for mid-sized manufacturers. North American nutraceutical clusters depend on distributor networks for REACH-compliant European sourcing.
- Direct Sales:Large-volume pharmaceutical and nutraceutical compounders negotiate long-term offtake agreements with qualified producers, eliminating margin layers. This channel captures the deepest buyer relationships and secures allocation during supply constraints.
- Pharmacies:Retail pharmacy chains stock finished zinc L-pidolate supplements as over-the-counter mineral products. German and Swiss pharmacy systems maintain strict quality verification protocols for shelf placement.
Direct sales anchor institutional procurement; distributor networks sustain mid-market access.
Application:
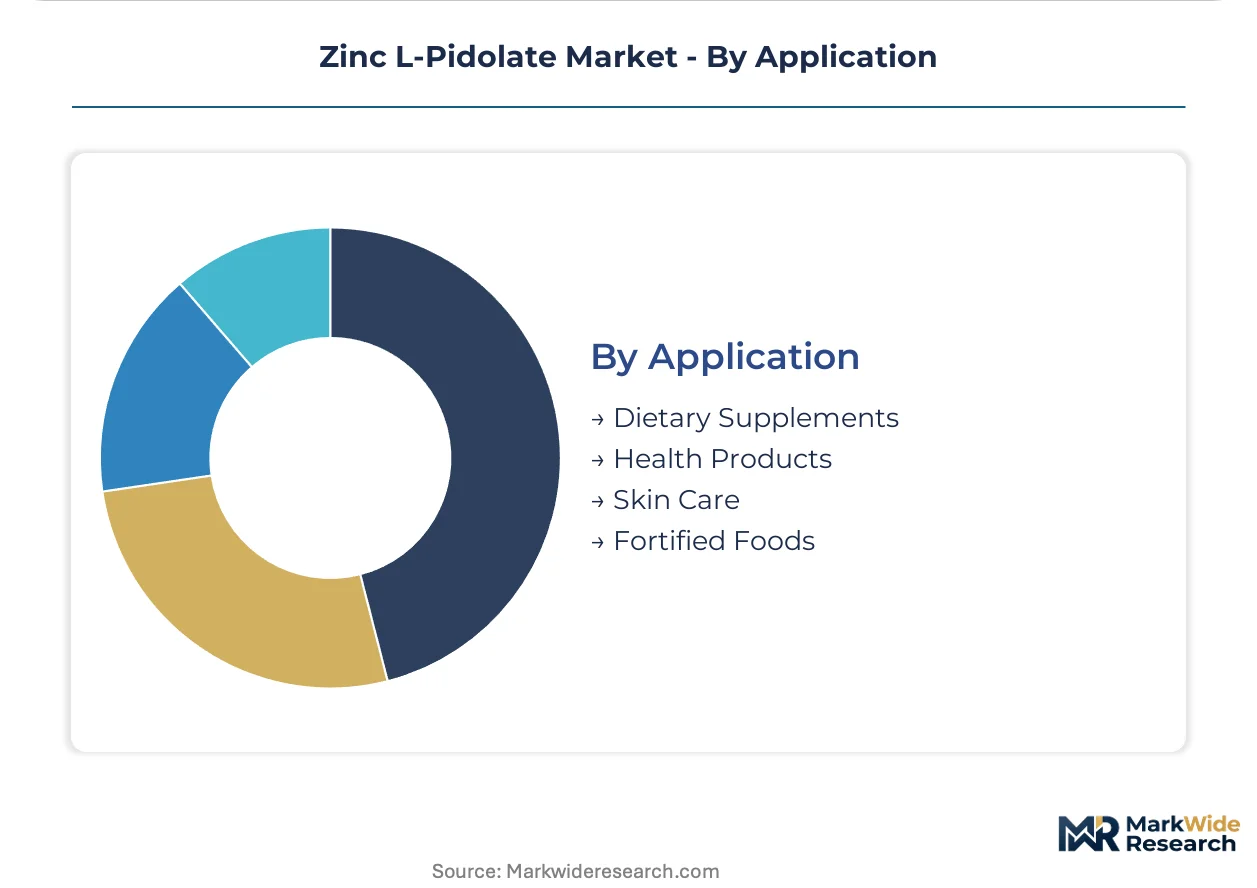
Application segmentation tracks regulatory pathway divergence: dietary supplements and health products navigate food-supplement frameworks, while skin care formulations face cosmetic regulation. Fortified foods occupy the most stringent novel food authorization territory.
- Dietary Supplements:Capsule, tablet, and powder formats delivering targeted zinc supplementation dominate consumer-facing revenue. North American brand owners reformulate portfolios to capture USP verification and third-party testing credentials. This application absorbs the greatest absolute volume.
- Health Products:Functional foods, medical foods, and clinical nutrition products incorporate zinc L-pidolate for specific patient populations. French and Swiss hospital nutrition services specify pharmaceutical-grade material for enteral feeding protocols.
- Skin Care:Topical formulations exploit zinc L-pidolate's stability and skin compatibility for acne treatment and barrier function support. Korean cosmetic manufacturers lead formulation innovation in this niche.
- Fortified Foods:Breakfast cereals, dairy alternatives, and beverages incorporate zinc L-pidolate for mineral enrichment where taste neutrality and bioavailability matter. EU novel food authorization requirements constrain launch velocity.
Dietary supplements hold established volume leadership; health products gain share through clinical nutrition contract expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical-grade buyers in Germany and the United States concentrate procurement for bioavailable mineral formulations. REACH compliance costs and USP verification requirements are filtering supplier eligibility across developed markets. Manufacturing clusters in these countries anchor quality-certified production for nutraceutical and clinical nutrition applications.
United States
Dietary supplement brand owners in California and New Jersey drive reformulation toward chelated zinc alternatives. FDA cGMP enforcement and USP verification programs elevate barrier costs for new suppliers. Greater Boston hosts contract manufacturers specifying custom-granulated material for direct-compression tablet operations.
Germany
Nutraceutical compounders in Bavaria and North Rhine-Westphalia expand pharmaceutical-grade procurement for EFSA-compliant health claim products. REACH Annex XVII updates for chelated metal salts tighten nickel and cadmium thresholds. Dr. Paul Lohmann GmbH leverages its pharmaceutical-grade certification to dominate European institutional contracts.
Switzerland
Hospital nutrition services in Zurich and Geneva specify pharmaceutical-grade zinc L-pidolate for enteral feeding protocols. Swissmedic oversight maintains stringent endotoxin and microbial purity standards. Basel-area clinical nutrition manufacturers secure multi-year offtake agreements with qualified producers.
France
Dermatological formulators in Île-de-France incorporate chelated zinc into topical barrier-repair products. ANSM cosmetic regulation shapes permissible marketing claims for mineral-enriched skin care. Lyon-based contract manufacturers serve European beauty brands seeking bioavailable active ingredients.
China
L-pyroglutamic acid precursor production clusters in Jiangsu and Zhejiang provinces supply global chelation operations. NMPA oversight of imported dietary supplement ingredients affects export qualification pathways. Shanghai-area chemical manufacturers face pressure to validate alternative synthesis routes for REACH-compliant European buyers.
Zinc L-Pidolate Market Competitive Landscape
Player mix skews toward pharmaceutical-grade specialists with pharmacopeial certifications and vertically integrated elemental metal producers. The supplier base stratifies across three tiers: German-certified pharmaceutical compounders, North American integrated producers, and Asian precursor manufacturers. Tier-1 players defend position through analytical capability investments and long-term institutional contracts. Tier-2 participants compete on custom granulation specifications and regional distributor relationships.
Within the certified-pharmaceutical tier, Dr. Paul Lohmann GmbH and American Elements occupy distinct geographic anchor positions. Dr. Paul Lohmann GmbH exemplifies European regulatory compliance leadership through its German pharmaceutical-grade certification. American Elements represents North American vertical integration from elemental zinc through finished chelate production. Gonmisol Fine Ingredients sits within the specialization tier, focusing on custom particle engineering for direct-compression compatibility.
| Leading Market Players |
|---|
| Angene International Limited |
| Gonmisol Fine Ingredients |
| Changzhou Xiaqing Technological Co., Ltd. |
| Dr. Paul Lohmann GmbH |
| Zinc Oxide LLC |
| American Elements |
| GHC Limited |
| Spectrum Chemical Manufacturing Corp. |
| Santa Cruz Biotechnology, Inc. |
| Others |
Value Network & Pricing Analysis
Substitution of zinc oxide and sulfate by chelated L-pidolate forms is simultaneously redrawing procurement geography toward German and US pharmaceutical-grade suppliers and compressing margin structures in cost-sensitive feed-grade tiers. This displacement dynamic concentrates pricing power with certified compounders while forcing legacy inorganic producers into defensive volume retention.
Pricing Analysis
Cost-plus contracts with zinc metal indexation dominate institutional procurement, insulating qualified suppliers from raw material volatility while locking in modest but predictable margins. Three-tier pricing structure across pharmaceutical, nutraceutical, and feed grades reflects analytical capability investment and certification depth. Price compression runs through feed-grade tiers where commodity zinc sulfate anchors buyer willingness-to-pay. Pharmaceutical buyers in Switzerland and France exhibit lowest price sensitivity, prioritizing batch-specific CoA documentation and endotoxin compliance over unit cost.
Supply Chain Analysis
Jiangsu and Zhejiang province production of L-pyroglutamic acid creates a single-source chokepoint that underwrites global chelation capacity and exposes compounders to logistics disruption or geopolitical friction. Zinc L-pidolate manufacturing draws from Chinese amino acid precursors, German pharmaceutical-grade finishing, and North American elemental zinc refining. REACH registration cost burden presents structural risk for European supplier base consolidation. Distribution runs through direct sales channels for institutional buyers and regional chemical distributors for mid-market blenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense imperative as inorganic zinc salts retain cost anchoring in private-label supplement categories, requiring strategic positioning against commodity price pressure.
For Market Incumbents: Secure multi-year offtake agreements with French and Swiss hospital nutrition services to lock in pharmaceutical-grade volume allocation. Deepen backward integration into L-pyroglutamic acid precursor supply through Japanese or European partnership structures to reduce Chinese supply concentration risk. For New Entrants and Emerging Players: Lead with custom granulation capabilities targeting German direct-compression tablet manufacturers seeking particle size distribution precision. Pediatric gummy and liquid format contracts offer the most penetrable white space, with taste-masked formulation expertise as the critical go-to-market wedge. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors analytical-capability-rich specialists over undifferentiated commodity producers. Five-to-ten year viability hinges on pharmacopeial certification moats and institutional contract duration. Watch EFSA health claim expansion velocity as the primary demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Reduces exposure to Chinese L-pyroglutamic acid concentration and REACH compliance bottlenecks. |
| Pharmaceutical-Grade Certification Investment | Unlocks Swissmedic and ANSM institutional procurement channels with multi-year contract security. |
| Custom Granulation Capability Expansion | Captures German direct-compression tablet demand with particle engineering precision. |
| Pediatric Format Formulation Development | Addresses palatability requirements in European and North American children's nutrition SKU expansion. |
| Long-Term Institutional Supply Agreement | Eliminates spot market exposure and secures allocation priority during precursor supply constraints. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with nutraceutical procurement directors, pharmaceutical quality assurance leads, contract manufacturing executives, and ingredient distribution specialists; and secondary validation through USP monograph documentation, EFSA health claim registers, REACH Annex XVII updates, and customs trade flow records. Bottom-up volume estimates from product-grade consumption patterns were triangulated against top-down market sizing from chelated mineral salt production disclosures.
Across the projection horizon, the analytical framework modeled segmentation across product format, end-use industry, distribution channel, and geographic regulatory cluster. CAGRs were derived from fitted growth curves incorporating EFSA claim expansion timelines, direct-compression adoption rates in tablet manufacturing, and REACH compliance cost pass-through assumptions. Zinc metal price index volatility and L-pyroglutamic acid supply concentration served as key forecast sensitivity inputs.
The analysis sits within stated boundaries; outcomes outside sustained EFSA health claim pathway expansion or absent REACH Annex XVII enforcement intensification would require recalibration. Practitioners should keep alternative scenarios live as pharmacopeial monograph revision timelines and precursor supply geography evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Vinyl Cyclohexane Market
Bulk Chemicals
Asia-Pacific Caustic Soda Market
Bulk Chemicals
2-Methylfuran Market
Bulk Chemicals
2-Ethylhexanoyl Chloride Market
Bulk Chemicals
Global Bitumen Market
Bulk Chemicals
Global Lithium Fluoride Market
Bulk Chemicals
Mangiferin Market
Bulk Chemicals
Global Ammonium Chloride Market
Bulk Chemicals
Magnesium Sulfate Market
Bulk Chemicals
Aluminum Chloride Hexahydrate Market
Bulk Chemicals
Polyferric Sulfate Market
Bulk Chemicals
Gypsum-Free Lactic Acid Market
Bulk Chemicals
Global Sodium Percarbonate Market
Bulk Chemicals
Methyl Methacrylate (MMA) Market
Bulk Chemicals
Dimethyl Disulphide (DMDS) Market
Bulk Chemicals
United States Calcium Chloride Market