
 Fixing Agent Market | 2026-2036
Fixing Agent Market Size, Share, and Industry Trends Forecast 2026-2036
Fixing Agent Market Foresight
Multi-source procurement for cationic polymer intermediates is pivoting toward captive synthesis among large textile chemical suppliers. Fineotex Chemical Limited leverages backward integration into ethyleneamine derivatives to secure feedstock continuity. CHT Group anchors its European position through ISO-certified manufacturing hubs that sustain compliance with evolving eco-label criteria.
Fixing agents are functional additives that form insoluble complexes with dyes or pigments to enhance substrate adhesion, typically comprising quaternary ammonium salts, polyamine condensates, or epoxy-functional polymers with active content ranging from twenty to sixty percent. Their primary purpose is to lock colorants onto cellulose, protein, or synthetic fibers during wet-processing to prevent bleeding and meet wash-fastness standards. Polymer-based formulations command premium positioning due to superior compatibility with reactive dyes in digital textile printing, while organic compounds retain volume leadership in conventional pad-batch operations. Liquid forms dominate factory-floor dispensing systems, though powder variants are gaining traction in regions with high humidity storage constraints.
REACH registration requirements and the EU Green Deal's chemical sustainability targets are tightening permissible limits on free formaldehyde and APEO content in textile auxiliaries. India's BIS colorfastness standards and China's GB 18401 national textile safety technical code are converging on stricter migration thresholds, forcing reformulation investments across export supply chains. Stakeholders must monitor regulatory divergence between European hazard-classification schemes and emerging-market enforcement capacities to calibrate product registration priorities and manufacturing location decisions.
Market Dynamics
REACH restrictions on quaternary ammonium compounds are forcing European textile chemical suppliers to rebuild their fixing agent portfolios around bio-based polymer alternatives, compressing reformulation timelines and redirecting R&D budgets toward epoxy-functional and polyamine condensate platforms.
Growth Catalysts
- Digital textile printing expansion:Textile manufacturers in India and Bangladesh are scaling reactive dye adoption for inkjet systems, creating pull for polymer-based fixing agents with superior colorfastness profiles.
- BIS colorfastness mandates:India's Bureau of Indian Standards is tightening wash-fastness requirements for export-oriented fabric producers, accelerating procurement of high-performance cationic fixing agents.
- Formaldehyde-free formulation demand:Apparel brands sourcing from Vietnam and Turkey are specifying zero-formaldehyde auxiliaries to meet EU Green Deal chemical sustainability targets.
Market Restraints
- Ethyleneamine feedstock volatility:Captive synthesis of cationic polymer intermediates requires substantial ethyleneamine derivative access, where supply bottlenecks in Middle Eastern petrochemical corridors create input cost instability.
- REACH registration burden:The European Chemicals Agency's substance evaluation protocols impose multi-year compliance timelines and testing expenditures that deter mid-scale suppliers from maintaining EU market presence.
- Natural dye substitution threat:Bio-sourced colorants derived from agricultural waste streams are gaining traction in premium apparel segments, reducing fixing agent intensity per unit of fabric processed.
Strategic Opportunities
- Underpenetrated African markets:Egypt and Morocco's expanding textile export zones lack established auxiliary supply chains, creating first-mover potential for ISO-certified fixing agent distributors with local blending capabilities.
- Reactive dye-pigment hybrid systems:Convergence of digital printing hardware with nano-pigment dispersion chemistry is opening demand for fixing agents compatible with mixed colorant architectures.
- China GB 18401 alignment:The national textile safety technical code's stricter migration thresholds are forcing domestic dye houses to upgrade auxiliary specifications, favoring imported polymer-based formulations with certified compliance documentation.
Industry Challenges
- Reformulation technical debt:Legacy quaternary ammonium salt production lines require complete process reengineering to manufacture bio-based alternatives, stretching engineering resources and extending product validation cycles.
- Cross-regulatory certification complexity:Simultaneous pursuit of OEKO-TEX Standard 100, bluesign, and ZDHC MRSL conformance demands parallel testing tracks that fragment quality assurance teams and dilute R&D focus.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fixing Agent Market |
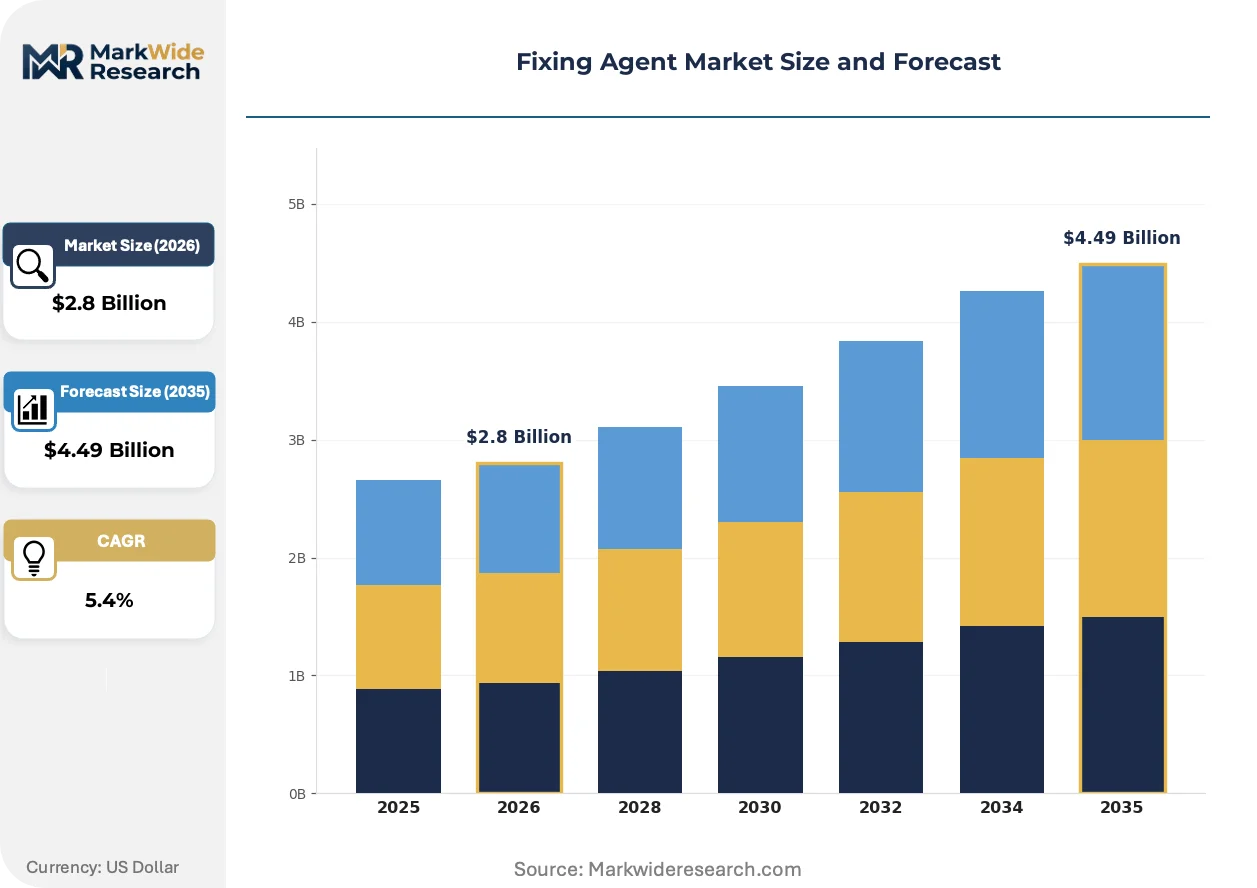
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Compounds, Inorganic Compounds, Polymer-Based, Hybrid Agents Application: Textile Printing, Paper Coating, Leather Processing, Construction Materials, Adhesives, Paints End User Industry: Textile Manufacturers, Paper Producers, Leather Tanneries, Chemical Formulators, Construction Firms Form: Liquid, Powder, Granular, Emulsion, Paste |
| Companies Covered | Fineotex Chemical Limited, Viswaat Chemicals Limited, CHT Group, Piedmont Chemical Industries, NICCA Chemical, Achitex Minerva, eksoy Chemicals, Protex Korea, Avocet Dye & Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fixing Agent Market Shifts & Advancements
Epoxy-functional polymer platforms are displacing conventional quaternary ammonium architectures as the dominant fixing agent chemistry, driven by compatibility requirements for high-speed digital textile printing and tightening formaldehyde emission standards across major import markets.
Epoxy-functional polymers with tailored molecular weight distributions are overtaking polyamine condensates in reactive dye applications for cotton and viscose substrates. Digital printing houses in Turkey and Portugal are adopting these systems at accelerating rates to achieve 4-5 wash-fastness ratings without formaldehyde release. This chemistry shift is compressing margins on legacy quaternary ammonium salt volumes while creating premium positioning for suppliers with captive epichlorohydrin derivative production.
REACH Annex XIV authorization requirements for specific quaternary ammonium compounds are forcing auxiliary suppliers to submit substitution plans or cease European supply. The restriction's industrial consequence is a wholesale portfolio rebuild toward polyamine and epoxy alternatives, with compliance deadlines compressing between 2026 and 2030. Small and mid-scale textile chemical blenders in Italy and Spain are most affected, many lacking capital reserves for parallel registration and reformulation programs.
Specification-driven procurement is consolidating buying power among large vertically integrated textile groups in India and Vietnam, displacing traditional distributor networks. These buyers now demand fixing agent suppliers provide bundled compliance documentation covering BIS, GB 18401, and OEKO-TEX standards in single submissions. The shift is most visible in Tamil Nadu's knitwear export corridor, where mill-direct contracts with auxiliary manufacturers are replacing multi-tier chemical distribution.
Fixing Agent Market Segmentation
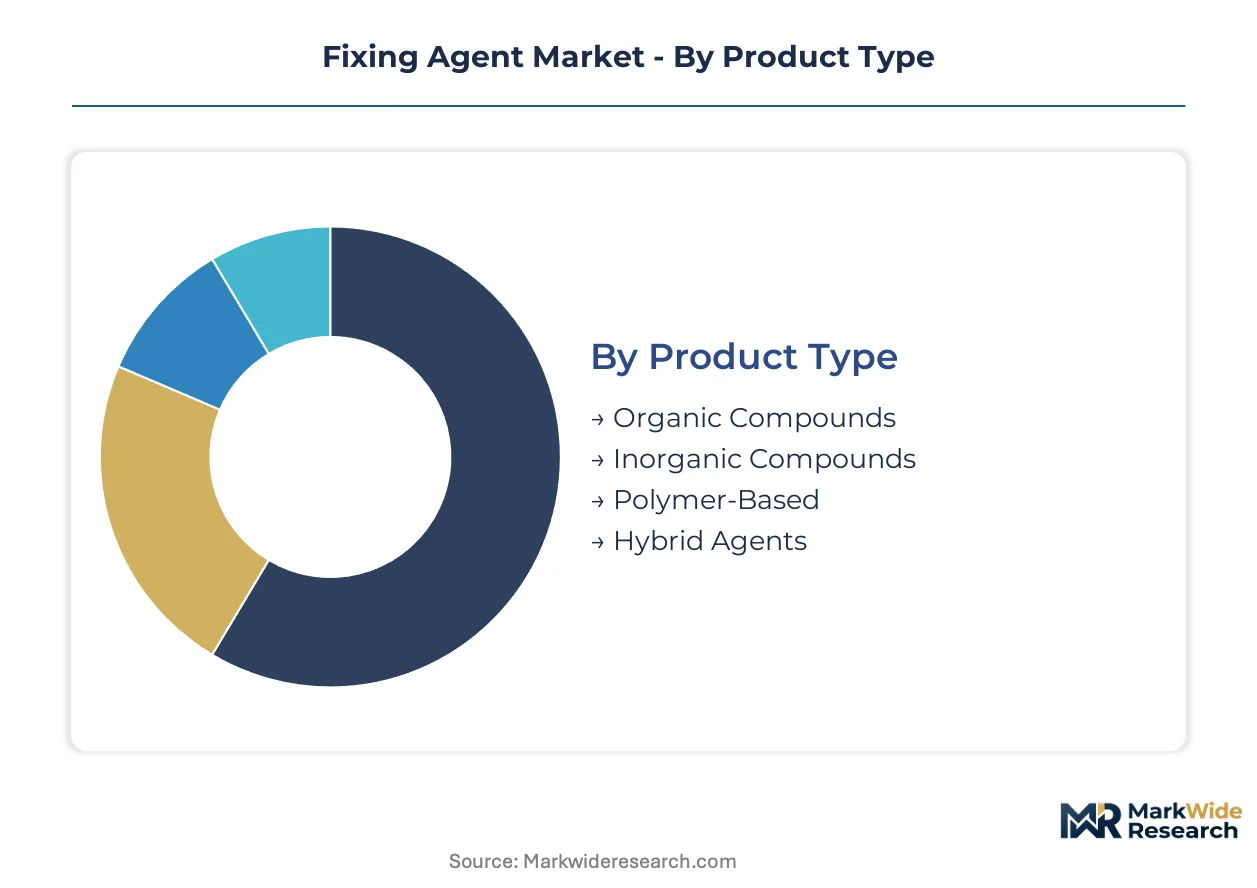
Fixing agent procurement patterns diverge sharply across chemistry platforms and end-use specifications, with textile applications demanding polymer-based colorfastness performance while construction and paper segments prioritize cost-optimized inorganic formulations.
Product Type:
Supply concentration tilts toward polymer-based platforms as REACH restrictions on quaternary ammonium salts force European manufacturers to rebuild capacity around epoxy-functional alternatives.
- Organic Compounds:Traditional formaldehyde-based condensates and quaternary ammonium salts dominate legacy pad-batch operations in South Asian cotton processing. Demand is compressing in Europe where ECHA substance evaluation protocols are accelerating phase-out timelines for cationic surfactant chemistries.
- Polymer-Based:Epoxy-functional and polyamine architectures with tailored molecular weight distributions deliver 4-5 wash-fastness ratings for reactive dye digital printing. Procurement is concentrating among Turkey's inkjet textile houses and Tamil Nadu's knitwear export mills seeking BIS-compliant documentation bundles.
- Inorganic Compounds:Metal salt complexes serve paper coating and construction adhesive applications where colorfastness specifications remain less stringent than apparel mandates.
- Hybrid Agents:Dual-chemistry systems blending organic cationic charges with polymer backbones occupy niche positions in leather processing.
Polymer-Based formulations absorb the bulk of installed capacity; Hybrid Agents are expanding most quickly as tanneries seek compromise solutions between performance and registration cost.
Application:
Cost tier differentiation separates premium textile specifications from commodity-grade construction and paper applications, with digital printing quality standards widening the price spread.
- Textile Printing:Reactive dye fixation for cotton, viscose, and blended substrates requires cationic polymer intermediates with active content between 20-60%. India's BIS wash-fastness mandates and Vietnam's EU-export compliance requirements are pulling specification-grade procurement toward certified polymer platforms.
- Adhesives:Construction-grade bonding applications utilize lower-purity inorganic fixing agents where migration thresholds under China's GB 18401 code remain the primary regulatory constraint.
- Paper Coating:Pigment retention in coated paperboard relies on cost-optimized quaternary ammonium salts with less stringent formaldehyde emission limits than apparel auxiliaries.
- Leather Processing:Chrome-tanned hide color fixation employs specialized hybrid chemistries balancing wet-fastness with substrate compatibility.
- Construction Materials:Cement and plaster modifiers use bulk inorganic compounds where price-per-kilogram drives procurement decisions.
- Paints:Pigment dispersion stability in architectural coatings represents a volume-stable but low-margin application segment.
Textile Printing commands the steepest expansion trajectory; Construction Materials and Paper Coating absorb volume without margin premium.
End User Industry:
Customer type fragmentation concentrates buying power among vertically integrated textile groups while chemical formulators and construction firms remain price-sensitive spot purchasers.
- Textile Manufacturers:Mill-direct procurement in India's Tiruppur and Surat clusters now demands bundled BIS, OEKO-TEX, and ZDHC MRSL compliance documentation from auxiliary suppliers. Large knitwear exporters are displacing traditional distributor networks with captive formulation partnerships.
- Chemical Formulators:Mid-scale blenders in Italy and Spain face compressed reformulation timelines as REACH Annex XIV authorization requirements force portfolio rebuilds without capital reserves for parallel registration programs.
- Paper Producers:Coated paperboard mills in Germany and Finland prioritize supply security over performance differentiation.
- Leather Tanneries:Italian and Portuguese vegetable-tanning specialists seek hybrid fixing agents compatible with chrome-free processing trends.
- Construction Firms:Cement additive procurement in Turkey and Egypt operates on price-tender mechanisms with minimal technical specification barriers.
Textile Manufacturers absorb the bulk of installed capacity; Chemical Formulators are consolidating fastest as REACH registration burdens eliminate marginal competitors.
Form:
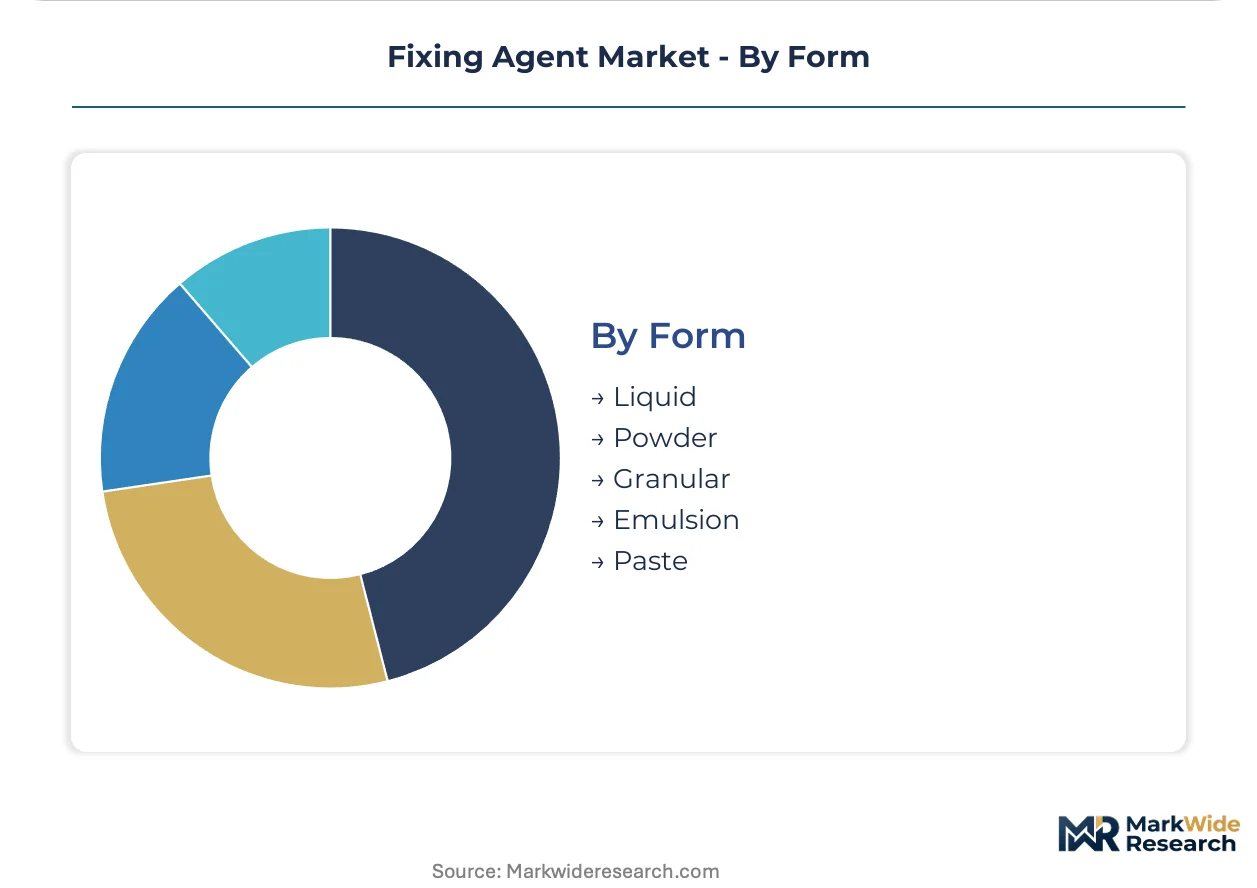
Volume concentration favors liquid dispensing systems in automated textile finishing lines while powder and granular alternatives serve humidity-constrained storage environments and construction batch mixing.
- Liquid:Pump-dispersed formulations with controlled viscosity profiles dominate continuous pad-dyeing operations in Bangladesh and Vietnam. Factory-floor automation compatibility and precise metering capability sustain preference despite higher freight costs per active unit.
- Powder:Low-moisture packaging suits Tamil Nadu's monsoon-season storage constraints and African distribution corridors where cold-chain infrastructure remains underdeveloped.
- Granular:Dust-free handling characteristics serve paper mill bulk silo systems and construction site manual mixing protocols.
- Emulsion:Water-based dispersions with extended shelf stability occupy leather processing niches requiring gradual release kinetics.
- Paste:High-viscosity formulations target small-batch textile printers and artisanal tanneries with limited metering equipment.
Liquid forms absorb the bulk of installed capacity; Powder variants are gaining share fastest in high-humidity geographies and emerging-market distribution networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India absorbs the steepest procurement acceleration as export-oriented textile clusters scale reactive dye adoption for digital printing. ECHA's REACH Annex XIV restrictions on quaternary ammonium compounds are compressing reformulation timelines across European auxiliary suppliers. Mill-direct specification requirements now span BIS, GB 18401, and OEKO-TEX documentation bundles in single submissions.
India
Tamil Nadu's Tiruppur knitwear corridor drives polymer-based fixing agent procurement for EU and US export compliance. BIS tightened wash-fastness standards for cotton and blended fabrics in 2024, forcing dye houses to upgrade from legacy quaternary ammonium salts. Surat's synthetic textile cluster is displacing traditional distributor networks with captive formulation partnerships.
China
Yangtze River Delta dye houses face GB 18401 migration threshold reductions that favor imported polymer-based formulations with certified compliance documentation. Digital textile printing expansion in Zhejiang and Jiangsu provinces pulls epoxy-functional fixing agents for reactive dye inkjet systems. Shanghai-based auxiliary distributors are consolidating procurement volumes among vertically integrated textile groups.
Turkey
Istanbul and Bursa inkjet textile houses adopt epoxy-functional polymers at accelerating rates to achieve 4-5 wash-fastness ratings without formaldehyde release. EU Green Deal chemical sustainability targets drive zero-formaldehyde auxiliary specifications from apparel brand sourcing offices. The country's Bureau of Standards alignment with OEKO-TEX Standard 100 is compressing margins on legacy quaternary ammonium volumes.
Germany
Baden-Württemberg textile chemical suppliers anchor European compliance manufacturing through ISO-certified hubs sustaining eco-label criteria evolution. ECHA substance evaluation protocols impose multi-year registration timelines that deter mid-scale blenders from maintaining EU market presence. Stuttgart-area formulators are rebuilding portfolios around bio-based polymer alternatives ahead of 2026-2030 REACH authorization deadlines.
Vietnam
Ho Chi Minh City and Binh Duong garment export zones specify zero-formaldehyde fixing agents to meet EU Green Deal targets for apparel shipments. BIS-equivalent wash-fastness requirements from Indian buyers are pulling specification-grade procurement toward certified polymer platforms. Factory-floor automation in continuous pad-dyeing operations sustains preference for liquid-form dispensing systems despite higher freight costs.
Fixing Agent Market Competitive Landscape
Backward integration into ethyleneamine derivatives dominates the current landscape as large textile chemical suppliers secure feedstock continuity against Middle Eastern petrochemical corridor volatility. The supplier base fragments across three tiers: multinational auxiliary conglomerates with captive synthesis capabilities, regional formulators with ISO-certified blending operations, and commodity traders serving humidity-constrained storage markets. Strategic archetypes include vertically integrated polymer specialists, compliance-focused documentation bundlers, and price-tender inorganic compound distributors. M&A activity concentrates among European REACH-impacted blenders, while capacity expansion clusters in India's Tamil Nadu and Vietnam's southern export zones.
Among Indian specialty chemical producers, Fineotex Chemical Limited and Viswaat Chemicals Limited exemplify the backward integration archetype through ethyleneamine derivative production. CHT Group represents the compliance-focused tier with ISO-certified European manufacturing hubs. These three anchors illustrate how geographic origin and corporate structure align with strategic positioning—limited liability entities in India and Germany reflecting distinct regulatory exposure profiles.
| Leading Market Players |
|---|
| Fineotex Chemical Limited |
| Viswaat Chemicals Limited |
| CHT Group |
| Piedmont Chemical Industries |
| NICCA Chemical |
| Achitex Minerva |
| eksoy Chemicals |
| Protex Korea |
| Avocet Dye & Chemical |
| Others |
Supply & Pricing Matrix
Ethyleneamine derivative price indices cascade through fixing agent supply chains, compressing margins on legacy quaternary ammonium formulations while amplifying premiums for epoxy-functional polymer alternatives with captive feedstock security.
Pricing Analysis
Volume leadership sits with commodity-grade inorganic compounds for construction and paper applications, while polymer-based textile formulations capture margin premiums through BIS and OEKO-TEX certification bundling. Price differentiation hinges on active content concentration and REACH compliance documentation depth, with formaldehyde-free specifications commanding substantial uplifts over legacy condensates. Cost compression in South Asian spot markets is intensifying as Indian and Bangladeshi mills consolidate procurement through mill-direct contracts. Chemical formulators in Europe exhibit lowest price sensitivity due to regulatory substitution mandates, while construction firms in Turkey and Egypt operate on pure price-tender mechanisms.
Supply Chain Analysis
India's Bureau of Indian Standards tightening of colorfastness requirements is reshaping sourcing patterns toward domestic polymer synthesis capabilities, displacing imported quaternary ammonium salt volumes. Manufacturing concentrates in India, Germany, and China, with feedstock supply anchored in Middle Eastern ethyleneamine corridors and European epichlorohydrin derivative production. Raw material procurement draws from petrochemical intermediates, bio-based amine platforms, and epoxy resin precursors. Single-source vulnerability pervades ethyleneamine derivative access, where Middle Eastern supply disruptions transmit immediately into formulation cost instability. Distribution runs through vertically integrated textile groups in Tamil Nadu and Zhejiang, bypassing traditional chemical distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fixing agent competition has become a vertical-integration race, with upstream control over ethyleneamine derivatives and epichlorohydrin feedstocks determining margin sustainability as REACH deadlines compress.
For Market Incumbents: Deepen captive synthesis of cationic polymer intermediates to insulate margin structures from Middle Eastern petrochemical corridor volatility. Expand ISO-certified manufacturing presence in India's Tamil Nadu knitwear corridor to capture mill-direct specification contracts displacing distributor networks. Prioritize parallel registration tracks for BIS, GB 18401, and ZDHC MRSL documentation bundling before 2026 REACH authorization deadlines eliminate mid-scale European competitors. For New Entrants and Emerging Players: Small-batch textile printers in Vietnam's Ho Chi Minh City garment zones represent the most penetrable buyer archetype, underserved by incumbent liquid-form dispensing systems optimized for large-scale continuous operations. Target powder-formulation distribution in African emerging markets where humidity-constrained storage infrastructure remains underdeveloped. Pursue specification-grade positioning through reactive dye-pigment hybrid system compatibility rather than commodity quaternary ammonium substitution. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale European textile chemical blenders in Italy and Spain facing REACH Annex XIV registration burdens without capital reserves for parallel reformulation programs. Long-term viability centers on acquisition targets with existing epoxy-functional polymer platforms and established OEKO-TEX certification infrastructure. Watch ECHA substance evaluation protocol acceleration as the inflection signal for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethyleneamine Derivatives | Fineotex Chemical Limited's captive feedstock production secures supply continuity against Middle Eastern petrochemical volatility. |
| REACH-Compliant Portfolio Rebuild | CHT Group's ISO-certified European manufacturing sustains market access as ECHA authorization deadlines eliminate marginal competitors. |
| Mill-Direct Distribution Partnerships | Surat's synthetic textile cluster displacement of distributor networks concentrates procurement power among vertically integrated auxiliary suppliers. |
| Zero-Formaldehyde Formulation Development | Turkey's inkjet textile houses adopt epoxy-functional polymers to meet EU Green Deal chemical sustainability targets for apparel exports. |
| African Market Distribution Infrastructure | Egypt and Morocco's expanding textile export zones lack established auxiliary supply chains, creating first-mover potential for certified distributors with local blending capabilities. |
Research Methodology
Document review covered customs and trade data, REACH registration filings, BIS technical standards documentation, and SEC 10-K disclosures from listed textile chemical suppliers, complemented by interviews with plant managers at Indian dye houses, procurement leads at Vietnamese garment exporters, distribution channel partners in European auxiliary markets, and technical R&D directors at polymer synthesis facilities. Bottom-up demand modeling triangulated against top-down market sizing from import-export statistics and production capacity databases.
Segment-level volume and value trajectories emerged from chemistry platform splits, end-use application tiers, and regional regulatory cluster differentiation across the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating digital textile printing adoption rates and REACH substitution timeline compliance. Industry-specific forecast inputs included reactive dye fixation efficiency benchmarks and BIS wash-fastness standard enforcement intensity.
Revisions become necessary when ECHA accelerates substance evaluation protocols, when Middle Eastern ethyleneamine supply corridors experience sustained disruption, or when India's BIS mandates expand beyond current cotton and blended fabric coverage. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Global Spray Polyurethanes Foam Market
Specialty Chemicals
Automotive Silicone Market
Specialty Chemicals
Security Ink Market
Specialty Chemicals
Global Tetrakis (Hydroxymethyl) Phosphonium Sulfate Market
Specialty Chemicals
UV/IR Blocker Market
Specialty Chemicals
Panthenol Market
Specialty Chemicals
Precipitated Barium Sulfate Market
Specialty Chemicals
Global Sodium Hyaluronate-Based Products Market
Specialty Chemicals
Insoluble Fibers Market
Specialty Chemicals
Contouring Products Market
Specialty Chemicals
Natural Phytosphingosine Market
Specialty Chemicals
Naphthol AS-IRG Market
Specialty Chemicals
Global Flame Retardants Market
Specialty Chemicals
Perfluoroalkoxy Alkane (PFA) Market
Specialty Chemicals
Eitelite Market
Specialty Chemicals
Ethylhexane Diol Market