
 Polymer Colloids Market | 2026-2036
Polymer Colloids Market Size, Share, and Industry Trends Forecast 2026-2036
Polymer Colloids Market Outlook
Capital-intensity divergence between integrated petrochemical giants and regional emulsion specialists is reorganizing competitive tiers in polymer colloids. BASF SE leverages its Ludwigshafen Verbund site to captive-produce acrylic monomers for colloid synthesis. Dow Inc. anchors North American supply through its Freeport, Texas, manufacturing complex. Evonik Industries AG differentiates via specialty silica-acrylic hybrid nanoparticles for high-performance coatings.
Polymer colloids are aqueous dispersions of sub-micron polymer particles, typically 50–500 nm in diameter, stabilized by surfactant systems and synthesized via emulsion or miniemulsion polymerization; they function as film-forming binders, rheology modifiers, and controlled-release matrices across industrial and consumer applications. Emulsions dominate volume consumption in architectural coatings and adhesives, while nanoparticles command premium pricing in pharmaceutical delivery systems. Water-based formulations are displacing solvent alternatives as environmental compliance tightens across OECD manufacturing bases.
EPA VOC regulations under the Clean Air Act and REACH registration requirements are elevating compliance costs for solvent-based colloid producers while accelerating qualification of aqueous systems. FDA guidance on polymer excipients in drug formulations shapes nanoparticle approval pathways for parenteral applications. ISO 10993 biocompatibility standards increasingly determine market access for medical-grade microgels. Stakeholders must track evolving chemical hazard classifications in the EU and US to anticipate reformulation mandates and raw material substitution cycles.
Market Dynamics
REACH restrictions on solvent-based formulations are redirecting procurement budgets toward compliant aqueous polymer technologies, compressing qualification cycles for water-based emulsion systems across OECD manufacturing bases.
Growth Catalysts
- EPA VOC regulations:The Clean Air Act mandates are accelerating displacement of solvent-borne coatings in US architectural applications, pulling demand toward low-VOC acrylic emulsions.
- Film-forming binders:Water-based polymer colloids now dominate volume consumption in architectural coatings and adhesives as environmental compliance tightens.
- East Asian specialty chemical clusters:Demand concentrates around Shanghai and Osaka, where coatings manufacturers scale purchases of compliant aqueous systems.
Market Restraints
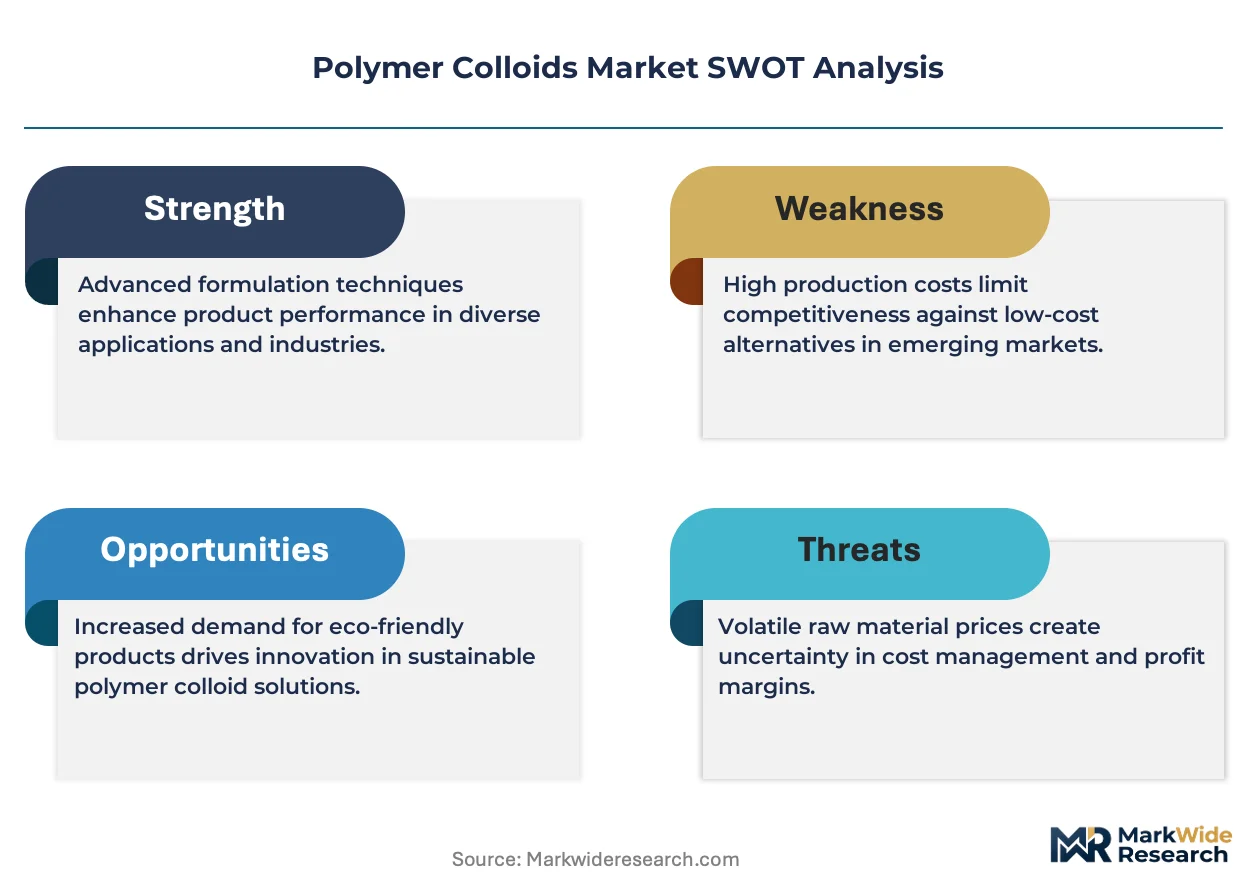
- Acrylic monomer cost volatility:Petrochemical feedstock exposure creates margin pressure for emulsion specialists lacking captive monomer supply.
- Silica-acrylic hybrid production concentration:Specialty nanoparticle synthesis requires controlled-atmosphere facilities concentrated in Germany and Japan.
- ISO 10993 biocompatibility timelines:Medical-grade microgel certification extends commercialization cycles for parenteral delivery applications.
Strategic Opportunities
- Pharmaceutical delivery systems:Nanoparticles command premium pricing in controlled-release matrices as FDA guidance on polymer excipients clarifies approval pathways.
- Rheology modifier applications:Miniemulsion polymerization advances enable functionalized particles for high-shear industrial coatings.
- EU Green Deal chemical hazard reclassifications:Anticipated substance restrictions will force reformulation cycles favoring early-mover aqueous technology suppliers.
Industry Challenges
- Surfactant stabilization expertise:Formulation chemists with emulsion polymerization process knowledge remain scarce relative to solvent-borne coating specialists.
- Emulsion-to-solvent line conversion:Coatings manufacturers face capex intensity for tank farm and drying infrastructure reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polymer Colloids Market |
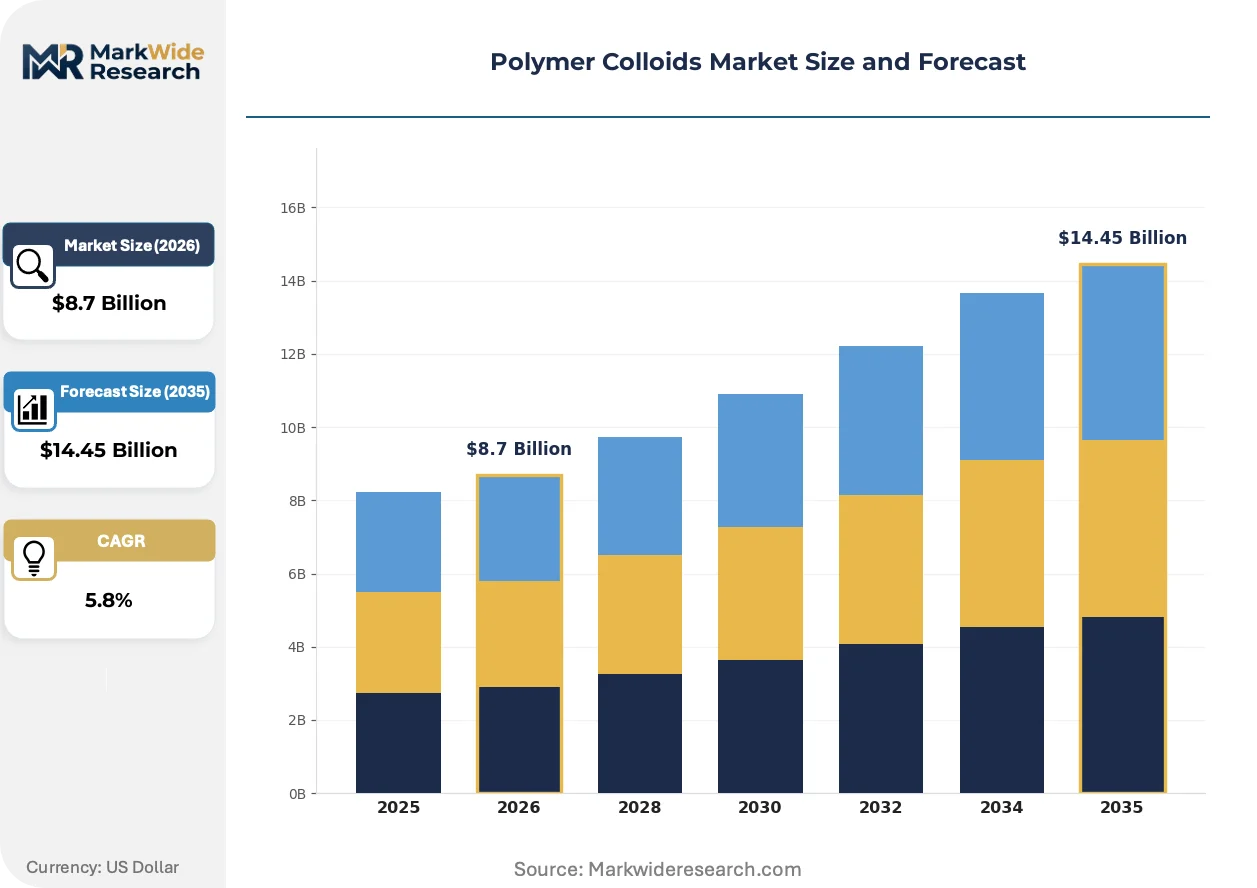
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsions, Microgels, Nanoparticles, Dispersions End User: Pharmaceuticals, Coatings, Food and Beverage, Cosmetics Application: Adhesives, Paints, Ink, Sealants Formulation: Water-Based, Solvent-Based, Powder, Hybrid |
| Companies Covered | BASF SE, Dow Inc., Evonik Industries AG, Wacker Chemie AG, Mallard Creek Polymers, Apcotex Industries Limited, LAIEX, Gellner Industrial LLC, AkzoNobel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polymer Colloids Market Strategic Shifts
Polymer colloid technology is compressing particle size distributions while regulatory frameworks accelerate aqueous system qualification across multiple industrial verticals.
Hybrid silica-acrylic nanoparticle synthesis is miniaturizing film-forming architectures for high-performance coatings. Automotive OEMs in Germany and Japan are adopting these systems for scratch-resistant clearcoats within compressed development cycles. The technology is miniaturizing performance gaps between water-borne and solvent-borne formulations in demanding exterior applications.
REACH registration requirements are elevating compliance costs for imported polymer colloids while accelerating qualification of EU-synthesized aqueous alternatives. ECHA substance evaluations are forcing reformulation of legacy styrene-acrylic emulsions in decorative coatings. German coatings manufacturers are redirecting procurement toward Ludwigshafen-based supply to secure registration certainty.
Coatings manufacturers now unbundle technical service from bulk emulsion supply contracts, compressing supplier switching cycles. Regional distributors in the US Midwest are losing share to direct mill-to-plant relationships for large-volume architectural coatings buyers. This pattern is most visible in Texas and Ohio, where water-based system qualification labs co-locate with manufacturing complexes.
Polymer Colloids Market Segmentation
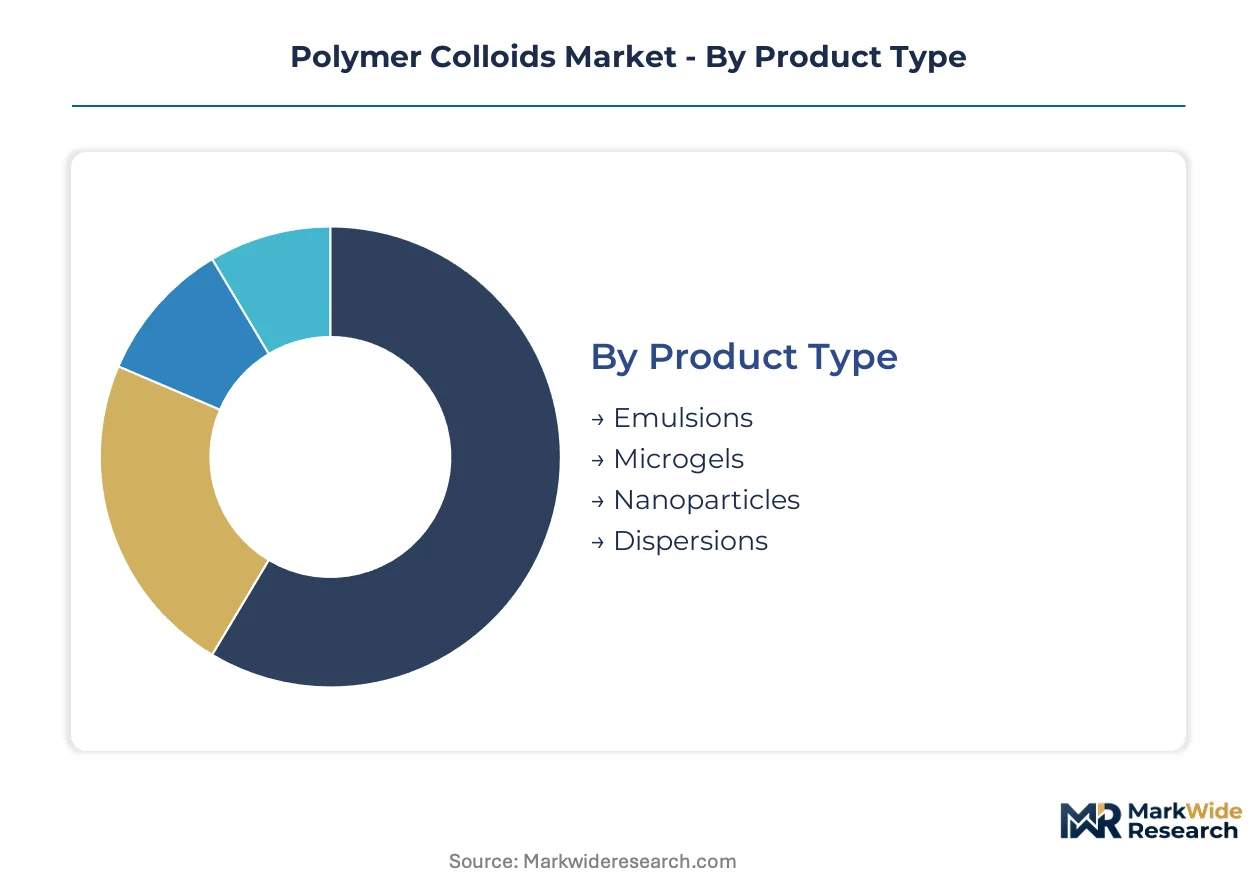
Polymer colloid suppliers face divergent substitution pressures across product architectures and end-use specifications. Segmentation reveals where aqueous technologies displace legacy solvent systems versus where material science barriers protect incumbent formats.
Product Type:
Emulsions confront the most acute substitution threat from solvent-borne alternatives in high-performance coatings, while nanoparticles remain insulated by patent-protected synthesis methods.
- Emulsions:Aqueous dispersions of 50–500 nm polymer particles stabilized by surfactant systems, synthesized via batch or continuous emulsion polymerization. German coatings manufacturers around Ludwigshafen and Leverkusen are scaling purchases of low-VOC acrylic emulsions as REACH restrictions compress qualification cycles for water-based architectural binders.
- Nanoparticles:Sub-100 nm polymer or hybrid particles engineered via miniemulsion or controlled radical polymerization, commanding premium positioning in pharmaceutical delivery and optical coatings. Silica-acrylic hybrid production concentrates in controlled-atmosphere facilities near Essen and Osaka, limiting supply expansion despite climbing demand from Japanese automotive clearcoat formulators.
- Microgels:Crosslinked hydrogel particles swelling in aqueous media, functioning as rheology modifiers and controlled-release matrices.
- Dispersions:Broader particle size distributions than emulsions, often spray-dried to powder form for reconstitution in industrial adhesives.
Emulsions retain volume leadership; nanoparticles hold the steepest expansion curve.
End User:
Customer procurement sophistication varies sharply, with pharmaceutical buyers demanding ISO 10993 biocompatibility documentation that coatings formulators rarely require.
- Pharmaceuticals:Parenteral drug delivery systems utilize functionalized nanoparticles for controlled-release kinetics. FDA guidance on polymer excipients shapes approval pathways, extending commercialization timelines for medical-grade microgels relative to industrial applications.
- Coatings:Architectural and industrial finish manufacturers represent the dominant volume sink, with water-based system qualification accelerating across US and EU manufacturing bases under EPA and REACH compliance pressure.
- Food and Beverage:Edible film coatings and encapsulation systems for flavor protection.
- Cosmetics:Skin-care formulations employing microgels for texture modification and active ingredient delivery.
Coatings commands absolute volume; pharmaceuticals posts the most rapid value-per-kilogram gains.
Application:
Performance specifications diverge most acutely between exterior architectural exposures and controlled indoor industrial environments.
- Adhesives:Pressure-sensitive and structural bonding applications favor emulsion systems for porous substrates, while solvent-based dispersions retain share in moisture-sensitive electronics assembly.
- Paints:Film-forming binders in architectural and automotive clearcoats, where hybrid silica-acrylic nanoparticles are compressing performance gaps between water-borne and solvent-borne exterior durability.
- Ink:Flexographic and gravure printing formulations.
- Sealants:Construction and automotive gap-filling applications requiring elastomeric recovery.
Paints dominates tonnage; adhesives shows the most rapid formulation turnover toward aqueous platforms.
Formulation:
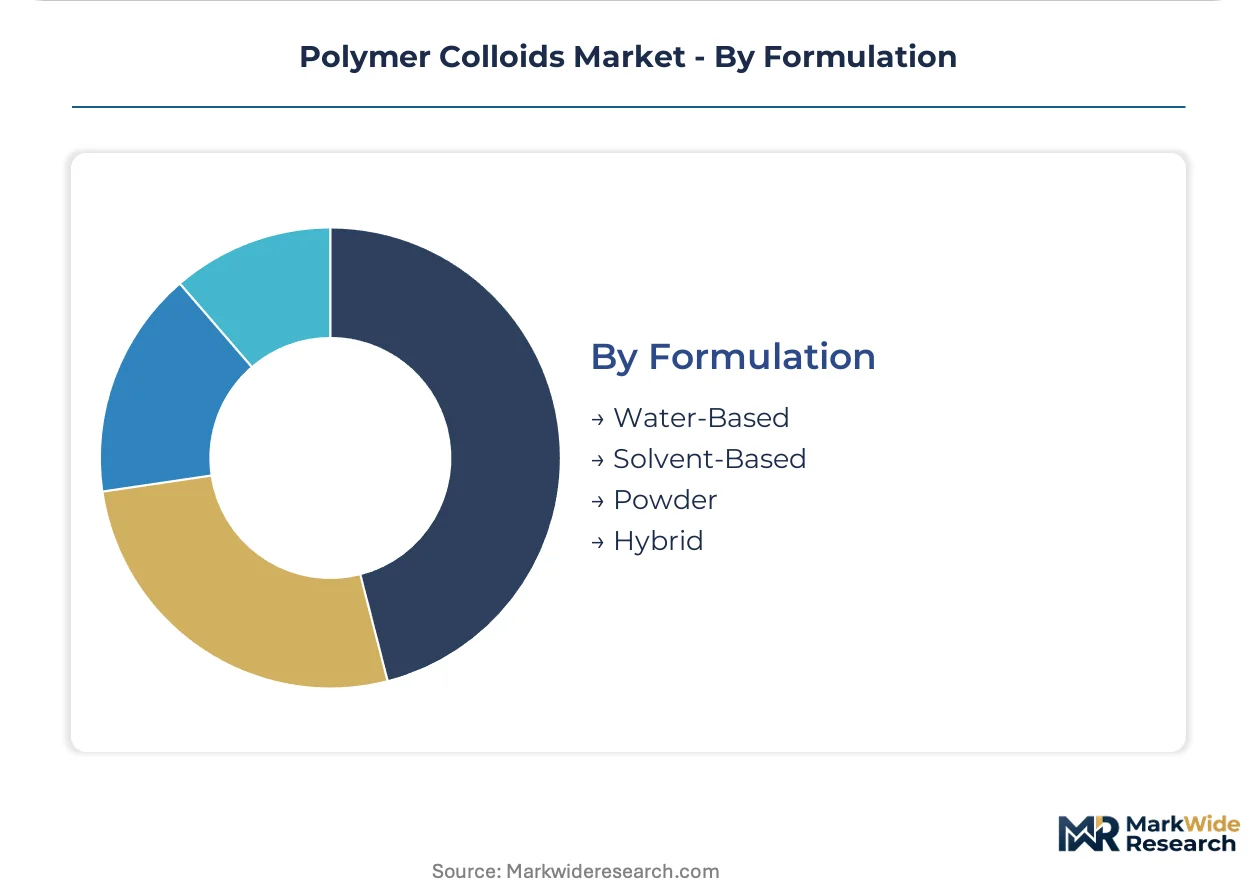
Regulatory geography determines viable formulation chemistry more than end-use performance requirements.
- Water-Based:Surfactant-stabilized aqueous systems now qualifying for previously solvent-restricted applications. EPA Clean Air Act mandates and REACH substance evaluations are redirecting procurement budgets toward compliant aqueous polymer technologies across OECD manufacturing bases.
- Solvent-Based:Hydrocarbon or oxygenated solvent carriers retaining share in high-solids industrial coatings and moisture-sensitive electronics applications where water-borne cure kinetics prove incompatible.
- Powder:Spray-dried emulsion particles for reconstitution at point-of-use, reducing shipping weight in remote construction markets.
- Hybrid:Dual-cure or water-reducible systems bridging performance and compliance requirements.
Water-based formulations capture incremental share fastest; solvent-based retains defensive positions in performance-critical niches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coatings buyers in Germany and the United States absorb price premiums for REACH-compliant emulsions with minimal volume elasticity, while procurement teams in China and India remain acutely sensitive to acrylic monomer cost fluctuations.
United States
Architectural coatings manufacturers in Texas and Ohio are accelerating water-based system qualification as EPA Clean Air Act mandates tighten VOC limits for solvent-borne formulations. The agency's architectural coatings rule is compressing reformulation timelines for exterior paint producers. Direct mill-to-plant relationships now dominate procurement around the Freeport manufacturing complex, bypassing traditional Midwest distributors.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg are scaling purchases of hybrid silica-acrylic nanoparticles for scratch-resistant clearcoats. ECHA substance evaluations under REACH are forcing legacy styrene-acrylic emulsion reformulations in decorative coatings. Procurement budgets are redirecting toward Ludwigshafen-based supply chains to secure registration certainty and shorten qualification cycles.
China
Construction coatings demand concentrates in the Yangtze River Delta around Shanghai, where local manufacturers face MEE enforcement of volatile organic compound discharge standards. The ministry's tightening environmental inspections are accelerating displacement of solvent-based architectural formulations. Domestic emulsion producers are expanding captive acrylic monomer capacity to offset petrochemical feedstock volatility.
Japan
Automotive clearcoat formulators in Osaka and Nagoya command premium pricing for controlled-atmosphere synthesized nanoparticles. METI's chemical substance management policies are elevating documentation requirements for imported polymer colloids. Production of silica-acrylic hybrids remains concentrated in Essen-linked technical partnerships and domestic Osaka Bay facilities.
India
Industrial adhesives manufacturers in Maharashtra and Gujarat are qualifying water-based emulsions for porous substrate applications as BIS environmental standards tighten. The bureau's harmonization with ISO formulations is accelerating displacement of solvent-borne systems in packaging adhesives. Regional emulsion specialists are expanding technical service capabilities in Pune and Ahmedabad to capture switching demand.
Polymer Colloids Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Integrated petrochemical giants with captive monomer supply dominate volume positioning, while regional emulsion specialists compete on formulation service and rapid qualification support. Three archetypes define the field: backward-integrated multinationals controlling upstream acrylic supply, specialty nanoparticle synthesis houses with controlled-atmosphere capabilities, and regional formulators unbundling technical service from bulk supply. Capacity expansion and direct mill-to-plant relationship building constitute the dominant competitive moves across all tiers.
Among German-based integrated chemical producers, BASF SE exemplifies the backward-integrated archetype through its Ludwigshafen Verbund operations. Dow Inc. anchors North American supply positioning from its Texas manufacturing base. Evonik Industries AG occupies the specialty synthesis tier, representing controlled-atmosphere nanoparticle capabilities concentrated in German and Japanese technical clusters.
| Leading Market Players |
|---|
| BASF SE |
| Dow Inc. |
| Evonik Industries AG |
| Wacker Chemie AG |
| Mallard Creek Polymers |
| Apcotex Industries Limited |
| LAIEX |
| Gellner Industrial LLC |
| AkzoNobel |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between German coatings manufacturers and Ludwigshafen-based suppliers lock in both acrylic monomer supply and price visibility, insulating integrated producers from petrochemical feedstock volatility while compressing margin flexibility for regional emulsion specialists.
Pricing Analysis
Technical service bundling drives lifetime value across the polymer colloid value chain. Three-tier pricing structure across premium, standard, and economy levels separates ISO 10993-certified medical-grade microgels from industrial emulsions and commodity architectural binders. Cost compression in standard-grade architectural emulsions is intensifying because Chinese domestic producers are expanding captive monomer capacity. Coatings formulators in India and China exhibit acute price sensitivity, while pharmaceutical buyers in Germany and Japan absorb premiums for biocompatibility documentation.
Supply Chain Analysis
Inventory buffers for controlled-atmosphere nanoparticle synthesis stretch lead times to 8-12 weeks for automotive clearcoat formulators in Osaka and Nagoya. Supply concentrates in Germany, China, and the United States for emulsion polymerization capacity, while silica-acrylic hybrid production draws from Essen and Osaka Bay technical clusters. Single-source vulnerability pervades specialty nanoparticle feedstocks, with surfactant stabilization chemistries anchored in German and Japanese formulation expertise. Distribution runs through direct mill-to-plant relationships in Texas and Ohio, bypassing traditional Midwest distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polymer colloids market functions as a defensive-moat story where regulatory entrenchment protects incumbents: REACH registration requirements and ISO 10993 certification timelines create switching costs that lock in qualified supplier relationships.
For Market Incumbents: Secure captive acrylic monomer supply through backward integration or long-term offtake agreements with Ludwigshafen and Freeport petrochemical complexes. Expand controlled-atmosphere nanoparticle capacity in Essen-linked technical partnerships before Japanese automotive OEMs consolidate supplier panels. Regulatory compliance costs threaten margin structures for non-integrated players.
For New Entrants and Emerging Players: Anchor in Indian industrial adhesives markets where BIS environmental standards are accelerating displacement of solvent-borne systems in Maharashtra and Gujarat packaging applications. Target technical service unbundling as a go-to-market angle, offering rapid qualification support that bypasses traditional distributor relationships in Pune and Ahmedabad.
For Investors and Strategic Acquirers: Regional emulsion specialists with formulation service capabilities and established mill-to-plant relationships in Texas or Ohio represent the most defensible acquisition targets. Long-term viability hinges on positioning ahead of EU Green Deal chemical hazard reclassifications that will force reformulation cycles favoring early-mover aqueous technology suppliers. Watch ECHA substance evaluation timelines as the inflection signal for legacy styrene-acrylic displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive acrylic monomer production at Ludwigshafen insulates BASF from petrochemical volatility. |
| Capacity Expansion | Controlled-atmosphere nanoparticle facilities in Essen meet climbing demand from Japanese automotive OEMs. |
| Long-term Supply Agreement | Direct mill-to-plant contracts in Texas and Ohio compress switching cycles for architectural coatings buyers. |
| Green Manufacturing Transition | REACH-compliant aqueous emulsion qualification accelerates displacement of solvent-borne formulations. |
| Joint Venture | Osaka Bay technical partnerships concentrate silica-acrylic hybrid synthesis expertise for premium clearcoats. |
Study Parameters
Operator-level perspectives from coatings formulators, pharmaceutical excipient specialists, and emulsion polymerization plant managers anchored the qualitative base for this study. Primary interviews with procurement leads at German automotive OEMs, technical R&D directors at regional Indian emulsion producers, and distribution channel partners in the US Midwest combined with secondary validation from ECHA substance evaluation databases, EPA Clean Air Act regulatory filings, and SEC 10-K disclosures from integrated chemical producers. Bottom-up volume modeling and top-down value triangulation cross-checked segment-level assumptions.
Sensitivity analysis across feedstock price scenarios, regulatory enforcement timelines, and substitution elasticity parameters shaped the analytical framework. Segmentation dimensions modeled include product architecture, end-use industry, formulation chemistry, and regional production hub concentration. CAGRs were derived from trend extrapolation anchored in documented qualification cycle compression and displacement rates of solvent-borne systems. Forecast inputs incorporated REACH registration cost trajectories and MEE enforcement intensity in the Yangtze River Delta.
Material uncertainties — acrylic monomer cost volatility, ECHA substance evaluation outcomes, and MEE inspection enforcement variability — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory compliance timelines and feedstock price regimes. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Conditioning Polymers Market
Polymers & Resins
Low Density Polyethylene Market
Polymers & Resins
Global Encapsulation Resins Market
Polymers & Resins
Europe Super Absorbent Polymers (SAP) Market
Polymers & Resins
Biaxially Oriented Polypropylene Market
Polymers & Resins
GCC Vinyl Flooring Market
Polymers & Resins
Polyalkylene Glycols (Pags) Market
Polymers & Resins
Flame Retardant Polyester Resins Market
Polymers & Resins
Acrylonitrile Butadiene Styrene (ABS) Market
Polymers & Resins
Expanded Polypropylene (EPP) Foam Market
Polymers & Resins
Global Polyurethane Dispersions Market
Polymers & Resins
Aromatic Ketone Polymer Market
Polymers & Resins
Global Medical Superabsorbent Polymers Market
Polymers & Resins
Global Polypropylene Random Copolymer Market
Polymers & Resins
Latent Curing Agents for Epoxy Resin Market
Polymers & Resins
Paste PVC Resin Market