
 Vinyl Cyclohexane Market | 2026-2036
Vinyl Cyclohexane Market Size, Share, and Industry Trends Forecast 2026-2036
Vinyl Cyclohexane Market Analysis
A capital-intensity divergence between integrated petrochemical giants and specialty chemical operators is unwinding competitive dynamics across vinyl cyclohexane supply chains. Exxon Mobil Corporation leverages its Gulf Coast cracking infrastructure to sustain captive feedstock economics for standard-grade material. BASF SE anchors European supply through Ludwigshafen-based polymer intermediates capacity, while Merck KGaA differentiates via ultra-high-purity grades serving semiconductor packaging applications.
Vinyl cyclohexane is a cyclic olefin intermediate produced through catalytic hydrogenation of vinylbenzene or dehydrogenation of ethylcyclohexane, typically refined to purities exceeding 99% for polymer-grade specifications; it functions primarily as a comonomer and modifier in polystyrene derivatives, enhancing thermal stability and processability in extrusion systems. Specialty Grades command disproportionate margin pools due to pharmaceutical and electronics-grade certification requirements, while Industrial Grades face commoditization pressure from Asian bulk producers. The Plastics application segment dominates volume offtake through polystyrene and ABS modification, though Coatings applications in automotive refinish systems represent the fastest-expanding demand vector.
EPA oversight of volatile organic compound emissions shapes formulation standards for coatings and adhesives applications in the United States, while REACH registration requirements and ECHA substance evaluation protocols govern market access across European Union member states. China's MIIT enforces GB standards for chemical purity in electronics-grade material, creating divergent compliance pathways for multinational suppliers. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions, as regulatory spillover into cyclic olefin chemistries could redirect R&D investment toward halogen-free modification technologies.
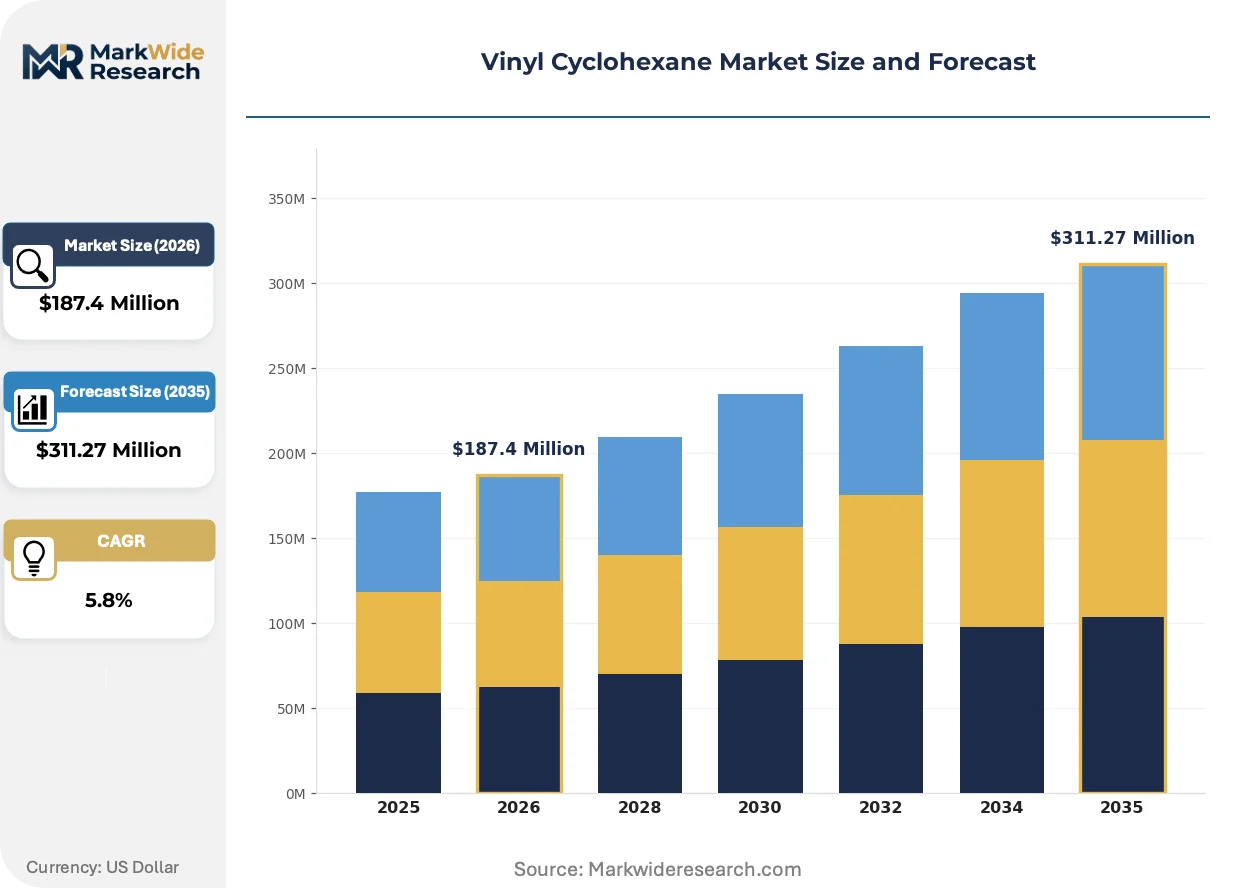
Market Dynamics
Automotive lightweighting mandates and semiconductor packaging grade requirements are bifurcating vinyl cyclohexane demand into two distinct purity tiers, forcing producers to recalibrate reactor configurations and certification investments.
Growth Catalysts
- REACH substance evaluation protocols:ECHA's tightening purity specifications for cyclic olefins are accelerating specialty-grade capacity expansions across European polymer compounding clusters. German automotive OEMs now require sub-50 ppm impurity thresholds for underhood applications.
- Ethylcyclohexane dehydrogenation yield improvements:Novel platinum-alumina catalyst formulations are lifting selectivity above 94%, reducing hydrogen consumption and per-unit production costs for integrated producers.
- Polystyrene thermal stability requirements:Extrusion-grade resin processors in packaging and construction are substituting linear olefins with cyclic structures to meet elevated service temperature specifications.
Market Restraints
- Benzene feedstock volatility:Vinylbenzene hydrogenation economics remain tethered to aromatics complex margins, exposing non-integrated operators to margin compression when naphtha spreads widen.
- Asian bulk supply concentration:China's Shandong and Jiangsu provinces host expanding merchant capacity targeting industrial-grade specifications, pressuring European and North American standard-grade pricing.
- Catalytic deactivation rates:Sulfur and nitrogen contaminants in ethylcyclohexane feedstocks accelerate catalyst poisoning, necessitating costly regeneration cycles and extended turnaround intervals.
Strategic Opportunities
- India electronics manufacturing incentives:PLI scheme disbursements for semiconductor packaging substrates are creating demand for electronics-grade vinyl cyclohexane with metallic impurity controls below 10 ppb.
- Halogen-free flame retardant convergence:Cyclic olefin copolymers incorporating vinyl cyclohexane units are displacing brominated additives in connector housings, opening automotive electrical system applications.
- Direct procurement from integrated producers:Polymer compounders in Germany's industrial chemical corridor are bypassing distributors to secure volume commitments with Ludwigshafen-based suppliers.
Industry Challenges
- Pharmaceutical-grade certification timelines:ICH Q7 compliance documentation for excipient-grade material requires 18-24 month validation cycles, delaying market entry for new production assets.
- Reactor metallurgy for ultra-high-purity production:Eliminating iron and nickel contamination demands specialized alloy construction, doubling capital intensity versus standard-grade trains.
- Legacy polystyrene formulation compatibility:High-cyclic content modifications require recalibration of extrusion temperature profiles, creating adoption friction among established processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vinyl Cyclohexane Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low Density, High Density, Specialty Grades, Industrial Grades Application: Plastics, Coatings, Adhesives, Fillers End User: Manufacturing, Automotive, Construction, Electronics Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | Exxon Mobil Corporation, Dow Inc, BASF SE, Merck KGaA, DuPont de Nemours, Inc., Chevron Phillips Chemical Company LLC, SABIC, PTT Global Chemical Public Company Limited, China National Petroleum Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vinyl Cyclohexane Market Emerging Trajectories
Process intensification and regulatory chemistry are redefining competitive advantage in vinyl cyclohexane production, with purification technology and compliance architecture becoming primary differentiation vectors.
Membrane-assisted reactive distillation is decomposing traditional multi-stage separation trains for specialty-grade production. Semiconductor packaging material suppliers in Japan and South Korea are adopting these hybrid units to achieve metallic impurity reductions without cryogenic recrystallization. The technology is decomposing capital barriers for mid-scale entrants seeking electronics-grade certification.
EPA volatile organic compound emission standards for coatings formulations are tightening permissible solvent content in automotive refinish systems. Cyclic olefin resins incorporating vinyl cyclohexane offer lower vapor pressure profiles than aromatic alternatives, enabling compliance without sacrificing film formation properties. Refinish formulators in Michigan and Ohio are reformulating product lines to maintain NHTSA-approved coating system qualifications.
Compounders are consolidating purchase agreements around certified mass-balance chains rather than spot-market sourcing. Polymer processors serving automotive OEMs in Stuttgart and Wolfsburg now require ISCC PLUS documentation for bio-attributed feedstock fractions. This verification-driven procurement pattern favors integrated petrochemical operators with established sustainability certification infrastructure over merchant traders.
Vinyl Cyclohexane Market Segmentation
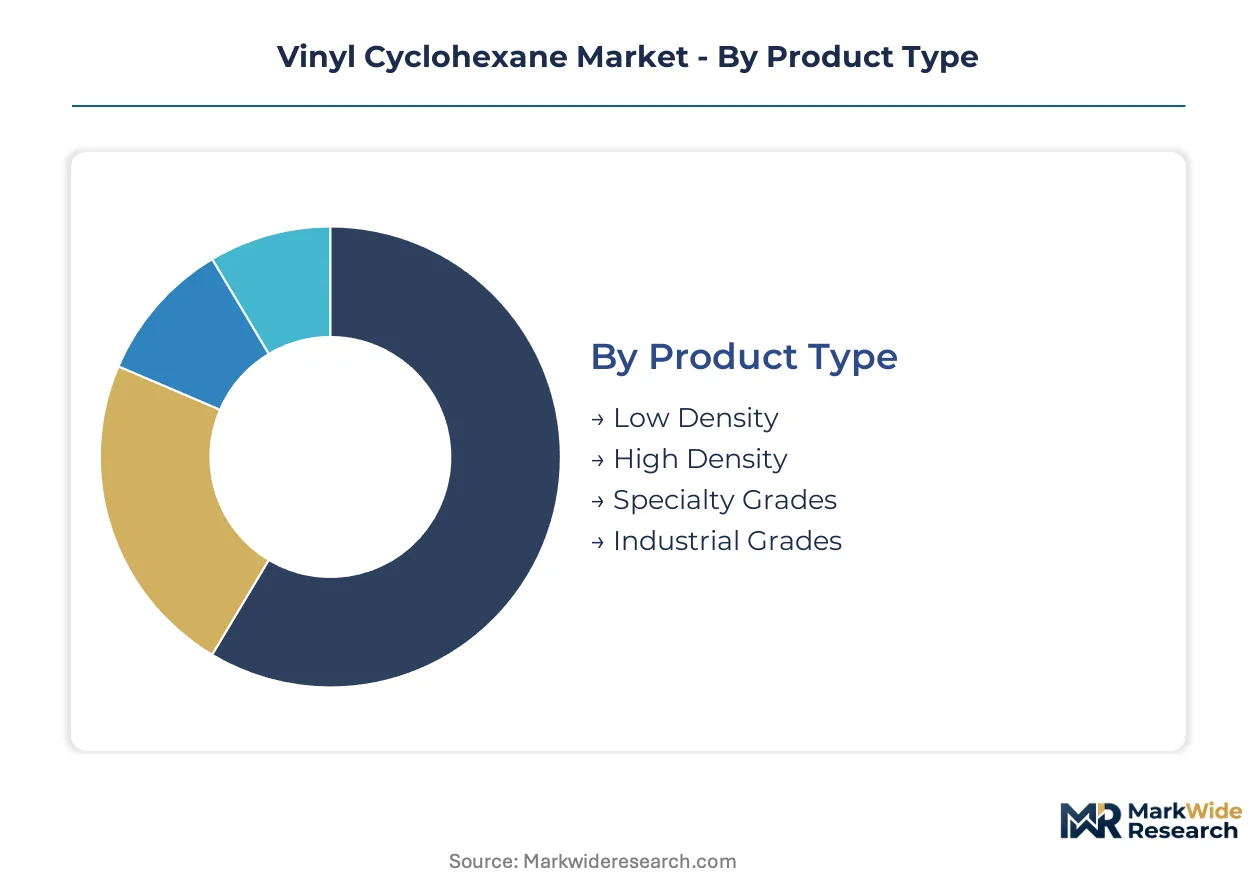
Segmentation in vinyl cyclohexane reveals how purity gradients and channel economics fragment margin capture across the value chain. Producers must align reactor configurations and certification investments with the specific performance thresholds each tier demands.
Product Type:
Specialty-grade segments face acute substitution pressure from bio-based cyclic olefins and mass-balance certified alternatives as automotive and electronics OEMs tighten sustainability procurement protocols.
- Specialty Grades:Ultra-high-purity formulations exceeding 99.9% purity with metallic impurity controls below 10 ppb. Semiconductor packaging substrate manufacturers in Germany's industrial chemical corridor source these grades for advanced interconnect materials. REACH substance evaluation protocols are accelerating capacity investments as sub-50 ppm thresholds become mandatory for underhood automotive applications.
- Industrial Grades:Standard polymer-grade material refined to 99% purity serving bulk polystyrene modification. Shandong and Jiangsu province producers in China are expanding merchant capacity targeting this specification, compressing pricing for European and North American non-integrated operators exposed to benzene feedstock volatility.
- Low Density:Lower molecular weight variants optimized for extrusion-grade resin flow properties in packaging applications.
- High Density:Higher molecular weight grades enhancing dimensional stability in construction-grade polystyrene foam systems.
Industrial Grades retain volume leadership; Specialty Grades hold the steepest expansion curve.
Application:
Coatings applications command disproportionate margin expansion as EPA volatile organic compound standards force automotive refinish formulators toward lower vapor pressure cyclic olefin systems.
- Coatings:Automotive refinish and industrial coating systems leveraging vinyl cyclohexane's reduced vapor pressure profile versus aromatic alternatives. Refinish formulators in Michigan and Ohio are reformulating product lines to maintain NHTSA-approved coating system qualifications while meeting tightened solvent content limits.
- Plastics:Dominant volume application through polystyrene and ABS modification, where cyclic olefin incorporation enhances thermal stability for elevated service temperature specifications in extrusion systems. Packaging and construction resin processors are substituting linear olefins with these cyclic structures.
- Adhesives:Pressure-sensitive and structural adhesive formulations requiring improved thermal resistance in automotive assembly applications.
- Fillers:Specialty additive applications in polymer compounding where cyclic olefin modifiers adjust rheological properties.
Plastics maintains volume dominance; Coatings is climbing the fastest as regulatory compliance reshapes formulation economics.
End User:
Electronics manufacturing concentrates the most stringent purity requirements and certification timelines, creating structural barriers for new entrants.
- Electronics:Semiconductor packaging and advanced substrate manufacturing demanding electronics-grade material with metallic impurity controls below 10 ppb. India's PLI scheme disbursements for semiconductor packaging substrates are creating new demand nodes for certified suppliers.
- Automotive:Lightweighting mandates and underhood thermal management specifications are bifurcating demand into sub-50 ppm impurity thresholds for specialty grades versus standard industrial specifications for interior applications.
- Manufacturing:Polymer compounding and resin processing operations serving packaging, construction, and consumer goods sectors.
- Construction:Extruded polystyrene foam and insulation systems requiring elevated service temperature performance.
Manufacturing retains volume leadership; Electronics holds the steepest expansion curve.
Distribution Channel:
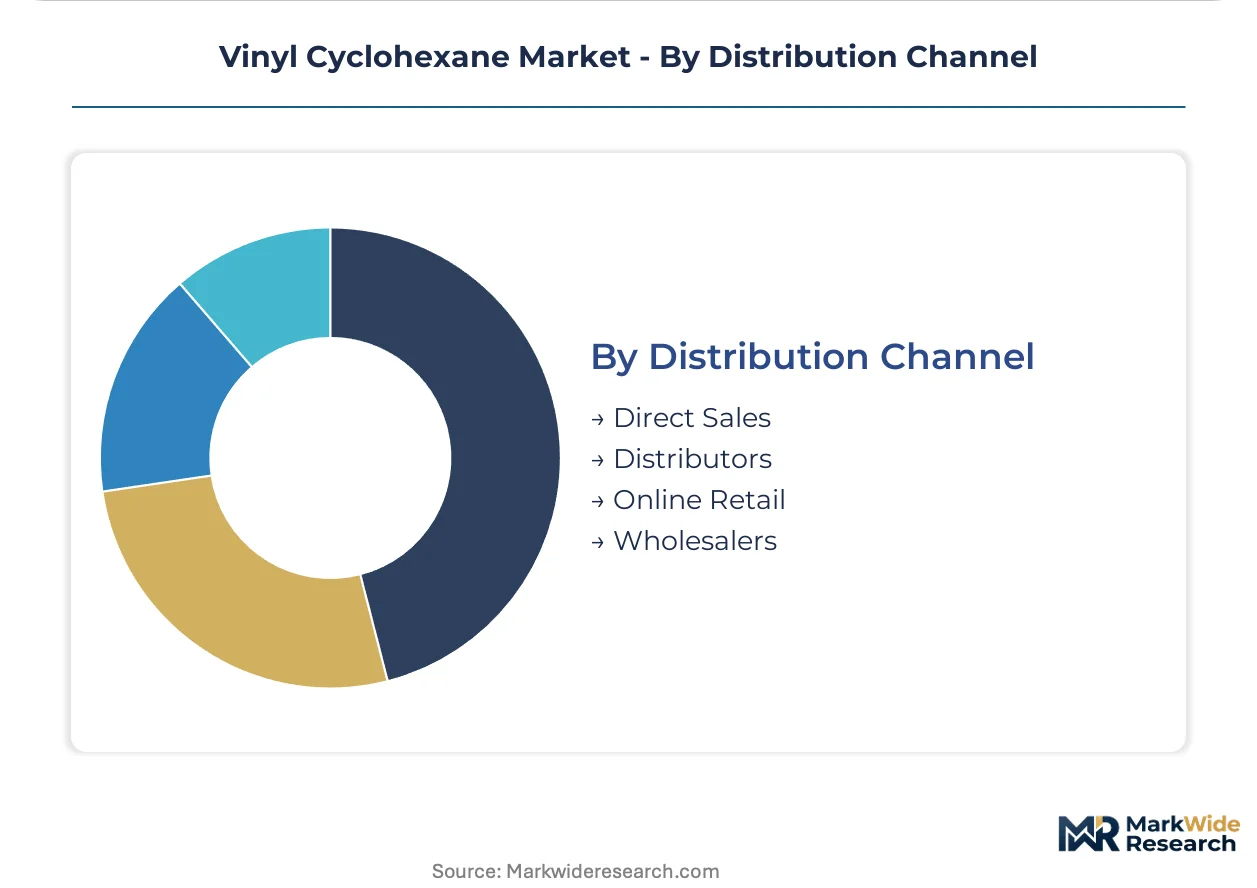
Direct procurement patterns are restructuring channel economics as integrated producers bypass traditional distributor networks to capture margin and secure volume commitments.
- Direct Sales:Volume commitments between integrated producers and polymer compounders, particularly in Germany's industrial chemical corridor where Ludwigshafen-based suppliers anchor supply relationships. ISCC PLUS documentation requirements favor operators with established sustainability certification infrastructure.
- Distributors:Merchant traders serving mid-scale processors and regional compounders lacking scale for direct procurement, facing compression as certified mass-balance chains consolidate around primary supplier relationships.
- Online Retail:Emerging channel for small-volume specialty grades and sample quantities serving R&D laboratories and formulation development.
- Wholesalers:Bulk aggregation for industrial-grade material in Asian supply markets with fragmented downstream processing bases.
Direct Sales retains volume leadership; Online Retail is gaining share fastest as digital procurement platforms penetrate specialty chemical sourcing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China's merchant-grade markets exhibit acute price sensitivity to benzene feedstock spreads, while semiconductor packaging manufacturers in Germany and South Korea absorb substantial premiums for sub-10 ppb metallic impurity controls.
Germany
Automotive OEMs in Stuttgart and Wolfsburg now mandate sub-50 ppm impurity thresholds for underhood vinyl cyclohexane applications. ECHA's REACH substance evaluation protocols are tightening purity specifications across cyclic olefin supply chains. Ludwigshafen-based polymer intermediates capacity anchors European specialty-grade production.
China
Shandong and Jiangsu provinces host expanding merchant capacity targeting industrial-grade specifications for bulk polystyrene modification. MIIT enforces GB standards for chemical purity in electronics-grade material. Yangtze River Delta semiconductor packaging substrate manufacturers source certified ultra-high-purity grades through direct procurement channels.
United States
Refinish formulators in Michigan and Ohio are reformulating coating systems to meet EPA volatile organic compound emission standards. NHTSA-approved automotive coating qualifications require lower vapor pressure cyclic olefin alternatives. Gulf Coast cracking infrastructure sustains captive feedstock economics for standard-grade material.
India
PLI scheme disbursements for semiconductor packaging substrates are creating demand nodes for electronics-grade material with metallic impurity controls below 10 ppb. Karnataka and Telangana electronics manufacturing clusters are consolidating purchase agreements around certified suppliers. Domestic polymer compounders lack scale for direct procurement from integrated producers.
Japan
Semiconductor packaging material suppliers adopt membrane-assisted reactive distillation to achieve metallic impurity reductions. METI oversees industrial chemical safety protocols governing cyclic olefin market access. Kyushu-based advanced substrate manufacturers source specialty grades through established mass-balance certified chains.
Vinyl Cyclohexane Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated petrochemical giants commanding feedstock economics while specialty operators capture certification premiums. The market structure bifurcates between Gulf Coast and European integrated producers with captive cracking capacity, and mid-scale specialty houses focused on electronics-grade purification. Three archetypes dominate: upstream-integrated majors with aromatics complex leverage, ultra-high-purity specialists with semiconductor-grade certification, and Asian merchant producers with bulk industrial-grade scale. Competitive moves center on reactor metallurgy investments for contamination control and direct procurement relationships bypassing distributor networks.
Among integrated petrochemical operators, Exxon Mobil Corporation and BASF SE exemplify the upstream-integrated archetype with captive feedstock infrastructure. Merck KGaA occupies a position within the ultra-high-purity tier, representing specialty-grade differentiation through semiconductor packaging certification. These three anchors illustrate how competitive advantage separates feedstock-cost leadership from purity-technology leadership.
| Leading Market Players |
|---|
| Exxon Mobil Corporation |
| Dow Inc |
| BASF SE |
| Merck KGaA |
| DuPont de Nemours, Inc. |
| Chevron Phillips Chemical Company LLC |
| SABIC |
| PTT Global Chemical Public Company Limited |
| China National Petroleum Corporation |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day order lead times for electronics-grade vinyl cyclohexane concentrate pricing power with Ludwigshafen-based integrated producers serving German automotive OEMs, while Shandong merchant suppliers compress industrial-grade margins through spot-market liquidity.
Pricing Analysis
After-sales technical service contracts for extrusion-grade resin processors anchor lifetime value capture for specialty-grade suppliers. Three-tier pricing structure across electronics-grade, automotive-grade, and industrial-grade levels stratifies by metallic impurity thresholds and certification documentation. Cost compression in industrial-grade material is intensifying because Shandong and Jiangsu bulk capacity expansion feeds Asian spot markets. Polymer compounders in Germany's industrial chemical corridor exhibit lowest price sensitivity due to captive direct procurement relationships, while Indian domestic processors face acute margin pressure from freight and duty stacking.
Supply Chain Analysis
Port congestion on Rotterdam-Antwerp chemical corridors and container tightness across Asia-Europe lanes elevate inbound logistics costs for non-integrated European operators. Supply concentrates in Germany, China, and the United States, with Ludwigshafen, Shandong-Jiangsu, and Gulf Coast cracking complexes anchoring regional availability. Feedstock economics draw from benzene-aromatics complex margins, platinum-alumina catalyst supply, and hydrogen utility costs. Single-source vulnerability runs through German semiconductor-grade purification capacity. Distribution runs through direct sales agreements for specialty tiers and merchant traders for industrial bulk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as polymer compounders in Stuttgart and Wolfsburg consolidate purchase agreements around ISCC PLUS-certified mass-balance chains, squeezing distributor intermediation.
For Market Incumbents: Fortify Ludwigshafen-based specialty-grade capacity with reactor metallurgy investments eliminating iron and nickel contamination, defending against Japanese membrane-assisted reactive distillation entrants. Anchor backward integration into captive ethylcyclohexane feedstock to buffer benzene spread volatility eroding merchant producer economics.
For New Entrants and Emerging Players: Lead with India's PLI scheme semiconductor packaging substrate opportunity, where electronics-grade demand with sub-10 ppb metallic impurity controls outruns domestic supply. Karnataka and Telangana electronics manufacturing clusters present the most penetrable geography for certified new capacity. Pursue direct procurement bypass of distributor networks through volume commitment structures mirroring German industrial chemical corridor patterns.
For Investors and Strategic Acquirers: Long-term, this sits as a certification-arbitrage play because REACH substance evaluation protocols and ECHA tightening will structurally advantage operators with existing ICH Q7 documentation infrastructure. Target acquisition archetype: mid-scale specialty houses with semiconductor-grade purification technology but underutilized reactor trains. Watch EPA volatile organic compound standard revisions for coatings as inflection signal redirecting formulation R&D spend toward cyclic olefin systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Reactor Metallurgy Upgrade | Specialized alloy construction eliminates metallic contamination for semiconductor-grade certification. |
| Backward Integration into Ethylcyclohexane | Captive feedstock economics insulate margin from benzene-aromatics spread volatility. |
| Membrane-Assisted Reactive Distillation Adoption | Hybrid separation technology reduces capital barriers for electronics-grade purification entry. |
| ISCC PLUS Mass-Balance Certification | Verified bio-attributed chains secure automotive OEM procurement consolidation in Germany. |
| Direct Procurement Relationship Formation | Volume commitments with polymer compounders bypass distributor margin extraction. |
Methodological Framework
Initial hypotheses were tested against primary input from plant managers at integrated petrochemical complexes, procurement leads at German automotive OEMs, technical R&D directors in semiconductor packaging substrate manufacturing, and distribution channel partners in Asian merchant markets, and refined through secondary validation against customs/trade data, ACC and Cefic industry reports, SEC 10-K filings from listed chemical operators, and ECHA substance evaluation documentation. Bottom-up capacity and demand modeling was cross-checked against top-down macroeconomic elasticity estimates.
Variance decomposition across purity grade, end-use application, regional production hub, and certification tier structured the analytical framework. CAGRs were derived from segmented growth rate reconciliation against aggregate market expansion. Key forecast inputs included ethylcyclohexane dehydrogenation yield improvement trajectories and REACH compliance cost pass-through elasticity for specialty-grade material.
Forecasts assume regulatory continuity in EPA volatile organic compound standards, ECHA REACH protocols, and China's MIIT GB standards; material policy shifts would require re-modeling. Specific risks include per- and polyfluoroalkyl substance regulatory spillover into cyclic olefin chemistries and unexpected catalyst deactivation rate increases. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Global Plastics Market
Bulk Chemicals
Global Hexane Market
Bulk Chemicals
Caustic Potash Market
Bulk Chemicals
Middle East Formaldehyde Market
Bulk Chemicals
Global Naphthalene Derivatives Market
Bulk Chemicals
Barium Sulphate Market
Bulk Chemicals
North America Calcium Carbonate Market
Bulk Chemicals
Ethyl Mercaptan Market
Bulk Chemicals
North America Acetic Acid Market
Bulk Chemicals
Magnesium Phosphate Market
Bulk Chemicals
Calcined Petcoke Market
Bulk Chemicals
Borates Market
Bulk Chemicals
Bulk Molding Compounds Market
Bulk Chemicals
Copper (II) Carbonate Basic Market
Bulk Chemicals
China Starch and Starch Derivatives Market
Bulk Chemicals
Propionic Acid Market