
 Inorganic Coagulants Market | 2026-2036
Inorganic Coagulants Market Size, Share, and Industry Trends Forecast 2026-2036
Inorganic Coagulants Market Analysis
Food-grade and low-residual specification tiers is reorganizing procurement priorities across municipal and industrial buyer segments. Kemira Oyj anchors Nordic and Baltic water treatment markets through integrated alumina refining and coagulant production. BASF SE leverages its global chemicals distribution network to sustain supply security for ferric chloride buyers in European industrial zones. SNF S.A.S. dominates polyaluminum chloride manufacturing scale, with backward integration into acrylic acid chemistry supporting cost positions.
Inorganic coagulants are mineral-based water treatment chemicals, primarily aluminum or iron salts, that neutralize and aggregate suspended particles through charge neutralization and sweep flocculation at dosages typically ranging from 5 to 50 mg per liter depending on raw water turbidity. Their primary commercial purpose is to clarify drinking water, treat municipal and industrial wastewater, and condition process streams in pulp manufacturing and oilfield operations. Polyaluminum chloride commands premium pricing in high-turbidity applications due to lower required dosing and reduced sludge generation compared to conventional aluminum sulfate. Ferric chloride leads in phosphorus removal segments where regulatory discharge limits are tightening. Liquid formulations capture the majority of volume in municipal contracts, though powder and granular forms retain niche positions in remote mining and construction site deployments.
EPA Safe Drinking Water Act standards and EU Drinking Water Directive thresholds on aluminum residuals are reshaping product qualification requirements across North American and European utilities. REACH registration obligations and GB standards in China add compliance layers that favor suppliers with established technical dossiers and local testing capabilities. India BIS certification for drinking water chemicals creates additional market access conditions for imported formulations. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate which coagulant chemistries will qualify for future tenders.
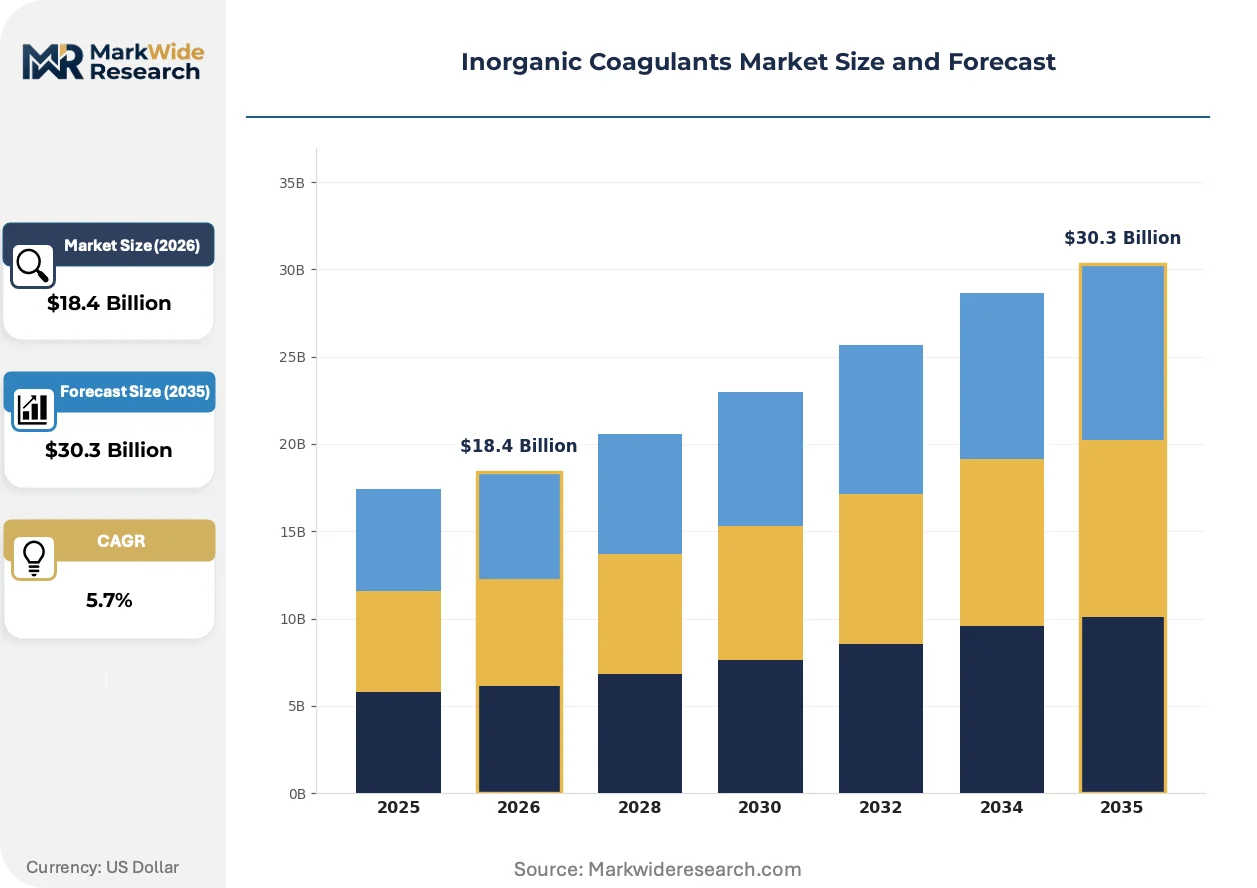
Market Dynamics
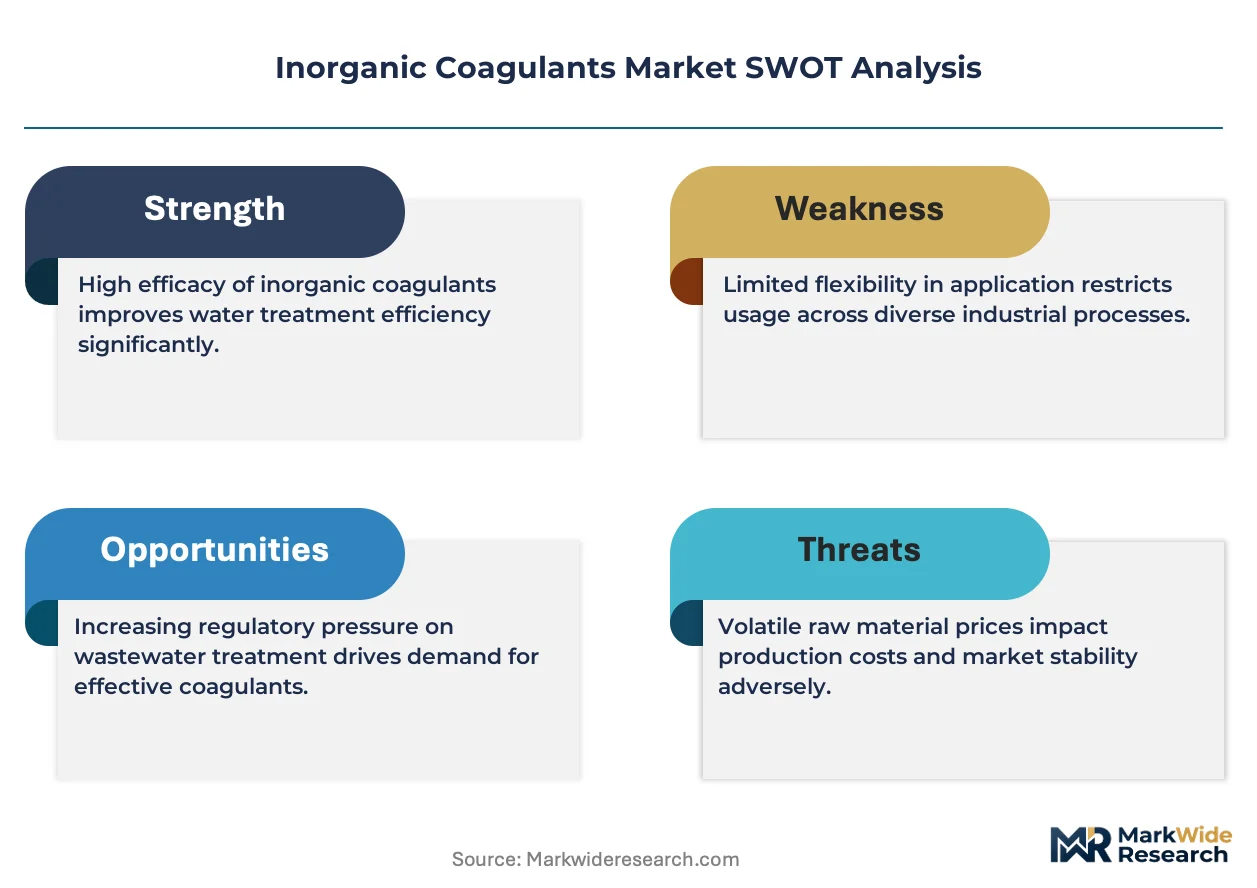
Reformulation pressure from residual aluminum limits is fragmenting procurement specifications across municipal water utilities, forcing suppliers to requalify products under divergent national standards while maintaining cost positions against ferric-based alternatives.
Growth Catalysts
- EU Drinking Water Directive thresholds:Tightening residual aluminum limits in European utilities are accelerating specification shifts toward ferric chloride and polyferric sulfate formulations.
- Urban wastewater infrastructure buildouts:Municipal utilities in China, India, and Indonesia are expanding treatment capacity to serve rapidly densifying metropolitan populations.
- Phosphorus removal mandates:Industrial discharge permits in pulp manufacturing and food processing are tightening total phosphorus limits, favoring ferric-based chemistries with superior precipitating performance.
Market Restraints
- Sulfuric acid feedstock volatility:Ferric chloride production depends on sulfuric acid availability, with pricing swings tied to smelter byproduct supply and fertilizer sector competition.
- Chinese supply concentration:Polyaluminum chloride manufacturing clusters in Shandong and Henan provinces create geographic risk exposure for international buyers.
- REACH registration burdens:European Chemicals Agency dossier requirements for aluminum and iron salt variants create fixed compliance costs that disadvantage smaller formulation suppliers.
Strategic Opportunities
- Indonesia municipal procurement expansion:Jakarta and Surabaya water authorities are tendering for bulk liquid coagulant supply contracts with 10-15 year durations.
- Remote mining site deployment:Powder and granular aluminum sulfate formats are penetrating fly-in-fly-out operations in Western Australia and Chilean Atacama where liquid logistics prove uneconomical.
- Food-grade certification tier:Drinking water chemical certifications under NSF/ANSI Standard 60 and BIS IS 15573 are creating premium pricing bands for qualified suppliers.
Industry Challenges
- Analytical chemist scarcity:Utilities and industrial buyers face recruitment gaps for jar testing and residual monitoring specialists capable of optimizing dose-response curves.
- Legacy dosing equipment incompatibility:Ferric chloride's corrosivity requires stainless steel or fiberglass storage and feed systems, complicating retrofits at aluminum sulfate-optimized facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inorganic Coagulants Market |
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $30.3 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum Sulfate, Ferric Chloride, Calcium Hydroxide, Polyaluminum Chloride Application: Water Treatment, Wastewater Treatment, Paper & Pulp Industry, Oil & Gas End User: Municipalities, Industrial Plants, Chemical Manufacturers, Mining Form: Liquid, Powder, Granular, Tablet |
| Companies Covered | Solenis LLC, Danaher Corporation, BASF SE, Suez SA, Evonik Industries AG, Kemira Oyj, SNF S.A.S., Nouryon, Ecolab Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inorganic Coagulants Market Emerging Trajectories
Product qualification protocols are diverging across jurisdictions while digital dosing controls and pre-polymerized chemistries reshape operational economics for municipal and industrial buyers.
Pre-hydrolyzed aluminum species in polyaluminum chloride formulations is fragmenting the conventional aluminum sulfate market by reducing required dosing rates and sludge volumes in high-turbidity source waters. Utilities on the Yangtze and Ganges basins are adopting these chemistries for seasonal monsoon loading. The technology is fragmenting competitive positions between commodity alum suppliers and integrated PAC manufacturers with captive bauxite refining.
EPA Safe Drinking Water Act secondary standards for aluminum are compelling US utilities to re-evaluate post-filtration residual targets, particularly in soft-water systems where natural pH elevates solubility. The regulatory pressure is driving pilot testing of ferric alternatives in New England and Pacific Northwest districts. Small-system operators in Maine and Oregon are consolidating purchasing through cooperative procurement vehicles to access technical support.
Specification compliance documentation is displacing price-only tender evaluation as the primary vendor selection criterion among European and North American water authorities. Third-party certification to NSF/ANSI 60, EN 1408, or BIS IS 15573 is becoming mandatory for contract eligibility. The shift is most pronounced in German and Dutch municipal markets where operator liability concerns dominate procurement committee deliberations.
Inorganic Coagulants Market Segmentation
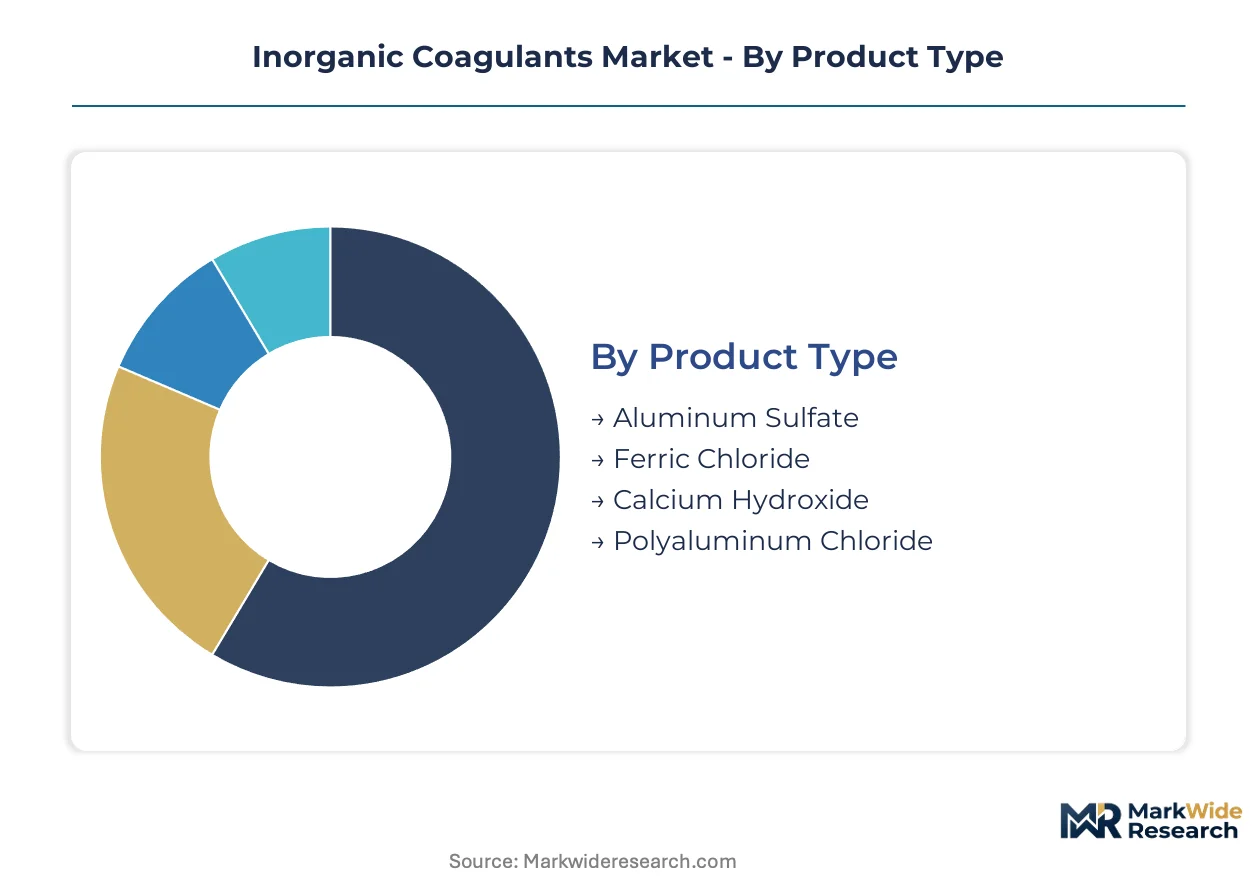
Segmentation in inorganic coagulants reveals how margin pools concentrate in pre-polymerized chemistries and liquid formulations. Procurement specifications diverge sharply between municipal utilities optimizing for residual compliance and industrial buyers prioritizing phosphorus removal performance.
Product Type:
Margin pools concentrate in polyaluminum chloride and ferric chloride where specification complexity limits commodity competition.
- Aluminum Sulfate:Conventional hydrated salt formulation with broad availability from bauxite-derived alumina refining. Municipal utilities in India and Indonesia deploy this chemistry for routine turbidity reduction in monsoon-season source waters where cost sensitivity dominates procurement.
- Ferric Chloride:Iron(III) chloride solution manufactured from steel pickling liquor or direct chlorination of iron ore. Industrial discharge permits in Germany and the Netherlands favor this chemistry for phosphorus precipitation where total phosphorus limits are tightening below 0.5 mg per liter.
- Calcium Hydroxide:Hydrated lime serving pH adjustment and co-precipitation roles in combined chemical-physical treatment trains.
- Polyaluminum Chloride:Pre-hydrolyzed aluminum polymer with higher charge density and lower dosing requirements than conventional alum.
Aluminum sulfate holds installed capacity across legacy municipal infrastructure. Polyaluminum chloride is rotating up the share rankings in high-turbidity applications.
Application:
Application segmentation tracks regulatory pressure points across drinking water safety and industrial discharge compliance.
- Water Treatment:Drinking water clarification targeting turbidity, color, and microbial reduction through charge neutralization and sweep flocculation. Utilities in China and the United States are requalifying chemistries under EPA Safe Drinking Water Act secondary standards and GB standards for aluminum residuals.
- Wastewater Treatment:Secondary and tertiary clarification with emphasis on phosphorus removal and sludge conditioning. Municipal plants in Jakarta and Surabaya are expanding capacity to serve densifying metropolitan populations with stricter effluent mandates.
- Paper & Pulp Industry:Process water clarification and retention chemistry in fiber recovery systems.
- Oil & Gas:Produced water treatment and drilling fluid conditioning in upstream operations.
Water treatment commands volume leadership. Wastewater treatment is climbing the fastest as phosphorus removal mandates proliferate.
End User:
End user segmentation reflects divergent procurement sophistication between municipal tender processes and industrial direct negotiations.
- Municipalities:Public water and wastewater utilities operating under regulatory frameworks including EPA Safe Drinking Water Act, EU Drinking Water Directive, and BIS IS 15573 certification requirements. Long-term supply contracts with 10-15 year durations are standard in Indonesian and Indian metropolitan markets.
- Industrial Plants:Food processing, pulp manufacturing, and chemical production facilities with site-specific discharge permits. Ferric chloride procurement dominates where total phosphorus limits are tightening in German and Dutch industrial zones.
- Chemical Manufacturers:Integrated producers consuming coagulants as process inputs or for on-site effluent treatment.
- Mining:Remote operations in Western Australia and Chilean Atacama deploying powder and granular formats where liquid logistics prove uneconomical.
Municipalities anchor procurement volume. Mining is gaining share fastest as remote site deployment expands.
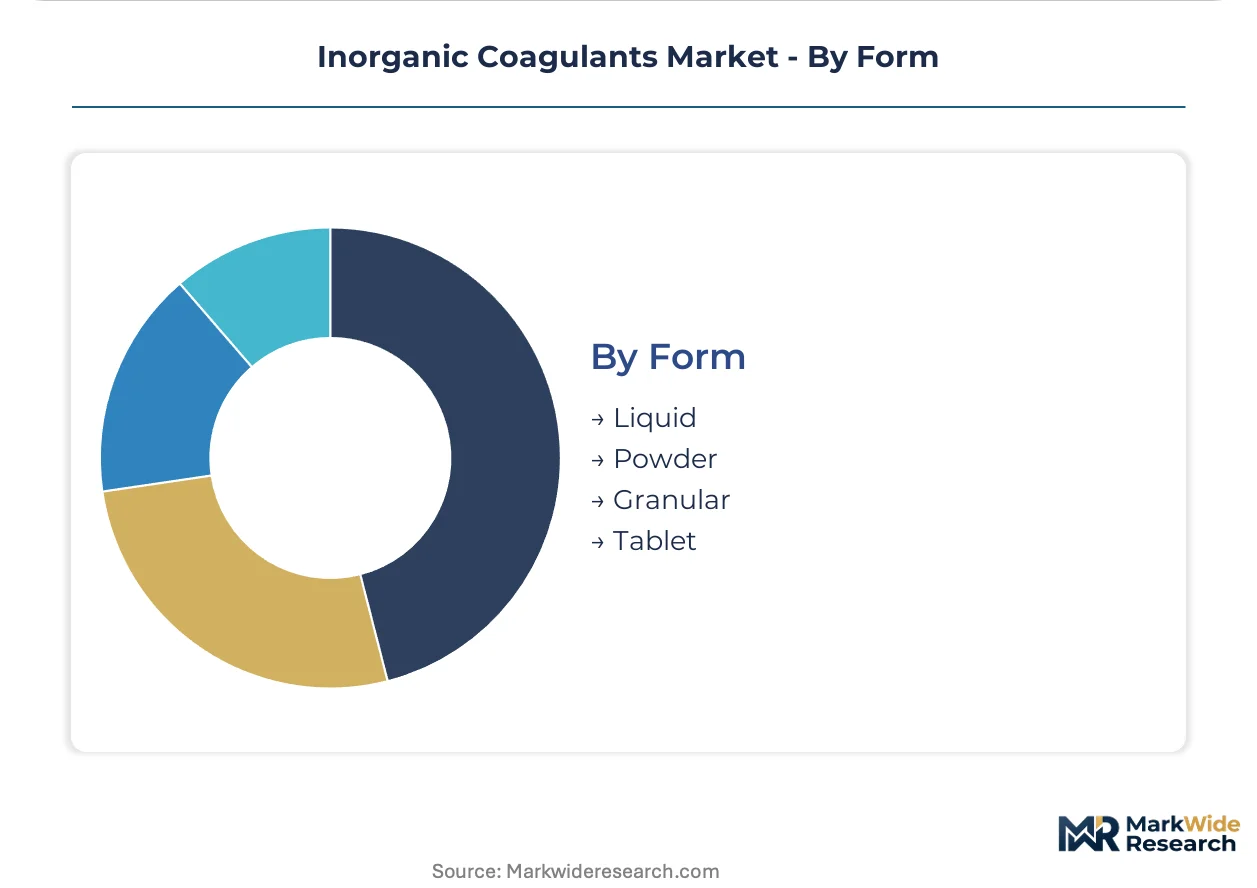
Form:
Form segmentation tracks logistics economics and dosing infrastructure compatibility across customer types.
- Liquid:Ready-to-feed solutions capturing majority volume in municipal contracts where automated dosing systems predominate. Corrosivity of ferric chloride variants requires stainless steel or fiberglass storage and feed infrastructure.
- Powder:Dehydrated aluminum sulfate and polyaluminum chloride for dry-feed systems at smaller utilities and remote industrial sites. Western Australian fly-in-fly-out mining operations favor this format for reduced transport cost.
- Granular:Coarse particulate forms with extended shelf stability for emergency stockpiles and intermittent use scenarios.
- Tablet:Compressed solid forms for small-scale or temporary treatment applications with minimal dosing equipment.
Liquid formulations dominate installed municipal infrastructure. Powder is rotating up the share rankings in remote mining deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese polyaluminum chloride manufacturers in Shandong and Henan provinces supply municipal utilities across Southeast Asia through bulk liquid shipment contracts. Export volumes concentrate on high-turbidity treatment applications where pre-hydrolyzed chemistries reduce dosing requirements.
China
Urban wastewater infrastructure buildouts in Shanghai and Guangzhou are accelerating procurement of polyaluminum chloride for seasonal monsoon loading. GB standards for drinking water chemicals enforce residual aluminum testing protocols that favor pre-polymerized formulations. Manufacturing clusters in Shandong province dominate export capacity to Indonesian and Vietnamese municipal tenders.
United States
EPA Safe Drinking Water Act secondary standards are compelling utilities in New England and the Pacific Northwest to pilot ferric chloride alternatives. Small-system operators in Maine and Oregon are consolidating purchasing through cooperative procurement vehicles. Soft-water systems in these regions face elevated aluminum solubility challenges that drive chemistry requalification.
Germany
Industrial discharge permits in the Ruhr industrial zone are tightening total phosphorus limits below 0.5 mg per liter, favoring ferric-based precipitation chemistries. REACH registration obligations for aluminum and iron salt variants create compliance barriers for non-European suppliers. Dutch and German municipal markets mandate third-party certification to EN 1408 for contract eligibility.
India
BIS IS 15573 certification requirements for drinking water chemicals are restructuring procurement specifications in Delhi and Mumbai metropolitan utilities. Monsoon-season turbidity spikes in the Ganges basin are rotating demand toward polyaluminum chloride for lower sludge generation. Long-term supply contracts with 10-15 year durations are standard in Jakarta-equivalent Indian tenders.
Indonesia
Jakarta and Surabaya water authorities are tendering for bulk liquid coagulant supply with decade-plus contract horizons. Urban densification is expanding wastewater treatment capacity to serve metropolitan populations exceeding 10 million. Local procurement is sourcing from Chinese and domestic blending facilities to meet BIS-equivalent quality specifications.
Inorganic Coagulants Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and certification depth, with publicly traded chemical conglomerates facing off against privately held water treatment specialists. The vendor base stratifies into three tiers: integrated multinationals with captive raw material positions, regional formulators with local testing capabilities, and commodity traders supplying spot markets. Strategic archetypes include backward-integrated alumina refiners, distribution-heavy chemical networks, and pre-polymerized chemistry specialists. Capacity expansion and qualification documentation are the dominant competitive moves as utilities shift from price-only to specification-weighted tender evaluation.
Within the integrated multinational tier, BASF SE and Kemira Oyj exemplify divergent geographic anchoring strategies. BASF leverages its Ludwigshafen-based chemicals distribution network to sustain supply security for ferric chloride buyers across European industrial zones. Kemira occupies a position in Nordic and Baltic markets through integrated alumina refining and coagulant production. SNF S.A.S. sits within the pre-polymerized chemistry specialist archetype, with manufacturing scale in polyaluminum chloride supported by upstream acrylic acid chemistry positions.
| Leading Market Players |
|---|
| Solenis LLC |
| Danaher Corporation |
| BASF SE |
| Suez SA |
| Evonik Industries AG |
| Kemira Oyj |
| SNF S.A.S. |
| Nouryon |
| Ecolab Inc. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts with 10-15 year durations lock in supply access and price visibility for Indonesian and Indian municipal utilities, insulating buyers from sulfuric acid feedstock volatility while committing suppliers to fixed-margin delivery schedules across monsoon-season demand spikes.
Pricing Analysis
Pre-polymerized aluminum species in polyaluminum chloride formulations command premium positioning over conventional aluminum sulfate, with price differentiation driven by NSF/ANSI Standard 60 certification tier and volume scale in municipal tenders. Cost compression in commodity alum grades is intensifying because Chinese manufacturing clusters are expanding export capacity into Southeast Asian spot markets. Industrial phosphorus removal buyers in Germany and the Netherlands show lowest price sensitivity due to regulatory compliance mandates, while Indian metropolitan utilities exhibit highest sensitivity during routine turbidity reduction procurement.
Supply Chain Analysis
Inventory cycles for liquid ferric chloride extend lead times during sulfuric acid supply constraints, with manufacturing gravity centering on Shandong and Henan provinces in China, the US Gulf Coast, and Nordic alumina refining corridors. Feedstock dependencies encompass bauxite-derived alumina, steel pickling liquor, and sulfuric acid from smelter byproduct streams. Single-source vulnerability concentrates in Chinese polyaluminum chloride export capacity, where geographic clustering creates disruption exposure for Indonesian and Vietnamese municipal buyers. Distribution feeds from regional blending facilities into bulk liquid tanker contracts for metropolitan utilities, with powder formats reaching remote mining sites through containerized logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specification fragmentation across EPA, EU Drinking Water Directive, and BIS IS 15573 certification regimes is carving out niche positions for qualified suppliers, creating entry points for specialists who can navigate divergent residual aluminum limits and qualification documentation requirements.
For Market Incumbents: Compound defensive positioning by securing captive bauxite refining capacity in Shandong province and accelerating EN 1408 certification dossiers for European municipal tenders. Ferric chloride corrosion compatibility threatens aluminum sulfate-optimized installed base, demanding stainless steel storage infrastructure investments to retain retrofit contracts. Backward integration into sulfuric acid supply hedges feedstock volatility exposure. For New Entrants and Emerging Players: BIS IS 15573 fast-track certification unlocks Delhi and Mumbai metropolitan procurement channels where incumbent documentation gaps persist. Remote mining deployment in Western Australia and Chilean Atacama represents the most penetrable white-space, with powder aluminum sulfate formats bypassing liquid logistics economics. Target fly-in-fly-out operations with granular packaging and emergency stockpile positioning. For Investors and Strategic Acquirers: Regional formulators with local testing capabilities in Jakarta and Surabaya municipal markets present acquisition targets with embedded 10-15 year contract visibility and Chinese supply relationships. Long-term viability hinges on qualification documentation depth rather than commodity scale. Monitor EPA Safe Drinking Water Act secondary standard enforcement intensity in New England soft-water systems as inflection indicator for ferric alternative adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alumina Refining | Captive bauxite supply secures polyaluminum chloride cost positions against Chinese export volatility. |
| NSF/ANSI Standard 60 Certification Investment | Third-party qualification unlocks premium municipal pricing tiers in US and European tenders. |
| Long-term Supply Agreement with Indonesian Utilities | Jakarta and Surabaya decade-plus contracts anchor volume visibility across monsoon demand cycles. |
| Capacity Expansion in Nordic Production Corridors | REACH-registered manufacturing serves German and Dutch phosphorus removal mandates with reduced compliance burden. |
| Joint Venture with Mining Logistics Specialists | Western Australian and Chilean powder distribution partnerships penetrate fly-in-fly-out remote site procurement. |
Methodological Framework
Cross-validation between regulatory filing analysis and procurement tender databases anchors the qualitative findings, combining primary interviews with municipal water utility procurement directors, industrial plant environmental compliance officers, coagulant manufacturing technical directors, and third-party certification laboratory managers with secondary validation through EPA enforcement records, ECHA REACH dossiers, BIS certification registries, and customs trade flow data. Bottom-up segment sizing triangulates against top-down macroeconomic indicators across the analysis window.
Sensitivity analysis around sulfuric acid price volatility and monsoon-season demand spikes informs the analytical framework, with segmentation dimensions encompassing product chemistry tier, application end-use, municipal versus industrial buyer archetype, liquid versus powder format, and regional regulatory cluster. CAGRs derive from regression against historical procurement volumes and infrastructure investment pipelines, incorporating jar testing adoption rates and residual monitoring equipment deployment as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained EPA and EU Drinking Water Directive enforcement intensity and continued Chinese export capacity expansion; material deviation in regulatory stringency or trade policy would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Hydrogen Sulphide Market
Industrial Chemicals
Global Sponge Applicator Market
Industrial Chemicals
Global N-MDEA Market
Industrial Chemicals
Profenofos Market
Industrial Chemicals
Oilfield Biocides and Bio-Solvents Market
Industrial Chemicals
Ferrocene Market
Industrial Chemicals
Plastic Contract Manufacturing Market
Industrial Chemicals
N-Ethyl-2-Pyrrolidone Market
Industrial Chemicals
Global Electronic Grade Sulfuric Acid Market
Industrial Chemicals
Global Aerosol Propellant Market
Industrial Chemicals
Europe Modified Bitumen Market
Industrial Chemicals
Methylene Diphenyl Di-Isocyanate (MDI) Market
Industrial Chemicals
Pentane Plus Market
Industrial Chemicals
Nitrous Oxide Market
Industrial Chemicals
Chlorine Trifluoride Market
Industrial Chemicals
Bleaching Clay Market