
 Aluminum Pouches Market | 2026-2036
Aluminum Pouches Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Pouches Market Outlook
E-commerce fulfillment channels is tilting toward lightweight, damage-resistant formats that cut shipping costs and extend shelf life. Amcor plc leverages its global converting footprint to supply major CPG brands with high-barrier laminates. Mondi Group sustains competitive intensity through integrated pulp-to-pouch operations across European and Asian mills. ProAmpac specializes in custom printed structures for direct-to-consumer subscription food boxes.
Aluminum pouches are multi-layer flexible packages incorporating aluminum foil barrier layers, typically laminated with polyethylene, polyester, or polyamide films to achieve oxygen transmission rates below 0.1 cc/m²/day and moisture vapor transmission rates under 0.01 g/m²/day, engineered to protect oxygen-sensitive and moisture-critical contents across ambient distribution chains. Stand-up pouches occupy the largest volume position due to their retail shelf presence and dispenser functionality in grains, pet food, and ready-to-eat meals. Flat pouches dominate pharmaceutical sachet applications where precise unit-dosing and minimal material waste govern procurement decisions. Zip lock closures lead in consumer convenience segments, though heat sealed formats retain cost advantages in single-serve commodity packs.
FDA food-contact substance notifications and EU REACH compliance on heavy metal migration limits shape raw material sourcing and adhesive selection across the supply base. EFSA evaluates aluminum dietary exposure thresholds that indirectly pressure pack weight reduction and foil gauge optimization. Stakeholders must monitor evolving extended producer responsibility frameworks in California and the EU, as these programs will recast cost structures for multilayer flexible packaging recovery and recycling infrastructure investment.
Market Dynamics
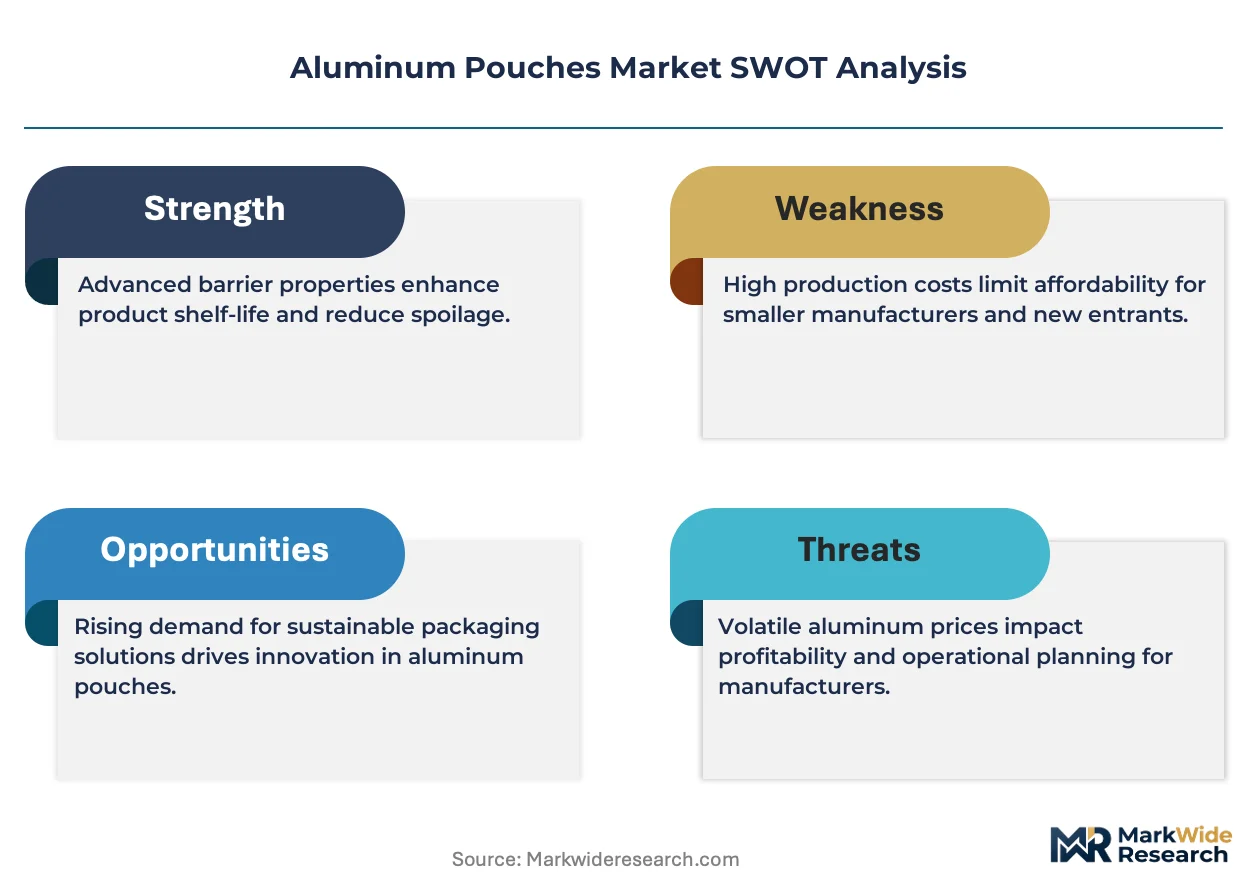
Extended producer responsibility frameworks in California and the EU are recasting cost structures for multilayer flexible packaging recovery, forcing converters to redesign laminate structures for recyclability while maintaining barrier performance.
Growth Catalysts
- REACH heavy metal migration limits:EU regulations on aluminum dietary exposure thresholds pressure pack weight reduction and foil gauge optimization, accelerating demand for high-performance thin-gauge laminates.
- China processed food consumption:Domestic demand for shelf-stable grains, pet food, and ready-to-eat meals concentrates procurement of stand-up pouch formats with extended ambient distribution capability.
- E-commerce fulfillment optimization:Lightweight, damage-resistant formats cut shipping costs and extend shelf life across direct-to-consumer subscription channels.
Market Restraints
- Aluminum foil supply concentration:Primary foil rolling capacity concentrates among Chinese and European metal processors, creating input cost volatility and lead time uncertainty for converters.
- Multilayer laminate incompatibility:Current mechanical recycling infrastructure cannot separate aluminum, polyethylene, polyester, and polyamide layers, limiting end-of-life options and increasing disposal costs.
- Adhesive regulatory friction:FDA food-contact substance notifications and EU REACH compliance requirements on solvent-based laminating adhesives extend qualification timelines for new material combinations.
Strategic Opportunities
- India processed food expansion:FSSAI regulations on packaged food safety and rising urban middle-class consumption create underpenetrated demand for retort-compatible aluminum laminates.
- Pharmaceutical unit-dosing:Precise sachet applications for OTC medications and nutraceuticals favor flat pouch formats with minimal material waste and tamper-evident features.
- EU Green Deal packaging mandates:Recyclability targets and extended producer responsibility schemes incentivize investment in mono-material or paper-aluminum hybrid structures.
Industry Challenges
- Barrier engineer talent scarcity:Specialized expertise in multilayer coextrusion, adhesive lamination, and oxygen transmission rate optimization remains concentrated among senior technical staff at established converters.
- Recycling infrastructure capex:Chemical depolymerization and advanced sorting facilities for flexible packaging require substantial capital commitment with uncertain payback timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Pouches Market |
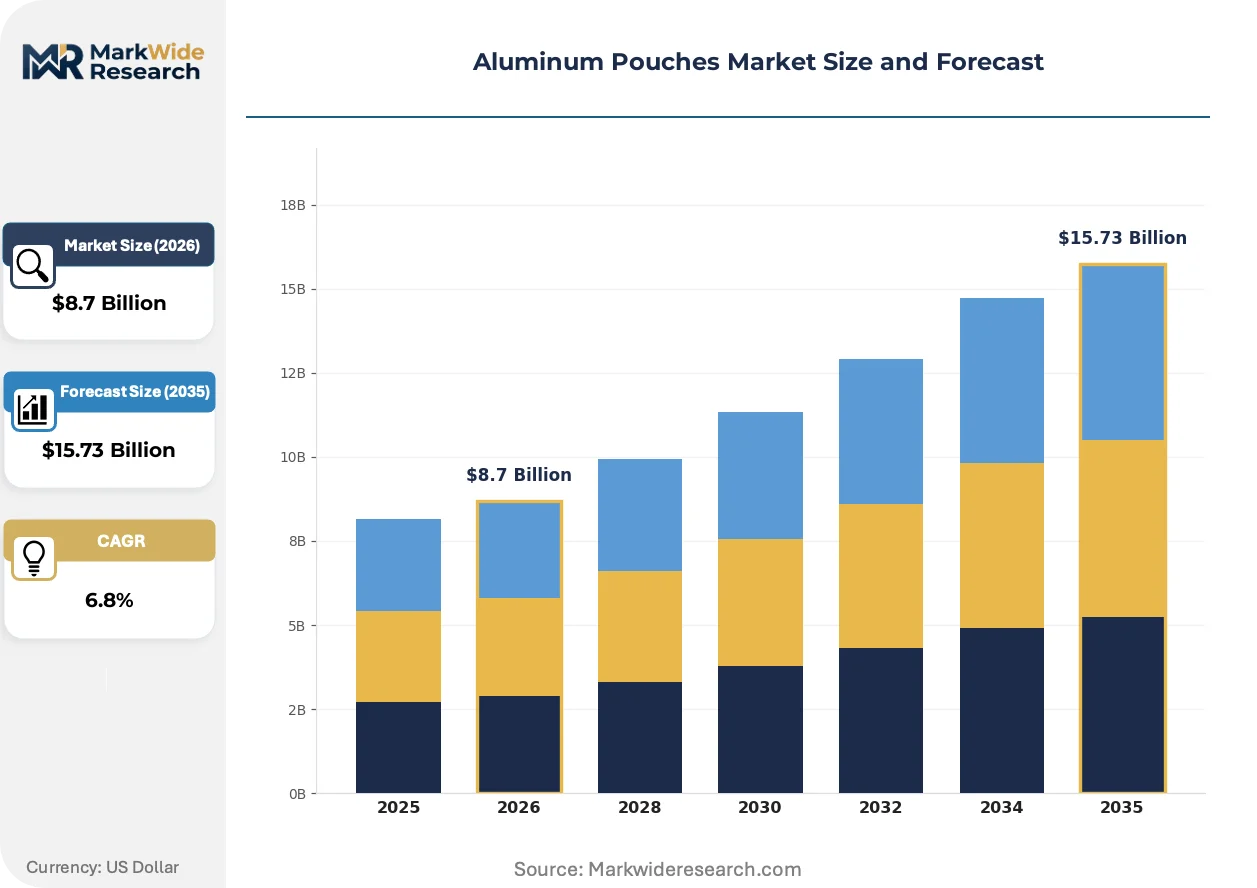
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Stand-Up Pouches, Flat Pouches, Zip Pouches, Slide Seal Pouches Application: Food Packaging, Beverage Packaging, Pharmaceutical Packaging, Personal Care Products Closure Type: Zip Lock, Heat Sealed, Tear Notch, Easy Open End User: Manufacturers, Retailers, Distributors, E-Commerce |
| Companies Covered | Amcor plc, Mondi Group, Berry Global Group, Constantia Flexibles Group GmbH, Huhtamaki Oyj, Sonoco Products Company, Sealed Air Corporation, ProAmpac, SPS Pouches, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Pouches Market Strategic Shifts
Digital printing and smart packaging integration are compressing minimum order quantities and enabling batch-level traceability, while regulatory pressure on recyclability forces material science innovation across the laminate stack.
Digital printing technology is digitizing artwork changeover and variable data insertion for aluminum pouch converters. Food manufacturers adopting direct-to-consumer channels now specify run lengths below 5,000 units with personalized graphics. This capability is digitizing procurement patterns and compressing the traditional economies of scale that favored rotogravure cylinder investments.
EU REACH restrictions on per- and polyfluoroalkyl substances in food-contact materials are eliminating fluoropolymer coatings from high-barrier laminates. Converters must qualify silicone oxide or aluminum oxide plasma-deposited alternatives with equivalent moisture vapor transmission performance. Retort pouch applications for ready-to-eat meals face the steepest reformulation timelines and validation requirements.
Subscription box procurement models are consolidating buying power among direct-to-consumer brands and displacing traditional retail-driven volume commitments. These buyers prioritize custom printed structures with zip lock closures and matte finishes over commodity specifications. North American pet food and specialty nutrition verticals exhibit the most pronounced channel migration toward curated unboxing experiences.
Aluminum Pouches Market Segmentation
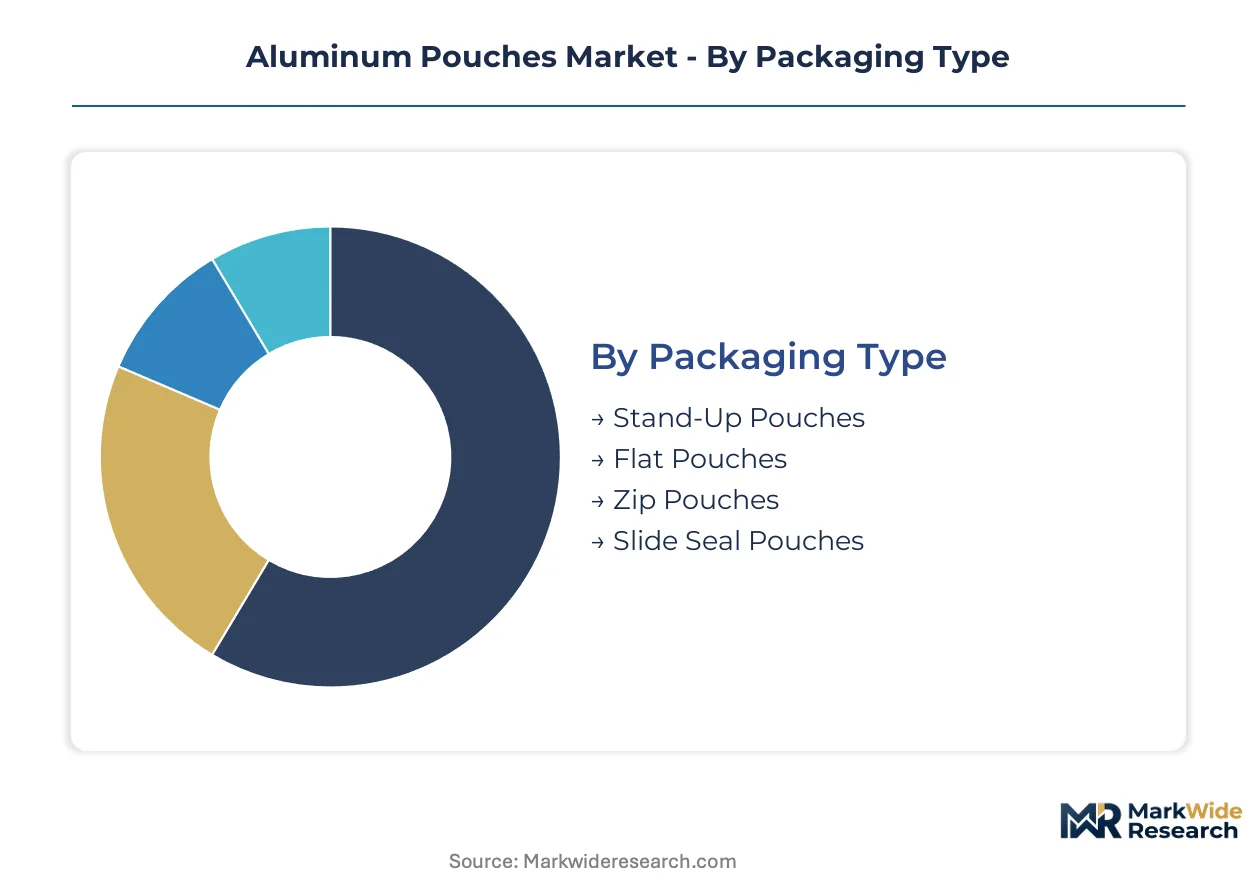
Aluminum pouch procurement patterns diverge sharply across end-use requirements, with barrier specifications, closure mechanics, and channel economics driving format selection. Converters must align laminate engineering with precise oxygen transmission and moisture vapor targets while navigating regulatory constraints across food-contact and pharmaceutical applications.
Packaging Type:
Use-case spectrum spans retail shelf presence, unit-dose precision, resealability demands, and controlled dispensing across ambient distribution chains.
- Stand-Up Pouches:Three-dimensional structures with gusseted bases enable vertical retail display and gravity-fed dispensing. Grains, pet food, and ready-to-eat meals in China concentrate procurement here, driven by shelf-stable format requirements and ambient distribution capability.
- Flat Pouches:Two-dimensional laminates minimize material waste and enable precise unit-dosing. Pharmaceutical sachets for OTC medications and nutraceuticals dominate demand, governed by tamper-evident requirements and minimal pack weight optimization under EFSA aluminum exposure thresholds.
- Zip Pouches:Integrated interlocking tracks provide consumer resealability without heat-sealing equipment. Specialty nutrition and direct-to-consumer subscription channels specify these for curated unboxing experiences.
- Slide Seal Pouches:Slider mechanisms across pouch mouths offer repeated access with one-handed operation. Premium pet food and personal care applications favor this closure for perceived quality differentiation.
The dominant share belongs to Stand-Up Pouches, while Zip Pouches are closing the gap fastest.
Application:
Cost tier segmentation separates commodity volume plays from premium barrier investments and regulated pharmaceutical qualifications.
- Food Packaging:Retort-compatible laminates with aluminum foil barriers protect oxygen-sensitive contents across grains, snacks, and ready-to-eat meals. Processed food consumption expansion in India under FSSAI safety regulations drives retort pouch demand.
- Beverage Packaging:Spouted and fitmented pouches replace rigid containers for concentrates and aseptic liquids. Extended shelf life requirements in ambient distribution favor high-barrier foil laminates over metallized alternatives.
- Pharmaceutical Packaging:Unit-dose sachets and strip packs demand precise barrier control for moisture-critical APIs. FDA food-contact substance notifications and EU REACH compliance govern adhesive and coating selection.
- Personal Care Products:Samples, masks, and single-use treatments prioritize shelf appeal and portability. Matte finishes and custom printed structures align with direct-to-consumer brand positioning.
Food Packaging commands volume leadership, though Pharmaceutical Packaging is expanding most quickly on regulatory compliance investments.
Closure Type:
Customer type segmentation distinguishes convenience-driven consumer specifications from cost-optimized industrial procurement.
- Zip Lock:Interlocking plastic tracks enable repeated reseal without tools. Consumer convenience segments in North American pet food and specialty nutrition specify these for subscription box formats.
- Heat Sealed:Thermal bonding of laminate layers provides tamper evidence at lowest unit cost. Single-serve commodity packs retain this format for cost advantages in high-volume production.
- Tear Notch:Laser-scored or die-cut initiation points enable clean opening without scissors. Portion-controlled food and pharmaceutical applications favor this for controlled access.
- Easy Open:Peelable seal technologies separate along engineered interfaces. Aging demographics and on-the-go consumption drive specification for reduced dexterity requirements.
Heat Sealed retains the dominant share on commodity volume, while Zip Lock is gaining share fastest on e-commerce channel migration.
End User:
Supply concentration varies across integrated brand owners, fragmented retail networks, layered distribution systems, and platform-mediated direct channels.
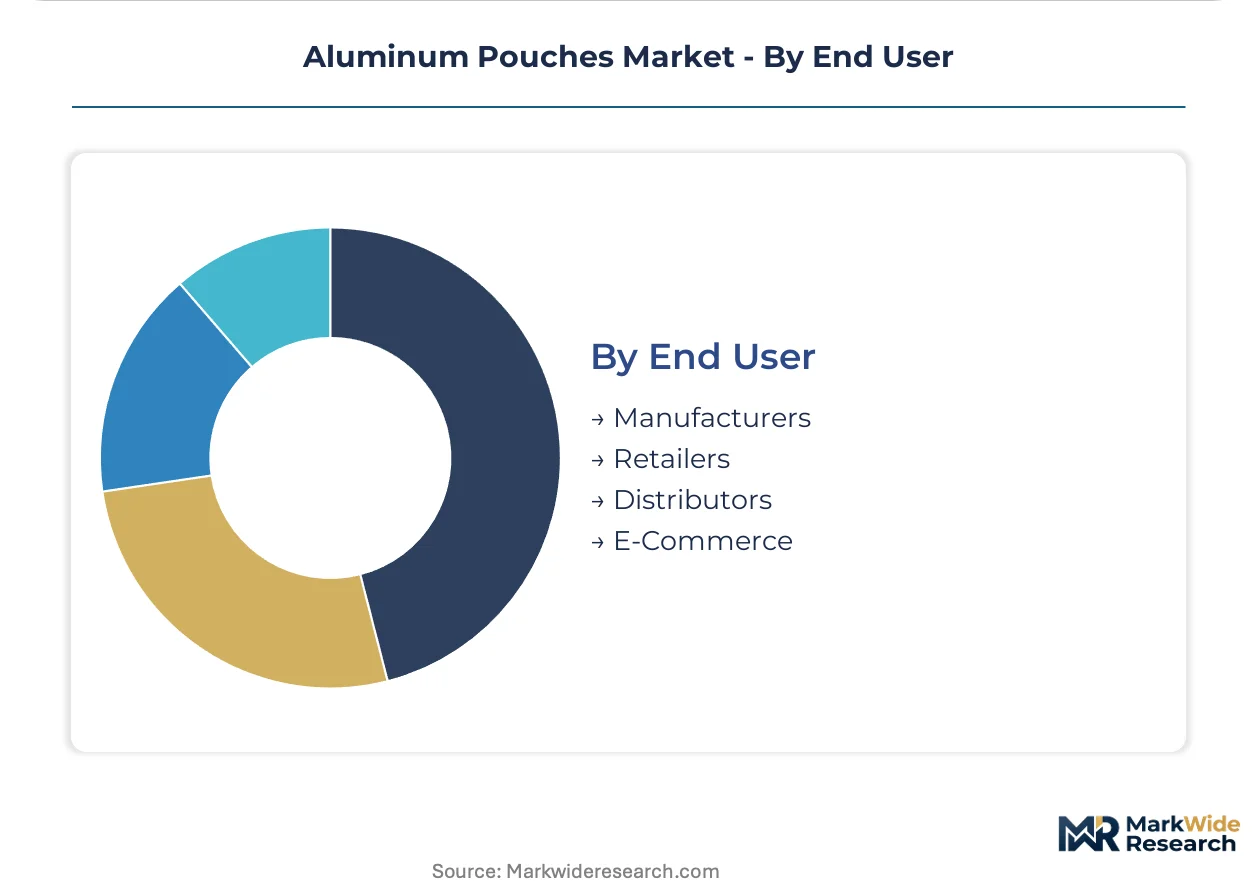
- Manufacturers:CPG brand owners and co-packers specify laminate structures at production scale. REACH and FDA compliance requirements shape raw material sourcing and adhesive qualification timelines.
- Retailers:Private label programs and shelf-ready packaging specifications drive format standardization. Extended producer responsibility frameworks in California and the EU recast cost structures for private label procurement.
- Distributors:Intermediate inventory holders influence pack sizes and palletization for logistics efficiency. Regional warehouse networks prioritize damage resistance in mixed-load distribution.
- E-Commerce:Platform sellers and direct-to-consumer brands compress order quantities and demand variable data printing. Digital printing technology enables batch-level traceability and personalized graphics below 5,000-unit runs.
Manufacturers hold the dominant share through integrated specification control, while E-Commerce is climbing the fastest on channel shift acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Chinese converters serving domestic processed food brands, while European suppliers absorb compliance premiums under REACH and extended producer responsibility frameworks without full cost pass-through.
China
Domestic consumption of shelf-stable grains and ready-to-eat meals drives stand-up pouch procurement at scale. SAMR food-contact regulations and GB standards govern laminate safety compliance. Yangtze River Delta converters in Zhejiang and Jiangsu provinces operate integrated foil-to-pouch production lines serving pan-Asian distribution networks.
United States
E-commerce subscription channels and direct-to-consumer pet food brands specify custom-printed zip-lock formats below 5,000-unit minimums. FDA food-contact substance notifications extend adhesive qualification timelines for new laminate structures. Chicago and Dallas-Fort Worth logistics hubs concentrate pouch converting capacity serving North American fulfillment networks.
Germany
EU REACH heavy metal migration limits and EFSA aluminum exposure thresholds pressure foil gauge reduction in pharmaceutical and food applications. ECHA compliance requirements reshape raw material sourcing across the laminate stack. Baden-Württemberg and North Rhine-Westphalia host integrated pulp-to-pouch operations with captive adhesive compounding facilities.
India
FSSAI packaged food safety regulations and rising urban middle-class consumption create demand for retort-compatible aluminum laminates. Processed food expansion in Maharashtra and Gujarat concentrates procurement of high-barrier formats. Mumbai-Pune and Ahmedabad-Vadodara industrial corridors attract converter investments targeting domestic and export markets.
Japan
Aging demographics and single-person households drive specification for easy-open peelable seals and portion-controlled formats. METI circular economy guidelines and plastic resource recycling laws incentivize mono-material structure development. Kansai region converters in Osaka and Kyoto prefectures specialize in precision laminates for pharmaceutical unit-dosing applications.
Aluminum Pouches Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in foil rolling, adhesive formulation, and precision coating. The supplier base organizes into three tiers: multinational converters with global converting footprints, regional specialists with integrated material operations, and niche players focused on digital printing or custom closure engineering. Capacity expansion and portfolio diversification toward recyclable mono-material structures represent the dominant competitive moves as extended producer responsibility frameworks recast cost structures.
Among integrated multinational converters, Amcor plc, Mondi Group, and ProAmpac exemplify distinct strategic positioning archetypes. Amcor occupies the global platform tier with broad geographic coverage across major CPG supply relationships. Mondi represents the vertically integrated model with captive pulp and paper operations feeding flexible packaging lines. ProAmpac sits within the specialty converter segment, emphasizing custom printed structures and shorter run lengths for direct-to-consumer channels. Each anchors a different value-capture point in the laminate supply chain without overlapping strategic territory.
| Leading Market Players |
|---|
| Amcor plc |
| Mondi Group |
| Berry Global Group |
| Constantia Flexibles Group GmbH |
| Huhtamaki Oyj |
| Sonoco Products Company |
| Sealed Air Corporation |
| ProAmpac |
| SPS Pouches |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Chinese foil rolling mills is compressing input costs for converters while simultaneously eroding pricing power across standard-grade laminates, forcing suppliers to differentiate through configured-to-order structures or absorb margin erosion in commodity segments.
Pricing Analysis
The customization-premium spread separates configured-to-order pricing for direct-to-consumer subscription formats from standard heat-sealed commodity specifications. Three-tier pricing structure across premium, standard, and economy levels stratifies by barrier performance certification and volume commitment scale. Pricing pressure stems from REACH compliance costs that converters cannot fully pass through to private-label buyers. E-commerce channel procurement exhibits the lowest price sensitivity due to unboxing experience requirements, while industrial co-packers drive aggressive cost compression in high-volume retort applications.
Supply Chain Analysis
Contract-manufacturing concentration clusters among Yangtze River Delta converters in Zhejiang and Jiangsu provinces, with captive foil-to-pouch production lines serving pan-Asian distribution networks. Primary aluminum foil supply draws from Chinese and European metal processors, while adhesive formulation relies on specialized laminating chemistry from Germany and Japan. Single-source vulnerability concentrates in thin-gauge foil rolling capacity below 6 micrometers. Distribution runs through regional logistics hubs in Chicago, Dallas-Fort Worth, and Mumbai-Pune industrial corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: FDA food-contact substance notifications and EU REACH compliance create multi-year qualification timelines that lock in incumbent converter relationships.
For Market Incumbents: Harden barrier engineering capabilities through captive adhesive compounding investments in Baden-Württemberg and North Rhine-Westphalia to defend against emerging mono-material specialists. Deepen technical staff retention programs addressing the concentrated scarcity of multilayer coextrusion expertise among senior personnel. For New Entrants and Emerging Players: Establish a beachhead in India's retort-compatible aluminum laminates segment where FSSAI regulations are recasting procurement standards and domestic converter capacity lags processed food expansion. Pursue digital printing integration to capture direct-to-consumer subscription box volumes below 5,000-unit minimums. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated specialists with captive pulp-to-pouch operations and established REACH compliance infrastructure rather than pure-play converters exposed to raw material volatility. Monitor ECHA regulatory bulletins on per- and polyfluoroalkyl substance restrictions as the primary inflection signal for laminate reformulation capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Structure Development | EU Green Deal recyclability targets force aluminum-polyethylene hybrid qualification timelines. |
| Digital Printing Capability Investment | Variable data insertion below 5,000-unit runs captures direct-to-consumer subscription procurement. |
| Captive Adhesive Compounding | In-house solvent-free laminating chemistry shortens FDA notification timelines for new structures. |
| Thin-Gauge Foil Optimization | EFSA aluminum exposure thresholds drive sub-6-micrometer barrier layer engineering. |
| Extended Producer Responsibility Prepositioning | California and EU frameworks recast cost structures for multilayer flexible packaging recovery. |
Study Parameters
Cross-validation between primary interviews with flexible packaging procurement managers, adhesive formulation chemists, and regulatory compliance officers and secondary validation through FDA food-contact substance notifications, ECHA regulatory bulletins, and customs trade data anchors the qualitative findings. Bottom-up triangulation across converter capacity disclosures and top-down reconciliation against processed food production statistics ensures segmentation integrity.
Calibration against historical laminate pricing indices and capacity utilization rates across Chinese and European foil rolling mills shapes the analytical framework across the analysis window. Segmentation dimensions modeled include packaging type, closure mechanism, end-use application, and regional regulatory cluster. CAGRs derive from elasticity-adjusted demand projections incorporating e-commerce channel penetration curves and REACH compliance cost absorption rates.
Sensitivities concentrate around EFSA aluminum dietary exposure threshold revisions and extended producer responsibility framework implementation timelines in California and the EU. Forecasts reflect assumptions on mechanical recycling infrastructure deployment and chemical depolymerization facility investment cadence. Quarterly review of ECHA regulatory bulletins and SAMR food-contact standard updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Contour Pouches Market
Pouch
Flexible Plastic Drinking Pouch Market
Pouch
Pouch Equipment Market
Pouch
Digital Printed Pouch Market
Pouch
Telemetry Pouch Market
Pouch
Four Side Flat Pouch Market
Pouch
Brazil Pouch Packaging Market
Pouch
Heat Seal Pouch Market
Pouch
Horizontal Premade Pouch Packing Machine Market
Pouch
Liquid Pouch Market
Pouch
India Pouch Packaging Market
Pouch
Fin Seal Pouches Market
Pouch
Retort Pouch Packaging Market
Pouch
Aluminum-Free Food Pouch Market
Pouch
Nigeria Pouch Packaging Market
Pouch
North America Stand-Up Pouch Packaging Market