
 Contour Pouches Market | 2026-2036
Contour Pouches Market Size, Share, and Industry Trends Forecast 2026-2036
Contour Pouches Market Outlook
A capital-intensity divergence between large-scale laminate converters and boutique specialty printers is bifurcating competitive dynamics in flexible packaging. Glenroy Inc sustains significant extrusion and printing capacity across North American facilities, positioning it for high-volume food contracts. Bischof + Klein SE & Co. KG anchors European pharmaceutical and medical pouch demand through certified barrier laminates. Omniplast Private Limited competes on cost-engineered structures for emerging market personal care brands.
Contour pouches are three-dimensional flexible packages formed from multilayer films—typically combining polyethylene, polyethylene terephthalate, and aluminum foil layers totaling 80–200 microns—through heat-sealing and die-cutting processes that create curved side-seal geometries enabling upright shelf display and efficient palletization. Stand-up pouches occupy the largest volume share as retail brands replace glass jars and metal cans for sauces, detergents, and pet food, though spouted pouches generate premium margin pools in toddler nutrition and liquid soap segments where dispensing convenience commands price premiums. Composite materials lead value contribution due to their oxygen and moisture barrier performance, while paper-based alternatives face technical limitations in high-humidity supply chains despite sustainability marketing appeal.
FDA food-contact notification requirements and EU REACH compliance on adhesive and ink constituents shape material selection and supplier qualification timelines for any pouch entering regulated markets. EFSA migration testing protocols for multilayer structures add certification costs that favor established converters with in-house analytical laboratories over smaller competitors. Stakeholders must monitor evolving extended producer responsibility frameworks in California and the EU, as pending packaging fee structures based on recyclability assessments could reallocate margin across material categories and favor mechanical recycling-compatible mono-material designs over current composite standards.
Market Dynamics
Migration limits under FDA food-contact notifications and EFSA multilayer testing protocols are forcing converters toward certified cleanroom production and in-house analytical capabilities, raising barriers for smaller competitors while rewarding established laminate specialists.
Growth Catalysts
- EFSA Migration Testing Mandates:Stricter certification requirements for multilayer plastic films favor converters with captive laboratory infrastructure, consolidating contract awards toward qualified suppliers in Germany and France.
- Pet Food Segment Conversion:Premium pet nutrition brands across North America are abandoning metal cans for high-barrier stand-up pouches with resealable closures, driving pouch volume expansion.
- Aluminum Foil Composite Demand:Oxygen and moisture barrier performance requirements in pharmaceutical packaging sustain value premiums for aluminum-containing laminate structures despite recyclability concerns.
Market Restraints
- Resin Price Volatility:Polyethylene and polyethylene terephthalate feedstock costs fluctuate with crude oil and natural gas benchmarks, compressing converter margins on fixed-price annual contracts.
- Mechanical Recycling Incompatibility:Current multilayer composite designs incorporating aluminum foil and adhesive laminates face rejection from mainstream mechanical recycling streams, exposing brands to pending extended producer responsibility fees.
- Cleanroom Certification Costs:Pharmaceutical and medical pouch production requires ISO 14644 compliant environments, requiring seven-figure capital deployment that excludes mid-scale converters from premium segments.
Strategic Opportunities
- Mono-Material Design Transition:California and EU extended producer responsibility frameworks based on recyclability assessments create first-mover advantage for converters developing all-polyethylene barrier structures compatible with existing recycling infrastructure.
- Spouted Pouch Expansion:Toddler nutrition and liquid soap segments command price premiums for dispensing convenience, offering margin pools unavailable in standard stand-up formats.
- Ready-to-Eat Meal Penetration:European foodservice and retail brands are accelerating flexible packaging conversion for shelf-stable prepared meals, displacing rigid trays and lidding films.
Industry Challenges
- Adhesive and Ink Compliance Timelines:EU REACH substance restrictions on adhesive constituents and ink chemistries extend supplier qualification cycles, delaying new product launches by 12-18 months.
- Barrier Film Talent Scarcity:Specialized expertise in coextrusion die design and multilayer lamination process control concentrates among aging engineering cohorts, constraining capacity expansion at independent converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contour Pouches Market |
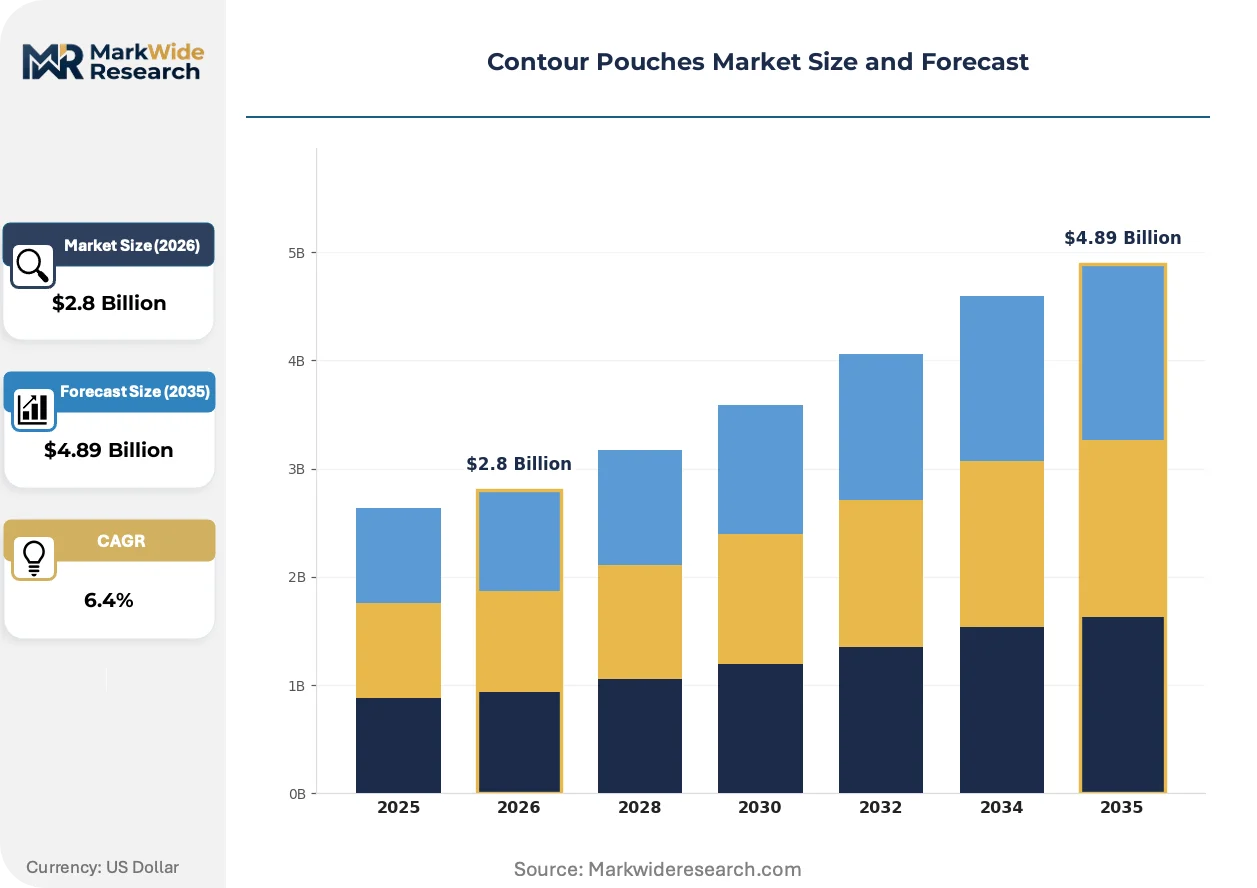
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Flat Pouches, Spouted Pouches, Zipper Pouches Material: Plastic, Paper, Aluminum Foil, Composites End User: Food & Beverage, Personal Care, Healthcare, Industrial Size: Small, Medium, Large, Extra Large |
| Companies Covered | Glenroy Inc, Swiss Pac Pvt. Ltd, PAC Worldwide, Polynova Industries Inc, Ampac Holdings, Bischof + Klein SE & Co. KG, PouchTec Industries LLC, Omniplast Private Limited, Smart Pouches, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contour Pouches Market Strategic Shifts
Digital printing and mono-material barrier development are converging with regulatory pressure on recyclability, reshaping converter investment priorities and brand specification criteria across food, personal care, and pharmaceutical end-uses.
Digital flexographic and inkjet printing systems are supplanting conventional rotogravure for short-run customized pouch production. Mid-size food brands in the United States and United Kingdom are adopting digitally printed SKUs for seasonal and regional product variants, compressing minimum order quantities from 50,000 units toward 5,000 units and enabling mass customization without cylinder inventory costs.
California's extended producer responsibility legislation and the EU Packaging and Packaging Waste Regulation are mandating recyclability assessments and fee structures tied to design for recycling scores. Brand owners are responding by specifying mono-material polyethylene or polypropylene structures with enhanced barrier coatings, displacing aluminum foil laminates in non-oxygen-sensitive applications and reallocating converter R&D spending toward coating technology.
Retailers are consolidating flexible packaging procurement through direct converter relationships, bypassing traditional broker and distributor channels. Mass-market grocery chains in Germany and France are negotiating direct supply agreements with certified converters, compressing intermediary margins and requiring converters to assume inventory and logistics responsibilities previously managed by distributors.
Contour Pouches Market Segmentation
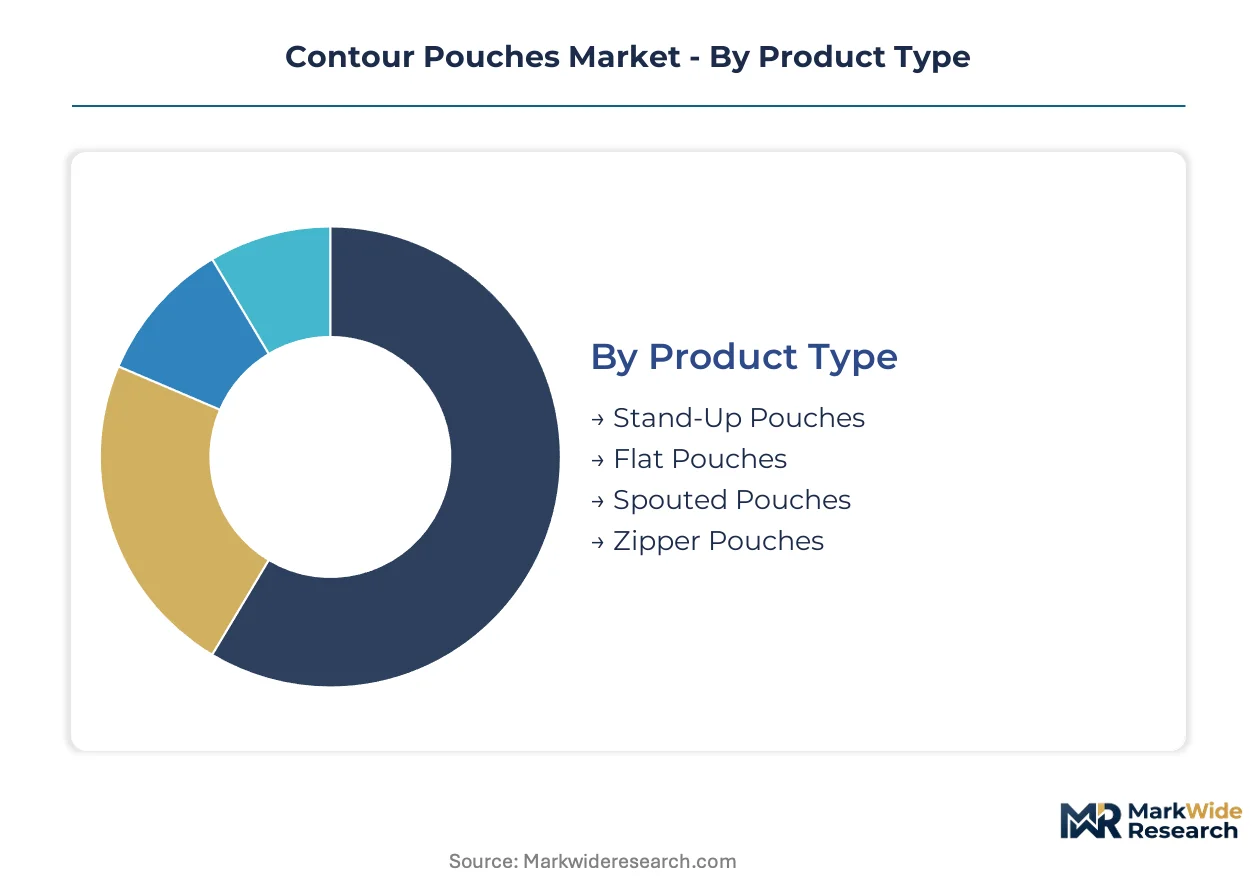
Contour pouch specifications diverge sharply across end-use requirements, with FDA and EFSA migration limits forcing material selections that trade barrier performance against recyclability compliance. Brand procurement teams segment supplier qualification by cleanroom certification status and composite structure capabilities, not merely unit economics.
Product Type:
EFSA multilayer testing protocols and FDA food-contact notification requirements create divergent qualification timelines across pouch geometries, with pharmaceutical-facing formats demanding ISO 14644 certified production environments.
- Stand-Up Pouches:Three-dimensional structures with curved side-seal geometries enabling upright shelf display, formed from 80-200 micron multilayer films combining polyethylene, polyethylene terephthalate, and aluminum foil. German and French retail chains specify these for sauces and detergents displacing rigid containers, though EFSA migration certification adds 6-9 months to supplier onboarding.
- Spouted Pouches:Integrated dispensing fitments welded to laminated film bodies, requiring precision heat-sealing around spout flange interfaces. Toddler nutrition and liquid soap brands in the United States command price premiums for this convenience format, with California's extended producer responsibility framework now assessing recyclability of the multi-component assembly.
- Flat Pouches:Two-dimensional sealed envelopes without structural support, competing primarily on unit cost for single-serve condiments and sample sachets.
- Zipper Pouches:Reclosable interlocking profiles laminated into pouch headers, specified for pet food and ready-to-eat meals requiring repeated access.
Stand-Up Pouches handle the majority of throughput; Spouted Pouches are gaining share fastest on premium positioning.
Material:
Cost tiers separate commodity converters from barrier specialists, with aluminum foil composites commanding 3-4x the per-square-meter pricing of mono-material polyethylene structures.
- Composites:Multilayer laminates incorporating adhesive-bonded aluminum foil, polyethylene, and polyethylene terephthalate achieving oxygen transmission rates below 0.1 cc/m²/day. Pharmaceutical packaging in Germany and medical device sterilization pouches sustain value premiums despite pending EU Packaging and Packaging Waste Regulation fees targeting mechanical recycling incompatibility.
- Plastic:Mono-material polyethylene or polypropylene structures with enhanced barrier coatings, specified by brand owners responding to California extended producer responsibility legislation. Coating technology R&D concentrates among converters with captive extrusion lines in the United States and United Kingdom.
- Aluminum Foil:Unlaminated foil webs for high-barrier pharmaceutical blister lidding, facing displacement by coated polymer alternatives in non-critical applications.
- Paper:Fiber-based substrates with polymer barrier coatings, limited to dry goods by moisture sensitivity despite sustainability marketing appeal.
Composites dominate value contribution; Plastic is expanding most quickly on recyclability-driven specification shifts.
End User:
Application requirements dictate cleanroom investment thresholds, with healthcare and pharmaceutical volumes accessible only to converters with seven-figure capital deployment capability.
- Food & Beverage:The largest volume category, spanning sauces, ready-to-eat meals, and pet food conversion from metal cans and glass jars. North American brands accelerate flexible packaging adoption for shelf-stable prepared meals, while EFSA migration testing mandates consolidate contract awards toward qualified European suppliers.
- Healthcare:Sterilization pouches and medical device packaging requiring ISO 14644 compliant production environments. German converters anchor this segment through certified cleanroom infrastructure.
- Personal Care:Liquid soap, shampoo, and cosmetic formats where dispensing convenience commands specification attention. Spouted configurations penetrate toddler nutrition adjacent segments.
- Industrial:Chemical and lubricant containment with less stringent barrier requirements, competing primarily on cost-engineered structures.
Food & Beverage handles the majority of throughput; Healthcare climbs the fastest on margin expansion.
Size:
Volume scale determines equipment utilization economics, with mid-size formats optimizing converter throughput across food and personal care production runs.
- Medium:500ml-2L fill volumes, capturing the bulk of retail sauce, detergent, and pet food specifications. German and French mass-market grocery chains consolidate procurement around this format for logistics efficiency.
- Small:Single-serve condiments, sample sachets, and pharmaceutical unit doses below 100ml, enabling premium positioning through portion control.
- Large:Family-size food service and industrial chemical formats, requiring enhanced seal strength specifications.
- Extra Large:Bulk institutional and foodservice applications with limited barrier sophistication.
Medium handles the majority of throughput; Small shows the steepest expansion trajectory on portion-control trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German converters command pricing premiums three to four times above Indian commodity suppliers, reflecting cleanroom certification costs and EFSA compliance infrastructure that Southeast Asian competitors cannot replicate.
United States
Pet food brands accelerate conversion from metal cans to high-barrier stand-up pouches with resealable closures, driving volume expansion across Midwest production corridors. FDA food-contact notification requirements extend supplier qualification timelines by 12-18 months for adhesive and ink constituents. Chicago-area converters serve mass-market grocery chains through direct procurement relationships that displace traditional distribution channels.
Germany
Pharmaceutical and medical pouch demand anchors European value pools through certified barrier laminates requiring ISO 14644 compliant production environments. EFSA multilayer testing protocols consolidate contract awards toward qualified suppliers with captive analytical laboratories. Bielefeld and surrounding North Rhine-Westphalia clusters host established laminate specialists serving premium personal care and healthcare clients.
China
Domestic food and beverage brands adopt flexible contour formats for sauces and ready-to-eat meals as retail infrastructure modernizes. GB standards for food-contact materials impose migration testing requirements that favor converters with in-house quality systems. Yangtze River Delta manufacturing hubs concentrate extrusion and printing capacity for both export and domestic consumption.
India
Emerging market personal care brands specify cost-engineered structures for liquid soap and cosmetic formats where unit economics dominate procurement decisions. FSSAI food safety regulations tighten compliance requirements for multilayer plastic films entering regulated channels. Maharashtra-based converters compete on price-accessible mono-material designs for regional brand owners.
United Kingdom
Mid-size food brands adopt digitally printed SKUs for seasonal and regional product variants, compressing minimum order quantities toward 5,000 units. EU REACH substance restrictions on adhesive constituents extend supplier qualification cycles despite post-Brexit regulatory divergence. Greater Manchester and Midlands production facilities serve retailers consolidating flexible packaging procurement through direct converter relationships.
Contour Pouches Market Competitive Environment
Concentration sits with large-scale laminate converters possessing captive extrusion lines and in-house analytical laboratories, while mid-scale competitors face exclusion from pharmaceutical segments due to seven-figure cleanroom certification thresholds. Boutique specialty printers occupy regional niches through digital flexographic capabilities for short-run customization. Two dominant competitive moves reshape positioning: backward integration into polymer compounding to secure resin supply, and strategic partnerships with coating technology developers to advance mono-material barrier performance.
Among North American-based converters, Glenroy Inc exemplifies the scale-driven archetype with significant extrusion and printing capacity across multiple facilities. Bischof + Klein SE & Co. KG anchors European pharmaceutical and medical pouch demand through certified cleanroom production in Germany. Omniplast Private Limited occupies the cost-engineering position for emerging market personal care brands seeking price-accessible structures.
| Leading Market Players |
|---|
| Glenroy Inc |
| Swiss Pac Pvt. Ltd |
| PAC Worldwide |
| Polynova Industries Inc |
| Ampac Holdings |
| Bischof + Klein SE & Co. KG |
| PouchTec Industries LLC |
| Omniplast Private Limited |
| Smart Pouches |
| Others |
Value Chain & Pricing Dynamics
Long-term annual contracts with take-or-pay provisions dominate procurement between North American food brands and Midwest converters, locking in resin supply visibility while exposing both parties to polyethylene and PET feedstock volatility indexed to crude oil benchmarks.
Pricing Analysis
The customization-premium spread separates commodity stand-up pouches from configured spouted formats with integrated fitments, with the latter commanding substantial uplifts for dispensing convenience in toddler nutrition and liquid soap segments. Three-tier pricing structure across premium pharmaceutical-grade, standard food-contact, and economy industrial tiers reflects ISO 14644 certification status and EFSA migration testing completion. Cost compression in economy tiers is intensifying as Indian converters deploy price-accessible mono-material designs for emerging market personal care brands. Mass-market grocery chains exhibit highest price sensitivity, while pharmaceutical and medical device manufacturers prioritize barrier performance over unit economics.
Supply Chain Analysis
Inventory cycles stretching 8-12 weeks for aluminum foil laminates contrast with 3-4 week turns on mono-material polyethylene structures, compressing working capital efficiency for barrier specialists. Manufacturing concentrates in Germany, the United States, and China, with the Yangtze River Delta and North Rhine-Westphalia clusters anchoring extrusion and printing capacity. Raw material flows draw from Saudi Arabian polyethylene producers, South Korean PET resin suppliers, and domestic aluminum rolling mills. Single-source vulnerability concentrates in pharmaceutical-grade adhesive formulations subject to EU REACH substance restrictions. Distribution runs through direct converter-retailer relationships bypassing traditional broker channels in Germany and France.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flexible packaging incumbents face sustained substitution pressure from rigid container recovery in premium food segments, requiring defensive repositioning around barrier performance and sustainability credentials.
For Market Incumbents: Shield pharmaceutical and medical pouch franchises through accelerated ISO 14644 cleanroom certification investments that exclude mid-scale competitors from seven-figure capital thresholds. Deepen backward integration into polymer compounding to secure resin supply continuity amid feedstock volatility. Defend against aluminum foil displacement by advancing coating technology partnerships for mono-material barrier alternatives.
For New Entrants and Emerging Players: Lead with digitally printed short-run capabilities for seasonal and regional SKU proliferation, compressing minimum order quantities toward 5,000 units without cylinder inventory burdens. Target mid-size food brands in the United Kingdom and United States adopting mass customization for market testing. Penetrate through direct e-commerce channel relationships that bypass consolidated grocery procurement.
For Investors and Strategic Acquirers: Capital is best deployed toward converters with captive analytical laboratories and EFSA-qualified cleanroom infrastructure, as regulatory compliance barriers widen the competitive moat. The 5-10 year viability window favors laminate specialists with demonstrated migration testing capabilities over commodity extrusion operators. Monitor California extended producer responsibility fee implementation as the inflection signal for mono-material design transition economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Barrier Development | California EPR frameworks reward mechanical recycling-compatible designs with favorable fee structures. |
| Cleanroom Certification Investment | ISO 14644 compliance unlocks pharmaceutical contract awards inaccessible to uncertified competitors. |
| Digital Printing Capacity Expansion | Short-run flexibility captures seasonal SKU demand from mid-size food brands in Germany and France. |
| Direct Retailer Relationship Development | Bypassing distributor channels compresses intermediary margins and secures volume commitments. |
| Coating Technology Partnership | Enhanced barrier polymers displace aluminum foil in non-oxygen-sensitive food applications. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA food-contact notification databases, EFSA migration testing protocols, and EU REACH substance restriction registers. Conversations with extrusion line operators, laminate converters, brand procurement managers, and pharmaceutical packaging engineers informed supply-side and demand-side perspectives. Customs trade data, SEC filings from listed packaging companies, and industry association production statistics provided volume validation. Bottom-up capacity assessments triangulated against top-down end-use consumption estimates.
Segmentation dimensions modeled include pouch geometry, material structure, end-use application, fill volume tier, and regional regulatory cluster across the analysis window. CAGRs derive from trend extrapolation adjusted for substitution elasticity between rigid and flexible formats. Forecast inputs incorporate EFSA certification timeline delays, California EPR fee structure assumptions, and pet food segment conversion rates from metal cans.
The analysis sits within stated boundaries; outcomes outside sustained resin price stability or accelerated mono-material barrier performance gains would require recalibration. Forecasts reflect documented assumptions regarding regulatory implementation schedules and brand sustainability commitment durability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Spain Pouch Packaging Market
Pouch
Middle East and Africa Pouch Packaging Market
Pouch
Digital Printed Pouch Market
Pouch
Japan Pouch Packaging Market
Pouch
Inflatable Pouches Market
Pouch
Canada Pouch Packaging Market
Pouch
Utility Pouches Market
Pouch
Egypt Pouch Packaging Market
Pouch
Benelux Pouch Packaging Market
Pouch
Box Pouch Market
Pouch
Sterilization Pouches Market
Pouch
Nigeria Pouch Packaging Market
Pouch
Four Side Flat Pouch Market
Pouch
Global Pouches Packaging Market
Pouch
Europe Retort Pouches Market
Pouch
Four Side-Sealed Pouches Market