
 Fin Seal Pouches Market | 2026-2036
Fin Seal Pouches Market Size, Share, and Industry Trends Forecast 2026-2036
Fin Seal Pouches Market Foresight
Food-grade barrier specifications are redrawing competitive positioning in fin seal pouch supply. Amcor plc leverages its global film extrusion network to sustain leadership in high-oxygen-barrier laminates for protein packaging. Mondi PLC anchors European demand through integrated kraft paper and plastic film operations that compete on sustainability credentials. Berry Global Inc. differentiates via vertical control over blown film assets, allowing rapid specification shifts as brand owners tighten material compliance.
Fin seal pouches are flexible packages sealed along one edge with a fin-style overlap joint, typically constructed from multi-layer coextruded films measuring 50–150 microns in total caliper to provide moisture and gas barrier protection for shelf-sensitive contents. Stand-up pouches and retort pouches command the dominant value share within product type segments, with retort formats capturing expanding margin pools as pet food and ready-meal brands shift from rigid cans. Plastic film and composites lead material demand, though aluminum foil laminates retain critical roles in pharmaceutical blister-compatible configurations where light and moisture exclusion are non-negotiable.
FDA food contact regulations, EU REACH compliance for adhesive and ink constituents, and ISO 9001 quality management standards collectively shape material selection, supplier qualification, and cross-border market access for fin seal pouch converters. The EU Packaging and Packaging Waste Regulation is accelerating demand for mono-material polyethylene and polypropylene structures that simplify mechanical recycling streams without sacrificing heat-seal integrity. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to invest in compatible mono-material capacity or pursue advanced chemical recycling partnerships to preserve specification flexibility.
Market Dynamics
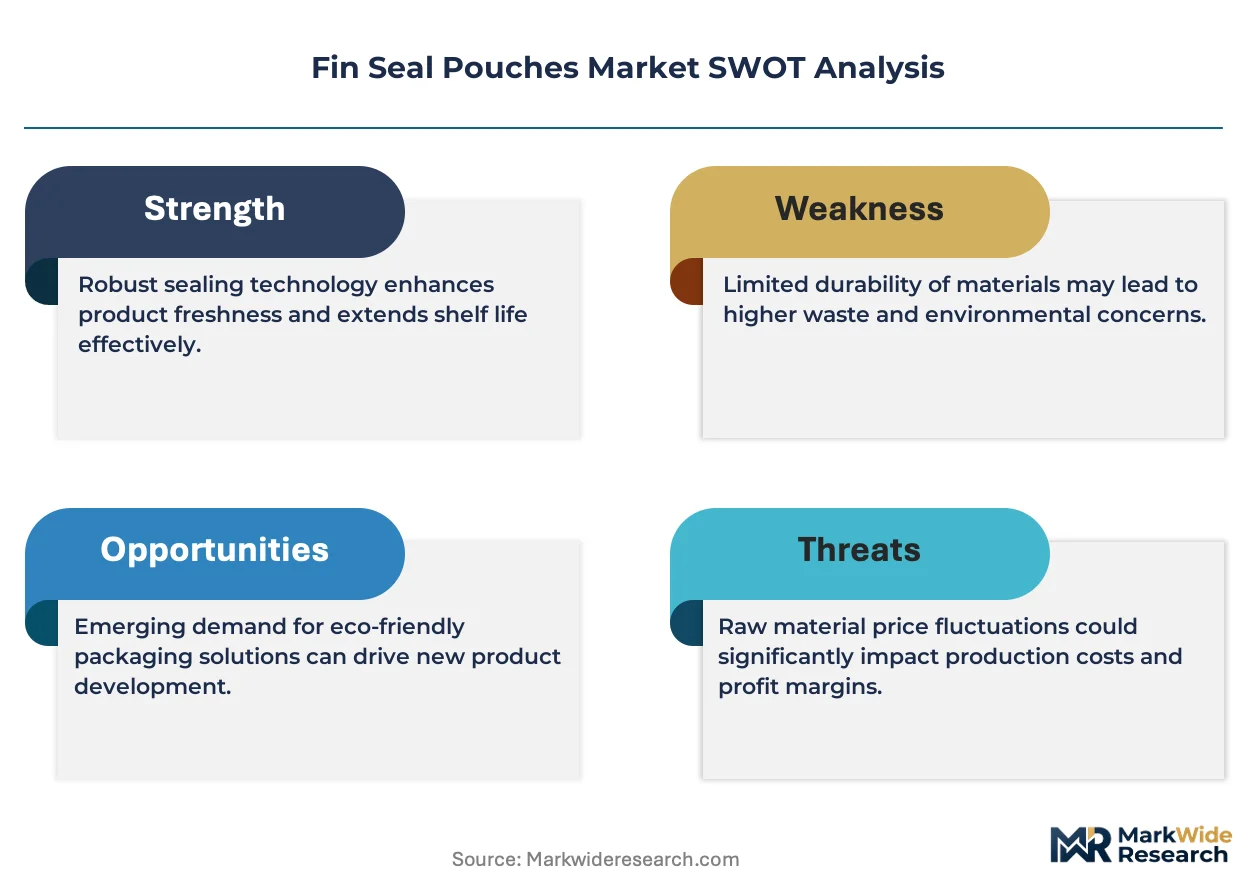
EU Packaging and Packaging Waste Regulation mandates are forcing converters to abandon multi-layer laminates in favor of mono-material polyethylene and polypropylene structures that preserve heat-seal integrity while enabling mechanical recycling.
Growth Catalysts
- EU Green Deal packaging circularity targets:Brand owners across Germany, France, and Italy are accelerating specification upgrades to mono-material fin seal formats ahead of 2030 recyclability deadlines.
- Pet food sector premiumization:Retort-compatible fin seal pouches are capturing volume from metal cans as private-label brands prioritize shelf differentiation and logistics efficiency.
- Barrier coating chemistry advances:Solvent-free adhesive systems and water-based oxygen barrier coatings are expanding high-performance applications without compromising seal strength.
Market Restraints
- Aluminum foil supply concentration:European foil rolling capacity is consolidating among three major suppliers, creating input cost volatility for pharmaceutical-grade light-barrier laminates.
- Mono-material performance ceiling:Current polyethylene coextrusion technology cannot match EVOH-based multi-layer structures for ultra-low oxygen transmission in extended shelf-life proteins.
- Extended producer responsibility fee structures:Germany's Verpackungsgesetz is imposing disproportionate compliance costs on small-batch converters serving regional food processors.
Strategic Opportunities
- Central European food processing clusters:Poland and Czech Republic meat packaging facilities are underserved by domestic high-barrier film suppliers, creating white space for specification-compliant entrants.
- Chemical recycling infrastructure partnerships:Converters aligning with advanced recycling projects can preserve multi-material flexibility while meeting EU circularity accounting standards.
- Pharmaceutical compliance differentiation:ISO 15378 certification for medicinal product packaging is creating premium positioning for converters serving blister-compatible pouch formats.
Industry Challenges
- Mono-material requalification timelines:Food brand owners demand 18-24 month validation cycles for new film structures, compressing converter development windows.
- Adhesive formulation chemistry expertise:Solvent-free lamination requires specialized polymer science talent that remains concentrated among legacy European suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fin Seal Pouches Market |
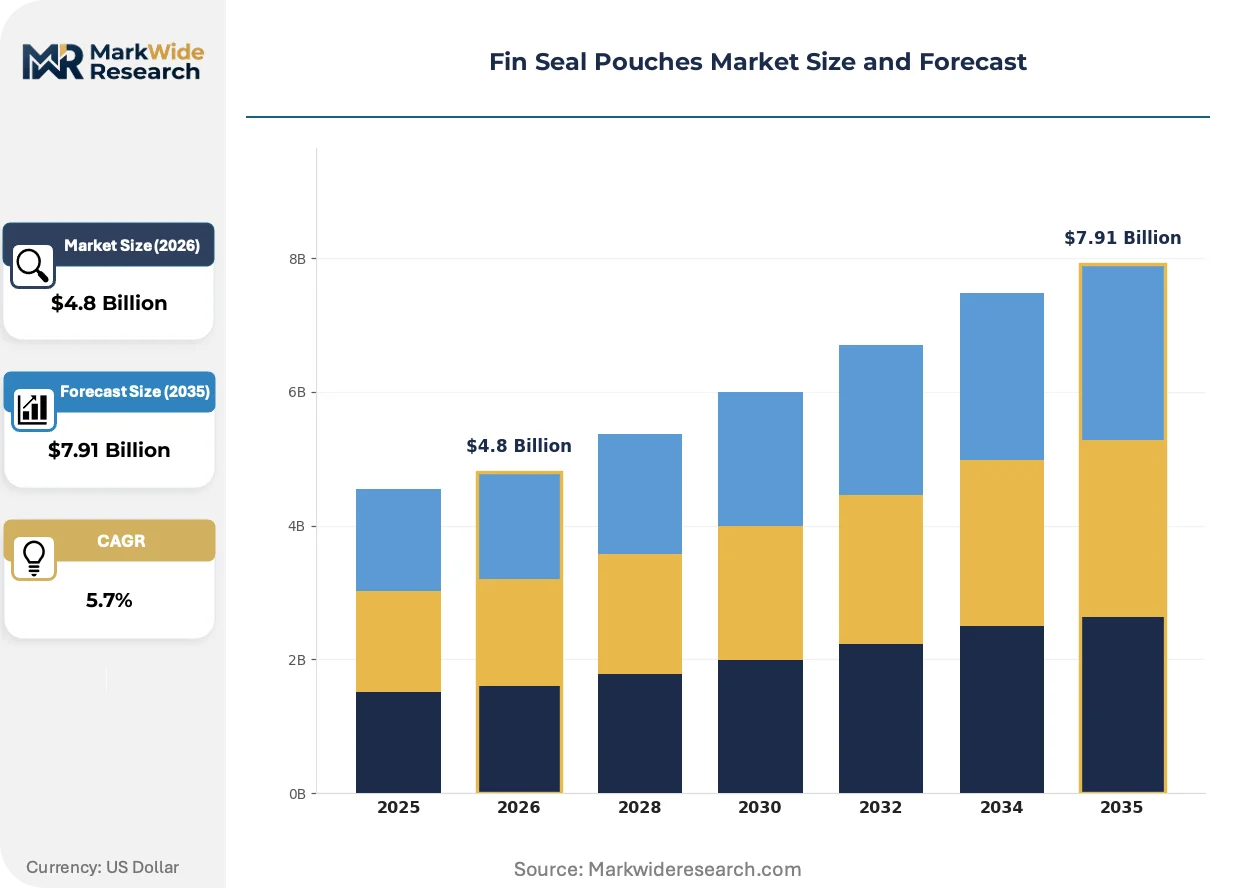
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Flat Pouches, Retort Pouches, Gusseted Pouches Material: Plastic Film, Aluminum Foil, Paper, Composites End User: Food Industry, Pharmaceutical Sector, Personal Care, Consumer Goods Packaging Type: Pre-Formed Bags, Flexible Packaging, Specialty Packs, Others |
| Companies Covered | Amcor plc, Mondi PLC, Berry Global Inc., Sealed Air Corporation, DS Smith plc, Sonoco Products Company, IMPAK Corporation, TedPack Company Limited, Clifton Packaging Group Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fin Seal Pouches Market Shifts & Advancements
Material science breakthroughs and regulatory compliance architectures are redefining competitive advantage in fin seal pouch manufacturing, separating specification-capable converters from commodity suppliers.
High-barrier coating technology is bifurcating the converter landscape. Thin-film silicon oxide and aluminum oxide vapor deposition systems are enabling transparent oxygen barriers that replace aluminum foil in microwaveable ready-meal applications. German and Italian food brands are specifying these coatings for premium protein lines. The technology is bifurcating margin pools toward equipment-intensive specialists and away from conventional adhesive laminators.
REACH compliance for adhesive and ink constituents is tightening material qualification protocols. ECHA substance of very high concern listings are forcing reformulation of polyurethane laminating adhesives and photoinitiator systems used in flexographic printing. Pharmaceutical and infant nutrition segments are responding with dedicated supply chain segregation and third-party migration testing investments.
Brand owner specification consolidation is compressing supplier diversity. Major European retailers are reducing approved film vendor lists from twelve to four converters per category, prioritizing partners with integrated extrusion, printing, and pouch forming capabilities. This concentration is most visible in Germany's discount retail channel, where private-label ready-meal volumes are concentrating among vertically integrated packaging groups.
Fin Seal Pouches Market Segmentation
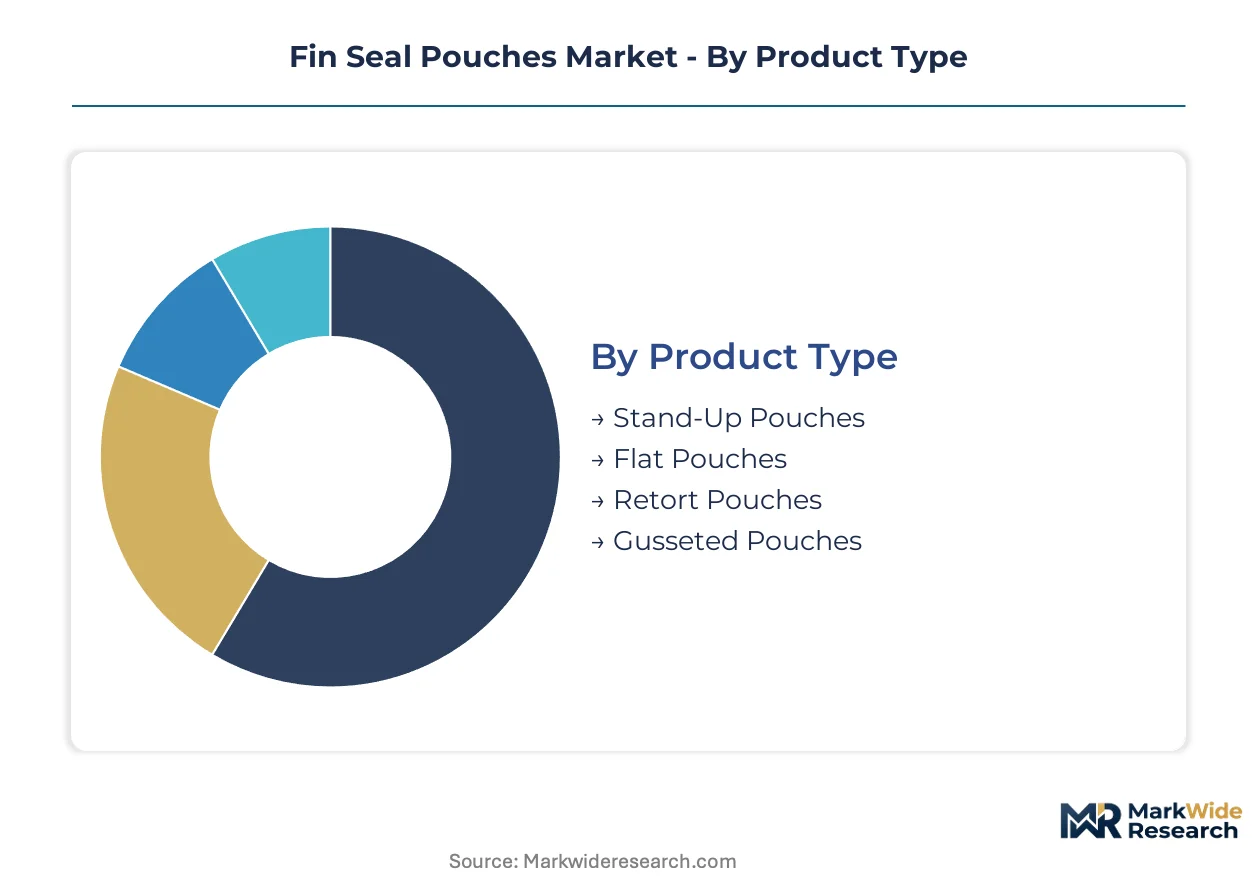
Fin seal pouch specifications fragment across four structural dimensions that determine converter capability requirements and margin profiles. Product type and material composition dictate barrier performance and recyclability compliance, while end-user verticals and packaging formats shape volume concentration and specification complexity.
Product Type:
Domestic European demand concentrates in retort-compatible and stand-up configurations, while flat and gusseted formats serve export-led commodity segments.
- Stand-Up Pouches:Self-supporting bottom gusset structures constructed from 80–120 micron coextruded films with integrated zipper or spout fitments. German discount retailers and French hypermarket chains specify these for private-label ready-meal lines requiring shelf presence and resealability. EU Green Deal recyclability mandates are accelerating mono-material polypropylene adoption despite requalification costs.
- Retort Pouches:Four-layer laminates with aluminum oxide or silicon oxide barrier coatings withstand 121°C sterilization cycles for shelf-stable proteins and pet food. Italian pet food brands and Czech meat processors are displacing metal cans with retort fin seals to reduce logistics cube and enable microwave preparation. The format climbs fastest as premiumization penetrates European private-label channels.
- Flat Pouches:Simple two-seal constructions for single-serve portions and sample packs, common in pharmaceutical blister-compatible configurations.
- Gusseted Pouches:Side-folded expansions for bulk dry goods, dominant in Central European grain and ingredient packaging.
Stand-Up Pouches holds the largest share; momentum sits with Retort Pouches.
Material:
Specification costs tier sharply by barrier performance, with pharmaceutical and extended shelf-life food applications commanding premium laminates while commodity segments migrate toward simpler structures.
- Plastic Film:Multi-layer polyethylene and polypropylene coextrusions dominate volume, with EVOH oxygen barrier layers in protein packaging and sealant grades optimized for high-speed form-fill-seal lines. German converters are investing in mono-material polyethylene capacity to satisfy Verpackungsgesetz extended producer responsibility requirements ahead of mechanical recycling deadlines.
- Aluminum Foil:Seven-micron annealed foil laminates provide absolute light and moisture barriers for pharmaceutical blister packs and infant nutrition. European foil rolling capacity concentration among three major suppliers creates input cost volatility that converters pass through via indexed contracts.
- Paper:Fiber-based structures with polymer barrier coatings compete in sustainability-positioned dry goods, though moisture sensitivity limits penetration.
- Composites:Hybrid paper-plastic or film-foil combinations balance printability with functional performance in premium confectionery and cosmetics.
Plastic Film captures the dominant volume position; aluminum foil laminates defend the highest margin tier despite supply concentration risks.
End User:
Application requirements span from mass-market food compliance to pharmaceutical-grade validation protocols, segmenting converter capabilities and customer concentration.
- Food Industry:Protein processors, ready-meal manufacturers, and pet food brands drive specification evolution. German meat packaging clusters and Polish cold-chain distributors demand high-oxygen-barrier structures with extended shelf-life validation. REACH-compliant adhesive systems and migration-tested ink formulations are mandatory for EU market access.
- Pharmaceutical Sector:Blister-compatible pouch formats for unit-dose medications require ISO 15378 certification and dedicated cleanroom production segregation. Swiss and German medicinal product packaging regulations impose batch traceability and stability testing protocols that exclude commodity converters.
- Personal Care:Cosmetic and hygiene product pouches prioritize aesthetic print quality and dispensing convenience over extended barrier performance.
- Consumer Goods:Household chemical and automotive fluid pouches emphasize chemical resistance and child-resistant closure integration.
Food Industry absorbs the largest volume; pharmaceutical certification creates the steepest competitive moat.
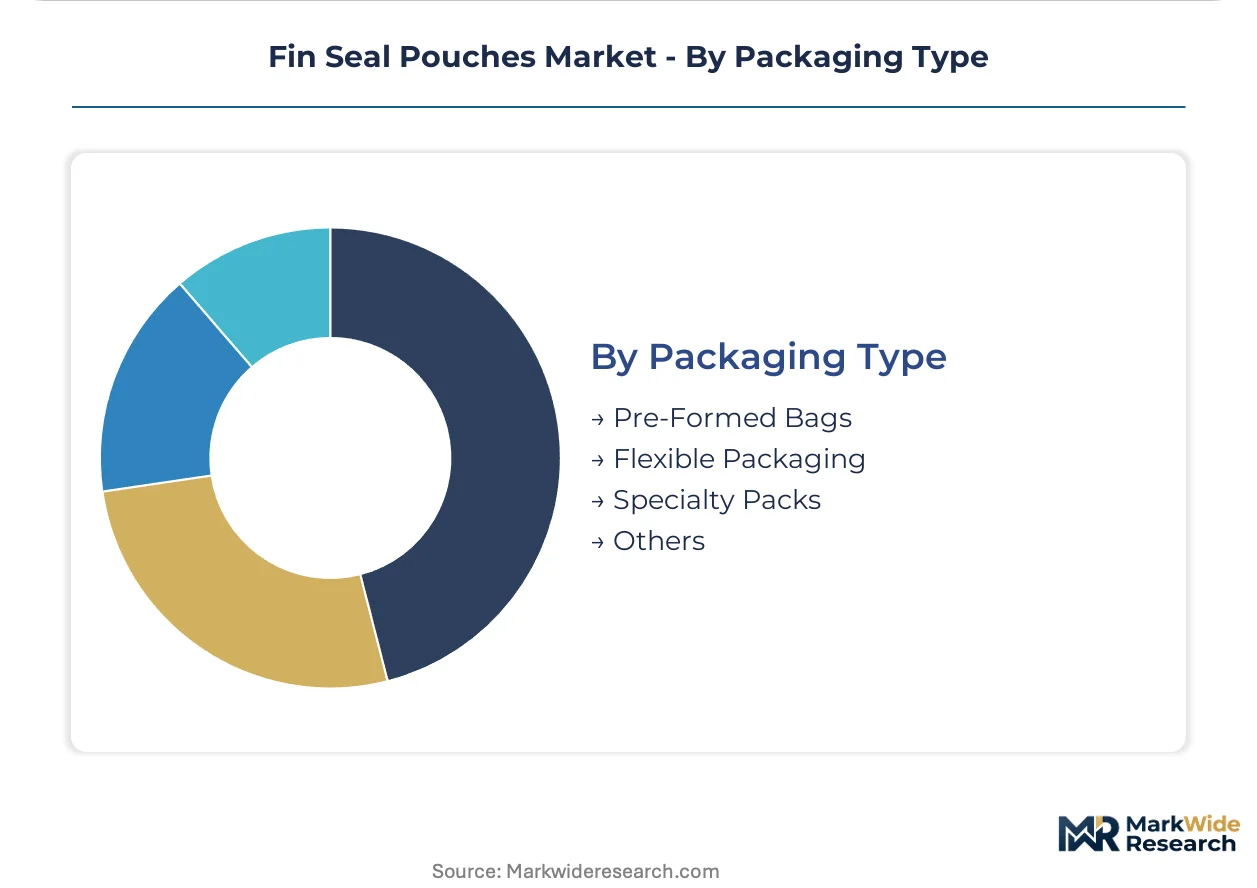
Packaging Type:
Supply chain integration depth varies by format, with pre-formed bags demanding converter forming capability and flexible packaging materials serving brand-owner vertical integration strategies.
- Pre-Formed Bags:Finished pouches supplied to co-packers and food processors with integrated fitments and registered graphics. Italian and Spanish co-packing networks favor this format to minimize capital investment in forming equipment.
- Flexible Packaging:Rollstock and unformed web materials for brand-owner captive pouch forming lines. Major German retailers are consolidating supplier lists toward integrated extrusion-printing-forming converters.
- Specialty Packs:Custom geometries and functional enhancements for promotional and limited-edition product launches.
- Others:Niche configurations including vacuum skin packs and modified atmosphere formats for specific protein applications.
Flexible Packaging leads in volume terms; Pre-Formed Bags expands most quickly as co-packer networks proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in fin seal pouches favor European converters with integrated film extrusion and forming capabilities. Germany maintains a structural surplus in high-barrier pouch supply, while Central European meat processors import specification-grade retort formats from Italian and Spanish converters. Asian manufacturers compete on commodity flat pouch volumes, though EU regulatory compliance barriers limit penetration into food-contact applications.
Germany
Verpackungsgesetz extended producer responsibility fees are accelerating converter consolidation around mono-material polyethylene capacity. The EU Packaging and Packaging Waste Regulation mandates 2030 recyclability targets that German discount retailers are enforcing through reduced supplier lists. Bavarian and North Rhine-Westphalia packaging clusters dominate high-oxygen-barrier film supply for protein processors across Central Europe.
France
French hypermarket chains are specifying stand-up pouch formats with integrated spout fitments for private-label ready-meal lines. ECHA REACH compliance for adhesive constituents is tightening qualification protocols for converters serving infant nutrition segments. The Lyon and Paris basin food processing corridors are driving demand for retort-compatible barrier coatings that displace metal cans in shelf-stable proteins.
Italy
Italian pet food brands are displacing rigid packaging with retort fin seal pouches to reduce logistics cube and enable microwave preparation. CE marking requirements for food contact materials are standardizing migration testing protocols across Lombardy and Emilia-Romagna converter networks. Bologna and Milan packaging innovation hubs are specializing in aluminum oxide vapor deposition for transparent oxygen barriers in premium protein lines.
Poland
Polish meat packaging facilities are underserved by domestic high-barrier film suppliers, creating white space for specification-compliant entrants from Germany and Czech Republic. The country's national environmental regulator is aligning extended producer responsibility frameworks with EU circularity targets ahead of mechanical recycling deadlines. Warsaw and Łódź cold-chain distribution clusters are demanding extended shelf-life validation for exported protein shipments.
United States
FDA food contact regulations are shaping material selection for converters supplying North American protein processors and ready-meal brands. Midwest meat packaging corridors and Southeast co-packer networks are importing European retort pouch technology for premium pet food applications. Chicago and Atlanta distribution hubs are consolidating procurement toward converters with integrated extrusion, printing, and pouch forming capabilities.
Fin Seal Pouches Market Competitive Landscape
Concentration sits with integrated film extruders and multinational packaging groups that control specification-compliant supply chains. The vendor base separates into three tiers: global converters with captive resin and coating operations, regional specialists with differentiated barrier technologies, and commodity formers competing on throughput. Strategic moves center on mono-material capacity investments and chemical recycling infrastructure partnerships that preserve multi-layer flexibility under EU circularity accounting standards.
Within the integrated multinational tier, Amcor plc, Mondi PLC, and Berry Global Inc. represent archetypes of scale-driven competitive positioning. Amcor exemplifies global film extrusion network leverage for high-oxygen-barrier laminates. Mondi occupies a position anchored in European sustainability credentials through integrated kraft paper and plastic film operations. Berry Global sits within the vertical manufacturing control archetype, with blown film assets enabling rapid specification shifts as brand owners tighten material compliance requirements.
| Leading Market Players |
|---|
| Amcor plc |
| Mondi PLC |
| Berry Global Inc. |
| Sealed Air Corporation |
| DS Smith plc |
| Sonoco Products Company |
| IMPAK Corporation |
| TedPack Company Limited |
| Clifton Packaging Group Ltd. |
| Others |
Supply & Pricing Matrix
EU REACH compliance for adhesive and ink constituents gates both supplier qualification and price differentiation simultaneously, as converters serving pharmaceutical and infant nutrition segments must absorb third-party migration testing investments that commodity suppliers cannot shoulder.
Pricing Analysis
Industrial OEM buyers anchor a contract-based pricing structure indexed to aluminum foil input costs and EVOH resin premiums. Three-tier pricing separates pharmaceutical-grade ISO 15378-certified laminates from food-grade barrier films and commodity mono-material polyethylene structures. Pricing pressure stems from Germany's Verpackungsgesetz extended producer responsibility fees disproportionately burdening small-batch converters. Private-label retail buyers exhibit highest price sensitivity, while pharmaceutical procurement committees prioritize batch traceability over unit cost.
Supply Chain Analysis
Port congestion on Asia-Europe container lanes and Baltic Sea route disruptions are elevating inbound logistics costs for seven-micron aluminum foil sourced from European rolling mills. Raw material supply concentrates in Germany, Italy, and Spain for high-barrier film extrusion, with biaxially oriented polypropylene and EVOH sealant resins drawing from petrochemical complexes in Belgium and the Netherlands. Single-source vulnerability sits with pharmaceutical-grade foil laminates where three European suppliers control rolling capacity. Distribution runs through converter-direct relationships with German discount retailers and Italian co-packer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fin seal pouch specification evolution resembles platform economics where mono-material recyclability standards and chemical recycling infrastructure interoperability determine which converter ecosystems capture brand owner volume.
For Market Incumbents: Secure mono-material polyethylene capacity investments ahead of EU Packaging and Packaging Waste Regulation mechanical recycling deadlines. Anchor backward integration into blown film assets to preserve margin pools as EVOH-based multi-layer structures face phase-out pressure from sustainability-positioned competitors. Prioritize ISO 15378 certification for medicinal product packaging to defend premium positioning against commodity converters. For New Entrants and Emerging Players: Chemical recycling infrastructure partnerships represent a service-layer gap where incumbents under-serve brand owners seeking multi-material flexibility under EU circularity accounting standards. Target Poland and Czech Republic meat packaging clusters underserved by domestic high-barrier film suppliers. Pursue specification-compliant retort pouch formats for pet food premiumization as the most penetrable application wedge. For Investors and Strategic Acquirers: EU Green Deal packaging circularity targets reshape the acquisition landscape toward converters with integrated extrusion-printing-forming capabilities and chemical recycling alignment. Five-to-ten year viability favors vertically integrated packaging groups over standalone formers facing supplier list consolidation. Monitor German discount retailer approved vendor list reductions as the signal for sector consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Capacity Expansion | Preserves heat-seal integrity while satisfying EU mechanical recycling mandates ahead of deadlines. |
| Chemical Recycling Infrastructure Partnership | Enables multi-layer specification flexibility under EU circularity accounting standards. |
| ISO 15378 Certification Investment | Creates premium positioning for blister-compatible pouch formats serving Swiss and German medicinal product regulations. |
| Backward Integration into Blown Film Assets | Allows rapid specification shifts as brand owners tighten REACH-compliant adhesive requirements. |
| Central European Geographic Expansion | Captures white space in Polish and Czech meat packaging facilities lacking domestic high-barrier suppliers. |
Research Methodology
Initial hypotheses were tested against primary input from converter operations managers, brand owner packaging specification leads, and chemical recycling project developers and refined through secondary validation against ECHA substance of very high concern listings, EU Packaging and Packaging Waste Regulation impact assessments, and SEC filings from integrated packaging groups. Bottom-up demand modeling across protein processor procurement volumes and top-down supply analysis from film extrusion capacity announcements were triangulated to produce segment-level outputs.
Variance decomposition across product type, material composition, end-use vertical, and packaging format dimensions structured the analytical framework over the projection horizon. CAGRs were derived from fitted growth curves applied to base-year volume estimates, with inputs including German Verpackungsgesetz compliance cost trajectories and Italian pet food brand packaging format shift disclosures.
Forecasts assume regulatory continuity in EU REACH and Packaging and Packaging Waste Regulation regimes; material policy shifts would require re-modeling. Aluminum foil supply concentration and EVOH performance ceiling constraints represent specific risk factors that could revise trajectory assumptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Heat Sealed Lamination Pouch Market
Pouch
Four Side Flat Pouch Market
Pouch
Doyen Style Pouches Market
Pouch
Slider Zipper Pouch Market
Pouch
Squeeze Pouch Market
Pouch
Automatic Pre-Made Pouch Packaging Machine Market
Pouch
Sterilization Pouches Market
Pouch
Saudi Arabia Pouch Packaging Market
Pouch
Foam Pouch Market
Pouch
Open Mouth Sacks Market
Pouch
Thailand Pouch Packaging Market
Pouch
PPWR-Compliant Recyclable PE/PP Stand-Up Pouch Recycling Systems Market
Pouch
Pillow Pouch Packaging Market
Pouch
Asia-Pacific Retort Pouch Market
Pouch
Dual-Chamber Pouches Market
Pouch
Twist Wrap Packaging Market