
 Ground Protection Mats Market | 2026-2036
Ground Protection Mats Market Size, Share, and Industry Trends Forecast 2026-2036
Ground Protection Mats Market Outlook
Aftermarket service revenue, including mat cleaning, inspection, and redeployment logistics, is tilting toward higher-margin recurring contracts as buyers prioritize total cost of ownership over upfront purchase price. Signature Systems Group leverages its North American rental network to capture this shift. Centriforce Products anchors its position through backward integration into recycled polymer sourcing. Oxford Plastics Systems differentiates via specialized composite formulations for European utility standards.
Ground protection mats are load-distribution surfaces, typically manufactured from high-density polyethylene, recycled rubber, or engineered composites, designed to prevent soil compaction and rutting under vehicle or equipment traffic across soft or sensitive terrain. Standard HDPE mats achieve load ratings exceeding 120 tons while remaining manually deployable by two workers. Composite mats command premium positioning due to superior durability-to-weight ratios and extended lifecycle performance in repeated deployment scenarios. Temporary roadway applications within the construction end-user segment represent the most mature volume pool, while utility-sector ground protection for renewable energy installations shows the fastest trajectory.
OSHA workplace safety mandates in the United States, REACH chemical compliance requirements across Europe, and EPA stormwater runoff regulations collectively shape product material specifications and market access conditions for ground protection mat suppliers. The EU Green Deal's circular economy provisions are accelerating recycled content thresholds that manufacturers must satisfy for public procurement eligibility. Stakeholders must monitor how evolving carbon-border adjustment mechanisms and state-level infrastructure spending prioritization reshape competitive cost structures and geographic demand distribution.
Market Dynamics
Construction site managers across Germany, Texas, and Queensland are expanding mat deployment for heavy equipment access, while the EU Green Deal's circular economy provisions force rapid reformulation toward recycled polyethylene content.
Growth Catalysts
- Utility Infrastructure Expansion:Renewable energy installations in Texas, North Rhine-Westphalia, and Queensland require temporary access roads for turbine and solar farm construction. Ground protection mats enable year-round mobilization across soft or sensitive terrain.
- REACH Chemical Compliance:European manufacturers reformulating with recycled content gain preferential access to public procurement channels. The EU Green Deal accelerates recycled polymer thresholds for infrastructure contracts.
- OSHA Workplace Safety Mandates:United States construction sites face stricter soil stabilization requirements for heavy equipment operation. Mats reduce rutting hazards and stormwater runoff violations under EPA regulations.
Market Restraints
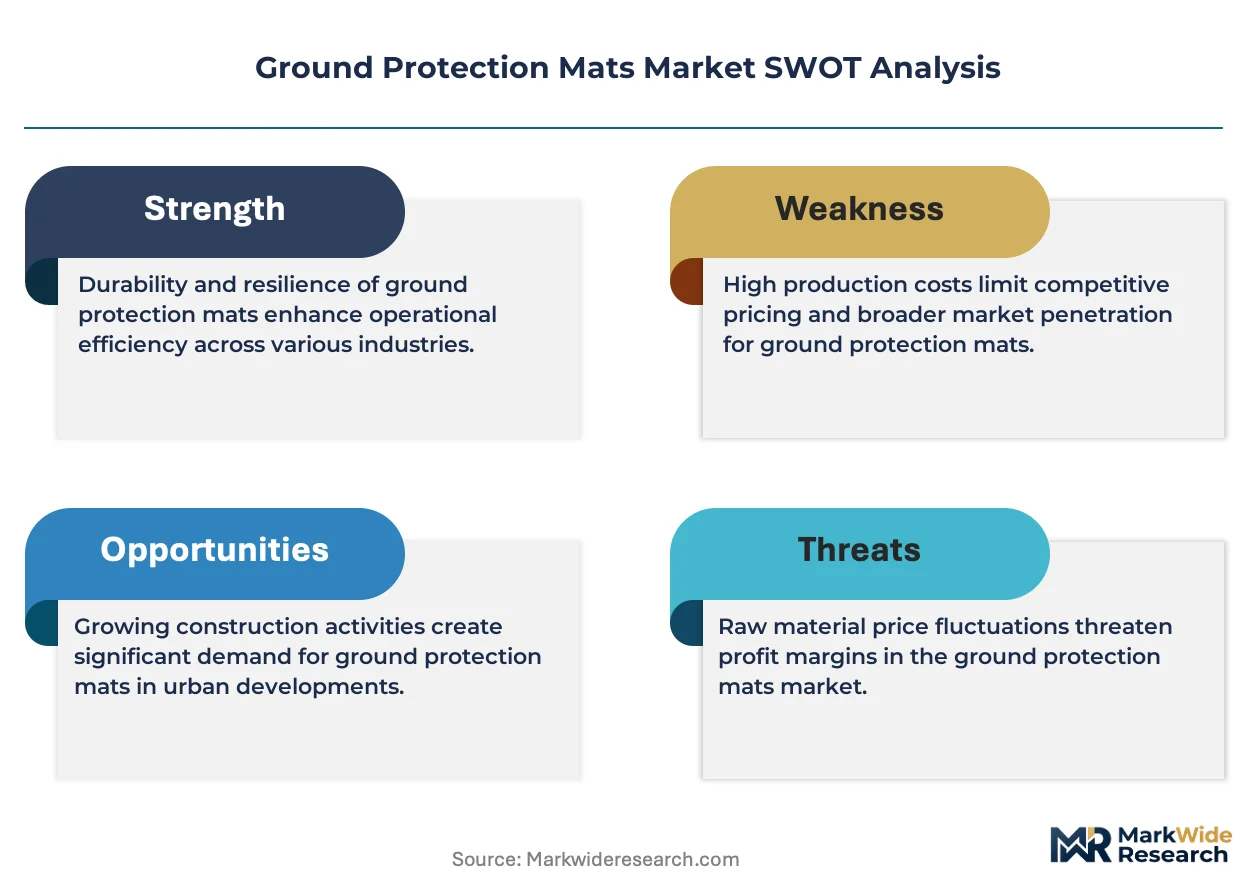
- Recycled Polymer Input Volatility:Post-consumer HDPE supply concentrates among specialized recyclers in Northern Europe. Price swings in recycled feedstock compress margin predictability for mat producers.
- Composite Material Technical Limitations:Engineered formulations achieving premium durability-to-weight ratios require precise temperature control during extrusion. Manufacturing yield rates lag behind standard HDPE processes.
- Substitution by Geotextile Reinforcement:Woven geotextiles combined with aggregate layers compete for low-load temporary access applications. Cost-sensitive buyers in developing markets favor this hybrid approach.
Strategic Opportunities
- Aftermarket Service Contracts:Mat cleaning, inspection, and redeployment logistics tilt toward recurring revenue models. Buyers prioritize total cost of ownership over upfront purchase price.
- Carbon-Border Adjustment Mechanisms:Evolving EU trade provisions reward low-carbon mat production. Manufacturers with backward integration into recycled polymer sourcing capture compliance premiums.
- Modular Composite-Convergence:Integration of sensor-enabled load monitoring with standard mat surfaces creates predictive maintenance capabilities. Smart infrastructure projects in Germany and the United States pilot these hybrid systems.
Industry Challenges
- Recycled Polymer Quality Certification:Batch-to-batch consistency in post-consumer HDPE requires sophisticated sorting and testing infrastructure. Producers must validate mechanical properties against virgin material specifications.
- Deployment Logistics Coordination:Multi-site utility projects demand synchronized mat repositioning across dispersed locations. Rental network density determines competitive service level attainment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ground Protection Mats Market |
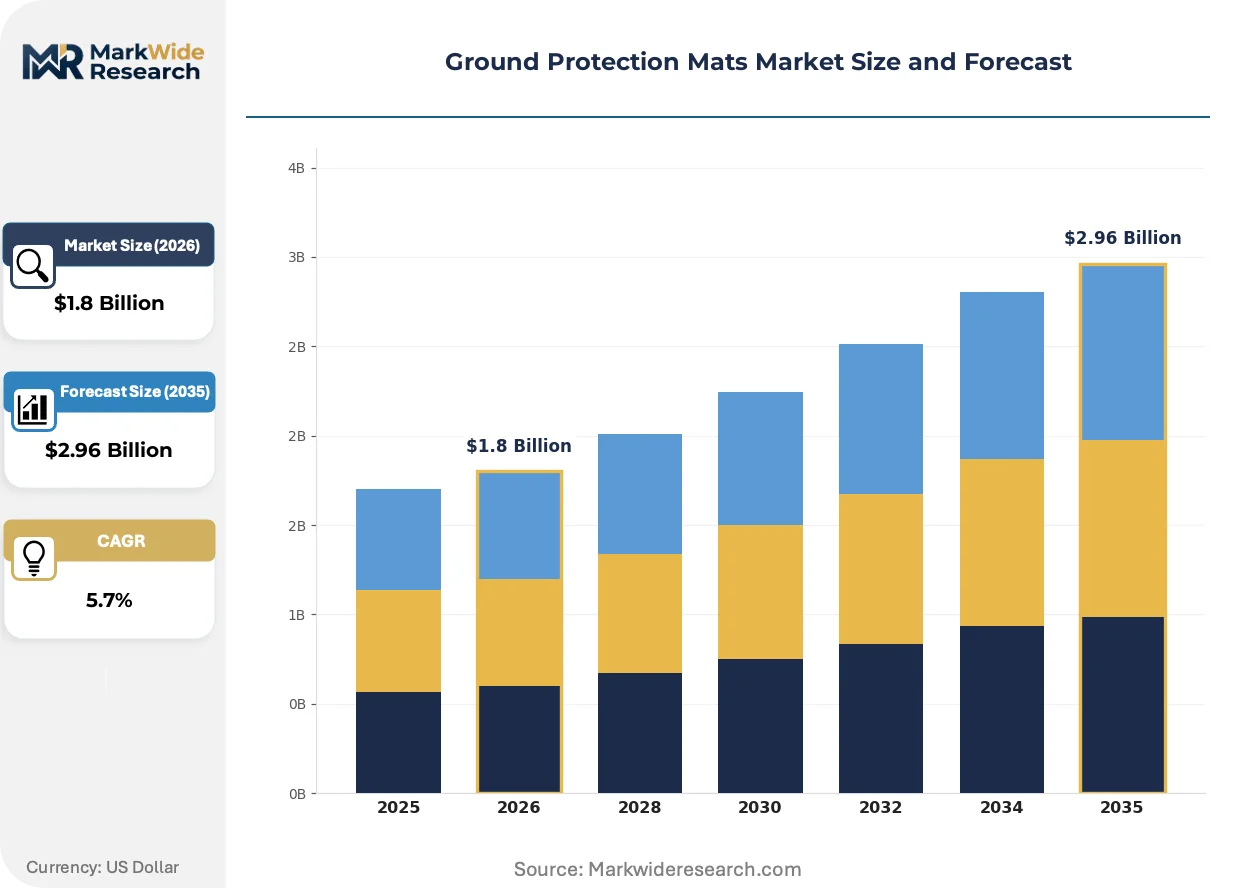
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubber Mats, Plastic Mats, Composite Mats, Wooden Mats End User: Construction, Events, Landscaping, Utilities Application: Site Access, Ground Protection, Temporary Roadways, Heavy Equipment Size: Small, Medium, Large, Extra Large |
| Companies Covered | Centriforce Products, Oxford Plastics Systems, Signature Systems Group, Groundtrax Systems, Newpark Resources, Quality Mat Company, LuxTek GmbH, The Jaybro Group, Checkers Safety Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ground Protection Mats Market Strategic Shifts
Material science breakthroughs and regulatory compliance automation are compressing product development cycles while reshaping procurement relationships between mat suppliers and infrastructure contractors.
Composite mat technology is migrating from niche premium positioning toward mainstream utility adoption. Wind farm developers in Germany and solar installation contractors in Texas specify engineered formulations for repeated deployment scenarios. The shift compresses lifecycle cost calculations and displaces standard HDPE in high-rotation applications.
REACH chemical compliance requirements across Europe are accelerating automated material traceability systems. Manufacturers deploy blockchain-verified chain-of-custody documentation for recycled content claims. Public procurement eligibility now hinges on real-time verification capabilities, favoring producers with integrated recycling operations.
Rental and service-based contracting models displace direct purchase arrangements in the United States construction segment. Large infrastructure contractors bundle mat provision with logistics management to reduce capital deployment. Texas utility projects demonstrate the fastest adoption of outcome-based access solutions over equipment ownership.
Ground Protection Mats Market Segmentation
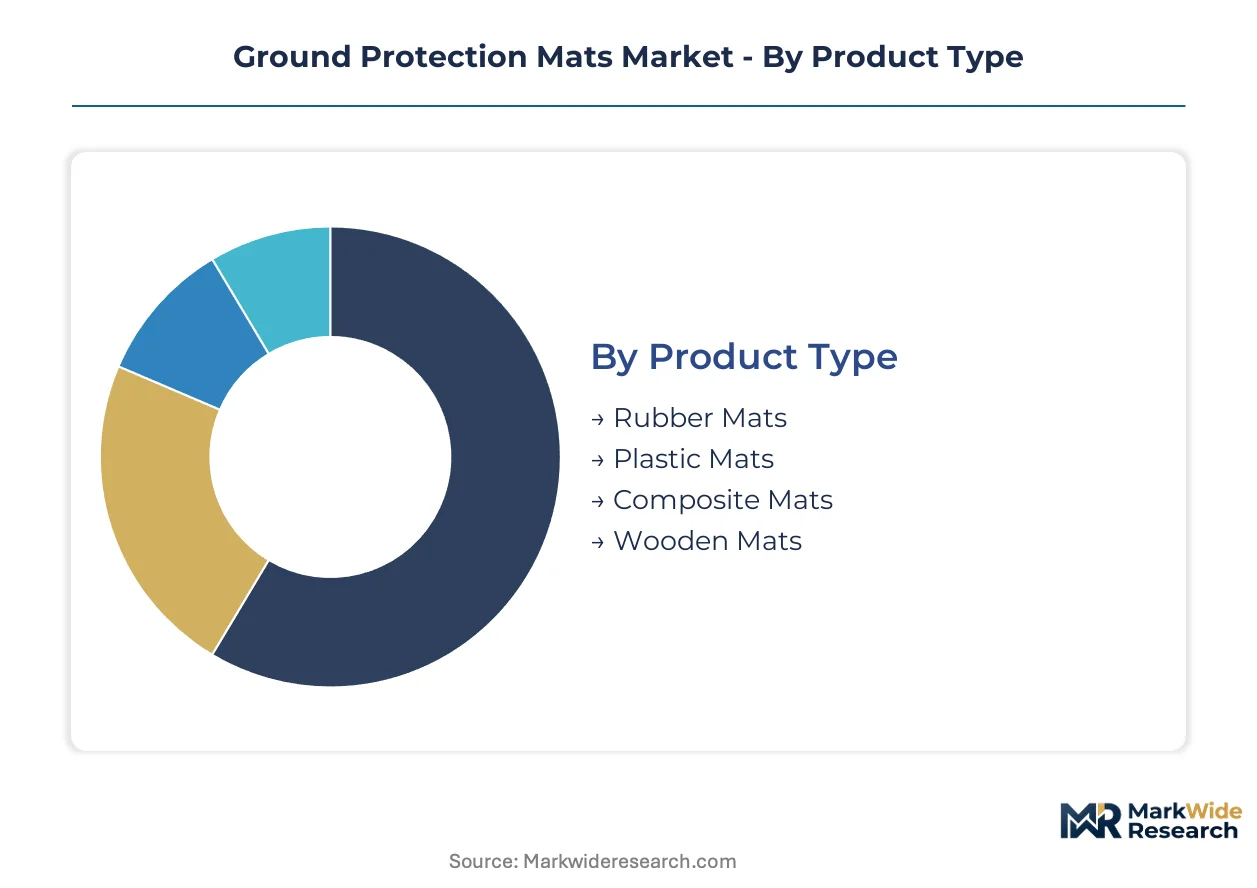
Ground protection mat segmentation reveals divergent replacement cycles across material formulations, with composite and rubber variants commanding extended service lives while plastic mats turn over rapidly in high-rotation construction environments. Understanding these velocity patterns enables suppliers to align inventory financing and service contract structures with actual field utilization.
Product Type:
Cycle times vary dramatically across material formulations, from rapid-turn plastic deployments to decade-spanning composite installations in permanent infrastructure staging areas.
- Plastic Mats:High-density polyethylene formulations achieve 120-ton load ratings while remaining manually deployable by two workers. Construction contractors in Texas and Queensland favor these for short-duration projects where rapid redeployment between sites compresses amortization schedules.
- Composite Mats:Engineered fiber-reinforced polymers deliver superior durability-to-weight ratios with extended lifecycle performance. German wind farm developers specify these for repeated turbine access scenarios where mat integrity across 50+ deployment cycles justifies premium positioning.
- Rubber Mats:Recycled rubber compounds absorb vibration and provide traction in wet conditions. Event staging companies in North Rhine-Westphalia deploy these for temporary pedestrian pathways and equipment staging.
- Wooden Mats:Laminated timber construction suits low-load landscaping applications where biodegradability aligns with project environmental commitments. Queensland conservation projects specify these for sensitive ecological access.
Plastic mats dominate installed base through volume accessibility. Composite mats are where expansion concentrates as lifecycle cost calculations displace upfront price sensitivity.
End User:
Margin structures diverge sharply between capital-constrained event operators and infrastructure contractors prioritizing total cost of ownership over multi-year horizons.
- Construction:General contractors bundle mat provision with site logistics management to reduce capital deployment. OSHA workplace safety mandates in the United States drive specification of load-rated surfaces for heavy equipment operation.
- Utilities:Renewable energy developers in Texas and North Rhine-Westphalia require year-round mobilization across soft terrain for turbine and solar farm construction. These projects demonstrate the steepest expansion trajectory as grid-scale installation accelerates.
- Events:Festival and exhibition operators prioritize rapid deployment and retrieval speed over durability. Rental network density determines competitive positioning in this segment.
- Landscaping:Residential and commercial grounds maintenance contractors favor small-format mats for light equipment access. Seasonal demand patterns create utilization challenges for dedicated fleet operators.
Construction commands the deepest installed base through project volume density. Utilities represent where specification value is climbing fastest as renewable infrastructure scales.
Application:
Functional requirements shape material selection, with load concentration and surface sensitivity driving formulation choices across deployment scenarios.
- Temporary Roadways:Continuous vehicle traffic demands maximum load distribution and surface stability. Composite mat technology is migrating from niche premium positioning toward mainstream adoption as wind farm developers specify engineered formulations.
- Heavy Equipment:Concentrated point loads from cranes and drilling rigs require highest-tier load ratings. Standard HDPE mats achieve necessary specifications while remaining field-repairable.
- Site Access:Intermittent light vehicle and personnel movement suits mid-duty plastic and rubber formulations. Event and landscaping end users concentrate demand here.
- Ground Protection:Vegetation preservation and soil stabilization objectives prioritize minimal ground pressure. Queensland environmental regulations mandate these surfaces for sensitive terrain access.
Temporary roadways anchor current deployment volume. Heavy equipment access is gaining specification priority as infrastructure project scale intensifies.
Size:
Format dimensions determine handling economics, with manual deployability thresholds separating rental-accessible segments from crane-dependent heavy formats.
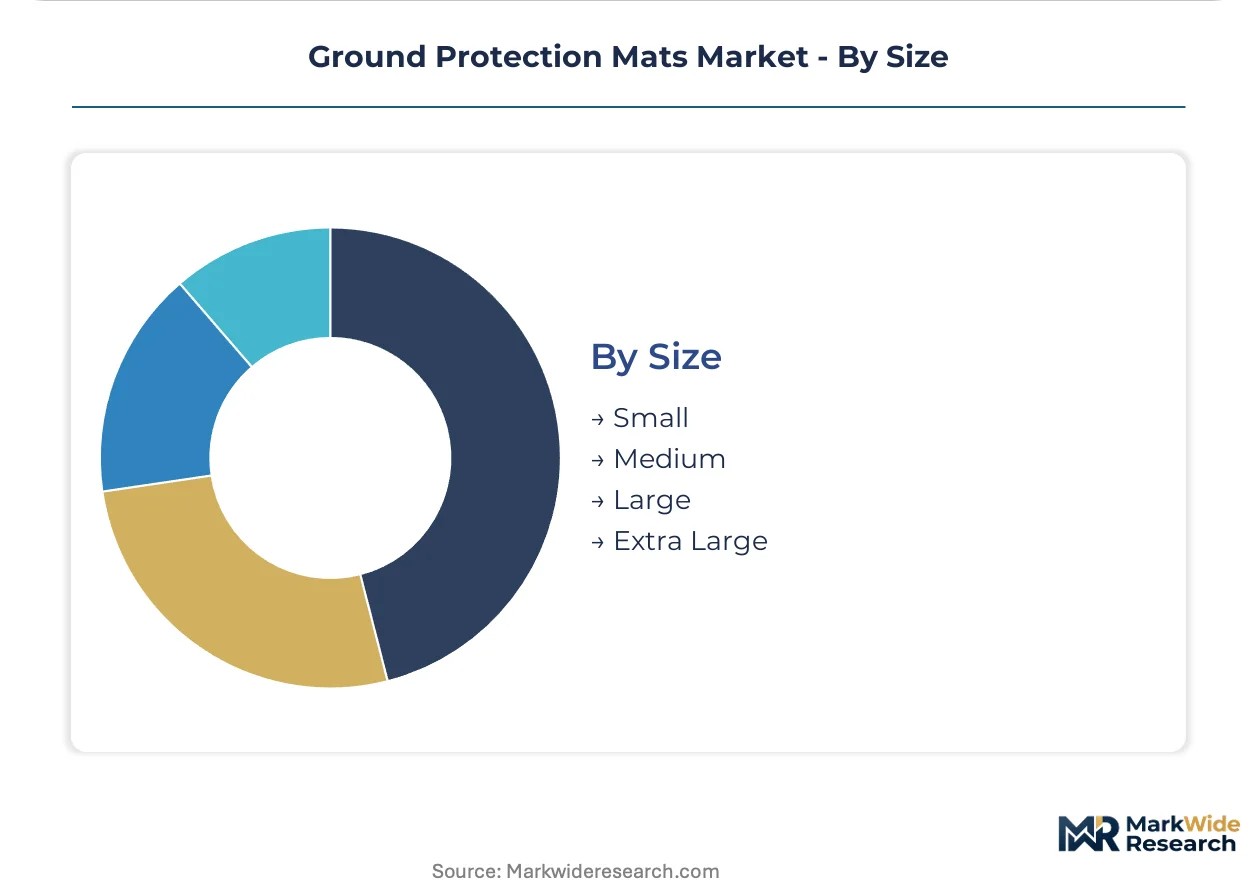
- Large:Standard industrial dimensions balance coverage area with two-worker manual handling. These formats capture the majority of construction and utility project specifications.
- Medium:Reduced dimensions suit confined site access and pedestrian pathway applications. Landscaping and event segments concentrate demand here.
- Small:Compact formats enable single-operator deployment for light equipment and utility vehicle access. Residential contractors favor these for maneuverability.
- Extra Large:Maximized coverage panels reduce seam count for heavy equipment pathways. Crane or forklift deployment requirements limit addressable market but command premium rental rates.
Large formats dominate fleet composition through versatility. Medium sizes are where rental network expansion is concentrating as event and landscaping demand diversifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German wind farm developers specify composite formulations for repeated turbine access cycles, while Texas utility contractors favor rapid-turn plastic mat rentals for solar construction staging. Queensland environmental mandates drive biodegradable wooden mat demand for sensitive terrain access. The EU Green Deal's recycled content thresholds reshape procurement eligibility across European public infrastructure contracts.
United States
Texas utility infrastructure projects demonstrate the steepest specification growth as grid-scale renewable installations accelerate. OSHA workplace safety mandates enforce load-rated surface requirements for heavy equipment operation across construction sites. Houston-area contractors bundle mat provision with logistics management to reduce capital deployment on multi-site solar farm projects.
Germany
North Rhine-Westphalia wind farm developers specify engineered composite formulations for 50-plus deployment cycle scenarios. REACH chemical compliance requirements accelerate automated material traceability systems with blockchain-verified chain-of-custody documentation. Manufacturers with backward integration into recycled polymer sourcing capture public procurement eligibility premiums under EU Green Deal circular economy provisions.
Australia
Queensland conservation projects specify laminated timber mats for sensitive ecological access where biodegradability aligns with environmental commitments. State-level environmental regulations mandate ground protection surfaces for vegetation preservation in temporary roadway applications. Brisbane-area rental networks expand medium-format fleet composition to serve diversifying event and landscaping demand.
United Kingdom
Scottish renewable energy installations require year-round mobilization across soft peat terrain for onshore wind construction. The country's national environmental regulator enforces soil stabilization standards for temporary access infrastructure. Yorkshire-based contractors concentrate deployment logistics coordination for multi-site utility projects demanding synchronized mat repositioning.
Ground Protection Mats Market Competitive Environment
Capability concentration sits with composite formulation specialists; scale advantage sits with rental network operators. The vendor base separates into three functional tiers: integrated polymer recyclers controlling feedstock access, regional fabricators serving project-specific procurement, and rental-service platforms bundling logistics with equipment provision. Dominant competitive moves include backward integration into recycled material sourcing and geographic expansion of redeployment networks.
Among UK-based specialists, Oxford Plastics Systems exemplifies the premium-tier composite formulation segment. Signature Systems Group anchors the North American rental-service platform archetype. Centriforce Products occupies a position within the integrated recycling tier through captive supply of post-consumer polymer feedstock.
| Leading Market Players |
|---|
| Centriforce Products |
| Oxford Plastics Systems |
| Signature Systems Group |
| Groundtrax Systems |
| Newpark Resources |
| Quality Mat Company |
| LuxTek GmbH |
| The Jaybro Group |
| Checkers Safety Group |
| Others |
Value Chain & Pricing Dynamics
Rotterdam-Antwerp freight corridors govern recycled polymer feedstock movements between Northern European recyclers and German composite manufacturers, with bunker fuel surcharges compressing margin buffers and forcing three-tier pricing stratification across premium composite, standard HDPE, and economy rental tiers.
Pricing Analysis
Long-term offtake agreements with utility-scale renewable developers anchor pricing stability for composite mat producers, while spot-market plastic mat rentals fluctuate with construction seasonality. Price differentiation rests on REACH certification grade and backward integration into recycled polymer sourcing. Cost compression in standard HDPE tiers intensifies because post-consumer feedstock volatility transfers directly to contract renegotiations. Event rental operators exhibit highest price sensitivity; wind farm developers prioritize lifecycle cost over upfront expenditure.
Supply Chain Analysis
Tariff exposure between United States and Chinese virgin HDPE suppliers dominates supply chain risk calculus for North American fabricators. Manufacturing gravity centers on Germany, Texas, and Queensland, with each cluster drawing from distinct polymer feedstock pools. Raw material dependencies encompass post-consumer HDPE bales, glass fiber reinforcement, and rubber crumb from tire recycling. Single-source vulnerability concentrates in specialized composite resin formulations. Distribution runs through rental-service platforms that bundle logistics with equipment provision.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket service contracts for mat cleaning, inspection, and redeployment logistics expand faster than hardware sales as infrastructure contractors prioritize outcome-based access solutions over capital deployment.
For Market Incumbents: Pre-empt composite formulation commoditization by deepening captive supply of post-consumer polymer feedstock and accelerating blockchain-verified material traceability investments. Rental network density in Texas and North Rhine-Westphalia serves as the critical defensive moat against regional fabricators winning utility-scale contracts. REACH compliance automation separates procurement-eligible suppliers from margin-compressed alternatives. For New Entrants and Emerging Players: Build out medium-format rental fleets targeting Queensland event and landscaping segments where incumbent coverage remains sparse. This white-space opportunity offers faster payback periods than competing directly in construction-heavy markets. Partner with Brisbane-area logistics coordinators to achieve synchronized redeployment capabilities without proprietary network buildout. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized ground protection mat divisions lacking integrated recycling operations. Long-term viability hinges on circular economy credentialing that secures public procurement eligibility across EU infrastructure spending. Monitor EU carbon-border adjustment mechanism implementation timelines as the inflection signal for competitive cost structure realignment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Polymer Sourcing | Captive HDPE feedstock supply insulates margin predictability against Northern European recycler price volatility. |
| Rental Network Geographic Expansion | Density in Texas utility corridors enables outcome-based contracting that displaces direct purchase arrangements. |
| Blockchain Material Traceability Deployment | Real-time verification satisfies EU Green Deal procurement eligibility thresholds for public infrastructure contracts. |
| Composite Formulation R&D Investment | Engineered fiber-reinforced polymers displace standard HDPE in high-rotation wind farm access scenarios. |
| Aftermarket Service Contract Bundling | Cleaning and redeployment logistics tilt revenue mix toward recurring streams with superior retention economics. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with construction site managers, utility procurement officers, rental fleet operators, and composite manufacturing engineers. Secondary validation drew from EPA stormwater enforcement records, EU public procurement databases, customs trade data for polymer feedstock flows, and SEC filings from listed infrastructure equipment lessors. Bottom-up deployment volume estimates triangulated against top-down infrastructure spending allocations.
Calibration against historical deployment patterns in Texas renewable installations and German wind farm construction anchored growth trajectory assumptions across the analysis window. Segmentation modeling incorporated material formulation tier, end-user industry, application functional requirement, and regional regulatory cluster. CAGRs were derived from slope-intercept analysis of deployment velocity curves, with specific inputs including utility-scale solar pipeline data and REACH compliance cost pass-through coefficients.
Practitioners should monitor recycled polymer price volatility, EU carbon-border adjustment implementation pace, and composite manufacturing yield improvements for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction and Engineering
Pneumatic Conveying Systems Market
Construction and Engineering
Europe HVAC Equipment Market
Construction and Engineering
Torque Limiting Couplings Market
Construction and Engineering
Flushing Systems Market
Construction and Engineering
Grabber Pole Market
Construction and Engineering
Global Pipe and Tube Bending Machine Market
Construction and Engineering
Demolition Equipment Market
Construction and Engineering
Multi Attachment Loaders Market
Construction and Engineering
Concrete Floating Floors System Market
Construction and Engineering
Woodworking Sanders Market
Construction and Engineering
Ultra Hard Material Cutting Machines Market
Construction and Engineering
Elevator Modernization Market
Construction and Engineering
Europe Dehumidifier Market
Construction and Engineering
Mining Drill Market
Construction and Engineering
Yard Scraper Market
Construction and Engineering
US Prefabricated Buildings Market