
 Structural Insulated Panels (Sips) Market | 2026-2036
Structural Insulated Panels (Sips) Market Size, Share, and Industry Trends Forecast 2026-2036
Structural Insulated Panels (Sips) Market Analytics
Market Context
The gap between site-built and panelized construction is narrowing as digital fabrication and CNC cutting advance precision in SIP manufacturing. Kingspan Group leverages its European manufacturing footprint to supply prefabricated building envelopes across multiple continents. Owens Corning sustains R&D intensity in glass wool-core panels that compete with conventional foam systems. PFB Corporation anchors its position in North American residential construction through regional plant networks and builder-direct distribution.
Technical Definition and Segment Structure
Structural insulated panels are composite building elements consisting of a rigid insulating core—typically expanded polystyrene, polyurethane foam, or fiberglass—sandwiched between two structural facings, usually oriented strand board or metal, engineered to carry both axial and transverse loads while providing thermal resistance in a single component. Polystyrene-core products dominate volume shipments due to cost parity with conventional framing, while polyurethane panels command premium positioning in cold storage and industrial envelopes where higher R-values per inch reduce overall wall thickness. Prefabricated delivery mode is expanding fastest as developers seek schedule compression, though custom-fabricated panels retain margin pools in architect-driven commercial projects where irregular openings and aesthetic facings dominate specifications.
Regulatory Framework and Outlook
The EPA energy efficiency standards and ICC building code cycles in the United States, alongside Canada's National Building Code and provincial adaptations in British Columbia and Ontario, are mandating lower U-factors that favor high-performance envelope assemblies. The EU Green Deal and national implementations through France's RE2020 regulation and Germany's Building Energy Act are creating parallel demand pull for factory-insulated panels that guarantee thermal bridge-free construction. Stakeholders must monitor how code adoption timelines in sub-national jurisdictions determine near-term specification shifts versus long-term replacement demand in existing building stock.
Market Dynamics
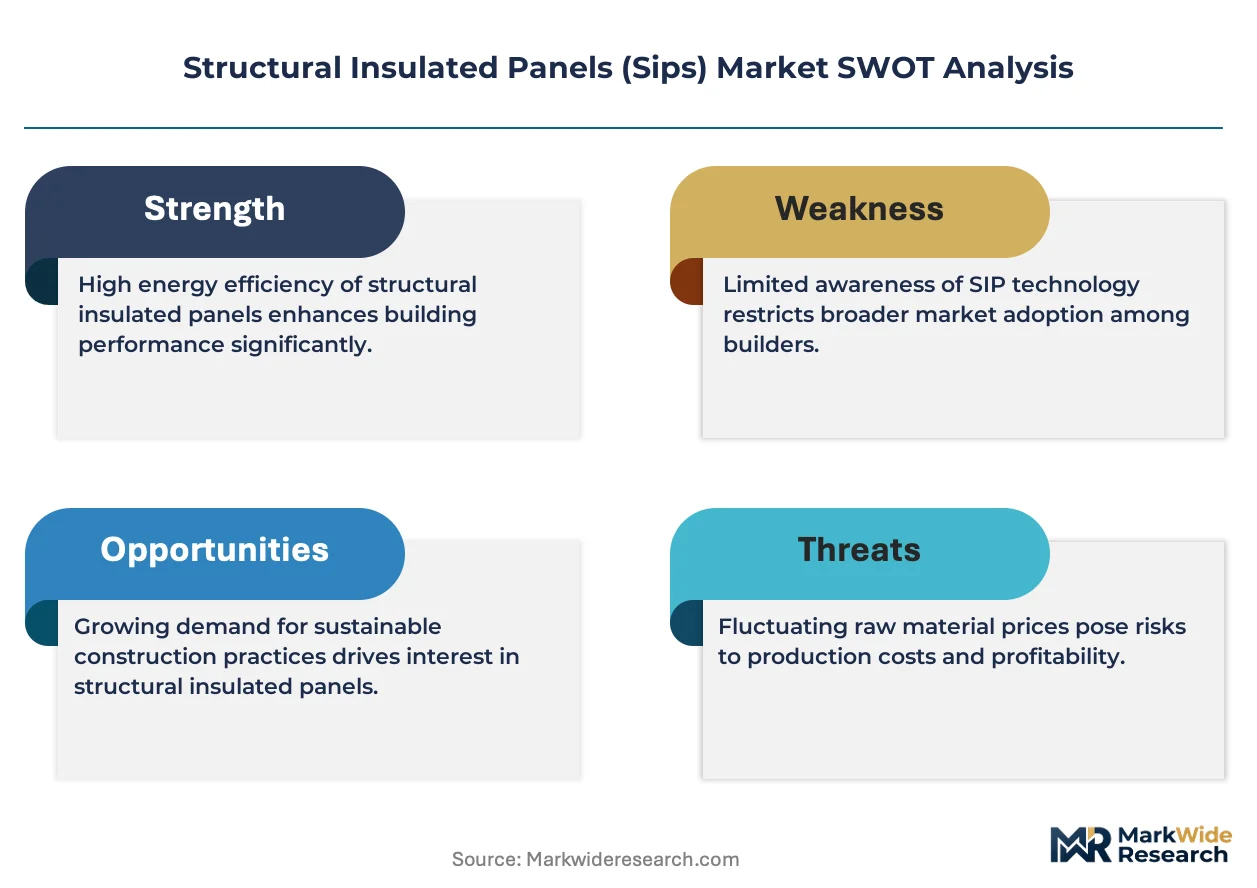
Code-mandated thermal performance thresholds are compressing specification cycles for envelope assemblies, forcing builders to abandon stick-frame methods in favor of factory-insulated panel systems that guarantee blower-door test results.
Growth Catalysts
- EPA energy efficiency mandates:Tightening U-factor requirements for new residential construction in the United States are eliminating conventional framing from net-zero-ready project pipelines.
- Cold storage logistics expansion:Food distribution networks require polyurethane-core panels with R-values exceeding 7 per inch to minimize refrigeration loads in warehouse envelopes.
- Canadian provincial code acceleration:British Columbia and Ontario have adopted building code cycles that mandate passive-house-equivalent envelopes by 2030.
Market Restraints
- OSB facing cost volatility:Structural oriented strand board prices fluctuate with Pacific Northwest timber harvest cycles and mill capacity constraints.
- Foam core chemical feedstock concentration:Polyurethane precursor supply chains cluster around Gulf Coast petrochemical complexes, exposing buyers to hurricane disruption risk.
- Stick-frame substitution persistence:Custom homebuilders in low-code-enforcement jurisdictions retain lumber-yard relationships that undercut panelized delivery on perceived flexibility.
Strategic Opportunities
- EU Green Deal implementation gaps:France's RE2020 regulation and Germany's Building Energy Act are creating demand for thermally bridge-free factory panels that domestic European manufacturers cannot fully supply.
- Mass timber hybrid assemblies:Cross-laminated timber facing bonded to rigid foam cores opens specification in architect-driven commercial projects seeking biogenic material credentials.
- Direct-to-developer distribution platforms:Digital configuration tools that generate CNC cutting files from architectural BIM models bypass traditional lumber-yard channels.
Industry Challenges
- Panel installation crew certification:SIP erection requires specialized training in air-sealing protocols and structural connection detailing that conventional framing crews lack.
- Factory capital intensity:Automated foam-in-place production lines and large-format presses demand eight-figure equipment investments with long depreciation horizons.
- Legacy HVAC sizing conflicts:Building mechanical contractors accustomed to rule-of-thumb load calculations oversize equipment for tight envelopes, degrading performance and client satisfaction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Structural Insulated Panels (Sips) Market |
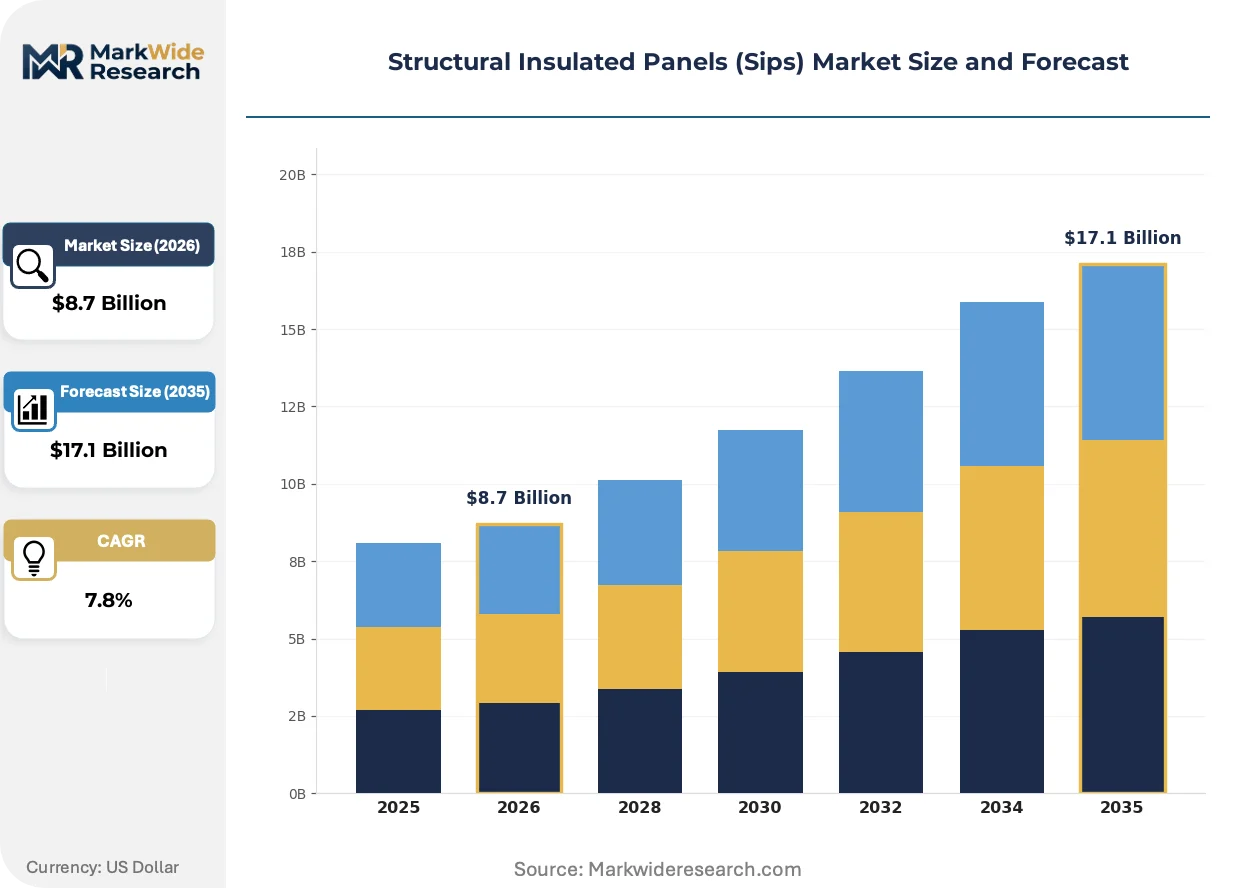
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Polystyrene, Composite, Fiberglass Application: Residential, Commercial, Industrial, Cold Storage Delivery Mode: Manufactured On-Site, Prefabricated, Modular, Custom End User: Contractors, Architects, Builders, Developers |
| Companies Covered | Owens Corning, Kingspan Group, PFB Corporation, Enercept Inc., ACME Panel Company, METECNO, Alubel SpA, Extreme Panel Technologies Inc., Foard Panel Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Structural Insulated Panels (Sips) Market Evolving Landscape
Digital fabrication workflows are collapsing the traditional separation between architectural design and manufacturing execution, enabling mass-customization of panel geometries that were previously hand-cut on site.
Automated CNC routing of expanded polystyrene cores is rendering obsolete the manual hot-wire cutting that introduced dimensional tolerance errors and thermal bridge risks at panel joints. Production facilities in the Pacific Northwest and Upper Midwest have adopted robotic fabrication cells that process architect-supplied BIM files directly into machine instructions. This shift compresses delivery schedules from weeks to days while eliminating the rework costs associated with field-modified panels.
REACH chemical registration requirements in the European Union are restricting legacy blowing agents used in polyurethane foam cores, forcing reformulation toward hydrofluoroolefin alternatives with lower global warming potential. Panel manufacturers serving EU export markets must maintain dual inventory streams or convert entire production lines to compliant chemistries. The regulatory pressure is accelerating most rapidly in France and Germany, where national building codes now reference embodied carbon metrics that disadvantage conventional foam systems.
Developer procurement teams are consolidating envelope specification decisions at the corporate level rather than delegating to project architects, compressing the vendor pool to manufacturers with national distribution networks and standardized warranty terms. This concentration favors producers with multi-plant footprints capable of serving dispersed development pipelines. The pattern is most pronounced among multifamily builders in the United States Sun Belt, where scale economics of repetitive unit types reward panelized delivery over site-built alternatives.
Structural Insulated Panels (Sips) Market Segmentation
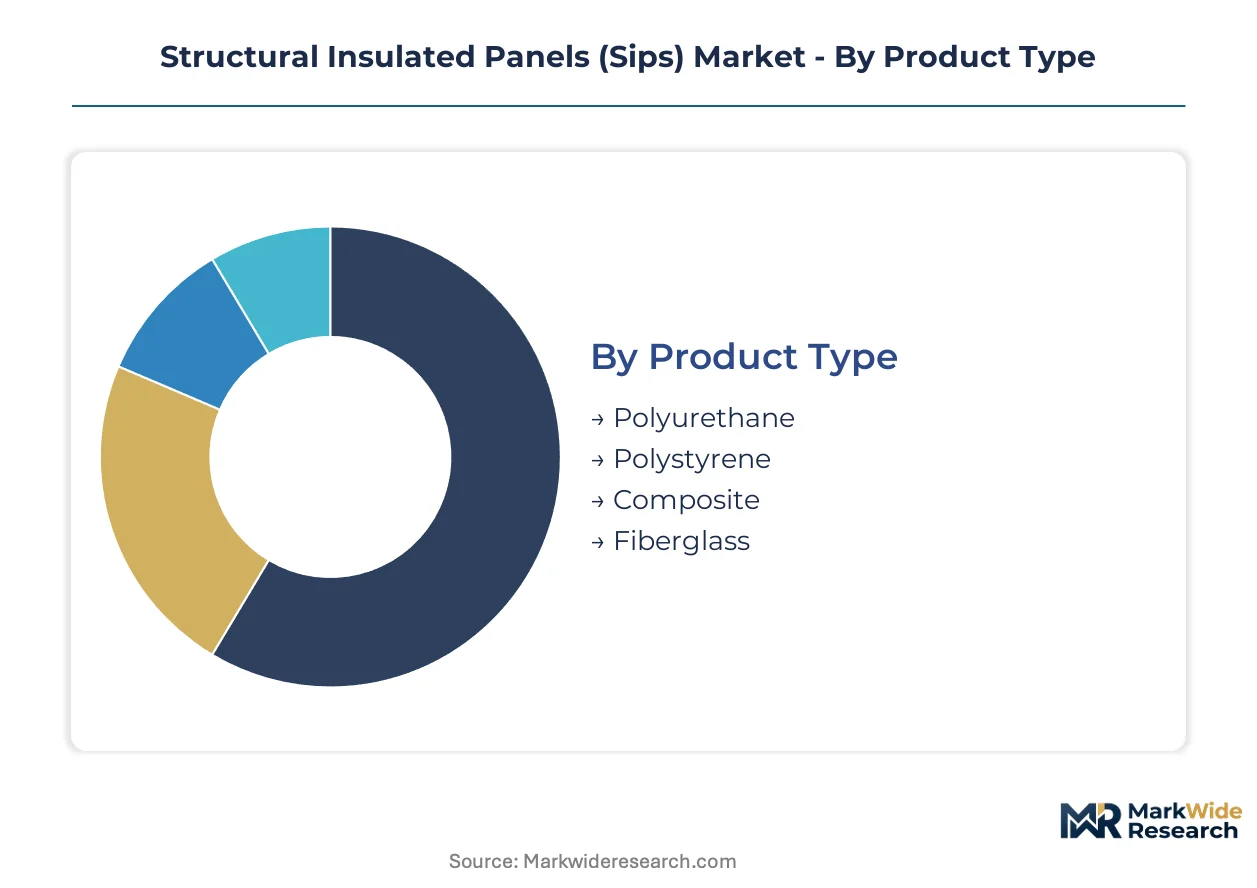
SIP specification varies sharply across core material chemistry, project scale, and procurement channel. Each segmentation dimension carries distinct margin profiles and regulatory exposure that shape manufacturer positioning.
Product Type:
Cost tier stratification in core materials determines thermal performance thresholds and project budget compatibility.
- Polyurethane:Closed-cell foam chemistry achieves R-values exceeding 7 per inch, enabling thinner wall assemblies in cold storage warehouses and passive-house envelopes where space constraints dominate. Demand concentrates in industrial refrigeration facilities across the United States Pacific Northwest and Canadian prairie provinces where energy cost escalation justifies premium material outlays.
- Polystyrene:Expanded and extruded variants deliver cost parity with conventional stick-frame construction while meeting baseline code requirements. Volume shipments flow into tract housing developments in jurisdictions with moderate thermal mandates, particularly where builder-direct distribution channels compress procurement overhead.
- Composite:Hybrid core formulations blend mineral wool or bio-based fillers with synthetic binders to address embodied carbon metrics in EU Green Deal procurement frameworks.
- Fiberglass:Glass wool cores from Owens Corning and competing mineral fiber systems compete in fire-rated commercial assemblies where code mandates non-combustible envelope components.
Polystyrene holds installed capacity. Polyurethane is rotating up the share rankings.
Application:
End-use context dictates panel thickness, facing specification, and connection detailing requirements.
- Residential:Single-family and multifamily builders specify 4.5-inch to 6.5-inch polystyrene-core panels with OSB facings to achieve blower-door targets below 1.0 ACH50. Net-zero-ready project pipelines in British Columbia and Ontario are eliminating conventional framing from subdivision developments.
- Commercial:Architect-driven office and retail envelopes demand custom panel geometries with metal or cementitious facings for aesthetic integration. Irregular opening patterns and curtain-wall interfaces reward CNC-fabricated delivery over field-modified alternatives.
- Industrial:Manufacturing facilities and warehouse envelopes prioritize speed of enclosure to compress construction schedules and accelerate tenant occupancy.
- Cold Storage:Refrigerated distribution centers specify polyurethane-core panels with R-30+ roof assemblies to minimize mechanical refrigeration loads in 24/7 operations.
Residential commands volume leadership. Cold Storage is climbing the fastest as food logistics networks expand.
Delivery Mode:
Supply chain configuration determines lead times, dimensional precision, and field labor requirements.
- Manufactured On-Site:Mobile production units deploy foam-in-place equipment directly to large-scale project sites, eliminating transportation costs for remote industrial developments in northern Canada and Alaska where road access constrains prefabricated panel logistics.
- Prefabricated:Factory-produced panels with pre-cut openings and integrated electrical chases compress field erection schedules from weeks to days. Digital BIM-to-CNC workflows enable mass-customization that was previously hand-cut on site.
- Modular:Complete volumetric units with pre-installed SIP envelopes ship as finished building segments for workforce housing and hospitality prototypes.
- Custom:One-off architectural commissions with irregular geometries retain premium margin pools despite longer production cycles and higher engineering overhead.
Prefabricated dominates shipment value. Modular is gaining share fastest among multifamily developers seeking repeatable unit types.
End User:
Customer type shapes specification authority, warranty requirements, and channel access preferences.
- Contractors:General and specialty trade contractors with SIP installation certification command premium labor rates in markets where trained crews remain scarce. Their specification influence peaks in design-build delivery models common in industrial and cold storage construction.
- Architects:Design professionals drive panel selection in institutional and commercial projects where envelope aesthetics and thermal bridge detailing determine professional liability exposure. BIM-native specification tools are collapsing traditional separation between design intent and manufacturing execution.
- Builders:Production homebuilders consolidate envelope decisions at corporate procurement offices, compressing vendor pools to manufacturers with national distribution networks and standardized warranty terms.
- Developers:Multifamily and commercial real estate developers evaluate SIP systems through total project cost and schedule compression metrics rather than per-square-foot material pricing alone.
Builders anchor procurement volume. Developers are ascending fastest as corporate-level envelope standardization spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in structural insulated panels track manufacturing capacity concentration against code-stringent demand centers. The United States maintains a modest trade surplus in prefabricated panels, shipping factory-insulated envelopes to Canadian developers facing British Columbia's accelerated building code timelines while importing specialty polyurethane-core systems from European suppliers for cold storage projects.
United States
Net-zero-ready housing pipelines in the Pacific Northwest and Sun Belt multifamily corridors absorb prefabricated panel volumes at scale. EPA energy efficiency mandates for new residential construction tighten U-factor thresholds that eliminate conventional stick-frame methods from compliant projects. Manufacturing clusters in the Upper Midwest leverage robotic CNC fabrication cells to serve dispersed development pipelines with compressed delivery schedules.
Canada
British Columbia and Ontario building code cycles mandate passive-house-equivalent envelopes by 2030, eliminating specification flexibility for conventional framing. Provincial adaptations of the National Building Code accelerate thermal performance requirements faster than federal timelines. Panel manufacturers anchor production networks across the Prairie Provinces to supply northern remote industrial developments where on-site mobile production units circumvent road access constraints.
Germany
The Building Energy Act drives specification of thermally bridge-free factory panels in residential and commercial new construction. REACH chemical registration requirements restrict legacy blowing agents, forcing reformulation toward hydrofluoroolefin alternatives with lower global warming potential. Manufacturing concentration in Baden-Württemberg and Bavaria serves domestic demand while supplying export markets across the EU Green Deal implementation zone.
France
RE2020 regulation embeds embodied carbon metrics that disadvantage conventional foam systems in public procurement and large-scale development. National building codes now reference lifecycle carbon performance, favoring composite-core panels with mineral wool or bio-based fillers. Production facilities in the Auvergne-Rhône-Alpes cluster export thermally optimized envelopes to neighboring jurisdictions with aligned regulatory timelines.
United Kingdom
Offsite construction targets in government housing programs compress specification cycles toward factory-insulated panel systems. The Midlands and North England manufacturing bases supply London and Southeast development corridors where land values reward schedule compression. Building regulations tightening fabric energy efficiency standards align with EU-adjacent thermal performance trajectories despite post-Brexit regulatory divergence.
Structural Insulated Panels (Sips) Market Competitive Landscape
On the supply side, the industry is consolidating around manufacturers with multi-plant footprints capable of serving dispersed development pipelines through standardized warranty terms. Production scale and CNC fabrication capability separate national distributors from regional fabricators dependent on manual hot-wire cutting. Three archetypes dominate: integrated building materials conglomerates with cross-continental manufacturing networks, mid-cap specialists focused on polyurethane-core industrial envelopes, and regional fabricators serving builder-direct residential channels. Competitive moves center on capacity expansion in code-accelerating jurisdictions and strategic partnerships with multifamily developers seeking envelope standardization.
Among building materials conglomerates, Kingspan Group and Owens Corning occupy positions that exemplify scale-driven competitive advantage. Kingspan leverages its European manufacturing footprint to supply prefabricated building envelopes across multiple continents, while Owens Corning sustains research intensity in glass wool-core panels that compete with conventional foam systems. Mid-cap specialists including PFB Corporation anchor North American residential construction through regional plant networks and builder-direct distribution channels that compress procurement overhead for production homebuilders.
| Leading Market Players |
|---|
| Owens Corning |
| Kingspan Group |
| PFB Corporation |
| Enercept Inc. |
| ACME Panel Company |
| METECNO |
| Alubel SpA |
| Extreme Panel Technologies Inc. |
| Foard Panel Inc. |
| Others |
Value Network & Pricing Analysis
The Upper Midwest manufacturing cluster anchors North American panel capacity, and its automated CNC fabrication density translates directly into pricing leverage over regional fabricators still dependent on manual hot-wire cutting. Cost compression in polystyrene-core residential tiers intensifies as these high-throughput facilities absorb OSB facing volatility through volume commitments to Pacific Northwest mills.
Pricing Analysis
Industrial OEM buyers anchor project-based pricing structures across cold storage and commercial envelope segments. Three-tier pricing stratification separates polyurethane premium systems from polystyrene standard offerings and economy-grade site-fabricated alternatives. Price differentiation rests on R-value certification tiers and geographic delivery radius from manufacturing hubs. Margins are tightening in residential polystyrene tiers due to builder-direct procurement consolidation, while cold storage buyers show lowest price sensitivity given energy cost recovery timelines.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Gulf Coast petrochemical complexes sustain polyurethane precursor flows despite hurricane exposure. Manufacturing concentrates in the United States, Canada, and Germany, with each hub serving distinct regulatory compliance zones. Raw material dependencies center on oriented strand board from Pacific Northwest timber operations, isocyanate and polyol feedstocks from Gulf Coast chemical complexes, and glass wool fibers from Owens Corning's integrated operations. Tariff exposure on Canadian softwood lumber imports creates structural cost risk. Distribution runs through builder-direct channels for residential volume and specialized cold-storage contractors for industrial premium tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified SIP installation crews remain scarce across North American construction markets, and this capability gap constrains envelope quality at scale regardless of manufacturing capacity expansion. The shortage of trained erection teams capable of executing blower-door-compliant air-sealing protocols creates a binding bottleneck on market development.
For Market Incumbents: Pre-empt margin erosion in residential polystyrene tiers by anchoring backward integration into OSB facing production or securing long-term fiber supply agreements with British Columbia timber operators. Add CNC fabrication capacity in Ontario to capture British Columbia and Ontario code acceleration demand. Defend against emerging mass-timber hybrid entrants by accelerating R&D in bio-based core formulations that satisfy EU Green Deal embodied carbon metrics.
For New Entrants and Emerging Players: Pursue cold storage logistics networks in the United States Pacific Northwest and Canadian prairie provinces where polyurethane premium pricing sustains newcomer margins. Target manufactured on-site delivery mode for remote northern Canadian industrial developments where road access constraints eliminate prefabricated competition. Lead with mobile production units and crew certification training programs to bypass established distribution relationships.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compression play because code-mandated thermal performance thresholds eliminate specification alternatives across successive building code cycles. Acquisition targets should display multi-plant geographic footprints and established builder-direct channel control. The signal to watch is provincial adoption timelines for passive-house-equivalent envelope mandates, which determine near-term demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Adds CNC fabrication lines in Ontario to serve British Columbia's accelerated code timelines. |
| Backward Integration | Captures OSB facing supply through timber agreements with Pacific Northwest mills. |
| Green Manufacturing Transition | Reformulates polyurethane cores to hydrofluoroolefin blowing agents for EU REACH compliance. |
| Long-term Supply Agreement | Locks isocyanate precursor flows from Gulf Coast petrochemical complexes. |
| Joint Venture | Partners mass timber producers with foam core specialists for architect-driven commercial projects. |
Research Methodology
Desk research of building code adoption timelines, EPA energy efficiency mandate documentation, and customs trade data preceded structured interviews with SIP manufacturing executives, residential production homebuilder procurement officers, cold storage facility developers, certified panel installation contractors, and provincial building code officials. Secondary validation drew from National Building Code of Canada publications, ICC International Code Council cycle documentation, EU Green Deal implementation trackers, and SEC filings from publicly traded building materials conglomerates. Bottom-up shipment volume estimates triangulated against top-down construction permit data across the analysis window.
Assumptions held fixed include current EPA U-factor mandate trajectories and British Columbia's passive-house-equivalent envelope deadline; scenarios varied Canadian provincial adoption speed and EU REACH chemical restriction enforcement intensity. The analytical framework modeled core material chemistry, project application type, delivery mode configuration, and end-user procurement channel across the projection horizon. CAGRs derived from segment-level volume build-ups incorporating construction permit forecasts and panel penetration rate assumptions. Industry-specific inputs included OSB price indices from Pacific Northwest timber markets and polyurethane precursor supply disruption frequencies from Gulf Coast hurricane patterns.
Macroeconomic conditions sit as an overlay; deviation in residential construction starts, commercial real estate financing availability, or energy cost escalation would shift the trajectory. The forecasts reflect these documented assumptions; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Waterproofing Systems Market
Building & Construction Materials
India Pipe Fabrication Market
Building & Construction Materials
Global Screw Piles Market
Building & Construction Materials
Roof Window Market
Building & Construction Materials
Sliding Bearing Market
Building & Construction Materials
Drinking Water Pipe Repair Market
Building & Construction Materials
Reclaimed Lumber Market
Building & Construction Materials
Foldable Houses Market
Building & Construction Materials
Elevated Water Storage Tanks Market
Building & Construction Materials
European Cross-Laminated Timber Market
Building & Construction Materials
Autoclaved Aerated Concrete (AAC) Blocks Market
Building & Construction Materials
Magnesium Oxide Boards Market
Building & Construction Materials
Gulf Corporation Council Cement Market
Building & Construction Materials
North America Concrete Conditioner Market
Building & Construction Materials
Fiber Cement Rainscreen Panels Market
Building & Construction Materials
Particleboard Market