
 Prefabricated Homes Market | 2026-2036
Prefabricated Homes Market Size, Share, and Industry Trends Forecast 2026-2036
Prefabricated Homes Market Analytics
Buyer concentration among large-scale rental-housing operators is consolidating demand for repeatable, code-compliant dwelling units at volume. Clayton Homes leverages captive retail financing and vertical manufacturing depth to anchor the US manufactured-housing base. Sekisui House sustains precision-engineered steel-frame systems that dominate Japanese prefabricated supply. Skyline Champion Corporation competes across both manufactured and modular categories with distributed plant coverage spanning North American population corridors.
Prefabricated homes are dwelling units produced in factory-controlled environments where structural components or complete modules are assembled under covered conditions, then transported to permanent sites for installation on foundations; wall panels typically achieve tighter dimensional tolerances than site-built equivalents, and whole-module construction compresses weather-dependent scheduling risk. Modular homes occupy the premium tier of factory-built housing, commanding higher margins through customization flexibility and conventional mortgage eligibility. Panelized systems lead in single-family detached applications where local crews complete on-site assembly. Shipping container conversions remain nascent in most jurisdictions, constrained by zoning ambiguity and lender discomfort with non-standard collateral.
US HUD Code enforcement and state-level modular-program administration jointly determine product eligibility for federal mortgage insurance, directly shaping manufacturer design priorities. Japan's Ministry of Land, Infrastructure, Transport and Tourism enforces seismic-grade certification that elevates engineering standards for prefabricated structures in earthquake zones. Stakeholders must monitor evolving local zoning amendments that alternately restrict or permit factory-built housing density, as these municipal decisions increasingly determine addressable market footprint regardless of federal standardization progress.
Market Dynamics
The US Department of Housing and Urban Development's tightened energy-efficiency standards are forcing manufacturers to retool assembly lines for higher thermal performance, compressing margins for smaller fabricators while advantaging scaled producers with captive engineering resources.
Growth Catalysts
- First-time buyer demand surge:Affordability pressures in conventional housing markets are redirecting entry-level purchasers toward manufactured alternatives eligible for FHA Title I financing.
- Sun Belt permitting velocity:Local jurisdictions across Texas, Florida, and Arizona are streamlining modular approval timelines, compressing project delivery schedules by months versus site-built equivalents.
- Steel-frame seismic engineering:Japanese precision manufacturing protocols are migrating into North American supply chains, elevating structural resilience ratings for factory-built units in earthquake-prone zones.
Market Restraints
- Lumber and OSB input volatility:Commodity price swings for engineered wood products compress fabrication margins unpredictably, forcing producers to absorb costs or risk volume erosion.
- Zoning fragmentation:Municipal ordinances in high-density coastal municipalities restrict factory-built housing density, capping addressable footprint regardless of federal standardization progress.
- Site-built substitution:Conventional stick-frame construction retains lender preference and buyer familiarity in markets where land costs dominate total project economics.
Strategic Opportunities
- Underserved rural corridors:Counties across the US Great Plains and Mountain West exhibit manufactured-housing penetration gaps where land abundance and limited local construction labor favor factory delivery models.
- Green building certification tailwinds:ENERGY STAR and LEED pathways for modular structures unlock utility rebate streams and carbon-accounting premiums in environmentally regulated jurisdictions.
- Cross-laminated timber convergence:Mass-timber engineering intersects with prefabrication to create carbon-sequestering structural systems for mid-rise multifamily applications previously reserved for concrete and steel.
Industry Challenges
- Skilled installation labor scarcity:Factory output capacity outpaces availability of certified set crews capable of completing foundation anchoring and utility tie-ins to code.
- HUD Code compliance timelines:Design approval bottlenecks at the federal level delay product launches by quarters, eroding first-mover advantage for innovation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prefabricated Homes Market |
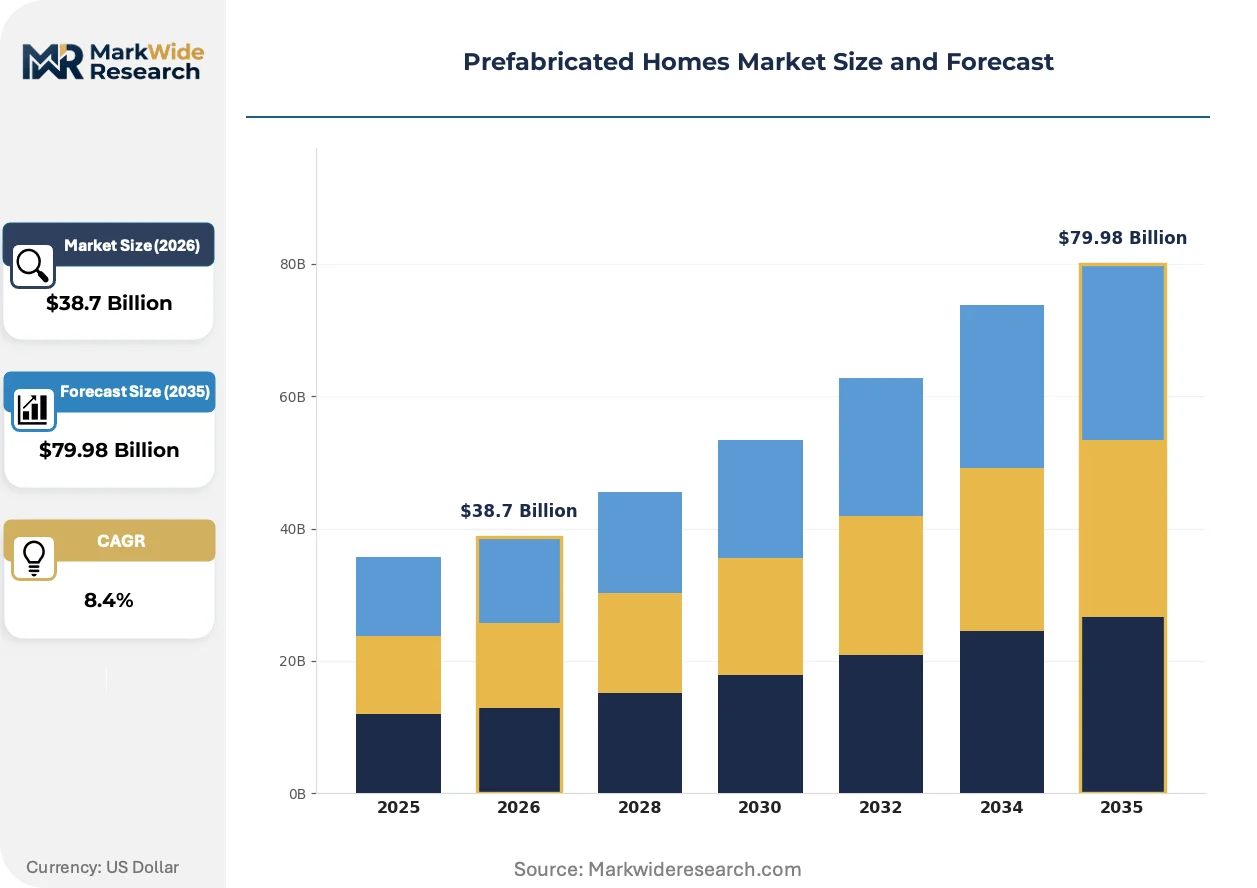
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Homes, Panelized Homes, Pre-Cut Homes, Shipping Container Homes Construction Method: Wood Framing, Steel Framing, Concrete Modules, Hybrid Systems End User: First-Time Buyers, Investors, Vacation Home Owners, Developers Distribution Channel: Direct Sales, Online Platforms, Retail Outlets, Construction Firms |
| Companies Covered | Sekisui House, Blu Homes, Clayton Homes, Plant Prefab, Connect Homes, Skyline Champion Corporation, Method Homes, Boxabl Inc., Cavco Industries Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prefabricated Homes Market Evolving Landscape
Digital fabrication and advanced building science are compressing the performance gap between factory-built and site-built housing, while regulatory pressure and capital flows restructure competitive positioning across the value chain.
Building information modeling paired with automated CNC cutting is consolidating design-to-delivery workflows in panelized manufacturing. Single-family detached builders are adopting these systems at accelerating rates to offset skilled carpentry shortages. The technology is consolidating supplier tiers as fabricators internalize engineering and procurement functions previously outsourced to fragmented trade contractors.
The US Department of Housing and Urban Development's 2024 thermal envelope amendments are mandating blower-door testing thresholds for all factory-built units. Manufacturers must redesign wall assemblies and HVAC integration to meet specific air-leakage limits. Modular producers targeting conventional mortgage markets are responding fastest, as their buyer base demands energy-cost predictability and resale value protection.
Institutional rental-housing operators are consolidating procurement around repeatable dwelling-unit specifications, displacing fragmented single-project contracting. Large-scale developers are establishing direct supplier relationships with modular fabricators, bypassing traditional general-contractor intermediaries. This concentration is most visible across the US Sun Belt, where REITs and build-to-rent platforms are scaling asset deployment through factory-built velocity.
Prefabricated Homes Market Segmentation
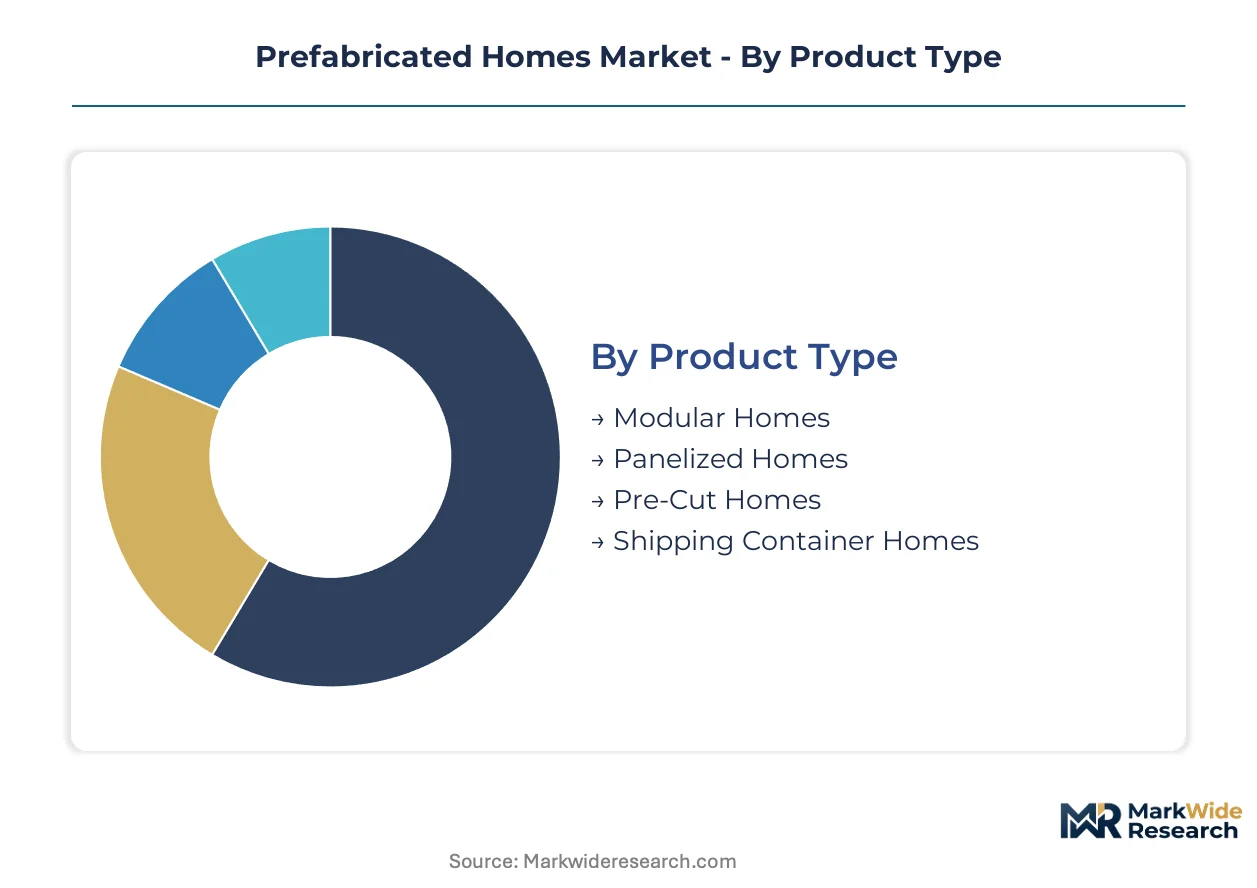
Segmentation in prefabricated housing reveals how manufacturing depth, material science, and buyer economics stratify addressable demand. Each axis exposes different margin profiles, regulatory exposure, and installation complexity that reshape competitive positioning across factory-built supply chains.
Product Type:
Engineering sophistication and on-site completion requirements differentiate factory-built categories along the value chain.
- Modular Homes:Complete three-dimensional modules are produced in climate-controlled facilities with finished interiors, then crane-set onto permanent foundations. Demand concentrates among first-time buyers in Texas and Florida where FHA Title I financing eligibility and conventional mortgage access reduce borrowing friction.
- Panelized Homes:Precut wall, floor, and roof assemblies ship flat-packed for local crew assembly, compressing weather-dependent scheduling risk. Penetration is deepest in single-family detached applications across the US Mountain West where skilled carpentry scarcity and land abundance favor hybrid delivery models.
- Pre-Cut Homes:Component packages arrive with numbered framing members for site assembly by owner-builders or small contractors. Demand clusters in rural Great Plains counties with limited local construction labor.
- Shipping Container Homes:Repurposed intermodal containers are modified off-site for residential occupancy, constrained by municipal zoning ambiguity and lender collateral discomfort in most US jurisdictions.
Mature deployment sits with Panelized Homes. Newer deployment is concentrated in Modular Homes.
Construction Method:
Material selection governs seismic resilience, thermal performance, and transportation logistics across manufacturing networks.
- Wood Framing:Dimensional lumber and engineered wood products dominate North American factory output, though OSB and lumber input volatility compress margins unpredictably. The category anchors US Sun Belt production where established supplier relationships and familiar code approval pathways reduce design-cycle friction.
- Steel Framing:Cold-formed steel studs and precision-welded structural frames enable seismic-grade certification and dimensional stability. Japanese engineering protocols are migrating into California and Pacific Northwest supply chains where earthquake resilience ratings command buyer premiums.
- Concrete Modules:Precast concrete wall and floor systems deliver fire resistance and acoustic separation for mid-rise multifamily applications. Deployment concentrates in urban infill projects where factory curing eliminates weather delays.
- Hybrid Systems:Combinations of wood, steel, and engineered materials optimize strength-to-weight ratios for specific structural loads. Adoption is accelerating in custom modular projects where performance specifications exceed single-material capabilities.
Volume leadership belongs to Wood Framing. Steepest expansion trajectory is visible in Steel Framing.
End User:
Buyer economics and holding-period expectations segment demand across financing channels and customization requirements.
- First-Time Buyers:Entry-level purchasers facing conventional housing affordability pressures are redirecting toward manufactured alternatives with FHA-insured financing. This cohort is expanding most quickly across the US Sun Belt where land costs remain manageable relative to total project economics.
- Investors:Institutional rental-housing operators and build-to-rent platforms are consolidating procurement around repeatable dwelling-unit specifications. REITs in Texas and Arizona are establishing direct supplier relationships with modular fabricators, bypassing traditional general-contractor intermediaries.
- Vacation Home Owners:Seasonal residence buyers prioritize accelerated delivery timelines and simplified permitting in recreational markets. Demand clusters in Florida and Arizona where modular velocity compresses time-to-occupancy.
- Developers:Large-scale residential developers leverage factory-built units for workforce housing and master-planned community phases. Procurement concentrates in jurisdictions with streamlined modular approval timelines.
Procurement consolidation is most advanced among Investors. Fragmented demand persists with Vacation Home Owners.
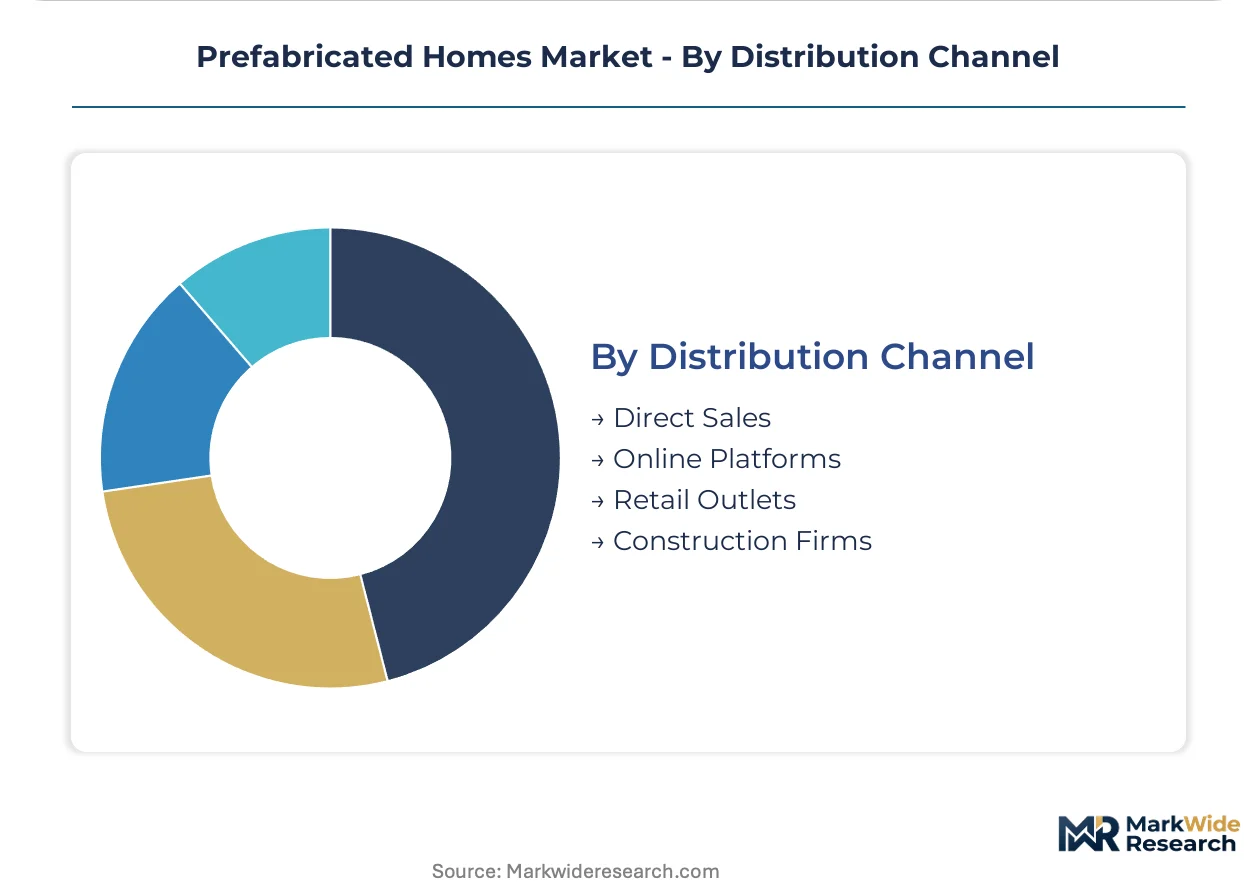
Distribution Channel:
Channel structure determines margin capture, buyer education burdens, and installation coordination responsibilities.
- Direct Sales:Manufacturers maintain captive retail networks and commissioned sales staff who shepherd buyers through financing, customization, and site preparation. Clayton Homes anchors this model with vertically integrated manufacturing and lending operations across the US Southeast.
- Online Platforms:Digital configurators and remote sales processes are emerging for standardized product lines, though foundation and utility coordination still require local presence. Penetration remains limited to pre-cut and container categories with simpler specification requirements.
- Retail Outlets:Independent dealers maintain model home centers where buyers evaluate finishes and floor plans before factory order. The channel dominates manufactured housing distribution in rural markets where manufacturer presence is sparse.
- Construction Firms:General contractors and regional builders source panelized or modular components as subcontracted scope within larger site-built projects. This channel is gaining share in single-family detached construction where skilled labor scarcity favors hybrid delivery.
Established infrastructure supports Retail Outlets. Channel investment is concentrating in Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
First-time buyers in the United States Sun Belt are concentrating demand for factory-built units as conventional housing affordability erodes. Japan's precision-engineered steel-frame protocols are migrating into North American supply chains. Germany's modular fabricators are expanding cross-laminated timber capacity for mid-rise multifamily applications.
United States
Texas and Florida municipalities are streamlining modular approval timelines, compressing project delivery by months versus site-built equivalents. The Department of Housing and Urban Development's 2024 thermal envelope amendments mandate blower-door testing thresholds for all factory-built units. Clayton Homes anchors manufacturing and captive retail financing operations across the Southeast, while Skyline Champion Corporation maintains distributed plant coverage spanning Sun Belt population corridors.
Japan
Seismic-grade engineering standards elevate prefabricated structural resilience ratings in earthquake-prone zones. The Ministry of Land, Infrastructure, Transport and Tourism enforces certification protocols that govern factory-built housing design priorities. Sekisui House sustains precision-engineered steel-frame systems that dominate domestic supply and are migrating into California and Pacific Northwest markets.
Germany
Cross-laminated timber convergence with prefabrication creates carbon-sequestering structural systems for mid-rise multifamily applications. The EU Green Deal and national building energy codes tighten thermal performance thresholds for factory-assembled units. Industrial clusters in Bavaria and Baden-Württemberg concentrate mass-timber engineering expertise serving Central European residential developers.
Canada
Rural counties across the Prairie Provinces exhibit manufactured-housing penetration gaps where land abundance and limited local construction labor favor factory delivery models. Health Canada and the PMRA regulate material emissions standards for residential construction products. Ontario and British Columbia municipalities are amending zoning ordinances to permit higher-density factory-built housing in infill locations.
Australia
Skilled installation labor scarcity in remote mining and agricultural regions drives demand for complete modular dwelling units. The Therapeutic Goods Administration does not regulate building products; state-level building codes govern factory-built housing approval pathways. Queensland and Western Australia project corridors concentrate demand for accelerated delivery timelines in resource-extraction workforce housing.
Prefabricated Homes Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue technology-enabled customization and alternative material platforms. The vendor base stratifies across three tiers: vertically integrated manufacturers with captive financing, precision-engineered specialists serving seismic-grade markets, and venture-backed entrants advancing automated fabrication. Consolidation pressure favors scaled producers with in-house engineering resources capable of absorbing HUD Code compliance costs. Dominant competitive moves include geographic expansion through distributed plant networks and strategic partnerships with institutional rental-housing operators.
Among Japanese precision-engineered specialists, Sekisui House exemplifies seismic-grade steel-frame manufacturing protocols migrating into North American supply chains. Within the US vertically integrated tier, Clayton Homes anchors captive retail financing and manufacturing depth across the Southeast. Skyline Champion Corporation occupies a position spanning both manufactured and modular categories with distributed plant coverage. These three fabricators represent distinct archetypes: precision-engineered seismic resilience, vertically integrated mass-market penetration, and cross-category operational flexibility.
| Leading Market Players |
|---|
| Sekisui House |
| Blu Homes |
| Clayton Homes |
| Plant Prefab |
| Connect Homes |
| Skyline Champion Corporation |
| Method Homes |
| Boxabl Inc. |
| Cavco Industries Inc. |
| Others |
Value Network & Pricing Analysis
Certified set crew scarcity across the US Mountain West and Great Plains widens pricing-tier spreads between premium modular and economy manufactured units, as labor-cost differentials compound transportation logistics and foundation complexity.
Pricing Analysis
Volume leadership in manufactured housing compresses margins at the economy tier while modular customization sustains premium returns. Three-tier pricing structure across premium, standard, and economy levels separates FHA Title I-eligible units from conventional mortgage-grade modules and luxury custom builds. Cost compression in economy manufactured units is intensifying because lumber and OSB input volatility forces absorption trade-offs. First-time buyers exhibit highest price sensitivity; institutional rental-housing operators demonstrate lowest sensitivity due to holding-period economics and scale procurement.
Supply Chain Analysis
Single-source vulnerability sits with engineered wood product suppliers concentrated in the Pacific Northwest and Southeast US. Raw material flows draw from Canadian softwood lumber, domestic OSB mills, and Japanese cold-formed steel imports. Tariff exposure on Canadian lumber and steel inputs elevates cost unpredictability for cross-border supply chains. Distribution runs through vertically integrated manufacturer retail networks, independent dealer model home centers, and direct procurement relationships with institutional developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where HUD Code compliance timelines and retooling costs for energy-efficiency standards force smaller fabricators toward exit or acquisition.
For Market Incumbents: Lock in engineering talent pools and captive financing capacity as defensive moats against venture-backed entrants advancing automated fabrication. Absorb federal design-approval bottlenecks through in-house regulatory affairs teams to sustain first-mover advantage on thermal envelope innovations. Deepen backward integration into panelized component manufacturing to offset skilled installation labor scarcity.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in custom modular offers white-space targeting for technology-enabled configurators with accelerated delivery timelines. Underserved rural corridors across the Prairie Provinces and US Great Plains present the most penetrable geography given land abundance and limited local construction labor. Pursue direct-to-developer go-to-market positioning that bypasses traditional general-contractor intermediaries.
For Investors and Strategic Acquirers: Re-rating potential sits with precision-engineered steel-frame specialists given seismic-grade certification migration into California and Pacific Northwest markets. Long-term viability favors fabricators with demonstrated HUD Code navigation capabilities and distributed plant coverage across Sun Belt population corridors. Watch for municipal zoning amendments permitting higher-density factory-built housing as the inflection indicator for addressable market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Retail Financing Expansion | Clayton Homes anchors borrower access through vertical lending operations across the Southeast. |
| Seismic-Grade Engineering Certification | Sekisui House protocols migrate into North American supply chains for earthquake resilience premiums. |
| Distributed Plant Network Coverage | Skyline Champion Corporation spans Sun Belt corridors to compress delivery timelines versus site-built. |
| Cross-Laminated Timber Capacity Buildout | German fabricators in Bavaria serve Central European carbon-sequestering mid-rise multifamily demand. |
| Direct REIT Procurement Relationships | Texas and Arizona build-to-rent platforms bypass general-contractor intermediaries for repeatable units. |
Research Methodology
Multi-period observation of permitting velocity, financing origination volumes, and factory shipment data anchored the trend analysis, supplemented by interviews with modular fabricator executives, HUD Code compliance officers, institutional rental-housing procurement directors, and certified set crew contractors. Secondary validation drew from US Census Bureau manufactured housing shipments, Department of Housing and Urban Development regulatory filings, FHA Title I loan performance data, and municipal zoning ordinance amendments. Bottom-up plant capacity assessments and top-down housing affordability indices were triangulated to cross-check demand estimates.
The input-output matrix framed projections across product type, construction method, end-user archetype, and distribution channel dimensions throughout the forecast period. CAGRs were derived from segmented growth rate differentials applied to base-year estimates. Industry-specific forecast inputs included Sun Belt population migration patterns, lumber futures price volatility bands, and ENERGY STAR certification adoption curves.
Inputs from HUD regulatory filings and Census shipment data were available through the study window; gaps in real-time municipal zoning amendment tracking introduce uncertainty bands around addressable market footprint estimates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Construction
Global Manufactured Homes Market
Residential Construction
Europe Residential Construction Market
Residential Construction
Residential Roofing Market
Residential Construction
UK Residential Construction Market
Residential Construction
Asia-Pacific Prefabricated Housing Market
Residential Construction
Global Prefabricated Housing Market
Residential Construction
Saudi Arabia Manufactured Homes Market
Residential Construction
Canada Manufactured Homes Market
Residential Construction
Bathroom Remodeling Market
Residential Construction
Austria Prefabricated Housing Market
Residential Construction
US Residential Construction Market
Residential Construction
Residential Construction Market
Residential Construction
Canada Residential Construction Market
Residential Construction
Saudi Arabia Residential Construction Market
Residential Construction
North America Prefabricated Housing Market
Residential Construction
Outdoor Living Structure Market