
 Latex Caulk Market | 2026-2036
Latex Caulk Market Size, Share, and Industry Trends Forecast 2026-2036
Latex Caulk Market Foresight
North American petrochemical feedstock availability is decoupling from Asian supply chains, reshaping regional latex emulsion economics. Dow Inc. leverages its integrated acrylic monomer operations to secure cost-advantaged feedstock positions. Henkel AG & Co. KGaA anchors its caulk portfolio through specialized distribution partnerships with big-box retailers. H.B. Fuller Company differentiates via adhesive-sealant hybrid formulations that blur traditional product boundaries.
Latex caulk comprises water-based acrylic polymer emulsions, typically containing 40-60% solids by volume, that cure through ambient moisture evaporation to form flexible, paintable seals. Manufacturers formulate these products with biocides, plasticizers, and rheology modifiers to achieve Shore A hardness values between 15 and 35 for joint movement accommodation. Interior formulations dominate volume shipments, while exterior grades command premium positioning due to UV stabilizer loadings and extended durability warranties. DIY application channels are expanding fastest, driven by homeowner education content and simplified cartridge-to-gun interfaces that reduce skill barriers.
EPA VOC content limits under 40 CFR Part 59 regulate architectural coating emissions, directly constraining solvent additive levels in latex caulk formulations. California Air Resources Board Suggested Control Measures impose stricter thresholds than federal baselines, creating a bifurcated compliance landscape for national suppliers. ASTM C834 and ISO 11600 standards govern elastomeric joint sealant performance classifications, shaping product labeling and specification eligibility. Stakeholders must monitor evolving state-level low-VOC mandates and assess whether reformulation investments or regional SKU segmentation delivers superior returns.
Market Dynamics
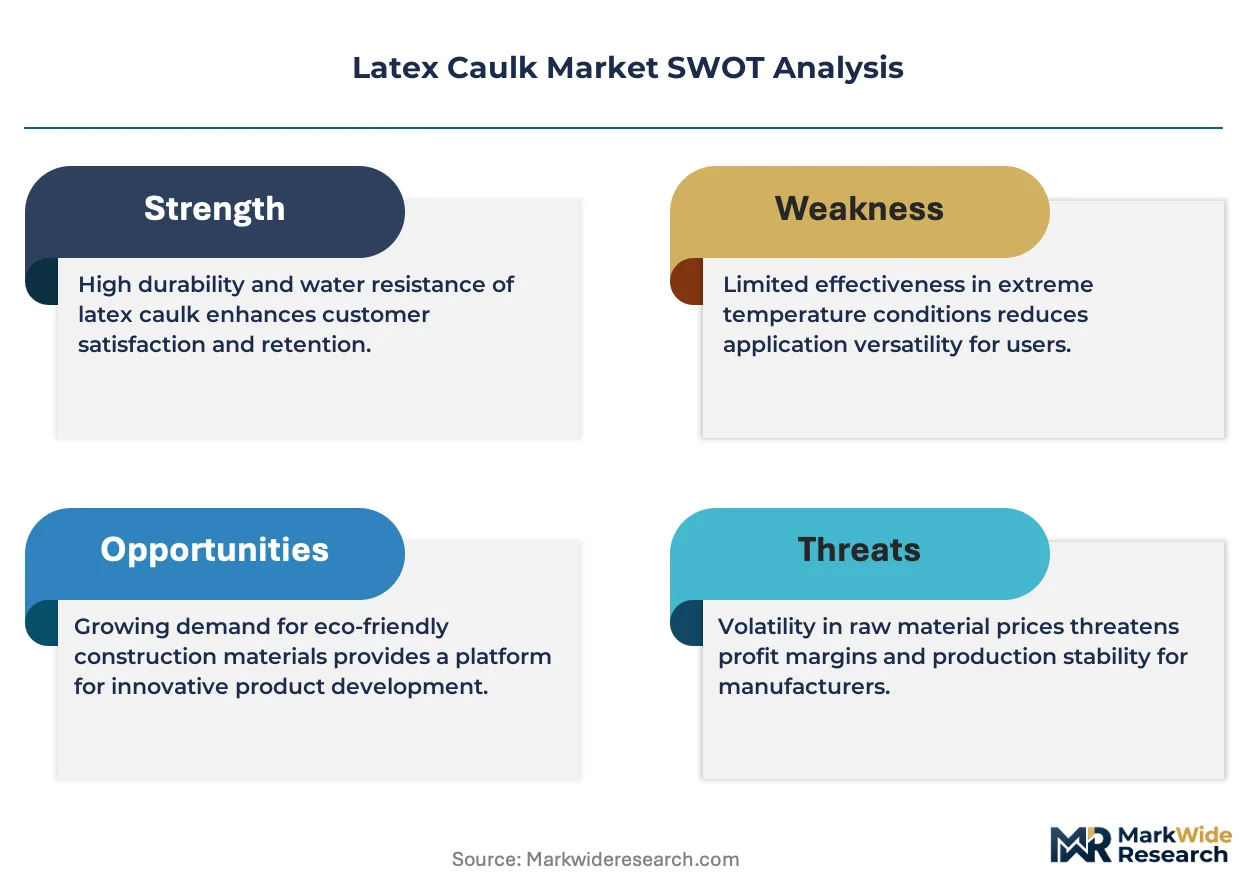
State-level low-VOC mandates in California are bifurcating formulation requirements for national suppliers, forcing parallel SKU development and regional manufacturing footprints that reshape competitive economics.
Growth Catalysts
- Sun Belt Housing Construction:Active residential development across Texas, Florida, and Arizona concentrates demand for flexible sealant solutions in high-movement climate zones.
- 40 CFR Part 59 Compliance:EPA architectural coating emissions limits are accelerating water-based formulation adoption over solvent alternatives in professional contractor segments.
- DIY Interface Simplification:Cartridge-to-gun design improvements are reducing skill barriers and expanding homeowner self-application in renovation projects.
Market Restraints
- Acrylic Monomer Feedstock Volatility:North American petrochemical supply chain realignment creates input cost uncertainty for emulsion manufacturers.
- Silicone Sealant Substitution:Premium exterior applications increasingly specify silicone for superior UV resistance and movement accommodation.
- ASTM C834 Certification Friction:Elastomeric joint sealant performance testing timelines delay product commercialization and specification eligibility.
Strategic Opportunities
- Adhesive-Sealant Hybrid Formulations:Blurred product boundaries are opening specification opportunities in window installation and trim carpentry applications.
- California Suggested Control Measures:Stricter state thresholds than federal baselines create first-mover advantage for compliant formulation specialists.
- Big-Box Retail Education Content:Homeowner tutorial investments are building brand preference and repeat purchase intent in the DIY channel.
Industry Challenges
- Biocide Efficacy Expertise Gap:Formulation chemists with in-can preservation and dry-film mildew resistance specialization remain scarce in regional labor markets.
- ISO 11600 Classification Complexity:Multi-jurisdictional performance standard alignment demands sustained technical documentation investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latex Caulk Market |
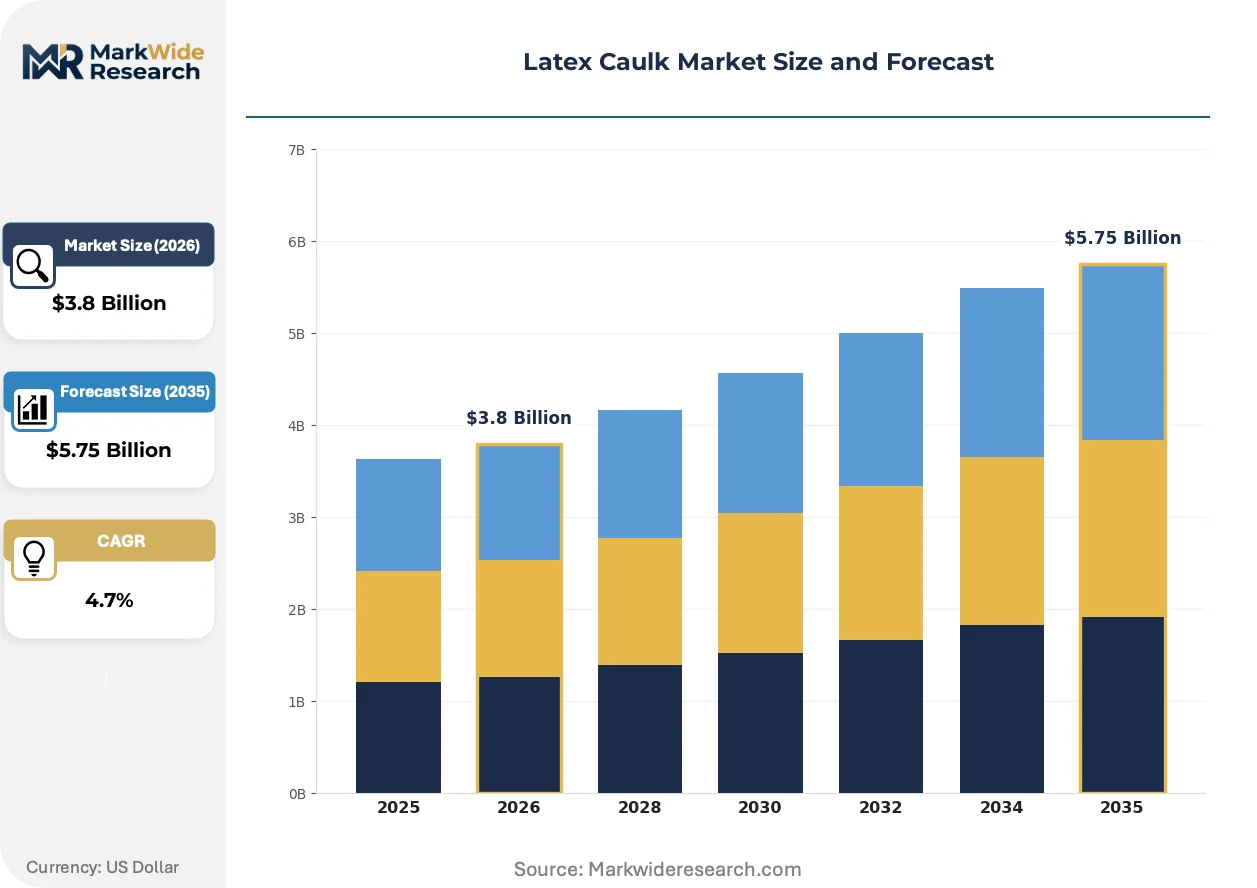
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interior, Exterior, Adhesive, Sealant Application: Residential, Commercial, Industrial, DIY Formulation: Acrylic, Silicone, Polyurethane, Hybrid Packaging Type: Tubes, Caulking Guns, Pails, Buckets |
| Companies Covered | 3M Company, Henkel AG & Co. KGaA, Dow Inc., Arkema Group, H.B. Fuller Company, Sika AG, RPM International Inc., The Sherwin-Williams Company, Franklin International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latex Caulk Market Shifts & Advancements
Formulation chemistry and distribution economics are converging to compress product development cycles while expanding addressable application spaces beyond traditional joint sealing.
Low-VOC water-based acrylic emulsions are consolidating position as the default architectural sealant technology. Professional contractors now specify these formulations for 80% of interior residential applications. This consolidation is compressing solvent-based product lines and redirecting R&D investment toward rheology modification rather than resin system replacement.
California Air Resources Board Suggested Control Measures are tightening VOC thresholds below federal EPA baselines. National suppliers face dual compliance burdens or regional SKU segmentation. Exterior-grade latex caulk producers are responding with accelerated UV stabilizer loading and extended durability warranty programs to justify premium positioning.
Homeowner education content is displacing contractor-mediated purchase decisions in renovation applications. YouTube tutorials and retailer app-based project calculators are building confidence in self-application. This behavioral shift concentrates fastest in Sun Belt states where housing turnover and cosmetic upgrade frequency exceed national averages.
Latex Caulk Market Segmentation
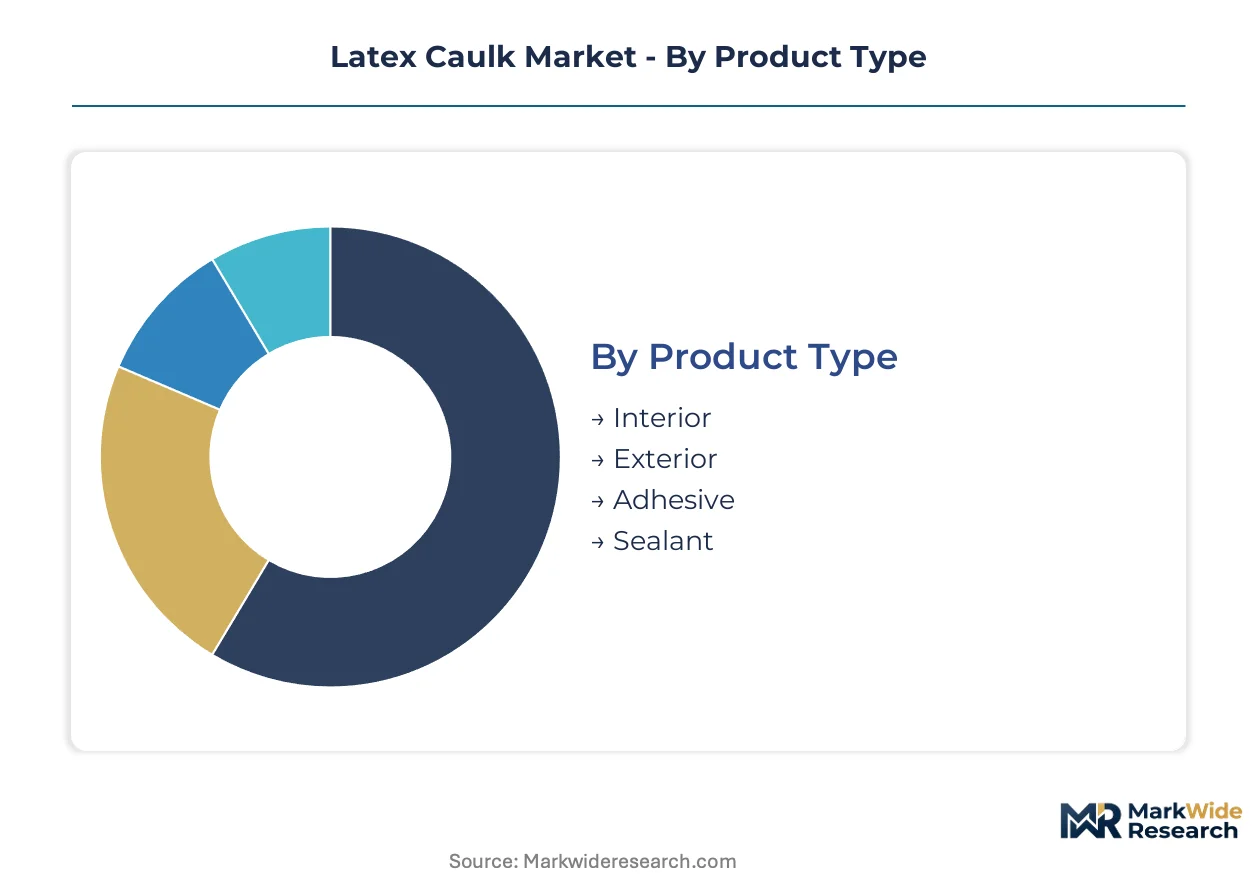
Latex caulk segmentation reveals how formulation chemistry, application environment, and distribution channel intersect to determine compliance burdens and margin structures. ASTM C834 and ISO 11600 certifications segment the market by performance tier, while EPA 40 CFR Part 59 and California Air Resources Board thresholds create divergent qualification pathways for each product category.
Product Type:
Interior grades require ASTM C834 elastomeric joint sealant certification for residential specification eligibility, while exterior formulations must additionally demonstrate UV resistance under accelerated weathering protocols. Adhesive-sealant hybrids face dual compliance with AAMA 800 window installation standards.
- Interior:Water-based acrylic emulsions with 40-60% solids content dominate residential renovation demand. These formulations achieve Shore A hardness of 15-25 for joint movement in climate-controlled environments. Demand concentrates in Sun Belt states where housing turnover drives cosmetic refresh cycles, constrained by EPA VOC limits under 40 CFR Part 59 that restrict solvent additive loading.
- Exterior:UV-stabilized formulations with enhanced biocide packages command premium positioning through extended durability warranties. These products require accelerated weathering certification for specification in high-movement climate zones. Texas and Florida residential construction concentrates demand, with silicone substitution pressure in premium applications.
- Adhesive:Pressure-sensitive formulations for trim carpentry and substrate bonding applications.
- Sealant:Elastomeric joint-filling products for expansion and control joint applications.
Interior sits at the top of the volume ranking, with Adhesive climbing the fastest as hybrid formulations blur traditional product boundaries.
Application:
Contractor-mediated procurement dominates commercial and industrial segments with specification-driven purchasing, while DIY channels expand through simplified cartridge-to-gun interfaces and retailer education content.
- Residential:New construction and renovation applications specify latex caulk for 80% of interior joint sealing. Professional contractors drive volume through builder partnerships, with Sun Belt housing construction concentrating demand in high-movement climate zones. EPA compliance requirements accelerate water-based adoption over solvent alternatives.
- DIY:Homeowner self-application expands fastest through YouTube tutorials and big-box retailer app-based project calculators. Cartridge-to-gun design improvements reduce skill barriers, building repeat purchase intent in renovation-focused markets. California and Texas lead this behavioral shift.
- Commercial:Specification-driven procurement through architectural and engineering firms for institutional and retail construction.
- Industrial:Heavy-duty applications requiring enhanced chemical resistance and movement accommodation.
Residential commands the largest volume share, with DIY gaining share fastest as homeowner education displaces contractor mediation.
Formulation:
Raw material feedstock availability and regional petrochemical supply chain configuration determine cost structures across resin system categories.
- Acrylic:Water-based polymer emulsions cure through ambient moisture evaporation to form flexible, paintable seals. North American petrochemical feedstock availability supports cost-advantaged production positions. These formulations dominate interior residential applications and face tightening California Air Resources Board VOC thresholds.
- Silicone:Superior UV resistance and movement accommodation specifications in premium exterior applications.
- Polyurethane:High-performance elastomeric sealants for industrial and heavy commercial movement joints.
- Hybrid:Blended resin systems combining acrylic water-based handling with enhanced durability characteristics.
Acrylic leads volume shipments, with Hybrid expanding most quickly as manufacturers bridge performance gaps between traditional categories.
Packaging Type:
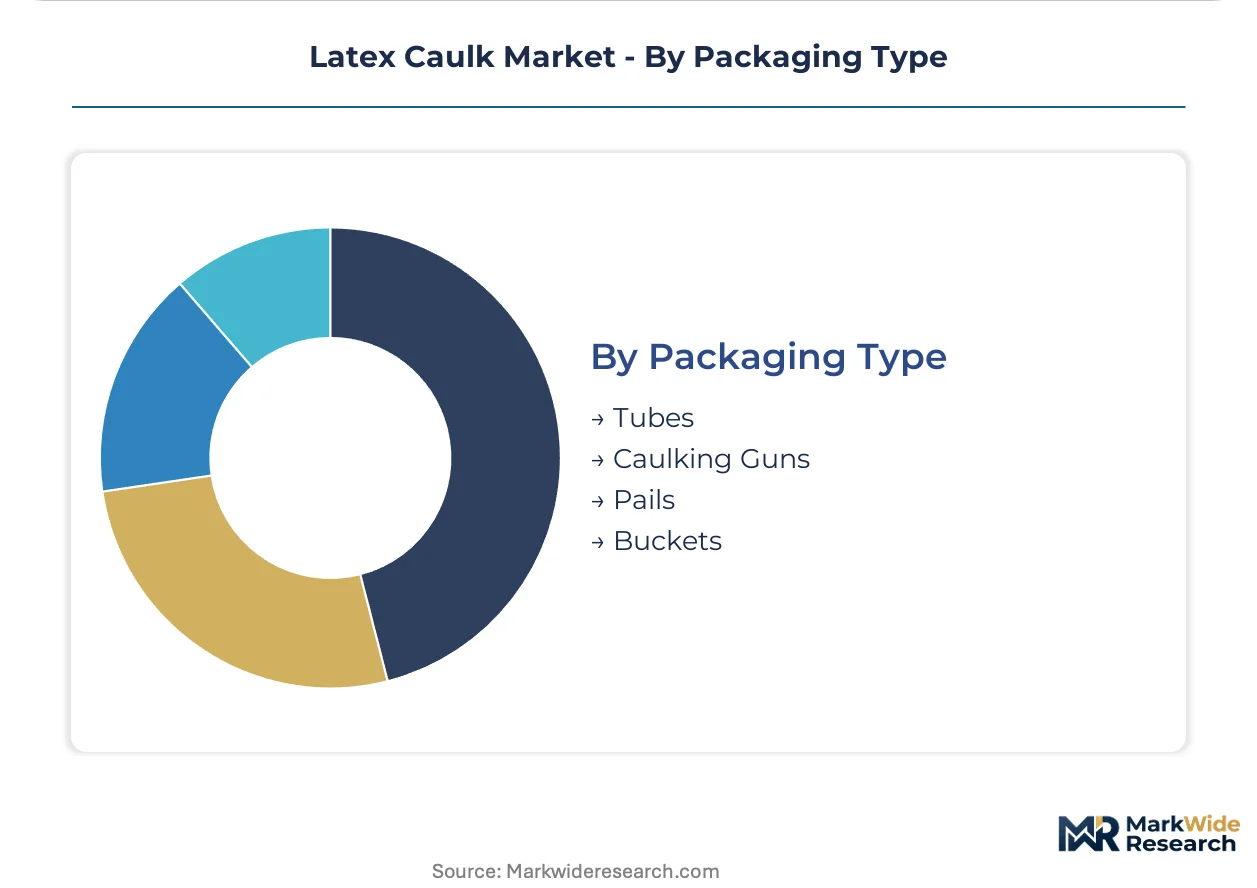
Distribution channel economics and application scale determine packaging format selection, with retail-friendly formats commanding premium unit economics.
- Caulking Guns:Standard 10-ounce cartridges dominate professional contractor procurement and DIY renovation. These formats interface with simplified application tools that reduce skill barriers for homeowner self-application. Big-box retail partnerships concentrate distribution in high-turnover housing markets.
- Tubes:Squeeze tubes target small-scale repair and touch-up applications in consumer channels.
- Pails:Bulk containers for commercial and industrial scale application with pneumatic dispensing equipment.
- Buckets:Large-volume packaging for new construction and industrial maintenance applications.
Caulking Guns anchor volume leadership, with Tubes showing steepest expansion trajectory in repair and maintenance segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration patterns track diverging compliance costs across jurisdictions. Manufacturers relocate formulation capacity toward regions with favorable VOC thresholds and feedstock access.
United States
Sun Belt housing construction concentrates demand in Texas, Florida, and Arizona. EPA 40 CFR Part 59 regulates architectural coating emissions nationwide. Dallas-Fort Worth metroplex hosts multiple emulsion production facilities serving regional distribution networks.
China
Construction chemical manufacturing clusters in Yangtze River Delta and Pearl River Delta. GB standards govern volatile organic compound limits in building materials. Shanghai-based producers supply water-based acrylic emulsions for both domestic consumption and export markets.
Germany
REACH compliance requirements shape formulation chemistry across European markets. Industrial sealant specification standards influence global product development. Rhine-Ruhr industrial corridor maintains specialized adhesive-sealant manufacturing capabilities.
India
Urban residential construction drives sealant consumption in metropolitan markets. BIS certification requirements establish product quality baselines for imported and domestic formulations. Maharashtra and Gujarat host expanding construction chemical production infrastructure.
Brazil
Infrastructure investment programs stimulate commercial construction sealant demand. ANVISA regulates chemical product registration and environmental safety. São Paulo state anchors South American formulation capacity for regional distribution.
Latex Caulk Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adhesive-sealant hybrid niches. The market exhibits moderate concentration with integrated petrochemical operators holding feedstock advantages. Three archetypes dominate: vertically integrated resin suppliers, specialized formulation houses, and diversified construction chemical portfolios. Capacity expansion and regional SKU segmentation represent the primary competitive maneuvers.
Among North American integrated operators, Dow Inc. exemplifies upstream resin control, while H.B. Fuller Company occupies a position bridging adhesive and sealant applications. Henkel AG & Co. KGaA represents the diversified construction chemical archetype with retail channel anchoring. These three entities illustrate distinct strategic postures without exhausting the competitive field.
| Leading Market Players |
|---|
| 3M Company |
| Henkel AG & Co. KGaA |
| Dow Inc. |
| Arkema Group |
| H.B. Fuller Company |
| Sika AG |
| RPM International Inc. |
| The Sherwin-Williams Company |
| Franklin International |
| Others |
Supply & Pricing Matrix
California Air Resources Board Suggested Control Measures gate qualified supply access and premium-tier pricing power by bifurcating national formulation requirements. EPA 40 CFR Part 59 compliance investments compress margins on standard-grade products while concentrating margin capture among specialized low-VOC suppliers.
Pricing Analysis
Retailer markup layers compress manufacturer netbacks by 15-25 points in DIY channels versus direct contractor procurement. Three-tier pricing structure across premium, standard, and economy levels stratifies by ASTM C834 certification grade and California compliance status. Cost compression in economy tiers intensifies because acrylic monomer feedstock volatility feeds through emulsion contracts. Professional contractors show lowest price sensitivity due to specification lock-in, while DIY homeowners exhibit highest elasticity to unit price shifts.
Supply Chain Analysis
Freight cost differentials between Gulf Coast petrochemical hubs and Sun Belt demand centers favor regional emulsion production over long-haul finished goods distribution. Supply concentrates in the United States, China, and Germany, with acrylic monomer and biocide packages drawing from North American and Asian chemical corridors. Single-source vulnerability in specialized UV stabilizer inputs creates specification risk for exterior-grade producers. Distribution runs through big-box retail partnerships for DIY volumes and direct-to-builder programs for new construction segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory layering, with EPA 40 CFR Part 59 and California Suggested Control Measures driving reformulation demand that rewards specialized compliance investment.
For Market Incumbents: Acquire captive biocide formulation capabilities to secure dry-film mildew resistance expertise that emerging entrants cannot replicate. Anchor Sun Belt distribution through dedicated Texas and Florida emulsion production to neutralize freight cost disadvantages. Silicone substitution pressure in premium exterior applications demands accelerated hybrid R&D to blur performance boundaries. For New Entrants and Emerging Players: California Suggested Control Measures in the United States opens a window for low-VOC formulation specialists to capture specification share from national suppliers burdened by dual compliance costs. Target adhesive-sealant hybrid niches in window installation where AAMA 800 certification barriers remain surmountable. Build channel presence through big-box retail education content partnerships that reduce customer acquisition friction. For Investors and Strategic Acquirers: Roll-up economics work for regional formulation specialists because fragmented compliance landscapes favor localized SKU development over centralized national supply. Five-to-ten year viability hinges on feedstock-advantaged positioning in Gulf Coast petrochemical corridors. Watch Sun Belt housing permit volatility as the primary demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Monomer | Dow Inc. leverages captive Gulf Coast feedstock to secure cost-advantaged emulsion positions. |
| Regional SKU Segmentation | Dual California-federal compliance footprints reduce cross-contamination risk in formulation facilities. |
| Hybrid Formulation Development | Adhesive-sealant blends capture specification share in window installation and trim carpentry. |
| Big-Box Retail Education Investment | Homeowner tutorial content builds brand preference and repeat purchase intent in DIY channels. |
| Extended Durability Warranty Programs | UV stabilizer loading investments justify premium positioning against silicone substitution pressure. |
Research Methodology
Coverage spans the United States, China, Germany, India, and Brazil, with primary inputs from each market informing demand calibration. Formulation chemists, big-box retail category managers, professional contractor procurement leads, and emulsion plant operations directors provided ground-level intelligence. Secondary validation drew from EPA regulatory filings, ASTM standard documentation, ACC construction chemical reports, and customs trade flow records. Bottom-up segment sizing triangulated against top-down petrochemical feedstock consumption patterns.
Rate-of-change decomposition separated volume growth from value expansion across the projection horizon. Segmentation modeling spanned product type, application channel, formulation chemistry, and packaging format dimensions. CAGRs derived from housing construction permit trajectories, renovation spending indices, and VOC regulatory implementation timelines. Acrylic monomer price elasticity and silicone substitution thresholds served as industry-specific sensitivity inputs.
Revisions become necessary when housing construction permit volatility, feedstock price dislocations, or state-level regulatory acceleration materialize beyond baseline assumptions. Forecasts reflect documented judgments about compliance cost pass-through and channel mix evolution. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Concrete Conditioner Market
Building & Construction Materials
Travertine Tiles Market
Building & Construction Materials
Indonesia Ready-Mix Concrete Market
Building & Construction Materials
US Prefabricated Steel Market
Building & Construction Materials
Japan Concrete Conditioner Market
Building & Construction Materials
Corrugated Polycarbonate Panels Market
Building & Construction Materials
Building Vibration Isolation Market
Building & Construction Materials
Softwood Lumber Market
Building & Construction Materials
Exterior Sheathing Market
Building & Construction Materials
Wood Panel Market
Building & Construction Materials
Japan Prefab Wood Building Market
Building & Construction Materials
Global Screw Piles Market
Building & Construction Materials
Construction Elastomers Market
Building & Construction Materials
US Ceiling Tiles Market
Building & Construction Materials
Israel Ceramic Tiles Market
Building & Construction Materials
Rubber Expansion Joints Market