
 Belt Scales Market | 2026-2036
Belt Scales Market Size, Share, and Industry Trends Forecast 2026-2036
Belt Scales Market Analysis
The EU Green Deal is restructuring capital equipment priorities across heavy processing industries, pushing buyers toward precision measurement systems that cut material waste and energy intensity. Schenck Process Holding GmbH anchors German engineering credibility in high-accuracy bulk weighing, while Rice Lake Weighing Systems leverages North American manufacturing scale to dominate aftermarket service networks. Siemens AG competes through automation integration, embedding belt scales into broader digital plant architectures.
A belt scale is a conveyor-integrated weighing instrument that measures bulk material mass flow in real time, typically achieving accuracies within 0.25% to 1% of totalized load depending on installation class and calibration protocol. The device employs load cells, speed sensors, and integrators to compute throughput for process control, inventory management, and commercial settlement in continuous material handling operations. Electronic systems capture the dominant value share due to superior accuracy and connectivity, while hybrid configurations grow fastest as retrofit demand bridges legacy mechanical installations with digital plant networks. Mining end users command the largest installed base, though recycling applications expand rapidly on contamination accountability requirements and circular economy mandates.
EMA machinery directives and EU Green Deal procurement standards shape European product specifications, while China's GB standards and MEE enforcement dictate domestic certification requirements for environmental compliance. The US Mine Safety and Health Administration and EPA emissions tracking rules drive precision investment in North American mineral processing. Stakeholders must monitor how carbon border adjustment mechanisms and Scope 3 reporting obligations redefine the business case for real-time mass flow measurement.
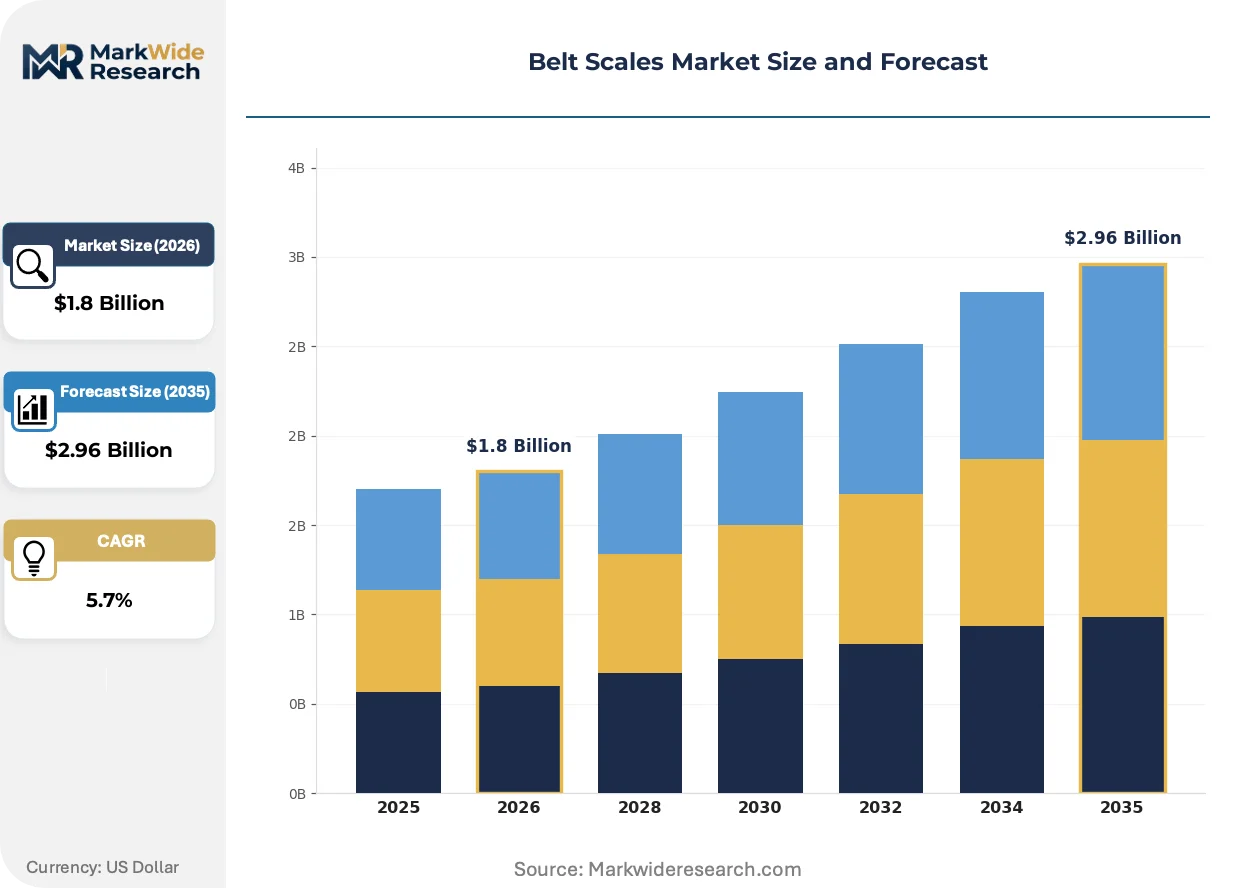
Market Dynamics
Carbon border adjustment mechanisms and Scope 3 emissions tracking obligations are restructuring capital equipment procurement priorities across bulk material processing industries, forcing real-time mass flow measurement from optional efficiency tool to compliance infrastructure.
Growth Catalysts
- EU Green Deal procurement mandates:European processing facilities must install precision weighing systems to document material throughput for carbon intensity reporting, creating binding demand for certified belt scale installations.
- China's dual carbon goals:MEE enforcement of GB standards for bulk material handling drives replacement of mechanical scales with electronic systems in coal and iron ore conveyor networks.
- Recycling contamination accountability:Circular economy mandates in advanced economies require real-time mass tracking of recycled feedstocks to prove origin and purity for tax credits.
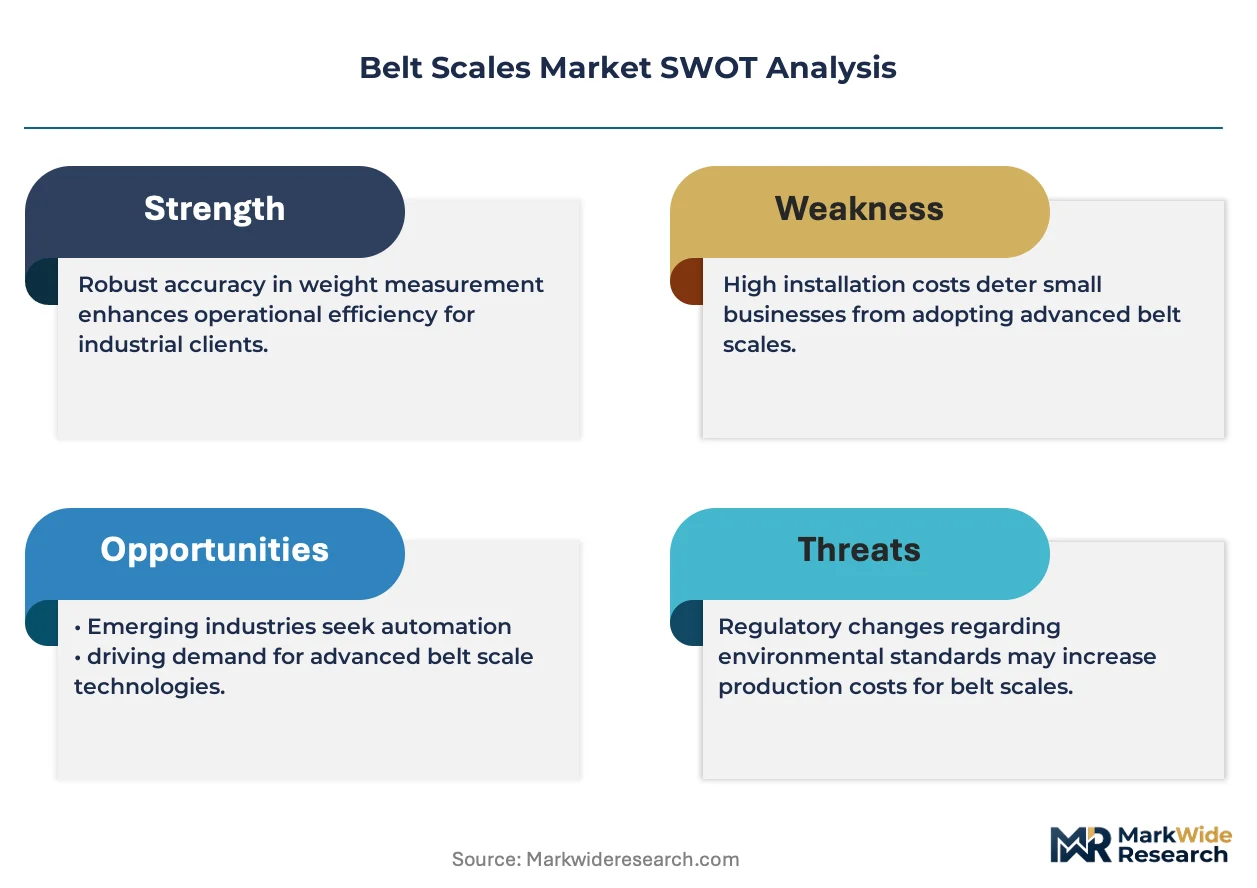
Market Restraints
- Load cell supply concentration:Strain gauge manufacturing clusters in Germany and Japan create single-source vulnerability for high-accuracy belt scale producers during demand surges.
- Calibration labor intensity:Achieving OIML R50 certification requires specialized technicians, limiting deployment speed in remote mining locations.
- Mechanical scale longevity:Legacy mechanical installations in emerging markets operate for 15-20 years, delaying replacement cycles despite accuracy disadvantages.
Strategic Opportunities
- India's PLI scheme for mining equipment:Domestic production incentives attract belt scale assembly to serve South Asian and Middle Eastern bulk handling projects.
- Hybrid retrofit configurations:Bridge installations combining existing mechanical frames with digital load cells and IoT integrators capture mid-tier buyers unwilling to replace full conveyor sections.
- Aftermarket service unbundling:Independent calibration and certification providers penetrate owner-operated mining sites in Australia and Chile, displacing OEM service monopolies.
Industry Challenges
- Integration complexity with SCADA architectures:Belt scale data protocols must map to proprietary automation platforms from Siemens, Rockwell, and Schneider, extending commissioning timelines.
- Certification timeline compression:Multiple national type approvals (OIML, NTEP, Measurement Canada) delay product launches by 8-14 months for global suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Belt Scales Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic, Mechanical, Hybrid, Load Cell Installation: Fixed, Portable, Mobile, Belt-Way End User: Mining, Agriculture, Food Processing, Recycling Technology: Weighing Mechanism, Digital Display, Automation, Integration |
| Companies Covered | Rice Lake Weighing Systems, Thermo Fisher Scientific Inc., Schenck Process Holding GmbH, Thayer Scale-Hyer Industries, Belt-Way Scales, Siemens AG, Avery Weigh-Tronix, Tecweigh (Tecnetics Industries), Mettler Toledo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Belt Scales Market Emerging Trajectories
Digital plant architectures are absorbing bulk weighing instruments into unified data layers, transforming standalone belt scales from measurement points into continuous process intelligence nodes feeding predictive maintenance and emissions accounting systems.
Multi-idler electronic belt scale configurations are expanding into high-value mineral concentrate lines where 0.25% accuracy justifies capital investment. Copper and lithium producers in Chile and Western Australia deploy these systems to satisfy offtake contract mass reconciliation requirements. The technology is expanding into commercial settlement applications previously reserved for static weighbridges, compressing the market for truck-scale infrastructure at processing facilities.
REACH and RoHS substance restrictions are forcing load cell manufacturers to reformulate solder alloys and encapsulation compounds. European belt scale assemblers now audit upstream suppliers for SVHC compliance documentation, adding procurement friction but creating competitive differentiation for certified component streams. German engineering houses leverage this regulatory barrier to defend premium positioning against lower-cost Asian competitors.
Buyer consolidation among multinational mining houses concentrates specification authority in centralized technical standards teams. Rio Tinto, BHP, and Vale now mandate interoperable digital protocols across all greenfield conveyor investments, forcing belt scale vendors to embed OPC-UA and MQTT connectivity as baseline features rather than premium options. This pattern is most visible in Australia's Pilbara iron ore district where standardized procurement templates accelerate vendor qualification but compress margin differentiation.
Belt Scales Market Segmentation
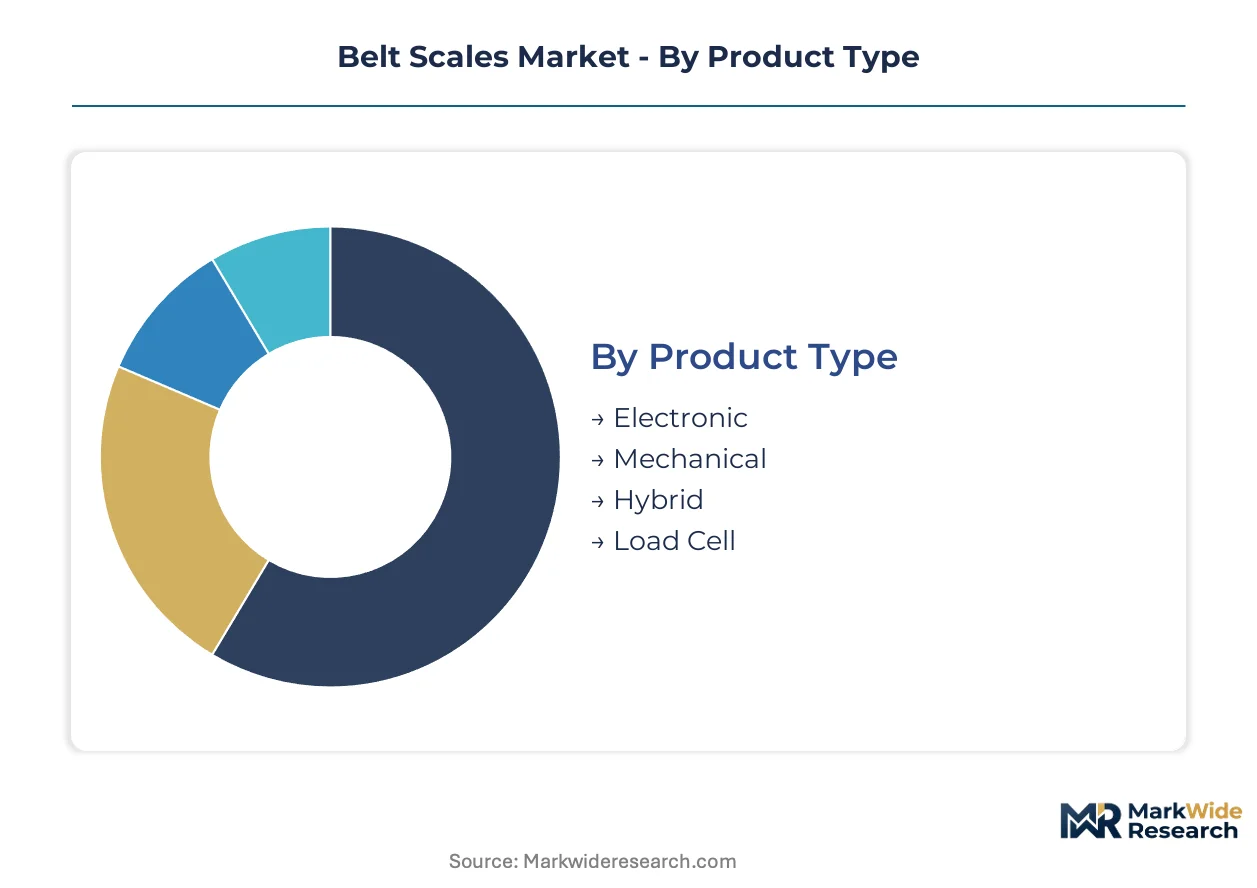
Belt scale procurement decisions split across technical performance tiers, installation constraints, and compliance requirements. Buyers weigh accuracy certification against capital outlay, while retrofit demand reshapes product mix across legacy conveyor infrastructure.
Product Type:
Cost tier separates buyers seeking OIML-certified precision from those tolerating mechanical trade-offs for lower upfront investment.
- Electronic:Load cell arrays and digital integrators deliver 0.25% accuracy for commercial settlement applications. Mining houses in Chile and Western Australia specify electronic systems for copper and lithium concentrate lines where offtake contracts mandate mass reconciliation.
- Mechanical:Lever and spring-based designs persist in emerging market coal handling where capital constraints override accuracy requirements. Fifteen-to-twenty year service life delays replacement cycles despite inferior precision.
- Hybrid:Bridge configurations retrofit digital sensors onto existing mechanical frames, capturing mid-tier buyers unwilling to replace full conveyor sections.
- Load Cell:Strain gauge assemblies constitute the core sensing element, with German and Japanese manufacturing clusters supplying high-accuracy components.
Volume sits with Electronic; growth tilts toward Hybrid.
Installation:
Application environment dictates mounting approach, from permanent pit installations to temporary quarry deployments.
- Fixed:Permanent conveyor integration at processing plants requires civil foundation work and certified calibration protocols. Iron ore facilities in Australia's Pilbara district standardize fixed installations across greenfield developments.
- Portable:Skid-mounted systems serve contract crushing operations and short-term mining campaigns where relocation frequency exceeds capital recovery timelines.
- Mobile:Self-contained units with onboard power support construction aggregate screening and demolition waste sorting applications.
- Belt-Way:Idler-mounted configurations suspend measurement hardware directly on conveyor stringers, minimizing structural modification for retrofit projects.
Fixed installations dominate greenfield capital; Portable configurations expand fastest in contract mining.
End User:
Customer type determines accuracy requirements, with commercial settlement applications demanding certified precision versus internal inventory tracking.
- Mining:Bulk material throughput measurement for process control and royalty calculation commands the largest installed base. BHP and Rio Tinto mandate interoperable digital protocols across Australian iron ore conveyor networks.
- Agriculture:Grain elevator and port terminal applications require moisture compensation and seasonal calibration adjustment. Midwest US cooperatives prioritize NTEP certification for commodity payment accuracy.
- Food Processing:Hygienic load cell enclosures and washdown-rated integrators satisfy USDA and FDA sanitation requirements in meat and dairy operations.
- Recycling:Circular economy mandates in the EU and California drive real-time mass tracking of recycled feedstocks for contamination accountability and tax credit verification.
Mining anchors current revenue; Recycling climbs the fastest on extended producer responsibility enforcement.
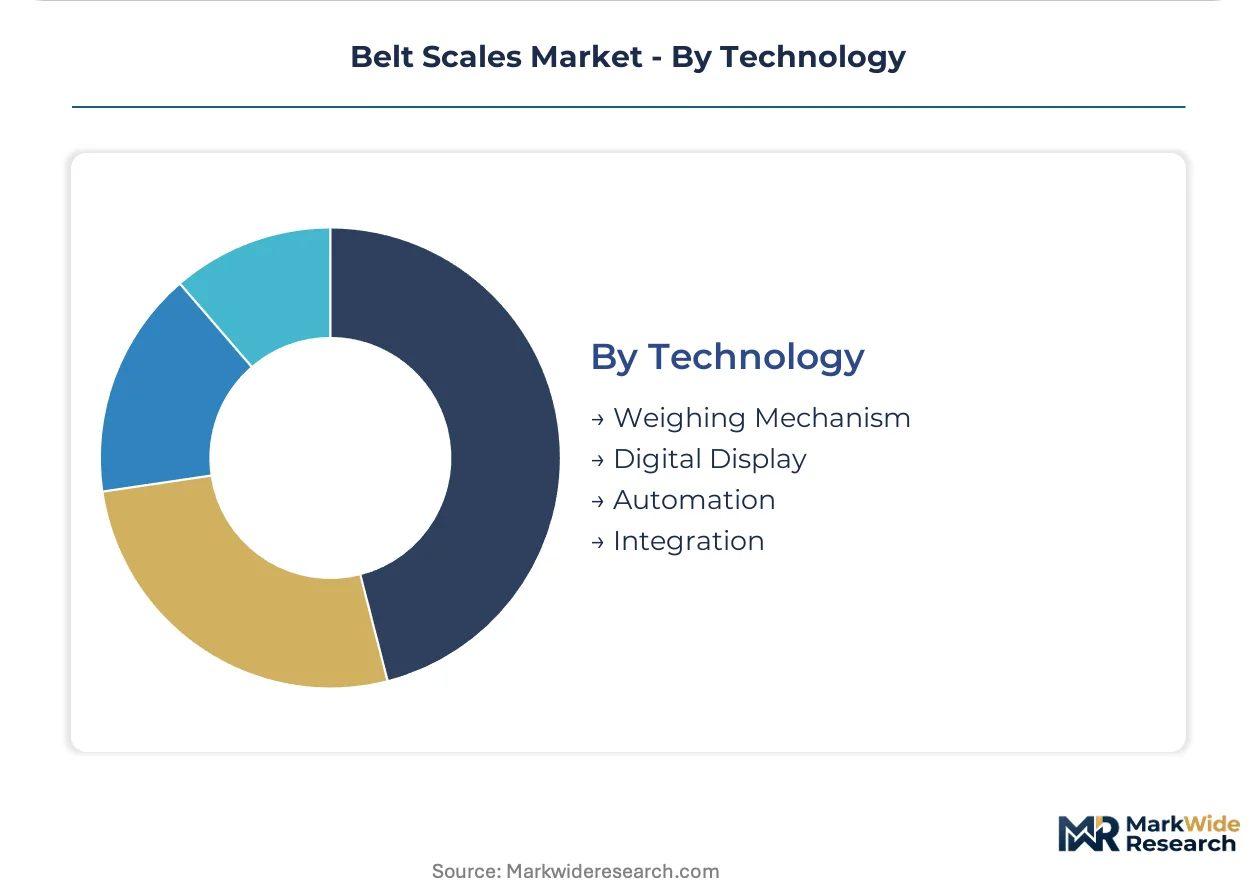
Technology:
Maturity gradient separates proven weighing hardware from emerging integration layers that embed scales into plant-wide data architectures.
- Weighing Mechanism:Multi-idler configurations distribute load across four to six idler stations, reducing belt tension effects and achieving 0.25% accuracy for high-value mineral concentrates.
- Digital Display:Local readout terminals provide operator visibility for troubleshooting, though standalone displays cede importance to networked data feeds.
- Automation:PID control loops adjust feeder rates based on real-time mass flow, closing process control loops in cement and aggregate batching operations.
- Integration:OPC-UA and MQTT protocols map belt scale data to SCADA architectures, feeding predictive maintenance and emissions accounting systems at digitized processing facilities.
Weighing Mechanism generates current margin; Integration captures expansion as digital plant architectures mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in Germany and Japan while consumption clusters in mining-intensive economies. Australia and Chile import precision systems for bulk mineral handling. China's domestic production serves its coal and iron ore conveyor networks.
Australia
Pilbara iron ore operations drive demand for OIML-certified multi-idler configurations. The country's national mining safety regulator mandates precision mass flow documentation for royalty calculations. Perth-based technical standards teams at BHP and Rio Tinto enforce interoperable digital protocols across greenfield conveyor investments.
Chile
Copper and lithium concentrate lines require 0.25% accuracy for offtake contract compliance. Environmental enforcement through the country's national environmental authority pressures processors to document material throughput for carbon intensity reporting. Antofagasta and Atacama mining corridors host concentrated belt scale deployment for commercial settlement applications.
China
Coal and iron ore infrastructure expansion creates replacement demand for electronic systems. MEE enforcement of GB standards accelerates retirement of mechanical scales in bulk handling networks. Shanxi and Inner Mongolia coal basins concentrate domestic belt scale procurement as state-owned processors modernize conveyor infrastructure.
Germany
Precision engineering exports anchor European supply capability for high-accuracy load cells. EU Green Deal procurement standards restructure equipment specifications across heavy processing industries. Düsseldorf and Munich industrial corridors host Schenck Process engineering operations serving global mining houses.
United States
Midwest grain cooperatives and Appalachian coal operations sustain aftermarket demand for NTEP-certified systems. EPA emissions tracking rules and MSHA safety requirements drive precision investment in mineral processing. Wisconsin and Minnesota manufacturing clusters produce load cell assemblies for North American service networks.
Belt Scales Market Vendor Landscape
The competitive structure tilts toward engineering-led specialists with deep calibration expertise. Three tiers separate premium OIML-certified suppliers from mid-tier hybrid retrofit providers and economy mechanical fabricators. Consolidation pressure concentrates among German precision houses and North American automation integrators. Strategic moves center on digital protocol standardization and aftermarket service unbundling.
Among precision engineering specialists, Schenck Process Holding GmbH anchors German manufacturing credibility in high-accuracy bulk weighing. Siemens AG occupies a position representing automation integration archetypes that embed measurement hardware into broader digital plant architectures. Rice Lake Weighing Systems exemplifies North American scale fabricators leveraging regional manufacturing presence to dominate service network density.
| Leading Market Players |
|---|
| Rice Lake Weighing Systems |
| Thermo Fisher Scientific Inc. |
| Schenck Process Holding GmbH |
| Thayer Scale-Hyer Industries |
| Belt-Way Scales |
| Siemens AG |
| Avery Weigh-Tronix |
| Tecweigh (Tecnetics Industries) |
| Mettler Toledo |
| Others |
Supply Flow & Price Mechanics
EU Green Deal procurement mandates for carbon intensity documentation are forcing belt scale buyers toward OIML-certified electronic systems, compelling suppliers to absorb strain gauge cost volatility and extend calibration service bundling to defend margin.
Pricing Analysis
Throughput-guarantee contracts anchor value-based pricing for multi-idler configurations serving Chilean copper concentrate lines. Three-tier pricing structure across premium OIML-certified, standard NTEP-compliant, and economy mechanical tiers separates mining houses from grain cooperatives and emerging market coal handlers. Cost compression in the economy tier intensifies as Chinese domestic manufacturers scale electronic load cell production. Midwest US agricultural cooperatives exhibit highest price sensitivity, prioritizing NTEP certification over 0.25% accuracy.
Supply Chain Analysis
Refurbishment flows for legacy mechanical frames feed hybrid retrofit demand, with remanufactured idler assemblies extending service life in Australian contract crushing operations. Strain gauge manufacturing concentrates in Germany and Japan, while final assembly clusters in China and the United States. Hysteresis-compensated steel and hermetic encapsulation compounds constitute critical input dependencies. Single-source vulnerability in high-accuracy load cell supply creates exposure during mining demand surges. Distribution runs through OEM-direct channels for greenfield projects and independent service networks for aftermarket calibration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Strain gauge foundry capacity constraints in Germany and Japan prop pricing for precision tiers, sustaining incumbent margin structures despite Chinese electronic scale expansion.
For Market Incumbents: Deepen captive calibration certification capabilities to offset independent service network encroachment in Australian and Chilean mining corridors. Backward integration into strain gauge assembly insulates against German and Japanese supply concentration. Prioritize OPC-UA protocol standardization to lock in greenfield conveyor specifications at BHP and Rio Tinto. For New Entrants and Emerging Players: Direct-to-mine digital service platforms offer low-friction entry points for aftermarket calibration unbundling in owner-operated Australian sites. India's PLI scheme for mining equipment assembly presents the most penetrable geography for mid-tier hybrid manufacturing. Target recycling sector mass-tracking mandates in California and the EU with IoT-integrator bundles bypassing mechanical scale replacement. For Investors and Strategic Acquirers: The window for entry favors calibration-software specialists with EPA emissions accounting integration. Long-term viability rests on carbon border adjustment mechanism compliance infrastructure rather than commodity scale volume. Monitor EU CBAM implementation timelines as inflection signal for precision measurement demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Service Network Expansion | Independent certification penetration displaces OEM service monopolies at Chilean copper concentrators. |
| Hybrid Retrofit Configuration Development | Bridge installations capture mid-tier buyers unwilling to replace full Pilbara conveyor sections. |
| OPC-UA Protocol Standardization | Interoperable digital architectures satisfy Rio Tinto centralized technical standards mandates. |
| Backward Integration into Load Cell Manufacturing | In-house strain gauge production reduces exposure to German and Japanese supply concentration. |
| Recycling Sector Mass-Tracking Solutions | Real-time feedstock origin verification satisfies California extended producer responsibility enforcement. |
Methodological Framework
Independent corroboration across maintenance directors at Australian iron ore facilities, calibration technicians at Chilean copper processors, and procurement leads at German engineering houses underwrites the qualitative findings. Plant engineers, aftermarket service heads, and OEM procurement teams provided primary field intelligence. Secondary validation drew from OIML certification registries, EPA emissions tracking disclosures, SEC 10-K filings of listed automation suppliers, and EU Green Deal procurement directive documentation. Bottom-up installation counts triangulate against top-down bulk handling capital expenditure estimates.
Rate-of-change decomposition separates volume growth in fixed installations from value expansion in integration-layer technologies across the analysis window. Product type, installation configuration, end-user industry, and technology maturity segment the forecast framework. CAGRs derive from weighted regression of historical replacement cycles against regulatory compliance deadline clustering. Modeled inputs include MEE enforcement intensity for GB standards compliance and EU CBAM phased implementation schedules.
The model holds under stable regulatory enforcement timelines; deviation in carbon border adjustment acceleration or strain gauge supply disruption would shift replacement demand curves. Practitioners should monitor EU CBAM technical documentation requirements and Chinese MEE inspection frequency for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Wear Plates Market
Material Handling Equipment
Middle East and Africa Conveyors Market
Material Handling Equipment
India Automated Material Handling (AMH) Market
Material Handling Equipment
Tube Rotator Market
Material Handling Equipment
Fork Lift Attachments Market
Material Handling Equipment
Loader Crane Market
Material Handling Equipment
Dry Bulk Handling System Market
Material Handling Equipment
Warehouse Freight Elevators Market
Material Handling Equipment
Hydraulic Hoist Market
Material Handling Equipment
Lever Hoist Market
Material Handling Equipment
North America Screw Conveyor Market
Material Handling Equipment
Pipe Clamp Market
Material Handling Equipment
High-Density Racks Market
Material Handling Equipment
North America Conveyor Belt Market
Material Handling Equipment
US Forklift Market
Material Handling Equipment
Rotary Breaker Market