
 Allergy Immunotherapy Market | 2026-2036
Allergy Immunotherapy Market Size, Share, and Industry Trends Forecast 2026-2036
Allergy Immunotherapy Market Intelligence
Subscription-based maintenance programs for sublingual drop regimens is restructuring how allergy clinics procure immunotherapy, shifting from episodic purchasing to multi-year patient adherence contracts. ALK-Abello leverages its European distribution network to anchor these service arrangements across Nordic markets. Stallergenes Greer competes through specialized pharmacy partnerships in France and Italy. Merck KGaA extends its position via integrated diagnostic-to-treatment platforms in German-speaking regions.
Allergy immunotherapy encompasses repeated administration of standardized allergen extracts to induce antigen-specific immune tolerance, typically involving purified protein fractions at concentrations ranging from 100 to 300,000 standard quality units per maintenance dose. The clinical objective centers on modifying the underlying Type I hypersensitivity response rather than merely suppressing symptoms through pharmacological intervention. Sublingual immunotherapy now occupies the fastest-expanding margin pool as home-administered tablets reduce clinic burden and improve compliance trajectories. Injectable subcutaneous protocols still dominate absolute revenue within specialty clinics due to higher per-patient value and established reimbursement codes. Epicutaneous delivery through patch-based systems represents an emerging structural segment where DBV Technologies and others are positioning for pediatric food allergy indications.
FDA oversight of biologic allergen products under BLA pathways intersects with EMA centralized marketing authorization requirements for standardized extracts, creating divergent clinical trial obligations across Atlantic markets. The EU MDR and FDA's evolving guidance on peptide immunotherapy platforms are forcing manufacturers to rebuild technical documentation and post-market surveillance systems. Stakeholders must monitor how reimbursement authorities in Germany, France, and the United Kingdom calibrate long-term outcome metrics against upfront treatment costs.
Market Dynamics
Subscription-based maintenance programs for sublingual drop regimens are restructuring clinic procurement patterns, shifting episodic purchasing toward multi-year patient adherence contracts that lock in manufacturer relationships and reshape competitive positioning across European allergy centers.
Growth Catalysts
- EU MDR Framework:Tightened clinical evidence requirements for allergen extract products are accelerating consolidation among manufacturers, strengthening positions of established players with robust technical documentation capabilities.
- Pediatric Care Networks:Expansion of sublingual immunotherapy protocols across Germany, France, and the United Kingdom is driving volume concentration in Western European centers with established reimbursement pathways.
- Home-Administered Tablets:Sublingual delivery systems reduce clinic burden and improve compliance trajectories, expanding addressable patient populations beyond traditional injectable protocol candidates.
Market Restraints
- Allergen Extract Standardization:Biological variability in source materials creates batch-to-batch consistency challenges that complicate manufacturing scale-up and quality assurance protocols.
- Reimbursement Fragmentation:Divergent long-term outcome metrics across German, French, and British health technology assessment bodies create pricing uncertainty and delay market access negotiations.
- Clinical Trial Duration:Three-to-five-year efficacy demonstration requirements for immunotherapy products extend development timelines and elevate capital requirements beyond typical pharmaceutical benchmarks.
Strategic Opportunities
- Epicutaneous Patch Systems:DBV Technologies and emerging competitors are positioning patch-based delivery for pediatric food allergy indications, opening a structural segment with limited incumbent competition.
- Diagnostic-to-Treatment Platforms:Integrated allergen testing and personalized immunotherapy formulation services create stickier patient relationships and capture margin across the care continuum.
- Nordic Market Penetration:ALK-Abello's distribution infrastructure provides anchor points for service-based contracts in underpenetrated Scandinavian markets with favorable public health procurement frameworks.
Industry Challenges
- Post-Market Surveillance Rebuild:EU MDR and FDA evolving guidance on peptide immunotherapy platforms force manufacturers to reconstruct technical documentation systems and vigilance reporting infrastructure.
- Specialized Pharmacy Integration:Stallergenes Greer's partnership model in France and Italy requires significant training investment to ensure proper cold-chain handling and patient counseling capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Allergy Immunotherapy Market |
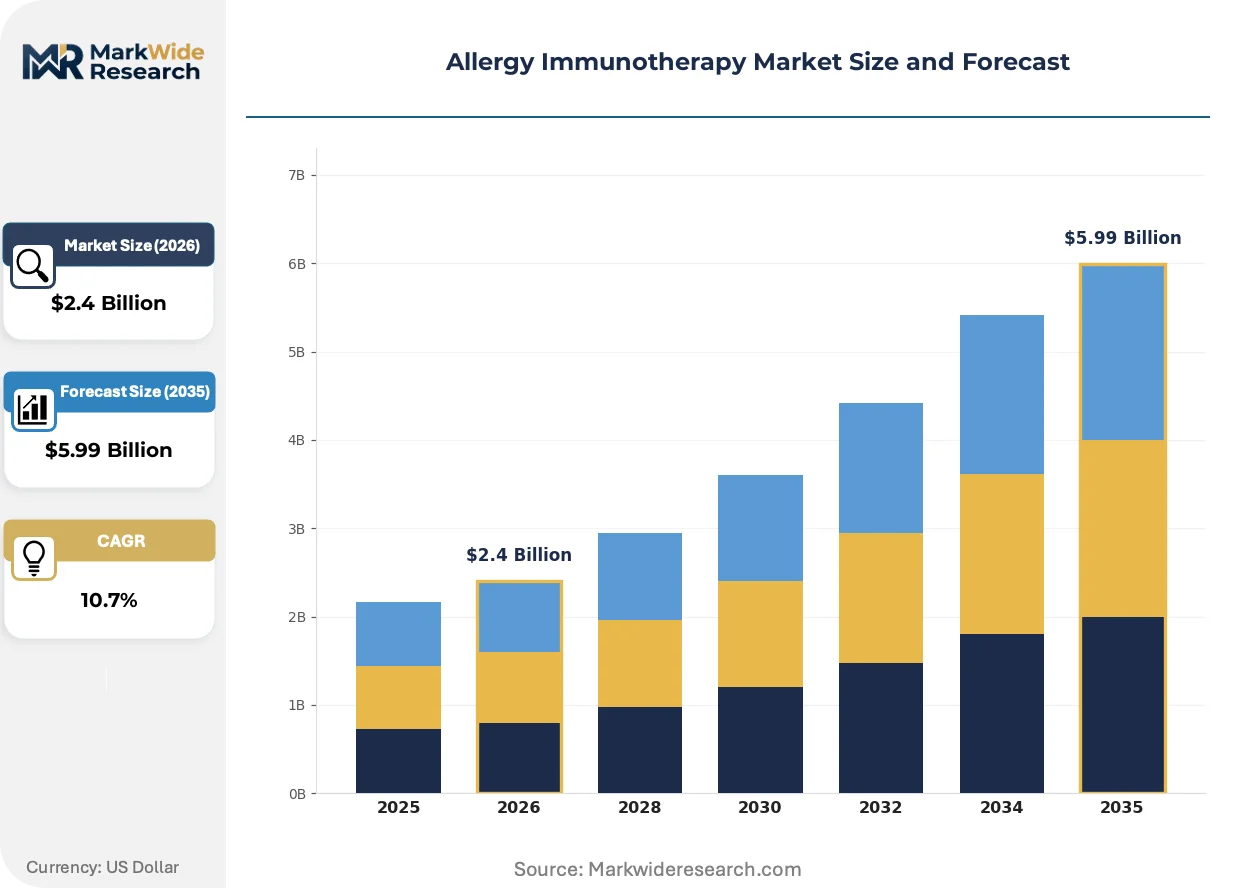
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.99 Billion |
| CAGR (2026 – 2036) | 10.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Subcutaneous Immunotherapy, Sublingual Immunotherapy, Oral Tablets, Nasal Sprays, Epicutaneous Immunotherapy Indication: Allergic Rhinitis, Asthma Control, Atopic Dermatitis, Food Allergy, Insect Venom Allergy End User: Specialty Clinics, Allergy Centers, Pediatric Care, Pulmonology Units, Dermatology Practices Delivery Mode: Injectable, Oral, Nasal, Transdermal, Sublingual Drops |
| Companies Covered | HAL Allergy Group, DBV Technologies, ALK-Abello, LETI Pharma, Torii Pharmaceutical, Stallergenes Greer, Aimmune Therapeutics, Merck KGaA, Allergy Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Allergy Immunotherapy Market Strategic Shifts & Innovations
Peptide immunotherapy platforms and digital adherence monitoring tools are converging to reshape how allergy specialists manage long-term desensitization regimens, compressing the gap between clinical trial efficacy and real-world outcomes.
Recombinant allergen technology is integrating precision protein engineering to replace crude natural extracts, enabling defined epitope targeting and reduced IgE-mediated side effect profiles. German-speaking allergy centers are adopting these next-generation formulations fastest, driven by integrated diagnostic-to-treatment platform investments from established manufacturers. This shift is enabling outcome-based contracting models that tie reimbursement to demonstrated symptom reduction metrics.
EMA centralized marketing authorization requirements for standardized extracts are intersecting with FDA BLA pathways to create divergent clinical trial obligations across Atlantic markets. Manufacturers must now maintain parallel documentation systems for biologic allergen products, elevating regulatory affairs capabilities from cost center to strategic differentiator. Pediatric food allergy indications face the steepest compliance burden under this dual-track framework.
Patient adherence contracts are displacing fee-for-service purchasing in Western European allergy clinics, with multi-year subscription models capturing lifetime patient value upfront. French and Italian pharmacy partnerships are replacing traditional wholesale distribution for sublingual drop regimens, concentrating channel control with manufacturers willing to invest in specialized logistics infrastructure. This behavioral shift is most visible in Nordic markets where public procurement frameworks favor total-cost-of-ownership calculations over unit pricing.
Allergy Immunotherapy Market Segmentation
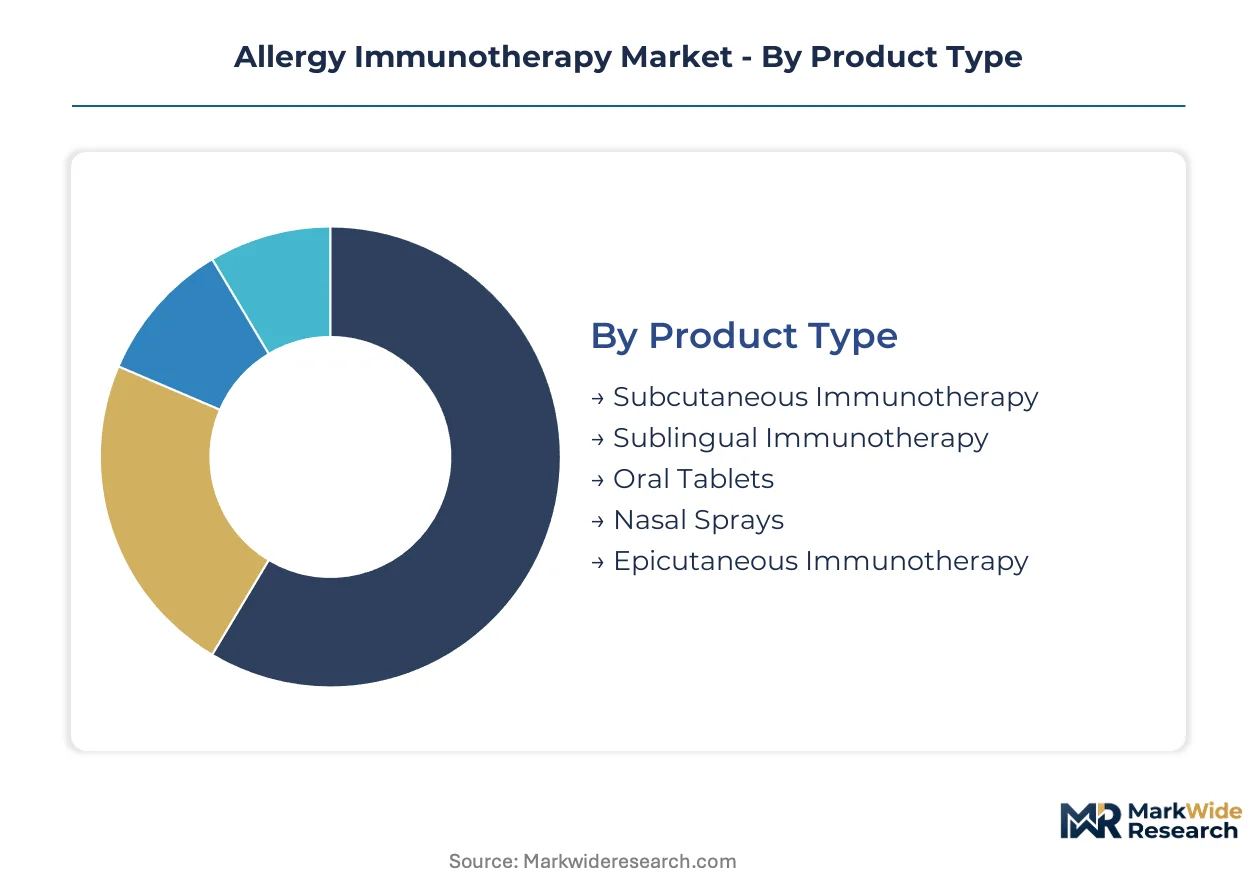
Segmentation in allergy immunotherapy reveals how treatment protocols fragment across clinical settings and patient populations. Each dimension exposes distinct procurement patterns, reimbursement pathways, and manufacturer positioning strategies that shape competitive dynamics.
Product Type:
Standalone administration dominates injectable and tablet formats, while embedded systems characterize combination diagnostic-to-treatment platforms.
- Subcutaneous Immunotherapy:Injectable allergen extracts administered in supervised clinical settings at standardized concentrations. German allergy centers and Nordic hospital networks anchor demand due to established reimbursement codes and specialty nursing infrastructure.
- Sublingual Immunotherapy:Home-administered drops or tablets inducing immune tolerance through oral mucosal exposure. French and Italian pharmacy partnerships are displacing wholesale distribution as patients prioritize convenience over clinic visits.
- Oral Tablets:Pre-measured allergen doses in solid form with extended stability profiles. Regulatory harmonization challenges across EMA and FDA pathways constrain launch sequencing.
- Nasal Sprays:Localized delivery for upper respiratory allergen exposure. Limited penetration outside seasonal rhinitis protocols.
- Epicutaneous Immunotherapy:Patch-based systems for transdermal allergen delivery. Pediatric food allergy indications in French and British centers drive early adoption.
Subcutaneous protocols lead volumes today; epicutaneous systems are gaining share fastest.
Indication:
Cost tier stratification separates chronic maintenance indications from acute intervention segments, with reimbursement depth varying accordingly.
- Allergic Rhinitis:Perennial and seasonal nasal inflammation driven by airborne allergens. Sublingual tablets in German-speaking regions capture volume as first-line disease-modifying therapy.
- Asthma Control:Immunotherapy as adjunct to pharmacological management for allergic asthma. British pulmonology units are expanding protocols following NICE guideline updates.
- Atopic Dermatitis:Skin barrier dysfunction with allergen sensitization component. French dermatology practices pilot sublingual protocols for moderate cases.
- Food Allergy:Desensitization for peanut, milk, and egg allergens. DBV Technologies and emerging competitors target this segment with patch-based pediatric solutions.
- Insect Venom Allergy:Life-threatening hypersensitivity to hymenoptera stings. Subcutaneous protocols remain standard across European allergy centers with mandatory observation periods.
Allergic rhinitis commands the largest patient base; food allergy applications are climbing the fastest.
End User:
Customer type determines procurement authority, with hospital-affiliated centers operating under distinct tender mechanisms versus independent practice purchasing.
- Specialty Clinics:Dedicated allergology practices with diagnostic and treatment capabilities. German and Austrian centers consolidate purchasing through regional buying cooperatives.
- Allergy Centers:Multidisciplinary facilities integrating immunotherapy with pulmonary and dermatological services. British NHS foundation trusts dominate this channel.
- Pediatric Care:Child-focused protocols with modified dosing regimens and adherence support. French hospital networks are expanding sublingual tablet access for school-age patients.
- Pulmonology Units:Respiratory-focused departments managing allergic asthma. Italian regional health systems fund integrated diagnostic-to-treatment pathways.
- Dermatology Practices:Skin-specialist settings addressing atopic conditions with allergen immunotherapy. Private practice concentration in Switzerland and Belgium.
Specialty clinics lead volumes today; pediatric care is expanding most quickly.
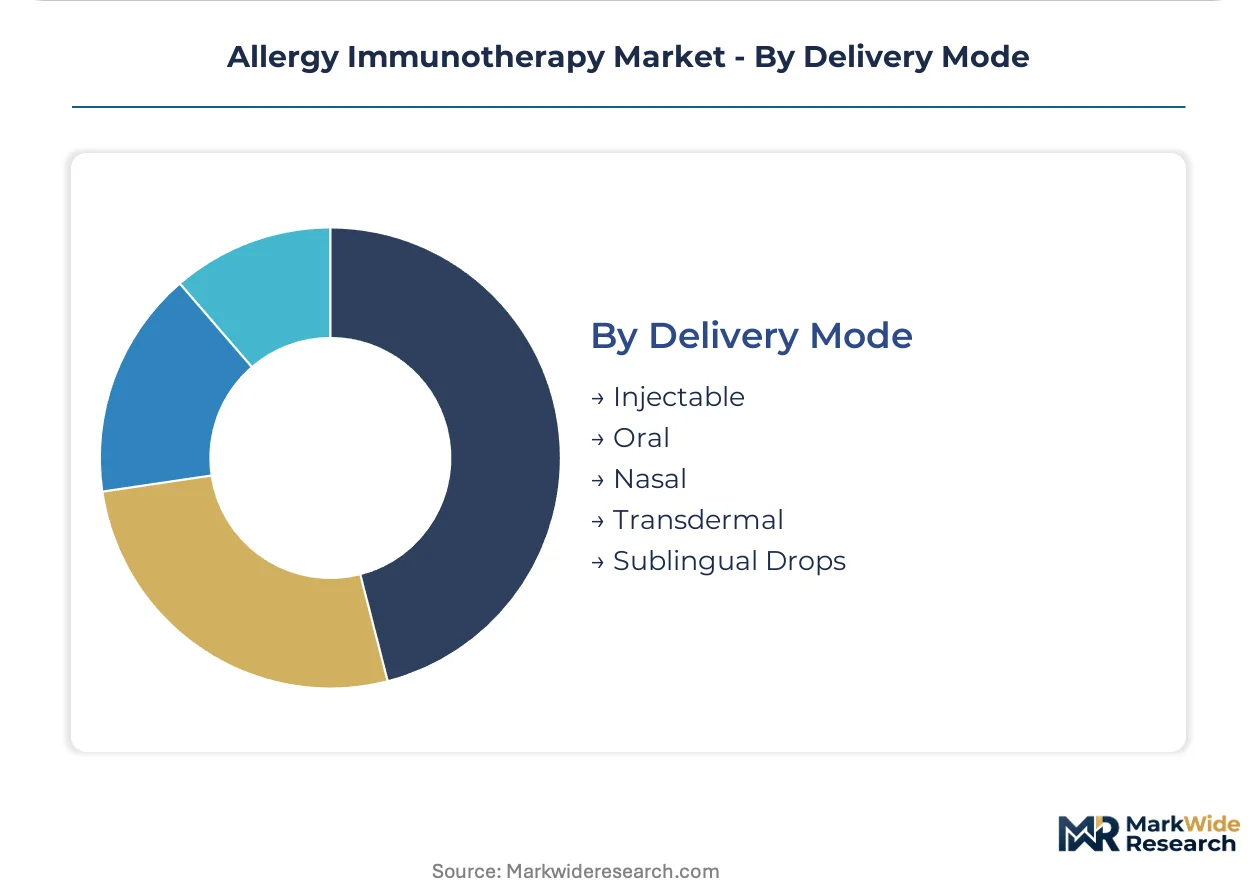
Delivery Mode:
Supply concentration in manufacturing infrastructure separates parenteral from non-parenteral formats, with biologics production capabilities limiting competitive entry.
- Injectable:Subcutaneous or intramuscular administration requiring clinical supervision. ALK-Abello and Stallergenes Greer anchor European supply through dedicated manufacturing facilities.
- Oral:Swallowed tablet or capsule formats with gastric absorption. Limited immunotherapy-specific applications outside combination products.
- Nasal:Topical mucosal delivery for localized immune response. Adjunctive use in seasonal protocols rather than standalone disease modification.
- Transdermal:Patch-mediated allergen exposure through intact skin. DBV Technologies' Viaskin platform represents the primary commercialization effort.
- Sublingual Drops:Liquid formulations absorbed under the tongue without swallowing. Italian and Spanish pharmacy networks are replacing clinic-based distribution for maintenance regimens.
Injectable formats dominate revenue today; sublingual drops are displacing share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and France diverge sharply in immunotherapy procurement models, with German allergy centers favoring integrated diagnostic-to-treatment platforms while French pharmacy networks drive sublingual tablet distribution through specialized partnerships.
Germany
Pediatric care networks in Bavaria and North Rhine-Westphalia are expanding sublingual immunotherapy protocols for school-age patients. The Federal Joint Committee (G-BA) maintains stringent outcome-based reimbursement criteria that tie long-term desensitization payments to demonstrated symptom reduction metrics. Frankfurt and Munich anchor manufacturing and clinical trial activity for recombinant allergen formulations.
France
Pharmacy partnerships in Lyon and Marseille are replacing traditional wholesale distribution for sublingual drop regimens, concentrating channel control with manufacturers investing in cold-chain logistics. ANSM oversight of allergen extract standardization aligns with EMA centralized marketing authorization requirements. Paris-based allergy centers pilot epicutaneous patch systems for pediatric food allergy indications.
United Kingdom
NHS foundation trusts in London and Manchester dominate procurement through regional buying cooperatives for injectable subcutaneous protocols. NICE guideline updates are expanding immunotherapy access within British pulmonology units for allergic asthma management. The Medicines and Healthcare products Regulatory Agency (MHRA) enforces post-Brexit divergence from EU MDR technical documentation standards.
Italy
Regional health systems in Lombardy and Emilia-Romagna fund integrated diagnostic-to-treatment pathways linking allergen testing to personalized formulation services. Italian pharmacy networks are displacing clinic-based distribution for sublingual maintenance regimens. Milan anchors specialized logistics infrastructure for temperature-controlled allergen extract handling.
Spain
Barcelona and Madrid allergy centers concentrate demand for home-administered tablet formats as patients prioritize convenience over supervised injection visits. The Spanish Agency for Medicines and Health Products (AEMPS) enforces EMA-aligned clinical evidence requirements for standardized extracts. Pediatric networks in Catalonia are piloting digital adherence monitoring tools for long-term desensitization regimens.
Allergy Immunotherapy Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with consolidated positions in subcutaneous injectables contrasting fragmented competition in emerging epicutaneous formats. Three to five established players anchor European supply through dedicated allergen extract manufacturing facilities. Strategic archetypes include integrated diagnostic-to-treatment platform operators, specialized pharmacy partnership builders, and recombinant protein engineering specialists. Competitive moves center on multi-year patient adherence contracts and regional buying cooperative penetration.
Within the integrated platform tier, Merck KGaA and ALK-Abello exemplify divergent geographic anchoring strategies, with the former concentrating on German-speaking diagnostic-to-treatment convergence and the latter leveraging Nordic distribution infrastructure for service-based contracts. DBV Technologies occupies a distinct position representing the epicutaneous delivery archetype, with patch-based systems targeting pediatric food allergy indications where incumbent competition remains limited. Stallergenes Greer sits within the pharmacy partnership model, its French and Italian channel investments illustrating how specialized logistics capabilities can reshape procurement patterns away from traditional wholesale relationships.
| Leading Market Players |
|---|
| HAL Allergy Group |
| DBV Technologies |
| ALK-Abello |
| LETI Pharma |
| Torii Pharmaceutical |
| Stallergenes Greer |
| Aimmune Therapeutics |
| Merck KGaA |
| Allergy Therapeutics |
| Others |
Cost & Logistics Intelligence
Captive allergen extract manufacturing in Germany and Denmark anchors both supply security and pricing power for established European manufacturers, insulating them from third-party purification cost volatility while enabling multi-year patient adherence contracting.
Pricing Analysis
Capacity additions in France and Italy are reshaping price floors for sublingual tablet formats as pharmacy partnerships displace wholesale markups. Three-tier pricing structure across premium recombinant formulations, standard natural extracts, and economy bulk protocols separates manufacturers by technical documentation depth. Pricing pressure stems from divergent health technology assessment timelines across German, French, and British reimbursement bodies. Pediatric care networks exhibit highest price sensitivity due to budget cap constraints, while specialty clinics with established nursing infrastructure show lowest sensitivity.
Supply Chain Analysis
EMA centralized marketing authorization and FDA BLA compliance certifications gate entry for allergen extract suppliers, concentrating viable production in Germany, France, and Denmark. Source material draws from standardized pollen, mite, and venom collections with batch-to-batch biological variability as the primary quality assurance challenge. Single-source vulnerability runs through specialized cold-chain logistics providers for temperature-sensitive extracts. Distribution runs through pharmacy partnership networks in Southern Europe and regional buying cooperatives in German-speaking markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between EU MDR technical documentation requirements and FDA peptide immunotherapy guidance creates cost differentials for manufacturers with parallel compliance capabilities.
For Market Incumbents: Deploy diagnostic-to-treatment platform integration to lock in patient lifetime value before recombinant allergen specialists capture German-speaking markets. Consolidate positions through captive extract manufacturing investments that insulate against raw material standardization failures. Counter subscription-based pharmacy partnerships by anchoring multi-year adherence contracts directly with Nordic public health procurement frameworks. For New Entrants and Emerging Players: Direct-to-clinic digital adherence monitoring tools offer the lowest barrier entry path for pediatric food allergy indications where patch-based delivery remains underpenetrated. Target British NHS foundation trusts with outcome-based contracting models aligned to NICE guideline updates for allergic asthma. Pursue specialized logistics partnerships in Italy and Spain to bypass entrenched wholesale relationships. For Investors and Strategic Acquirers: Roll-up economics work for recombinant protein engineering specialists because EU MDR documentation requirements have eliminated sub-scale competitors from viable acquisition pools. Five-to-ten-year viability hinges on peptide immunotherapy platform maturation. Monitor EMA-FDA regulatory convergence signals as the primary inflection indicator for cross-Atlantic manufacturing consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | Aligns German G-BA outcome metrics with French ANSM pharmacy partnership requirements. |
| Manufacturing Scale-Up | Expands recombinant allergen capacity in Frankfurt and Munich clusters. |
| Regulatory Approval Pathway | Navigates divergent EMA centralized and FDA BLA documentation demands. |
| Platform Integration | Links diagnostic testing to personalized immunotherapy formulation services. |
| Strategic Partnership | Secures cold-chain logistics for sublingual drop distribution in Lyon and Marseille. |
Research Approach
Direct dialogue with allergy center medical directors, pharmaceutical regulatory affairs leads, hospital procurement managers, and specialized pharmacy network operators grounded qualitative findings, cross-referenced against EMA marketing authorization databases, FDA BLA submission records, ClinicalTrials.gov immunotherapy protocols, and national health technology assessment body publications. Bottom-up patient volume estimates and top-down manufacturer revenue analysis provided triangulation.
Bottom-up modeling aggregated allergen extract production capacity by delivery mode and indication, while top-down analysis calibrated against reimbursement expenditure data across German statutory health insurance, French national health system, and British NHS foundation trust procurement records. Segmentation dimensions included product type, indication, end user, and delivery mode. CAGRs derived from historical immunotherapy adoption curves and projected desensitization protocol expansion rates.
The model assumes a particular technology adoption path; alternative pathways for epicutaneous patch systems would alter the outlook. Forecasts reflect assumptions about EU MDR implementation timelines and pediatric food allergy indication approvals. A model refresh is warranted upon material change in EMA-FDA regulatory convergence or German reimbursement outcome metric recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Medicine
Acupuncture Lasers Market
Alternative Medicine
Electrotherapy Market
Alternative Medicine
US Chiropractic Market
Alternative Medicine
Disposable Acupuncture Needle Market
Alternative Medicine
Biopuncture Treatment Market
Alternative Medicine
Aromatherapy Market
Alternative Medicine
Global Homeopathic Product Market
Alternative Medicine
Cold Laser Therapy Market
Alternative Medicine
Orthomolecular Medicine Market
Alternative Medicine
Global Acupuncture Market
Alternative Medicine
Fire Cupping Market
Alternative Medicine
Global OTC Herbal and Traditional Medicine Market
Alternative Medicine
US Aromatherapy Market
Alternative Medicine
Complementary and Alternative Medicine for Anti Aging and Longevity Market
Alternative Medicine
Ozone Therapy Units Market
Alternative Medicine
Homeopathy Products Market