
 Complementary and Alternative Medicine for Anti Aging and Longevity Market | 2026-2036
Complementary and Alternative Medicine for Anti Aging and Longevity Market Size, Share, and Industry Trends Forecast 2026-2036
Complementary and Alternative Medicine for Anti Aging and Longevity Market Intelligence
Personalized nutrigenomics is rewriting how anti-aging protocols are formulated and delivered, shifting from generic supplement regimens to DNA-matched compound blends. Dabur India leverages its Ayurvedic manufacturing scale to supply standardized herbal extracts across Asian wellness markets. Sulwhasoo anchors premium skin rejuvenation segments through hanbang-based formulations with documented ginsenoside concentrations.
Complementary and alternative medicine for anti-aging and longevity encompasses botanical extracts, needle-based stimulation techniques, dilute therapeutic preparations, and targeted micronutrient formulations designed to modulate cellular senescence, oxidative stress markers, and metabolic function. These interventions serve both preventive wellness consumers and clinical longevity programs seeking non-pharmaceutical intervention pathways. Nutritional Supplements captures the largest margin pool due to recurring purchase patterns and formulation patentability, while Acupuncture grows fastest among clinic-based delivery modes as licensed practitioners expand into cosmetic and regenerative applications. Herbal Remedies maintains volume leadership in retail channels across South Asian and Southeast Asian markets where traditional medicine systems retain strong consumer trust.
FDA oversees dietary supplement GMP compliance and adverse event reporting through its Office of Dietary Supplement Programs, while EMA's Herbal Medicinal Products Committee evaluates monograph standards for botanical longevity claims in European markets. India's Ministry of AYUSH promotes Ayurvedic anti-aging research through dedicated research councils and export certification schemes. Stakeholders must monitor how evolving pharmacovigilance requirements for traditional medicine products reshape formulation transparency and cross-border market access conditions.
Market Dynamics
The convergence of nutrigenomic testing platforms with traditional herbal formulation is compressing protocol development cycles and forcing manufacturers to integrate DNA analytics into product pipelines.
Growth Catalysts
- DSHEA Enforcement Priorities:FDA's clarified adverse event reporting requirements for dietary supplements are building consumer confidence in longevity product safety profiles and expanding retail pharmacy distribution.
- Cosmetic Acupuncture Applications:Licensed practitioners in South Korea and Japan are expanding needle-based techniques into facial rejuvenation clinics, creating new revenue streams beyond pain management.
- BfArM Reimbursement Trials:Germany's expanded coverage experiments for homeopathic anti-aging treatments are attracting private clinic investment and validating dilute therapeutic preparations for longevity protocols.
Market Restraints
- Botanical Supply Concentration:Wild-harvested ginseng and ashwagandha root dependencies on Indian and Chinese agricultural zones create raw material volatility and authentication challenges.
- EMA Monograph Delays:Pending Herbal Medicinal Products Committee evaluations for novel longevity claims are freezing product launch timelines across European markets.
- Biomarker Standardization Gaps:Absence of consensus oxidative stress and telomere length measurement protocols limits clinical trial comparability and insurance reimbursement negotiations.
Strategic Opportunities
- Subscription-Based Personalized Formulations:Direct-to-consumer nutrigenomic services in the US are creating recurring revenue models that bypass traditional retail pharmacy markups.
- Ministry of AYUSH Export Certification:India's dedicated research councils and quality authentication schemes are opening standardized Ayurvedic anti-aging products to Middle Eastern and Southeast Asian markets.
- Acupuncture-Pharma Integration:Japanese metabolic clinics are combining needle-based stimulation with GLP-1 protocols, creating hybrid delivery models for longevity-focused patients.
Industry Challenges
- Practitioner Certification Bottlenecks:Licensed acupuncture training programs cannot scale quickly enough to meet cosmetic and regenerative application demand in urban wellness centers.
- GMP Compliance Capital Requirements:Small-scale herbal extract manufacturers face facility upgrade costs to meet FDA dietary supplement manufacturing standards without losing margin to contract manufacturers.
- Cross-Border Pharmacovigilance Complexity:Divergent traditional medicine safety reporting requirements between FDA, EMA, and India's CDSCO are fragmenting global product registration strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Complementary and Alternative Medicine for Anti Aging and Longevity Market |
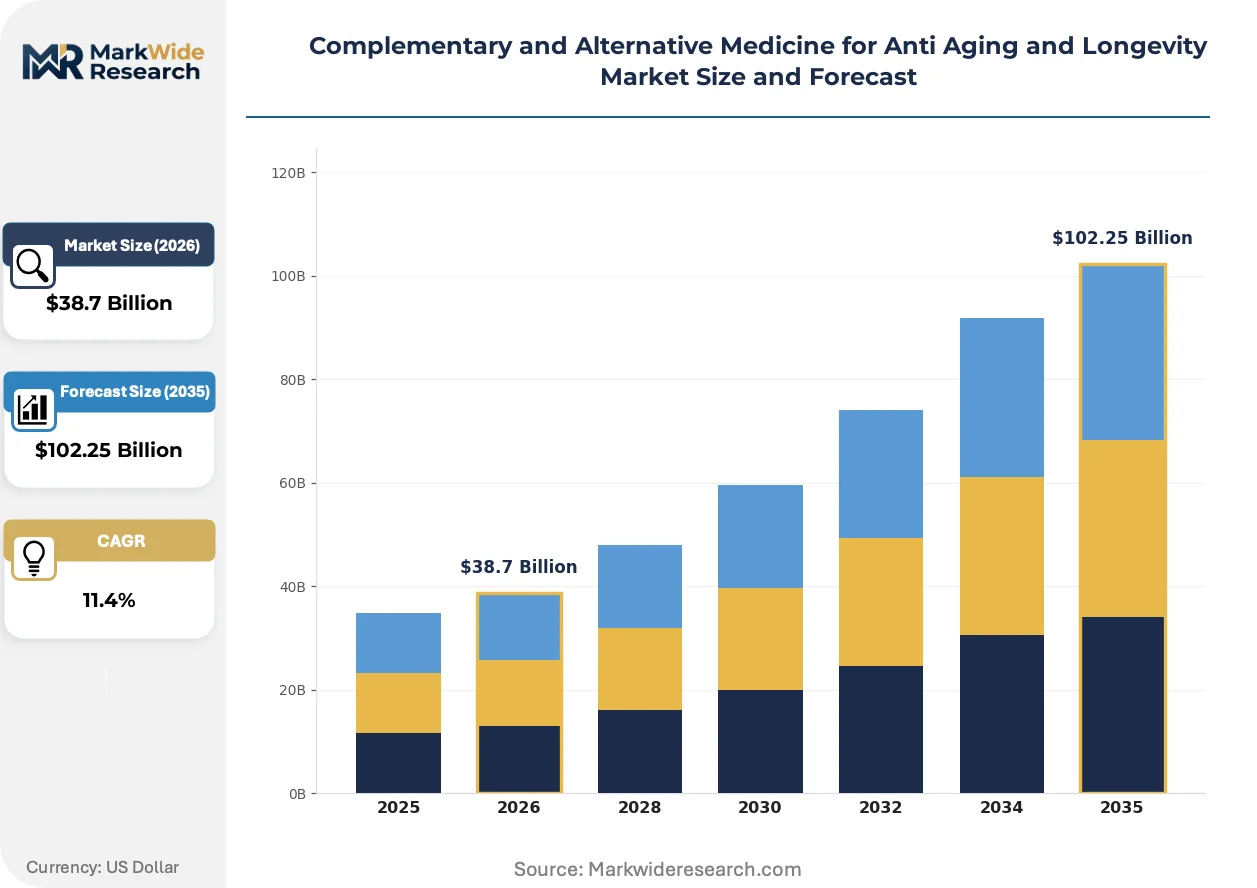
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbal Remedies, Acupuncture, Homeopathy, Nutritional Supplements Application: Skin Rejuvenation, Weight Management, Stress Relief, Cellular Repair End User: Individuals, Wellness Centers, Clinics, Healthcare Practitioners Delivery Mode: In-person Sessions, Online Consultations, Workshops, Retail Products |
| Companies Covered | Dabur India, Patanjali Ayurved, Sulwhasoo, iHerb, Mountain Rose Herbs, Kama Ayurveda, Herb Pharm, Anadolu Medical Center, Sinomedica, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Complementary and Alternative Medicine for Anti Aging and Longevity Market Strategic Shifts & Innovations
DNA-matched compound blending is replacing generic supplement regimens as the dominant formulation paradigm, compressing development cycles and rewiring competitive advantage toward bioinformatics capabilities.
Multi-omics screening platforms are migrating from research laboratory settings into consumer-facing wellness applications. Functional medicine clinics in California and Texas are adopting whole-genome sequencing plus metabolomic panels as standard intake protocols. This technology shift is enabling personalized anti-aging stacks that displace one-size-fits-all longevity supplements.
EMA's Herbal Medicinal Products Committee is tightening monograph standards for botanical longevity claims, requiring documented ginsenoside and withanolide concentration thresholds. European manufacturers must now submit chromatographic fingerprinting data for registration. German and Swiss markets are responding by investing in in-house phytochemical testing laboratories rather than outsourcing to third-party certifiers.
Subscription-based replenishment models are capturing recurring revenue from preventive wellness consumers who previously purchased supplements through retail pharmacies. Direct-to-consumer brands in the US and UK are bundling at-home biomarker testing with automated formula adjustments. This channel shift is most visible among high-income urban demographics aged 45-65 seeking continuous protocol optimization without clinic visits.
Complementary and Alternative Medicine for Anti Aging and Longevity Market Segmentation
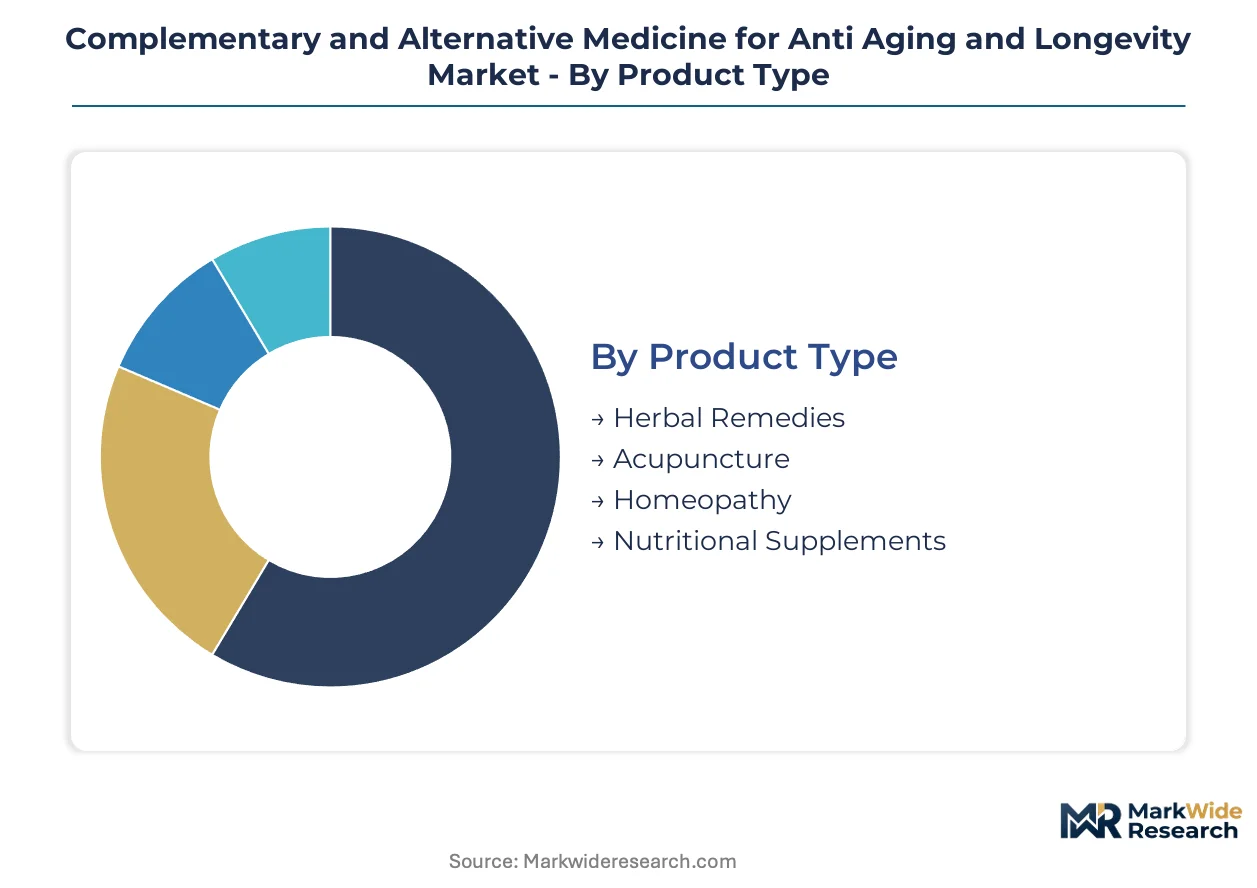
Segmentation in the complementary and alternative medicine for anti-aging and longevity market reveals distinct service intensity requirements across product categories. After-sales engagement varies dramatically between one-time retail purchases and ongoing practitioner relationships, reshaping how manufacturers allocate customer support resources.
Product Type:
After-sales-service intensity diverges sharply across these categories, with practitioner-delivered modalities demanding sustained client relationship management while retail products require minimal post-purchase contact.
- Herbal Remedies:Standardized botanical extracts and traditional formulations require batch-specific quality documentation and adverse event monitoring. Demand concentrates in German wellness clinics pursuing BfArM reimbursement eligibility, where documented phytochemical profiles determine insurance coverage acceptance.
- Nutritional Supplements:Targeted micronutrient stacks and DNA-matched compound blends dominate direct-to-consumer channels with subscription replenishment models. Recurring purchase patterns in US urban markets drive formulation patent investments and automated formula adjustment services.
- Acupuncture:Licensed needle-based stimulation techniques for cosmetic and regenerative applications carry high practitioner dependency.
- Homeopathy:Dilute therapeutic preparations face regulatory scrutiny despite German coverage experiments.
Nutritional Supplements holds the largest share; momentum sits with Acupuncture.
Application:
Cost tier stratification separates premium clinic-based interventions from accessible self-administered protocols, with price elasticity varying significantly across therapeutic goals.
- Skin Rejuvenation:Topical botanical applications and cosmetic acupuncture protocols target visible aging markers with measurable outcome expectations. Premium positioning in South Korean facial clinics drives ginsenoside concentration standardization and practitioner certification investments.
- Cellular Repair:Senolytic herbal compounds and metabolic support formulations address biological aging mechanisms through systemic intervention. Research-oriented wellness centers in Switzerland and Japan prioritize biomarker-validated protocols with telomere length monitoring.
- Weight Management:Metabolic modulation through traditional medicine systems competes with pharmaceutical alternatives.
- Stress Relief:Adaptogenic formulations and mindfulness-based delivery modes serve preventive wellness consumers.
Skin Rejuvenation commands premium pricing; Cellular Repair gains share fastest.
End User:
Volume concentration patterns reveal how institutional procurement scales differently than individual purchasing, with bulk formulation contracts reshaping manufacturing priorities.
- Wellness Centers:Integrated longevity protocols combining multiple modalities require vendor consolidation and protocol standardization. North American facilities expanding into Ayurvedic and traditional Chinese medicine drive bulk herbal extract procurement and staff certification programs.
- Individuals:Direct-to-consumer purchases through subscription services and retail pharmacies dominate unit volume. Personalized nutrigenomic testing adoption in high-income demographics shifts purchasing toward DNA-matched formulations with automated replenishment.
- Clinics:Medical facility integration demands regulatory compliance documentation.
- Healthcare Practitioners:Independent provider networks influence prescription patterns.
Wellness Centers represents the largest institutional segment; Individuals drive volume expansion.
Delivery Mode:
Customer type differentiation separates high-touch service relationships from transactional product sales, with channel strategy determining margin capture and retention economics.
- In-person Sessions:Practitioner-administered acupuncture and consultation-based protocol development command premium pricing and loyalty advantages. Japanese metabolic clinics combining needle-based stimulation with pharmaceutical protocols illustrate hybrid service model evolution.
- Retail Products:Standardized supplements and herbal preparations through pharmacies and specialty stores maximize accessibility. India's Ministry of AYUSH export certification schemes enable Middle Eastern market penetration for authenticated Ayurvedic formulations.
- Online Consultations:Telehealth-enabled protocol customization expands geographic reach.
- Workshops:Group education formats reduce per-client service costs.
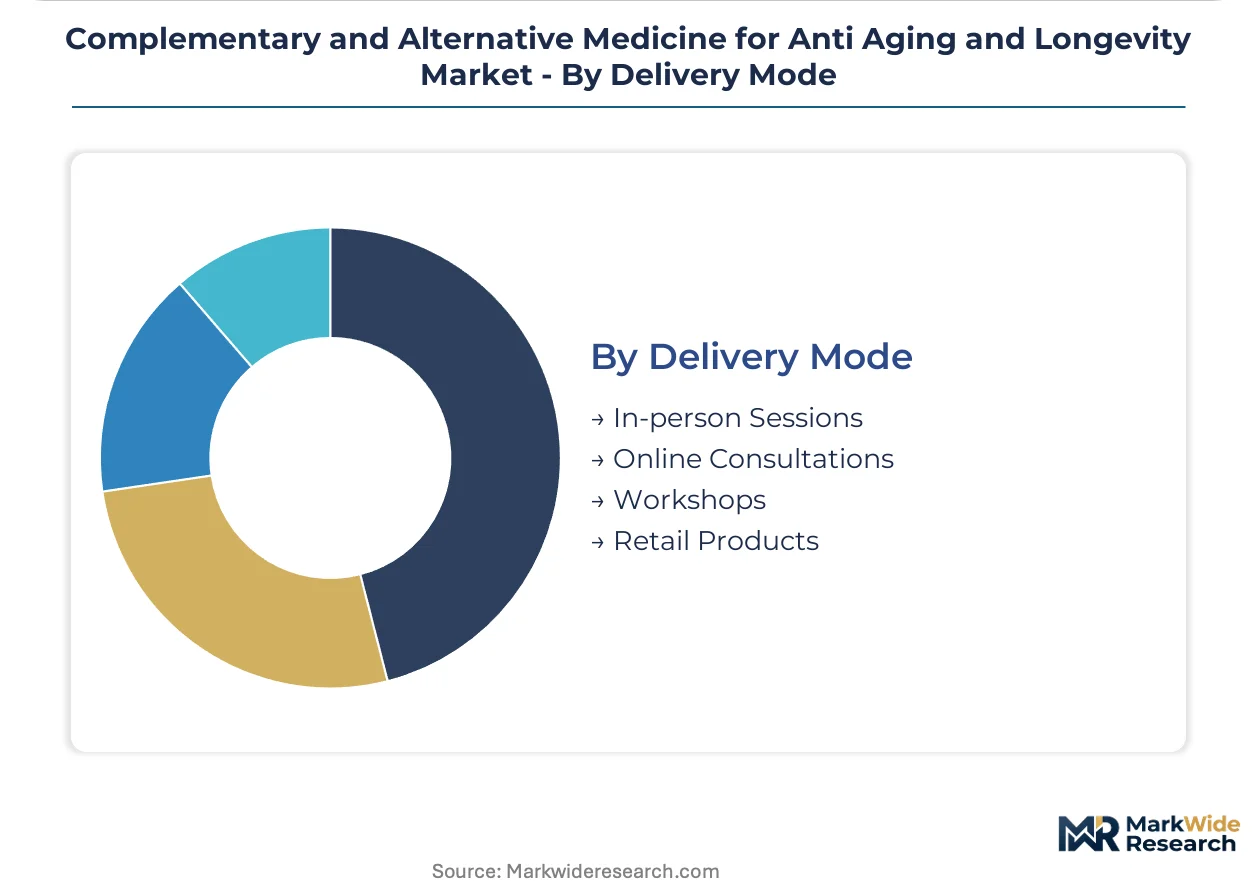
Retail Products holds broadest penetration; In-person Sessions carries highest lifetime value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export certification schemes and cross-border nutrigenomic service flows are reshaping regional trade balances, with raw material sourcing from South Asia and finished formulation distribution concentrating in North American and European wellness channels.
United States
Direct-to-consumer nutrigenomic platforms and subscription supplement services drive demand intensity in urban coastal markets. FDA's Office of Dietary Supplement Programs enforces GMP compliance and adverse event reporting requirements that determine retail pharmacy access. California functional medicine clusters in Los Angeles and San Francisco integrate whole-genome sequencing with Ayurvedic protocol customization.
Germany
Wellness clinic investment and homeopathic treatment reimbursement experiments concentrate demand in metropolitan wellness corridors. BfArM's expanded coverage trials for dilute therapeutic preparations validate longevity protocol insurance acceptance. Berlin and Munich host phytochemical testing laboratory expansions serving EMA monograph compliance requirements.
India
Standardized herbal extract manufacturing and AYUSH export certification schemes position the country as raw material supplier to Middle Eastern and Southeast Asian markets. The Ministry of AYUSH promotes dedicated research councils and quality authentication programs. Manufacturing clusters in Uttar Pradesh and Gujarat scale Ayurvedic anti-aging formulation output for international distribution.
Japan
Cosmetic acupuncture applications and metabolic clinic hybrid protocols combine needle-based stimulation with pharmaceutical interventions. METI oversight of wellness technology integration shapes clinic licensing frameworks. Tokyo and Osaka anchor facial rejuvenation practitioner certification programs expanding into regenerative medicine applications.
South Korea
Premium skin rejuvenation segments and hanbang-based formulation standardization drive ginsenoside concentration documentation requirements. MFDS regulation of cosmetic acupuncture clinics shapes service delivery protocols. Seoul's Gangnam district concentrates facial rejuvenation centers integrating traditional medicine with aesthetic dermatology.
Complementary and Alternative Medicine for Anti Aging and Longevity Market Key Industry Players
On the supply side, the industry is tiered between multinational botanical extract manufacturers, direct-to-consumer nutrigenomic platforms, and regional traditional medicine specialists. Three strategic archetypes dominate: vertically integrated Ayurvedic conglomerates with captive agricultural supply, subscription-based personalized formulation services leveraging bioinformatics capabilities, and premium cosmetic acupuncture clinic networks. Competitive intensity centers on formulation patent investments and practitioner certification scale.
Among India-based Ayurvedic manufacturers, Dabur India exemplifies scale-driven vertical integration from agricultural sourcing through standardized extract production. Sulwhasoo occupies a position within the premium hanbang formulation tier, anchoring ginsenoside concentration documentation as a competitive differentiator. Patanjali Ayurved represents the mass-market Ayurvedic archetype, leveraging domestic distribution density to compete on accessibility metrics.
| Leading Market Players |
|---|
| Dabur India |
| Patanjali Ayurved |
| Sulwhasoo |
| iHerb |
| Mountain Rose Herbs |
| Kama Ayurveda |
| Herb Pharm |
| Anadolu Medical Center |
| Sinomedica |
| Others |
Cost & Logistics Intelligence
Single-source dependency on wild-harvested ginseng and ashwagandha root from Indian and Chinese agricultural zones compresses pricing tier spreads between authenticated premium extracts and unverified commodity grades while forcing supply chain consolidation around vertically integrated manufacturers with captive cultivation contracts.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the nutritional supplements segment. Price differentiation stems from documented phytochemical concentration thresholds and FDA GMP certification tier, with premium tiers commanding spreads based on chromatographic fingerprinting data. Cost compression in the economy tier is intensifying because contract manufacturers compete for wellness center bulk procurement contracts. Individual consumers through subscription services exhibit the lowest price sensitivity, while retail pharmacy distributors face margin pressure from direct-to-consumer channel displacement.
Supply Chain Analysis
Extended payment terms from German wellness clinics pursuing BfArM reimbursement eligibility are reshaping supplier financing structures for botanical extract manufacturers. Raw material sourcing draws from India, China, and South Korea for standardized herbal inputs including ginseng root, ashwagandha, and fermented hanbang bases. Single-source vulnerability concentrates in wild-harvested ginseng from specific Korean mountain regions. Distribution runs through direct-to-consumer subscription platforms, specialized wellness center procurement channels, and authenticated retail pharmacies with Ministry of AYUSH export certification documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
DNA-matched nutrigenomic formulation platforms are disrupting generic supplement regimens, with FDA's clarified DSHEA enforcement priorities creating regulatory inflection points that separate compliant manufacturers from adverse event reporting laggards.
For Market Incumbents: Insulate formulation patent portfolios against bioinformatics-enabled entrants by investing in captive ginseng cultivation contracts in Korean agricultural zones and acquiring chromatographic testing laboratories to secure EMA monograph compliance ahead of Herbal Medicinal Products Committee evaluations. Certification investment in Ministry of AYUSH export schemes opens Middle Eastern market access before regional competitors consolidate distribution. For New Entrants and Emerging Players: Cosmetic acupuncture protocols in Japanese metabolic clinics represent the most penetrable entry point for needle-based stimulation services, with hybrid GLP-1 integration models creating differentiated positioning against standalone pharmaceutical alternatives. Practitioner certification scale in South Korean facial rejuvenation centers offers second-mover advantage through accelerated training program partnerships with existing clinic networks. For Investors and Strategic Acquirers: BfArM's expanded reimbursement trials for homeopathic anti-aging treatments reshape the acquisition landscape toward German wellness clinic networks with documented insurance coverage acceptance. Long-term viability centers on platforms combining nutrigenomic testing with automated formula adjustment capabilities. The signal to watch is EMA monograph approval velocity for novel longevity claims, which would unlock European market access for previously frozen product pipelines.| Strategic Initiative | Industry Significance |
|---|---|
| Chromatographic Testing Laboratory Investment | German manufacturers secure EMA monograph compliance ahead of Herbal Medicinal Products Committee evaluations. |
| Practitioner Certification Scale-Up | South Korean facial rejuvenation clinics expand cosmetic acupuncture capacity beyond pain management applications. |
| Subscription Platform Integration | Direct-to-consumer brands capture recurring revenue through automated nutrigenomic formula adjustments. |
| Ministry of AYUSH Export Certification | Indian manufacturers unlock Middle Eastern distribution through quality authentication schemes. |
| Hybrid Protocol Development | Japanese metabolic clinics combine needle-based stimulation with pharmaceutical interventions for longevity patients. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA adverse event reporting databases, EMA Herbal Medicinal Products Committee submissions, Ministry of AYUSH export certification records, and customs trade data for standardized botanical extracts. Primary interviews engaged functional medicine clinic directors, Ayurvedic manufacturing procurement leads, licensed acupuncture practitioners, wellness center operations managers, and nutrigenomic platform product directors. Bottom-up demand modeling from individual subscription patterns and wellness center procurement contracts triangulates against top-down market sizing from regulatory filing volumes and trade flow analysis.
Forecast inputs include modeled segmentation across product type, application, end user, and delivery mode dimensions, with additional granularity on phytochemical concentration tier and certification status. CAGRs derive from regression analysis of historical subscription growth patterns, clinic expansion rates, and regulatory approval velocity across the projection horizon. Industry-specific inputs incorporate BfArM reimbursement trial enrollment trajectories and FDA Office of Dietary Supplement Programs enforcement action frequency.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending on preventive wellness, agricultural commodity price volatility for ginseng and ashwagandha, or regulatory enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions on nutrigenomic adoption curves and practitioner certification scaling capacity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Medicine
Orthomolecular Medicine Market
Alternative Medicine
Aromatherapy Market
Alternative Medicine
Homeopathic Medicine Market
Alternative Medicine
Traditional Chinese Medicine Market
Alternative Medicine
Allergy Immunotherapy Market
Alternative Medicine
Bio Magnetic Ear Stickers Market
Alternative Medicine
Acupuncture Lasers Market
Alternative Medicine
Natural Cold, Cough, and Sore Throat Remedies Market
Alternative Medicine
Global Complementary and Alternative Medicines Market
Alternative Medicine
Global Homeopathic Product Market
Alternative Medicine
Flower Essences Market
Alternative Medicine
Biopuncture Treatment Market
Alternative Medicine
Traditional Chinese Herbal Medicine Market
Alternative Medicine
US Aromatherapy Market
Alternative Medicine
Disposable Acupuncture Needle Market
Alternative Medicine
Vacuum Cupping Market