
 Human Combination Vaccines Market | 2026-2036
Human Combination Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
Human Combination Vaccines Market Outlook
Market Context
Premium multivalent formulations and commodity single-combination vaccines are rebalancing across procurement channels, with UNICEF and Gavi driving volume while private markets reward complex antigen cocktails. GlaxoSmithKline leverages its adjuvant platforms to sustain margin in high-complexity pediatric combinations. Sanofi Pasteur anchors European supply security through multi-site manufacturing. Serum Institute of India dominates affordable pentavalent and hexavalent supply for low-income country programs.
Technical Definition and Segment Structure
Human combination vaccines are biologics containing two or more antigens in a single formulation, produced through fermentation, purification, and formulation steps that preserve immunogenicity while preventing antigenic interference between components. Their primary purpose is reducing injection burden, improving compliance, and lowering cold-chain logistics costs for national immunization programs. Conjugate vaccines lead value generation due to complex chemistry and pneumococcal-meningococcal premium positioning, while live attenuated platforms face constrained capacity and higher biosafety infrastructure requirements. Intramuscular delivery occupies the dominant share, though intranasal routes are gaining development priority for respiratory combination candidates.
Regulatory Framework and Outlook
FDA's Center for Biologics Evaluation and Research and EMA's Committee for Medicinal Products for Human Use set the benchmark for combination vaccine licensure through comparative immunogenicity and non-inferiority trial designs. WHO prequalification unlocks Gavi and UNICEF procurement eligibility, creating a dual-track regulatory reality where manufacturers navigate separate standards for donor-funded and commercial markets. Stakeholders must monitor how the EU AI Act and FDA's evolving guidance on platform technologies will reshape clinical evidence requirements for next-generation combinations.
Market Dynamics
mRNA platform convergence with established conjugate chemistry is compressing development timelines and forcing legacy manufacturers to rebuild biological production capabilities around nucleic acid manufacturing infrastructure.
Growth Catalysts
- WHO Prequalification Pathway:The WHO prequalification program accelerates Gavi and UNICEF procurement eligibility, channeling donor-funded volume toward compliant manufacturers and standardizing quality benchmarks across low-income country immunization programs.
- Hexavalent Formulation Demand:National health systems in India and Nigeria are consolidating infant schedules around six-antigen single-injection products, reducing cold-chain logistics burden and improving caregiver compliance rates.
- Intramuscular-to-Intranasal Route Migration:Respiratory combination candidates are prioritizing mucosal delivery platforms, promising superior IgA response profiles and needle-free administration for pediatric populations.
Market Restraints
- Fermentation Capacity Concentration:Bulk antigen production concentrates among three dominant biologics manufacturers, creating supply vulnerability when microbial contamination events trigger multi-month batch recovery cycles.
- EMA Non-Inferiority Trial Costs:The Committee for Medicinal Products for Human Use mandates expanded immunogenicity cohorts for novel combinations, driving Phase III expenditure beyond reach of mid-scale developers.
- Aluminum Adjuvant Price Volatility:Primary aluminum salt suppliers face energy cost pressure from European carbon border adjustments, transmitting input inflation to formulation economics.
Strategic Opportunities
- Indonesian Domestic Manufacturing Scale-Up:The country's national immunization program expansion creates procurement volume for local fill-finish partnerships with technology transfer from established conjugate producers.
- FDA Platform Technology Designation:The Center for Biologics Evaluation and Research's evolving guidance on master protocol trials promises streamlined licensure for mRNA-based combination candidates leveraging prior safety databases.
- Direct Government Contracting Channels:Brazil's ANVISA and national procurement agency are bypassing traditional distributor networks for pentavalent and hexavalent tenders, compressing margin leakage and accelerating payment cycles.
Industry Challenges
- Antigen-Stabilization Formulation Expertise Gap:The specialized protein chemistry workforce required for multi-valent shelf-life extension concentrates at legacy European and North American facilities, constraining technology transfer to emerging manufacturing hubs.
- Legacy Cold-Chain Infrastructure Integration:National immunization programs in sub-Saharan Africa operate 2-8°C distribution networks ill-suited to frozen mRNA storage requirements, forcing reformulation investment or parallel supply system construction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Human Combination Vaccines Market |
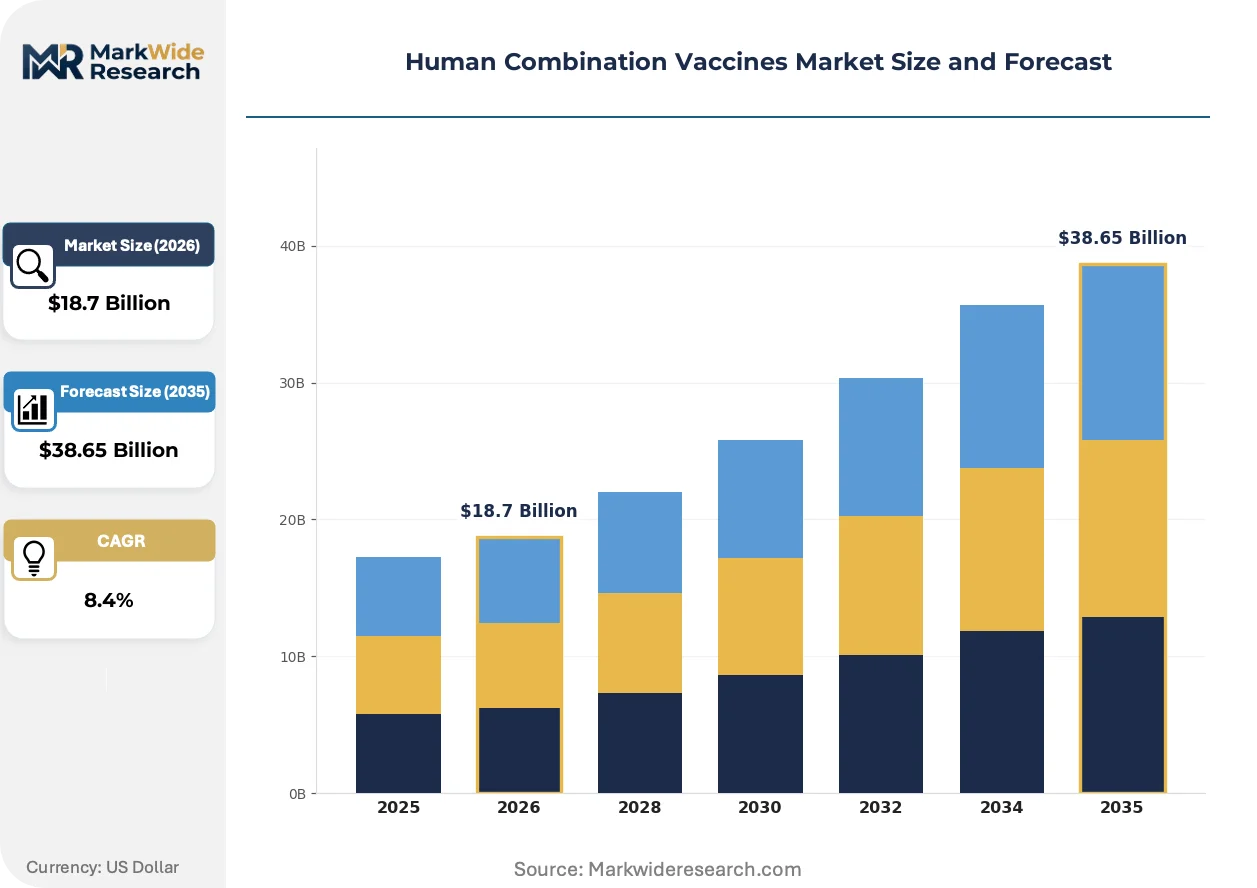
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Live Attenuated, Inactivated, Subunit, Conjugate Therapy Area: Immunization, Pediatric, Travel Medicine, Infectious Disease Delivery Mode: Intramuscular, Subcutaneous, Oral, Intranasal End User: Hospitals, Clinics, Healthcare Providers, Pharmacies |
| Companies Covered | GlaxoSmithKline, Sanofi Pasteur, Merck & Co., Pfizer, Serum Institute of India, AstraZeneca, CSL Limited, Biological E, Panacea Biotec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Human Combination Vaccines Market Strategic Shifts
Bioprocess intensification and digital quality systems are compressing batch release timelines while regulatory convergence around platform technologies is reshaping evidence requirements for novel combinations.
Continuous bioprocessing technology is integrating perfusion fermentation with real-time analytical control, enabling higher cell density cultures and reduced facility footprints. Contract development and manufacturing organizations serving mid-scale vaccine developers are adopting these platforms to compete with legacy batch facilities. The structural consequence is integrating high-throughput process development with accelerated tech transfer timelines, collapsing the traditional 18-month scale-up window.
The EU AI Act's risk classification framework for medical device software is extending to algorithm-driven batch release and quality prediction systems used in combination vaccine manufacturing. EMA guidance on artificial intelligence in medicinal product lifecycle management is forcing manufacturers to document training data provenance and model validation protocols. European facilities deploying machine learning for in-process monitoring face the steepest compliance burden, with notified body review timelines extending certification schedules.
Brazilian and Indian government buyers are consolidating pentavalent and hexavalent procurement through multi-year tenders with stringent local production requirements, displacing spot-market purchasing. UNICEF's vaccine independence initiative is channeling volume toward manufacturers with demonstrated supply security during prior shortage events. This pattern concentrates most visibly in India's government procurement system, where domestic manufacturers capture preferential allocation under phased manufacturing program incentives.
Human Combination Vaccines Market Segmentation
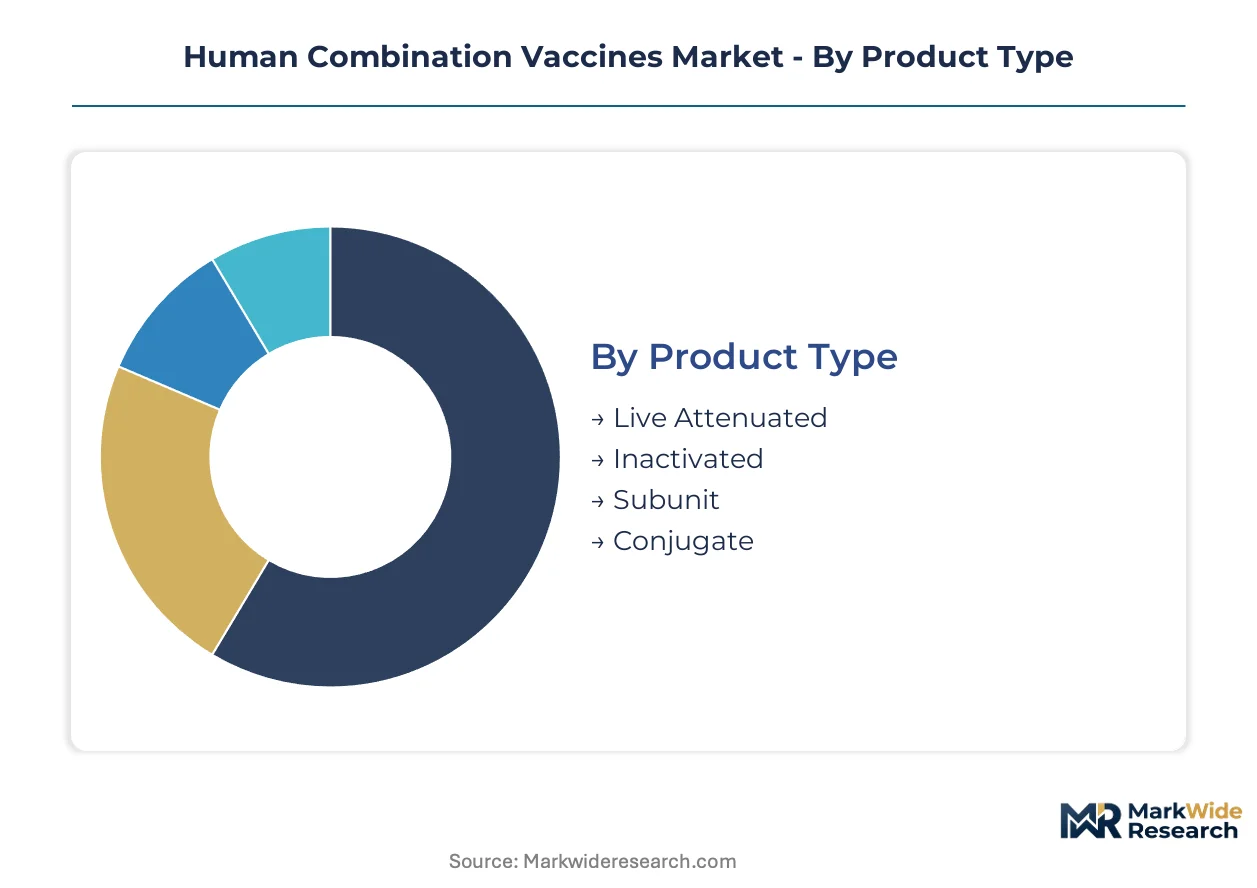
Segmentation in human combination vaccines reveals how formulation chemistry, clinical application, and administration logistics create distinct competitive arenas. Manufacturers align R&D investment and manufacturing capacity against the segments where regulatory pathways and procurement economics offer sustainable returns.
Product Type:
Upgrade cycles in pediatric immunization programs are displacing older monovalent schedules with multivalent formulations that reduce injection burden and cold-chain complexity.
- Live Attenuated:Contains weakened pathogen strains that replicate minimally in vivo to stimulate cellular immunity. Demand concentrates in measles-mumps-rubella-varicella combinations across WHO Expanded Program on Immunization schedules; constrained manufacturing capacity and biosafety infrastructure requirements limit supplier entry.
- Conjugate:Links polysaccharide antigens to protein carriers to elicit T-cell dependent responses in infants. Procurement volumes cluster in pneumococcal and meningococcal programs funded by Gavi and national governments; complex chemistry sustains premium pricing relative to other platforms.
- Inactivated:Uses killed pathogens or split virions preserved through chemical or thermal treatment. Hexavalent and pentavalent pediatric combinations in India and Nigeria drive placement scale.
- Subunit:Purified protein or peptide antigens selected for immunogenicity without whole-pathogen components. Recombinant hepatitis B and acellular pertussis components anchor demand in combination formulations.
Volume placements concentrate in Conjugate; the faster expansion belongs to Live Attenuated as combination schedules consolidate.
Therapy Area:
Cost tier differentiation separates donor-funded universal programs from private-market travel and occupational health segments with divergent price sensitivity and regulatory evidence requirements.
- Immunization:Routine preventive vaccination against common infectious diseases through national program schedules. UNICEF and Gavi procurement channels dominate volume; WHO prequalification serves as the gateway credential for supplier eligibility.
- Pediatric:Infant and early childhood formulations designed for developing immune systems. India's Universal Immunization Program and Nigeria's national schedule are consolidating demand around hexavalent single-injection products to improve caregiver compliance.
- Travel Medicine:Pre-departure prophylaxis for typhoid, hepatitis A/B, and yellow fever exposure. Private clinics and occupational health providers in Europe and North America sustain margin through direct-pay pricing.
- Infectious Disease:Targeted outbreak response and epidemic preparedness formulations. Emergency procurement mechanisms and stockpiling agreements shape demand volatility.
Procurement scale clusters in Immunization; steepest expansion trajectory is occurring in Pediatric as national programs consolidate schedules.
Delivery Mode:
Application requirements dictate formulation stability, adjuvant selection, and device compatibility, with intramuscular platforms commanding manufacturing investment due to established immunogenicity databases.
- Intramuscular:Injection into skeletal muscle tissue for depot formation and sustained antigen release. Dominates pediatric combination schedules in India, Brazil, and Indonesia due to proven safety profiles and healthcare worker familiarity.
- Intranasal:Mucosal delivery generating secretory IgA responses at respiratory pathogen entry points. Development priority for COVID-19 and influenza combinations; needle-free administration promises compliance advantages in school-based programs.
- Subcutaneous:Injection into adipose tissue beneath the dermis. Limited to specific live attenuated combinations with established subcutaneous immunogenicity data.
- Oral:Enteric-coated or live attenuated formulations surviving gastric transit. Restricted to polio and rotavirus combinations where mucosal gut immunity is clinically relevant.
Manufacturing capacity concentrates in Intramuscular; Intranasal is climbing the fastest as respiratory combination candidates advance through Phase III.
End User:
Customer type determines procurement channel, payment mechanism, and cold-chain infrastructure requirements, with government-funded national programs operating on fundamentally different economics than private providers.
- Hospitals:Integrated health systems managing birth-dose administration and inpatient vaccination. Government procurement contracts in Brazil and India channel pentavalent and hexavalent volume through hospital-based immunization clinics.
- Clinics:Outpatient facilities serving routine pediatric and adult vaccination. Travel medicine and private-pay combinations sustain margin in European and North American clinic networks.
- Healthcare Providers:Individual practitioners and group practices administering vaccines in community settings. India's private pediatricians drive demand for premium hexavalent formulations outside government programs.
- Pharmacies:Retail settings with expanded vaccination authority in select jurisdictions. Community pharmacy access programs in the US and UK are capturing influenza and travel vaccine volume.
Contract volume concentrates in Hospitals; Pharmacies are gaining share fastest as scope-of-practice expansion proceeds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pune anchors the developing-world supply base for affordable combination vaccines, with Serum Institute of India's manufacturing complex driving pentavalent and hexavalent output for Gavi-eligible countries.
United States
FDA's Center for Biologics Evaluation and Research maintains the reference standard for combination vaccine licensure through comparative immunogenicity protocols. The agency's evolving platform technology guidance is compressing clinical evidence requirements for mRNA-based candidates. Maryland's biologics corridor clusters adjuvant chemistry expertise and process development capacity for next-generation formulations.
India
Domestic manufacturers capture preferential allocation under the phased manufacturing program as the Universal Immunization Program consolidates demand around single-injection hexavalent products. CDSCO's streamlined review pathways for WHO-prequalified vaccines accelerate market entry for export-oriented producers. Hyderabad's vaccine cluster concentrates conjugate chemistry capability and fill-finish infrastructure for African and Southeast Asian procurement.
Germany
EMA's Committee for Medicinal Products for Human Use mandates expanded immunogenicity cohorts that elevate Phase III costs for novel combinations seeking European licensure. The EU AI Act's risk classification framework extends to algorithm-driven batch release systems, extending certification timelines for machine learning deployments. Marburg's biologics hub sustains legacy protein stabilization expertise for multi-valent shelf-life extension.
Brazil
ANVISA and the national procurement agency are bypassing traditional distributor networks for pentavalent and hexavalent tenders, compressing margin leakage and accelerating payment cycles. Direct government contracting channels are displacing spot-market purchasing for routine immunization programs. São Paulo's pharmaceutical corridor clusters fill-finish partnerships with technology transfer from established conjugate producers.
Indonesia
The national immunization program expansion is creating procurement volume for local fill-finish partnerships with technology transfer agreements. Domestic manufacturing scale-up targets supply security for pentavalent demand across the archipelago's distributed health system. Jakarta's biomedical zone is consolidating regulatory affairs capacity to navigate WHO prequalification pathways for regional export.
Human Combination Vaccines Market Competitive Environment
Capital-heavy producers compete with asset-light designers across a tiered structure where bulk antigen fermentation capacity concentrates among legacy biologics manufacturers while mid-scale developers rely on contract manufacturing partnerships. The vendor base separates into three strategic archetypes: integrated multinationals with adjuvant platforms, volume-focused emerging-market suppliers, and specialty conjugate chemistry houses. Competitive positioning hinges on backward integration into aluminum salt supply and upstream control over protein carrier production.
Within the integrated multinational tier, GlaxoSmithKline and Sanofi Pasteur exemplify divergent geographic anchoring strategies, with the former leveraging European adjuvant expertise and the latter sustaining multi-site manufacturing across continental supply nodes. Serum Institute of India occupies a distinctive position as a volume-scale, emerging-market headquartered supplier whose procurement relationships with Gavi and UNICEF exemplify the donor-funded channel archetype. These three anchors illustrate how regulatory pathway access and manufacturing geography combine to determine sustainable competitive position.
| Leading Market Players |
|---|
| GlaxoSmithKline |
| Sanofi Pasteur |
| Merck & Co. |
| Pfizer |
| Serum Institute of India |
| AstraZeneca |
| CSL Limited |
| Biological E |
| Panacea Biotec |
| Others |
Value Chain & Pricing Dynamics
EU carbon border adjustment mechanisms on aluminum salt production gate qualified supply access and premium-tier pricing for adjuvant-dependent formulations. Manufacturers sourcing aluminum hydroxide from European smelters face input cost inflation that transmits directly to hexavalent and pentavalent combination pricing, while WHO-prequalified producers in India bypass this premium through domestic adjuvant supply.
Pricing Analysis
Outcome-based pricing anchored to infant immunization schedule completion rates distinguishes Gavi-procured volumes from private-market transactions. Three-tier pricing structure across premium, standard, and economy levels stratifies by WHO prequalification status and cold-chain reliability certification. Cost compression in economy-tier pentavalent supply intensifies as Indonesian and Nigerian government tenders consolidate multi-year contracts. UNICEF and national procurement agencies exhibit highest price sensitivity; private pediatric clinics in India demonstrate lowest sensitivity due to caregiver willingness to pay for injection-burden reduction.
Supply Chain Analysis
Specialized protein chemistry workforce scarcity in Hyderabad and Pune constrains technology transfer timelines for multi-valent formulation scale-up. Bulk antigen production concentrates in India, Belgium, and the United States, with fermentation capacity anchored in legacy European and North American facilities. Aluminum salt adjuvants, polysaccharide carriers, and mRNA lipid nanoparticles constitute critical input dependencies. Single-source vulnerability in protein carrier supply creates exposure when microbial contamination triggers batch recovery cycles. Distribution runs through government procurement channels in donor-funded markets and distributor networks in private-pay segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA's evolving platform technology guidance functions as a cost-of-compliance moat, elevating clinical evidence requirements beyond reach of undercapitalized developers and protecting incumbent positions.
For Market Incumbents: Cement backward integration into aluminum salt supply and captive protein carrier production to defend margin against input volatility. Expand fill-finish capacity in São Paulo and Jakarta to capture Brazilian and Indonesian government tender volume shifting toward direct contracting. Prioritize EMA non-inferiority trial completion before mRNA platform competitors secure streamlined licensure pathways. For New Entrants and Emerging Players: Travel medicine clinics in North America and Europe represent an underserved buyer archetype with direct-pay pricing tolerance and lower regulatory barriers than national immunization program procurement. Target intranasal respiratory combination development to exploit mucosal delivery platform white space ahead of Phase III data readouts. Pursue contract manufacturing partnerships with established CDMOs rather than greenfield fermentation investment. For Investors and Strategic Acquirers: FDA platform technology designation awards to mRNA-based combination candidates are the leading indicator that nucleic acid manufacturing infrastructure will command acquisition premiums over legacy protein facilities. Position for five-to-ten year horizon consolidation around bioprocess intensification capabilities and digital quality systems. Monitor WHO prequalification pathway expansion announcements as signals of procurement volume reallocation toward compliant manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA platform technology designation compresses clinical evidence requirements for mRNA-based candidates leveraging prior safety databases. |
| Manufacturing Scale-Up | Continuous bioprocessing adoption in Hyderabad and Marburg reduces facility footprints and accelerates batch release timelines. |
| Long-term Supply Agreement | Brazilian government direct contracting for pentavalent and hexavalent tenders compresses margin leakage and accelerates payment cycles. |
| Technology Licensing | Conjugate chemistry technology transfer to Indonesian fill-finish partnerships secures procurement preference under national immunization program expansion. |
| Pipeline Diversification | Intranasal respiratory combination candidates address IgA response profiles and needle-free administration demand in school-based programs. |
Study Parameters
FDA filings, EMA submissions, and WHO prequalification records formed the secondary backbone, supplemented by ClinicalTrials.gov protocol analysis and Gavi procurement disclosure documents. Primary interviews with regulatory affairs leads at combination vaccine manufacturers, formulary directors at UNICEF, and hospital procurement managers in Brazil and India validated demand assumptions. Bottom-up volume modeling across product type, therapy area, delivery mode, and end user segments was triangulated against top-down national immunization program budget allocations.
Historical trendline analysis of pediatric schedule consolidation patterns and donor-funded procurement volumes informed projection parameters across the analysis window. Segmentation dimensions modeled included formulation chemistry platform, regional regulatory cluster, and procurement channel archetype. CAGRs were derived from elasticity-adjusted demand curves incorporating hexavalent adoption rates and cold-chain infrastructure investment trajectories. Forecast inputs incorporated aluminum adjuvant price volatility indices and mRNA platform licensure timeline assumptions.
Revisions become necessary when WHO prequalification pathway modifications, EMA non-inferiority trial requirement changes, or EU AI Act enforcement interpretations materialize differently than modeled. Forecasts reflect documented assumptions regarding Gavi funding continuity and national immunization program expansion schedules. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Immunomodulators Market
Pharmaceuticals
Global Ethical Pharmaceuticals Market
Pharmaceuticals
Osteoarthritis Drugs Market
Pharmaceuticals
Lansoprazole API Market
Pharmaceuticals
Systemic Antibiotics Market
Pharmaceuticals
Europe Laxative Market
Pharmaceuticals
Multiple Myeloma Drugs Market
Pharmaceuticals
Bevacizumab Market
Pharmaceuticals
Lignocaine/ Lidocaine Market
Pharmaceuticals
Antiepileptic Drugs (AED) Market
Pharmaceuticals
Germany Pharmaceutical Warehousing Market
Pharmaceuticals
Global Neuroprotective Agents Market
Pharmaceuticals
Articaine Hydrochloride Market
Pharmaceuticals
Germany Diabetes Drugs Market
Pharmaceuticals
Asia-Pacific Biguanide Market
Pharmaceuticals
Global Zika Vaccines Market