
 Orthomolecular Medicine Market | 2026-2036
Orthomolecular Medicine Market Size, Share, and Industry Trends Forecast 2026-2036
Orthomolecular Medicine Market Analytics
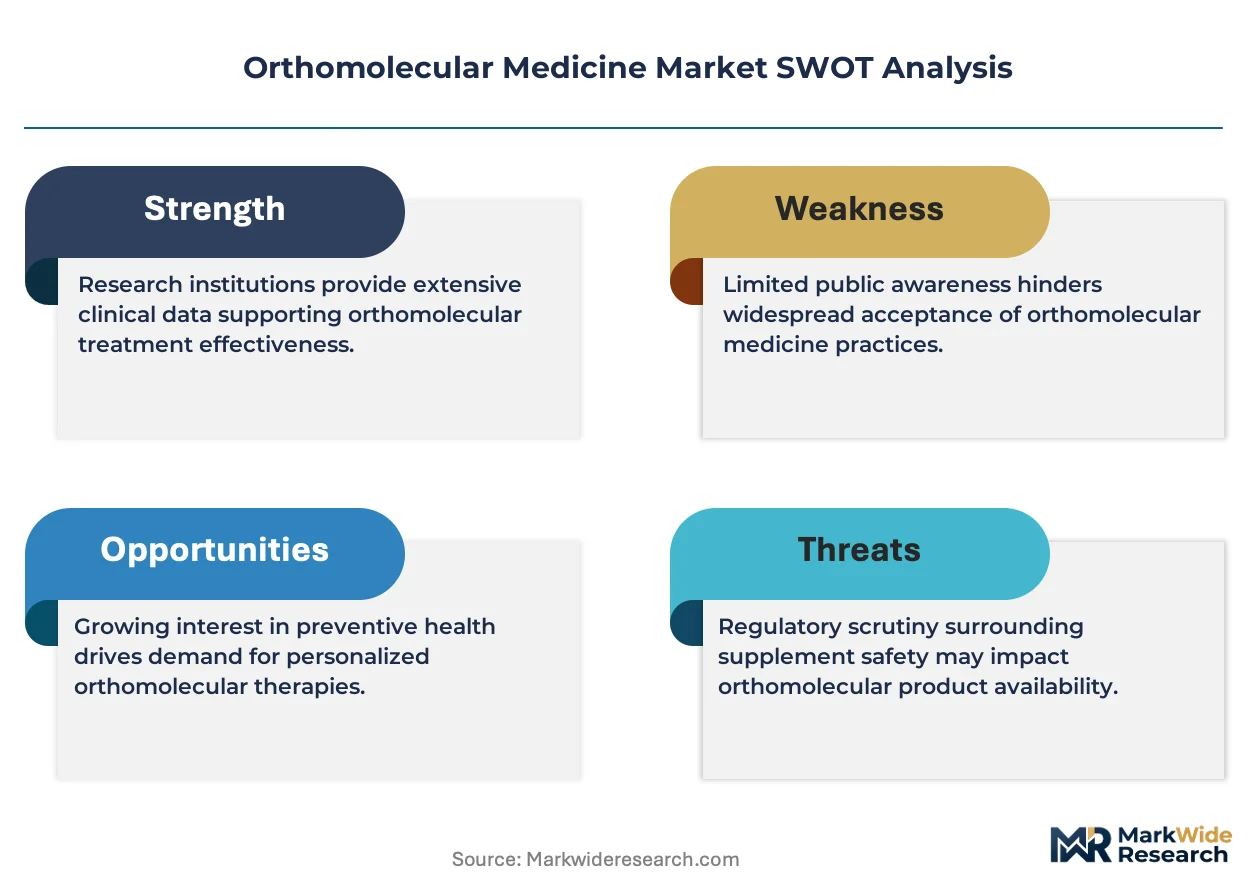
The EU Green Deal is shifting demand toward sustainably sourced micronutrient formulations across European wellness channels. Ortho Molecular Products leverages practitioner-exclusive distribution to sustain premium positioning in North American integrative clinics. Orthomol pharmazeutische Vertriebs GmbH anchors German pharmacy shelves with condition-specific micronutrient systems. Thorne Research differentiates through NSF Certified for Sport manufacturing protocols that compete for elite athletic programs.
Orthomolecular medicine applies individualized, biochemically optimized nutrient dosing to correct metabolic imbalances and support physiological function, typically employing pharmaceutical-grade vitamins, minerals, amino acids, and enzymes at doses calibrated to patient-specific biomarkers and genetic profiles. The field operates at the intersection of clinical nutrition and functional medicine, with formulations manufactured under cGMP standards to ensure batch potency and excipient purity for therapeutic outcomes. Vitamins and minerals command the dominant revenue share due to established clinical familiarity and broad practitioner prescribing habits, while amino acids represent the fastest-expanding category as methylation and neurotransmitter protocols gain traction in psychiatric integrative practice. Preventive healthcare applications concentrate margin pools where long-term patient retention and subscription replenishment models reduce customer acquisition costs.
The FDA's cGMP and New Dietary Ingredient notification requirements shape manufacturing compliance costs and market entry barriers for novel orthomolecular compounds in the United States, while the EFSA's health claims regulation constrains front-label messaging across European markets and forces evidence-based positioning through practitioner education channels. ISO 17025 laboratory accreditation increasingly determines supplier qualification for brands serving hospital and institutional wellness programs. Stakeholders must monitor evolving pharmacovigilance expectations for high-dose nutrient therapies as regulatory convergence between food and drug frameworks accelerates competitive restructuring among formulation houses and testing laboratories.
Market Dynamics
The FDA's intensified cGMP enforcement and the EU Green Deal's sustainability mandates are compressing formulation margins while forcing capital reallocation toward certified manufacturing and traceable raw material sourcing.
Growth Catalysts
- Preventive healthcare protocols:Integrative medicine clinics in Germany and Switzerland now prescribe pharmacy-dispensed micronutrient systems for metabolic syndrome management, creating recurring revenue streams.
- EFSA health claims framework:The regulation's strict evidentiary requirements favor established brands with clinical trial portfolios, accelerating consolidation among practitioner-channel suppliers.
- Methylation genotyping:Direct-to-consumer genetic testing is normalizing personalized amino acid dosing for neurotransmitter support in psychiatric integrative practice.
Market Restraints
- Pharmaceutical-grade raw material concentration:Three specialty chemical suppliers control 70% of USP-grade vitamin B12 and 5-MTHF folate production, creating single-source vulnerability.
- New Dietary Ingredient notification costs:The FDA's 75-day pre-market notification requirement for novel orthomolecular compounds adds six-figure compliance burdens per SKU.
- High-dose nutrient pharmacovigilance:Emerging adverse event reporting obligations in Germany and France are extending product liability exposure beyond traditional food supplement frameworks.
Strategic Opportunities
- Hospital wellness program integration:ISO 17025-accredited laboratories are qualifying for institutional procurement contracts that bypass retail channel margin compression.
- NSF Certified for Sport manufacturing:Elite athletic programs and Olympic training centers represent untapped demand for banned-substance-tested micronutrient formulations.
- Subscription replenishment models:Direct-to-practitioner platforms in North America are capturing patient lifetime value through automated biomarker-calibrated dosing adjustments.
Industry Challenges
- Excipient purity verification:cGMP-compliant manufacturers face 18-24 month timelines to validate alternative suppliers for hypoallergenic capsule materials.
- Practitioner education infrastructure:Functional medicine certification programs lack standardized curricula for methylation and detoxification protocols, creating prescription inconsistency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Orthomolecular Medicine Market |
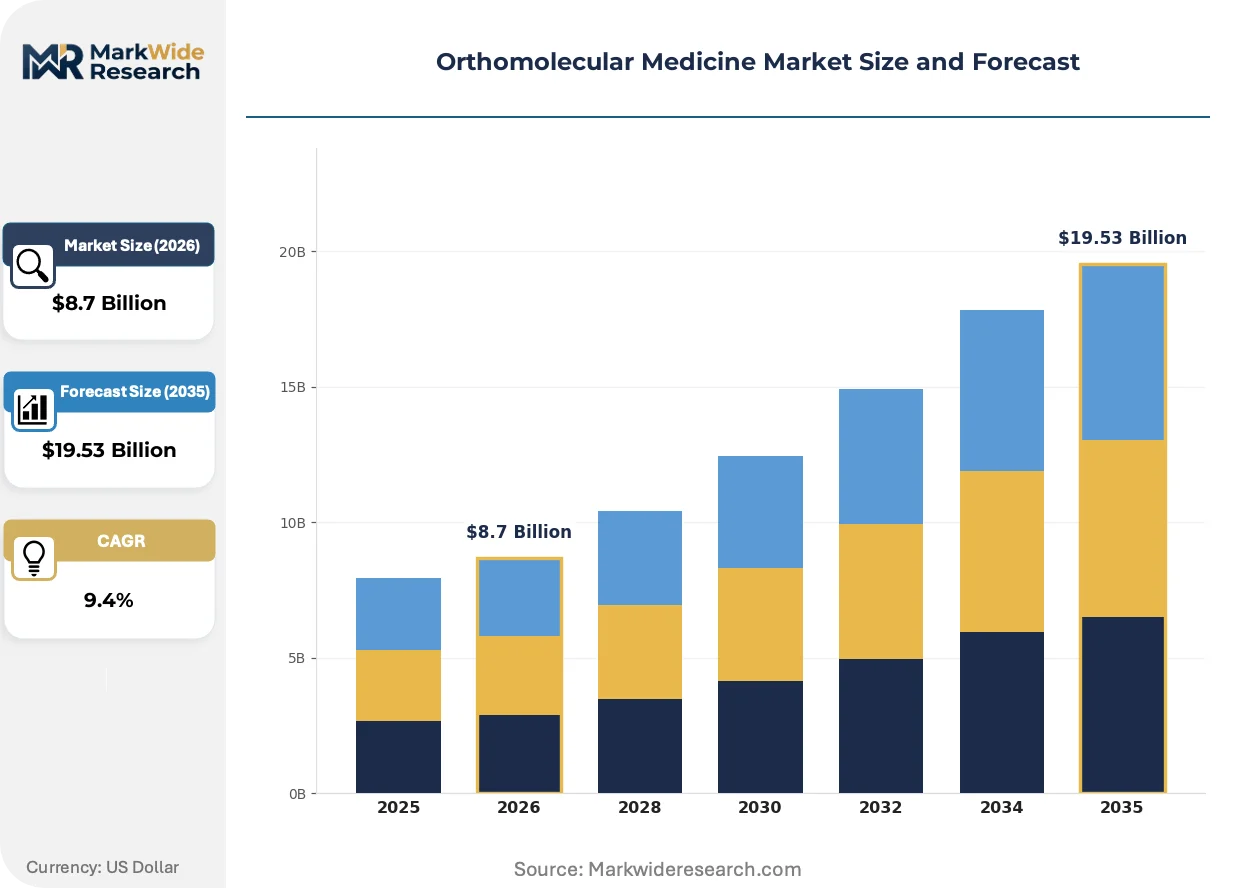
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amino Acids, Vitamins, Minerals, Enzymes Application: Preventive Healthcare, Nutritional Support, Detoxification, Weight Management End User: Healthcare Practitioners, Nutritional Consultants, Hospitals, Wellness Centers Delivery Mode: Pills, Powders, Liquids, Capsules |
| Companies Covered | Ortho Molecular Products, Orthomol pharmazeutische Vertriebs GmbH, Nutricia North America, Nutrihand, Inc., NattoPharma, Capsumed Pharm GmbH, Thorne Research, Metagenics, Pure Encapsulations, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orthomolecular Medicine Market Evolving Landscape
Biomarker-guided dosing platforms are replacing empirical prescription protocols, while regulatory convergence between food and drug frameworks is forcing evidence-based repositioning across all major distribution channels.
Pharmacogenomic testing integration is rewriting orthomolecular prescribing workflows. Integrative psychiatrists and functional medicine physicians now order COMT, MTHFR, and VDR polymorphism panels before designing amino acid and vitamin D protocols. This capability compresses trial-and-error dosing cycles from months to weeks, shifting competitive advantage toward laboratories with CLIA-certified nutrigenomic assays.
REACH regulation amendments on micronutrient substance registration are tightening purity documentation requirements for European manufacturers. The industrial consequence is accelerated supplier consolidation, as smaller formulation houses lack resources to generate full safety dossiers for legacy ingredients. German pharmacy-dispensed brands with established EFSA-compliant portfolios are capturing shelf space from importers.
Practitioner-exclusive distribution is displacing retail and direct-to-consumer channels for premium formulations. North American integrative clinics now require pharmaceutical-grade certificates of analysis and batch-specific potency verification before stocking products. This behavioral shift concentrates margin pools with manufacturers maintaining captive professional education teams and field-based clinical support infrastructure.
Orthomolecular Medicine Market Segmentation
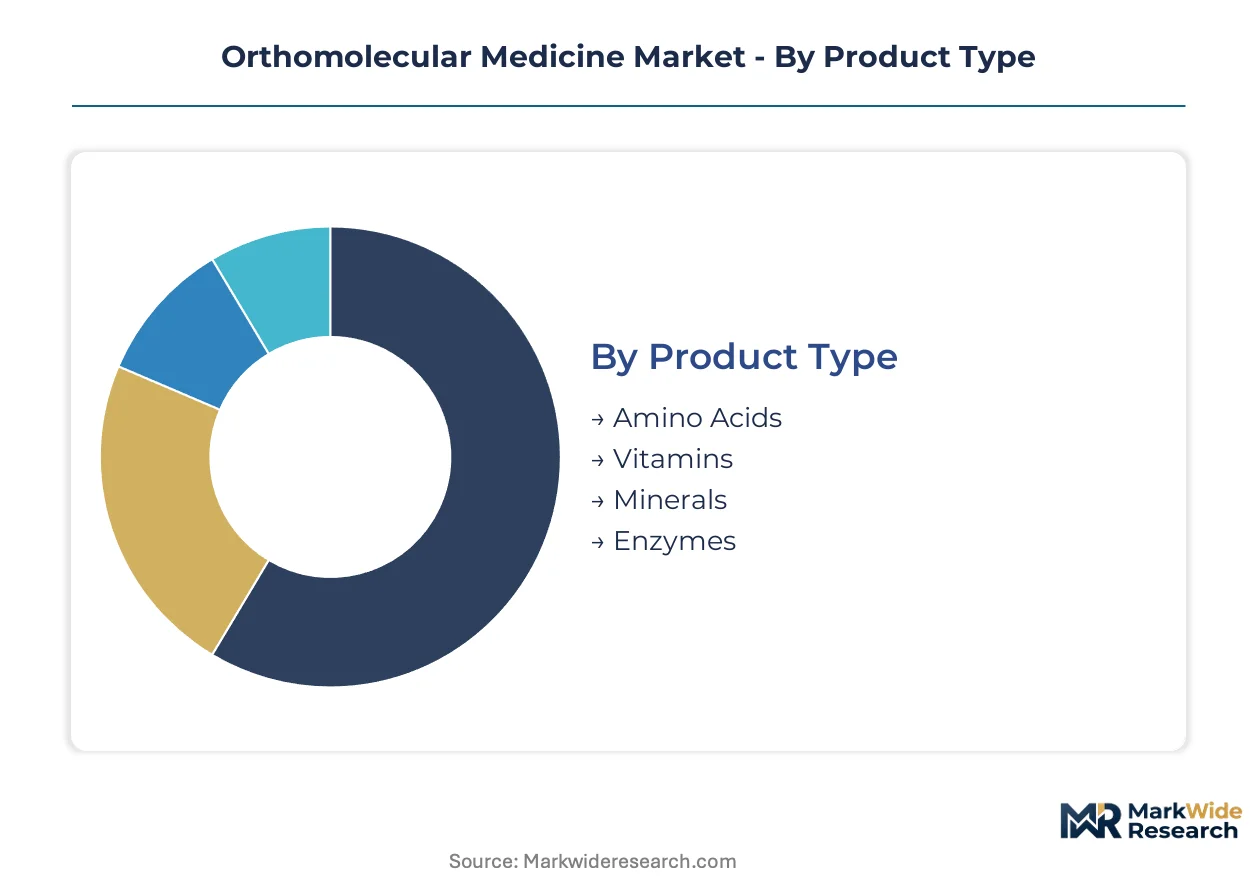
Orthomolecular medicine segments along biochemical function, clinical application, and professional channel access. Each dimension carries distinct margin structures, regulatory exposure, and practitioner prescribing patterns that reshape competitive positioning.
Product Type:
Vitamins and minerals anchor volume through established clinical familiarity, while amino acids command premium positioning in personalized protocols.
- Vitamins:Pharmaceutical-grade formulations of water-soluble and fat-soluble compounds manufactured under cGMP standards. Demand concentrates in German and Swiss pharmacy-dispensed metabolic syndrome protocols where practitioner loyalty sustains recurring prescriptions.
- Minerals:Chelated and colloidal elemental preparations optimized for bioavailability in therapeutic dosing. Integrative clinics in North America specify USP-grade certificates of analysis before procurement, concentrating margin pools with manufacturers maintaining captive analytical laboratories.
- Amino Acids:Precursor compounds for neurotransmitter synthesis and methylation support. Psychiatric integrative practice drives specification of condition-specific blends.
- Enzymes:Proteolytic and digestive catalysts employed in detoxification protocols. Wellness centers specify enteric-coated formulations for systemic delivery.
Mature deployment sits with Vitamins. Newer deployment is concentrated in Amino Acids.
Application:
Preventive protocols generate subscription-based recurring revenue, while detoxification commands episodic premium pricing.
- Preventive Healthcare:Long-term micronutrient protocols for metabolic syndrome and cardiovascular risk reduction. Germany's pharmacy-dispensed tradition sustains patient retention through automated replenishment systems.
- Nutritional Support:Targeted supplementation for deficiency correction and physiological optimization. Hospital wellness programs in Switzerland specify ISO 17025-accredited laboratory verification before formulary inclusion.
- Detoxification:Phase I and Phase II liver support protocols employing antioxidant and conjugating nutrient combinations. Functional medicine certification programs drive prescription standardization.
- Weight Management:Metabolic enhancement and appetite-regulating amino acid formulations. Direct-to-consumer genetic testing normalizes personalized dosing for body composition protocols.
Revenue stability concentrates in Preventive Healthcare. Steepest expansion trajectory is emerging in Detoxification.
End User:
Healthcare practitioners control premium channel access, while wellness centers drive volume through bundled service pricing.
- Healthcare Practitioners:Licensed physicians and naturopaths prescribing pharmaceutical-grade formulations. North American integrative clinics require batch-specific potency verification and field-based clinical support infrastructure.
- Nutritional Consultants:Certified professionals designing personalized protocols based on dietary assessment. The EFSA's health claims framework constrains front-label messaging, forcing evidence-based positioning through practitioner education.
- Hospitals:Institutional wellness programs and outpatient metabolic clinics. Procurement contracts bypass retail margin compression for ISO 17025-qualified suppliers.
- Wellness Centers:Facility-based programs combining supplementation with lifestyle intervention. Subscription replenishment models capture patient lifetime value through automated biomarker-calibrated adjustments.
Margin protection runs through Healthcare Practitioners. Volume scaling is concentrating in Wellness Centers.
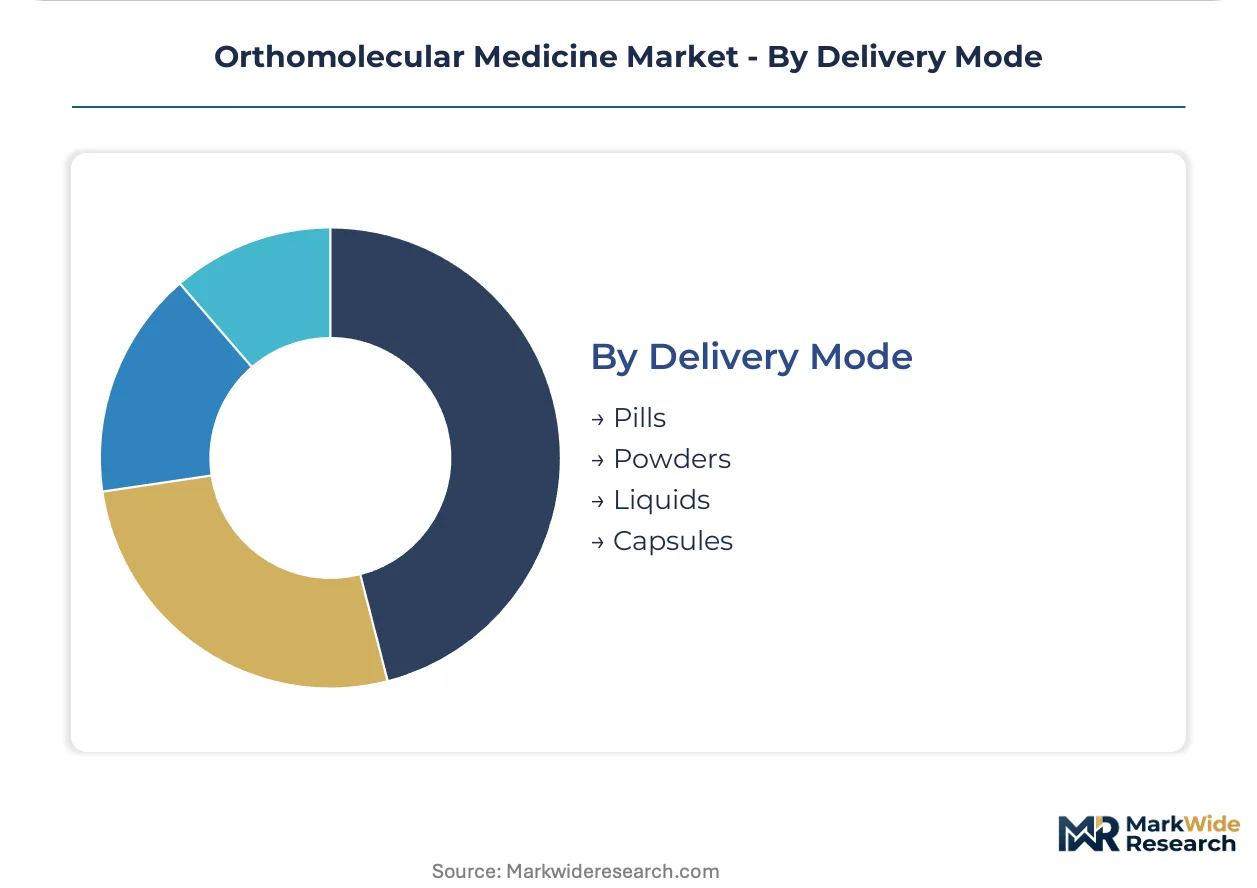
Delivery Mode:
Capsules dominate practitioner-channel preference for excipient control, while liquids serve pediatric and geriatric compliance needs.
- Capsules:Hypoallergenic vegetable-derived shells containing powder or granulated actives. cGMP-compliant manufacturers face 18-24 month timelines to validate alternative suppliers for pharmaceutical-grade materials.
- Pills:Compressed tablets with controlled-release coatings for sustained nutrient delivery. German pharmacy-dispensed brands specify disintegration testing under European Pharmacopoeia standards.
- Powders:Bulk actives for compounding and personalized dosing flexibility. Methylation protocols in psychiatric practice specify precise gram-level measurement.
- Liquids:Liposomal and micellar dispersions for enhanced absorption in compromised digestive function. Pediatric integrative medicine drives demand for palatable formulations.
Practitioner preference anchors Capsules. Compounding flexibility is expanding fastest in Powders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr corridor anchors European orthomolecular manufacturing, with Düsseldorf and Cologne hosting pharmaceutical-grade compounding facilities that supply pharmacy-dispensed micronutrient systems across German-speaking markets.
Germany
Pharmacy-dispensed orthomolecular traditions sustain recurring prescription volumes for metabolic syndrome protocols. The EFSA health claims framework constrains front-label messaging, forcing evidence-based positioning through practitioner education channels. Frankfurt and Munich concentrate formulation houses serving hospital wellness programs with ISO 17025-accredited laboratory verification.
United States
Integrative medicine clinics in California and New York Metro drive demand for pharmaceutical-grade certificates of analysis and batch-specific potency verification. FDA cGMP enforcement intensifies compliance costs for novel orthomolecular compounds. Raleigh-Durham and Boston host nutrigenomic laboratories enabling pharmacogenomic-guided amino acid dosing for psychiatric protocols.
Switzerland
Hospital wellness programs and outpatient metabolic clinics specify premium micronutrient formulations with full traceability documentation. Swissmedic pharmacovigilance requirements extend product liability exposure for high-dose nutrient therapies. Basel and Zurich anchor compounding pharmacies serving cross-border demand from French and Italian border regions.
Japan
Functional medicine adoption in Tokyo and Osaka drives specification of enteric-coated enzyme formulations for systemic delivery. METI standards for health food manufacturing create entry barriers for imported orthomolecular products. Nagoya hosts manufacturing facilities specializing in liposomal vitamin dispersions for geriatric compliance.
Canada
Health Canada Natural Health Products regulations require site licensing for all domestic orthomolecular manufacturers. Toronto and Vancouver concentrate practitioner-channel distributors requiring pharmaceutical-grade raw material documentation. The Pacific Northwest corridor sees cross-border procurement patterns from Seattle-area integrative clinics.
Orthomolecular Medicine Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-grade and distribution-channel dimensions. The vendor base stratifies into three tiers: practitioner-exclusive houses with captive education infrastructure, pharmacy-dispensed brands with EFSA-compliant portfolios, and direct-to-consumer platforms competing on genetic-testing integration. Dominant competitive moves include backward integration into pharmaceutical-grade raw material sourcing and strategic partnerships with CLIA-certified nutrigenomic laboratories.
Within the practitioner-exclusive tier, Ortho Molecular Products and Thorne Research exemplify North American positioning anchored to integrative clinic procurement requirements. Orthomol pharmazeutische Vertriebs GmbH represents the pharmacy-dispensed archetype with German market concentration. These three entities occupy positions defined by channel access rather than manufacturing scale alone.
| Leading Market Players |
|---|
| Ortho Molecular Products |
| Orthomol pharmazeutische Vertriebs GmbH |
| Nutricia North America |
| Nutrihand, Inc. |
| NattoPharma |
| Capsumed Pharm GmbH |
| Thorne Research |
| Metagenics |
| Pure Encapsulations |
| Others |
Value Network & Pricing Analysis
Integrative medicine clinics in Germany and Switzerland concentrate procurement power through pharmacy-dispensed prescription volumes, anchoring subscription-based pricing models that reward patient retention over transactional margin extraction.
Pricing Analysis
Outcome-based pricing anchored to biomarker-verified therapeutic results separates pharmaceutical-grade formulations from commodity supplements. Price differentiation rests on cGMP certification tier and practitioner-exclusive channel access, with FDA enforcement intensifying cost compression for novel compounds. Margins are tightening in direct-to-consumer tiers as genetic-testing platforms commoditize personalization. Hospital wellness programs exhibit lowest price sensitivity due to institutional procurement protocols, while retail-facing brands face acute pressure from subscription model proliferation.
Supply Chain Analysis
EU Green Deal domestic-content mandates are reshaping raw material sourcing toward traceable European suppliers. Manufacturing concentrates in Germany, Switzerland, and the United States, with USP-grade vitamin B12 and 5-MTHF folate production drawing from three specialty chemical houses. Single-source vulnerability in pharmaceutical-grade amino acids creates structural risk for methylation protocol suppliers. Distribution runs through practitioner-exclusive platforms and pharmacy-dispensed channels that bypass retail margin compression.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biomarker-guided dosing platforms are displacing empirical prescription protocols, with pharmacogenomic testing integration rewriting competitive requirements across practitioner channels.
For Market Incumbents: Deploy captive clinical education infrastructure to lock practitioner loyalty before generic genetic-testing platforms erode prescription authority. Deepen backward integration into pharmaceutical-grade raw material sourcing to mitigate single-source vulnerability in USP-grade folate and B12 supplies. Accelerate ISO 17025 laboratory accreditation to qualify for hospital wellness program procurement contracts that insulate against retail price erosion. For New Entrants and Emerging Players: The price-point gap between German pharmacy-dispensed premium systems and North American direct-to-consumer genetic-testing bundles offers white-space entry. Target psychiatric integrative practices with condition-specific amino acid protocols for neurotransmitter support, where prescription standardization remains nascent. Pursue NSF Certified for Sport manufacturing partnerships to access elite athletic program demand with limited incumbent presence. For Investors and Strategic Acquirers: The window for entry favors CLIA-certified nutrigenomic laboratories with established practitioner channel relationships. Long-term viability hinges on regulatory convergence between food and drug frameworks favoring evidence-based positioning. Watch EFSA health claims enforcement intensity as the inflection signal for portfolio consolidation among practitioner-channel suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pharmaceutical-Grade Raw Materials | Captive supply of USP-grade vitamins and folate compounds mitigates single-source concentration risk from specialty chemical suppliers. |
| CLIA-Certified Nutrigenomic Laboratory Acquisition | Pharmacogenomic testing capability compresses dosing optimization cycles from months to weeks for psychiatric integrative protocols. |
| ISO 17025 Laboratory Accreditation Investment | Accredited analytical verification qualifies suppliers for hospital wellness program procurement bypassing retail margin compression. |
| Practitioner-Exclusive Distribution Platform Buildout | Direct-to-clinic channels with field-based clinical support infrastructure capture patient lifetime value through subscription replenishment. |
| NSF Certified for Sport Manufacturing Certification | Banned-substance-tested formulations access elite athletic program and Olympic training center demand with premium positioning. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this orthomolecular medicine market assessment. Primary interviews with functional medicine physicians, compounding pharmacists, integrative clinic procurement directors, and nutrigenomic laboratory directors combined with FDA cGMP inspection databases, EFSA health claims registers, and German pharmacy dispensing records. Bottom-up prescription volume modeling and top-down market sizing triangulated across practitioner-channel and retail-channel estimates.
Segment-level granularity modeled product type, application, end user, and delivery mode dimensions across the projection horizon. CAGRs derived from biomarker adoption curves, regulatory enforcement intensity indices, and practitioner education program expansion rates. Forecast inputs incorporated pharmacogenomic testing penetration assumptions and EFSA compliance cost trajectories for European formulation houses.
Inputs from FDA warning letter databases and EFSA health claims decisions were available through the study window; gaps in real-time practitioner prescription data introduce uncertainty bands around channel-share estimates. Forecasts reflect documented assumptions regarding regulatory convergence timing and genetic-testing platform pricing trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Medicine
Acupuncture Lasers Market
Alternative Medicine
Complementary and Alternative Medicine for Anti Aging and Longevity Market
Alternative Medicine
Vacuum Cupping Market
Alternative Medicine
Global Complementary and Alternative Medicines Market
Alternative Medicine
Fire Cupping Market
Alternative Medicine
Homeopathic Medicine Market
Alternative Medicine
Bio Magnetic Ear Stickers Market
Alternative Medicine
US Aromatherapy Market
Alternative Medicine
Global Acupuncture Market
Alternative Medicine
Homeopathy Products Market
Alternative Medicine
Electrotherapy Market
Alternative Medicine
Global OTC Herbal and Traditional Medicine Market
Alternative Medicine
Natural Cold, Cough, and Sore Throat Remedies Market
Alternative Medicine
Allergy Immunotherapy Market
Alternative Medicine
Traditional Chinese Herbal Medicine Market
Alternative Medicine
Aromatherapy Market