
 Acupuncture Lasers Market | 2026-2036
Acupuncture Lasers Market Size, Share, and Industry Trends Forecast 2026-2036
Acupuncture Lasers Market Analysis
Capital-intensity divergence between R&D-heavy diode specialists and assembly-dependent portable-device makers is rotating competitive advantage toward firms with captive semiconductor sourcing. Erchonia Corporation leverages vertical integration in laser diode fabrication to command premium positioning in Class IV systems. Meditech Laser anchors its European footprint through rehabilitation-center partnerships that sustain recurring consumable revenue. LiteCure LLC dominates the North American physiotherapy channel with application-specific training protocols that extend clinician loyalty.
Acupuncture lasers emit coherent light at specific wavelengths to stimulate anatomical points without needle penetration, typically operating in the red to near-infrared spectrum at power densities below 500 mW for low-level applications and above 500 mW for Class IV therapeutic interventions. Diode laser technology leads installed base volumes due to compact form factors and electrical efficiency, while LED laser variants capture fastest growth in home-use portable segments where cost thresholds dominate purchase decisions. Clinics represent the most mature end-user channel with established reimbursement pathways, whereas rehabilitation centers concentrate emerging margin pools as post-acute care protocols expand laser modalities.
FDA 510(k) clearance requirements shape US product entry timelines, while the EU MDR and CE marking impose clinical evidence burdens that filter smaller manufacturers from European distribution. China's NMPA oversees device registration for laser acupuncture systems integrated into hospital traditional medicine departments. Germany's KBA does not regulate this sector; instead, Germany's national pharmaceutical regulator, the BfArM, influences reimbursement classification for photobiomodulation therapies. Stakeholders must monitor evolving FDA guidance on at-home laser devices and MDR notified-body capacity constraints that could bottleneck European market access.
Market Dynamics
EU Medical Device Regulation clinical evidence burdens are filtering smaller manufacturers from European distribution while concentrating procurement authority among hospital systems with dedicated traditional medicine departments.
Growth Catalysts
- Traditional medicine integration:China's NMPA registration pathways for laser acupuncture systems in hospital departments accelerate institutional adoption.
- Post-acute care expansion:Rehabilitation centers in Germany are embedding photobiomodulation protocols into standard recovery regimens.
- Diode efficiency gains:Compact semiconductor form factors reduce device footprint and electrical consumption for clinic deployments.
Market Restraints
- Notified-body capacity constraints:EU MDR certification bottlenecks delay European market access for new entrants.
- Laser diode supply concentration:Specialized semiconductor foundries in East Asia create single-source vulnerability for Class IV system manufacturers.
- Reimbursement classification ambiguity:Germany's BfArM has not established consistent photobiomodulation therapy codes, creating payment uncertainty.
Strategic Opportunities
- Home-use portable segments:LED laser variants capture cost-sensitive consumers seeking needle-free acupuncture alternatives.
- FDA at-home device guidance:Evolving US regulatory clarity for consumer-directed laser systems opens direct-to-patient channels.
- Pain management clinic networks:Specialized outpatient facilities in Germany present concentrated demand for Class IV therapeutic interventions.
Industry Challenges
- Clinician training standardization:Application-specific protocols vary across physiotherapy and acupuncture practitioner communities.
- 510(k) evidence requirements:FDA clearance timelines for novel wavelength or power configurations extend product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acupuncture Lasers Market |
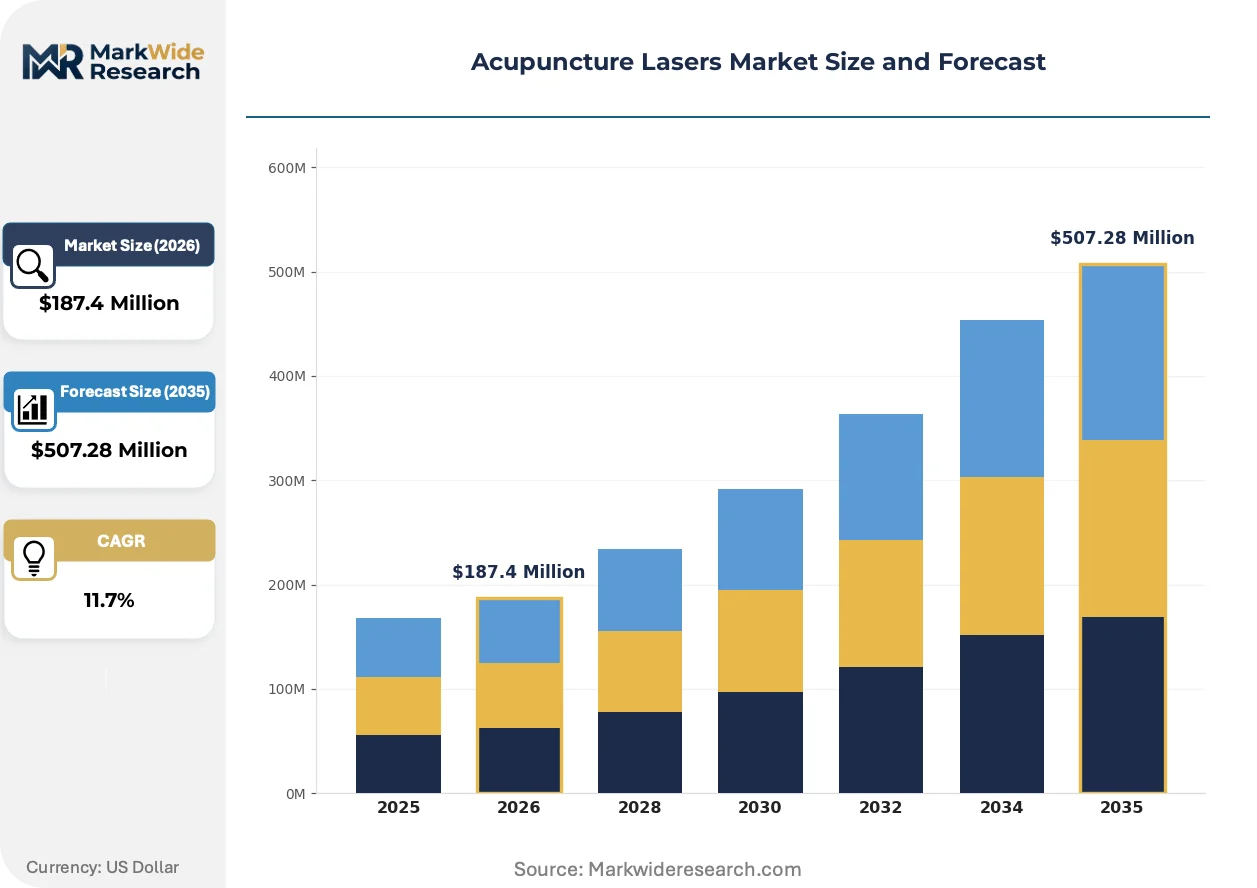
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Class IV Lasers, Low Level Lasers, Desktop Lasers, Portable Lasers Technology: Diode Lasers, Gas Lasers, Fiber Lasers, LED Lasers End User: Clinics, Hospitals, Rehabilitation Centers, Physiotherapy Application: Pain Management, Tissue Repair, Inflammation Reduction, Muscle Relaxation |
| Companies Covered | Erchonia Corporation, Meditech Laser, ASA Laser, LiteCure LLC, RJ Laser, Sedatelac, Hwato, Schwa-medico GmbH, B-Cure Laser LTD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acupuncture Lasers Market Emerging Trajectories
Device architecture is compressing toward portable formats while regulatory frameworks harden evidence requirements and procurement authority consolidates within integrated health systems.
Semiconductor laser technology is miniaturizing through advanced diode packaging that integrates driver electronics and thermal management into single modules. Rehabilitation centers and home-use buyers are adopting these compact systems at accelerating rates. This miniaturization is compressing price points and enabling wearable form factors that displace tabletop clinic installations.
EU MDR clinical evidence mandates are elevating documentation burdens for laser acupuncture device manufacturers seeking CE marking. Smaller firms without dedicated regulatory affairs functions are exiting European distribution. Class III and IV therapeutic systems face the steepest compliance costs, favoring established players with captive clinical trial capabilities.
Hospital procurement departments are consolidating laser acupuncture purchases through centralized traditional medicine equipment tenders. Specialist distributors serving individual acupuncture practices are losing share to direct manufacturer contracts with health system administrators. This concentration is most visible in China's tier-one cities where public hospital networks dominate device acquisition decisions.
Acupuncture Lasers Market Segmentation
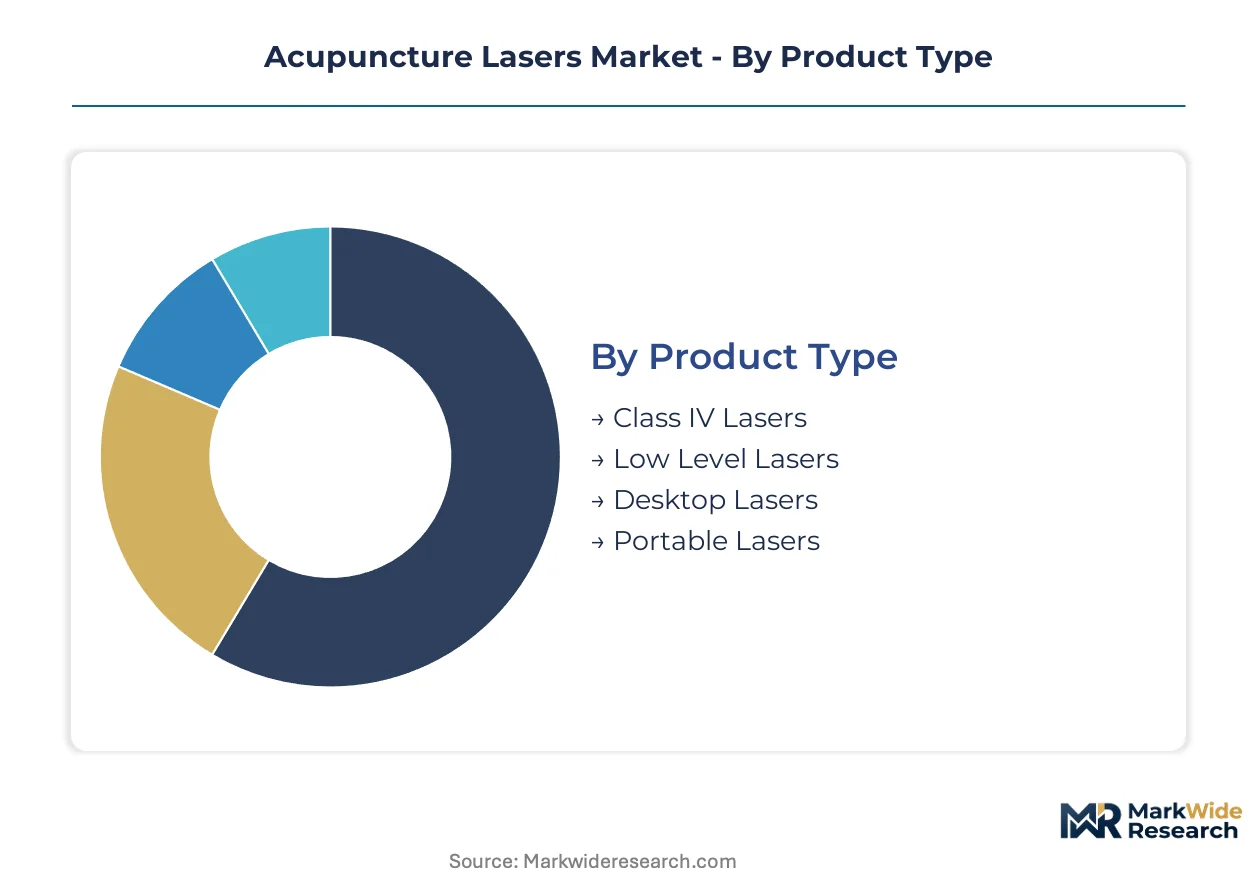
Acupuncture laser manufacturers navigate divergent compliance pathways across power classifications and use environments. Segment-specific regulatory burdens determine viable distribution channels and pricing architecture for each product category.
Product Type:
FDA 510(k) clearance requirements and EU MDR clinical evidence standards create tiered entry barriers across power classifications and form factors.
- Class IV Lasers:These systems operate above 500 mW with therapeutic depth penetration for chronic pain interventions. Pain management clinics in Germany concentrate procurement of these devices due to established photobiomodulation protocols in post-acute care settings.
- Low Level Lasers:Operating below 500 mW, these devices trigger cellular photobiomodulation without thermal tissue damage. Rehabilitation centers across Europe favor this category for conservative treatment regimens where thermal risk must be minimized.
- Desktop Lasers:Stationary clinic installations with integrated power supplies and fixed wavelength outputs.
- Portable Lasers:Battery-operated handheld units targeting home-use segments where NMPA registration in China accelerates hospital department adoption.
Established volume favors Class IV Lasers; emerging adoption favors Portable Lasers.
Technology:
Semiconductor sourcing economics and electrical efficiency separate scalable manufacturing approaches from niche production methods.
- Diode Lasers:Compact solid-state devices converting electrical current directly to coherent light through semiconductor junctions. China's hospital traditional medicine departments drive volume procurement due to favorable NMPA registration pathways for diode-based systems.
- LED Lasers:Non-coherent light-emitting diode arrays simulating acupuncture stimulation at reduced cost thresholds. Home-use buyers in North America favor this technology where FDA guidance on consumer-directed devices is evolving.
- Gas Lasers:Helium-neon configurations producing stable red-wavelength output for research applications.
- Fiber Lasers:Rare-earth-doped fiber amplification systems delivering high beam quality for specialized therapeutic depths.
Diode Lasers dominate installed base economics; LED Lasers are climbing the fastest in consumer channels.
End User:
Procurement authority concentration and reimbursement clarity determine channel profitability and customer acquisition costs.
- Clinics:Independent acupuncture and pain management practices with established reimbursement relationships. Germany's pain management clinic networks sustain concentrated demand for Class IV therapeutic interventions despite BfArM classification ambiguity.
- Rehabilitation Centers:Post-acute care facilities embedding photobiomodulation into standardized recovery protocols. These centers in Germany represent the steepest expansion trajectory as insurers gradually recognize outcome documentation.
- Hospitals:Integrated health systems with centralized traditional medicine equipment tenders in China's tier-one cities.
- Physiotherapy:Movement-focused practices requiring portable systems for in-session patient mobility.
Clinics retain margin stability; Rehabilitation Centers gain share fastest in European procurement.
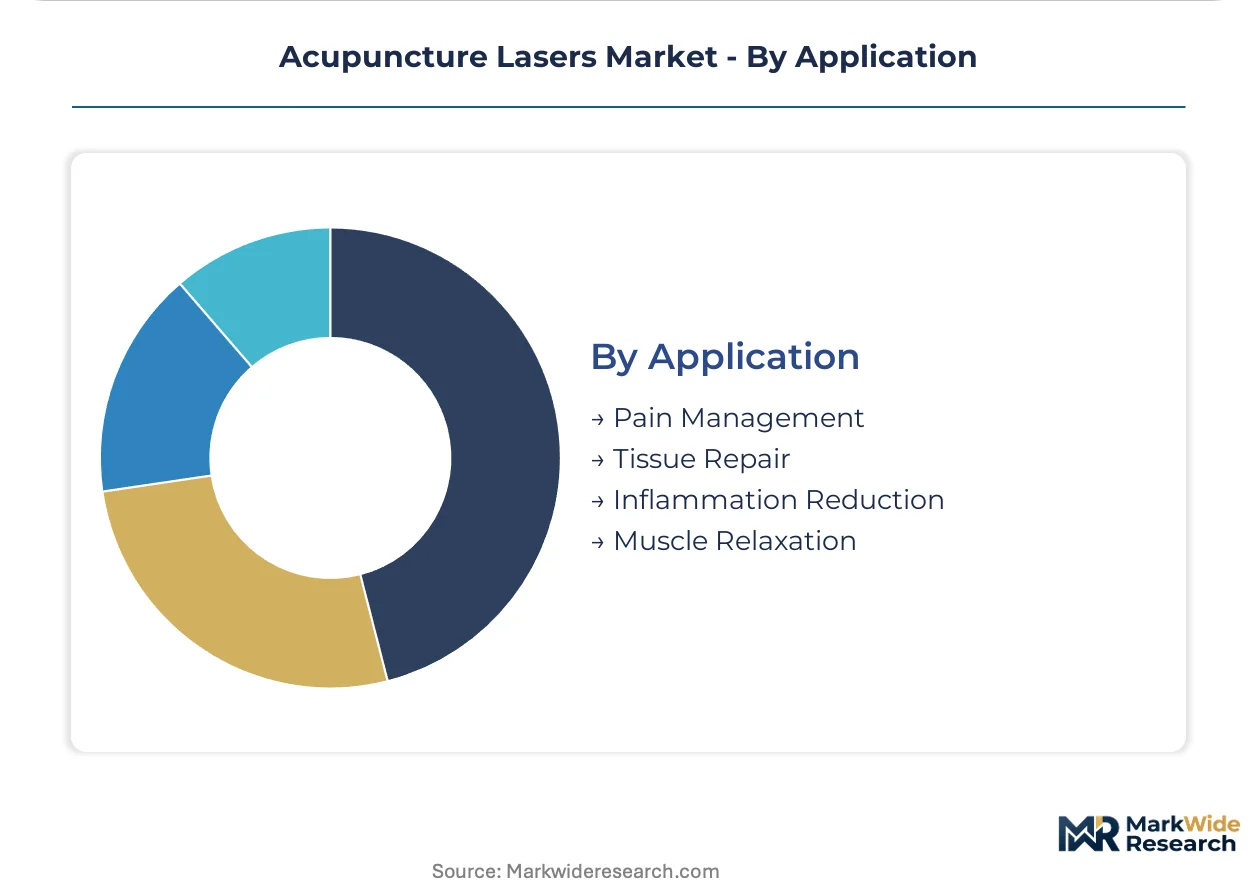
Application:
Clinical evidence requirements and outcome measurability shape regulatory acceptance and practitioner training investments.
- Pain Management:Neuromodulation of nociceptive pathways through wavelength-specific photon absorption. This application concentrates demand in Germany where KBA transport sector occupational therapy programs experiment with laser protocols.
- Tissue Repair:Acceleration of collagen synthesis and angiogenesis through mitochondrial stimulation. Rehabilitation centers prioritize this indication for post-surgical recovery where measurable healing endpoints satisfy payer scrutiny.
- Inflammation Reduction:Cytokine modulation and lymphatic drainage enhancement for chronic inflammatory conditions.
- Muscle Relaxation:Reduction of motor neuron excitability and localized blood flow improvement for spasticity management.
Pain Management anchors reimbursement negotiations; Tissue Repair shows steepest protocol expansion in post-acute settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China's hospital procurement departments show the lowest price elasticity, absorbing premium diode systems through centralized tenders. German pain management clinics exhibit moderate sensitivity, prioritizing clinical evidence over cost. North American home-use consumers demonstrate the highest elasticity, driving LED laser adoption at reduced price points.
China
NMPA registration pathways for laser acupuncture systems accelerate institutional procurement through hospital traditional medicine departments. The regulator's streamlined Class II device approvals compress market entry timelines for domestic manufacturers. Shanghai and Beijing's tier-one hospital networks concentrate procurement authority, displacing independent distributor channels.
Germany
BfArM reimbursement classification ambiguity for photobiomodulation therapies creates payment uncertainty that slows clinic adoption despite clinical efficacy documentation. The EU MDR elevates clinical evidence burdens for CE marking, filtering smaller manufacturers from European distribution. Munich and Berlin pain management clinic networks sustain concentrated Class IV laser demand through post-acute care protocol expansion.
United States
FDA 510(k) clearance requirements extend product development timelines for novel wavelength configurations, favoring established players with regulatory affairs infrastructure. Evolving guidance on at-home laser devices opens direct-to-patient channels for LED-based systems. California and Texas rehabilitation center chains drive physiotherapy channel consolidation through standardized equipment purchasing.
Japan
PMDA device registration maintains rigorous clinical evidence standards that limit new entrant penetration in hospital acupuncture departments. METI industrial policy supports domestic semiconductor laser diode production, reducing import dependency for therapeutic system manufacturers. Osaka's medical device cluster anchors manufacturing for Class III laser systems targeting conservative treatment protocols.
Australia
TGA medical device regulations align with EU MDR standards, creating parallel compliance burdens for manufacturers seeking market access. Private physiotherapy practice networks concentrate demand for portable low-level laser systems outside public hospital procurement. Sydney and Melbourne rehabilitation center expansion drives post-acute care equipment procurement at accelerating rates.
Acupuncture Lasers Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with backward integration into laser diode fabrication separating premium positioning from assembly-dependent competitors. The vendor base stratifies across three archetypes: semiconductor-captive system integrators, rehabilitation-channel specialists with recurring consumable revenue, and cost-optimized portable device assemblers. Competitive moves concentrate on M&A for regulatory capability acquisition and strategic partnerships with hospital procurement networks.
Among North American therapeutic laser developers, Erchonia Corporation and LiteCure LLC exemplify divergent channel strategies—one anchored in vertical semiconductor control, the other in application-specific training protocol deployment. Meditech Laser represents the European specialist archetype, occupying a position within rehabilitation-center partnership models that sustain recurring revenue streams. These three firms collectively illustrate how regulatory infrastructure and channel relationships determine viable competitive positioning across power classifications and geographic markets.
| Leading Market Players |
|---|
| Erchonia Corporation |
| Meditech Laser |
| ASA Laser |
| LiteCure LLC |
| RJ Laser |
| Sedatelac |
| Hwato |
| Schwa-medico GmbH |
| B-Cure Laser LTD |
| Others |
Supply Flow & Price Mechanics
Semiconductor diode fabrication scale economies in East Asia concentrate laser component supply among a handful of captive foundries, compressing price floors for Class IV system integrators while elevating procurement leverage for volume buyers in China's hospital networks. This concentration cascades downstream, forcing assembly-dependent portable device makers to absorb margin pressure or cede share to vertically integrated competitors with in-house diode production.
Pricing Analysis
Consumable and service contract revenue streams anchor lifetime value calculations for therapeutic laser manufacturers, with three-tier pricing structure across premium, standard, and economy levels differentiating Class IV institutional systems from LED-based home-use alternatives. Certification grade—specifically FDA 510(k) versus EU MDR CE marking—drives substantial price differentiation between regulated clinical channels and emerging consumer-direct segments. Cost compression in portable LED segments intensifies because semiconductor commoditization erodes hardware margins. Home-use buyers in North America exhibit highest price elasticity, while China's hospital procurement departments demonstrate lowest sensitivity due to centralized tender absorption of premium diode systems.
Supply Chain Analysis
Strategic stockpile preferences dominate inventory strategy for specialized laser diode components, with manufacturers maintaining 90-120 day buffers against foundry allocation volatility. Supply concentrates in Taiwan, South Korea, and Japan for gallium arsenide and indium phosphide semiconductor substrates essential to near-infrared therapeutic wavelengths. Raw material dependencies span rare-earth doping elements, precision optical coatings, and thermal management substrates. Single-source vulnerability in East Asian foundry capacity presents acute structural risk. Distribution runs through specialist medical device distributors in Europe, direct manufacturer contracts with Chinese hospital procurement departments, and physiotherapy channel consolidators in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
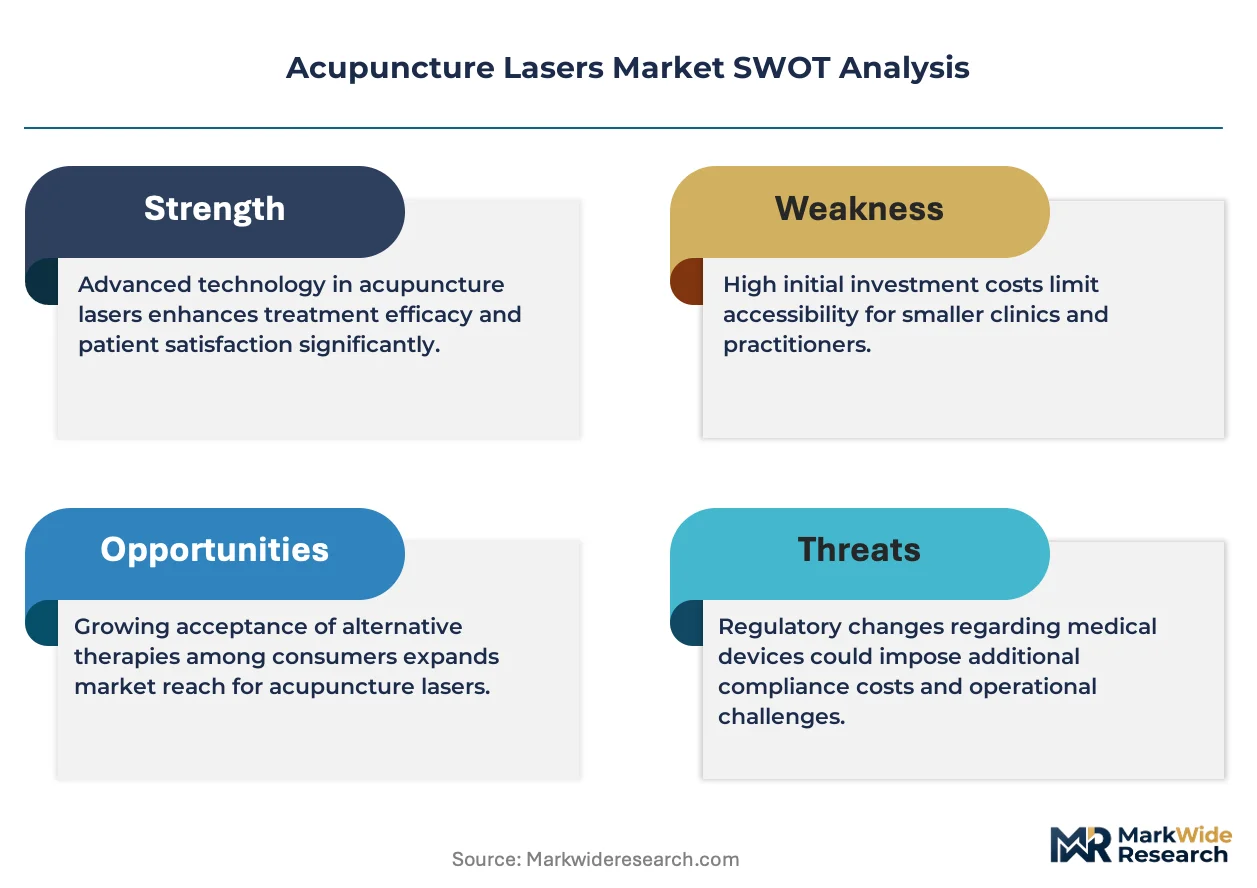
Fragmentation opportunity characterizes this market as regulatory complexity splinters procurement authority across divergent compliance pathways, creating defendable niches for specialists with captive capabilities in semiconductor sourcing or clinical evidence generation.
For Market Incumbents: Shield installed base relationships in German pain management clinic networks by embedding photobiomodulation training protocols that elevate switching costs for competitors. Deepen backward integration into laser diode fabrication to secure supply continuity against East Asian foundry allocation constraints. Prioritize M&A targeting regulatory affairs capabilities to navigate EU MDR clinical evidence burdens that filter smaller manufacturers from European distribution. For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for low-level laser devices present the most penetrable entry vector, enabling direct-to-patient channel development before scaling into institutional procurement. Target North American home-use segments where evolving regulatory clarity for consumer-directed systems creates temporary white space. Pursue white-label partnerships with established physiotherapy distributors to bypass capital-intensive channel buildout. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors semiconductor-captive system integrators over assembly-dependent portable device assemblers, as diode efficiency gains compress form factors and shift volume toward integrated manufacturers. Acquisition candidates with captive foundry relationships or dedicated clinical trial infrastructure command premium multiples. Watch EU MDR notified-body capacity constraints as inflection indicator—bottleneck resolution would accelerate new entrant penetration and compress incumbent pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence investment filters smaller competitors from European hospital procurement. |
| Hospital System Partnership | Direct contracts with China's tier-one hospital networks displace independent distributor channels. |
| Backward Integration | In-house laser diode fabrication secures supply continuity against East Asian foundry concentration. |
| Software Companion Development | Application-specific training protocols extend clinician loyalty and elevate switching costs. |
| Reimbursement Strategy | BfArM photobiomodulation code establishment would unlock German clinic procurement acceleration. |
Methodological Framework
Desk research of FDA 510(k) clearance databases, EU MDR notified-body registration records, and NMPA Class II device approval filings preceded structured interviews with hospital procurement managers, pain management clinic directors, rehabilitation center operations heads, and biomedical engineers at therapeutic laser manufacturers. Secondary validation drew from hospital equipment tender databases, GPO contract repositories, and semiconductor trade flow records. Bottom-up segment sizing triangulated against top-down macroeconomic healthcare expenditure models.
Variance decomposition across product type, technology, end user, and application dimensions structured the analytical framework over the projection horizon. CAGRs derived from segment-level unit economics and pricing trajectory assumptions, with cross-validation against clinician adoption rate surveys and reimbursement pathway progression timelines. Forecast inputs incorporated NMPA registration velocity, EU MDR notified-body capacity expansion, and FDA at-home device guidance evolution.
Decision-makers should treat outputs as directional under assumptions of stable regulatory enforcement intensity and continued traditional medicine integration in Chinese hospital departments; material deviation would warrant model refresh. Revision becomes warranted when EU MDR notified-body processing times or FDA 510(k) review durations cross threshold inflection points that alter competitive entry economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Medicine
Europe Complementary and Alternative Medicine Market
Alternative Medicine
Bio Magnetic Ear Stickers Market
Alternative Medicine
Global Complementary and Alternative Medicines Market
Alternative Medicine
Natural Cold, Cough, and Sore Throat Remedies Market
Alternative Medicine
Flower Essences Market
Alternative Medicine
Global OTC Herbal and Traditional Medicine Market
Alternative Medicine
US Aromatherapy Market
Alternative Medicine
Cold Laser Therapy Market
Alternative Medicine
Biopuncture Treatment Market
Alternative Medicine
Electrotherapy Market
Alternative Medicine
Disposable Acupuncture Needle Market
Alternative Medicine
Aromatherapy Market
Alternative Medicine
Ozone Therapy Units Market
Alternative Medicine
Traditional Chinese Herbal Medicine Market
Alternative Medicine
Global Homeopathic Product Market
Alternative Medicine
US Chiropractic Market