
 US Chiropractic Market | 2026-2036
US Chiropractic Market Size, Share, and Industry Trends Forecast 2026-2036
US Chiropractic Market Insights
Specialty certification tiers is bifurcating the competitive landscape into board-certified sports chiropractors and general practice operators. The Joint Corp. controls a retail-clinic footprint targeting convenience-driven patients with standardized adjustment protocols. Chiro One Wellness Centers, LLC leverages integrated wellness bundling to anchor recurring revenue streams. HealthSource Chiro differentiates through franchise-standardized rehabilitation protocols that reduce outcome variability.
Chiropractic care encompasses manual and instrument-assisted manipulation of the musculoskeletal system, primarily the spine, using controlled high-velocity low-amplitude thrusts typically delivered at forces of 100-400 Newtons to restore joint mobility and alleviate neural impingement. Its primary commercial purpose centers on non-pharmacological pain management and functional restoration for neuromusculoskeletal complaints. Spinal manipulation occupies the dominant revenue position due to established reimbursement codes and patient familiarity, while physical therapy segments exhibit faster structural growth as payers mandate conservative care prior to surgical authorization. Corporate customer channels represent an underdeveloped margin pool where occupational health contracts reduce long-term disability claims.
The National Board of Chiropractic Examiners sets competency standards that shape licensure mobility across state lines, while state chiropractic boards in Texas, California, and New York govern scope-of-practice boundaries that determine whether providers may perform diagnostic imaging or physical therapy modalities. OSHA workplace ergonomics guidelines indirectly stimulate employer-funded chiropractic utilization by linking musculoskeletal disorder prevention to reduced recordable injury rates. Stakeholders must monitor state-level scope expansion legislation and Medicare reimbursement rulemaking to anticipate volume shifts between cash-pay and insured patient segments.
Market Dynamics
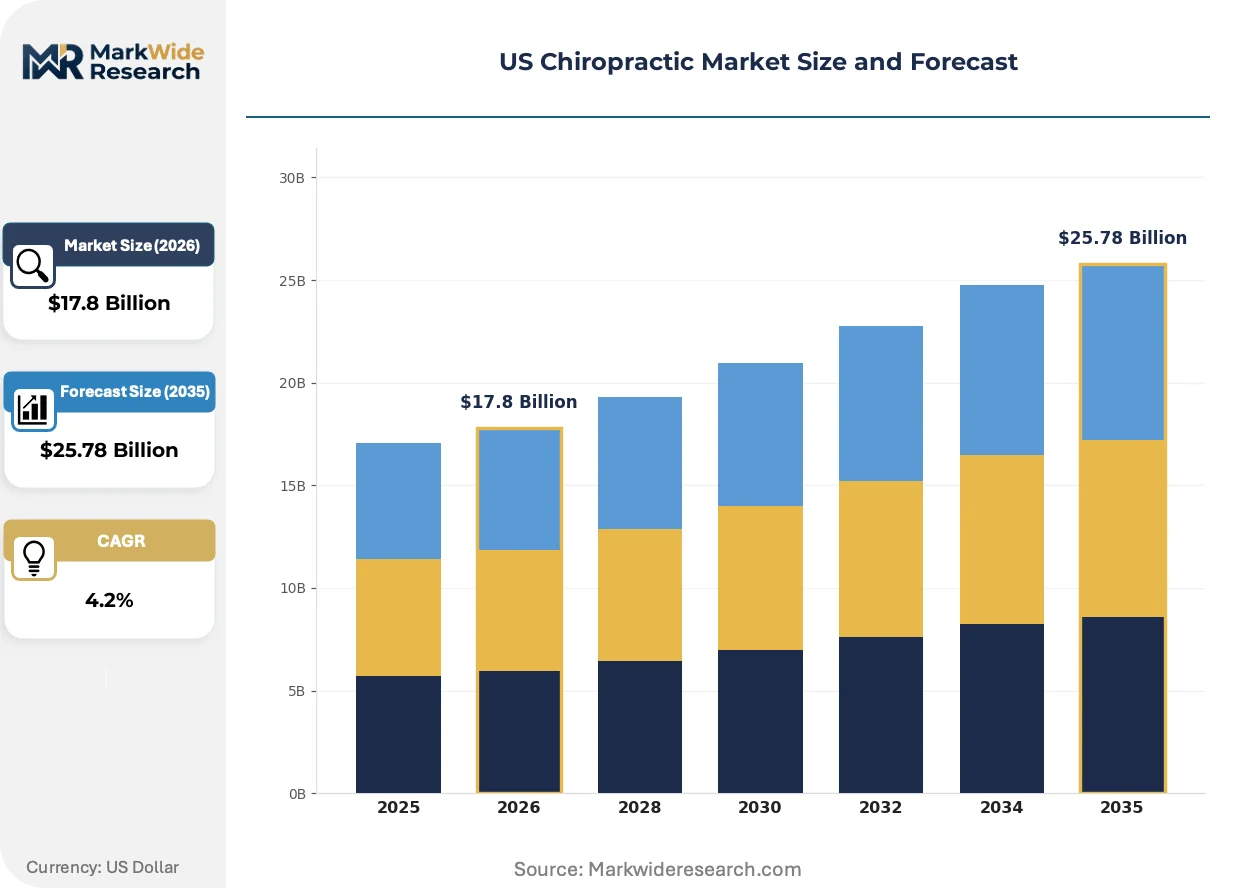
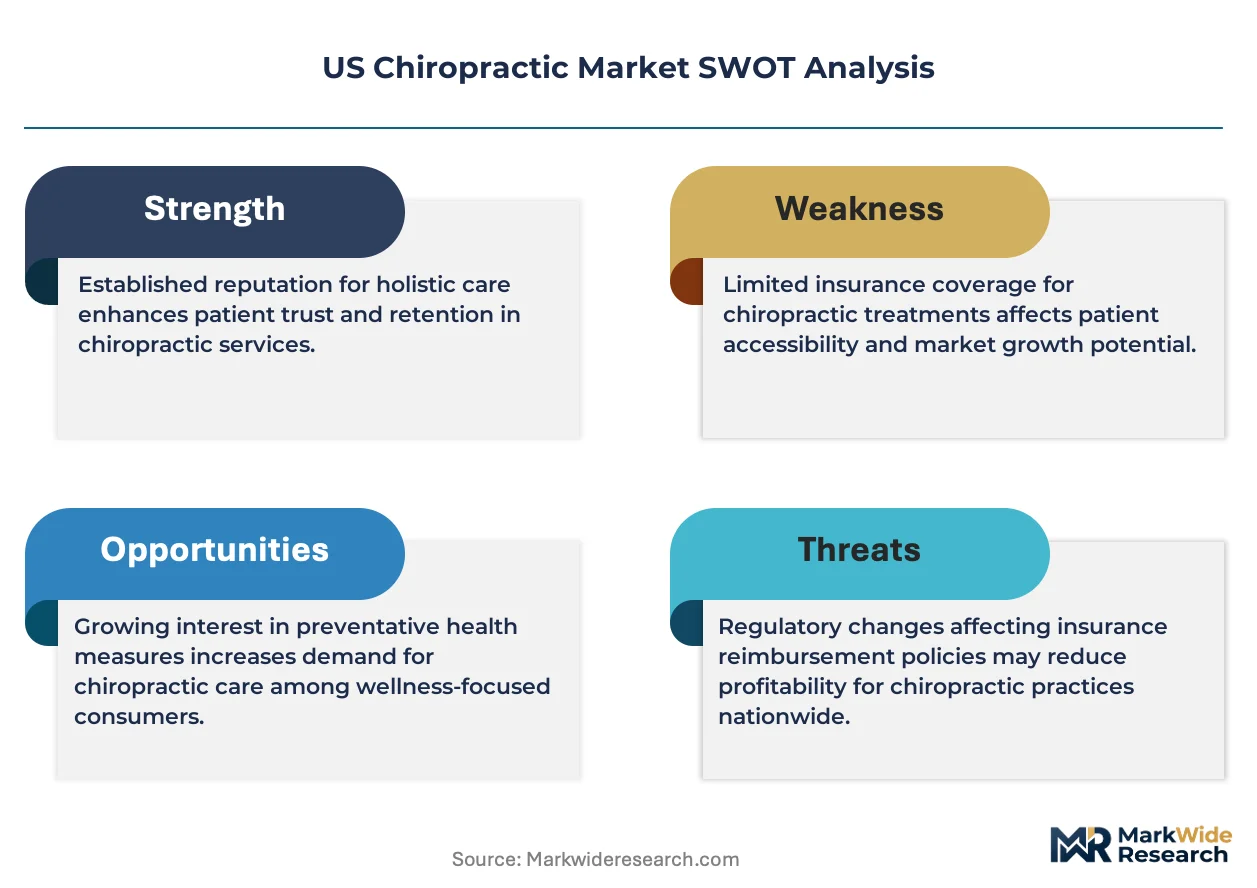
The US chiropractic market is undergoing structural compression as Medicare reimbursement rulemaking and employer-sponsored wellness program expansion simultaneously pull volume toward insured channels while squeezing cash-pay clinic margins.
Growth Catalysts
- OSHA workplace ergonomics guidelines:Federal mandates linking musculoskeletal disorder prevention to reduced recordable injury rates are driving occupational health contracts. Employers in manufacturing and logistics verticals now fund chiropractic utilization as a disability cost-containment tool.
- Conservative care prior authorization:Payer mandates requiring non-surgical intervention before surgical authorization are routing chronic back pain patients into chiropractic channels. This clinical pathway restructuring expands addressable patient volume.
- Texas-Florida-California clinic density:Aging demographic concentration and sports medicine integration in these three states generate disproportionate demand pull. Metro areas like Houston, Miami, and Los Angeles anchor national volume growth.
Market Restraints
- Medicare scope limitations:Federal reimbursement restrictions on diagnostic imaging and physical therapy modalities cap revenue per patient encounter. Legislative review timelines create planning uncertainty for multi-site operators.
- Specialty certification concentration:Board-certified sports chiropractors capture premium pricing tiers, compressing general practice operator margins. The certification gap limits workforce mobility into high-revenue service lines.
- Pharmacological substitution:Non-steroidal anti-inflammatory drugs and topical analgesics retain patient preference for acute pain episodes. OTC accessibility undermines chiropractic conversion for first-time musculoskeletal complaints.
Strategic Opportunities
- Corporate on-site clinics:Employer-funded occupational health contracts remain underpenetrated. Fortune 500 campuses in suburban Dallas and Atlanta present whitespace for embedded chiropractic service delivery.
- Integrated wellness bundling:Convergence of spinal manipulation with nutrition counseling and stress management protocols creates subscription revenue models. Patients in California wellness corridors demonstrate willingness to prepay for bundled care.
- Telehealth diagnostic triage:Remote initial assessment protocols are expanding rural patient access. State chiropractic boards in Texas and Florida have approved synchronous video consultations for new patient intake.
Industry Challenges
- Outcome standardization:Variable clinical protocols across franchise networks complicate payer contracting. HealthSource Chiro and similar operators struggle to demonstrate consistent disability reduction metrics to self-insured employers.
- Credentialing timeline compression:Multi-state licensure mobility remains constrained by non-uniform continuing education requirements. Practitioners face 6-18 month delays establishing practice authority when relocating across state lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Chiropractic Market |
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $25.78 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Spinal Manipulation, Physical Therapy, Massage Therapy, Rehabilitation Treatment Area: Back Pain, Neck Pain, Joint Issues, Headaches Device Type: Chiropractic Tables, Adjusting Instruments, Rehabilitation Equipment, Modalities Customer Type: Individual Patients, Corporates, Insurance Companies, Clinics |
| Companies Covered | Landmark Healthcare Services, Inc., Allied Health of Wisconsin, S.C., The Joint Corp., Multi-Specialty Healthcare Group, LLC, Sherman College of Chiropractic, Chiro One Wellness Centers, LLC, Magen David Community Center, Inc., HealthSource Chiro, Chiropractic Strategies Group, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Chiropractic Market Trends and Innovations
Technology adoption and reimbursement restructuring are fragmenting patient acquisition channels while elevating clinical outcome transparency as a competitive differentiator.
Instrument-assisted soft tissue mobilization (IASTM) tools incorporating piezoelectric feedback sensors are bifurcating treatment protocols between high-precision sports medicine applications and standardized retail clinic offerings. Board-certified practitioners in Florida and California are adopting these devices for objective tissue response measurement. The technology is bifurcating the market into outcome-documented premium tiers and convenience-driven adjustment-only segments.
Proposed Medicare coverage expansion for chiropractic services under federal legislative review is reshaping reimbursement structures. The policy shift would extend diagnostic imaging authority and physical therapy modality coverage to eligible providers. Texas and California markets are positioning for volume migration from cash-pay to insured patient segments.
Subscription-based membership models are displacing per-visit pricing in urban markets. Younger patient cohorts in Austin and Denver are prepaying for unlimited monthly adjustments. This behavioral shift concentrates revenue predictability for clinic operators while reducing administrative burden associated with claims processing.
US Chiropractic Market Segmentation
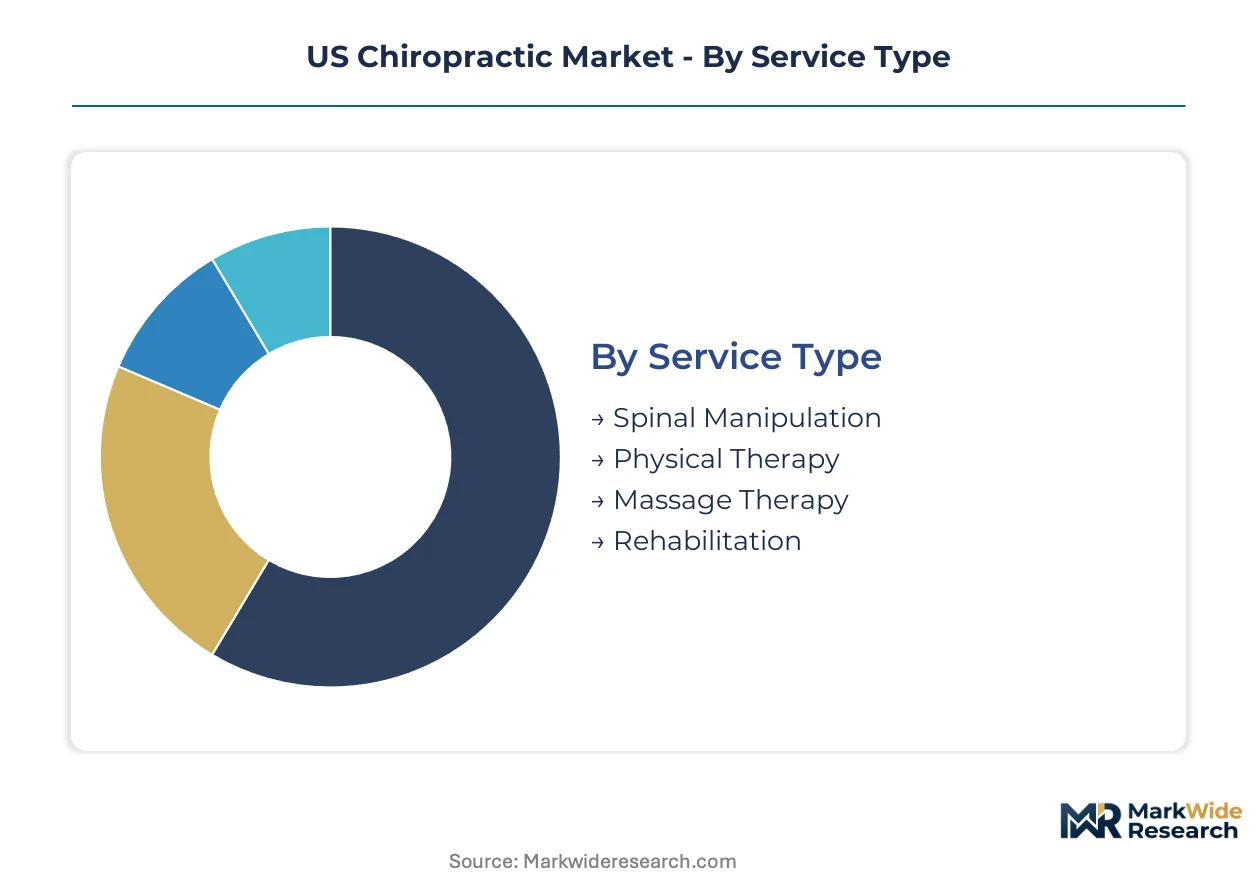
Segmentation reveals how chiropractic services compete against substitute therapies and device alternatives. Understanding these boundaries clarifies where margin pressure concentrates and where defensible revenue pools exist.
Service Type:
Physical therapy and massage services exert the strongest substitution pressure on traditional chiropractic delivery, forcing operators to differentiate through outcome documentation and speed of relief.
- Spinal Manipulation:Controlled high-velocity low-amplitude thrusts delivered at 100-400 Newtons restore joint mobility and alleviate neural impingement. Texas, Florida, and California clinics anchor national volume due to aging demographics and sports medicine integration driving encounter frequency.
- Physical Therapy:Exercise-based rehabilitation protocols targeting neuromuscular re-education and functional restoration. Payer mandates requiring conservative care prior to surgical authorization are routing chronic back pain patients into this segment, expanding addressable volume fastest.
- Massage Therapy:Soft tissue manipulation for myofascial release and circulatory enhancement, often bundled with spinal adjustment packages.
- Rehabilitation:Structured protocols combining therapeutic exercise with ergonomic education for disability reduction.
Spinal manipulation retains volume leadership; physical therapy holds the steepest expansion curve.
Treatment Area:
Cost tier stratification separates acute episodic care from chronic management contracts, with back pain commanding premium reimbursement while headache treatment faces OTC analgesic competition.
- Back Pain:Lumbar and thoracic spine complaints comprising the dominant clinical presentation. Houston and Dallas metro areas generate disproportionate demand pull from occupational injury patterns in energy and logistics sectors.
- Neck Pain:Cervical spine dysfunction often linked to workplace ergonomics and whiplash trauma. OSHA guidelines linking musculoskeletal disorder prevention to reduced recordable injury rates stimulate employer-funded utilization in manufacturing verticals.
- Joint Issues:Peripheral extremity complaints including shoulder, knee, and hip dysfunction requiring instrument-assisted mobilization.
- Headaches:Tension-type and cervicogenic headache presentations competing directly with pharmacological substitution from NSAIDs and triptans.
Back pain commands the highest encounter value; neck pain is climbing the fastest as workplace ergonomics awareness spreads.
Device Type:
Supply concentration among specialized manufacturers creates margin pressure for clinic operators while enabling premium pricing for precision-enabled equipment categories.
- Chiropractic Tables:Adjustable positioning systems enabling controlled patient positioning for thrust delivery. Standardized models dominate retail clinic footprints while specialized drop tables anchor sports medicine practices.
- Adjusting Instruments:Hand-held mechanical and electronic devices delivering instrument-assisted adjustments. Piezoelectric feedback sensors are bifurcating protocols between precision sports applications and standardized retail offerings.
- Rehabilitation Equipment:Resistance and proprioceptive training devices for functional restoration protocols.
- Modalities:Electrical stimulation, ultrasound, and thermal therapy adjuncts for pain modulation.
Chiropractic tables retain installed base dominance; adjusting instruments are gaining share fastest through precision differentiation.
Customer Type:
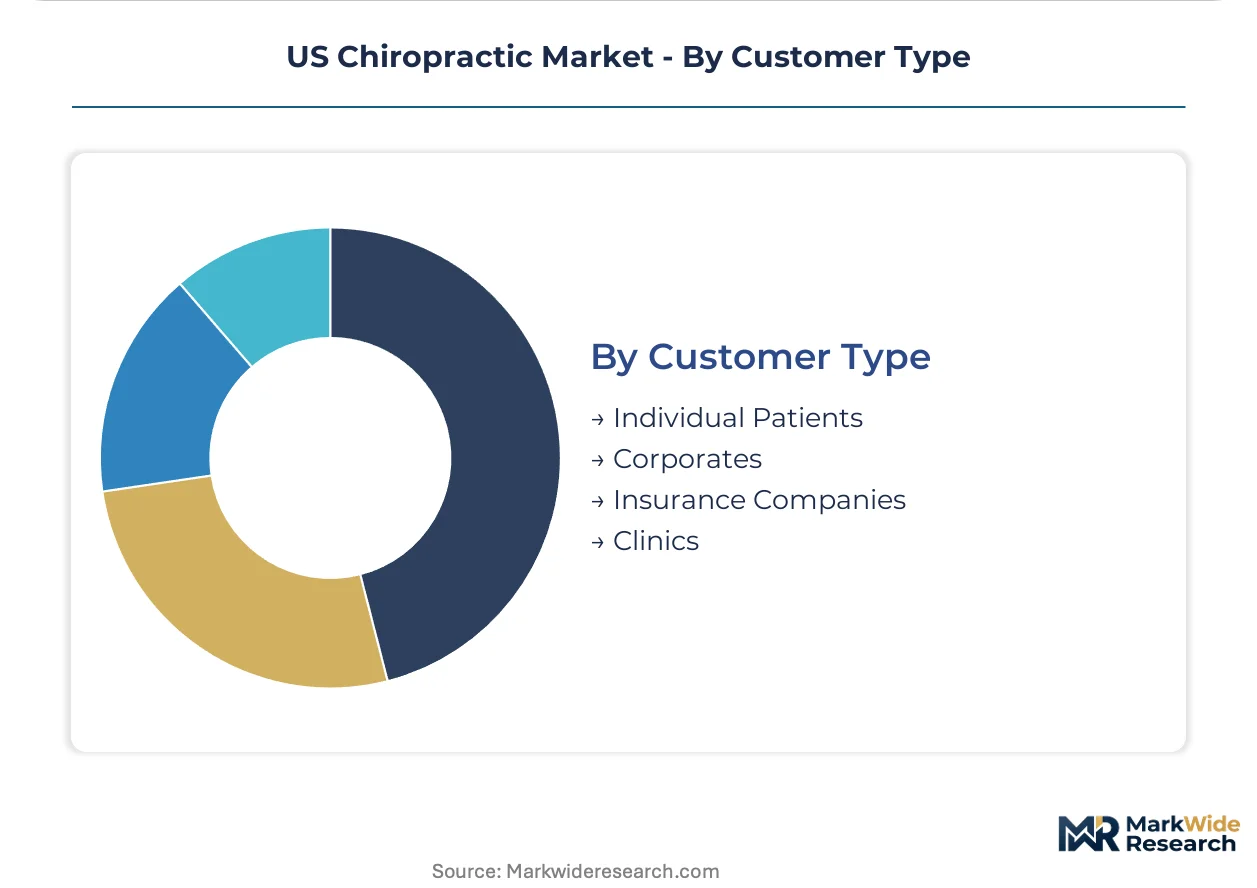
Customer maturity separates established insured channels from emerging direct-pay models, with corporate contracts representing the least penetrated margin pool.
- Individual Patients:Direct-pay and insured consumers seeking episodic or maintenance care. Austin and Denver cohorts demonstrate willingness to prepay for subscription-based unlimited monthly adjustments.
- Corporates:Employer-funded occupational health contracts for musculoskeletal disorder prevention. Fortune 500 campuses in suburban Dallas and Atlanta present whitespace for embedded service delivery with disability cost-containment value.
- Insurance Companies:Third-party payers mandating conservative care pathways and reimbursing standardized encounter codes.
- Clinics:Multi-site operators and franchise networks purchasing equipment and protocols at scale.
Individual patients retain volume leadership; corporate channels represent the steepest expansion opportunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chiropractic service flows concentrate domestically within the United States, with Texas, Florida, and California functioning as primary demand anchors that shape national clinic density and reimbursement policy development.
Texas
Houston and Dallas metro areas generate disproportionate demand pull from occupational injury patterns in energy and logistics sectors. OSHA workplace ergonomics guidelines stimulate employer-funded utilization as manufacturing verticals link musculoskeletal disorder prevention to reduced recordable injury rates. The Texas Board of Chiropractic Examiners governs scope-of-practice boundaries that determine diagnostic imaging authority.
Florida
Miami anchors national volume growth through aging demographic concentration and sports medicine integration driving encounter frequency. State chiropractic boards have approved synchronous video consultations for new patient intake, expanding telehealth diagnostic triage access. Piezoelectric feedback sensors in instrument-assisted soft tissue mobilization tools are bifurcating treatment protocols between precision sports applications and standardized retail offerings.
California
Los Angeles and wellness corridors in Austin demonstrate willingness to prepay for subscription-based unlimited monthly adjustments and integrated wellness bundling. Medicare coverage expansion for chiropractic services under federal legislative review is reshaping reimbursement structures, positioning the state for volume migration from cash-pay to insured patient segments. The California Board of Chiropractic Examiners oversees continuing education requirements that constrain multi-state licensure mobility.
New York
The New York Metro area exhibits concentrated demand for chronic back pain management as payer mandates requiring conservative care prior to surgical authorization route patients into chiropractic channels. State scope-of-practice regulations determine whether providers may perform physical therapy modalities. Manhattan and Brooklyn clinic networks face margin pressure from specialty certification concentration as board-certified sports chiropractors capture premium pricing tiers.
Illinois
Chicago anchors Midwest demand for non-pharmacological pain management alternatives competing directly with pharmacological substitution from NSAIDs. Chiro One Wellness Centers leverages integrated wellness bundling to anchor recurring revenue streams in this market. The Illinois Department of Financial and Professional Regulation governs licensure standards that shape workforce mobility into high-revenue service lines.
US Chiropractic Market Competitive Landscape
Listed leaders compete with private specialists across standardization and convenience dimensions, creating a tiered structure where retail clinic footprints target volume-driven patients while integrated wellness operators capture subscription revenue. The market fragments between franchise-standardized protocols and outcome-documented premium tiers. Three archetypes dominate: retail convenience operators with standardized adjustment protocols, integrated wellness bundlers anchoring recurring revenue, and specialty-certified sports medicine practitioners commanding premium pricing. Competitive moves concentrate on geographic expansion through franchise development and technology licensing for instrument-assisted precision differentiation.
Within the retail convenience tier, The Joint Corp. and HealthSource Chiro occupy positions exemplifying standardized protocol deployment across multi-site footprints. Chiro One Wellness Centers, LLC represents the integrated wellness bundling archetype, anchoring subscription-based revenue models that reduce administrative burden associated with claims processing. These three entities collectively illustrate the competitive bifurcation between volume-driven retail accessibility and outcome-documented premium service delivery.
| Leading Market Players |
|---|
| Landmark Healthcare Services, Inc. |
| Allied Health of Wisconsin, S.C. |
| The Joint Corp. |
| Multi-Specialty Healthcare Group, LLC |
| Sherman College of Chiropractic |
| Chiro One Wellness Centers, LLC |
| Magen David Community Center, Inc. |
| HealthSource Chiro |
| Chiropractic Strategies Group, Inc. |
| Others |
Pricing and Supply Chain Analysis
Multi-site operator scale economies in Texas and California drive purchasing leverage for chiropractic tables and adjusting instruments, compressing per-unit acquisition costs for franchise networks while independent practitioners face higher equipment procurement floors. This scale gradient concentrates supply relationships with specialized manufacturers and reinforces price stratification between retail clinic chains and solo practitioners.
Pricing Analysis
Next-generation piezoelectric feedback sensors in instrument-assisted soft tissue mobilization tools command premium positioning against legacy mechanical adjusting instruments and entry-level manual tables. Pricing stratifies across premium, standard, and economy tiers, with board-certified sports chiropractors capturing top-tier rates through outcome documentation while retail clinics compete on volume accessibility. Pricing pressure stems from Medicare reimbursement uncertainty as legislative review timelines delay insured channel expansion. Corporate occupational health buyers exhibit lowest price sensitivity due to disability cost-containment value, while individual cash-pay patients in urban markets demonstrate highest sensitivity to per-visit rates.
Supply Chain Analysis
Equipment inventory lead times for specialized drop tables and rehabilitation modalities extend 8-14 weeks from domestic manufacturers concentrated in Illinois, California, and Tennessee. Chiropractic table production draws from steel framing components, precision hydraulic systems, and medical-grade upholstery materials sourced from regional metal fabricators and specialty textile suppliers. Single-source vulnerability concentrates in piezoelectric sensor modules imported from South Korean electronics manufacturers. Distribution runs through direct manufacturer-to-clinic relationships for large multi-site operators, with independent practitioners purchasing through medical equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against pharmacological substitution as NSAIDs and topical analgesics retain acute pain episode preference, eroding first-time chiropractic conversion rates.
For Market Incumbents: Compound subscription revenue predictability through integrated wellness bundling that anchors patient retention beyond episodic spinal manipulation. Deepen backward integration into rehabilitation equipment supply to reduce procurement cost variability across multi-site footprints. Defensive positioning against The Joint Corp.'s retail convenience model requires outcome documentation investment to secure employer-funded occupational health contracts. For New Entrants and Emerging Players: Lead with telehealth diagnostic triage protocols approved by Texas and Florida state chiropractic boards to capture rural patient access whitespace. Target Fortune 500 corporate campuses in suburban Dallas and Atlanta for embedded on-site clinic deployment, where disability cost-containment value propositions face minimal established competition. Go-to-market positioning should emphasize OSHA workplace ergonomics alignment to unlock occupational health procurement channels. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated wellness bundlers with subscription membership models in California wellness corridors. Long-term viability across the analysis window favors operators with demonstrated outcome standardization for payer contracting and multi-state licensure mobility. Acquisition target archetype: mid-scale regional networks with established employer relationships and pending specialty certification concentration. Signal to monitor: Medicare reimbursement rulemaking finalization as volume migration catalyst from cash-pay to insured segments.| Strategic Initiative | Industry Significance |
|---|---|
| Specialty Certification Investment | Board-certified sports chiropractic credentials unlock premium pricing tiers and employer contracting access. |
| Corporate On-Site Clinic Expansion | Embedded service delivery at Fortune 500 campuses captures disability cost-containment procurement budgets. |
| Telehealth Diagnostic Triage Deployment | State-approved video consultation protocols expand rural patient acquisition beyond traditional geographic constraints. |
| Integrated Wellness Bundling | Convergence with nutrition counseling and stress management creates subscription revenue predictability. |
| Outcome Standardization Protocols | Consistent disability reduction metrics satisfy self-insured employer payer contracting requirements. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of CMS Medicare reimbursement databases, state chiropractic board regulatory filings, and OSHA workplace injury statistics. Primary interviews engaged clinic operators, employer benefits directors, chiropractic equipment manufacturers, and payer network managers. Secondary validation drew from National Board of Chiropractic Examiners competency standards, franchise disclosure documents, and hospital procurement databases. Bottom-up encounter volume modeling triangulates against top-down market sizing from reimbursement code analysis.
Segmentation dimensions modeled encompass service type, treatment area, device category, and customer channel across the projection horizon. CAGRs derive from encounter frequency trends, reimbursement rate trajectories, and demographic demand elasticity. Forecast inputs include aging population concentration in Texas-Florida-California corridors, employer wellness program expansion rates, and scope-of-practice legislative activity.
Forecasts assume regulatory continuity in Medicare reimbursement rulemaking and state chiropractic board authority; material policy shifts would require re-modeling volume migration between cash-pay and insured segments. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Medicine
US Aromatherapy Market
Alternative Medicine
Bio Magnetic Ear Stickers Market
Alternative Medicine
Disposable Acupuncture Needle Market
Alternative Medicine
Ozone Therapy Units Market
Alternative Medicine
Aromatherapy Market
Alternative Medicine
Orthomolecular Medicine Market
Alternative Medicine
Acupuncture Lasers Market
Alternative Medicine
Homeopathic Medicine Market
Alternative Medicine
Flower Essences Market
Alternative Medicine
Global OTC Herbal and Traditional Medicine Market
Alternative Medicine
Natural Cold, Cough, and Sore Throat Remedies Market
Alternative Medicine
Fire Cupping Market
Alternative Medicine
Global Acupuncture Market
Alternative Medicine
Global Homeopathic Product Market
Alternative Medicine
Electrotherapy Market
Alternative Medicine
Vacuum Cupping Market