
 Silica Fume Market | 2026-2036
Silica Fume Market Size, Share, and Industry Trends Forecast 2026-2036
Silica Fume Market Outlook
REACH is recalibrating the cost-of-entry calculus for silica fume producers seeking European market access, forcing investment in traceability systems and hazardous substance documentation. Elkem leverages its integrated ferrosilicon-silica fume production network to sustain cost advantages across Nordic and North American supply corridors. Ferroglobe anchors its competitive position through captive metallurgical feedstock and specialized densification technology. Simcoa Operations dominates Oceania supply through its Western Australian silicon metal complex, converting furnace off-gas into specification-grade silica fume for regional concrete admixture formulators.
Silica fume consists of ultrafine amorphous silicon dioxide particles recovered as a byproduct of silicon metal and ferrosilicon alloy production, with particle sizes typically below one micron and pozzolanic reactivity exceeding that of fly ash or slag. Its primary industrial purpose centers on enhancing concrete compressive strength, reducing permeability, and extending service life in aggressive chemical or marine environments. Dense silica fume leads volume consumption in ready-mix and precast concrete applications where bulk handling logistics favor flowable, low-dust material. Micronized silica fume commands premium positioning in electronics-grade encapsulants and high-purity coating formulations where particle size distribution directly governs rheological performance. Granulated silica fume occupies a narrowing mid-market niche as blenders seek to balance dust suppression with reactivity retention.
The EPA governs airborne silica exposure limits in US manufacturing and construction workplaces, while OSHA enforces permissible exposure standards that shape packaging, handling protocols, and end-user training requirements. China's MEE implements emissions controls on ferroalloy furnaces that simultaneously constrain silica fume raw material availability and drive quality upgrading. India's BIS certification requirements for silica fume used in dam and nuclear containment concrete create non-tariff barriers that favor established testing relationships. Stakeholders must monitor how tightening carbon border mechanisms and evolving pozzolan standards in major concrete-consuming jurisdictions reshape sourcing economics and product qualification timelines.
Market Dynamics
The EU Green Deal is compressing embodied carbon thresholds for construction materials, forcing silica fume suppliers to document supply chain emissions while positioning their pozzolanic reactivity as a cement-reduction lever for concrete producers facing Scope 3 pressure.
Growth Catalysts
- REACH compliance mandates:European chemical registration requirements are filtering out undocumented silica fume imports, consolidating volume with traceable producers who can certify hazardous substance profiles.
- Marine infrastructure specifications:Port authorities in the Netherlands and Singapore now require silica fume dosages in chloride-exposed concrete, embedding the material in durability standards for coastal construction.
- Ferrosilicon production clustering:China's dominance in metallurgical-grade silicon output creates raw material proximity that shortens logistics loops for domestic silica fume recovery and densification.
Market Restraints
- Electrode cost volatility:Graphite electrode prices swing with steelmaking demand cycles, squeezing margins for ferrosilicon operators whose furnace economics govern silica fume feedstock availability.
- Single-source furnace dependency:Individual silicon metal plants in Norway and Iceland represent concentrated supply nodes where unplanned maintenance triggers regional specification-grade shortages.
- Fly ash substitution:Coal-combustion residues from power plants undercut silica fume pricing in markets where permeability specifications remain unenforced.
Strategic Opportunities
- India dam certification pathways:BIS recognition for silica fume in nuclear containment and hydroelectric structures opens qualified-supplier status for testing laboratories with established Bureau relationships.
- Carbon border mechanism positioning:The EU's CBAM creates first-mover advantage for producers with verified low-carbon metallurgical routes and third-party emission audits.
- Geopolymer binder convergence:Alkali-activated cement formulations combining silica fume with slag are electrifying research pipelines at technical universities in Switzerland and Canada.
Industry Challenges
- Amorphous silica certification timelines:Laboratory validation of crystalline content below detection limits stretches qualification schedules for new furnace sources seeking ASTM C1240 recognition.
- Densification equipment capex:Pneumatic compaction systems for converting raw fume to bulk-density product require capital commitments that strain mid-scale ferroalloy operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silica Fume Market |
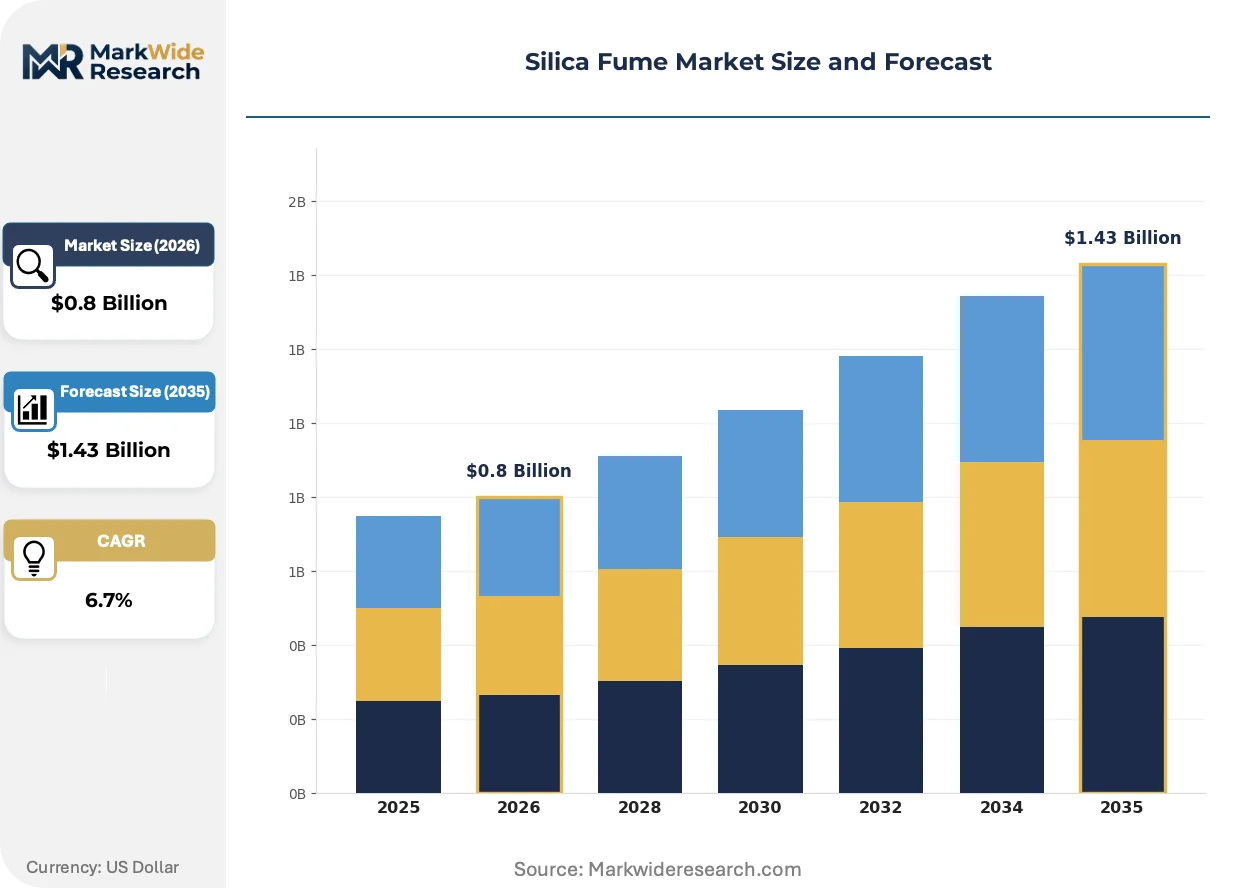
| Market Size in 2026 | $0.8 Billion |
| Market Size in 2035 | $1.43 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dense Silica Fume, Light Silica Fume, Micronized Silica Fume, Granulated Silica Fume Application: Construction, Electronics, Transportation, Coatings End User: Building Contractors, Aerospace Manufacturers, Electronics Assemblers, Paint Producers Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | RW Silicium GmbH, CCMA, Elkem, Washington Mills, Fesil, Ferroglobe, Wacker, Simcoa Operations, Finnfjord, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silica Fume Market Strategic Shifts
Electrification of metallurgical furnace operations and tightening concrete durability codes are compressing the window between silica fume recovery and specification-grade certification, rewarding producers with integrated quality control infrastructure.
Advanced densification technology is electrifying material handling economics in ready-mix concrete supply chains. Automated pneumatic compaction systems convert ultrafine raw fume into flowable, low-dust product that batch plants can pneumatically convey without respiratory protection protocols. Major concrete producers in Germany and California are retrofitting silo infrastructure to receive bulk-densified silica fume, compressing packaging costs and site labor requirements.
REACH Article 33 disclosure obligations are recalibrating documentation burdens across European construction chemical supply chains. Substance-of-very-high-conern screening now extends to silica fume impurities, compelling importers to maintain furnace-level traceability from ferrosilicon smelters in Iceland and Norway. Admixture formulators are consolidating supplier panels to entities with established SCIP database entries and downstream communication protocols.
Specification-driven procurement is consolidating buyer power among engineering-procurement-construction firms with in-house concrete durability expertise. Tier-one contractors in Australia and the United Arab Emirates now mandate silica fume dosages by performance grade rather than brand, displacing relationship-based sourcing with certified-test-result protocols. This compression of qualification criteria favors producers with multi-jurisdiction accreditation and third-party reactivity verification.
Silica Fume Market Segmentation
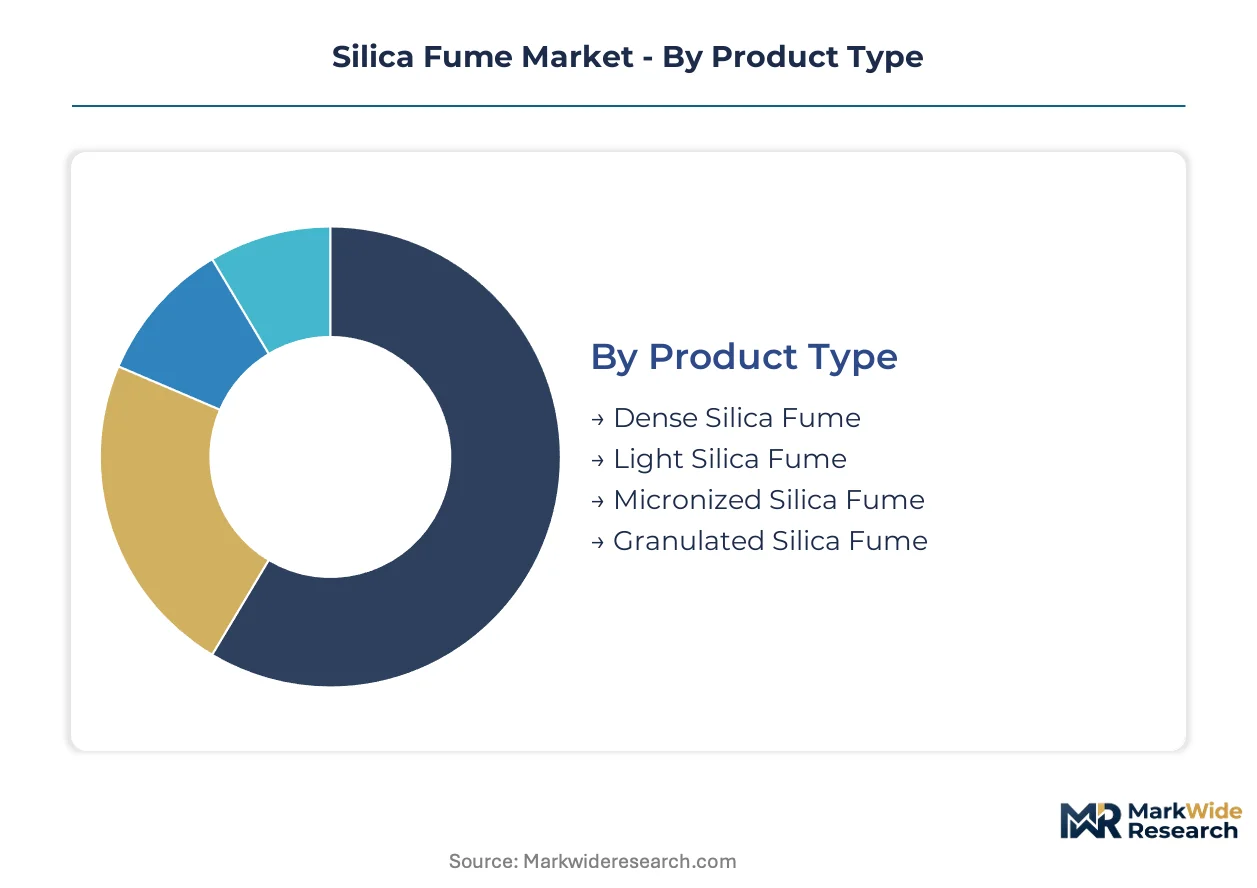
Silica fume specifications diverge sharply across handling requirements and purity thresholds, with product form dictating logistics economics and application suitability. Procurement patterns cluster around densification technology maturity and regional admixture infrastructure.
Product Type:
Buyers differentiate primarily by bulk density requirements and dust suppression needs at the batch plant.
- Dense Silica Fume:Pneumatically compacted to 500-700 kg/m³ bulk density, this flowable grade eliminates bag-breaking labor and respiratory exposure protocols. Ready-mix concrete producers in Germany and California favor pneumatic silo reception systems. Volume sits with dense silica fume; growth tilts toward micronized variants.
- Micronized Silica Fume:Sub-micron particle size distribution with tight PSD control enables high-purity encapsulant formulations for semiconductor packaging. Electronics assemblers in Japan and South Korea specify surface area above 20 m²/g for underfill applications.
- Light Silica Fume:Untreated ultrafine powder with bulk density below 300 kg/m³ requires specialized dust collection during handling. Regional concrete producers without pneumatic infrastructure absorb higher packaging costs.
- Granulated Silica Fume:Pelletized form balances dust suppression with partial reactivity retention, occupying mid-market positioning as blenders seek handling convenience without full densification investment.
Margin compression favors densification scale; specialty purity commands price premiums.
Application:
Specification intensity varies by exposure severity and structural performance requirements.
- Construction:Marine infrastructure specifications in the Netherlands and Singapore mandate silica fume dosages for chloride resistance in port structures. High-performance concrete for nuclear containment in India requires BIS-certified amorphous content below crystalline detection limits.
- Electronics:Semiconductor encapsulants and thermal interface materials exploit ultrafine particle packing density. Electronics-grade specifications from JIS and ASTM govern purity thresholds for die-attach adhesives.
- Transportation:Bridge deck overlays and tunnel linings specify silica fume for freeze-thaw durability. State DOTs in California and New York embed the material in accelerated construction warranties.
- Coatings:High-build industrial coatings leverage pozzolanic reactivity for corrosion protection on offshore platforms. Marine coating formulators in Norway specify low-impurity grades for immersion service.
Construction absorbs the heaviest tonnage; electronics applications expand most quickly on value-per-kilogram metrics.
End User:
Technical sophistication determines whether procurement emphasizes certified-test protocols or relationship-based supply assurance.
- Building Contractors:Tier-one EPC firms in Australia and the United Arab Emirates mandate performance-grade silica fume with third-party reactivity verification, displacing brand-loyal sourcing.
- Electronics Assemblers:Semiconductor packaging houses specify furnace-level traceability for SCIP database compliance under REACH Article 33 obligations.
- Aerospace Manufacturers:High-temperature composite prepregs require low-alkali silica fume for carbon fiber compatibility. OEM qualification timelines stretch 18-24 months for new furnace sources.
- Paint Producers:Industrial coating formulators prioritize consistent particle size distribution over absolute purity, sourcing through distributors with regional blending capabilities.
Contractor consolidation concentrates volume; electronics assemblers drive specification upgrading.
Distribution Channel:
Channel selection tracks shipment scale, technical service requirements, and geographic concentration of demand.
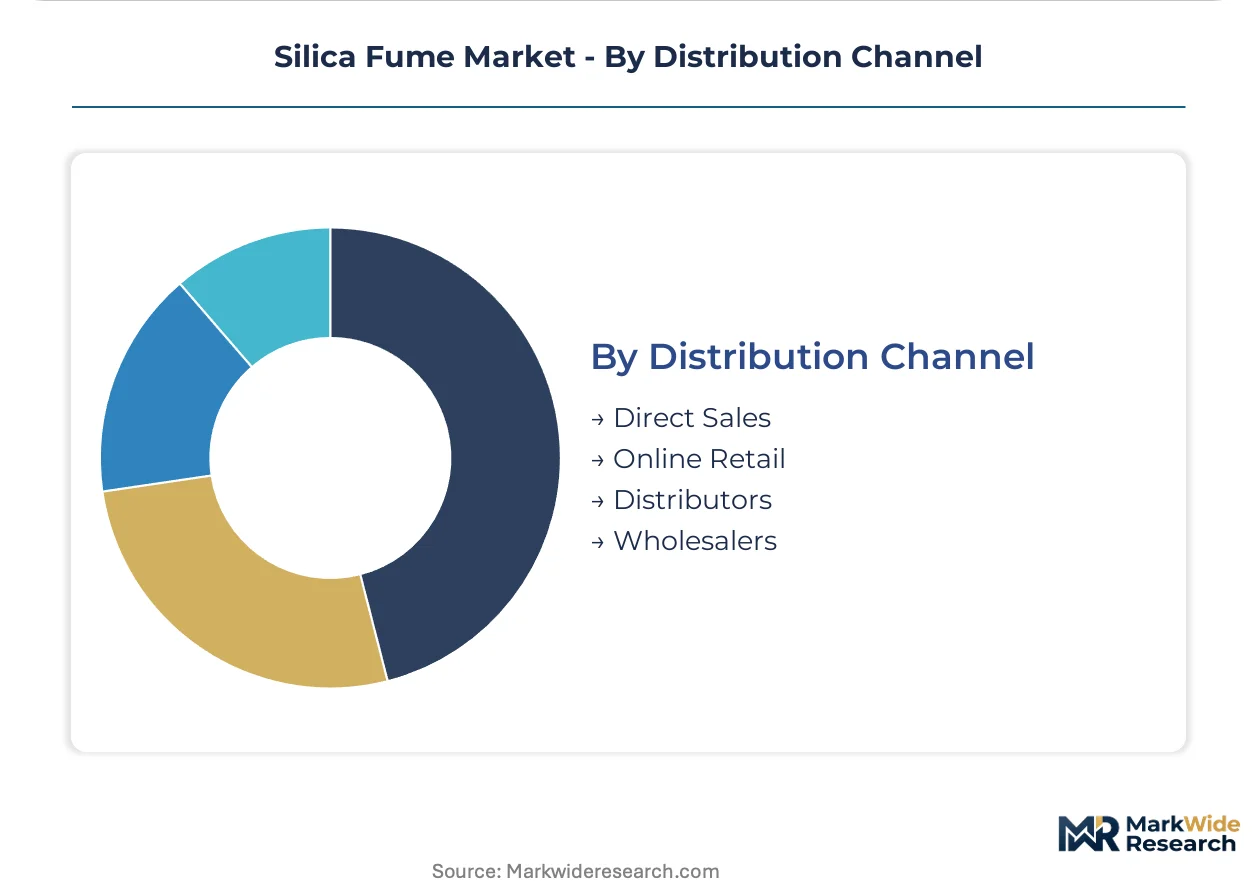
- Direct Sales:Captive supply agreements link ferrosilicon producers like Elkem with major concrete admixture formulators, bypassing margin layers for 500-tonne-plus annual offtake.
- Distributors:Regional construction chemical distributors stock densified silica fume for mid-scale ready-mix producers lacking silo infrastructure. Inventory carrying costs favor producers with Nordic and North American warehouse positioning.
- Wholesalers:Bagged product for small contractors and repair applications moves through building material wholesalers with established construction site delivery networks.
- Online Retail:Micronized and specialty grades for research institutions and coating formulators list through B2B platforms, though bulk silica fume resists e-commerce penetration.
Direct relationships dominate tonnage; distributors capture fragmented regional demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's ferrosilicon industrial parks concentrate silica fume recovery capacity near metallurgical feedstock sources. Norway and Iceland host furnace clusters leveraging low-carbon hydropower for silicon metal production. India's dam construction corridors drive specification-grade demand through BIS certification pathways.
China
Infrastructure buildout in the Yangtze River Delta and Pearl River Delta absorbs dense silica fume for high-performance concrete specifications. MEE emissions controls on ferroalloy furnaces simultaneously constrain raw material availability and drive quality upgrading among domestic producers. Ningxia and Inner Mongolia host integrated ferrosilicon-silica fume complexes serving regional admixture formulators.
Norway
Subsea tunnel and offshore platform specifications mandate silica fume dosages for chloride resistance in North Sea marine environments. REACH Article 33 disclosure obligations compel furnace-level traceability documentation for European market access. Rana and Mo i Rana anchor metallurgical clusters converting hydropower-fed silicon metal production into specification-grade silica fume.
United States
State DOTs in California and New York embed silica fume in accelerated bridge construction warranties and freeze-thaw durability standards. EPA airborne silica exposure limits and OSHA permissible exposure standards shape packaging, handling protocols, and end-user training requirements. Pacific Northwest concrete producers source from regional densification facilities serving marine infrastructure projects.
India
Hydroelectric dam and nuclear containment projects require BIS-certified silica fume with amorphous content below crystalline detection limits. The Bureau of Indian Standards certification creates non-tariff barriers favoring established testing relationships. Maharashtra and Gujarat host concrete admixture formulators building qualified-supplier status through documented furnace traceability.
Iceland
Carbon border mechanism positioning rewards producers with verified low-carbon metallurgical routes and third-party emission audits. EU Green Deal embodied carbon thresholds for construction materials force documentation of supply chain emissions from silicon metal feedstock. Grundartangi anchors a furnace complex supplying specification-grade silica fume to European concrete producers facing Scope 3 pressure.
Silica Fume Market Competitive Environment
Nordic producers anchor one tier; Chinese specialists hold volume positioning through ferrosilicon production clustering. The market structures around integrated metallurgical operators, regional densification specialists, and specification-grade certification laboratories. Three archetypes dominate: captive ferroalloy-silica fume complexes, independent densification processors, and electronics-grade purity refiners. Capacity expansion and backward integration into furnace feedstock represent the dominant competitive moves.
Among Nordic integrated operators, Elkem and Finnfjord exemplify the captive metallurgical model, leveraging hydropower-fed silicon metal production to supply specification-grade material. Ferroglobe occupies a position within the multi-jurisdiction furnace network tier, spanning European and North American production nodes. Simcoa Operations anchors the regional specialist archetype, converting Western Australian furnace off-gas into specification-grade product for Oceania concrete markets.
| Leading Market Players |
|---|
| RW Silicium GmbH |
| CCMA |
| Elkem |
| Washington Mills |
| Fesil |
| Ferroglobe |
| Wacker |
| Simcoa Operations |
| Finnfjord |
| Others |
Value Chain & Pricing Dynamics
Automated pneumatic densification systems are compressing unit economics for specification-grade material while simultaneously consolidating volume with producers possessing integrated furnace-to-silo infrastructure. This technology transition rewards operators with captive ferrosilicon feedstock and punishes merchant processors lacking compaction scale.
Pricing Analysis
Short lead-time premiums distinguish contract offtake from spot market transactions in specification-grade silica fume procurement. Three-tier pricing structure across electronics-grade, construction-densified, and raw-untreated levels reflects certification burden and handling investment. Pricing pressure stems from fly ash substitution in markets with unenforced permeability codes. Ready-mix concrete producers exhibit highest price sensitivity; semiconductor encapsulant formulators prioritize purity over cost.
Supply Chain Analysis
Freight economics from furnace clusters in Norway, Iceland, and China's Ningxia region dictate landed cost differentials across consumption nodes. Raw material availability draws from silicon metal and ferrosilicon smelter off-gas recovery, with graphite electrode costs feeding furnace economics. Single-source furnace vulnerability in Nordic hydropower regions creates regional shortage risk. Distribution runs through direct captive agreements for major admixture formulators and regional distributors for fragmented ready-mix demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH Article 33 disclosure obligations and BIS certification pathways erect compliance moats that favor incumbent producers with established traceability infrastructure and laboratory relationships.
For Market Incumbents: Deepen backward integration into furnace feedstock through long-term electrode supply agreements and hydropower purchasing contracts. Expand densification capacity in California and Germany to capture bulk-handling retrofit demand from major concrete producers. Fly ash substitution in Southeast Asian markets threatens pricing power in unregulated segments. For New Entrants and Emerging Players: The gap between premium electronics-grade and economy construction-densified pricing creates entry space for mid-purity specialists. Target India's dam certification corridor where BIS-qualified supplier status remains underpenetrated. Pursue joint-venture densification partnerships with ferrosilicon operators lacking compaction technology. For Investors and Strategic Acquirers: Re-rating potential sits with Nordic integrated operators given EU carbon border mechanism positioning and verified low-carbon metallurgical routes. Long-term viability hinges on Scope 3 documentation capability across cement industry customer bases. Monitor CBAM implementation timelines as inflection signal for low-carbon premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Furnace Feedstock | Captive electrode supply insulates margin from steelmaking demand cycles. |
| Densification Capacity Expansion | Pneumatic compaction scale captures ready-mix infrastructure retrofit demand in Germany. |
| BIS Certification Investment | Bureau of Indian Standards recognition unlocks qualified-supplier status for dam concrete. |
| Carbon Border Mechanism Positioning | Third-party emission audits enable EU Green Deal compliance for cement industry customers. |
| Geopolymer Binder R&D Partnership | Alkali-activated cement formulations with Swiss and Canadian universities open alternative demand. |
Study Parameters
Trade databases, ferroalloy industry associations, and construction chemical regulatory filings formed the secondary backbone of this analysis. Primary interviews with ferrosilicon plant managers, concrete admixture procurement leads, and BIS certification laboratory directors combined with bottom-up and top-down triangulation to validate volume estimates.
Bottom-up modeling of furnace recovery rates and densification throughput anchored the analytical lens, cross-checked against top-down cement consumption and pozzolan substitution elasticities. Segmentation by product form, application intensity, and end-user technical sophistication drove projection logic. CAGRs derived from elasticity modeling against infrastructure investment pipelines and emissions regulation trajectories.
Inputs from Chinese MEE emissions disclosures and EU ETS carbon cost data were available through the study window; gaps in furnace-level crystalline content testing introduce uncertainty bands around new source qualification timelines. Forecasts reflect documented assumptions on regulatory enforcement intensity and infrastructure spending continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
2-in-1 Material Rack Correction Machine Market
Industrial Materials
Powder Processing Service Market
Industrial Materials
Wedge Wire Screen Market
Industrial Materials
Polyurethane Processing Machine Market
Industrial Materials
Industrial Couplings Market
Industrial Materials
Chalk Reel and Line Chalk Market
Industrial Materials
Hardfacing Rods Market
Industrial Materials
Cryogenic Insulation Market
Industrial Materials
Steel Processing Market
Industrial Materials
Carbide Inserts Market
Industrial Materials
Plastic Recycling Machine Market
Industrial Materials
US Industrial Fasteners Market
Industrial Materials
Industrial Strainers Market
Industrial Materials
Briquetting Press Market
Industrial Materials
Europe Wood Activated Carbon Market
Industrial Materials
North America Phenolic Insulation Market