
 Smart Card Materials Market | 2026-2036
Smart Card Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Card Materials Market Intelligence
The EMVCo security certification cycle for payment chip technology is reorganizing the competitive landscape for material suppliers. Covestro leverages its polymer science expertise to offer specialized polycarbonate films that meet stringent durability requirements for payment cards. SABIC competes by providing a broad portfolio of engineering thermoplastics, including polycarbonate grades for various card layers. Thales sustains its position through integrated offerings combining secure software and card bodies, which influences material procurement choices across the value chain.
Smart card materials are specialized polymers, primarily PVC and polycarbonate, engineered for the multi-layer construction of secure microchip-enabled cards. These materials must exhibit high thermal stability and dimensional integrity to protect the embedded integrated circuit during lamination and personalization processes. PVC/Polycarbonate blends are gaining share over traditional PVC, driven by demand for more durable cards in the banking sector. In terms of functionality, dual-interface cards represent the fastest-growing segment, displacing older contact-only and magnetic stripe technologies.
Material selection is governed by international standards like ISO/IEC 10373 for card durability and environmental regulations such as the EU's REACH framework, which restricts certain chemical substances. In the United States, NIST standards for government identification cards indirectly influence material specifications for security and longevity. Suppliers now face a critical decision point on investing in bio-based and recycled polymer alternatives to meet corporate sustainability goals from financial institutions and government agencies.
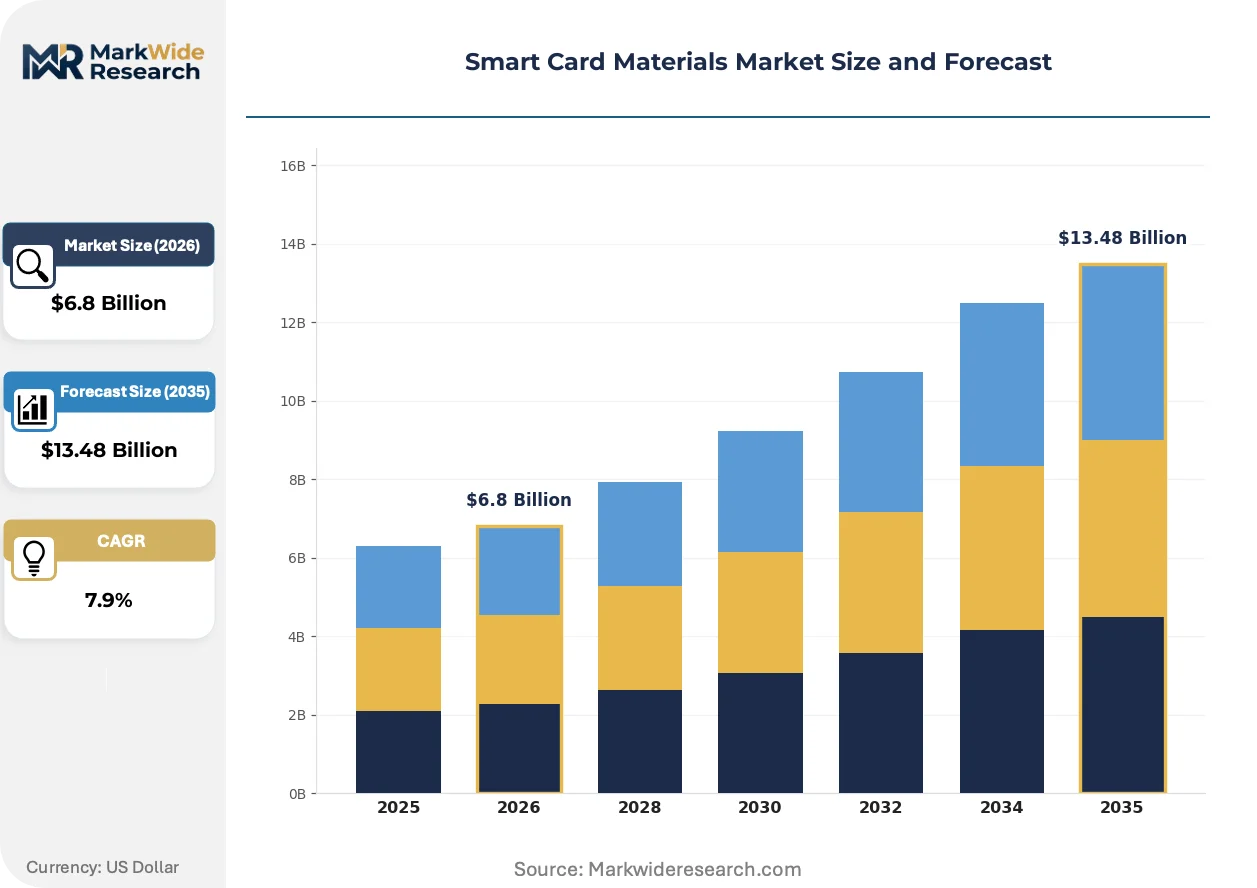
Market Dynamics
The central force shaping the smart card materials market is the technical demand for greater card body durability. This is driven by the global banking sector's transition to dual-interface payment systems, which require materials that can withstand rigorous use and protect sensitive embedded electronics.
Growth Catalysts
- Financial Inclusion Programs:Government-led initiatives in countries like India to provide citizens with secure bank accounts and digital identities are accelerating the large-scale issuance of chip-enabled cards, directly fueling material consumption.
- Dual-Interface Technology:The widespread adoption of dual-interface cards, which combine contact and contactless functionalities, necessitates advanced polymer blends that offer superior flexibility and resistance to delamination during daily use.
- Contactless Payment Infrastructure:Expansion of contactless point-of-sale terminals in retail and transit sectors globally creates a continuous replacement and new issuance cycle for payment cards, sustaining demand for core materials like PVC and polycarbonate.
Market Restraints
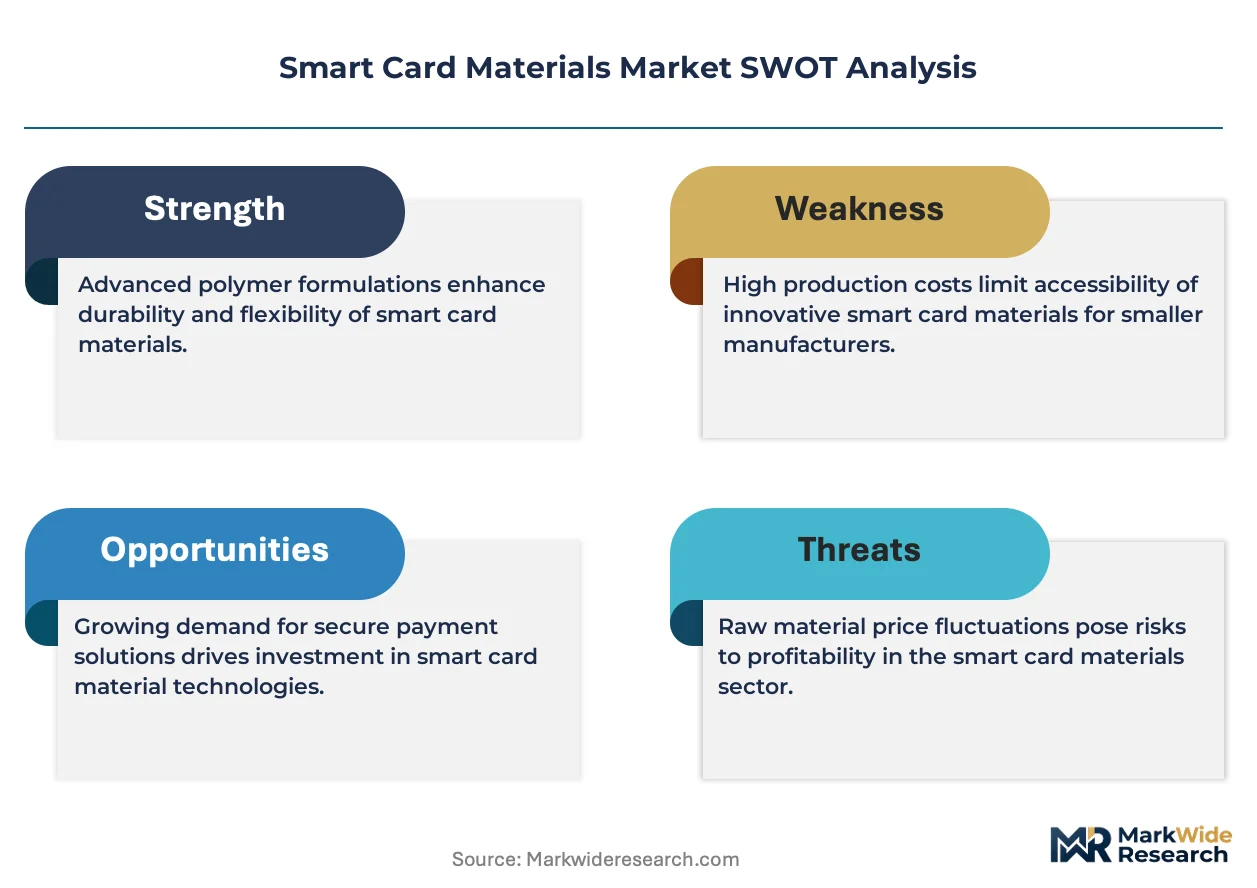
- Raw Material Price Volatility:The market is exposed to price fluctuations in petrochemical feedstocks for PVC and polycarbonate, which can compress margins for material converters and card manufacturers, creating pricing instability.
- Stringent Regulatory Compliance:Environmental regulations, particularly the EU's REACH framework, restrict the use of certain plasticizers and additives, complicating material formulation and requiring costly R&D for compliant alternatives.
- Technical Production Complexity:Manufacturing composite card bodies that maintain dimensional stability and protect the embedded chip during high-temperature lamination processes presents a significant technical barrier, limiting the number of qualified suppliers.
Strategic Opportunities
- Bio-Based and Recycled Polymers:Growing pressure from financial institutions and governments to meet sustainability targets creates a significant opportunity for suppliers to develop and commercialize card materials derived from recycled or bio-based sources.
- Healthcare and Transit Applications:Beyond banking and ID, there is an opportunity to supply specialized materials for smart cards used in secure healthcare data management and integrated public transportation systems in emerging economies.
- Advanced Security Features:The development of polymer films that incorporate unique security features, such as custom holograms or optically variable inks directly into the material layers, offers a path for value-added differentiation.
Industry Challenges
- Complex Certification Cycles:Material suppliers face long and expensive validation processes to meet security and durability standards, such as those from EMVCo, which can delay the introduction of new and innovative materials to the market.
- Supply Chain Reconfiguration:Shifting to more sustainable feedstocks like recycled polycarbonate requires significant investment in sourcing, purification, and quality control to ensure the material meets the stringent performance requirements of secure cards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Card Materials Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.48 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: PVC, PET, ABS, PVC/Polycarbonate Blend Card Functionality: Contact, Contactless, Dual Interface, Magnetic Stripe Application Area: Banking, Transportation, Access Control, Identification End User: Financial Institutions, Government Agencies, Corporations, Healthcare Providers |
| Companies Covered | Infineon Technologies, Eastman Chemical, Thales, Covestro, SABIC, IDEMIA, NXP Semiconductors, Teijin, Giesecke+Devrient, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Card Materials Market Strategic Shifts & Innovations
Material science is intersecting with security certification and sustainability mandates to redefine product development. The focus is on creating next-generation polymers that not only enhance card longevity and security but also align with the circular economy goals of major card issuers.
Advanced PVC/Polycarbonate (PVC/PC) composite films provide enhanced durability required for the construction of multi-layer smart cards. The banking and government ID sectors are rapidly adopting these materials for their superior resistance to bending, heat, and chemical exposure. This material evolution is supplanting traditional monolithic PVC substrates, which lack the structural integrity to protect the embedded electronics in modern dual-interface and biometric cards over their intended lifespan.
Sustainability-focused regulations, including the EU's Corporate Sustainability Reporting Directive (CSRD), are creating new pressures on the supply chain. This framework mandates that large companies, including major banks, report on the environmental impact of their operations and procurement. Consequently, material selection for payment and ID cards is now a factor in corporate ESG scores, compelling suppliers to accelerate the development of recycled and bio-based polymer grades.
A notable shift in purchasing behavior involves end-users prioritizing integrated, pre-certified solutions over individual components. This model disrupts the practice of sourcing card substrates separately from the chip and operating system, favoring suppliers who can provide a validated bundle. This trend is most visible in the high-security national ID and payment card segments, where assurance of interoperability and compliance with standards like ISO/IEC 10373 is critical.
Smart Card Materials Market Segmentation
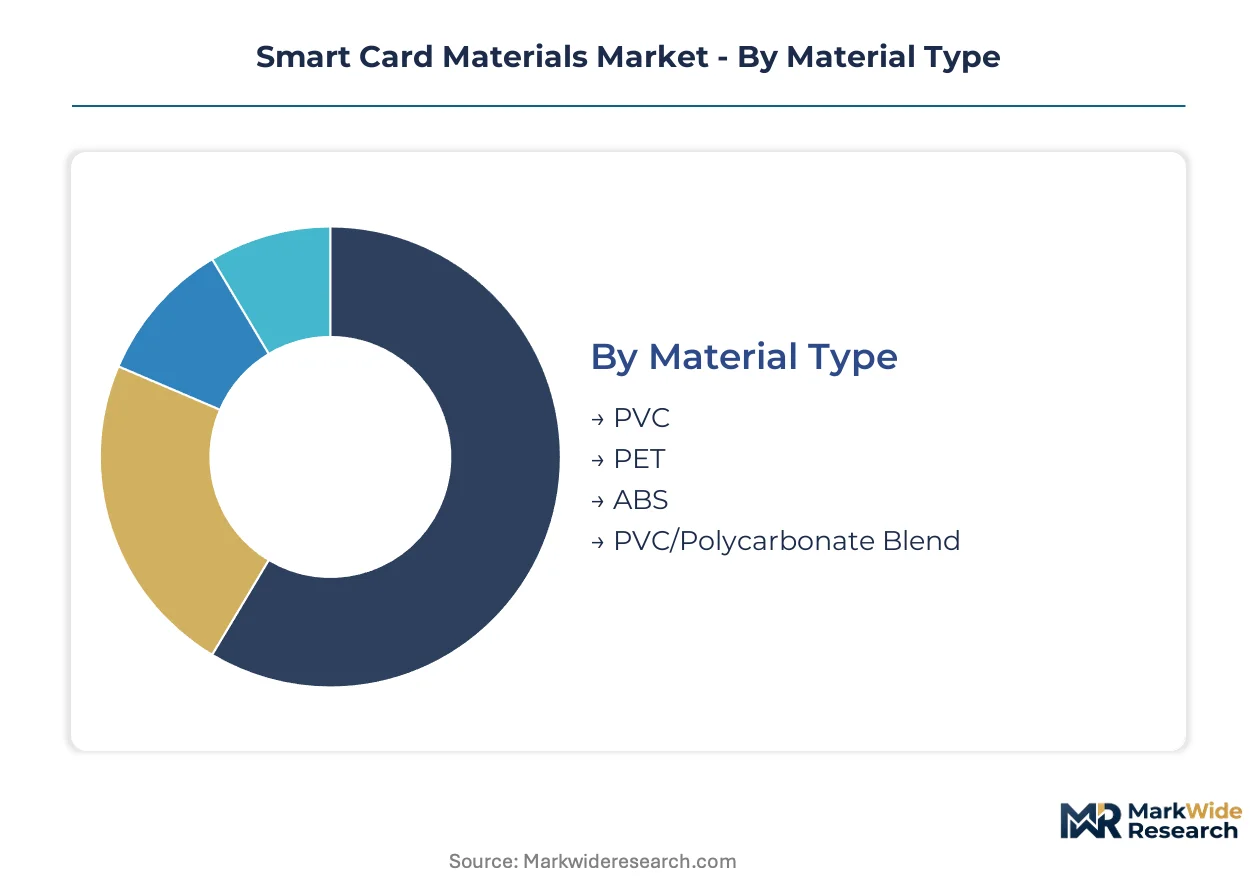
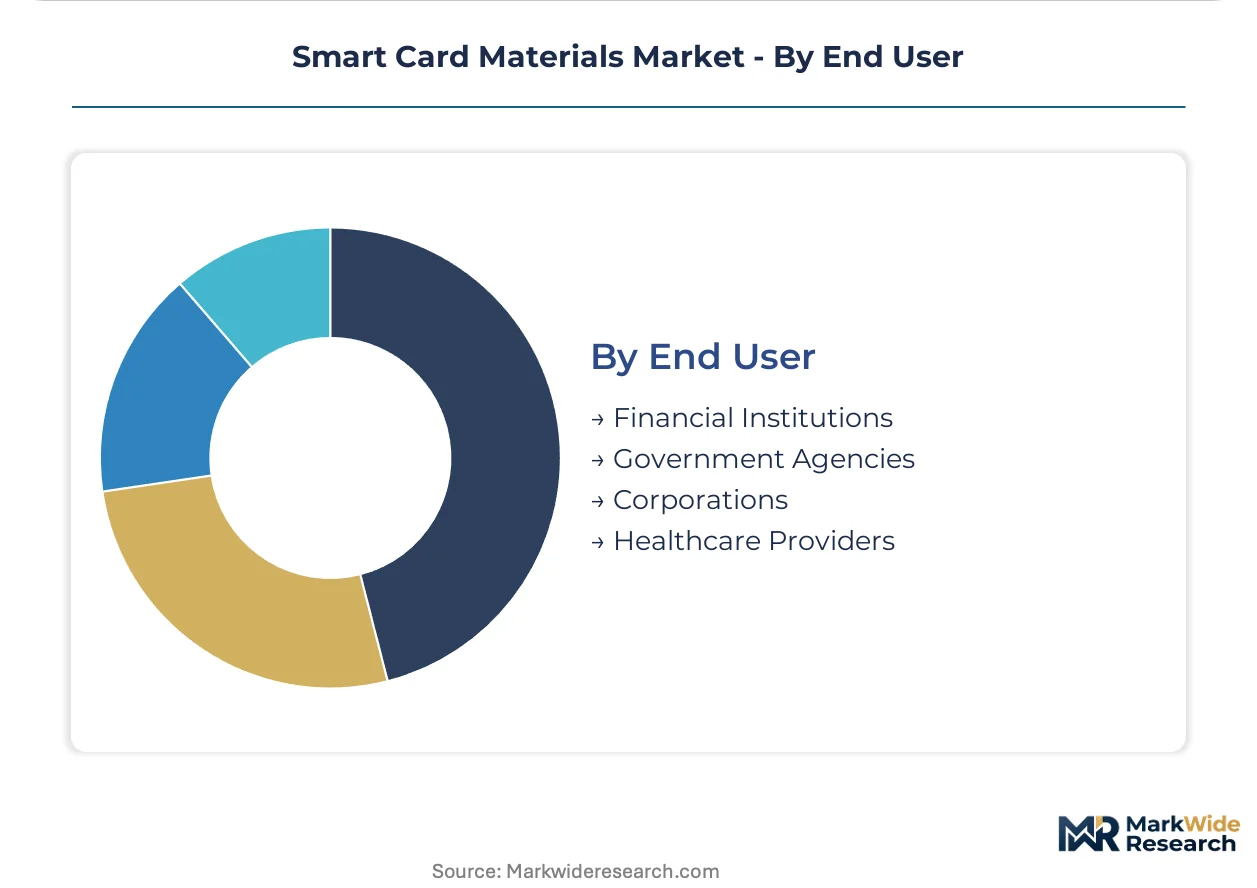
The smart card materials market is categorized by the diverse requirements of secure identification and payment systems. Segmentation highlights the specialized polymers and functional attributes necessary for card integrity and performance. This granular analysis reveals distinct demand patterns across various end-use sectors and technological evolutions.
Material Type:
Material adoption patterns often reflect regional manufacturing capabilities and specific regulatory preferences for durability.
- PVC/Polycarbonate Blend:These advanced composite films offer superior resistance to bending, heat, and chemical exposure, crucial for multi-layer smart cards. Demand concentrates in India, where government-led financial inclusion programs require robust card bodies for widespread issuance.
- PVC:Polyvinyl chloride remains a foundational material for smart card bodies due to its cost-effectiveness and ease of processing. Its use is prevalent in general-purpose identification cards and standard payment cards across diverse global markets.
- PET:Polyethylene terephthalate materials provide good thermal stability and environmental resistance for various card applications. These are often used in combination with other polymers to enhance specific card properties.
- ABS:Acrylonitrile butadiene styrene offers impact resistance and good printability, finding niche applications in specialized access control and loyalty cards.
PVC commands the established base. The steepest expansion runs through PVC/Polycarbonate Blend.
Card Functionality:
Card functionality segments the market based on the primary interaction method between the card and the reader device.
- Dual Interface:These cards combine both contact and contactless functionalities, enabling versatile payment and identification solutions. Widespread adoption in the banking sector, particularly for EMVCo-certified payment systems, drives material demand.
- Contactless:Contactless cards facilitate rapid transactions through Near Field Communication (NFC) technology, enhancing user convenience in retail and transit applications. The expansion of contactless point-of-sale terminals globally fuels this segment's growth.
- Contact:Traditional contact cards require direct physical connection to a reader for data exchange, primarily used for secure identification and older payment systems.
- Magnetic Stripe:This legacy technology stores data on a magnetic strip, still present on many cards for backward compatibility but increasingly supplanted by chip-based solutions.
This category sees Contact as foundational, while Dual Interface drives forward innovation.
Application Area:
The application area dictates specific material performance requirements, from security features to environmental resilience.
- Banking:This segment utilizes smart cards for secure payment transactions, debit, and credit card issuance, often requiring EMVCo compliance. The global transition to chip-enabled payment systems is a primary demand generator for specialized materials.
- Identification:Government-issued ID cards, national health cards, and driver's licenses fall into this category, prioritizing longevity and robust security features. India's Aadhaar program exemplifies large-scale material consumption for identification purposes.
- Transportation:Smart cards in this area facilitate ticketing, access, and payment for public transit systems, demanding durable materials for frequent use.
- Access Control:These cards manage entry to secure facilities and corporate premises, requiring materials that withstand daily wear and tear.
Growth within this segment is largely concentrated in Banking, with Identification showing significant future promise.
End User:
End-user segments reflect the diverse institutional procurement processes and scale of card issuance.
- Financial Institutions:Banks and credit unions are major consumers of smart card materials for payment card issuance, driving demand for high-security and durable polymer blends. Their sustainability goals influence material innovation.
- Government Agencies:National and local government bodies procure materials for large-scale identification, healthcare, and social welfare programs. NIST standards for government identification cards indirectly influence material specifications.
- Corporations:Businesses use smart cards for employee identification, access control, and loyalty programs, seeking cost-effective yet reliable material solutions.
- Healthcare Providers:Hospitals and clinics utilize smart cards for patient identification and secure data access, requiring materials that meet specific hygiene and data security standards.
The demand landscape is heavily influenced by Financial Institutions, with Government Agencies representing a critical growth vector.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Global digital payment infrastructure underwrites the smart card materials market, enabling secure transactions and identity verification across diverse geographies. These extensive networks drive demand for specialized polymers in chip-enabled cards. Material innovation directly supports the expansion and resilience of this critical infrastructure.
India
India's robust digital public infrastructure fuels demand for smart card materials in large-scale financial inclusion and identity programs. The Aadhaar program, managed by the UIDAI, drives the issuance of secure identification cards. Bengaluru's technology ecosystem supports the development and deployment of these advanced digital identity solutions.
United States
The United States market sees significant demand for materials in secure government identification and payment card upgrades. NIST standards for government identification cards influence material specifications for security and longevity. Silicon Valley companies drive innovation in payment card technology and secure credentialing.
Germany
Germany's advanced manufacturing sector requires high-performance smart card materials for industrial and e-government applications. The EU's REACH framework imposes stringent environmental regulations on polymer formulations. Munich's high-tech manufacturing cluster specializes in secure chip card production and material research.
China
China's vast digital economy and national identification programs drive substantial demand for smart card materials. The People's Bank of China (PBOC) promotes secure payment card technologies across the country. Shenzhen's extensive electronics manufacturing base supports high-volume production of smart cards.
Japan
Japan exhibits consistent demand for smart card materials in sophisticated public transportation and retail loyalty systems. JIS standards ensure high durability and performance for various card applications. Tokyo's financial and technology centers lead in developing next-generation payment and transit card solutions.
Smart Card Materials Market Key Industry Players
Listed leaders compete with private specialists across the smart card materials value chain, focusing on polymer science and secure card manufacturing. The market exhibits a tiered structure, with large chemical companies supplying base polymers and specialized firms integrating these into card bodies. Strategic archetypes include raw material producers, integrated card solution providers, and specialized film manufacturers. Companies often pursue portfolio diversification and strategic partnerships to enhance their market reach and technological capabilities.
Within the integrated solutions tier, Thales Group occupies a position combining secure software with card body manufacturing, influencing material procurement choices across the value chain. Covestro AG exemplifies specialized polymer science expertise, anchoring demand for advanced polycarbonate films that meet stringent durability requirements for payment cards. SABIC, a global chemical company, represents a broad portfolio provider, offering engineering thermoplastics, including diverse polycarbonate grades for various card layers and security applications.
| Leading Market Players |
|---|
| Infineon Technologies |
| Eastman Chemical |
| Thales |
| Covestro |
| SABIC |
| IDEMIA |
| NXP Semiconductors |
| Teijin |
| Giesecke+Devrient |
| Others |
Cost & Logistics Intelligence
PVC/Polycarbonate blend adoption, displacing traditional PVC, reshapes the smart card materials supply geography and pricing economics. This shift demands specialized polymer production, influencing material cost structures globally.
Pricing Analysis
Certification level, particularly EMVCo and ISO/IEC 10373 compliance, creates the primary pricing spread for smart card materials. Pricing operates on a contract-based long-term offtake model for large-volume orders, with per-unit transactional pricing for smaller, specialized batches. Material durability from PVC/Polycarbonate blends and integrated security features drive differentiation. Pricing softness stems from petrochemical feedstock volatility, while financial institutions remain highly price-sensitive for mass issuance programs.
Supply Chain Analysis
Inventory management for specialized smart card polymers involves balancing long lead times for custom formulations with just-in-time delivery for high-volume production. Geographic supply concentrates in Germany, China, and Saudi Arabia for base polymers and films. The supply chain relies on petrochemical feedstocks and embedded microchips. Commodity price volatility for these inputs presents a structural risk. Distribution runs through direct sales to card body converters and integrated solution providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart card materials market presents a service-attach opportunity, with secure software and personalization services expanding faster than physical card body hardware. Integrated offerings that combine materials with digital security layers capture higher value.
For Market Incumbents: Fortify core market positions by accelerating investment in bio-based and recycled polymer alternatives to meet corporate sustainability goals. Deepen vertical integration into secure film production to mitigate raw material price volatility and ensure supply stability. Certification investments, particularly for EMVCo standards, protect against emerging material substitutes. This defends against margin pressure from sustainability mandates and technical production complexity.
For New Entrants and Emerging Players: Specialized material development for niche applications in healthcare and transit represents a service-layer gap where incumbents under-serve. New entrants should target emerging economies, particularly India, for large-scale government ID and financial inclusion programs. Focus on advanced security features like custom holograms integrated into polymer films for differentiation. A go-to-market angle involves offering pre-certified, bundled material solutions for faster market entry.
For Investors and Strategic Acquirers: The market sits at a growth phase that favors specialized polymer science firms and integrated solution providers. Long-term viability depends on continuous innovation in durable and sustainable materials for secure identification and payment systems. Acquisition targets should include companies with strong intellectual property in bio-based or recycled polymer formulations. Watch for increasing adoption rates of sustainable materials in large tenders from financial institutions as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Increasing production of PVC/Polycarbonate blends supports dual-interface card adoption in banking. |
| Green Manufacturing Transition | Implementing sustainable production processes addresses EU's CSRD mandates for financial institutions. |
| Long-term Supply Agreement | Securing feedstock supply mitigates raw material price volatility for card body manufacturers. |
| Product Launch (Bio-based Polymers) | Introducing recycled content materials meets corporate sustainability goals of government agencies. |
| Strategic Partnership | Collaborating with secure software providers influences material procurement choices across the value chain. |
Research Approach
Desk research of EMVCo specifications, ISO/IEC standards, and national financial inclusion program reports preceded structured interviews with material R&D directors, card body manufacturers, and financial institution procurement leads. This approach combined primary insights with secondary validation. Bottom-up market sizing was triangulated against top-down revenue projections.
Variance decomposition isolated the impact of key market drivers and restraints across the analysis window. The analytical framework modeled market dynamics by material type, card functionality, application area, end user, and regional regulatory frameworks. Compound annual growth rates were derived from historical trends and projected future demand. Forecast inputs included contactless payment infrastructure expansion and government-led identity program rollouts.
Underlying assumptions cover stable geopolitical conditions and consistent regulatory enforcement, with deviation risk concentrated in raw material price volatility and evolving environmental compliance. Forecasts reflect these assumptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Materials
Global Thin Film Coatings Market
Functional Materials
Global Piezoelectric Smart Materials Market
Functional Materials
Flexible Thin Film Market
Functional Materials
Global Smart Material Market
Functional Materials
Thin-Film Encapsulation Market
Functional Materials
Energy Efficient Materials Market
Functional Materials
Thin Film Materials Market
Functional Materials
Functional Composites Market
Functional Materials
UHMWPE for Li-Battery Market
Functional Materials
Ferroelectric Materials Market
Functional Materials
Global Thin and Ultra-Thin Films Market
Functional Materials
Global Positive Material Identification Market
Functional Materials
Potassium Tetrafluoroborate Market
Functional Materials
Functional Additives and Barrier Coatings Market
Functional Materials
Korea Personal Care Encapsulation Materials Market
Functional Materials
Thermal Interface Pads and Material Market