
 Alginates and Derivatives Market | 2026-2036
Alginates and Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
Alginates and Derivatives Market Intelligence
The high capital expenditure required for seaweed harvesting and biorefinery infrastructure is narrowing the field of new market entrants. Large, established players like Cargill leverage extensive global supply chains to secure raw material access. KIMICA Corporation specializes in high-purity alginates for pharmaceutical applications, creating a defensible niche. DuPont de Nemours differentiates through its focus on specialty propylene glycol alginate formulations for the food and beverage industry.
Alginates are natural anionic polysaccharides extracted from the cell walls of brown seaweed. Their unique polymer structure, composed of mannuronic and guluronic acid blocks, dictates their gelling and viscosity properties. These biopolymers serve primarily as thickening, stabilizing, and gelling agents across various industries. Sodium alginate continues to dominate the product landscape due to its versatility, while the food and beverage additives application represents the largest and most mature end-use segment.
Market access hinges on compliance with food additive and pharmaceutical excipient standards set by bodies like the US FDA and the European Food Safety Authority (EFSA). These regulations define purity levels and acceptable daily intake, directly influencing product formulation and labeling. Navigating the complex regulatory landscape in key markets such as China, governed by the NMPA, is critical for pharmaceutical-grade sales. Future success depends on securing sustainable and traceable seaweed supply chains to meet quality and ethical sourcing demands.
Market Dynamics
The market's structure is defined by the geographic concentration of brown seaweed harvesting and the high capital investment required for biorefineries. This dynamic creates a significant barrier to entry and concentrates power among incumbents with established, large-scale supply chains capable of managing raw material variability.
Growth Catalysts
- Plant-Based Foods:The food processing sector's expansion into plant-based meat and dairy alternatives drives consumption of alginates as essential texturizing and stabilizing agents.
- Pharmaceutical Standards:Evolving pharmacopeia standards in the US and Europe for high-purity alginates in drug delivery and advanced wound care are creating new value-added segments.
- Textile Industry Demand:The textile sector in China and India utilizes sodium alginate as a superior, eco-friendly thickener for reactive dye printing, replacing traditional starch-based agents.
Market Restraints
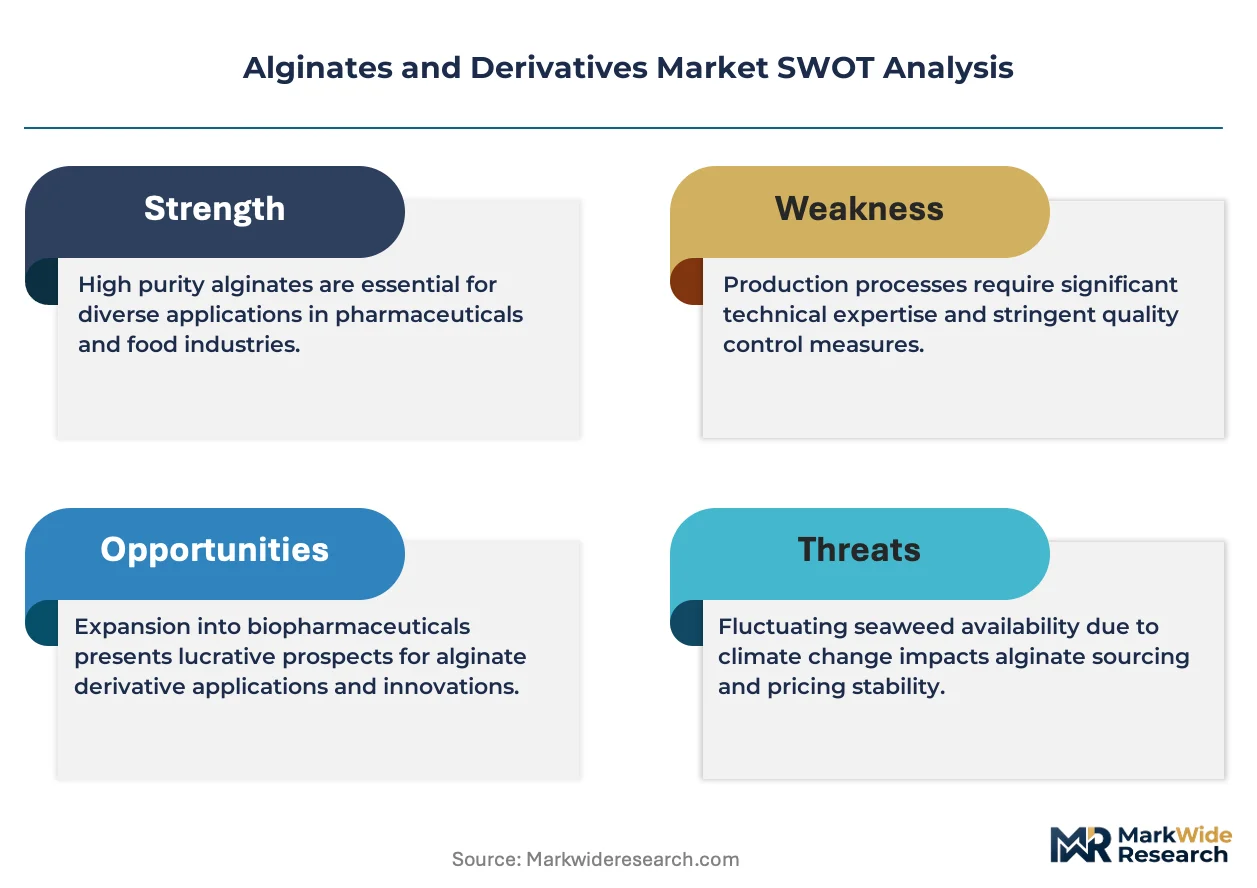
- Raw Material Volatility:Dependence on wild-harvested seaweed from specific coastal regions like Chile and China creates supply chain vulnerability to climate change and marine ecosystem disruptions.
- High Energy Costs:The extraction and purification processes for alginates are energy-intensive, making production costs highly susceptible to fluctuations in global energy prices.
- Competition from Hydrocolloids:In certain food applications, alginates face substitution threats from other hydrocolloids like xanthan gum, guar gum, and carrageenan based on price and functional performance.
Strategic Opportunities
- Biomedical Scaffolding:Advances in 3D bioprinting open opportunities for highly purified calcium alginate gels to be used as scaffolding material for tissue engineering and regenerative medicine.
- Cosmeceutical Formulations:The underpenetrated cosmeceuticals market in South Korea and Japan presents an opportunity for alginates as film-forming and moisturizing agents in high-performance skincare.
- Controlled-Release Agriculture:Development of alginate-based encapsulation for fertilizers offers a path to creating controlled-release products that improve crop yields and reduce environmental runoff.
Industry Challenges
- Inconsistent Seaweed Quality:A lack of standardized quality metrics for raw seaweed feedstock complicates processing, leading to batch-to-batch variability in final alginate viscosity and gelling strength.
- Navigating Multi-Region Food Safety:Manufacturers face operational hurdles in meeting divergent purity and testing requirements set by the US FDA, EFSA in Europe, and China's SAMR for food-grade products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alginates and Derivatives Market |
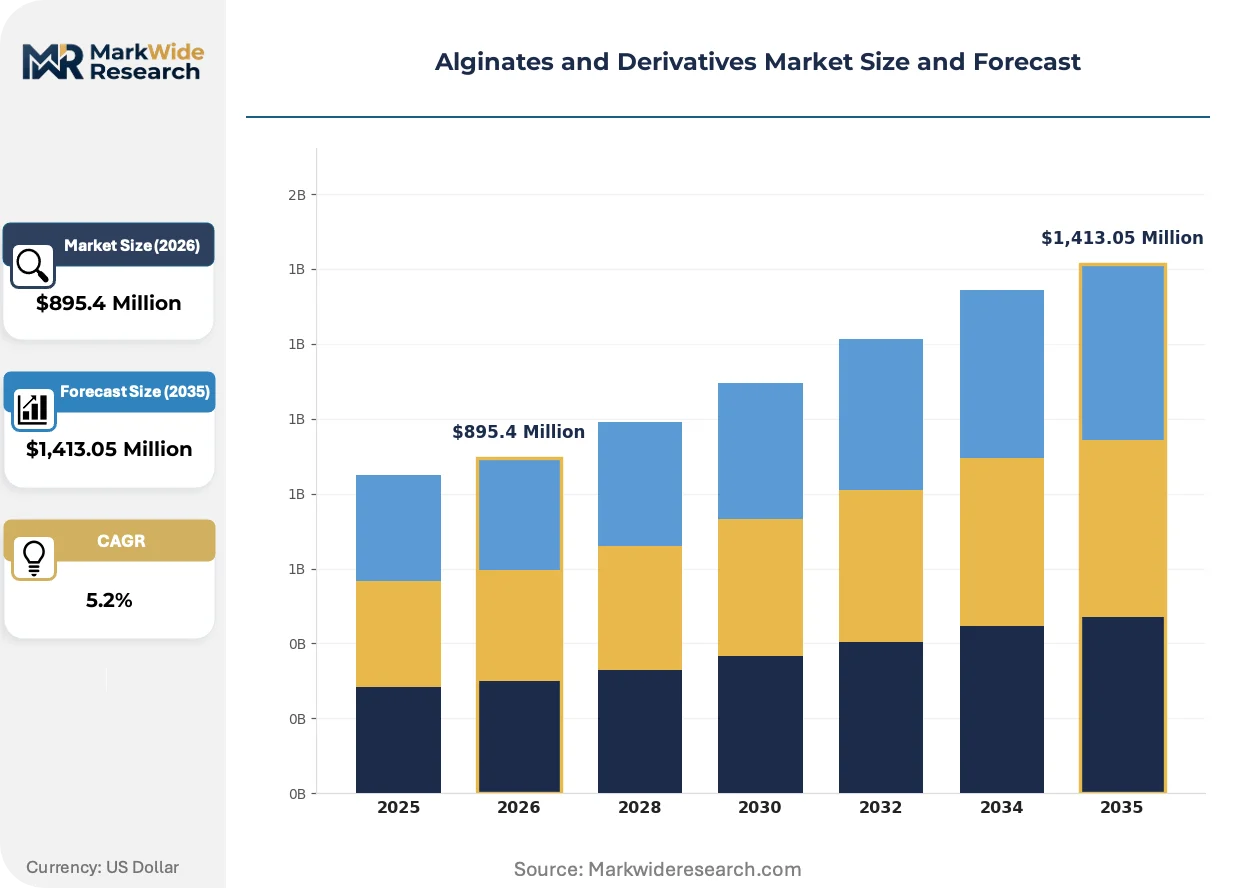
| Market Size in 2026 | $895.4 Million |
| Market Size in 2035 | $1,413.05 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Alginate, Calcium Alginate, Potassium Alginate, Ammonium Alginate, Propylene Glycol Alginate Application: Food & Beverage Additives, Pharmaceuticals, Textile Printing, Paper Coating, Cosmetic Formulations End User Industry: Food Processing Units, Pharmaceutical Manufacturers, Textile Mills, Packaging Companies, Personal Care Manufacturers Form: Powder, Granules, Fibers, Liquid, Flakes |
| Companies Covered | FMC Corporation, DuPont de Nemours, CP Kelco, Cargill, KIMICA Corporation, Algaia, SNAP Natural & Alginate Products, IRO Alginate Industry, Shandong Jiejing Group Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alginates and Derivatives Market Strategic Shifts & Innovations
Value creation in the market is shifting from commodity-grade thickeners to specialized, high-purity biopolymers. This evolution is driven by technological advancements in polymer chemistry and increasing quality demands from regulated end-use sectors like pharmaceuticals and medical devices.
Ultrapure, low-endotoxin alginates are a key technological evolution, offering precise control over gelling kinetics and biocompatibility. The pharmaceutical and biomedical research sectors are adopting these materials for cell encapsulation and advanced drug delivery. The focus of innovation is migrating from improving basic viscosity control to engineering specific polymer block structures for targeted therapeutic applications.
The European Union's push for sustainable supply chains under frameworks like the Corporate Sustainability Reporting Directive (CSRD) is impacting raw material sourcing. This regulation compels alginate producers to provide greater transparency on seaweed harvesting practices, including environmental impact. Food and beverage customers are most affected, now prioritizing suppliers who can provide verifiable documentation of sustainable sourcing to meet their own compliance obligations.
A notable shift in buyer behavior involves the unbundling of technical support from bulk material purchasing. Large food and pharmaceutical manufacturers are moving away from single-supplier contracts, instead engaging specialized formulation consultants to optimize alginate use. This trend is most visible in North American and European food innovation, where speed-to-market for new product formulations is critical.
Alginates and Derivatives Market Segmentation
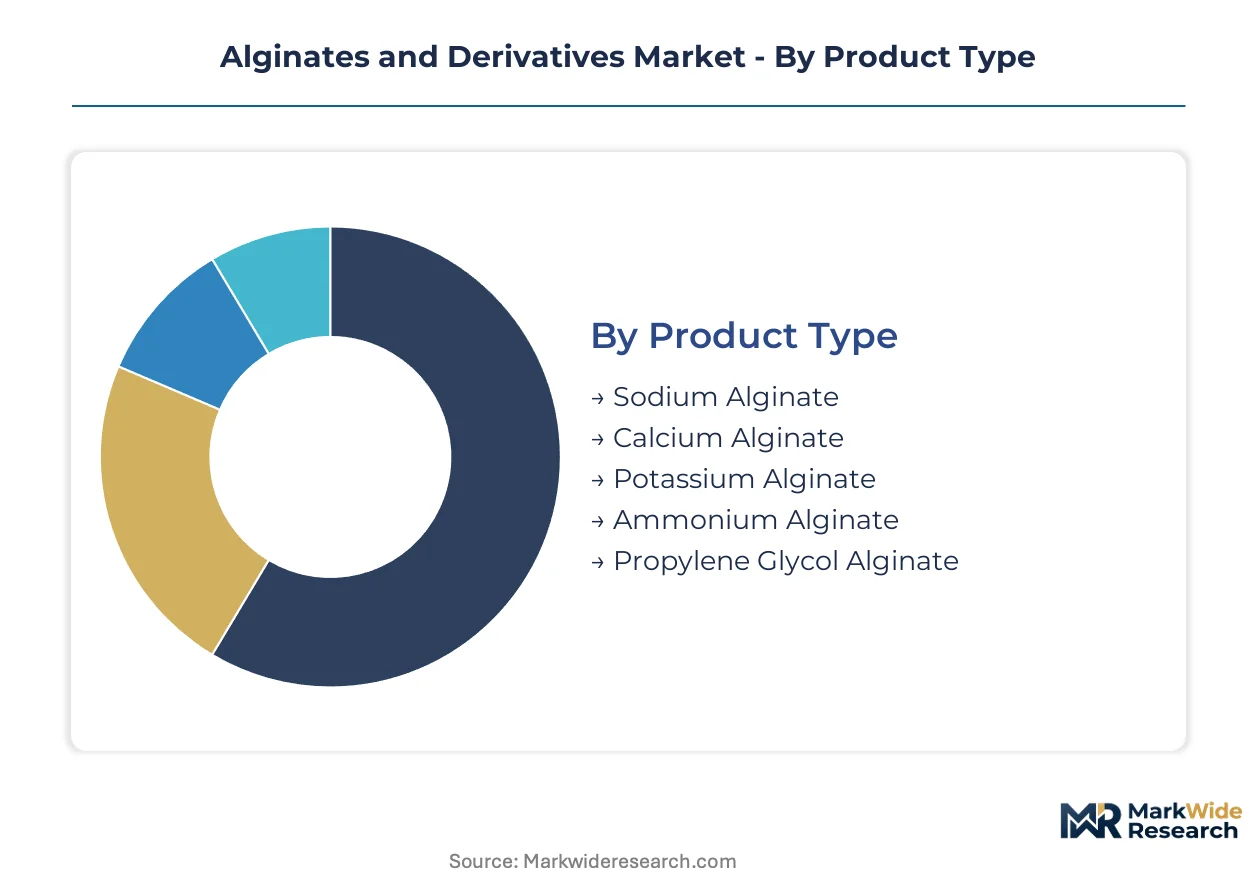
The Alginates and Derivatives market structure is defined by distinct product types, diverse applications, and varied end-user industries. Understanding these segments reveals where value creation occurs and highlights specific growth trajectories within the biopolymer landscape. This granular analysis provides clarity on functional properties and market demand.
Product Type:
Product type segmentation differentiates alginates based on their cation composition, which dictates their unique functional properties and suitability for specific industrial uses.
- Sodium Alginate:This widely utilized salt of alginic acid is highly soluble in water, forming viscous solutions and gels when calcium ions are present. Its versatility makes it a primary choice for thickening, gelling, and stabilizing across the food and beverage and textile industries.
- Calcium Alginate:Formed by the reaction of sodium alginate with calcium salts, this insoluble form is crucial for creating strong, thermally stable gels and fibers. It finds extensive use in advanced wound care dressings and biomedical applications due to its biocompatibility and hemostatic properties.
- Potassium Alginate:Often used as a gelling agent and thickener, potassium alginate offers properties similar to sodium alginate but with different ionic interactions.
- Ammonium Alginate:This variant serves as a stabilizer and thickener, particularly in applications where specific pH control or solubility profiles are required.
- Propylene Glycol Alginate:An esterified form of alginic acid, it functions as an emulsifier and stabilizer, especially effective in acidic food products and beverages.
Sodium Alginate commands the established base. The steepest expansion runs through Calcium Alginate.
Application:
Volume of consumption varies significantly across the diverse application spectrum, reflecting the different performance requirements and regulatory frameworks for alginates.
- Food & Beverage Additives:Alginates serve as essential thickeners, gelling agents, and stabilizers in a wide array of food products, including dairy alternatives, sauces, and confectionery. This segment represents the largest end-use, driven by consumer demand for plant-based and processed foods.
- Pharmaceuticals:In this high-value segment, alginates are used as excipients, drug delivery vehicles, and components in medical devices like wound dressings. The demand for high-purity, medical-grade alginates is driven by stringent regulatory standards and therapeutic innovation.
- Textile Printing:Sodium alginate acts as a superior thickener for reactive dye printing, offering sharp outlines and easy wash-off compared to traditional starches.
- Paper Coating:Alginates improve paper surface properties, enhancing printability, gloss, and ink holdout in various paper and board products.
- Cosmetic Formulations:These biopolymers function as film-forming agents, thickeners, and emulsifiers in skincare, haircare, and makeup products, providing desirable textures.
Food & Beverage Additives leads in current consumption. Pharmaceutical applications show significant future promise.
End User Industry:
Customer type influences product specifications and procurement patterns, with each industry requiring tailored alginate solutions based on their specific manufacturing processes and final product needs.
- Food Processing Units:These units utilize alginates extensively for texturizing, stabilizing, and gelling in a broad range of food and beverage products. Demand is concentrated in large-scale production of plant-based alternatives and convenience foods.
- Pharmaceutical Manufacturers:Manufacturers in this sector require high-purity, sterile alginates for drug encapsulation, tablet binding, and advanced wound care materials. Compliance with NMPA, US FDA, and EMA standards is critical for market access.
- Textile Mills:Mills primarily use sodium alginate as a printing paste thickener, valued for its environmental profile and superior print quality.
- Packaging Companies:Alginates are explored for biodegradable packaging films and coatings, offering barrier properties and sustainable alternatives.
- Personal Care Manufacturers:These companies incorporate alginates into formulations for skincare, haircare, and oral care products for their thickening and film-forming properties.
Demand concentration remains high in Food Processing Units. Pharmaceutical Manufacturers are poised for rapid uptake.
Form:
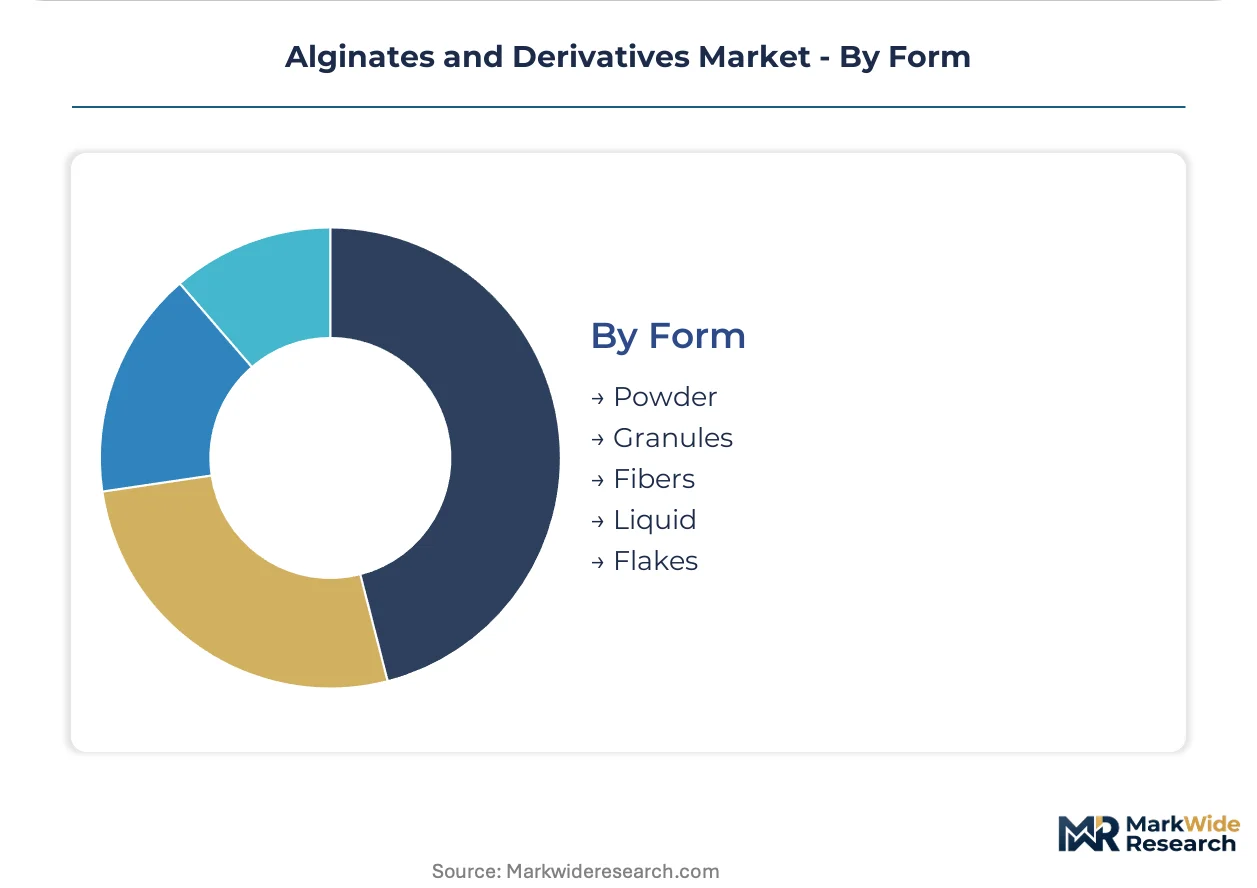
Maturity of product forms varies, with traditional powders dominating the market while specialized forms like fibers are expanding into niche, high-value applications.
- Powder:This is the most common and widely utilized form of alginate, offering significant advantages in handling, storage, and precise dosage for diverse industrial applications. Its versatility supports large-scale use across the food, pharmaceutical, and textile sectors due to ease of integration.
- Granules:Granular alginates provide improved flowability and reduced dust compared to powders, beneficial for certain manufacturing processes.
- Fibers:Calcium alginate fibers are specifically engineered for advanced wound care dressings, leveraging their high absorbency and gel-forming capabilities. This specialized form meets stringent medical device requirements.
- Liquid:Liquid alginate solutions offer convenience for direct incorporation into formulations, reducing preparation time for end-users.
- Flakes:Alginate flakes represent a less common form, often used in specific industrial processes where their physical properties are advantageous.
Powder dominates the market. Specialized fibers are carving out new spaces.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government policies promoting sustainable sourcing and advanced medical applications are increasingly shaping regional demand for alginates. These regulatory frameworks, coupled with evolving consumer preferences, drive market evolution across key economies. Focus on high-purity and traceability influences procurement decisions.
China
China's textile industry drives significant sodium alginate consumption for dye printing processes. The NMPA's stringent standards for pharmaceutical excipients also create demand for high-purity variants. Textile manufacturing hubs in Shandong and Jiangsu provinces actively integrate alginates.
United States
The United States sees strong demand for medical-grade calcium alginate in advanced wound care applications. US FDA regulations mandate high purity and biocompatibility for these pharmaceutical and medical device components. Research and manufacturing clusters in Boston and California lead biomedical innovation.
Germany
Food and beverage manufacturers in Germany utilize alginates as texturizing and stabilizing agents, particularly in plant-based products. EFSA guidelines for food additives dictate product formulation and safety profiles for market access. Food processing centers in Bavaria and North Rhine-Westphalia are key consumption areas.
Japan
Japan's cosmeceutical sector presents an opportunity for alginates as film-forming and moisturizing agents in high-performance skincare. PMDA standards for pharmaceutical ingredients also influence the demand for high-purity alginates. Innovation in Tokyo and Osaka drives new product development in personal care.
India
India's growing textile industry increasingly adopts sodium alginate for eco-friendly reactive dye printing. The FSSAI regulates food-grade alginates, impacting their use in the expanding processed food sector. Major textile production regions in Gujarat and Maharashtra represent significant consumption.
Alginates and Derivatives Market Key Industry Players
On the supply side, the industry is characterized by a tiered structure, with a few large, established players alongside specialized manufacturers. These companies compete through distinct strategic archetypes, including global raw material procurement and niche high-purity product development. Dominant competitive moves involve securing sustainable supply chains and strategic investments in advanced processing technologies.
Large, diversified corporations like FMC Corporation and DuPont de Nemours leverage extensive global supply chains and broad product portfolios. KIMICA Corporation occupies a position as a specialist, focusing on high-purity alginates for demanding pharmaceutical applications. These players exemplify the industry's balance between scale-driven efficiency and specialized value creation.
| Leading Market Players |
|---|
| FMC Corporation |
| DuPont de Nemours |
| CP Kelco |
| Cargill |
| KIMICA Corporation |
| Algaia |
| SNAP Natural & Alginate Products |
| IRO Alginate Industry |
| Shandong Jiejing Group Corporation |
| Others |
Cost & Logistics Intelligence
Geographic concentration of brown seaweed harvesting in regions like Chile and China directly shapes pricing power for established players. This upstream control over raw material access allows large incumbents to capture significant margin pools.
Pricing Analysis
Certification level, particularly for pharmaceutical and medical-grade variants, creates the primary spread in alginate pricing. Pricing stratifies across high-purity pharmaceutical grades, specialty food formulations, and commodity textile thickeners based on purity standards and functional properties. Pricing softness affects commodity-grade sodium alginate stemming from competition from other hydrocolloids like xanthan gum. Pharmaceutical manufacturers exhibit the lowest price sensitivity, prioritizing purity and efficacy, while textile mills are more price-sensitive.
Supply Chain Analysis
Export-control regimes do not directly impact alginate raw material flows, but regulatory frameworks like the EU's CSRD influence sourcing transparency. The supply chain for alginates draws primarily from wild-harvested brown seaweed in coastal regions of Chile and China. This dependence on specific marine ecosystems introduces significant supply chain vulnerability to climate change and marine disruptions. Large, established players maintain global distribution networks, often supplying bulk material directly to food processing units and pharmaceutical manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Alginates and Derivatives market presents a defensive-moat story, primarily due to significant regulatory entrenchment in pharmaceutical and food applications. High capital investment for biorefinery infrastructure also creates substantial barriers to entry.
For Market Incumbents: Fortify regulatory compliance moats through continuous investment in advanced purification technologies and certifications for pharmaceutical excipients. Secure long-term, traceable seaweed supply chains to mitigate raw material volatility and satisfy ethical sourcing demands. Expand global distribution networks to maintain market share against emerging regional players. This strategy defends against commodity price pressure and ensures access to high-value segments.
For New Entrants and Emerging Players: Build out niche capabilities in high-purity alginate derivatives for biomedical and cosmeceutical applications. Target the underpenetrated cosmeceuticals market in Japan and South Korea with film-forming and moisturizing agents. Offer specialized formulation consulting alongside material sales to differentiate from bulk suppliers. This approach bypasses the high capital expenditure required for commodity production.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized alginate manufacturers with proprietary high-purity processing technologies or strong intellectual property in biomedical applications. The long-term viability favors companies able to navigate complex regulatory landscapes and secure sustainable, traceable raw material sourcing. Monitor the successful commercialization of alginate-based 3D bioprinting scaffolds as an inflection indicator for regenerative medicine. These targets offer defensible positions and high-margin growth.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Expands production of pharmaceutical-grade alginates to meet evolving pharmacopeia standards in the US and Europe. |
| Green Manufacturing Transition | Adopts sustainable biorefinery processes, aligning with EU CSRD requirements and consumer demand for eco-friendly products. |
| Long-term Supply Agreement | Secures consistent access to quality brown seaweed feedstock, mitigating raw material volatility from climate change. |
| Product Launch | Introduces advanced low-endotoxin alginates for cell encapsulation and drug delivery, targeting biomedical research sectors. |
| Regulatory Approval Pathway | Navigates US FDA and European Medical Device Regulation to accelerate market entry for calcium alginate wound dressings. |
Research Approach
Operator-level perspectives from plant managers, R&D directors, and regulatory affairs specialists anchored the qualitative base of this analysis. Primary interviews were triangulated with extensive secondary validation from sources including US FDA filings, EFSA reports, and trade association publications. This approach integrated both bottom-up market insights and top-down industry trends.
Scenario-bracketing across optimistic and conservative outlooks informed the market projection framework throughout the analysis window. The model segmented the market by product type, application, end-user industry, form, and regional regulatory compliance. Compound Annual Growth Rates were derived from historical performance and projected growth drivers like plant-based food adoption. Seaweed harvest yields and pharmaceutical approval timelines served as key industry-specific forecast inputs.
Sensitivities concentrate around climate change impacts on seaweed supply and global energy price volatility for processing. Forecasts reflect assumptions regarding regulatory stability and competitive dynamics across key applications. Material shifts in marine ecosystem health or energy costs would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Hydrotalcite Market
Specialty Compounds
North America Customized Premixes Market
Specialty Compounds
Triallyl Isocyanurate Market
Specialty Compounds
Acetyl Tyrosine Market
Specialty Compounds
Specialty Monomer Market
Specialty Compounds
Global Antifreeze Proteins Market
Specialty Compounds
Global Compound Management Market
Specialty Compounds
Asia-Pacific Collagen Market
Specialty Compounds
Spackling Paste Market
Specialty Compounds
Kokum Butter Market
Specialty Compounds
Fluoropolymer Masterbatch Market
Specialty Compounds
Dysprosium Acetate Market
Specialty Compounds
EPDM Sealing Strip Market
Specialty Compounds
Potassium Hydrogen Sulphite Market
Specialty Compounds
Global Quaternary Ammonium Compounds Market
Specialty Compounds
Furniture Foam Market