
 Triallyl Isocyanurate Market | 2026-2036
Triallyl Isocyanurate Market Size, Share, and Industry Trends Forecast 2026-2036
Triallyl Isocyanurate Market Analytics
Specialty chemical producers in East Asia are broadening output of triallyl isocyanurate to serve radiation-curable resin formulators. Evonik Industries AG leverages its German manufacturing base to supply high-purity grades for European electronics laminators. Mitsubishi Chemical Corporation anchors its position through captive allyl chloride feedstock integration in Japan. Hunan Yixiang Chemical Industrial competes on volume cost structures for construction-sector adhesive makers.
Triallyl isocyanurate is a trifunctional allyl monomer built on an isocyanurate ring core, synthesized through allylation of cyanuric acid under phase-transfer catalysis, and functions primarily as a crosslinking co-agent for peroxide-cured elastomers and electron-beam curable coatings. The resin product type dominates current offtake from wire-cable jacket compounders seeking thermal stability. Coating applications are expanding fastest among automotive OEM clearcoat formulators migrating to solvent-free cure systems. Polymer-grade specifications command margin premiums due to stringent metal-ion limits demanded by semiconductor encapsulant buyers.
EPA regulations under TSCA Section 5 constrain new domestic manufacturing entrants without pre-manufacture notification clearance. REACH registration requirements in Europe mandate full toxicological dossiers for import volumes exceeding one tonne annually. China's MEE enforces GB standards on volatile organic compound emissions from allyl monomer production facilities. Stakeholders must monitor evolving peroxide cure system formulations in tire manufacturing, as shifts toward silica-silane coupling could alter co-agent specification requirements.
Market Dynamics
Peroxide cure system reformulation in tire manufacturing is compressing specification windows for co-agents while radiation-curable coating adoption in automotive OEMs is pulling high-purity grades into new volume tiers.
Growth Catalysts
- EPA TSCA Section 5 pre-manufacture notification:Regulatory clarity on new substance clearance is channeling investment toward established crosslinking chemistries with existing dossiers, reinforcing TAIC's position in domestic compounding.
- Silica-silane coupling migration:Tire manufacturers are rebalancing cure kinetics toward peroxide-based systems that demand trifunctional co-agents for optimal scorch safety and modulus development.
- East Asian electronics laminators:Semiconductor packaging demand for metal-ion-limited grades is creating specification premiums that justify capacity expansion in high-purity synthesis.
Market Restraints
- Allyl chloride feedstock volatility:Chlor-alkali co-product supply swings and propylene derivative pricing transmit directly into TAIC production economics, compressing margin predictability for non-integrated producers.
- REACH full toxicological dossier mandates:Registration costs for import volumes exceeding one tonne annually create fixed-cost barriers for specialty distributors serving European compounders.
- Triazine co-agent substitution:Domestic Chinese additive producers are accelerating local synthesis of alternative crosslinkers that compete on landed cost for construction-sector applications.
Strategic Opportunities
- India's specialty elastomer compounding:Underdeveloped peroxide cure penetration in domestic tire and cable production offers white-space expansion as BIS standards align with automotive export requirements.
- UV-LED curing convergence:Narrow-wavelength photoinitiator systems paired with TAIC-rich formulations are enabling energy-efficient clearcoat lines for automotive refinish operations.
- China MEE VOC emission enforcement:Stricter GB standards on allyl monomer production are accelerating consolidation toward integrated facilities with recovery systems, favoring scale players.
Industry Challenges
- Phase-transfer catalysis optimization:Yield consistency in cyanuric acid allylation requires specialized chemical engineering talent scarce outside established Japanese and German production clusters.
- Metal-ion certification timelines:Semiconductor encapsulant qualification protocols demand 18-24 month validation cycles that lock working capital and delay revenue recognition for new purity grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Triallyl Isocyanurate Market |
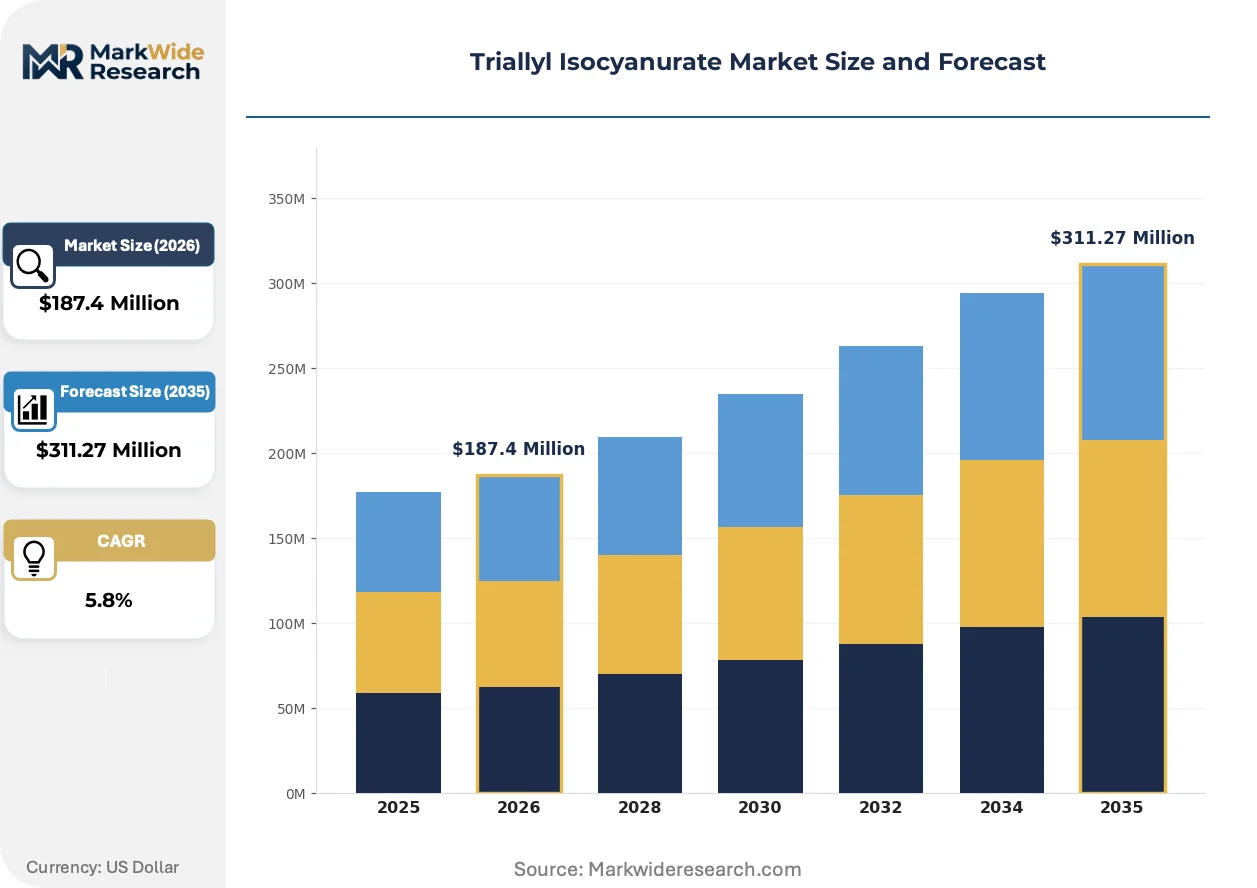
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Resin, Coating, Adhesive, Polymer Application: Construction, Automotive, Electronics, Aerospace End User: Manufacturers, Distributors, Contractors, Retailers Delivery Mode: Bulk, Drums, Containers, Pallets |
| Companies Covered | Evonik Industries AG, Allnex, Mitsubishi Chemical Corporation, ECEM European Chemical Marketing Bv, Hunan Yixiang Chemical Industrial, Liuyang Leader Materials&Technology, Beijing Credit New Material, Adeka Corporation, UBE Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Triallyl Isocyanurate Market Evolving Landscape
Electron-beam curable systems are displacing thermal cure methods in protective coatings while regulatory tightening on residual monomers is reshaping purity specifications across industrial tiers.
Hybrid peroxide-UV dual-cure formulations are converging with automotive OEM clearcoat requirements for solvent-free, high-build finishes. Tier-one formulators in Germany and Japan are piloting these systems for EV battery enclosure coatings. This convergence is compressing the addressable market for single-mechanism thermal cure products in transportation applications.
REACH registration requirements for import volumes exceeding one tonne annually are mandating full toxicological dossiers that smaller distributors cannot sustain. European electronics laminators are consolidating supplier bases toward registrant-holding manufacturers. High-purity polymer grades with existing dossiers are capturing disproportionate share in this compliance-filtered environment.
Compounders are consolidating procurement toward direct manufacturer relationships, bypassing specialty chemical distributors for TAIC volumes. Automotive wire-cable jacket producers in China and South Korea are establishing annual framework contracts with integrated allyl chloride producers. This channel compression is most visible in East Asia, where captive feedstock integration determines supplier viability.
Triallyl Isocyanurate Market Segmentation
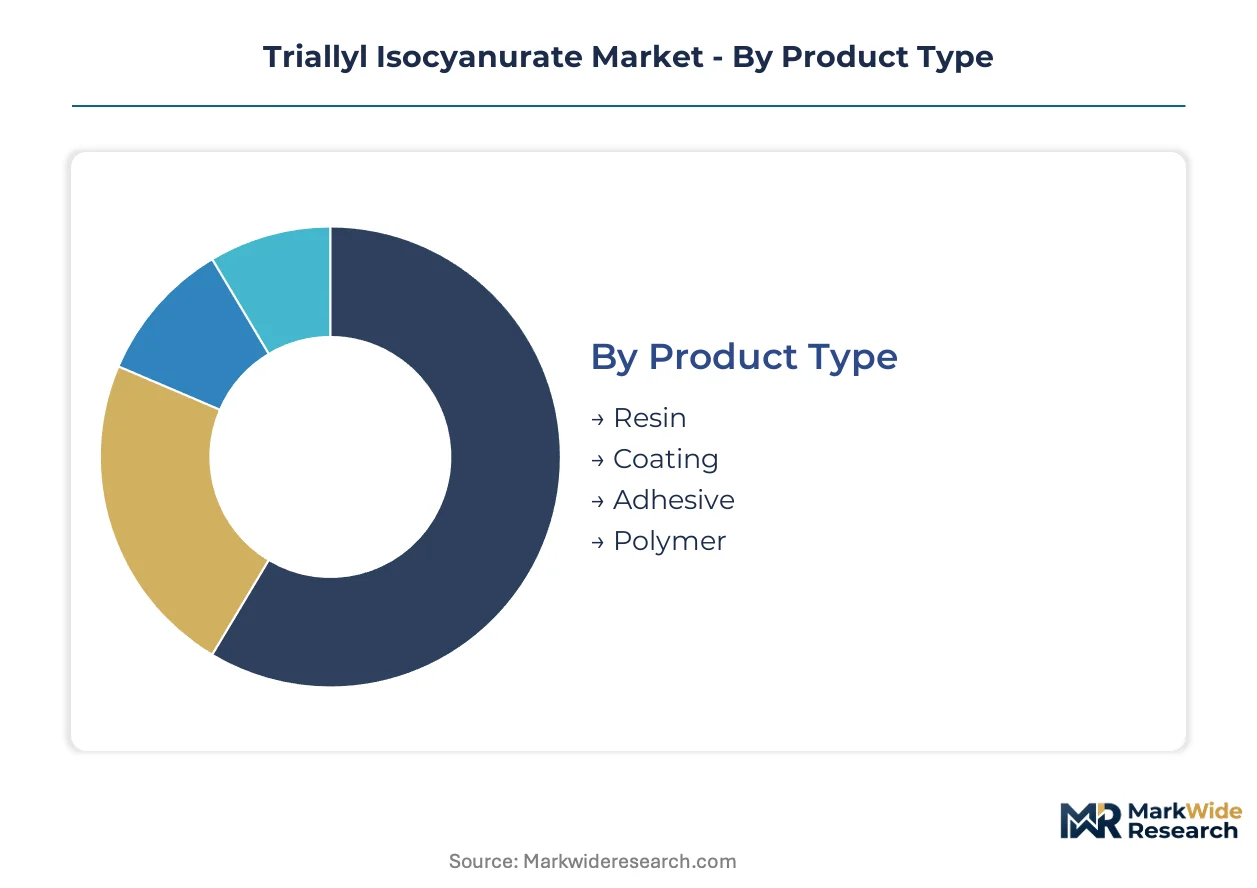
Triallyl isocyanurate's trifunctional chemistry creates divergent value pools across product types and end-use specifications. Segmentation reveals where margin concentrates versus where volume scales, guiding capacity allocation decisions for producers navigating feedstock volatility and regulatory compliance costs.
Product Type:
Integration depth varies sharply: resin and polymer grades embed directly into customer cure systems, while coating and adhesive forms demand downstream formulation partnership.
- Resin:Powder or liquid formulations containing TAIC as the primary crosslinking backbone, supplied to wire-cable jacket compounders seeking thermal stability in peroxide-cured systems. Demand concentrates in China and South Korea where automotive harness producers specify metal-ion-limited grades for EV battery enclosures.
- Polymer:High-purity specifications with stringent metal-ion limits below 10 ppm, synthesized through refined phase-transfer catalysis for semiconductor encapsulant buyers. Japanese electronics laminators in Osaka and Nagoya clusters drive specification premiums through 18-24 month qualification protocols.
- Coating:Electron-beam curable formulations for automotive OEM clearcoats migrating to solvent-free cure systems.
- Adhesive:Construction-sector applications where cost-competitive grades compete with locally synthesized triazine alternatives.
Resin leads volumes today; polymer is gaining share fastest through semiconductor packaging demand.
Application:
Cost tier stratification separates aerospace qualification premiums from construction commodity pricing.
- Electronics:Semiconductor encapsulants and printed circuit board laminates requiring ultra-low metal-ion specifications. German and Japanese laminators in Stuttgart and Tokyo-Yokohama corridors enforce the industry's most stringent purity thresholds, creating compliance-filtered supplier pools.
- Automotive:EV battery enclosure coatings and wire-cable jackets where hybrid peroxide-UV dual-cure formulations are displacing single-mechanism thermal cure. Tier-one formulators in Munich and Nagoya pilot these systems for solvent-free, high-build finishes.
- Construction:Adhesive and sealant applications where Chinese domestic producers substitute imported TAIC with locally synthesized alternatives.
- Aerospace:Specialized laminates and composites requiring extended thermal stability certification cycles.
Automotive commands the steepest expansion trajectory; electronics maintains the highest margin tier.
End User:
Procurement patterns bifurcate between direct manufacturer relationships and distributor-mediated access.
- Manufacturers:Integrated compounders and formulators establishing annual framework contracts with captive feedstock producers. Automotive wire-cable jacket producers in China and South Korea bypass distributors entirely, channeling procurement toward allyl chloride-integrated suppliers.
- Distributors:Specialty chemical intermediaries facing fixed-cost barriers from REACH registration requirements for volumes exceeding one tonne annually.
- Contractors:Construction-sector applicators sourcing through regional distribution networks.
- Retailers:Small-volume packaging for maintenance and repair operations.
Manufacturers dominate procurement value; distributors are consolidating fastest under regulatory pressure.
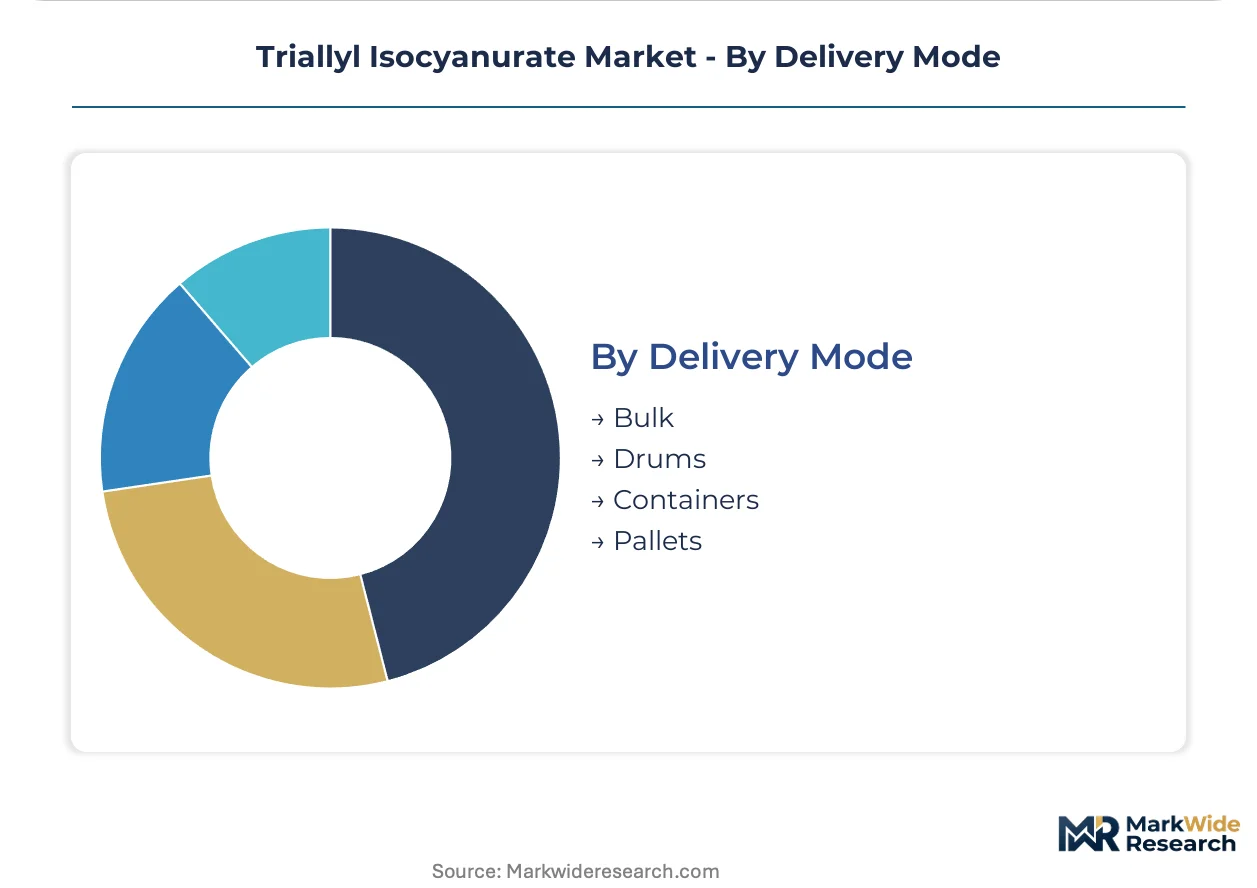
Delivery Mode:
Supply concentration shapes logistics economics, with bulk and drum formats reflecting captive feedstock integration.
- Bulk:Tanker or railcar delivery for high-volume resin and polymer offtake from integrated producers. Japanese and German manufacturing clusters with captive allyl chloride supply leverage this mode for wire-cable and electronics laminator contracts.
- Drums:Intermediate packaging for coating and adhesive formulators requiring frequent batch flexibility.
- Containers:ISO tank or flexitank options for intercontinental shipment to distributors.
- Pallets:Boxed or drum-stacked configurations for small-batch specialty orders.
Bulk leads tonnage moved; drums capture the broadest customer count.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost-of-compliance gaps between jurisdictions are redirecting triallyl isocyanurate production investment toward integrated facilities in East Asia, while European and North American markets absorb imported high-purity grades through compliance-filtered supply chains.
China
Domestic additive producers in Jiangsu and Zhejiang provinces are accelerating local synthesis of TAIC to substitute imported triazine co-agents for construction-sector adhesives. China's MEE enforces progressively stricter GB standards on volatile organic compound emissions from allyl monomer production facilities. The Yangtze River Delta chemical corridor around Shanghai hosts integrated producers with captive allyl chloride supply and solvent recovery systems that meet tightening environmental thresholds.
Germany
Electronics laminators in Stuttgart and Munich specify ultra-low metal-ion TAIC grades for semiconductor encapsulant applications, creating specification premiums that justify dedicated high-purity synthesis lines. ECHA REACH registration requirements mandate full toxicological dossiers for import volumes exceeding one tonne annually, consolidating supplier bases toward registrant-holding manufacturers. The Rhine-Main industrial cluster anchors European supply for radiation-curable coating formulators serving automotive OEMs.
Japan
Osaka and Nagoya electronics laminators drive 18-24 month qualification protocols for polymer-grade TAIC with metal-ion limits below 10 ppm, locking supplier relationships through extended validation cycles. METI oversees chemical substance management under the Act on the Evaluation of Chemical Substances, aligning with international semiconductor packaging standards. Mitsubishi Chemical Corporation's captive allyl chloride feedstock integration in the Chubu region secures supply continuity for domestic wire-cable compounders.
United States
EPA regulations under TSCA Section 5 constrain new domestic TAIC manufacturing entrants without pre-manufacture notification clearance, channeling investment toward established crosslinking chemistries with existing dossiers. Automotive wire-cable jacket producers in the Southeast and Midwest are establishing direct procurement relationships with integrated allyl chloride suppliers. The Gulf Coast petrochemical corridor provides feedstock access for specialty resin compounders serving peroxide-cure elastomer markets.
South Korea
Automotive harness producers specify metal-ion-limited TAIC grades for EV battery enclosures, pulling high-purity volumes into new specification tiers. The Korean Ministry of Environment administers K-REACH registration requirements that mirror European compliance burdens for import volumes above one tonne annually. The Ulsan-Busan industrial complex hosts formulators developing hybrid peroxide-UV dual-cure systems for solvent-free automotive clearcoats.
Triallyl Isocyanurate Market Competitive Landscape
German and Japanese producers anchor the premium-tier supply base for high-purity electronics grades; Chinese manufacturers hold volume-cost positions for construction and automotive applications. The vendor base stratifies into three functional tiers: integrated petrochemical majors with captive allyl chloride supply, specialty monomer houses focused on phase-transfer catalysis refinement, and regional compounders blending TAIC into downstream cure systems. Dominant competitive moves include backward integration into chlor-alkali co-product streams and strategic partnerships with radiation-curable coating formulators.
Among German-based chemical majors, Evonik Industries AG occupies a position exemplifying the premium-grade archetype through its manufacturing base serving European electronics laminators. Mitsubishi Chemical Corporation represents the integrated producer model with captive feedstock control in Japan. Hunan Yixiang Chemical Industrial and Liuyang Leader Materials & Technology exemplify the volume-competitive tier serving construction-sector adhesive markets in China. Adeka Corporation and UBE Industries Ltd. sit within the specialty monomer segment focused on refined synthesis protocols. Allnex and Beijing Credit New Material demonstrate the regional compounder archetype blending TAIC into downstream radiation-curable formulations.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Allnex |
| Mitsubishi Chemical Corporation |
| ECEM European Chemical Marketing Bv |
| Hunan Yixiang Chemical Industrial |
| Liuyang Leader Materials&Technology |
| Beijing Credit New Material |
| Adeka Corporation |
| UBE Industries Ltd. |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap chemical producers in Japan and Germany anchor premium-grade supply, translating captive allyl chloride control into pricing discipline that resists commodity erosion. Their concentrated ownership structures prioritize long-term customer lock-in over volume market share, compressing margin volatility for semiconductor-grade specifications while forcing cost-competitive Chinese players to absorb feedstock swings.
Pricing Analysis
Distributor margins have collapsed under REACH registration burdens, channeling automotive wire-cable procurement toward direct manufacturer contracts with 15-20 point discounts. Three-tier pricing structure across polymer-grade, resin-grade, and construction-grade specifications separates semiconductor encapsulant premiums from adhesive commodity levels. Cost compression in standard resin tiers is intensifying because domestic Chinese triazine co-agents are undercutting landed TAIC prices. Construction-sector compounders exhibit highest price sensitivity, while electronics laminators in Stuttgart and Osaka accept qualification-locked premiums.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from integrated automotive harness producers in China and South Korea, bypassing distributor inventory entirely. Supply concentrates in Japan, Germany, and China, with Japanese and German facilities drawing from captive chlor-alkali co-product streams. Raw material dependencies center on allyl chloride, cyanuric acid, and phase-transfer catalysts—inputs vulnerable to propylene derivative volatility. Single-source vulnerability from concentrated Japanese high-purity synthesis creates qualification risk for European electronics laminators. Distribution runs through annual framework contracts rather than spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA TSCA Section 5 clearance timelines and REACH dossier requirements perpetually filter supplier viability, consolidating demand toward incumbent registrants with existing toxicological portfolios.
For Market Incumbents: Deepen backward integration into chlor-alkali co-product streams to neutralize allyl chloride price volatility that erodes non-integrated competitors. Lock electronics laminators through extended 18-24 month metal-ion certification protocols that freeze out challengers. Prioritize capacity expansion in the Yangtze River Delta to capture consolidating Chinese demand under tightening MEE VOC enforcement. For New Entrants and Emerging Players: Enter via India's underpenetrated peroxide cure compounding sector, where BIS standard alignment with automotive export requirements is accelerating specification upgrades without entrenched supplier relationships. Target specialty radiation-curable coating formulators in the Ulsan-Busan corridor seeking hybrid peroxide-UV dual-cure co-agent partners. Lead with technical service partnerships rather than price undercutting. For Investors and Strategic Acquirers: Specialty resin compounders with captive allyl chloride supply are the most active acquirer in this space, seeking phase-transfer catalysis expertise to complete vertical coverage. Long-term viability hinges on semiconductor packaging demand durability and automotive EV battery enclosure coating migration. Watch for silica-silane coupling system reformulation in tire manufacturing as a demand inflection signal that could compress or expand co-agent specification windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Allyl Chloride | Mitsubishi Chemical's captive Chubu feedstock secures margin predictability against propylene derivative swings. |
| High-Purity Polymer Grade Expansion | Evonik's German synthesis lines capture specification premiums from Stuttgart semiconductor encapsulant laminators. |
| Direct OEM Framework Contracts | Chinese automotive harness producers in Jiangsu bypass distributors entirely under REACH cost pressure. |
| Hybrid Cure Formulation Partnerships | Ulsan-Busan formulators pilot peroxide-UV dual systems for solvent-free automotive clearcoats. |
| MEE VOC Compliance Investment | Yangtze River Delta integrated facilities with solvent recovery consolidate share under tightening GB standards. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured discussions with plant managers at Japanese and German TAIC synthesis facilities, procurement leads at Chinese automotive wire-cable OEMs, distribution channel partners facing REACH registration barriers, and technical R&D directors at radiation-curable coating formulators. Secondary validation drew from customs and trade flow databases, Cefic chemical industry reports, SEC 10-K filings from listed chemical majors, and EPA TSCA pre-manufacture notification records. Bottom-up volume modeling and top-down value triangulation cross-checked segment estimates.
Historical reference periods anchored the projection horizon to documented capacity expansions, qualification cycle completions, and regulatory milestone implementations across the analysis window. Segmentation dimensions modeled include product grade tier, end-use industry, delivery mode format, and regional production hub concentration. CAGRs were derived from slope analysis of normalized demand curves adjusted for feedstock cost pass-through elasticity and regulatory compliance cost trajectories. Industry-specific forecast inputs incorporated peroxide cure system penetration rates in tire manufacturing and electron-beam coating adoption curves in automotive OEM specifications.
Inputs from primary interviews and customs databases were available through the study window; gaps in real-time inventory positioning data and confidential contract pricing introduce uncertainty bands around quarterly volume estimates. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and feedstock supply continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Global Specialty Zeolites Market
Specialty Compounds
Organoclay Market
Specialty Compounds
Global Specialty Oilfield Chemicals Market
Specialty Compounds
Additive Masterbatch Market
Specialty Compounds
Alginates and Derivatives Market
Specialty Compounds
United States Hydroxypropyl Methylcellulose (HPMC) Market
Specialty Compounds
3-Hydroxyphenyl Phosphinyl Propanoic Acid Market
Specialty Compounds
Dip Molding and Coating Market
Specialty Compounds
Silk Protein Market
Specialty Compounds
Strontium Nitrate Market
Specialty Compounds
Hypalon Market
Specialty Compounds
Polypeptide Market
Specialty Compounds
Compounds Market
Specialty Compounds
US Non-Commercial Acrylic Paints Market
Specialty Compounds
Saudi Arabia Masterbatch Market
Specialty Compounds
United States Caustic Potash Market