
 North America Customized Premixes Market | 2026-2036
North America Customized Premixes Market Size, Share, and Industry Trends Forecast 2026-2036
North America Customized Premixes Market Analytics
Direct sales channels serving large-scale food manufacturers is tilting toward technical partnership models rather than transactional supply. DSM Nutritional Products leverages its vitamin and lipid premix portfolio to anchor long-term contracts with fortified dairy processors across the Upper Midwest. Cargill Incorporated competes through backward integration into raw vitamin sourcing, sustaining margin control amid ingredient volatility. Glanbia Nutritionals differentiates via its specialized sports nutrition premix expertise, occupying a defensible niche in protein fortification.
Customized premixes constitute precision-blended nutrient, mineral, vitamin, or functional additive formulations manufactured to client-specific dosing, solubility, and stability parameters for integration into finished consumer products. These blends typically achieve homogeneity coefficients above 95% through ribbon or tumble mixing processes, ensuring consistent bioactive distribution in low-inclusion-rate applications. Dry premixes dominate volume throughput due to extended shelf stability and lower transport costs, while liquid premixes capture expanding share in ready-to-drink beverage applications where rapid dispersion is critical. Functional premixes command premium positioning as probiotic, omega-3, and plant-protein combinations attract reformulation investment from health-positioned brands.
The FDA's food additive regulations and the USDA's organic certification standards govern ingredient permissibility and label claims across U.S. premix applications, while Health Canada's Natural Health Products Directorate shapes parallel requirements for Canadian market access. The FDA's evolving position on novel dietary ingredients creates compliance complexity that favors premix suppliers with established GRAS dossiers and regulatory navigation capabilities. Stakeholders must monitor emerging state-level clean-label mandates and track how the U.S. EPA's bioaccumulation assessments may restrict certain fat-soluble vitamin carriers.
Market Dynamics
Clean-label reformulation mandates from the FDA and USDA are compressing formulation timelines, forcing premix suppliers to rebuild stability matrices around natural carriers while maintaining bioactive potency across extended shelf-life requirements.
Growth Catalysts
- Fortification Mandates:The FDA's updated food additive regulations expand permissible vitamin D and folate dosing in dairy and grain applications, opening new formulation contracts for premix suppliers serving Midwestern processing corridors.
- Sports Nutrition:Protein fortification demand from functional beverage manufacturers in California's functional food cluster is accelerating adoption of specialized amino acid premixes with enhanced dispersibility profiles.
- Probiotic Integration:Microencapsulation advances enable stable co-delivery of probiotics with fat-soluble vitamins, rendering previously incompatible functional combinations commercially viable for ready-to-drink applications.
Market Restraints
- Input Cost Volatility:Vitamin A and E acetate prices fluctuate with palm oil derivative markets, compressing margin predictability for premix suppliers lacking backward integration into raw vitamin sourcing.
- Supply Concentration:China dominates crystalline vitamin B12 and D3 production, creating single-source dependency risks that compound during shipping disruptions across Pacific corridors.
- Regulatory Friction:Health Canada's Natural Health Products Directorate imposes distinct stability testing requirements that extend Canadian market entry timelines by 8-14 months versus U.S. equivalents.
Strategic Opportunities
- Underpenetrated Applications:Pet nutrition manufacturers across the U.S. Southeast represent untapped demand for species-specific premix formulations addressing coat health and digestive function.
- Regulatory Tailwind:The USDA's expanded organic certification standards for processed foods create premium positioning for premix suppliers with verified non-GMO carrier systems and synthetic-free preservative matrices.
- Technology Convergence:AI-driven formulation software combined with high-throughput stability screening is compressing development cycles from 18 months to 6 months for custom premix projects.
Industry Challenges
- Technical Talent Scarcity:Formulation chemists with dual expertise in food science and regulatory navigation command premium compensation, constraining mid-tier premix suppliers' R&D expansion capacity.
- Legacy System Integration:ERP compatibility gaps between premix suppliers' batch tracking systems and large food manufacturers' traceability platforms create data reconciliation friction during audits.
- Certification Timeline Compression:GRAS self-affirmation dossiers for novel carrier technologies face heightened FDA scrutiny, extending documentation preparation from 90 days to 8 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Customized Premixes Market |
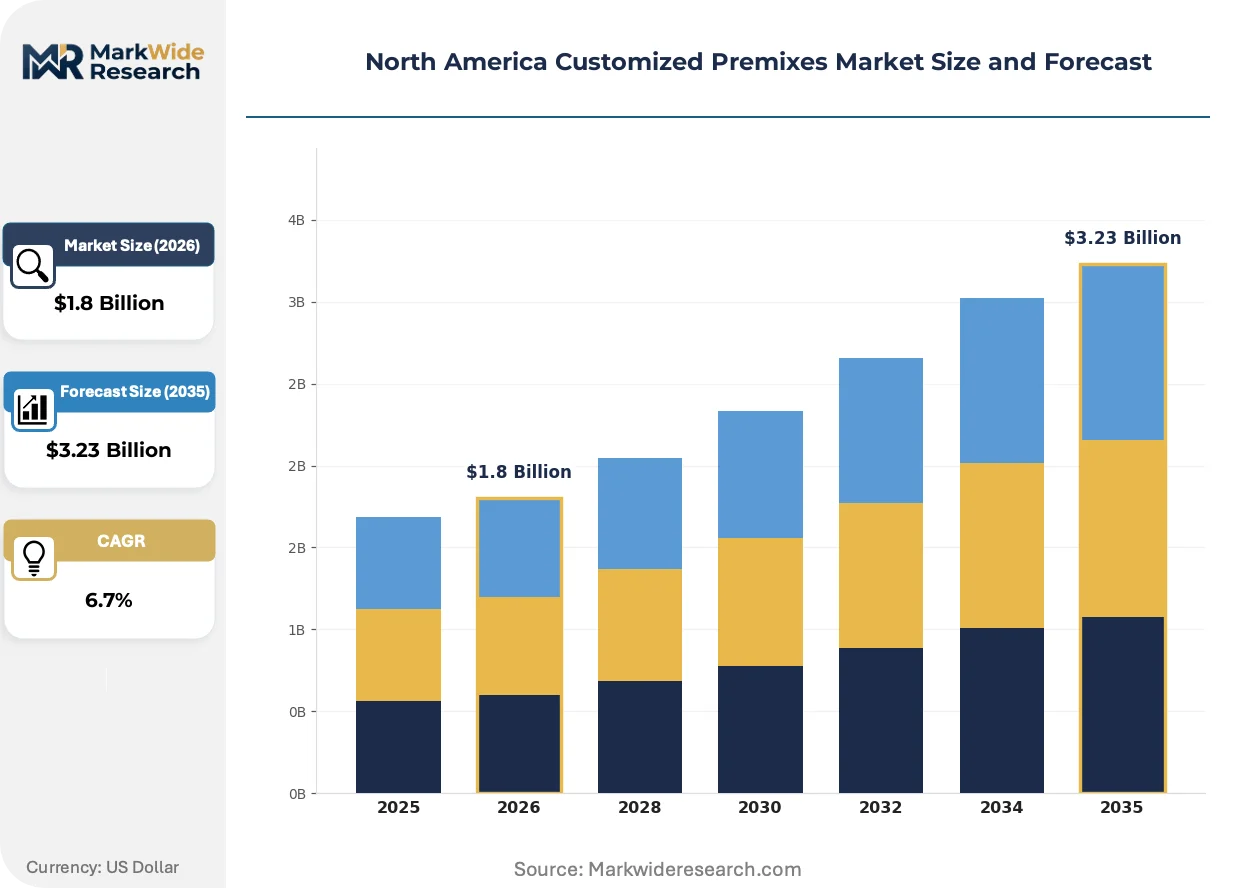
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Premixes, Liquid Premixes, Functional Premixes, Organic Premixes End User: Food Manufacturers, Beverage Producers, Dietary Supplements, Confectionery Application: Baked Goods, Dairy Products, Nutritional Foods, Sauces Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesale |
| Companies Covered | DSM Nutritional Products, Glanbia Nutritionals, Cargill Incorporated, Archer Daniels Midland, Prinova Group LLC, SternVitamin GmbH & Co. KG, Koninklijke DSM N.V., Corbion N.V., Watson Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Customized Premixes Market Evolving Landscape
Precision blending technologies and regulatory data transparency requirements are converging to reshape how premix suppliers demonstrate batch consistency and bioactive stability to large food manufacturers.
High-shear microencapsulation systems using modified starch and gum arabic carriers are rendering obsolete traditional spray-dried vitamin matrices that suffered from oxidative degradation during extended storage. Ready-to-drink beverage manufacturers in Texas and Florida are adopting these systems at accelerated pace. The technology is rendering obsolete shelf-life limitations that previously constrained premix inclusion in ambient-stable liquid products.
The FDA's evolving enforcement posture on New Dietary Ingredient notifications is tightening evidentiary standards for probiotic strain identity and colony-forming unit stability claims. Premix suppliers must now maintain whole-genome sequencing documentation and accelerated aging studies for each probiotic-inclusive formulation. Dietary supplement contract manufacturers in Utah and Arizona are most affected, responding by consolidating supplier relationships to those with established GRAS dossiers.
Large-scale food manufacturers are unbundling technical service contracts from raw material supply agreements, creating discrete purchasing categories for formulation consulting versus physical premix delivery. This procurement model change disrupts traditional full-service premix suppliers who bundled both capabilities. The shift is most visible among CPG conglomerates operating across the U.S. Midwest, where technical partnership RFPs now precede supply contract negotiations by 12-18 months.
North America Customized Premixes Market Segmentation
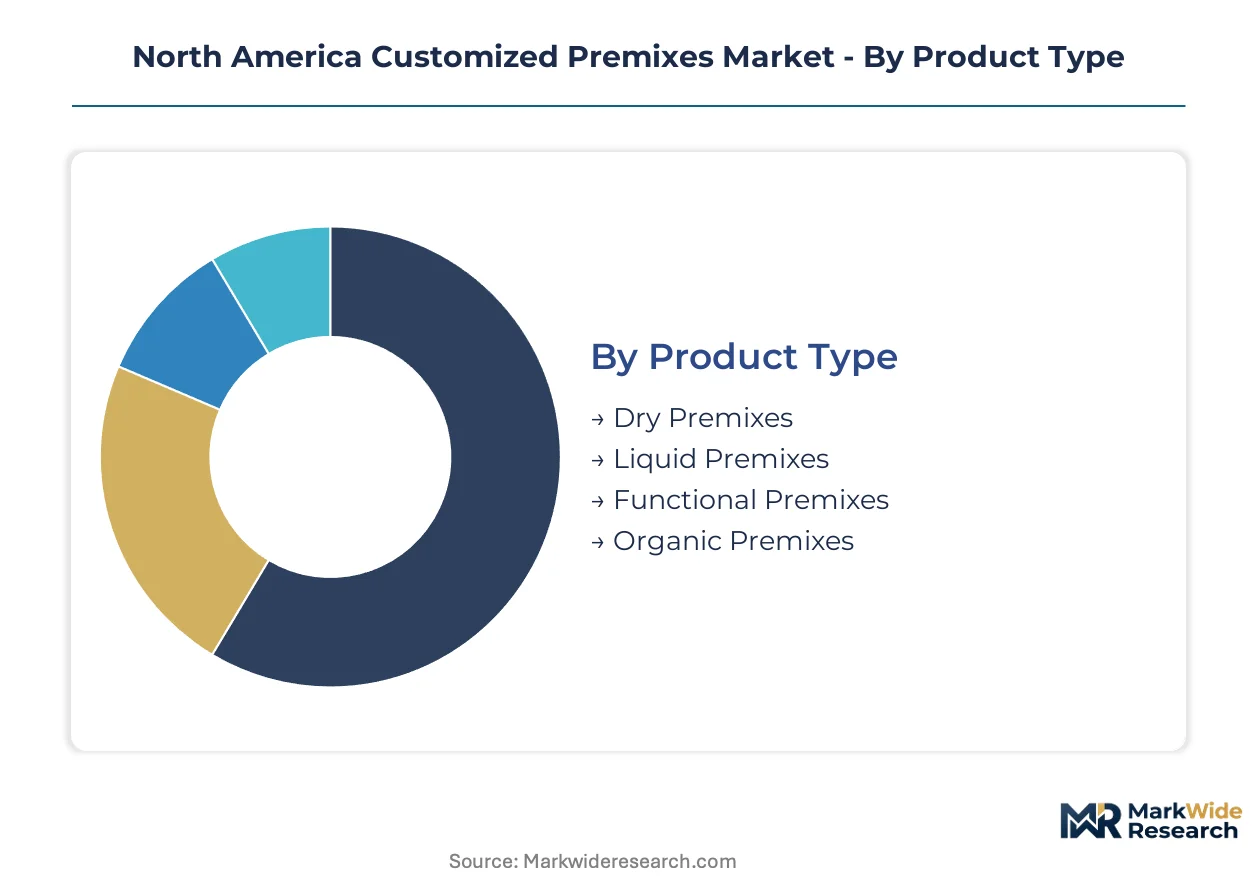
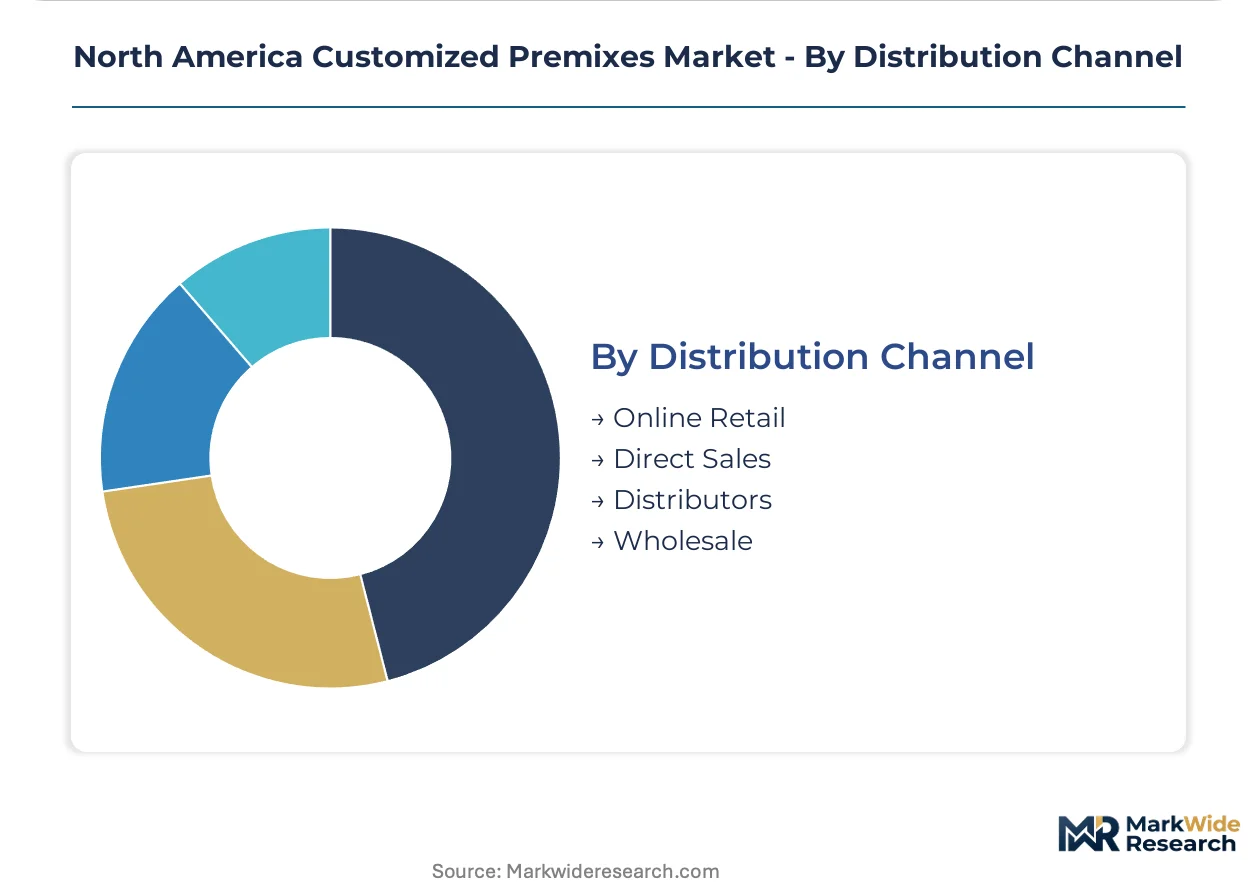
Segmentation reveals how formulation complexity, regulatory positioning, and supply chain configuration fragment demand across distinct technical and commercial profiles. Each dimension shapes procurement priorities, margin structures, and supplier qualification requirements differently across the North American market.
Product Type:
Dry, liquid, functional, and organic variants span powder handling requirements through clean-label certification tiers.
- Dry Premixes:Powder-based formulations achieve homogeneity coefficients above 95% through ribbon or tumble mixing, delivering extended shelf stability and lower transport costs. Midwestern dairy processors and grain millers in Minnesota and Wisconsin concentrate procurement here, driven by ambient storage infrastructure and bulk handling economies.
- Liquid Premixes:Suspension or solution formats enable rapid dispersion in ready-to-drink applications where powder dissolution kinetics constrain formulation. Beverage manufacturers in California's functional food cluster and Texas bottling corridors are expanding adoption, compelled by clean-label mandates that eliminate anti-caking agents required in dry formats.
- Functional Premixes:Probiotic, omega-3, and plant-protein combinations command premium positioning through microencapsulation advances that stabilize previously incompatible bioactives.
- Organic Premixes:USDA-certified organic variants utilize non-GMO carriers and synthetic-free preservative matrices for processed food label claims.
Established volume favors dry premixes; emerging adoption favors liquid premixes.
End User:
Customer archetypes diverge sharply between formulation sophistication requirements and regulatory navigation burden.
- Food Manufacturers:Large-scale CPG conglomerates across the U.S. Midwest unbundle technical service contracts from supply agreements, creating discrete purchasing categories that favor premix suppliers with AI-driven formulation platforms and established GRAS dossiers.
- Beverage Producers:Ready-to-drink and functional beverage specialists in Florida and Arizona demand rapid-dispersibility profiles and ambient stability matrices, compressing development cycles through high-throughput stability screening partnerships.
- Dietary Supplements:Utah and Arizona contract manufacturers face heightened FDA scrutiny on New Dietary Ingredient notifications, consolidating supplier relationships to those with whole-genome sequencing documentation and accelerated aging studies.
- Confectionery:Sugar and chocolate processors prioritize heat-stable vitamin matrices and masking technologies for mineral off-notes in high-temperature processing environments.
Food manufacturers anchor procurement volume; dietary supplements suppliers are climbing the fastest on regulatory complexity premiums.
Application:
Processing conditions and finished-product positioning dictate stability matrix specifications across thermal, acidic, and shear stress environments.
- Baked Goods:Heat-stable folate and B-vitamin formulations withstand proofing and baking temperatures without degradation. Southeastern U.S. commercial bakeries drive demand amid FDA-expanded fortification permissions for grain applications.
- Dairy Products:Fluid milk, yogurt, and cheese applications leverage vitamin D and calcium premixes with enhanced dispersibility in high-moisture matrices. Upper Midwest processing corridors concentrate procurement, shaped by updated FDA dosing guidelines.
- Nutritional Foods:Meal replacement and medical nutrition formats require precise macronutrient-micro-nutrient ratios with documented bioaccessibility.
- Sauces:Acidic and high-shear processing environments demand encapsulated mineral systems to prevent precipitation and metallic off-flavors.
Dairy products dominate current formulation contracts; nutritional foods show steepest expansion trajectory on personalized nutrition investment.
Distribution Channel:
Channel selection reflects order scale, technical service intensity, and traceability platform integration requirements.
- Direct Sales:Technical partnership models predominate for large-scale manufacturers, with 12-18 month RFP-to-contract cycles emphasizing formulation consulting capabilities ahead of physical supply. DSM Nutritional Products and Cargill Incorporated anchor this channel through backward integration and long-term stability data libraries.
- Distributors:Regional chemical and ingredient distributors serve mid-tier food processors lacking dedicated procurement teams, consolidating multiple premix categories with shared warehousing.
- Online Retail:E-procurement platforms capture small-batch and specialty formulation demand from emerging brands and contract research organizations.
- Wholesale:Volume-based pricing tiers serve commodity dairy and grain processors with standardized vitamin-mineral blends and minimal customization.
Direct sales command margin premiums; distributor networks are expanding most quickly on mid-tier manufacturer consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach and the Interstate 5 corridor anchor North American premix distribution, channeling Asian-sourced vitamins into California's functional food cluster while Midwestern rail networks feed dairy processing corridors across the Upper Midwest.
United States
California's functional food cluster drives demand for rapid-dispersibility liquid premixes in ready-to-drink applications. The FDA's updated food additive regulations expand vitamin D and folate dosing permissions in dairy and grain applications. Midwestern processing corridors in Minnesota and Wisconsin concentrate procurement of dry premixes for ambient storage economies.
Canada
Health Canada's Natural Health Products Directorate imposes distinct stability testing requirements that extend market entry timelines. The Prairie Provinces anchor canola-based omega-3 premix sourcing for functional food applications. Toronto and Vancouver serve as formulation consulting hubs for cross-border technical service contracts.
Mexico
The Bajío Region's dairy processing expansion creates demand for vitamin D fortification premixes in fluid milk applications. Mexico's national food safety regulator COFEPRIS aligns fortification standards with FDA guidelines to facilitate U.S. export compatibility. Monterrey and Guadalajara industrial corridors concentrate procurement for processed food manufacturing.
North America Customized Premixes Market Competitive Landscape
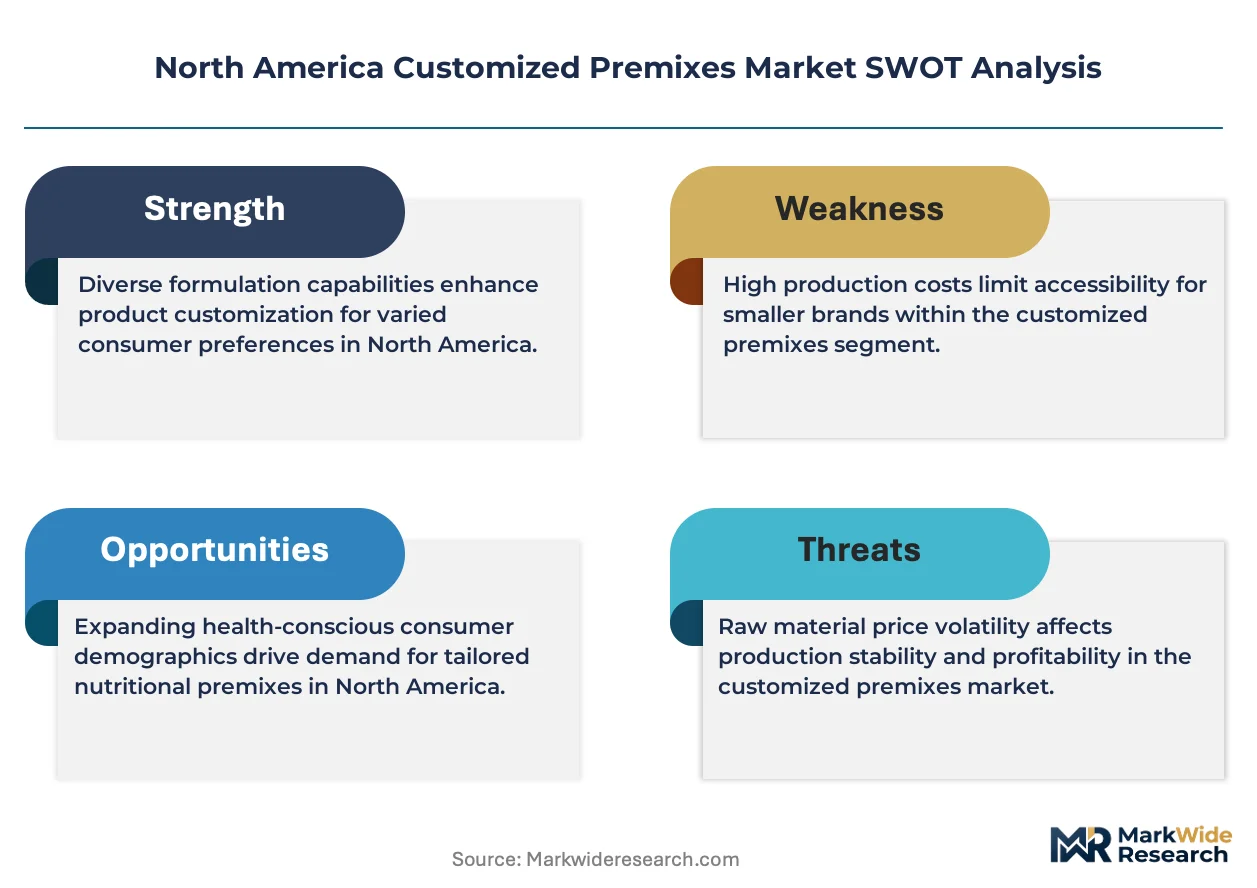
Platform integrators command the system tier; component specialists sit upstream. The North American customized premixes market structures around three tiers: multinational nutrition platforms with backward integration, mid-tier regional blenders with formulation expertise, and specialty microencapsulation technology providers. Competitive moves concentrate on long-term technical partnership contracts and AI-driven formulation platform deployment rather than capacity expansion.
Among multinational nutrition platforms, DSM Nutritional Products, Cargill Incorporated, and Glanbia Nutritionals exemplify distinct archetype positioning. DSM Nutritional Products represents the integrated platform model with vitamin and lipid premix portfolios anchoring long-term stability data libraries. Cargill Incorporated exemplifies backward integration strategy through captive raw vitamin sourcing. Glanbia Nutritionals occupies the specialized sports nutrition niche with protein fortification expertise. These three entities collectively illustrate how scale, integration depth, and application focus fragment competitive positioning across the premix value chain.
| Leading Market Players |
|---|
| DSM Nutritional Products |
| Glanbia Nutritionals |
| Cargill Incorporated |
| Archer Daniels Midland |
| Prinova Group LLC |
| SternVitamin GmbH & Co. KG |
| Koninklijke DSM N.V. |
| Corbion N.V. |
| Watson Inc. |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese crystalline vitamin B12 and D3 production facilities is compressing global spot prices while simultaneously amplifying margin volatility for North American premix suppliers lacking captive raw material sourcing. This utilization dynamic forces Midwestern dairy processors toward long-term contract structures that trade price premiums for supply security, while smaller beverage manufacturers absorb spot market exposure to preserve formulation flexibility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates functional microencapsulated premixes from conventional vitamin-mineral blends and commodity fortification bases. Premium tiers command spreads based on GRAS dossier depth and stability data libraries, while economy segments compete on bulk volume throughput to grain millers. Price differentiation hinges on certification grade—USDA organic and non-GMO Project Verified carriers extract 15-25% premiums—and customization level for proprietary bioactive combinations. Cost compression in standard tiers is intensifying because vitamin A and E acetate prices fluctuate with palm oil derivative markets. Large-scale CPG conglomerates exhibit lowest price sensitivity due to technical partnership bundling, whereas emerging functional beverage brands in Texas and Florida demonstrate highest elasticity, prioritizing rapid formulation iteration over supply security.
Supply Chain Analysis
Tariff exposure between China and the United States dominates risk calculus for crystalline vitamin B12, D3, and synthetic folate inputs that anchor premix formulations. Geographic supply concentration centers on China for bulk vitamin synthesis, India for specialized botanical extracts, and Switzerland for precision microencapsulation equipment. Raw material dependencies rest on palm oil derivatives for fat-soluble vitamin carriers, corn-derived maltodextrin for dry premix bases, and modified starch from Thai tapioca for encapsulation matrices. Single-source vulnerability compounds during Pacific shipping disruptions, particularly for premix suppliers without 90-day safety stock buffers. Distribution runs through direct technical partnerships for large manufacturers, regional chemical distributors for mid-tier processors, and e-procurement platforms for emerging brands requiring small-batch flexibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American customized premixes sit in early-cycle expansion as FDA-expanded fortification permissions for vitamin D and folate in dairy and grain applications accelerate contract acquisition velocity among formulation suppliers. This regulatory tailwind, combined with microencapsulation advances enabling previously incompatible probiotic-vitamin combinations, suggests penetration headroom remains substantial across ready-to-drink and functional food segments.
For Market Incumbents: Pre-empt margin erosion from backward-integrated competitors by locking 36-48 month technical partnership contracts with Upper Midwest dairy processors before Cargill Incorporated and DSM Nutritional Products consolidate shelf-space. Accelerate AI-driven formulation platform deployment to compress development cycles from 18 months to 6 months, denying mid-tier blenders R&D differentiation leverage. Defensive priority rests on building captive stability data libraries for novel carrier technologies ahead of heightened FDA GRAS scrutiny. For New Entrants and Emerging Players: Pursue pet nutrition manufacturers across the U.S. Southeast as the most penetrable white-space target, where species-specific premix demand for coat health and digestive function remains underserved by incumbent sports nutrition and dairy specialists. Target ready-to-drink beverage producers in Texas and Florida with rapid-dispersibility liquid premix expertise, exploiting clean-label mandates that eliminate anti-caking agents required in dry formats. Go-to-market angle should emphasize 6-month development cycles through high-throughput stability screening partnerships versus incumbent 18-month timelines. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among premix suppliers with established GRAS dossiers and long-term technical partnership contracts with large-scale CPG conglomerates. Five-to-ten year viability favors acquisition targets possessing AI-driven formulation platforms and verified non-GMO carrier systems aligned with USDA expanded organic certification standards. Signal to monitor: consolidation velocity among Utah and Arizona dietary supplement contract manufacturers responding to heightened FDA New Dietary Ingredient notification scrutiny, as supplier relationship rationalization creates acquisition windows for dossier-rich platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Vitamin Sourcing | Cargill Incorporated sustains margin control amid palm oil derivative volatility through captive supply of vitamin A and E acetates. |
| AI-Driven Formulation Platform Deployment | High-throughput stability screening compresses custom premix development cycles from 18 months to 6 months for beverage manufacturers. |
| GRAS Dossier Expansion for Novel Carriers | Premix suppliers with whole-genome sequencing documentation capture consolidated supplier relationships from Utah and Arizona contract manufacturers. |
| Technical Partnership Contract Structuring | DSM Nutritional Products anchors long-term stability data libraries with Midwestern dairy processors ahead of spot market volatility. |
| Pet Nutrition Premix Portfolio Buildout | Species-specific formulations for coat health and digestive function address underpenetrated demand across Southeastern U.S. manufacturers. |
Research Methodology
The analysis maps dry premix, liquid premix, functional premix, and organic premix sub-sectors, each validated through formulation chemists at leading suppliers, procurement directors at large-scale CPG conglomerates, regulatory affairs specialists navigating FDA and Health Canada requirements, and quality control managers at dietary supplement contract manufacturers. Primary interview insights triangulate against secondary sources including FDA food additive regulation filings, Health Canada Natural Health Products Directorate guidance documents, USDA organic certification standards, and SEC 10-K disclosures from publicly traded nutrition platforms. Bottom-up volume estimates from individual facility throughput reconcile with top-down market sizing derived from trade flow analysis across the Port of Long Beach and Midwestern rail networks.
Assumption sets held regulatory frameworks and fortification mandate timelines fixed while varying raw material price volatility scenarios and Pacific shipping disruption frequencies across the modeling period. Segmentation dimensions modeled include product type, end-user archetype, application processing environment, and distribution channel configuration. CAGRs emerge from slope analysis of year-over-year contract acquisition velocity and capacity utilization signals at crystalline vitamin production facilities. Industry-specific inputs incorporate vitamin A and E acetate price elasticity coefficients and microencapsulation technology adoption curves among ready-to-drink beverage manufacturers.
Sensitivities concentrate around FDA enforcement posture shifts on New Dietary Ingredient notifications, Health Canada stability testing requirement modifications, and bioaccumulation assessments from the U.S. EPA that may restrict certain fat-soluble vitamin carriers. Forecasts reflect these assumptions alongside documented procurement pattern changes among California functional food cluster participants. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Global Polymer Clay Market
Specialty Compounds
Propylene Trimer Market
Specialty Compounds
White Carbon Black Market
Specialty Compounds
Thermoset Molding Compounds Market
Specialty Compounds
Asia-Pacific Collagen Market
Specialty Compounds
Alginates and Derivatives Market
Specialty Compounds
Saudi Arabia Masterbatch Market
Specialty Compounds
Chromatography Silica Resins Market
Specialty Compounds
Polyurea Market
Specialty Compounds
Dextran Sulfate Sodium Market
Specialty Compounds
Global Zinc Acetylacetonate Market
Specialty Compounds
Global Heat Stabilizers Market
Specialty Compounds
Spackling Paste Market
Specialty Compounds
Dip Molding and Coating Market
Specialty Compounds
Potting Compound Market
Specialty Compounds
Global Specialty Zeolites Market