
 Spackling Paste Market | 2026-2036
Spackling Paste Market Size, Share, and Industry Trends Forecast 2026-2036
Spackling Paste Market Analytics
Water-based acrylic polymer technology is fragmenting the traditional solvent-based spackling segment into specialty niches by performance grade and substrate compatibility. DAP sustains broad retail distribution across home improvement channels, while Sherwin-Williams anchors professional-grade positioning through contractor-direct relationships. Quikrete Companies leverages its cementitious expertise to compete in powdered spackling formulations for large-scale construction repair.
Spackling paste is a pliable filler compound, typically comprising calcium carbonate, vinyl or acrylic polymer binders, and water or organic solvents, engineered to smooth surface imperfections in drywall, plaster, or wood before finishing. Ready-to-use formulations dominate residential convenience channels, while powdered products retain cost advantages for volume contractors. Vinyl-based spackling occupies the economy tier in wall repair applications, whereas acrylic variants command premium positioning in furniture restoration where flexibility and adhesion prove critical.
EPA VOC regulations constrain solvent-based formulation options, while OSHA workplace exposure standards shape contractor product selection and handling protocols. ISO 9001 quality certifications increasingly gate private-label supply relationships with national retailers. Stakeholders must monitor binder resin cost volatility and evolving state-level green building codes to align portfolio positioning with specification requirements.
Market Dynamics
EPA VOC regulations are forcing solvent-based spackling formulations into rapid obsolescence while water-based acrylic chemistry captures specification share across residential renovation channels.
Growth Catalysts
- EPA VOC Phase-Out:Federal limits on volatile organic compounds in architectural coatings are redirecting contractor procurement toward compliant water-based acrylic alternatives.
- Housing Stock Age:Pre-1980 residential structures in the United States require continuous drywall repair, sustaining baseline demand for ready-to-use spackling compounds.
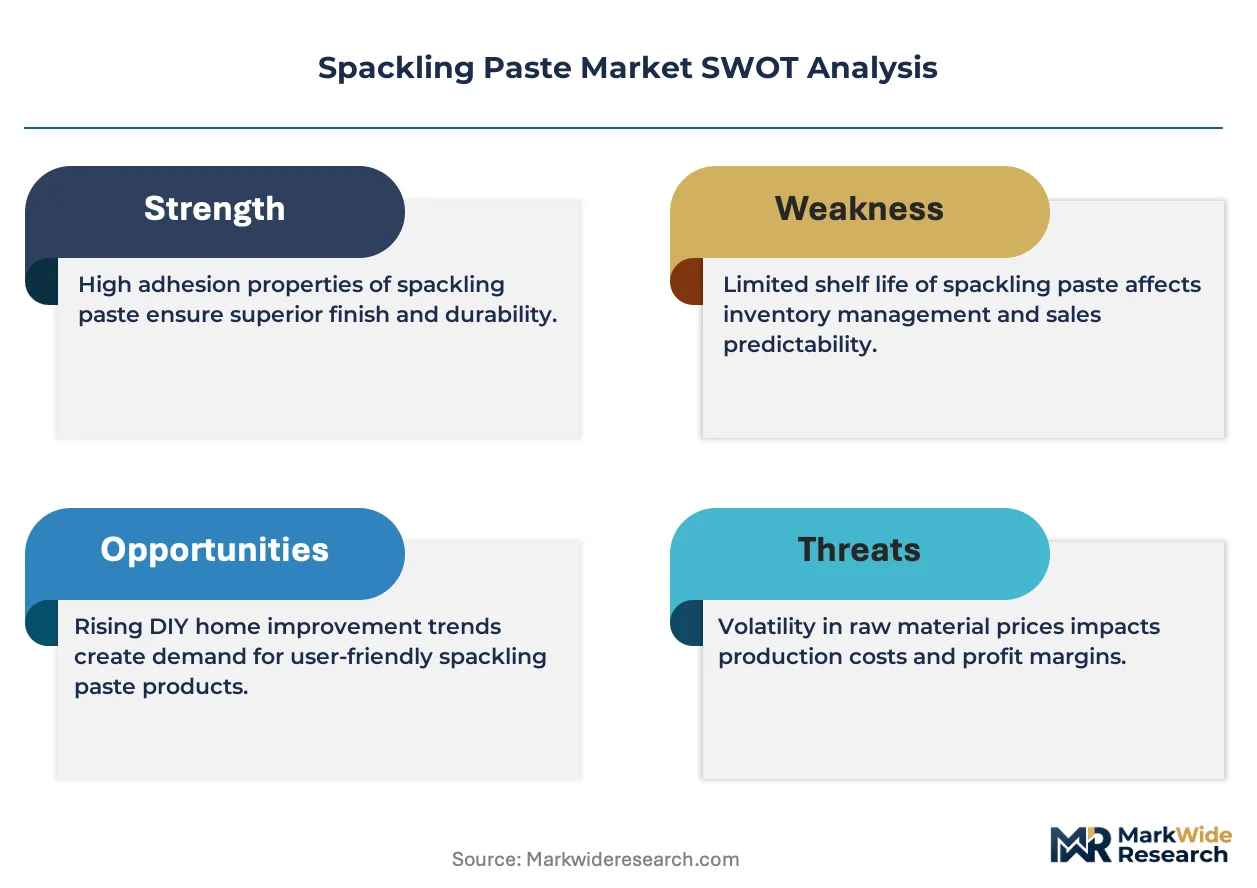
- DIY Channel Expansion:Home improvement retailers are expanding private-label spackling SKUs to capture renovation spending from non-professional applicators.
Market Restraints
- Acrylic Resin Cost Volatility:Petrochemical feedstock fluctuations compress margin stability for water-based formulation producers.
- Raw Material Concentration:Calcium carbonate supply clusters in select limestone-rich US states, exposing formulators to localized logistics disruptions.
- Performance Ceiling:Water-based acrylic spackling exhibits inferior sandability versus legacy solvent systems in high-humidity exterior applications.
Strategic Opportunities
- Green Building Code Alignment:California Title 24 and similar state-level mandates are creating specification pull for low-VOC repair compounds in commercial retrofit projects.
- Furniture Restoration Niche:Premium acrylic formulations with enhanced flexibility are penetrating antique wood repair applications previously served by traditional putties.
- Pro Contractor Direct Channels:Bypassing retail markup through distributor-direct relationships captures professional volume with higher attach rates for complementary finishing products.
Industry Challenges
- Formulation Chemistry Expertise Gap:Experienced compound chemists familiar with acrylic polymer rheology are concentrated among legacy manufacturers, constraining new entrant R&D velocity.
- ISO 9001 Certification Burden:National retailers now require quality management certification for private-label supply relationships, extending supplier onboarding timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spackling Paste Market |
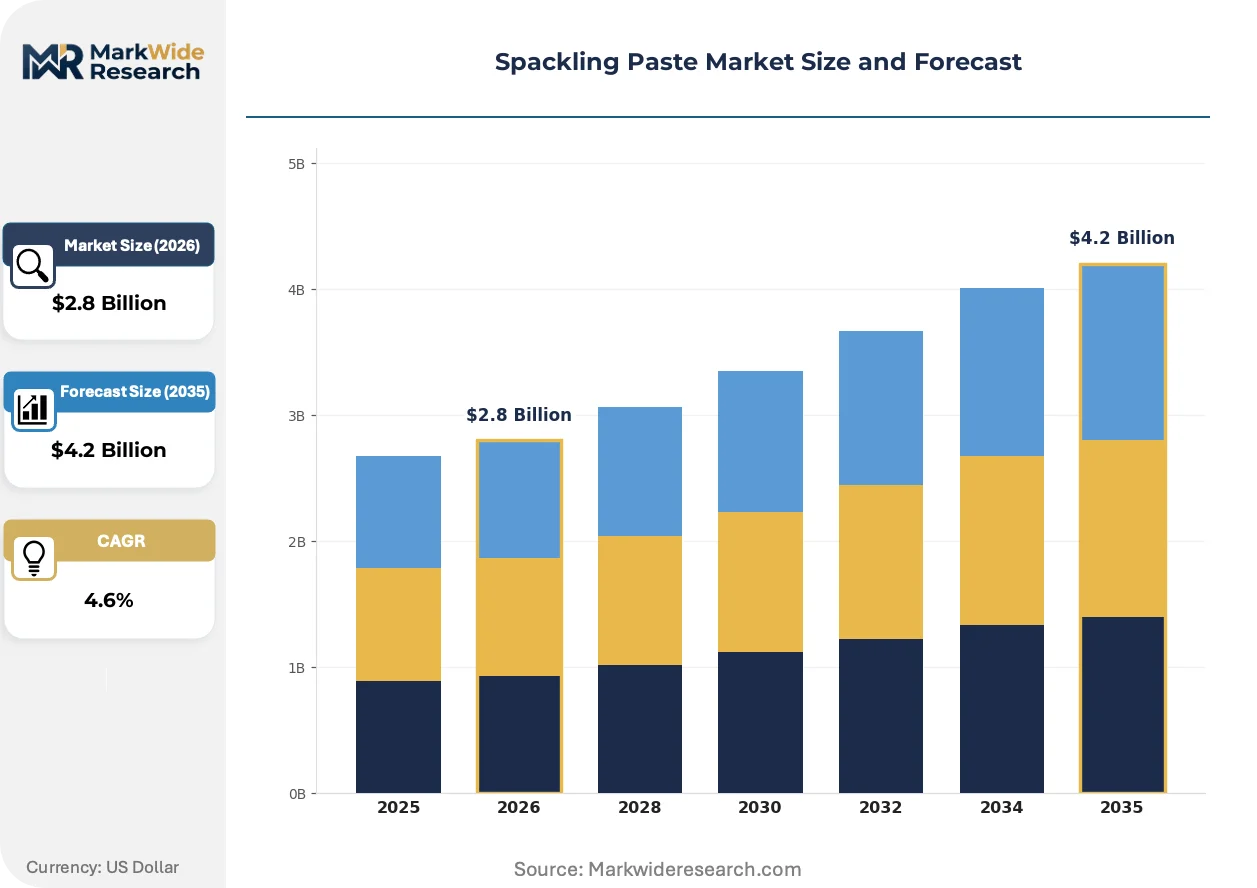
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vinyl, Acrylic, Powdered, Ready-to-Use Application: Wall Repair, Ceiling Repair, Wood Filling, Furniture Restoration End User: Contractors, DIY Enthusiasts, Renovators, Building Maintenance Packaging Type: Tube, Bucket, Cartridge, Pail |
| Companies Covered | Red Devil, Behr Process Corporation, DAP, Quikrete Companies, Crawford's, Sherwin-Williams, Macco Adhesives, Franklin International, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spackling Paste Market Evolving Landscape
Formulation chemistry is pivoting toward performance-specialized grades as regulatory pressure and substrate diversification fragment the historical commodity model.
Acrylic polymer spackling is migrating from interior drywall repair into exterior wood and fiber-cement applications where enhanced weather resistance and substrate adhesion command specification priority. Large-scale residential contractors in the southeastern United States are adopting these formulations for stucco remediation projects. The technology shift is compressing demand for traditional vinyl-based economy compounds in mid-tier renovation segments.
REACH substance restrictions in the European Union are accelerating disclosure requirements for spackling imported into member states, with SVHC candidate list screening now mandatory for construction product distributors. German and French importers are demanding full material composition documentation from Asian suppliers. The regulatory friction is favoring domestic EU compound manufacturers with established chemical safety dossiers.
Professional painting contractors are consolidating supplier relationships around single-source finishing system providers who bundle spackling with primers and topcoats. This procurement consolidation is displacing standalone spackling purchases through fragmented hardware channels. The pattern is most pronounced in metropolitan US markets where contractor fleet efficiency drives inventory simplification.
Spackling Paste Market Segmentation
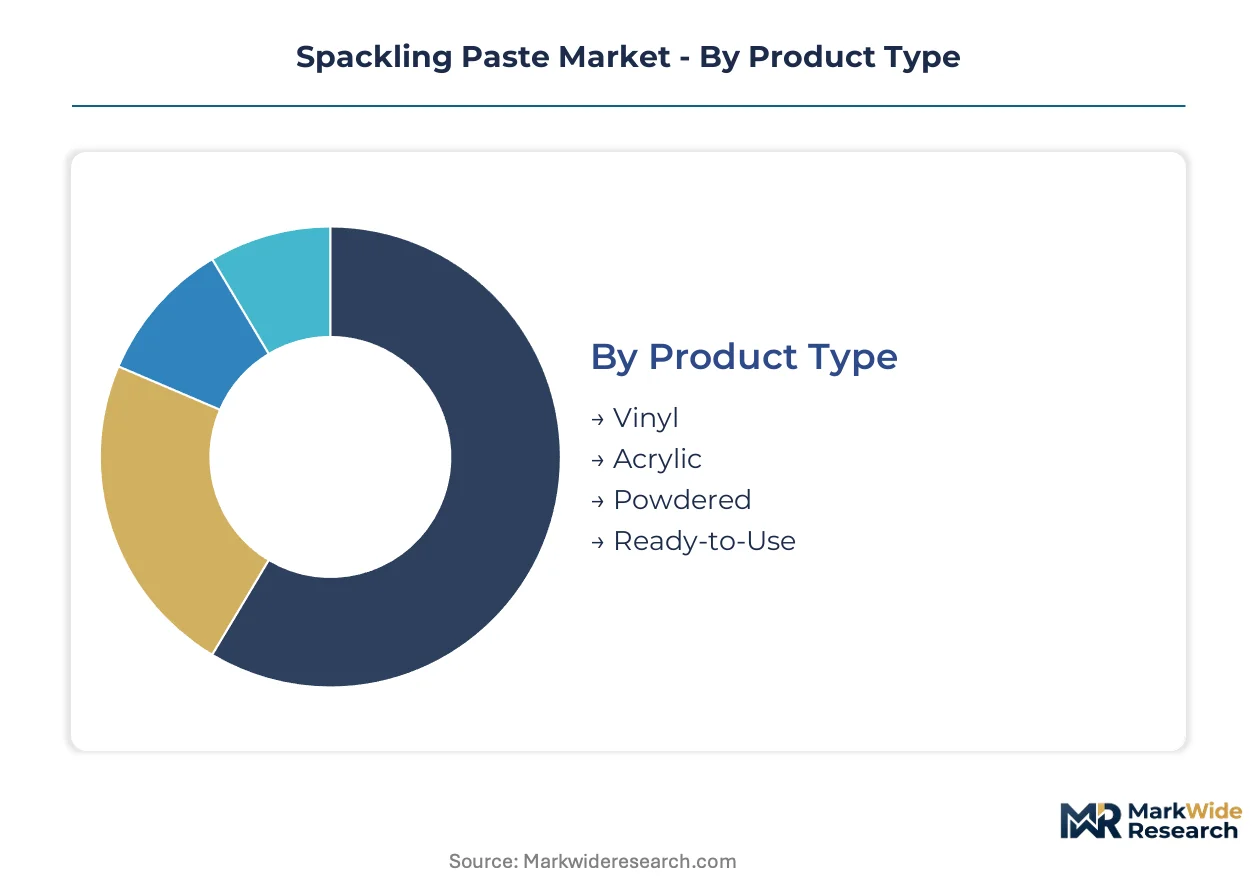
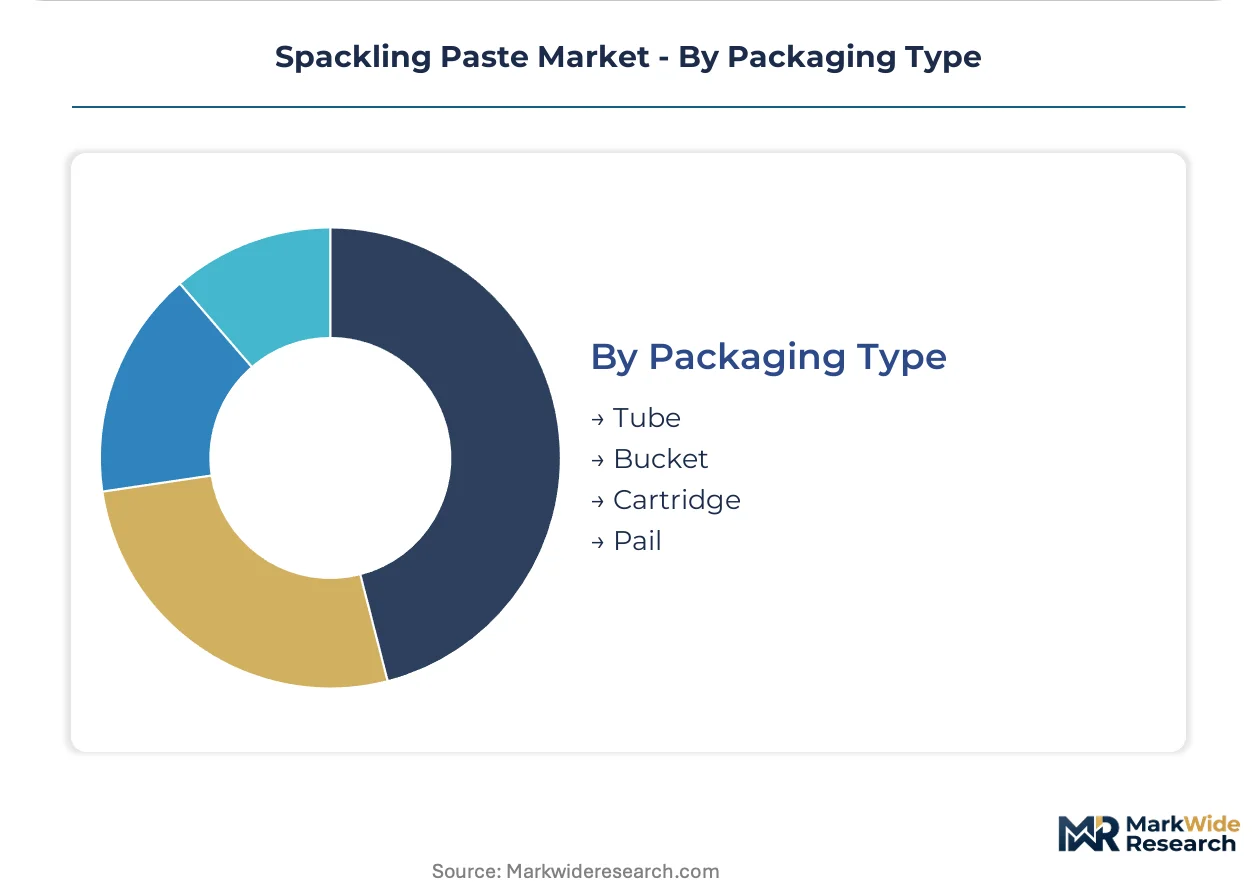
Spackling paste segmentation reflects divergent performance requirements across repair substrates and application expertise levels. Formulation chemistry and packaging format directly determine channel placement, pricing tiers, and regulatory compliance obligations.
Product Type:
Mature vinyl compounds anchor economy positioning while acrylic technology accelerates premium displacement across professional channels.
- Vinyl:Polyvinyl acetate binder systems deliver cost-optimized filler performance for interior drywall touch-ups. Demand concentrates in mass retail channels serving price-sensitive DIY renovators in the United States, though EPA VOC scrutiny is narrowing formulation flexibility.
- Acrylic:Water-based polymer emulsions provide superior flexibility, adhesion, and sandability for furniture restoration and exterior wood applications. Professional contractors in southeastern US stucco remediation projects are driving specification migration toward these higher-performance grades.
- Powdered:Cementitious blends requiring on-site water addition retain cost advantages for volume construction repair.
- Ready-to-Use:Pre-mixed formulations dominate residential convenience channels through home improvement retailers.
Ready-to-Use retains volume leadership; Acrylic holds the steepest expansion curve.
Application:
Substrate specialization fragments demand as contractors seek purpose-engineered compounds over historical multi-purpose formulations.
- Wall Repair:Drywall imperfection filling represents the foundational use case across residential renovation, with water-based acrylics displacing vinyl in mid-tier segments.
- Ceiling Repair:Overhead application demands non-sag rheology and extended open time, favoring premium formulations with enhanced thixotropic properties.
- Wood Filling:Exterior trim and siding repair requires flexible, paintable compounds with moisture resistance.
- Furniture Restoration:Antique repair applications command premium acrylic grades with reversible adhesion characteristics and stain compatibility.
Wall Repair commands the largest addressable base; Furniture Restoration exhibits the most rapid premiumization.
End User:
Procurement sophistication separates professional volume purchasers from intermittent retail consumers.
- Contractors:Fleet-based painting and drywall professionals consolidate supplier relationships around bundled finishing systems, bypassing fragmented hardware channels.
- DIY Enthusiasts:Home improvement retailer private-label capture targets non-professional applicators with convenience-oriented ready-to-use packaging.
- Renovators:Residential property improvement specialists balance cost control with specification compliance for client-facing projects.
- Building Maintenance:Commercial facility managers prioritize inventory simplification through multi-purpose compounds for recurring repair cycles.
Contractors drive the highest per-account revenue concentration; DIY Enthusiasts expand the broadest user base.
Packaging Type:
Format selection aligns with application scale, storage constraints, and point-of-purchase channel economics.
- Tube:Squeeze-dispensed containers dominate small-quantity retail for spot repairs and consumer convenience.
- Bucket:Rigid plastic pails serve professional contractors with volume requirements and repeated site access.
- Cartridge:Caulk-gun compatible formats enable precise application control for trim and detail work.
- Pail:Large-capacity packaging supports commercial maintenance operations and new construction touch-up programs.
Bucket formats retain professional channel preference; Cartridge designs gain traction in precision application segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Professional painting contractors and DIY renovators concentrate demand in mature housing markets with aged residential stock. Regulatory pressure on VOC emissions reshapes procurement patterns across North America and Europe.
United States
Pre-1980 housing stock sustains continuous drywall repair demand across the Midwest and Northeast corridors. EPA VOC regulations under the National Emission Standards for Hazardous Air Pollutants redirect contractor procurement toward water-based acrylic formulations. The Atlanta metropolitan cluster anchors southeastern stucco remediation activity where specialized spackling grades penetrate exterior repair segments.
Germany
REACH substance restrictions and SVHC candidate list screening accelerate disclosure requirements for construction product distributors. The country's national chemical safety regulator enforces stringent composition documentation for imported compounds. Industrial concentration in North Rhine-Westphalia supports domestic formulation manufacturing with established chemical safety dossiers.
United Kingdom
Victorian and Edwardian housing stock drives perennial repair demand in London and Southeast England. The country's building safety regulator implements post-Grenfell material traceability standards affecting repair compound specifications. Manchester and Birmingham distribution hubs channel professional-grade products to regional contractor networks.
Canada
Extreme climate cycling between seasons stresses exterior wood and siding substrates in Ontario and Quebec. Health Canada and PMRA oversee chemical safety standards for architectural coatings and repair materials. The Greater Toronto Area concentrates renovation contractor density with bundled finishing system procurement patterns.
Australia
Coastal humidity and bushfire recovery programs sustain demand for moisture-resistant repair compounds in New South Wales and Victoria. The country's therapeutic goods and chemical safety regulator enforces import screening for construction chemical composition. Sydney and Melbourne metropolitan markets channel premium acrylic grades through professional painting networks.
Spackling Paste Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented retail and professional distribution tiers. The vendor base separates into mass-market formulators, professional-grade specialists, and cementitious material producers. Three archetypes dominate: retail-anchored brands with home improvement chain relationships, contractor-direct suppliers with bundled finishing systems, and industrial compounders leveraging adjacent material expertise. Competitive moves center on portfolio diversification into complementary primers and topcoats, plus strategic partnerships with national retailer private-label programs.
Within the retail-anchored tier, DAP and Red Devil occupy positions exemplifying broad home improvement channel penetration. Sherwin-Williams anchors professional-grade positioning through contractor-direct relationships outside fragmented hardware distribution. Quikrete Companies represents the industrial-compounder archetype, leveraging cementitious material expertise into powdered spackling formulations for volume construction applications.
| Leading Market Players |
|---|
| Red Devil |
| Behr Process Corporation |
| DAP |
| Quikrete Companies |
| Crawford's |
| Sherwin-Williams |
| Macco Adhesives |
| Franklin International |
| 3M |
| Others |
Value Network & Pricing Analysis
Great Lakes freight corridors connecting limestone quarries in Ohio and Michigan to Midwest manufacturing centers transmit calcium carbonate cost volatility directly into spackling paste pricing tiers, while EPA compliance burdens widen spreads between economy vinyl formulations and premium acrylic grades.
Pricing Analysis
Cost-plus contracts indexed to acrylic resin spot markets dominate procurement between formulators and national retailers, with petrochemical feedstock fluctuations compressing margin stability for water-based producers. Three-tier pricing structure across premium, standard, and economy levels separates furniture restoration acrylics from mid-tier wall repair compounds and mass-market vinyl alternatives. Pricing pressure stems from raw material concentration in select limestone-rich states exposing formulators to localized logistics disruptions. DIY enthusiasts exhibit highest price sensitivity through private-label capture, while professional contractors prioritize performance over unit cost in bundled finishing system procurement.
Supply Chain Analysis
Export-control scrutiny on polymer emulsion technology limits technology transfer to Asian manufacturing partners, constraining new entrant R&D velocity. Supply concentrates in the United States, Germany, and China, with calcium carbonate extraction anchored in Ohio and Michigan limestone belts and acrylic resin production clustered in Gulf Coast petrochemical corridors. Formulation chemistry expertise rests on experienced compound chemists familiar with polymer rheology, concentrated among legacy manufacturers. Single-source vulnerability in calcium carbonate supply exposes producers to localized disruptions. Distribution runs through home improvement retail chains for DIY channels and distributor-direct relationships for professional contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA VOC phase-out mandates are accelerating water-based acrylic displacement of solvent-based alternatives, creating high-growth disruption as regulatory compliance becomes non-negotiable for market access.
For Market Incumbents: Insulate core contractor relationships by deepening backward integration into acrylic resin supply and accelerating ISO 9001 certification investments to gate private-label supply relationships against emerging competitors. Defend retail shelf space through exclusive SKU arrangements with home improvement chains that bundle spackling with complementary primers and topcoats.
For New Entrants and Emerging Players: Build out specialized formulation capabilities targeting furniture restoration niches where premium acrylic grades command specification priority and incumbent coverage remains thin. Target southeastern US stucco remediation contractors with moisture-resistant exterior formulations, leveraging direct distributor relationships to bypass established retail markup structures.
For Investors and Strategic Acquirers: Regional compounders with established chemical safety dossiers and REACH-compliant documentation represent prime acquisition targets as European regulatory friction favors domestic EU manufacturers over Asian imports. Monitor California Title 24 adoption patterns across additional states as the signal for green building code acceleration that would reshape specification requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Resin | Captive supply of petrochemical feedstocks insulates margin stability from spot market volatility. |
| Green Building Code Alignment | California Title 24 compliance opens specification pathways in commercial retrofit segments. |
| Professional Channel Consolidation | Bundled finishing systems capture contractor volume with higher attach rates for complementary products. |
| Furniture Restoration Specialization | Premium acrylic grades penetrate antique wood repair applications with reversible adhesion characteristics. |
| REACH Compliance Investment | Full material composition documentation satisfies German and French importer screening requirements. |
Research Methodology
Cross-validation between primary interviews with formulation chemists, procurement leads at national retailers, and distribution channel partners anchors the qualitative findings, while secondary validation draws from EPA regulatory filings, customs trade data on calcium carbonate imports, and home improvement retailer SKU databases. Bottom-up volume estimates from product-type and application segmentations triangulate against top-down market sizing derived from housing stock age demographics and renovation spending patterns.
Calibration against historical acrylic resin price series and contractor procurement survey data refines the analytical framework across the projection horizon. Segmentation dimensions modeled include formulation chemistry, packaging format, end-user expertise level, and substrate application. CAGRs derive from trend extrapolation of water-based displacement rates and housing renovation cycle analysis, with inputs from petrochemical feedstock forecast models and state-level green building code adoption timelines.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by cementitious material producers or accelerated REACH substance restrictions would shift outcomes. Material shifts in EPA VOC enforcement stringency or acrylic resin supply disruptions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Strontium Chloride Market
Specialty Compounds
Neohespiridine Market
Specialty Compounds
Polyoxin Market
Specialty Compounds
Joint Compound Market
Specialty Compounds
Polyimide Coatings Market
Specialty Compounds
Specialty Sorbents Market
Specialty Compounds
Thermoset Molding Compounds Market
Specialty Compounds
Lithium Compound Market
Specialty Compounds
Dextran Sulfate Sodium Market
Specialty Compounds
Methane Sulfonyl Chloride Market
Specialty Compounds
Global Zinc Acetylacetonate Market
Specialty Compounds
GCC Hydroxypropyl Methylcellulose Market
Specialty Compounds
Metasulphite Market
Specialty Compounds
Gulf Collagen Market
Specialty Compounds
United States Hydroxypropyl Methylcellulose (HPMC) Market
Specialty Compounds
Saudi Arabia Masterbatch Market