
 Asia-Pacific Collagen Market | 2026-2036
Asia-Pacific Collagen Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Collagen Market Outlook
Ingredient-grade gelatin sales is narrowing as hydrolyzed collagen and peptide concentrates command wider formulation premiums across Asia-Pacific nutraceutical channels. Rousselot leverages its European peptide technology base to extend premium positioning in Japanese cosmetic applications. Darling Ingredients anchors large-scale bovine and porcine raw material flows through integrated rendering operations. Nitta Gelatin Inc. dominates Japanese pharmaceutical-grade gelatin supply with decades of JIS-standard manufacturing pedigree.
Collagen comprises fibrous structural proteins rich in glycine, proline, and hydroxyproline amino acids, extracted through acid or enzymatic hydrolysis of bovine hides, porcine skins, or marine tissues to yield gelling, emulsifying, or bioactive functionalities. Hydrolyzed collagen and collagen peptides lead value generation due to superior bioavailability in nutraceutical and cosmeceutical matrices, while native collagen retains specialized pharmaceutical coating applications. Gelatin occupies mature, volume-driven positions in Asia-Pacific food and beverage stabilization, where price sensitivity constrains margin expansion compared to peptide segments.
Japan's PMDA and China's NMPA enforce divergent purity and sourcing documentation standards that fragment cross-border product registration pathways for collagen suppliers. India's CDSCO and FSSAI impose additional BIS-aligned testing protocols on imported animal-derived ingredients, lengthening market access timelines for non-domestic manufacturers. Stakeholders must monitor evolving halal and kosher certification requirements across Indonesia, Malaysia, and Thailand as these specifications increasingly determine eligibility for mainstream retail and pharmaceutical procurement channels.
Market Dynamics
China's NMPA novel food ingredient streamlining is compressing hydrolyzed collagen approval timelines from years to months, redistributing formulation investment toward functional beverages and shifting procurement patterns across coastal manufacturing clusters.
Growth Catalysts
- MFDS-aligned nutraceutical expansion:South Korean supplement firms are scaling joint-health peptide procurement as aging demographics accelerate prescription-to-OTC migration for osteoarthritis management.
- Marine collagen enzymatic hydrolysis:Advanced extraction protocols from tuna and cod skins are unlocking halal-certified supply chains for Indonesia and Malaysia's pharmaceutical procurement channels.
- Japan's PMDA pharmaceutical-grade pathway:Cosmetic peptide registrations for dermal matrix applications are creating premium pricing corridors distinct from commodity gelatin segments.
Market Restraints
- Bovine raw material cost volatility:Darling Ingredients and integrated renderers face margin pressure from feedstock competition with pet food and oleochemical buyers across Australian and New Zealand cattle processing.
- Cross-border regulatory friction:India's CDSCO and FSSAI BIS-aligned testing protocols extend import clearance timelines for European and North American collagen suppliers by 8-14 months.
- Plant protein substitution threat:Pea and rice protein isolates are capturing share in mass-market sports nutrition, constraining hydrolyzed collagen volume expansion in price-sensitive segments.
Strategic Opportunities
- Vietnam and Philippines underpenetration:Functional beverage channels in these markets lack dedicated collagen peptide SKUs, presenting first-mover positioning for halal-certified marine-derived formulations.
- Thailand's MOHAP cosmetic peptide pathway:Regulatory clarity on topical bioactive claims is enabling cosmeceutical brands to launch clinical-grade dermal repair serums with documented collagen penetration data.
- E-commerce direct-to-consumer channel innovation:Tmall and Shopee flagship stores are bypassing traditional pharmaceutical distribution, capturing margin previously allocated to hospital and clinic procurement officers.
Industry Challenges
- Peptide characterization skill scarcity:Analytical chemists capable of molecular weight distribution validation and bioactivity assay standardization command 40-60% salary premiums across Guangdong and Zhejiang processing facilities.
- Halal certification timeline compression:MUI Indonesia and JAKIM Malaysia have extended audit cycles for bovine-derived ingredients, forcing manufacturers to maintain dual-certified inventory buffers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Collagen Market |
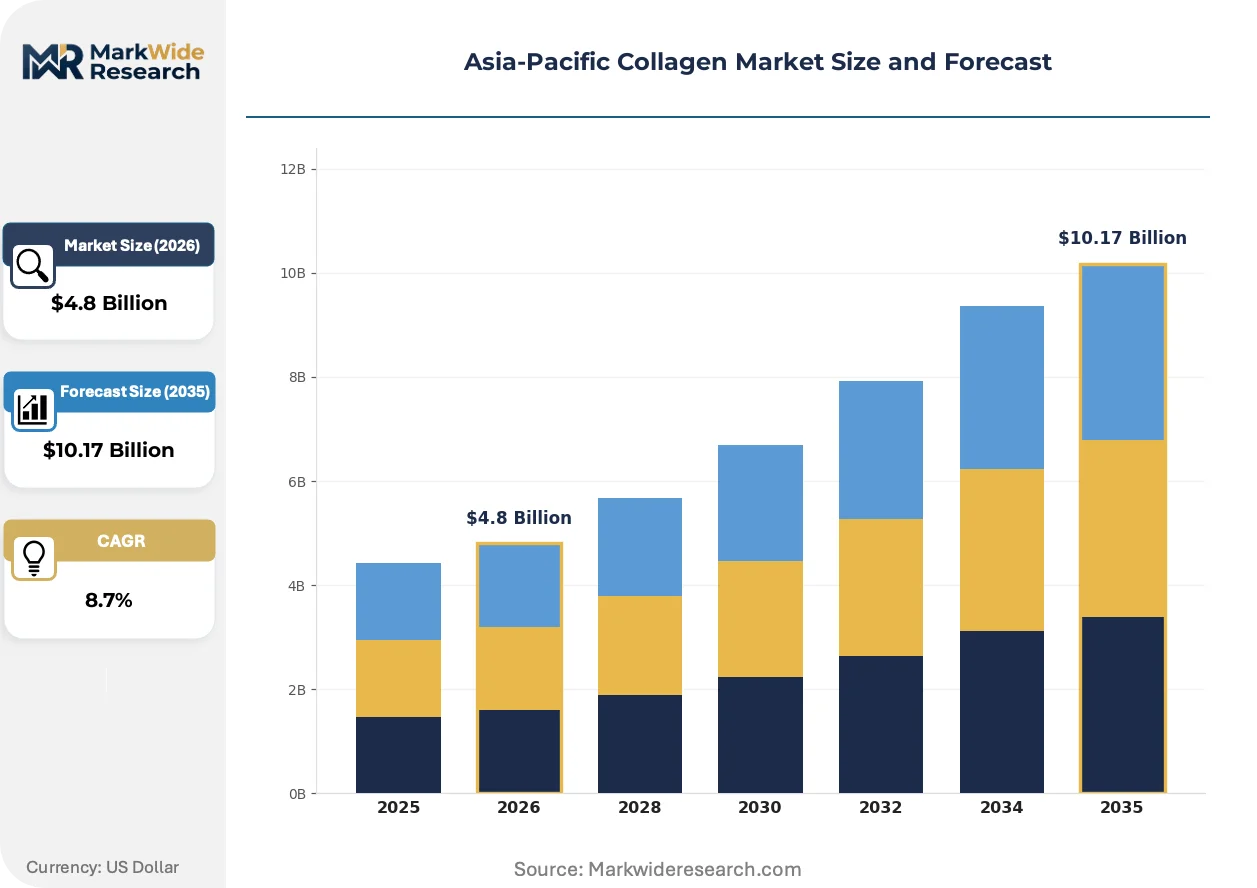
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gelatin, Hydrolyzed Collagen, Collagen Peptides, Native Collagen Application: Food & Beverage, Nutraceuticals, Cosmetics, Pharmaceuticals Form: Powder, Liquid, Capsules, Sheets End User: Manufacturers, Retail Consumers, Nutritional Supplement Firms, Research Institutions |
| Companies Covered | Gelita AG, Darling Ingredients, Hangzhou Nutrition Biotechnology Co. Ltd, Rousselot, Thai Union Ingredients, Jiangxi Cosen Biochemical Co., Ltd., Tessenderlo Group, Vinh Hoan Corporation, Nitta Gelatin Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Collagen Market Strategic Shifts
Enzymatic specificity and process analytical technology are displacing acid-hydrolysis legacy systems, while regulatory data harmonization efforts and channel disintermediation reshape competitive access patterns across the region.
Precision enzymatic hydrolysis is digitizing collagen manufacturing control systems. Protease specificity tuning enables targeted peptide chain length distributions for distinct nutraceutical bioavailability profiles. Japanese and South Korean cosmetic formulators are adopting these systems at pilot scale, with full production integration expected within 24 months. The technology is digitizing quality assurance workflows, compressing batch release timelines from weeks to days while reducing off-specification product rates.
China's NMPA streamlined novel food ingredient framework is eliminating redundant provincial-level review stages for hydrolyzed collagen. The policy shift reduces documentation requirements for functional beverage applications while maintaining pharmaceutical-grade stringency for injectable and wound-care segments. Domestic Chinese manufacturers are responding by accelerating SKU proliferation in ready-to-drink collagen waters, while importers face compressed windows to establish localized production partnerships.
Hospital procurement officers in Japan and South Korea are consolidating peptide supplier rosters from 8-12 vendors to 3-4 strategic partners. Direct long-term agreements with integrated renderers and peptide processors are replacing distributor-mediated spot purchasing. This concentration is most visible in Tokyo and Seoul metropolitan hospital networks, where formulary committees now mandate supplier audit transparency and documented cold-chain integrity from raw material sourcing through final formulation.
Asia-Pacific Collagen Market Segmentation
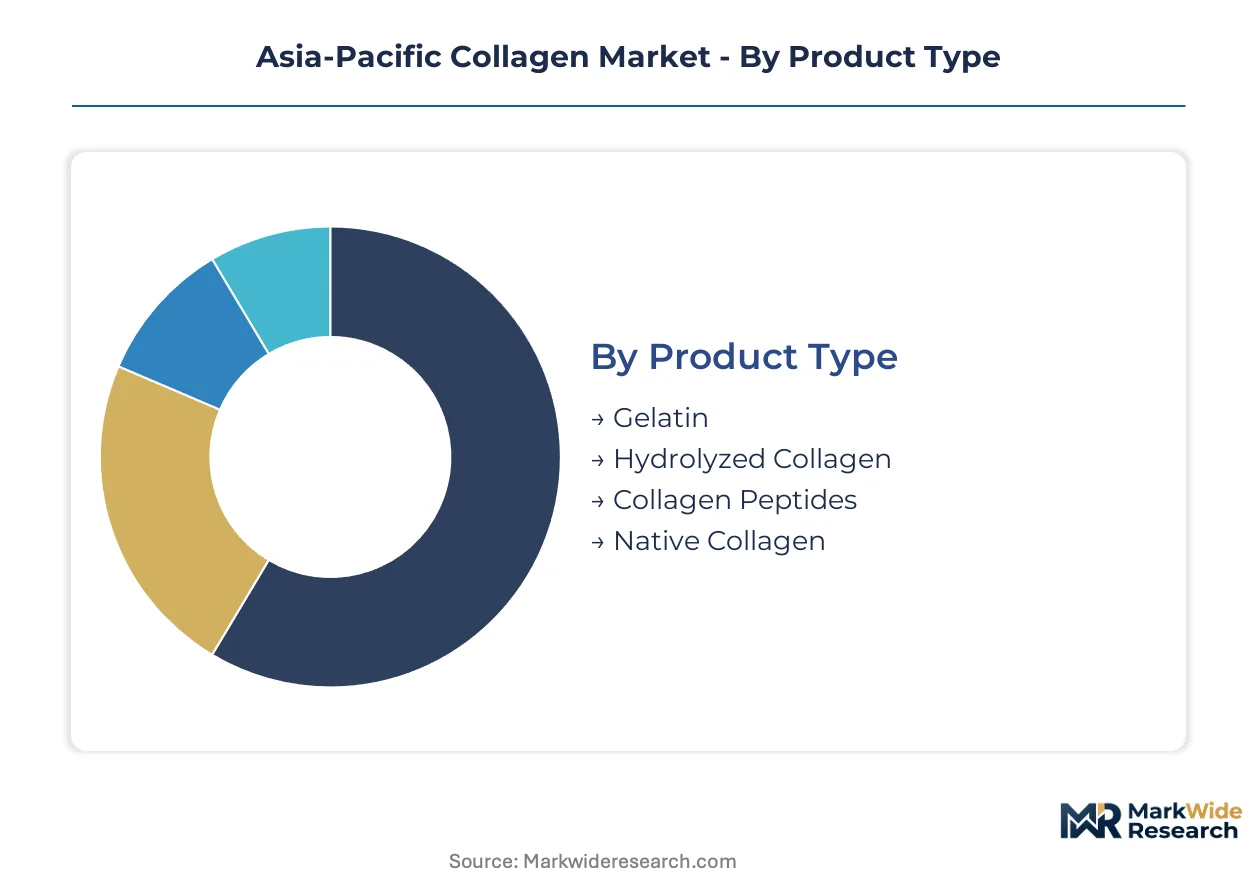
Segmentation in the Asia-Pacific collagen market exposes divergent margin profiles across extraction technologies and regulatory compliance tiers. Product form and end-user channel selection determine working capital intensity and certification burden for suppliers navigating fragmented national standards.
Product Type:
After-sales technical support requirements vary sharply across extraction methods, with enzymatic hydrolysis systems demanding sustained analytical chemistry partnerships.
- Hydrolyzed Collagen:Enzymatically cleaved protein chains averaging 2-5 kilodaltons deliver enhanced bioavailability in functional beverage matrices. Guangdong and Zhejiang manufacturers are expanding dedicated hydrolysis capacity to serve China's NMPA-streamlined novel food ingredient pathway.
- Collagen Peptides:Fractionated low-molecular-weight sequences below 3 kilodaltons optimized for dermal penetration and joint-health bioactivity. South Korean nutraceutical firms are scaling peptide procurement as MFDS-aligned aging demographics accelerate prescription-to-OTC migration for osteoarthritis management.
- Gelatin:Partially hydrolyzed collagen retaining gelling functionality for food stabilization and pharmaceutical coating applications.
- Native Collagen:Triple-helix intact protein structures reserved for specialized wound-care matrices and tissue-engineering scaffolds.
Hydrolyzed collagen holds the largest share; momentum sits with collagen peptides.
Application:
Cost tier stratification separates commodity food stabilization from premium pharmaceutical-grade formulations requiring documented cold-chain integrity.
- Nutraceuticals:Bioactive peptide concentrates formulated for joint, skin, and bone health claims with substantiated absorption kinetics. Japanese PMDA cosmetic peptide registrations are creating premium pricing corridors distinct from commodity gelatin segments.
- Cosmetics:Topical and ingestible formulations leveraging collagen for dermal matrix support and anti-aging positioning. Thailand's MOHAP regulatory clarity on topical bioactive claims is enabling clinical-grade dermal repair serums with documented penetration data.
- Food & Beverage:Stabilization, texture modification, and protein fortification in processed foods and ready-to-drink formats.
- Pharmaceuticals:Hard and soft capsule shells, tablet binders, and wound-care dressings meeting pharmacopeial purity standards.
Nutraceuticals command the steepest expansion trajectory; cosmetics is climbing the fastest on premium positioning.
Form:
Volume concentration favors powder formats in industrial procurement, while liquid and capsule forms capture direct-to-consumer margin.
- Powder:Bulk industrial input for food manufacturing and supplement formulation with extended shelf stability.
- Liquid:Ready-to-drink collagen waters and shot formats gaining traction in China's coastal urban centers.
- Capsules:Precise dosing convenience for nutraceutical and pharmaceutical channels.
- Sheets:Topical delivery systems for cosmetic masking and wound-care applications.
Powder dominates procurement volumes; liquid formats are gaining share fastest through e-commerce flagship expansion.
End User:
Customer type determines contract structure, with manufacturers locking multi-year supply agreements while retail channels favor spot purchasing flexibility.
- Nutritional Supplement Firms:South Korean and Japanese companies scaling peptide procurement for joint and skin health formulations with documented bioactivity assays.
- Manufacturers:Food, beverage, and pharmaceutical processors integrating collagen into finished goods with formulation technical support requirements.
- Retail Consumers:Individual purchasers accessing collagen through e-commerce direct-to-consumer channels bypassing traditional distribution.
- Research Institutions:Academic and clinical organizations sourcing pharmaceutical-grade materials for biomaterial and therapeutic development.
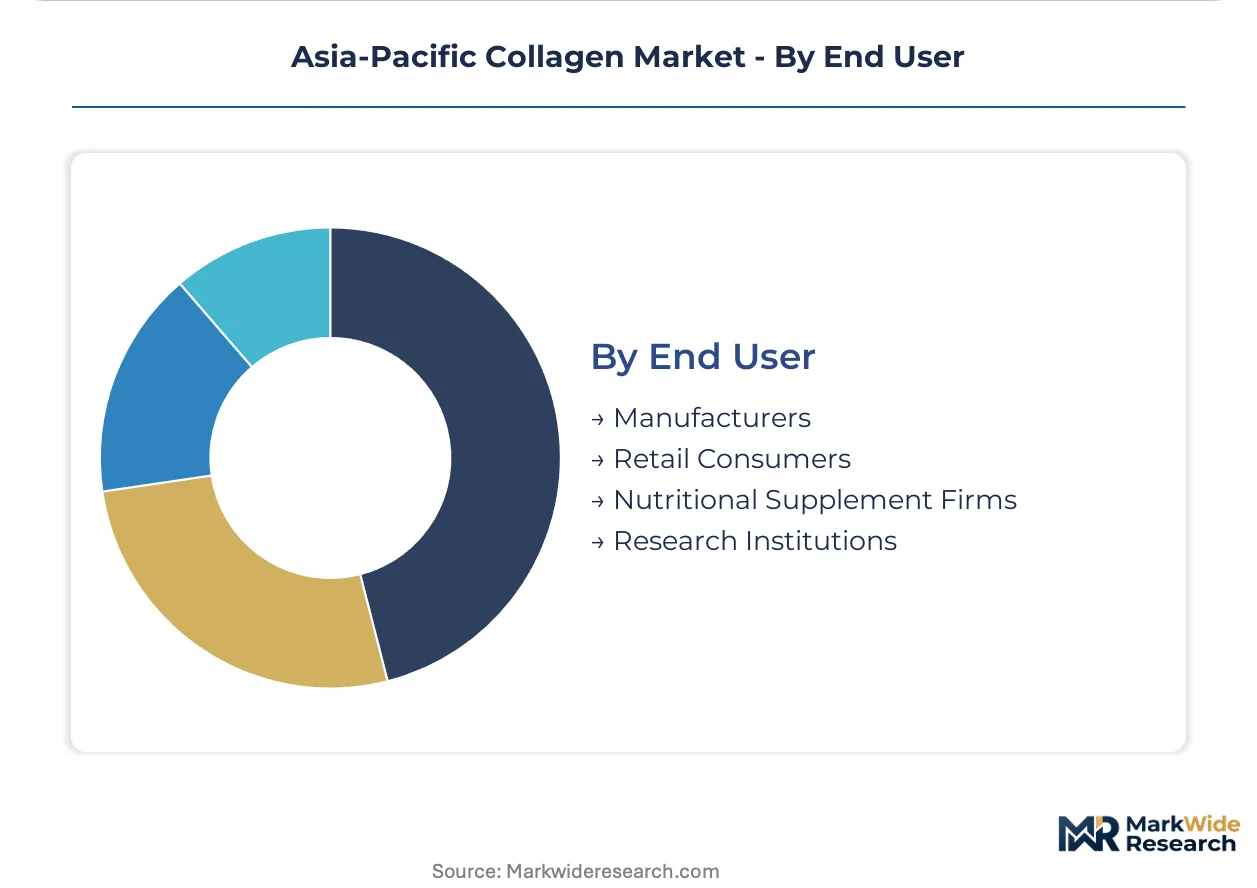
Manufacturers represent the largest procurement base; nutritional supplement firms are expanding most quickly on aging demographic tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Asia-Pacific diverge sharply by application mix. China prioritizes functional beverage fortification while Japan concentrates pharmaceutical-grade peptide procurement, and Southeast Asian markets gravitate toward halal-certified marine sources for cosmetic and nutraceutical channels.
China
Functional beverage manufacturers in Guangdong and Zhejiang provinces are accelerating hydrolyzed collagen adoption following NMPA's streamlined novel food ingredient approvals. The regulatory shift compresses approval timelines from years to months, redistributing formulation investment toward ready-to-drink collagen waters. Coastal manufacturing clusters now host converging gelatin and peptide processing capacity serving domestic brands and export markets.
Japan
Cosmetic peptide registrations for dermal matrix applications command premium pricing corridors distinct from commodity gelatin segments. PMDA enforces stringent purity documentation that fragments cross-border product registration pathways for non-domestic suppliers. Tokyo and Osaka metropolitan hospital networks are consolidating peptide supplier rosters from 8-12 vendors to 3-4 strategic partners with documented cold-chain integrity.
South Korea
MFDS-aligned nutraceutical firms are scaling joint-health peptide procurement as aging demographics accelerate prescription-to-OTC migration for osteoarthritis management. Seoul-based supplement manufacturers are locking multi-year supply agreements with integrated renderers to secure bioactive peptide concentrates. The country's cosmetic formulators are adopting precision enzymatic hydrolysis systems at pilot scale for targeted peptide chain length distributions.
Indonesia
Halal certification requirements increasingly determine eligibility for mainstream retail and pharmaceutical procurement channels. MUI has extended audit cycles for bovine-derived ingredients, forcing manufacturers to maintain dual-certified inventory buffers. Advanced enzymatic extraction protocols from tuna and cod skins are unlocking halal-certified supply chains for pharmaceutical-grade marine collagen.
Thailand
MOHAP regulatory clarity on topical bioactive claims enables cosmeceutical brands to launch clinical-grade dermal repair serums with documented collagen penetration data. Bangkok-based formulators are bypassing traditional pharmaceutical distribution through Shopee flagship stores, capturing margin previously allocated to clinic procurement officers. The country's functional beverage channels lack dedicated collagen peptide SKUs, presenting first-mover positioning for halal-certified marine-derived formulations.
Asia-Pacific Collagen Market Competitive Environment
Capability concentration sits with peptide specialists possessing enzymatic specificity and analytical chemistry partnerships; scale advantage sits with integrated renderers controlling bovine and porcine raw material flows across multi-source geographies. The vendor base stratifies into three tiers: European technology licensors commanding premium positioning in Japanese cosmetic applications, Asia-Pacific manufacturers leveraging coastal processing clusters for cost-competitive hydrolyzed collagen, and marine-derived specialists building halal-certified supply chains for Southeast Asian markets. Dominant competitive moves include backward integration into rendering operations and geographic expansion through localized production partnerships to circumvent extended import clearance timelines.
Within the European technology tier, Rousselot and Gelita AG exemplify premium peptide positioning through proprietary enzymatic hydrolysis systems. Darling Ingredients anchors scale-driven supply through integrated rendering operations spanning Australian and New Zealand cattle processing. Among Asia-Pacific manufacturers, Nitta Gelatin Inc. occupies a position within Japanese pharmaceutical-grade supply chains built on decades of JIS-standard manufacturing pedigree.
| Leading Market Players |
|---|
| Gelita AG |
| Darling Ingredients |
| Hangzhou Nutrition Biotechnology Co. Ltd |
| Rousselot |
| Thai Union Ingredients |
| Jiangxi Cosen Biochemical Co., Ltd. |
| Tessenderlo Group |
| Vinh Hoan Corporation |
| Nitta Gelatin Inc. |
| Others |
Value Chain & Pricing Dynamics
Guangdong and Zhejiang coastal manufacturing clusters concentrate hydrolyzed collagen capacity, translating raw material proximity into formulation cost advantages for functional beverage producers serving China's NMPA-streamlined approval pathway. This geographic density enables domestic brands to undercut imported peptide pricing while maintaining margin discipline.
Pricing Analysis
Long-term offtake agreements dominate procurement between integrated renderers and hospital networks in Japan and South Korea, compressing spot-market liquidity for mid-tier suppliers. Price differentiation separates pharmaceutical-grade peptide concentrates from commodity gelatin on PMDA documentation stringency and cold-chain audit depth. Cost compression in food-grade segments intensifies as plant protein isolates capture sports nutrition share. Nutraceutical formulators exhibit highest price sensitivity; cosmetic peptide buyers absorb premiums for dermal penetration validation.
Supply Chain Analysis
Bovine hides from Australian and New Zealand cattle processing, porcine skins from domestic Chinese slaughterhouses, and tuna skins from Indonesian marine fisheries constitute the upstream feedstock base. Raw material flows hinge on halal certification status for Southeast Asian pharmaceutical channels and JIS-standard pedigree for Japanese cosmetic applications. Single-source vulnerability concentrates in MUI Indonesia and JAKIM Malaysia audit bottlenecks for bovine-derived inventory. Distribution runs through Tmall and Shopee flagship stores disintermediating traditional clinic procurement in Thailand and Vietnam.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment moat story because NMPA, PMDA, and MFDS documentation requirements create multi-year certification barriers that protect incumbent peptide specialists from commodity substitution.
For Market Incumbents: Build certification depth as the primary moat by accelerating dual halal-kosher audit completion ahead of MUI Indonesia and JAKIM Malaysia timeline extensions. Secure backward integration into rendering operations to defend against Darling Ingredients and integrated competitors controlling Australian and New Zealand cattle flows. Channel control through direct long-term hospital agreements in Tokyo and Seoul metropolitan networks locks out distributor-dependent challengers facing 8-14 month CDSCO clearance delays. For New Entrants and Emerging Players: Establish a beachhead in Vietnam and Philippines functional beverage channels where dedicated collagen peptide SKUs remain absent and first-mover halal-certified marine positioning is uncontested. Target Thailand's MOHAP cosmetic peptide pathway for clinical-grade dermal repair serums with documented penetration data. A direct-to-consumer launch through Shopee flagship stores bypasses entrenched pharmaceutical distribution and captures margin previously allocated to clinic procurement officers. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because hospital procurement officer consolidation from 8-12 vendors to 3-4 strategic partners concentrates purchasing power with integrated peptide processors possessing enzymatic specificity and analytical chemistry partnerships. Acquisition targets should display captive supply relationships with tuna and cod skin fisheries for halal-certified marine collagen. The signal to watch is precision enzymatic hydrolysis pilot-scale adoption rates among Japanese and South Korean cosmetic formulators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rendering Operations | Darling Ingredients anchors bovine and porcine raw material flows across Australian and New Zealand cattle processing. |
| Dual Halal-Kosher Certification Investment | MUI Indonesia and JAKIM Malaysia audit extensions force inventory buffers that only scaled manufacturers can maintain. |
| Precision Enzymatic Hydrolysis Scale-Up | Japanese cosmetic formulators adopt pilot systems for targeted peptide chain length distributions with 24-month production integration. |
| Direct-to-Consumer Channel Launch | Tmall and Shopee flagship stores bypass hospital procurement officers and capture margin in Thailand and Vietnam. |
| Long-Term Hospital Supply Agreement | Tokyo and Seoul metropolitan networks consolidate vendor rosters to 3-4 partners with documented cold-chain integrity. |
Study Parameters
Operator-level perspectives from peptide manufacturing plant managers, nutraceutical procurement leads at South Korean supplement firms, pharmaceutical regulatory affairs directors navigating PMDA pathways, and cosmetic formulators adopting enzymatic hydrolysis systems anchored the qualitative base. Secondary validation drew from NMPA novel food ingredient filings, MFDS cosmetic peptide registrations, customs trade data on gelatin and hydrolyzed collagen flows, and SEC disclosures from integrated rendering operators. Bottom-up capacity assessments across Guangdong and Zhejiang processing facilities were triangulated against top-down demand modeling from functional beverage SKU proliferation rates.
Scenario-bracketing framed the analytical approach across the analysis window, with segmentation dimensions spanning extraction technology, molecular weight distribution tiers, application channels, and regulatory compliance grades. CAGRs were derived from elasticity-adjusted demand curves incorporating aging demographic prescription-to-OTC migration patterns and enzymatic hydrolysis adoption curves. Industry-specific inputs included MUI Indonesia halal certification timeline data and PMDA pharmaceutical-grade pathway approval velocity.
Sensitivities concentrate around NMPA regulatory reversals, marine raw material availability disruptions from tuna and cod fisheries, and plant protein substitution acceleration in mass-market sports nutrition. Forecasts embed assumptions on enzymatic specificity technology diffusion and hospital procurement consolidation velocity. Cross-checking against CDSCO and FSSAI import clearance timeline benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Small Molecules Innovator Contract Development and Manufacturing Organization Market
Specialty Compounds
Neohespiridine Market
Specialty Compounds
Lithopone Market
Specialty Compounds
Expandable Microspheres Market
Specialty Compounds
Dip Molding and Coating Market
Specialty Compounds
US Non-Commercial Acrylic Paints Market
Specialty Compounds
Specialty Nitriles Market
Specialty Compounds
Chemical Synthesis Methyl Salicylate Market
Specialty Compounds
Europe Polypropylene Compounds Market
Specialty Compounds
Spackling Paste Market
Specialty Compounds
Organoclay Market
Specialty Compounds
United Kingdom Collagen Peptides Market
Specialty Compounds
Opacifiers Market
Specialty Compounds
Latin America Hydroxypropyl Methylcellulose Market
Specialty Compounds
Polypeptide Market
Specialty Compounds
Potting Compound Market