
 Starch-Based Bioplastics Market | 2026-2036
Starch-Based Bioplastics Market Size, Share, and Industry Trends Forecast 2026-2036
Starch-Based Bioplastics Market Outlook
The EU Green Deal is decoupling starch-based bioplastics from fossil-plastic cost parity by mandating recycled and renewable content floors in packaging. Novamont SpA leverages its Italian fermentation complexes to dominate pharmaceutical-grade PLA-starch blends. BASF SE anchors European supply through backward integration into potato starch refining. Roquette Frères sustains global feedstock security via its vertical control over pea and maize starch extraction.
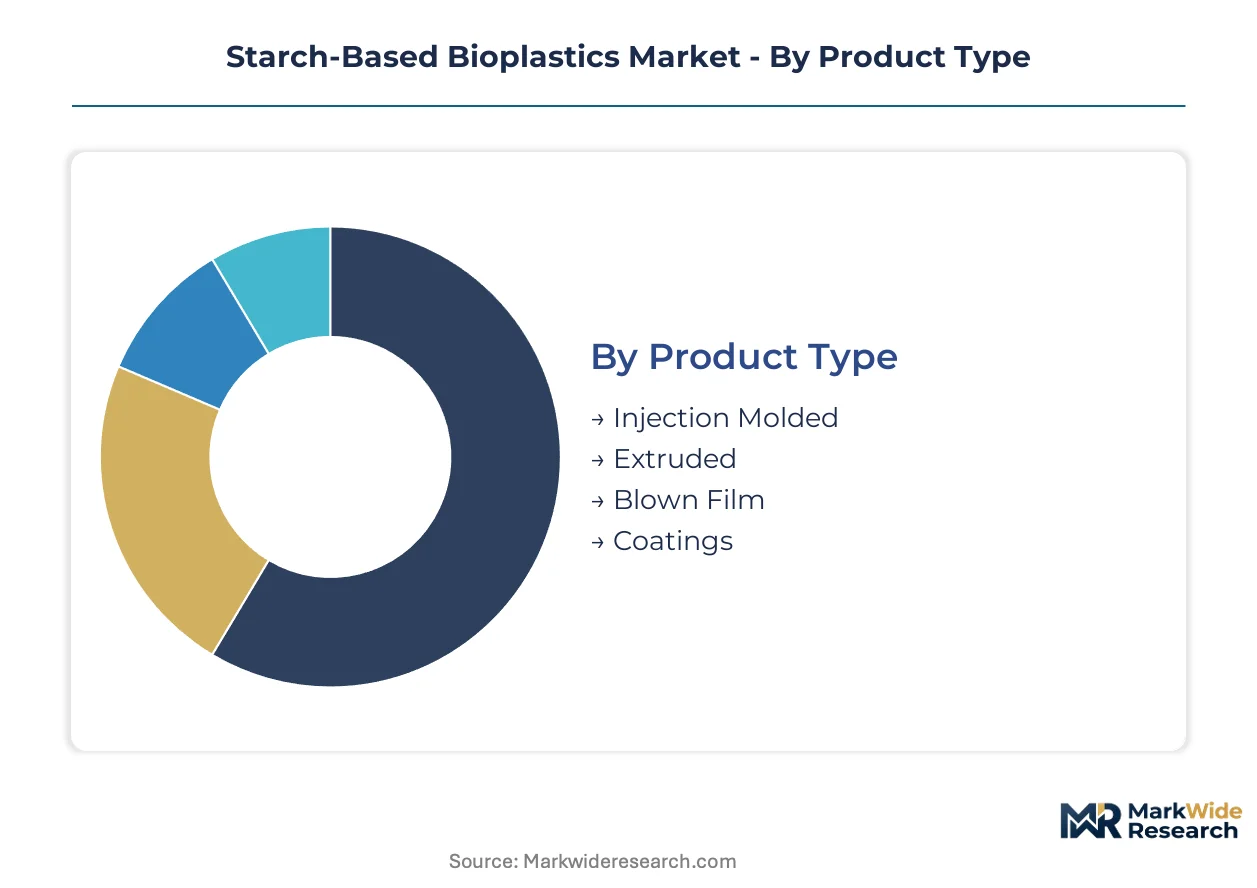
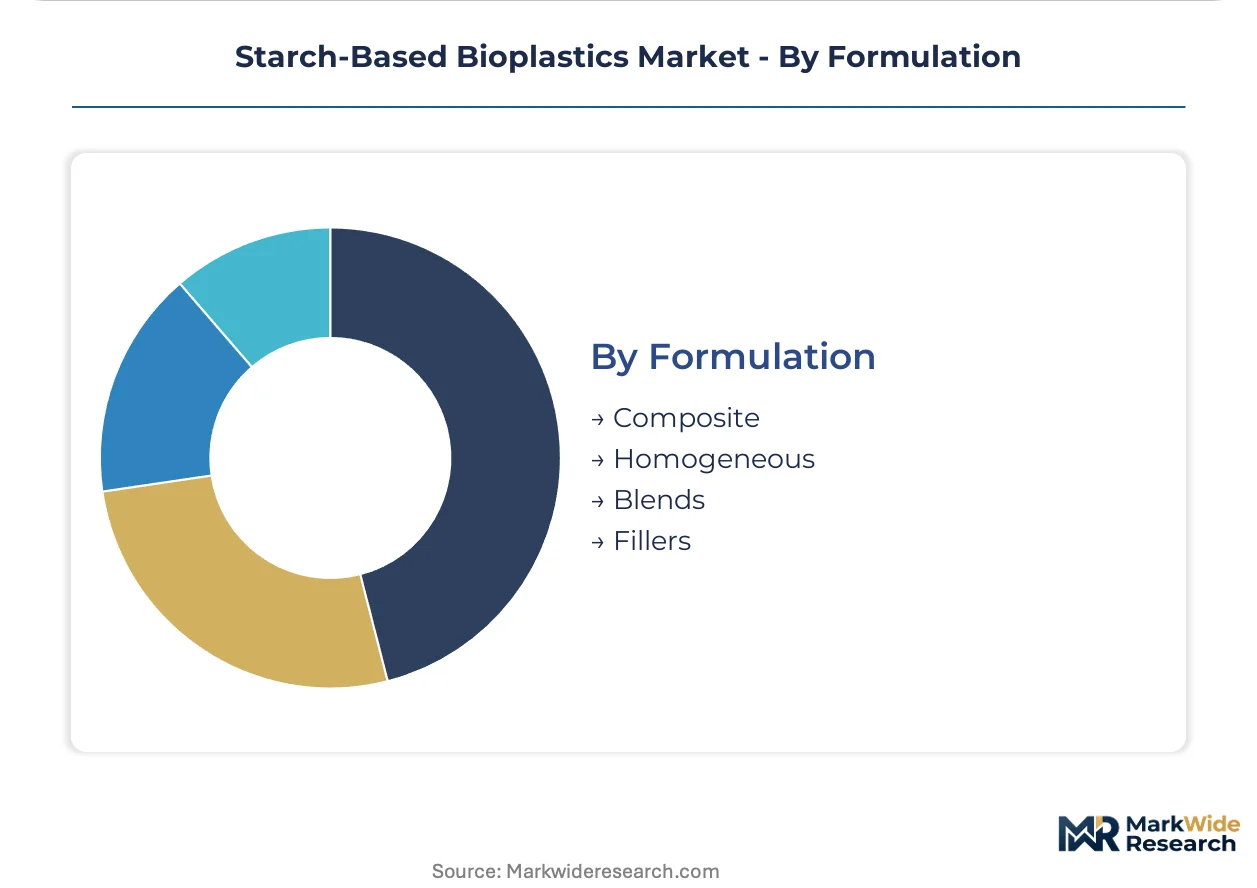
Starch-based bioplastics are thermoplastic materials derived from renewable carbohydrate feedstocks such as corn, potato, tapioca, or pea starch, typically plasticized with glycerol or sorbitol and processed at moisture levels below fifteen percent to achieve melt processability. These materials serve primarily as drop-in replacements for conventional polyolefins in applications requiring certified compostability or reduced carbon intensity. Injection Molded products occupy the largest volume share due to established tooling compatibility with existing polymer processing equipment. Packaging applications lead value generation, though Agriculture segments are expanding fastest as mulch film regulations tighten across the European Union. Composite formulations capture premium positioning by combining starch matrices with cellulose reinforcements to overcome brittleness limitations in high-humidity environments.
The European Chemicals Agency enforces REACH compliance for starch-based additives migrating into food contact materials, while the FDA maintains separate biopolymer clearance pathways through its food contact notification system in the United States. Germany's national packaging regulator implements the EU Single-Use Plastics Directive through extended producer responsibility fees that advantage certified compostable alternatives. Stakeholders must monitor how divergent biodegradability certification standards between OK Compost and BPI reshape cross-border product qualification requirements.
Market Dynamics
The EU Green Deal's packaging waste directives are compressing virgin plastic thresholds and mandating renewable content floors, forcing material substitution decisions across European food packaging supply chains before fossil-plastic cost parity is achieved.
Growth Catalysts
- EU Single-Use Plastics Directive:Germany's extended producer responsibility fees advantage certified compostable alternatives, accelerating quick-service restaurant procurement of starch-based trays and cutlery.
- Injection molding tooling compatibility:Established polymer processing equipment accepts starch-based feedstocks without retooling, lowering conversion barriers for packaging converters.
- Quick-service restaurant chains:Food and beverage end users are scaling compostable procurement across European franchise networks to meet corporate sustainability commitments.
Market Restraints
- Moisture sensitivity:Starch-based materials require processing below fifteen percent moisture to achieve melt processability, limiting high-humidity applications without cellulose reinforcement.
- Glycerol and sorbitol price volatility:Plasticizer input costs fluctuate with agricultural commodity cycles, compressing margins for compounders without captive supply.
- REACH compliance burden:The European Chemicals Agency enforces additive migration testing for food contact materials, extending qualification timelines for new formulations.
Strategic Opportunities
- Agricultural mulch films:EU regulations tightening biodegradable mulch standards create demand rotation from packaging into specialty agriculture applications.
- OK Compost certification expansion:Cross-border product qualification under harmonized biodegradability standards opens white space in Benelux and Nordic markets.
- Cellulose-starch composites:Converging reinforcement technologies with thermoplastic starch matrices overcome brittleness limitations in wet environments.
Industry Challenges
- Biodegradability certification divergence:OK Compost and BPI maintain incompatible testing protocols, forcing dual qualification investments for exporters.
- Fermentation complex capex:Pharmaceutical-grade PLA-starch blend production requires integrated fermentation and purification assets with long commissioning cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Starch-Based Bioplastics Market |
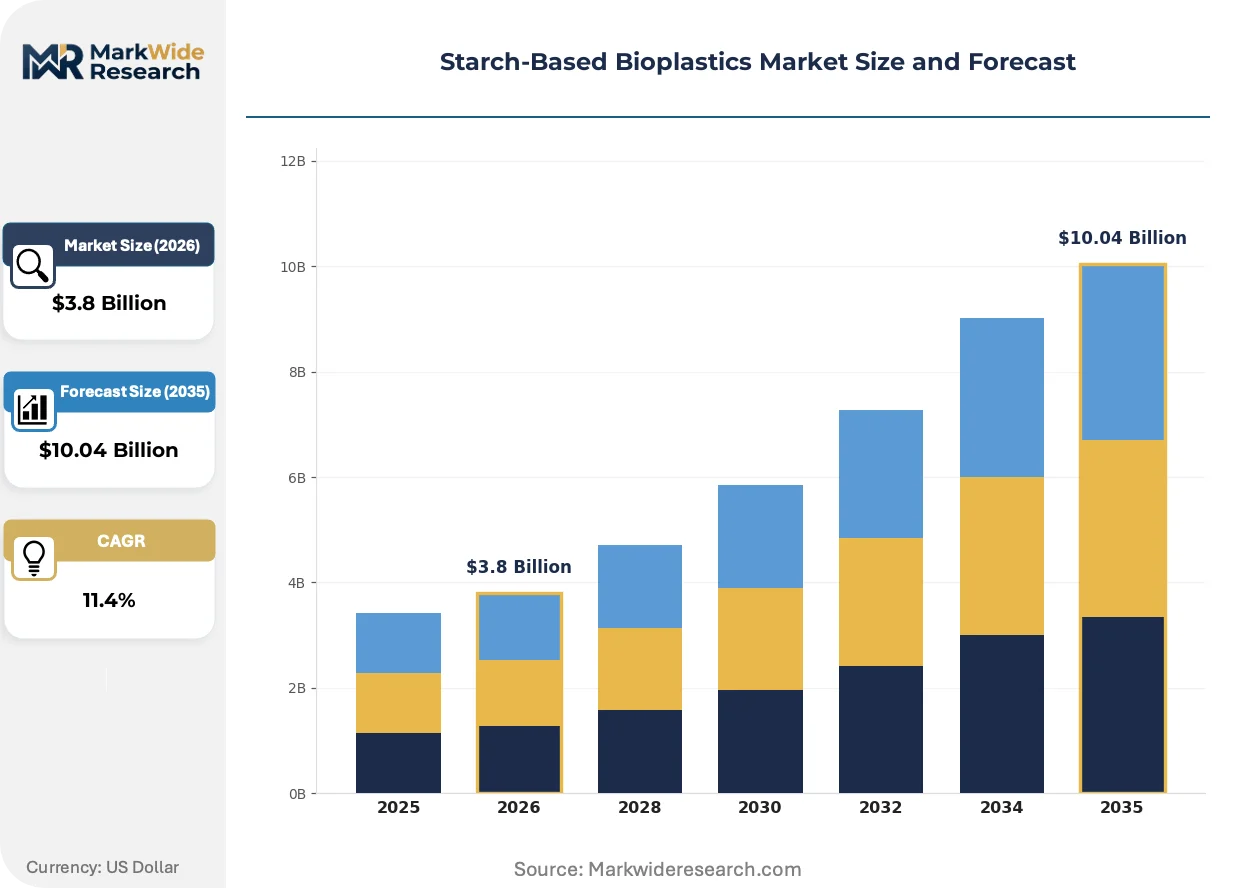
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injection Molded, Extruded, Blown Film, Coatings Application: Packaging, Agriculture, Consumer Goods, Automotive End User: Food and Beverage, Electronics, Medical, Textile Formulation: Composite, Homogeneous, Blends, Fillers |
| Companies Covered | TotalEnergies Corbion, Biome Bioplastics, BASF SE, KURARAY, Braskem, NatureWorks LLC, Mitsubishi Chemical Holding Corporation, Roquette Frères, Novamont SpA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Starch-Based Bioplastics Market Strategic Shifts
Material science advances and regulatory compression are collapsing the traditional separation between drop-in bioplastics and performance-engineered compounds, reshaping how compounders position starch-based formulations against fossil-derived alternatives.
Thermoplastic starch-cellulose composites are unifying structural reinforcement with compostable matrices to overcome humidity-induced brittleness. Packaging converters in Northern Europe are adopting these hybrid materials for fresh produce applications where condensation resistance is mandatory. This convergence is compressing the performance gap between starch-based and conventional polyolefins in demanding environments.
The EU Green Deal's packaging waste directives are mandating recycled and renewable content thresholds that fossil-plastic cannot satisfy without chemical recycling investments. Food contact material suppliers face reformulation deadlines that favor starch-based alternatives with established compostability certification. German quick-service restaurant chains are responding with accelerated procurement timelines for certified compostable cutlery and trays.
Certification-driven preference shifts are displacing price-only procurement in European food packaging. Buyers now require OK Compost or BPI verification before contract award, filtering uncertified suppliers from approved vendor lists. This behavioral change concentrates demand among compounders with in-house biodegradability testing capabilities, particularly visible in German and French retail supply chains.
Starch-Based Bioplastics Market Segmentation
Segmentation in starch-based bioplastics separates volume manufacturing from premium positioning. Processing method determines tooling compatibility and unit economics, while application focus dictates certification requirements and customer procurement criteria.
Product Type:
Injection molding commands volume share through existing polymer equipment compatibility, while blown film and extruded formats serve specialized barrier and structural applications.
- Injection Molded:Thermoplastic starch compounds process on standard single-screw extruders with minimal die modifications. Quick-service restaurant chains in Germany specify injection-molded cutlery and trays for EU Single-Use Plastics Directive compliance.
- Extruded:Continuous profile production enables sheet and foam formats for protective packaging. Sheet extruders near Rotterdam and Antwerp supply fresh produce trays to Benelux retail chains requiring OK Compost certification.
- Blown Film:Biaxial orientation produces thin-gauge mulch films and flexible pouches with controlled permeability. Agricultural applications in France and Italy drive demand for soil-biodegradable blown film formulations.
- Coatings:Aqueous starch dispersions provide paperboard barrier layers for grease resistance. Food contact coating lines in Barcelona and Milan serve Mediterranean corrugated packaging converters.
Today's leader: Injection Molded. Tomorrow's challenger: Blown Film.
Application:
Packaging generates dominant value through food contact certification premiums, though agriculture applications are expanding fastest as EU mulch film regulations tighten.
- Packaging:Rigid containers, flexible pouches, and foam protective formats replace polyolefins in fresh produce and dry goods. German and French supermarket private labels mandate compostable primary packaging for own-brand products.
- Agriculture:Mulch films, nursery pots, and crop support stakes eliminate retrieval labor and soil contamination. Italian tomato and strawberry growers in Emilia-Romagna convert to soil-biodegradable mulch under regional agricultural subsidy programs.
- Consumer Goods:Disposable tableware, hygiene product components, and cosmetic applicators leverage starch-based compostability claims. Nordic retail chains prioritize consumer goods with BPI or OK Compost verification for shelf placement.
- Automotive:Interior trim panels, seat cushioning, and temporary protective films utilize thermoplastic starch for carbon intensity reduction. Stuttgart-area automotive suppliers test starch-based foams for headliner applications.
Packaging retains revenue concentration. Agriculture climbs the fastest trajectory.
End User:
Food and beverage procurement scales through corporate sustainability mandates, while medical and electronics segments impose stricter purity and performance specifications.
- Food and Beverage:Quick-service restaurants, catering operators, and packaged food manufacturers specify certified compostable serviceware and primary packaging. McDonald's franchise networks across Germany, Austria, and Switzerland have accelerated starch-based tray procurement timelines.
- Electronics:Anti-static trays, temporary component carriers, and protective foams require controlled conductivity and moisture resistance. Semiconductor assemblers in Dresden and Leuven qualify starch-based alternatives for cleanroom logistics.
- Medical:Single-use instruments, pharmaceutical packaging, and diagnostic consumables demand USP Class VI or ISO 10993 biocompatibility. Novamont's pharmaceutical-grade PLA-starch blends target Milan-area medical device manufacturers.
- Textile:Fiber-grade thermoplastic starch enables nonwoven fabrics and temporary stitching yarns. Technical textile producers in Northern Italy evaluate starch-based fibers for agricultural geotextile applications.
Food and Beverage anchors volume. Medical commands margin premiums.
Formulation:
Homogeneous starch matrices serve cost-sensitive commodity applications, while composite and blend formulations capture performance-driven segments requiring humidity resistance or mechanical durability.
- Composite:Cellulose fiber or lignin reinforcement overcomes brittleness in high-moisture environments. Fresh produce packaging converters in the Netherlands adopt cellulose-starch composites for condensation-prone supply chains.
- Homogeneous:Pure thermoplastic starch with glycerol or sorbitol plasticizers serves single-use cutlery and dry-goods packaging. Basque Country compounders supply homogeneous formulations to Iberian quick-service restaurant chains.
- Blends:Starch-PLA or starch-PBAT alloys balance processability with biodegradation kinetics. French flexible packaging producers blend thermoplastic starch with PBAT for tear-resistant pouch films.
- Fillers:Mineral or bio-based particulates reduce material cost and modify thermal properties. Injection molders in Poland incorporate calcium carbonate fillers for rigid food service containers.
Composite formulations gain share fastest. Homogeneous grades defend volume position.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chemical engineers and Italian polymer scientists anchor European starch-based bioplastics innovation. Their proximity to industrial starch processing infrastructure and fermentation expertise concentrates supply-side capability in specific national clusters.
Germany
Quick-service restaurant procurement and automotive lightweighting drive German demand. The national packaging regulator implements extended producer responsibility fees under the EU Single-Use Plastics Directive. BASF SE operates integrated pilot lines near potato starch refining hubs in Ludwigshafen.
Italy
Pharmaceutical-grade PLA-starch blends and agricultural mulch films concentrate Italian production. Regional subsidy programs in Emilia-Romagna accelerate soil-biodegradable mulch conversion for tomato and strawberry growers. Novamont SpA leverages fermentation complexes near Milan for medical device supply chains.
France
Flexible packaging producers and fresh produce retailers shape French procurement patterns. The EU Green Deal's renewable content mandates force reformulation deadlines for food contact materials. Compounders near Lyon supply PBAT-starch blends for tear-resistant pouch films to supermarket private labels.
Netherlands
Benelux retail chains and condensation-resistant packaging converters dominate Dutch demand. OK Compost certification requirements filter supplier qualification for cross-border product distribution. Sheet extruders near Rotterdam supply certified compostable trays to supermarket distribution networks.
United States
Food contact notification pathways and biopolymer clearance systems structure American market entry. The FDA maintains separate regulatory tracks for starch-based additives migrating into packaging materials. NatureWorks LLC anchors North American PLA-starch blend supply from fermentation assets in Blair, Nebraska.
Starch-Based Bioplastics Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the starch-based bioplastics value chain. The market structure tilts toward consolidation among compounders with captive starch refining and fermentation assets. Three archetypes dominate: integrated chemical conglomerates with backward control over agricultural feedstocks, mid-scale biopolymer specialists with certification laboratory capabilities, and regional compounders serving quick-service restaurant procurement networks. Capacity expansion and strategic partnerships constitute the primary competitive moves, particularly for securing pharmaceutical-grade production qualifications.
Among European integrated players, BASF SE and Novamont SpA exemplify divergent scale strategies. BASF SE occupies a position anchored in industrial chemical manufacturing breadth. Novamont SpA represents the focused biopolymer specialist archetype with concentrated fermentation expertise. Roquette Frères sits within the agricultural processing tier, leveraging upstream control over pea and maize starch extraction to secure feedstock security for compounder customers.
| Leading Market Players |
|---|
| TotalEnergies Corbion |
| Biome Bioplastics |
| BASF SE |
| KURARAY |
| Braskem |
| NatureWorks LLC |
| Mitsubishi Chemical Holding Corporation |
| Roquette Frères |
| Novamont SpA |
| Others |
Value Chain & Pricing Dynamics
Backward integration into potato and maize starch refining anchors pricing power for European compounders serving quick-service restaurant procurement networks. BASF SE and Roquette Frères leverage captive agricultural processing assets to buffer margin compression from glycerol and sorbitol plasticizer volatility.
Pricing Analysis
Certification-bundled versus unbundled supply splits the market into contract tiers. Three-tier pricing structure across pharmaceutical-grade, food-contact, and commodity homogeneous formulations reflects OK Compost and BPI qualification investments. Pricing pressure stems from REACH compliance testing extending formulation qualification timelines. Quick-service restaurant chains exhibit highest price sensitivity, while medical device manufacturers absorb premium positioning for USP Class VI biocompatibility.
Supply Chain Analysis
Starch feedstock supply rests on German, Italian, and French agricultural processing infrastructure. Potato starch from the Benelux region, maize starch from Northern Italy, and pea starch from Roquette's French extraction facilities constitute primary inputs. Single-source vulnerability concentrates in pharmaceutical-grade fermentation assets near Milan. Distribution runs through Rotterdam and Antwerp sheet extruders serving Benelux retail chains with OK Compost-certified tray formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Green Deal packaging waste directives mandate renewable content floors that fossil-plastic cannot satisfy without chemical recycling investments.
For Market Incumbents: Cement backward control over fermentation and purification assets to defend against mid-scale biopolymer specialists with certification laboratory capabilities. Expand pharmaceutical-grade PLA-starch blend capacity near Milan-area medical device clusters. Prioritize in-house biodegradability testing capabilities to filter uncertified competitors from approved vendor lists.
For New Entrants and Emerging Players: E-commerce direct sourcing platforms offer white-space entry into quick-service restaurant procurement networks lacking transparent price discovery. Target Benelux and Nordic markets where OK Compost certification expansion opens cross-border distribution. Lead with cellulose-starch composite formulations for condensation-resistant fresh produce packaging.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale compounders with certification laboratory capabilities because EU Single-Use Plastics Directive implementation fragments demand across national extended producer responsibility schemes. Five-to-ten year viability hinges on fermentation complex asset ownership. Watch for OK Compost and BPI protocol harmonization as inflection signal for cross-border scale economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Starch Refining | Captive potato and maize feedstock secures margin stability against agricultural commodity cycles. |
| Pharmaceutical-Grade Fermentation Capacity | Milan-area medical device manufacturers demand USP Class VI PLA-starch blend supply security. |
| OK Compost Certification Investment | German and French supermarket private labels mandate verification before contract award. |
| Cellulose-Starch Composite Development | Dutch fresh produce converters adopt hybrid materials for condensation-prone supply chains. |
| Quick-Service Restaurant Direct Supply Agreements | McDonald's franchise networks across Germany accelerate procurement timelines for certified compostable serviceware. |
Study Parameters
Bottom-up food and beverage procurement modeling reconciled against top-down compounder capacity tracking forms the analytical core. Primary interviews with plant managers at starch refining facilities, procurement leads at quick-service restaurant chains, technical R&D directors at packaging converters, and certification laboratory managers combined with secondary validation from EU packaging waste directive filings, ECHA REACH registration databases, customs trade data, and SEC 10-K disclosures from diversified chemical conglomerates.
Historical trendline analysis across injection molded, extruded, blown film, and coating product formats informed projection frameworks. Segmentation dimensions encompassed processing method, application focus, end-user industry, and formulation type across the analysis window. CAGRs derived from capacity expansion announcements, fermentation complex commissioning timelines, and agricultural starch processing yield assumptions.
The model assumes a particular technology adoption path; alternative pathways for thermoplastic starch-cellulose composite convergence would alter the outlook. Forecasts reflect assumptions about EU regulatory harmonization and biodegradability certification standard alignment. Agricultural commodity price volatility and REACH compliance burden escalation warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioplastics
Automotive Bioplastic Market
Bioplastics
Bio-PET Market
Bioplastics
US Bioplastics Market
Bioplastics
Global Bio-Based PET Market
Bioplastics
North America Bioplastics Market
Bioplastics
Global Synthetic and Bio Based Biodegradable Plastics Market
Bioplastics
Biopolymer Films Market
Bioplastics
Compostable Phone Cases Market
Bioplastics
Global Bioresorbable (Resorbable) Polymers Market
Bioplastics
Bioplastics and Biopolymers Market
Bioplastics
China Bioplastics Market
Bioplastics
Bioplastic Textile Market
Bioplastics
Bio-Based Polyolefins Market
Bioplastics
Global Green and Bio-Based Plastic Additives Market
Bioplastics
Biopolymers Market
Bioplastics
Polyhydroxyalkanoate (PHA) Market