
 Hydrotalcite Market | 2026-2036
Hydrotalcite Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrotalcite Market Outlook
Technical support and formulation consulting is restructuring how hydrotalcite suppliers capture value beyond commodity sales. Sakai Chemical Industry Co., Ltd. leverages its integrated magnesium sourcing to dominate synthetic hydrotalcite supply for Japanese PVC processors. Kyowa Chemical Industry Co., Ltd. anchors the pharmaceutical-grade segment through dedicated excipient certification programs. Clariant AG competes in European flame retardant applications with halogen-free additive portfolios.
Hydrotalcite is a layered double hydroxide with the general formula Mg₆Al₂(OH)₁₆CO₃·4H₂O, synthesized through co-precipitation or hydrothermal methods to achieve controlled anion exchange capacity for acid scavenging and thermal stabilization. Its primary commercial purpose centers on neutralizing hydrochloric acid release during PVC processing and serving as an active pharmaceutical ingredient in antacid suspensions. Synthetic hydrotalcite commands the largest volume share due to consistent purity and tunable magnesium-aluminum ratios demanded by automotive wire coating specifications. Modified hydrotalcite variants represent the fastest-expanding product category as surface-treated grades penetrate high-temperature polyolefin applications. Pharmaceutical intermediates application generates premium pricing relative to plastic additives, though the latter absorbs substantially greater tonnage.
REACH registration requirements in the European Union and FDA excipient monograph standards in the United States impose batch-level traceability and residual heavy metal limits that elevate compliance costs for synthetic hydrotalcite manufacturers. China's GB standards for plastic additives and Japan's PMDA pharmaceutical material guidelines create divergent certification pathways that fragment supplier qualification regimes. Stakeholders must monitor evolving halogen-free flame retardant mandates in automotive and electronics sectors to anticipate substitution effects on hydrotalcite demand trajectories.
Market Dynamics
REACH compliance deadlines in the European Union are compressing supplier qualification timelines while Japanese pharmaceutical manufacturers accelerate excipient-grade hydrotalcite procurement, creating divergent purity premiums across Atlantic and Pacific supply corridors.
Growth Catalysts
- Halogen-free flame retardant mandates:Automotive wire harness specifications in Germany and Japan now exclude brominated additives, redirecting formulation demand toward magnesium-aluminum layered double hydroxides.
- PVC stabilizer consumption in East Asia:Polyvinyl chloride processors in China and South Korea are expanding modified hydrotalcite purchases for high-temperature cable insulation applications.
- FDA excipient monograph alignment:Antacid suspension manufacturers in the United States are qualifying synthetic hydrotalcite batches against tightened residual heavy metal thresholds.
Market Restraints
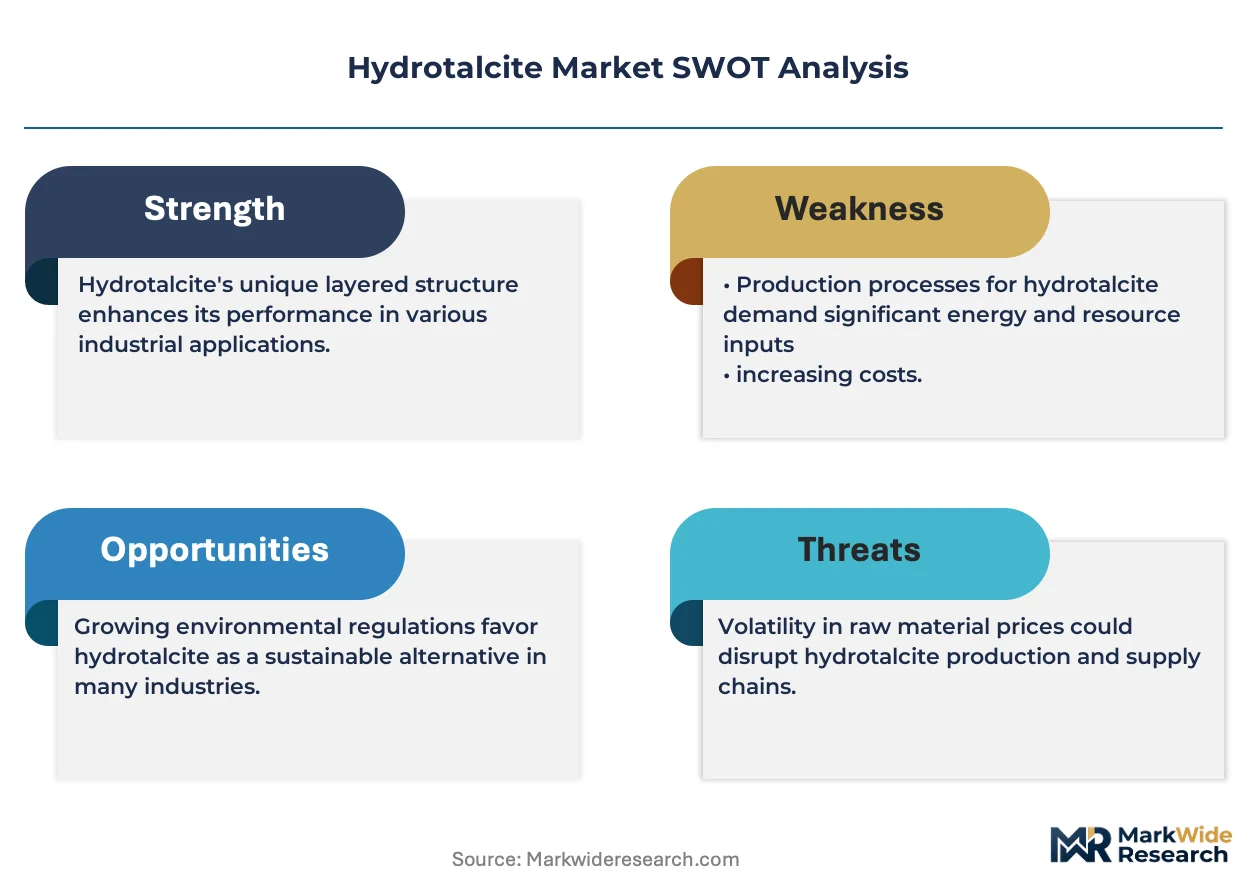
- Magnesium feedstock volatility:Synthetic hydrotalcite production depends on magnesium oxide or hydroxide chloride pricing, which fluctuates with Chinese smelter output and energy cost spikes.
- Supplier concentration in Japan:Two integrated chemical conglomerates control the majority of pharmaceutical-grade hydrotalcite capacity, creating single-source risk for European and North American formulators.
- Zeolite substitution in detergents:Builders and ion-exchange applications increasingly specify zeolite A or P over hydrotalcite for cost-sensitive powder formulations.
Strategic Opportunities
- Polyolefin high-temperature stabilization:Surface-treated hydrotalcite grades are penetrating automotive under-hood compounds in Germany and the United States, displacing conventional acid scavengers.
- Carbon capture material adaptation:Layered double hydroxide structures are being re-engineered for direct air capture sorbent applications, opening industrial gas processing demand.
- India pharmaceutical excipient registration:CDSCO filing pathways for antacid APIs remain underpenetrated by synthetic hydrotalcite specialists, offering first-mover positioning.
Industry Challenges
- Batch-level traceability infrastructure:REACH Article 33 and FDA Drug Master File requirements demand serialized documentation systems that mid-scale manufacturers lack.
- Anion exchange capacity standardization:No harmonized ISO test method exists for comparing acid neutralization performance across hydrotalcite grades, complicating buyer technical evaluation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrotalcite Market |
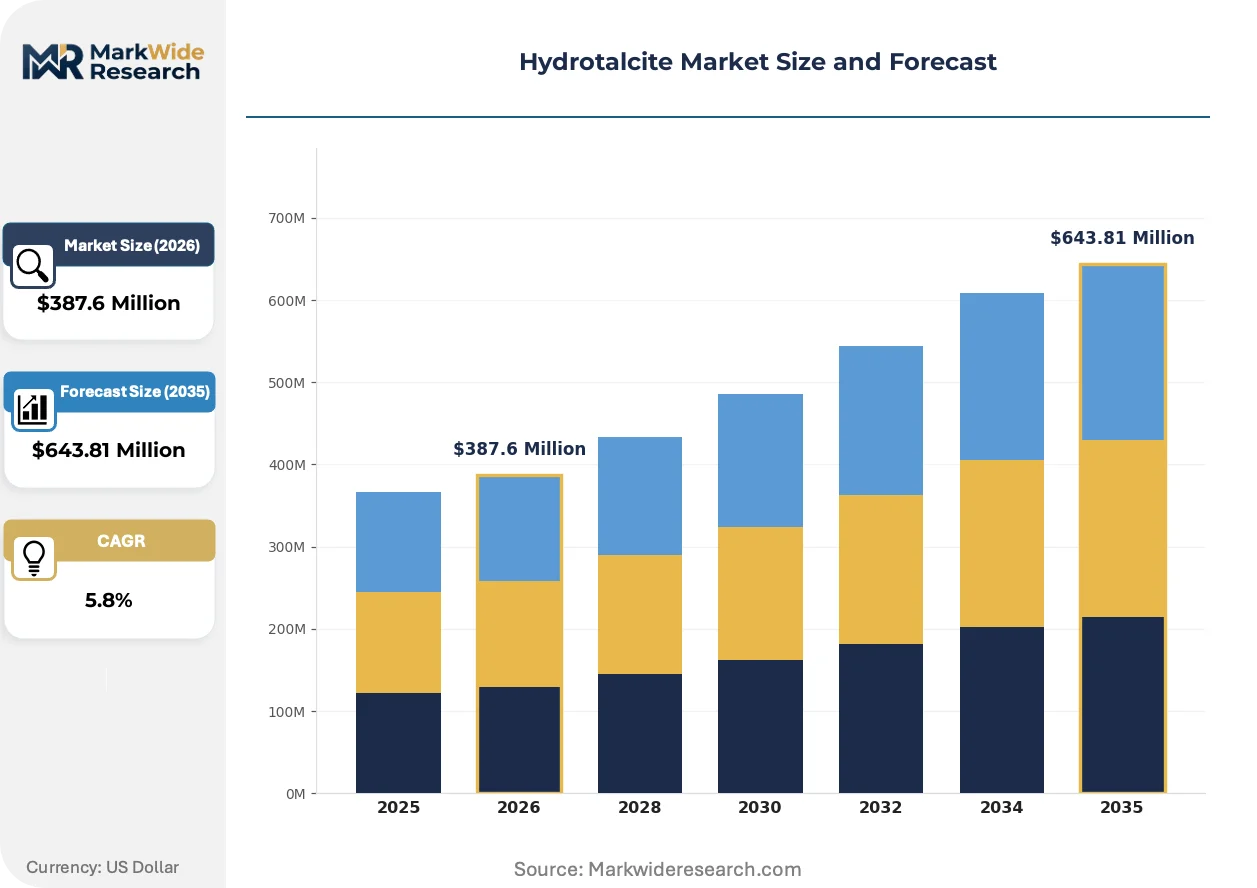
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Basic Hydrotalcite, Synthetic Hydrotalcite, Natural Hydrotalcite, Modified Hydrotalcite Application: Plastic Additives, Pharmaceutical Intermediates, Catalysts, Flame Retardants End User: Pharmaceuticals, Plastics, Construction, Agriculture Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Sakai Chemical Industry Co., Ltd., Akzo Nobel N.V., Kyowa Chemical Industry Co., Ltd., Arkema S.A., Solvay S.A., Clariant AG, Sinwon Chemical, GCH Technology, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrotalcite Market Strategic Shifts
Surface functionalization chemistry and regulatory-driven formulation substitution are restructuring competitive advantage around tunable anion exchange performance rather than commodity magnesium-aluminum ratios.
Organo-modified hydrotalcite is absorbing hydrophobic polymer compatibility requirements through interlayer gallery modification with stearate or phosphate anions. Automotive compounders in Germany and Japan are specifying these grades for polypropylene and polyamide heat stabilization. The technology is absorbing margin compression in conventional PVC additive markets by commanding 15-30% price premiums for engineered dispersion characteristics.
REACH authorization list expansion is forcing flame retardant formulators to document SVHC-free supply chains for hydrotalcite-containing compounds. ECHA notifications now require downstream communication when magnesium-aluminum hydroxycarbonates exceed 0.1% w/w in finished articles. Wire and cable manufacturers in Italy and Poland are responding by pre-qualifying synthetic grades with full substance composition disclosure.
Technical service unbundling is separating formulation consulting from material supply contracts. Japanese PVC processors now expect supplier laboratories to validate heat stability performance in customer-specific compound recipes before purchase commitment. This pattern concentrates procurement authority with compounders possessing in-house rheometry and colorimetry capabilities, visible across Osaka and Nagoya industrial clusters.
Hydrotalcite Market Segmentation
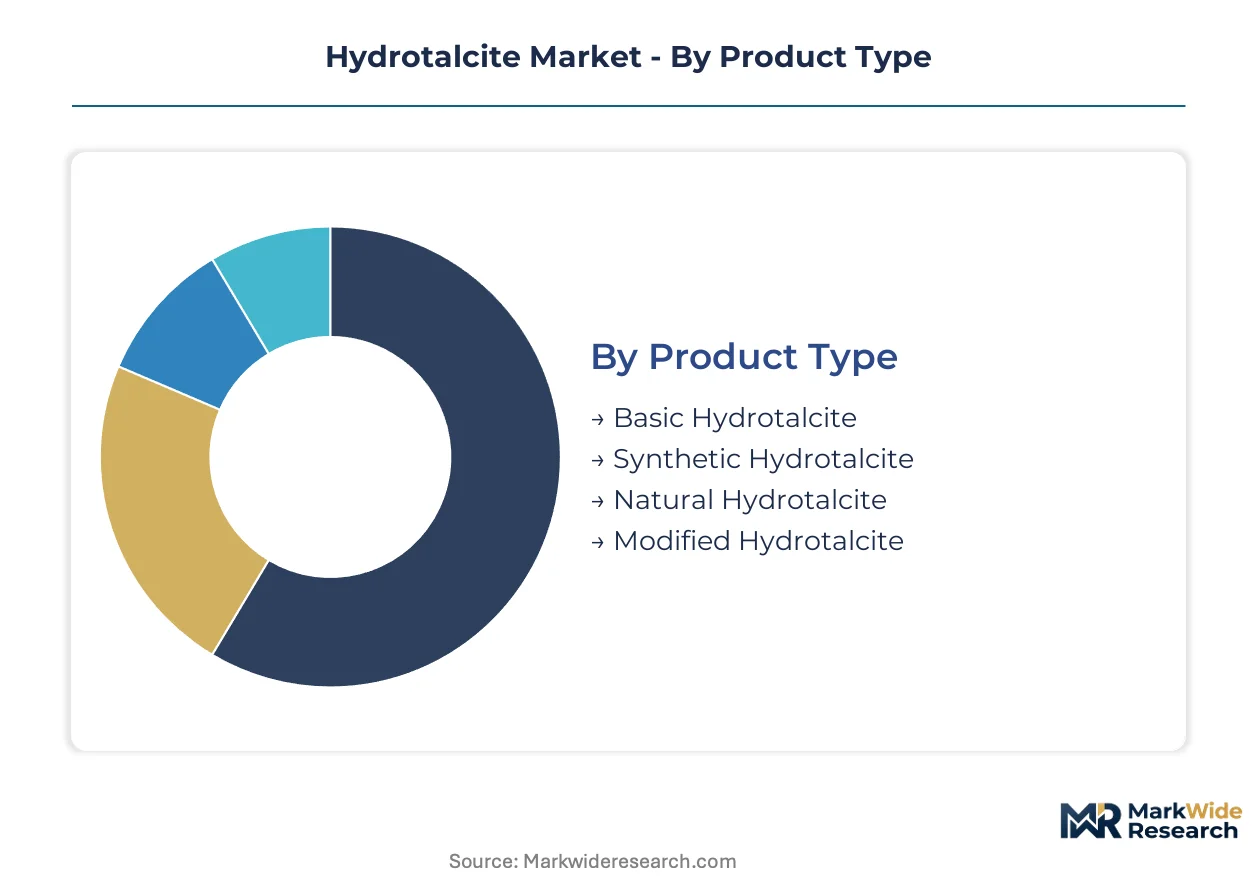
Hydrotalcite suppliers compete across distinct specification tiers where integration depth varies from standalone acid scavengers to embedded pharmaceutical formulations. Segmentation strategy determines margin capture, with synthetic grades commanding purity premiums and modified variants penetrating engineered polymer systems.
Product Type:
Standalone hydrotalcite grades serve commodity PVC stabilization, while surface-engineered variants embed into complex polymer matrices requiring dispersion compatibility.
- Basic Hydrotalcite:Standard magnesium-aluminum layered double hydroxide produced through co-precipitation without surface treatment. Demand concentrates in Chinese PVC cable manufacturers seeking cost-efficient hydrochloric acid neutralization during high-temperature extrusion.
- Synthetic Hydrotalcite:Manufactured via controlled hydrothermal synthesis to achieve tunable Mg/Al ratios and consistent carbonate interlayer spacing. Pharmaceutical formulators in Japan and Germany specify these grades for antacid excipient applications requiring batch-level heavy metal documentation.
- Natural Hydrotalcite:Mined deposits with variable mineral purity limit commercial viability to niche ceramic and refractory applications in Turkey and India.
- Modified Hydrotalcite:Surface-treated with stearate or phosphate anions to enhance hydrophobic polymer compatibility. Automotive under-hood compounders in Germany specify these grades for polypropylene heat stabilization.
Volume placements concentrate in Synthetic Hydrotalcite; the faster expansion belongs to Modified Hydrotalcite.
Application:
Cost tier stratification separates commodity plastic additives from premium pharmaceutical intermediates, with catalyst applications occupying a mid-tier technical position.
- Plastic Additives:PVC heat stabilizers and acid scavengers for wire coating specifications. East Asian cable manufacturers in China and South Korea drive bulk procurement of hydrotalcite for lead-free formulation transitions.
- Pharmaceutical Intermediates:Antacid active pharmaceutical ingredient requiring excipient-grade certification. Japanese PMDA and US FDA monograph compliance elevates purity thresholds and documentation burdens for suppliers.
- Catalysts:Base catalyst support and anion exchange media for fine chemical synthesis. German specialty chemical producers utilize hydrotalcite-derived materials in pharmaceutical intermediate manufacturing.
- Flame Retardants:Halogen-free synergist in polyolefin and elastomer compounds. REACH SVHC restrictions and automotive wire harness mandates in Germany redirect formulation demand from brominated alternatives.
Revenue concentration sits with Plastic Additives; Pharmaceutical Intermediates delivers the steepest margin expansion.
End User:
Customer type fragmentation reflects divergent procurement authority, with pharmaceutical formulators demanding technical service integration and construction buyers prioritizing volume scale.
- Pharmaceuticals:Antacid suspension manufacturers and solid dosage formulators. CDSCO registration pathways in India remain underpenetrated relative to established US and Japanese markets.
- Plastics:PVC processors and polyolefin compounders. Japanese integrated chemical conglomerates dominate supply relationships through captive technical service laboratories.
- Construction:Cement and concrete additive applications leveraging acid neutralization capacity. Chinese infrastructure spending supports regional demand for hydrotalcite as chloride scavenger.
- Agriculture:Slow-release fertilizer coating and soil amendment applications. Limited commercial penetration relative to industrial segments.
Procurement volume aggregates in Plastics; Pharmaceuticals generates the premium pricing differential.
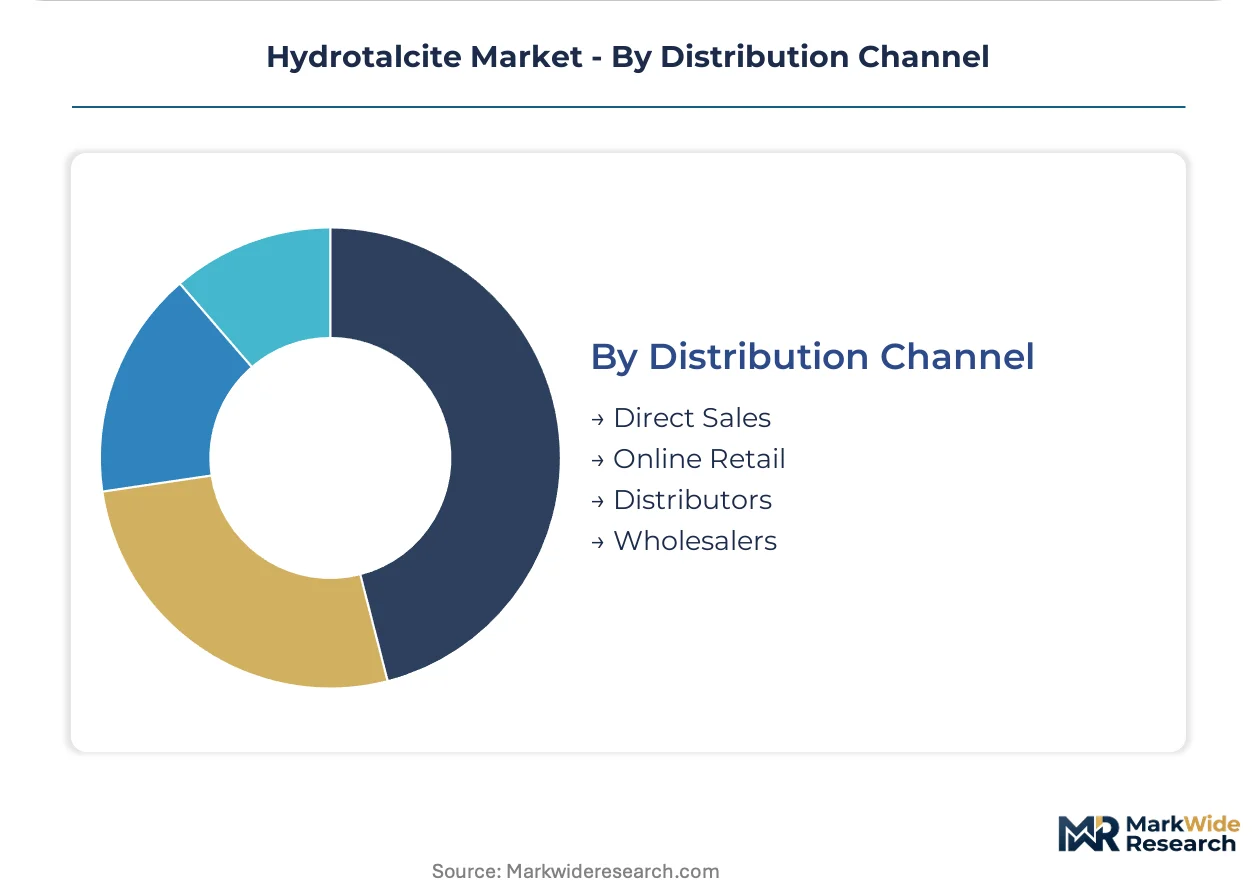
Distribution Channel:
Supply concentration dynamics favor direct relationships for specification-grade material, while commodity grades flow through distributor networks.
- Direct Sales:Long-term supply agreements with pharmaceutical and automotive compounders. Japanese PVC processors require pre-qualification testing in supplier laboratories before contract execution.
- Online Retail:Limited to laboratory-scale quantities and research-grade material. European REACH documentation requirements complicate cross-border e-commerce for industrial volumes.
- Distributors:Regional stocking for standard-grade plastic additives. Italian and Polish wire and cable manufacturers source through specialized polymer additive distributors.
- Wholesalers:Bulk material aggregation for construction and agricultural applications. Chinese domestic market fragmentation supports wholesaler intermediation.
Contract value concentrates in Direct Sales; Distributors handle the greatest transaction frequency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian manufacturers consume the majority of hydrotalcite output for PVC stabilization, while European and North American pharmaceutical formulators drive premium-grade procurement. Japanese and German chemical conglomerates dominate high-purity synthesis capacity. Chinese smelter output fluctuations ripple through magnesium feedstock pricing worldwide.
China
Polyvinyl chloride cable manufacturers in Jiangsu and Zhejiang provinces drive bulk hydrotalcite consumption for lead-free heat stabilization. GB standards for plastic additives mandate residual heavy metal documentation that elevates compliance costs for domestic suppliers. Qingdao and Ningbo industrial clusters host integrated magnesium oxide producers supplying captive hydrotalcite synthesis.
Germany
Automotive wire harness specifications from KBA now exclude brominated flame retardants, redirecting formulation demand toward magnesium-aluminum layered double hydroxides. REACH authorization list expansion forces compounders to document SVHC-free supply chains for hydrotalcite-containing materials. Cologne and Leverkusen chemical parks concentrate halogen-free additive development laboratories serving BMW and Volkswagen supply chains.
Japan
PMDA pharmaceutical material guidelines elevate excipient-grade purity thresholds that concentrate procurement with integrated chemical conglomerates. METI industrial standards for PVC stabilizers drive modified hydrotalcite specification in high-temperature automotive applications. Osaka and Nagoya industrial clusters host supplier laboratories pre-qualifying heat stability performance in customer-specific compound recipes.
United States
FDA excipient monograph alignment tightens residual heavy metal thresholds for antacid suspension manufacturers qualifying synthetic hydrotalcite batches. EPA industrial chemical oversight intersects with state-level environmental regulations governing magnesium processing emissions. Gulf Coast petrochemical corridors absorb modified hydrotalcite grades for polyolefin under-hood compounds in Detroit and Tennessee automotive supply chains.
India
CDSCO filing pathways for antacid APIs remain underpenetrated by synthetic hydrotalcite specialists relative to established US and Japanese markets. BIS certification requirements for pharmaceutical excipients create divergent qualification timelines from Western regulatory frameworks. Gujarat and Maharashtra pharmaceutical manufacturing clusters present first-mover positioning opportunities for excipient-grade suppliers.
Hydrotalcite Market Competitive Environment
Top-tier vendors anchor pharmaceutical-grade and engineered polymer segments, while mid-scale producers compete on commodity PVC additive volumes. Japanese integrated chemical conglomerates control the majority of excipient-grade capacity through captive magnesium sourcing and dedicated certification programs. European specialty chemical groups compete in flame retardant applications with halogen-free portfolios. Dominant competitive moves include backward integration into magnesium feedstock and technical service unbundling that separates formulation consulting from material supply contracts.
Within the integrated chemical conglomerate tier, Sakai Chemical Industry Co., Ltd. and Kyowa Chemical Industry Co., Ltd. exemplify Japanese producers leveraging domestic magnesium sourcing and PMDA certification infrastructure. Clariant AG occupies a position representing European specialty chemical groups competing in REACH-compliant flame retardant formulations. These three entities anchor distinct competitive vectors: captive raw material control, pharmaceutical-grade certification depth, and regional regulatory alignment respectively.
| Leading Market Players |
|---|
| Sakai Chemical Industry Co., Ltd. |
| Akzo Nobel N.V. |
| Kyowa Chemical Industry Co., Ltd. |
| Arkema S.A. |
| Solvay S.A. |
| Clariant AG |
| Sinwon Chemical |
| GCH Technology |
| BASF SE |
| Others |
Value Chain & Pricing Dynamics
Excipient-grade certification ladders in pharmaceutical hydrotalcite bifurcate sharply from commodity PVC stabilizer tiers, with PMDA and FDA documentation burdens embedding cost premiums that synthetic-grade suppliers in Japan and Germany translate into long-term offtake contracts, while Chinese bulk processors compete on magnesium oxide feedstock arbitrage and spot-market flexibility.
Pricing Analysis
Margin tightening in pharmaceutical-grade hydrotalcite reflects PMDA batch-traceability infrastructure investments that synthetic manufacturers in Osaka and Nagoya must recover through excipient-certification premiums. Three-tier pricing structure across premium, standard, and economy levels separates FDA-monograph-compliant antacid APIs from GB-standard PVC additives and unmodified construction-grade material. Cost compression in commodity stabilizers accelerates because Chinese magnesium smelter output fluctuations transmit directly into hydroxide chloride pricing. Construction buyers in Jiangsu province exhibit the highest price sensitivity, while Japanese pharmaceutical formulators prioritize documentation reliability over unit cost.
Supply Chain Analysis
Return flows of spent hydrotalcite from PVC extrusion operations remain negligible, though Japanese compounders in Nagoya industrial clusters increasingly specify closed-loop magnesium recovery from post-industrial scrap. Supply concentrates in China, Japan, and Germany, with Qingdao and Ningbo hosting integrated magnesium oxide-to-hydrotalcite synthesis, Osaka and Nagoya anchoring pharmaceutical-grade finishing, and Cologne-Leverkusen chemical parks specializing in flame-retardant compounding. Synthetic production draws from magnesium hydroxide chloride, aluminum nitrate, and sodium carbonate feedstocks. Single-source vulnerability concentrates in Japanese pharmaceutical-grade capacity controlled by two integrated conglomerates. Distribution runs through direct long-term contracts for specification-grade material and regional distributors for commodity PVC additives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hydrotalcite market is becoming a vertical-integration race as synthetic-grade manufacturers pursue captive magnesium oxide supply to insulate margin structures from Chinese smelter volatility and energy cost spikes.
For Market Incumbents: Acquire magnesium oxide production assets or hydrothermal synthesis patents to lock in feedstock cost predictability against Chinese energy price fluctuations. Secure PMDA and FDA Drug Master File registrations for excipient-grade batches before REACH authorization list expansion tightens SVHC documentation requirements. Defensive consolidation should target mid-scale European flame-retardant compounders facing REACH compliance cost escalation. For New Entrants and Emerging Players: Surface-functionalization chemistry for polyolefin heat stabilization offers a technology-first wedge into automotive under-hood applications in Germany and the United States. CDSCO pharmaceutical excipient registration in India presents the most penetrable geography, with Gujarat and Maharashtra manufacturing clusters lacking qualified synthetic hydrotalcite suppliers. Go-to-market positioning should emphasize pre-qualification testing in customer-specific compound recipes, mirroring Japanese technical service unbundling. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated specialists possessing captive magnesium sourcing and dual pharmaceutical-plastic additive certification infrastructure, given halogen-free flame retardant mandate acceleration in automotive wire harness specifications. Long-term viability across the projection horizon hinges on regulatory alignment depth rather than commodity volume scale. Monitor ECHA SVHC notification thresholds and KBA automotive specification revisions as inflection indicators for substitution-driven demand shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Magnesium Feedstock | Captive hydroxide chloride supply insulates Japanese and German synthetic-grade producers from Chinese smelter volatility. |
| Pharmaceutical Excipient Certification Expansion | PMDA and FDA Drug Master File registrations unlock premium pricing in antacid API formulations. |
| Surface Functionalization R&D Investment | Stearate and phosphate interlayer modification penetrates automotive polypropylene stabilization in Germany. |
| REACH-Compliant Supply Chain Documentation | SVHC-free substance disclosure secures wire and cable manufacturer pre-qualification in Italy and Poland. |
| CDSCO Registration in India | First-mover excipient-grade positioning captures Gujarat and Maharashtra pharmaceutical manufacturing demand. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this hydrotalcite market assessment, cross-referenced with primary interviews involving PVC plant managers in Jiangsu and Zhejiang, pharmaceutical procurement leads at Japanese and German antacid manufacturers, technical R&D directors at flame-retardant compounders in Cologne and Leverkusen, and distribution channel partners serving Italian wire and cable producers. Bottom-up triangulation of synthetic-grade production volumes and top-down validation against magnesium oxide consumption patterns ensured segmentation coherence across product type, application, and end-user dimensions.
Data-stream reconciliation across customs export records, PMDA pharmaceutical material registration databases, and ECHA REACH authorization notifications informed the analytical framework throughout the projection horizon. Segmentation modeling captured grade-tier stratification, end-use industry fragmentation, regional production hub concentration, and certification-level differentiation. CAGRs derived from volume-weighted average growth trajectories across plastic additive, pharmaceutical intermediate, catalyst, and flame-retardant application clusters, with specific adjustment for PVC cable demand in East Asia and antacid formulation trends in North America.
Several conditions sit outside the modeled scope, including potential zeolite substitution acceleration in detergent builders, breakthrough direct air capture sorbent commercialization, and abrupt magnesium oxide trade policy shifts. Forecasts reflect assumptions regarding REACH authorization timeline adherence and FDA excipient monograph stability. Practitioners should monitor ECHA SVHC list expansion velocity, KBA automotive wire harness specification revisions, and Chinese dual carbon policy implementation intensity for early signals warranting forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Opacifiers Market
Specialty Compounds
Film Dressing Market
Specialty Compounds
Microcapsules Market
Specialty Compounds
Global Specialty Amines Market
Specialty Compounds
Global Molding Compounds Market
Specialty Compounds
Acrylic Pad Market
Specialty Compounds
Saudi Arabia Collagen Market
Specialty Compounds
Saudi Arabia Masterbatch Market
Specialty Compounds
Thermoset Molding Compounds Market
Specialty Compounds
Quinoline Yellow WS Market
Specialty Compounds
Strontium Nitrate Market
Specialty Compounds
Thiocolchicoside Market
Specialty Compounds
Global Antifreeze Proteins Market
Specialty Compounds
Global Customized Premixes Market
Specialty Compounds
Germany Collagen Market
Specialty Compounds
Compounds Market