
 Furniture Foam Market | 2026-2036
Furniture Foam Market Size, Share, and Industry Trends Forecast 2026-2036
Furniture Foam Market Analysis
Residential buyers is collapsing toward premium memory foam configurations as hospitality procurement softens in select Western markets. Covestro AG leverages its polycarbonate precursor network to secure isocyanate supply chains for European foam converters. Carpenter Company anchors North American production through dedicated plants in Richmond and Conway. Sheela Foam Limited dominates India's branded mattress segment with Sleepwell and Kurlon distribution.
Furniture foam comprises cellular polymer structures engineered from polyurethane, latex, or viscoelastic compounds with densities ranging from 16 to 80 kilograms per cubic meter, produced via continuous slabstock or molded reaction injection processes to deliver specified indentation force deflection and resilience for load-bearing comfort applications. Polyurethane Foam leads volume production due to cost scalability across seating and bedding platforms, while Memory Foam commands margin concentration in premium residential channels. High Density grades capture institutional and hospitality specifications where durability cycles exceed residential benchmarks.
EPA oversees volatile organic compound emissions from foam manufacturing under Clean Air Act provisions, while REACH restricts certain isocyanate and flame retardant chemistries in European supply chains, and California's Bureau of Electronic and Appliance Repair directs flammability testing protocols that de facto shape North American formulation standards. Stakeholders must monitor regulatory divergence between flame retardant regimes as biomaterial feedstocks gain technical viability.
Market Dynamics
California's TB 117-2013 flammability mandate continues to force reformulation across polyurethane supply chains, compressing legacy flame retardant chemistries while elevating phosphorus-based alternatives in upholstered seating specifications.
Growth Catalysts
- REACH isocyanate restrictions:European REACH regulation on methylene diphenyl diisocyanate exposure limits accelerates closed-cell process adoption among converters seeking compliance certainty.
- Residential memory foam migration:North American household buyers gravitate toward viscoelastic mattress configurations, pulling slabstock demand toward higher-density specifications.
- Guangdong manufacturing clustering:China's concentrated foam fabrication capacity around Foshan and Dongguan generates scale economies that feed export upholstery programs.
Market Restraints
- Toluene diisocyanate price volatility:Petrochemical feedstock swings compress converter margins unpredictably, particularly for small-batch custom seating producers.
- Polyol supply concentration:Asia-Pacific polyether polyol manufacturing clusters create geographic single-point vulnerability for European and North American foam molders.
- Natural latex substitution pressure:Botanical latex from rubber plantations competes for premium mattress positioning, constraining polyurethane share in eco-positioned retail channels.
Strategic Opportunities
- India's branded mattress penetration:Organized retail expansion in tier-two Indian cities creates whitespace for certified foam suppliers beyond unorganized sector competition.
- EU Green Deal circularity mandates:Extended producer responsibility frameworks for furniture end-of-life incentivize recyclable foam chemistry development.
- Digital direct-to-installer channels:E-procurement platforms for hospitality FF&E buyers disintermediate traditional distributor markups in contract seating.
Industry Challenges
- Certified fire-testing backlog:TB 117-2013 compliance documentation delays at California Bureau of Electronic and Appliance Repair stretch product launch timelines for new formulations.
- Legacy blowing agent retrofit costs:Hydrofluorocarbon phase-down requirements force capital-intensive equipment upgrades at continuous slabstock plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Furniture Foam Market |
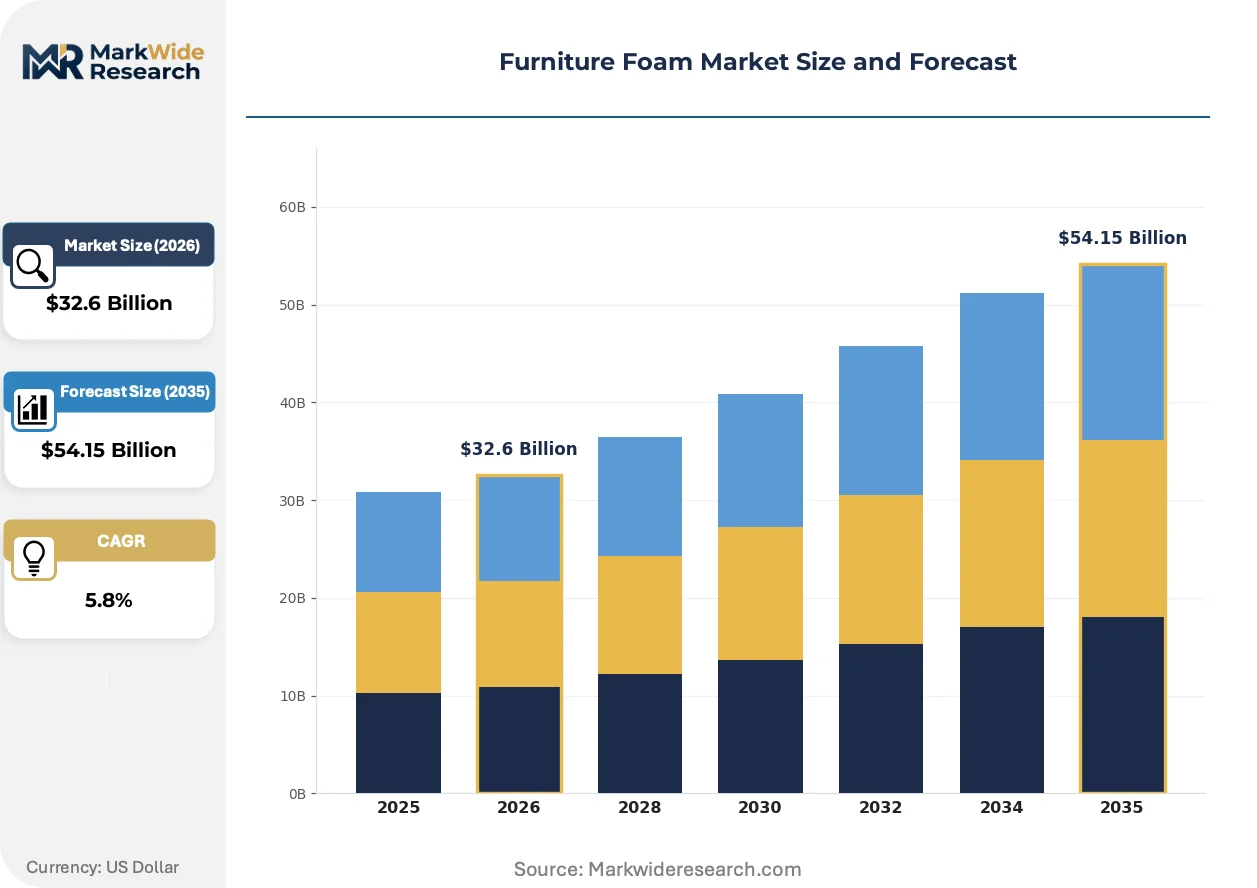
| Market Size in 2026 | $32.6 Billion |
| Market Size in 2035 | $54.15 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane Foam, Latex Foam, Memory Foam, Polyester Fiber Foam Density: Low Density, Medium Density, High Density, Extra High Density Application: Seating, Bedding, Upholstery, Acoustic Treatment End User: Residential, Commercial, Hospitality, Institutional |
| Companies Covered | BASF SE, Carpenter Company, Covestro AG, Dow Inc., Huntsman International LLC, Recticel, Sealed Air Corporation, Sheela Foam Limited, The Woodbridge Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Furniture Foam Market Emerging Trajectories
Bio-based feedstock integration and digital manufacturing controls are actively restructuring how foam converters align material properties with end-use performance specifications.
Plant-derived polyol formulations derived from soybean and castor oil feedstocks are decomposing petroleum dependency in flexible polyurethane production. European bedding manufacturers accelerate adoption to satisfy EU Green Deal procurement criteria. This chemistry shift is compressing carbon intensity metrics across supply chain reporting while maintaining indentation force deflection tolerances.
REACH authorization requirements for flame retardant substances reshape additive selection across upholstered furniture supply chains. The restriction of decabromodiphenyl ether and related halogenated compounds forces phosphorus-nitrogen synergist adoption. North American converters now align formulation strategies with European hazard classifications to maintain cross-Atlantic product uniformity.
Contract hospitality buyers consolidate vendor panels around full-service foam-to-finished-furniture suppliers. Traditional component-only procurement fragments as hotel chains seek single-source accountability for durability warranties. This consolidation concentrates specification influence among large FF&E procurement consortia operating across North American and European property portfolios.
Furniture Foam Market Segmentation
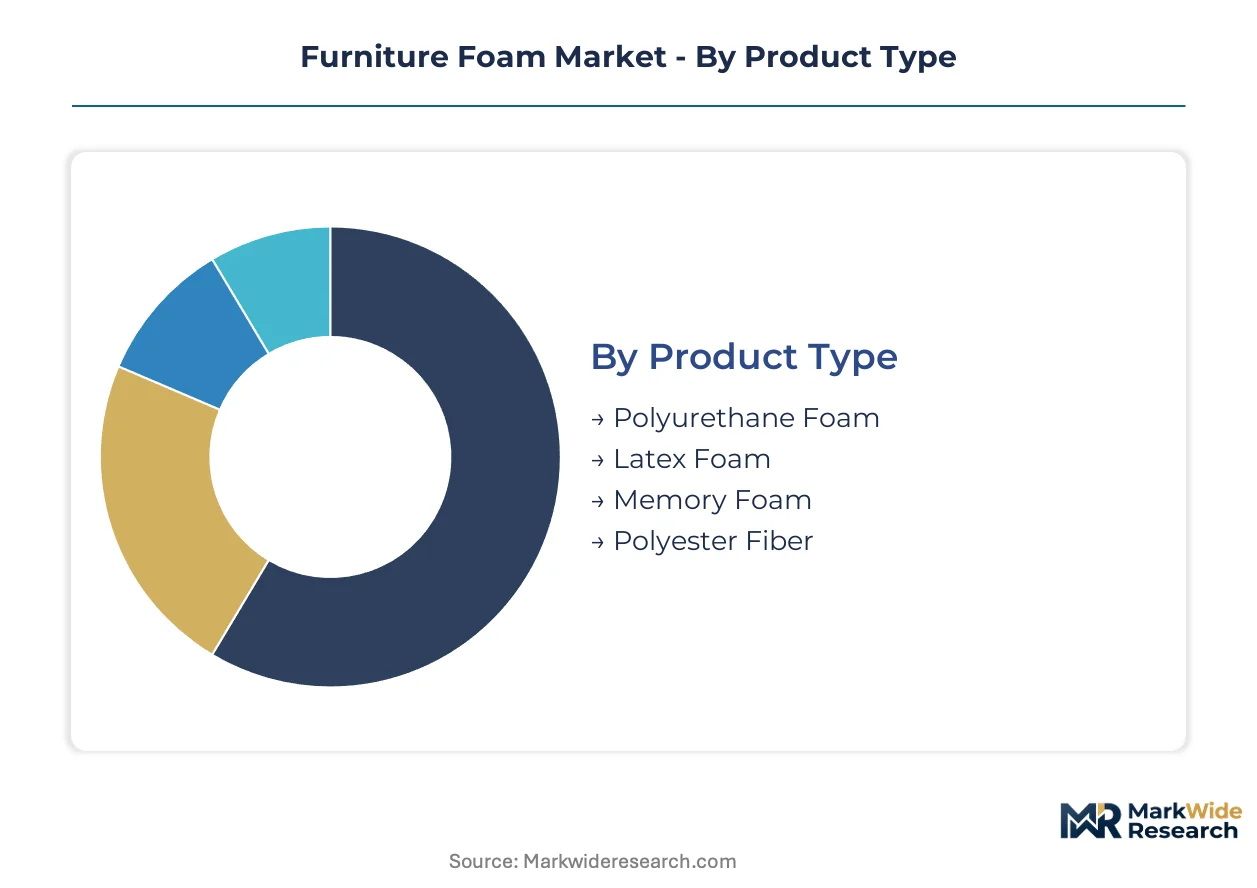
Foam converters align production configurations with distinct channel requirements. Specification intensity, certification burden, and volume scale vary sharply across residential retail, contract hospitality, and institutional procurement pathways.
Product Type:
Channel mix splits sharply: polyurethane feeds high-volume seating and bedding through mass retail and contract furniture distributors, while memory foam and latex command premium residential mattress showrooms and direct-to-consumer digital channels.
- Polyurethane Foam:Open-cell flexible polyurethane dominates slabstock production for seating cushions and mattress cores. Residential furniture manufacturers in China's Guangdong cluster absorb the majority of commodity-grade output, though California TB 117-2013 compliance costs are compressing margins for non-certified converters.
- Memory Foam:Viscoelastic polyurethane formulations with slow recovery properties target premium mattress channels. North American household buyers drive specification migration toward higher-density configurations, pulling demand away from traditional innerspring systems.
- Latex Foam:Natural rubber-derived cellular structures serve botanical-positioned mattress retailers. Dunlop and Talalay process variants compete for eco-certification recognition in European and North American specialty channels.
- Polyester Fiber:Thermally bonded synthetic fiber fills budget upholstery and acoustic panel applications. Institutional buyers specify these materials for cost-sensitive seating refresh cycles in educational and healthcare facilities.
By volume, Polyurethane Foam leads. By growth pace, Memory Foam is ahead.
Foam Density:
Cost tier stratification determines converter equipment allocation and raw material procurement patterns. Low-density formulations serve price-driven retail channels, while high-density grades capture specification-driven contract segments with extended durability requirements.
- Low Density:Open-cell structures below 24 kg/m³ fill disposable seating and packaging applications. Mass-market furniture retailers in India and Southeast Asia absorb volume shipments for entry-level sofa programs.
- Medium Density:24-40 kg/m³ specifications balance cost and comfort for mainstream residential mattresses. This tier captures the largest production volume across continuous slabstock lines globally.
- High Density:40-60 kg/m³ grades meet hospitality and healthcare durability standards. Hotel FF&E procurement consortia specify these formulations for mattress replacement cycles exceeding residential benchmarks.
- Extra High Density:Above 60 kg/m³ formulations serve heavy-use institutional seating and premium orthopedic mattress cores. REACH isocyanate exposure restrictions complicate European production of these grades.
Medium Density commands the largest revenue pool. Extra High Density delivers the steepest margin expansion.
Application:
Customer type concentration shapes formulation priorities: residential buyers prioritize pressure relief and thermal comfort, while commercial and institutional procurement teams weight fire certification and lifecycle cost above tactile performance.
- Seating:Cushion cores and backrest fills for residential sofas, office task chairs, and hospitality lounge furniture. TB 117-2013 compliance documentation delays at California's testing bureau stretch launch timelines for new seating formulations.
- Bedding:Mattress cores, toppers, and pillow fills across all density grades. This application captures the highest absolute foam consumption and drives memory foam specification migration in North American and European households.
- Upholstery:Backing layers, armrest fills, and decorative cushioning for furniture frames. Upholstery foam demand concentrates in China's manufacturing clusters feeding export furniture programs.
- Acoustic Treatment:Open-cell absorptive panels for commercial interiors, recording studios, and institutional common areas. Polyester fiber and reticulated polyurethane variants compete for architectural specification.
Bedding generates the highest tonnage. Acoustic Treatment is climbing the fastest as commercial interior retrofit activity accelerates.
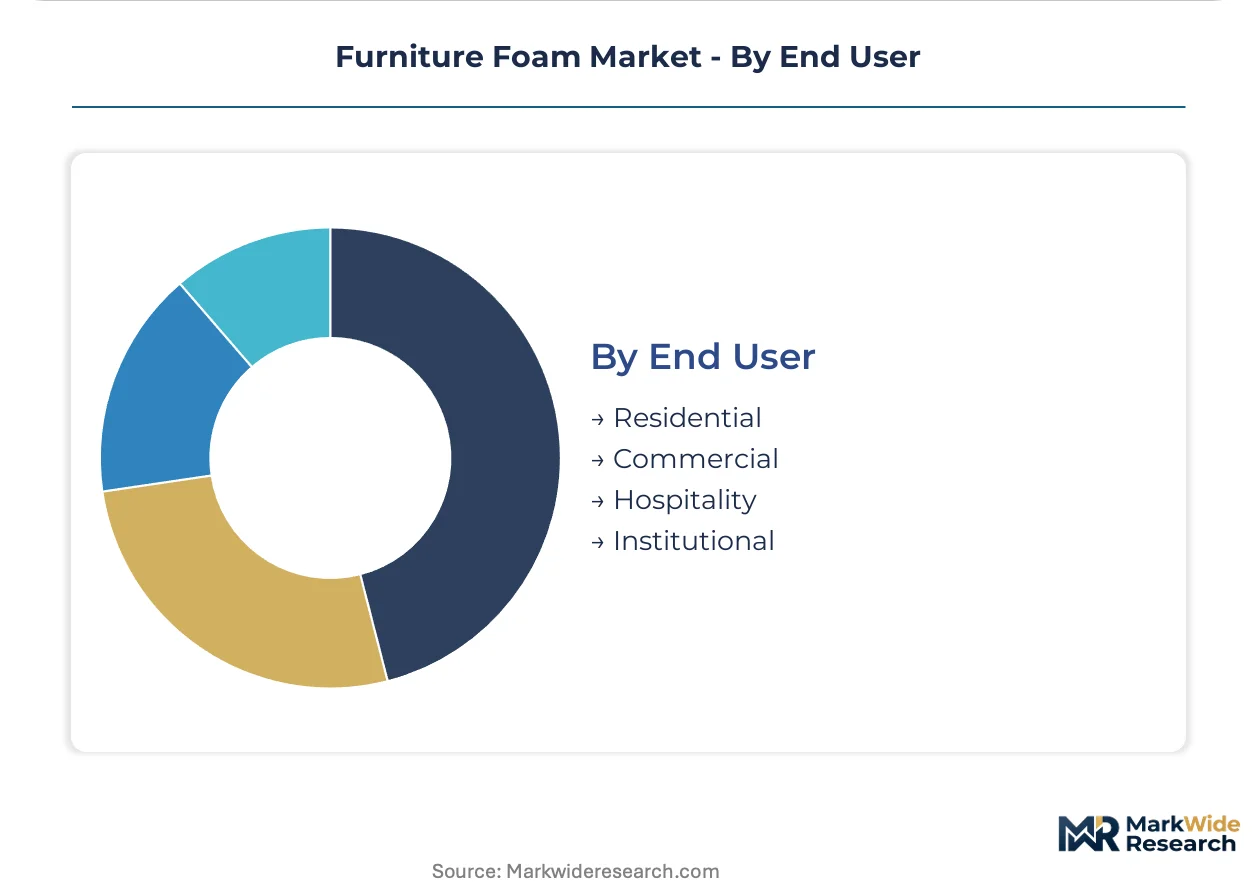
End User:
Geography and maturity differentiate procurement behavior: residential channels fragment across branded and unorganized retail, while hospitality and institutional buyers consolidate vendor panels around full-service suppliers.
- Residential:Individual households purchasing through furniture retailers, mattress specialty stores, and e-commerce platforms. Memory foam mattress penetration is expanding fastest among urban middle-income buyers in India and China's tier-two cities.
- Commercial:Corporate offices, co-working spaces, and retail environments procuring task seating and lounge furniture. Commercial buyers prioritize bulk pricing and rapid fulfillment over material specification sophistication.
- Hospitality:Hotel chains, resorts, and cruise lines sourcing FF&E through procurement consortia. These buyers consolidate around foam-to-finished-furniture suppliers seeking single-source durability warranties.
- Institutional:Healthcare facilities, educational institutions, and government entities with extended procurement cycles. Institutional specifications demand certified fire performance and documented lifecycle cost analysis.
Residential channels absorb the greatest volume. Hospitality procurement is gaining share fastest as hotel development rebounds in select markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Guangdong and Zhejiang manufacturing clusters export finished foam components to North American residential furniture retailers and European hospitality procurement networks, establishing the dominant east-west trade corridor in upholstered seating supply chains.
United States
California's TB 117-2013 flammability mandate forces phosphorus-based flame retardant adoption across polyurethane formulations. The EPA oversees volatile organic compound emissions under Clean Air Act provisions at domestic slabstock plants. High-density memory foam demand concentrates in North Carolina and Virginia manufacturing corridors serving premium mattress channels.
China
Foshan and Dongguan fabrication clusters generate scale economies feeding export upholstery programs for global furniture brands. The Ministry of Ecology and Environment enforces dual carbon goals that constrain petrochemical feedstock expansion. Guangdong province anchors half of Asia-Pacific flexible polyurethane output through integrated polyol-to-foam converter networks.
Germany
REACH isocyanate restrictions on methylene diphenyl diisocyanate exposure accelerate closed-cell process adoption among converters. Covestro AG leverages its polycarbonate precursor network to secure regional supply chain continuity. The North Rhine-Westphalia chemical corridor hosts formulation R&D for EU Green Deal compliant recyclable foam chemistries.
India
Tier-two city retail expansion creates whitespace for certified foam suppliers beyond unorganized sector competition. The Bureau of Indian Standards governs furniture safety and flammability testing protocols. Sheela Foam Limited anchors branded mattress distribution through Sleepwell and Kurlon retail networks penetrating Maharashtra and Karnataka urban markets.
Belgium
Extended producer responsibility frameworks under EU Green Deal circularity mandates incentivize recyclable foam chemistry development. The European Chemicals Agency coordinates REACH authorization requirements affecting flame retardant substance selection. Recticel operates flexible foam fabrication serving contract hospitality buyers consolidating vendor panels across European property portfolios.
Furniture Foam Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and geographic coverage dimensions. The vendor base fragments across chemical conglomerates, dedicated foam converters, and regional bedding specialists. Three archetypes dominate: integrated petrochemical suppliers controlling upstream isocyanate supply, pure-play foam fabricators focusing on formulation customization, and mattress brand owners backward-integrating into captive foam production. Competitive moves concentrate on strategic partnerships for bio-based feedstock access and geographic expansion into underpenetrated Indian and Southeast Asian retail channels.
Among chemical conglomerates, BASF SE and Covestro AG exemplify integrated suppliers leveraging polycarbonate and polyurethane precursor networks. Dow Inc. occupies a position bridging commodity chemical production and specialty foam formulation. These three listed entities anchor the supply-side structure through control of methylene diphenyl diisocyanate and polyether polyol manufacturing capacity that converters depend on for formulation consistency.
| Leading Market Players |
|---|
| BASF SE |
| Carpenter Company |
| Covestro AG |
| Dow Inc. |
| Huntsman International LLC |
| Recticel |
| Sealed Air Corporation |
| Sheela Foam Limited |
| The Woodbridge Group |
| Others |
Supply Flow & Price Mechanics
California's TB 117-2013 flammability regime gates both supplier qualification and price differentiation simultaneously, as phosphorus-based flame retardant compliance separates certified converters from commodity slabstock producers while hospitality buyers pay premiums for documented fire-performance traceability.
Pricing Analysis
Prior-generation commodity polyurethane slabstock, current-generation medium-density viscoelastic formulations, and next-generation bio-based polyol foams occupy distinct pricing tiers. Three-tier pricing structure across premium, standard, and economy levels tracks certification burden and density grade, with TB 117-2013 compliance documentation adding cost to California-bound shipments. Cost compression in economy-grade open-cell seating intensifies because Indian and Southeast Asian mass retailers squeeze converter margins on entry-level sofa programs. Hospitality procurement consortia exhibit lowest price sensitivity due to durability warranty requirements, while Indian unorganized sector mattress buyers drive hardest bargain negotiations.
Supply Chain Analysis
Container availability fluctuations on Asia-North America trade lanes disrupt just-in-time delivery schedules for Guangdong-exported foam components feeding US furniture retailers. Manufacturing gravity centers on China, India, and Germany, with Foshan and Dongguan clusters anchoring half of Asia-Pacific flexible polyurethane output. Converter operations draw from methylene diphenyl diisocyanate, polyether polyol, and flame retardant additive feedstocks. Single-source vulnerability concentrates in Asia-Pacific polyether polyol manufacturing clusters. Distribution runs through contract furniture distributors, mattress specialty retailers, and direct-to-installer digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflects as hospitality FF&E procurement consortia consolidate vendor panels around full-service foam-to-finished-furniture suppliers, replacing fragmented component sourcing with single-source accountability models.
For Market Incumbents: Secure backward integration into captive isocyanate supply through partnerships with polycarbonate precursor networks like Covestro AG's European infrastructure. Defend margin position by accelerating certified fire-testing documentation at California's Bureau of Electronic and Appliance Repair to compress new formulation launch timelines against smaller custom seating producers. For New Entrants and Emerging Players: Lead with bio-based polyol formulations targeting EU Green Deal procurement criteria to differentiate from petroleum-dependent incumbents. India's tier-two city branded mattress whitespace offers most penetrable geography, with direct-to-consumer digital channels providing lowest customer acquisition cost versus traditional retail slotting fees. For Investors and Strategic Acquirers: REACH authorization requirements for flame retardant substances reshape the acquisition landscape by devaluing converters dependent on decabromodiphenyl ether chemistries. Long-term viability favors targets with phosphorus-nitrogen synergist formulation capabilities and closed-cell process equipment. Watch for EU extended producer responsibility framework implementation as circularity mandate inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Isocyanate Supply | Covestro AG's polycarbonate precursor network secures formulation consistency for European converters facing REACH restrictions. |
| Bio-Based Polyol Chemistry Development | Plant-derived feedstocks from soybean and castor oil satisfy EU Green Deal procurement criteria for circularity compliance. |
| Direct-to-Installer Digital Platform Launch | E-procurement channels disintermediate traditional distributor markups for hospitality FF&E buyers consolidating vendor panels. |
| Closed-Cell Process Equipment Upgrade | Converters adopt sealed systems to meet methylene diphenyl diisocyanate exposure limits under REACH authorization requirements. |
| Tier-Two City Distribution Expansion | Sleepwell and Kurlon retail networks penetrate Maharashtra and Karnataka urban markets beyond organized sector competition. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of trade customs data, chemical industry association reports, and regulatory filing databases through structured interviews with foam plant managers, procurement leads at downstream furniture OEMs, distribution channel partners, and technical R&D directors. Bottom-up demand modeling triangulates against top-down supply-side capacity assessments across continuous slabstock and molded reaction injection process configurations.
Segmentation dimensions modeled include foam type, density grade, application, and end-user channel across the analysis window. CAGRs derive from regression analysis of historical shipment volumes and forward projection of replacement cycle dynamics, feedstock cost trajectories, and regulatory compliance cost absorption rates. Industry-specific inputs incorporate furniture manufacturing cluster output data and hospitality FF&E procurement consortium specification trends.
Forecasts assume regulatory continuity in California TB 117-2013, EU REACH, and EPA Clean Air Act enforcement regimes; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Phenylacetyl Chloride Market
Specialty Compounds
Middle East and Africa Color Masterbatch Market
Specialty Compounds
Global Specialty Zeolites Market
Specialty Compounds
Global Powder Injection Molding (PIM) Market
Specialty Compounds
Solketal Market
Specialty Compounds
Asia-Pacific Chromatography Resins Market
Specialty Compounds
Quinidine Sulfate Market
Specialty Compounds
Automated Compound Storage and Retrieval (ACSR) Market
Specialty Compounds
Chemical Hardener Compounds Market
Specialty Compounds
Pneumatic Seal Market
Specialty Compounds
Expandable Microspheres Market
Specialty Compounds
Joint Compound Market
Specialty Compounds
Strontium Chloride Market
Specialty Compounds
Europe Microencapsulation Market
Specialty Compounds
Global Specialty Oilfield Chemicals Market
Specialty Compounds
Global Acetyls Market