
 Global Compound Management Market | 2026-2036
Global Compound Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Compound Management Market Foresight
ISO 20387 biobanking quality requirements is redrawing competitive boundaries for system suppliers. Hamilton Company leverages its integrated liquid handling robotics to dominate high-throughput screening installations. Tecan Trading AG sustains technology leadership in modular automation architectures for compound libraries. Azenta US, Inc. anchors North American service density with cryogenic storage and logistics integration.
Compound management encompasses the systematic acquisition, registration, tracking, storage, retrieval, and distribution of chemical and biological samples maintained at controlled temperatures between -20°C and -196°C for research reproducibility. Automated Systems command the largest product type position due to labor cost pressures and throughput demands at large pharmaceutical firms, while Cloud-Based Software within the technology dimension captures expanding margin pools as multi-site research networks require real-time inventory synchronization. Biotechnology applications are outpacing pharmaceutical R&D in growth velocity as gene therapy and biologics pipelines multiply sample complexity.
FDA 21 CFR Part 11 compliance requirements and EMA GMP Annex 11 data integrity standards shape procurement criteria for end users across the United States and European Union, forcing legacy system replacements. China's NMPA pharmacovigilance expansions and Japan's PMDA quality management directives add parallel compliance layers for vendors serving Asia-Pacific biopharma clusters. Stakeholders must weigh regulatory validation timelines against automation ROI as sample volumes compound across decentralized research networks.
Market Dynamics
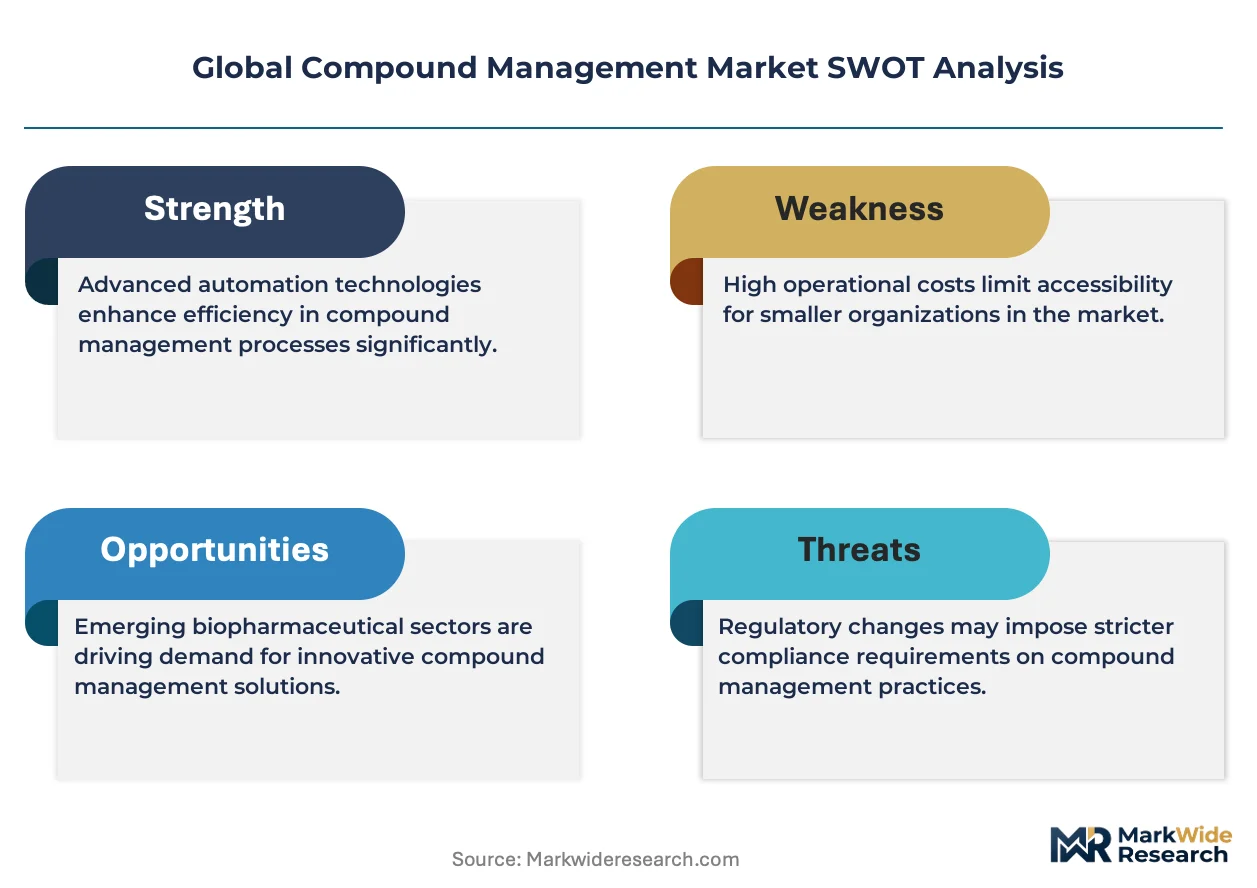
Automated liquid handling systems are compressing compound library operational costs while FDA 21 CFR Part 11 and EMA data integrity mandates force synchronized system upgrades across multi-site pharmaceutical networks.
Growth Catalysts
- Biologics Pipeline Expansion:Gene therapy developers in Boston and Basel are scaling cryogenic storage infrastructure to accommodate viral vector sample complexity. This demands integrated compound management platforms with temperature monitoring down to -196°C.
- FDA 21 CFR Part 11:Electronic records mandates are accelerating validated system procurement at contract research organizations. End-users must replace legacy inventory databases with audit-trail-compliant architectures before regulatory inspections.
- Modular Automation:Tecan's flexible liquid handling configurations allow pharmaceutical firms to reconfigure screening throughput without full platform replacement. This adaptability reduces capital risk during pipeline volatility.
Market Restraints
- Liquid Nitrogen Supply Concentration:Cryogenic infrastructure depends on regional gas supplier oligopolies in Germany and the United States. Price volatility for -196°C storage coolants constrains operating budget predictability at biobanks.
- Stainless Steel Tariff Exposure:Cold storage hardware fabrication faces input cost pressure from trade policy fluctuations. Chinese and Indian equipment vendors absorb margin compression that Western suppliers pass downstream.
- Legacy System Entrenchment:Proprietary data formats from 1990s-era compound databases resist migration to cloud-native architectures. Pharmaceutical IT departments face decade-long deprecation timelines for validated legacy inventory systems.
Strategic Opportunities
- India Biotech Corridor:CDSCO pharmacovigilance expansion and Hyderabad-Bengaluru biocluster growth create demand for ISO 20387-compliant biobanking infrastructure. Local service density remains underdeveloped relative to sample volume growth.
- AI-Assisted Compound Retrieval:Machine learning algorithms predicting sample degradation kinetics can integrate with automated storage systems. This convergence enables predictive maintenance and inventory optimization.
- Japan PMDA Quality Mandates:Revised GMP annex interpretations are forcing domestic pharmaceutical firms toward validated compound tracking. Foreign system suppliers can capture replacement cycles at mid-tier generics manufacturers.
Industry Challenges
- Cross-Domain Expertise Scarcity:Compound management operations require simultaneous competence in cryogenic engineering, regulatory validation, and laboratory informatics. Hiring pipelines for this hybrid skill profile remain thin in Boston-Cambridge and Basel-Rhine clusters.
- Multi-Site Integration Complexity:Synchronizing inventory data across decentralized research networks demands harmonization of disparate LIMS architectures. Cloud migration projects face 18-24 month validation timelines that delay ROI realization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Compound Management Market |
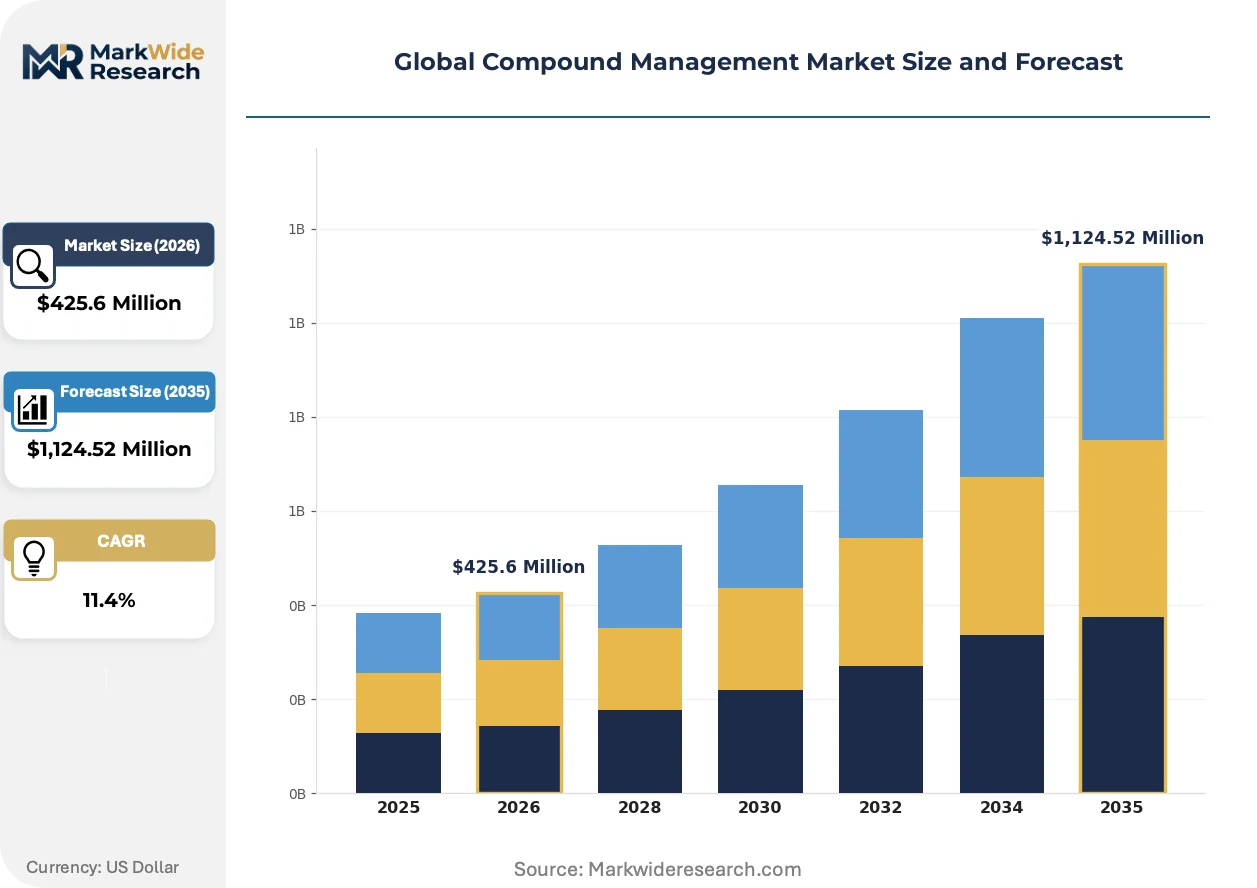
| Market Size in 2026 | $425.6 Million |
| Market Size in 2035 | $1,124.52 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Systems, Manual Systems, Hybrid Systems, Storage Solutions, Sample Tracking Equipment Technology: RFID, Barcoding, Robotics, Cloud-Based Software, Data Analytics Application: Pharmaceutical R&D, Biotechnology, Agrochemical Research, Chemical Research, Academic Research End User: Contract Research Organizations, Biotech Startups, Large Pharmaceutical Firms, Research Institutes |
| Companies Covered | Hamilton Company, Tecan Trading AG, Azenta US, Inc., Brooks Automation, SPT Labtech, LiCONiC AG, Titian Software, Evotec, Biosero, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Compound Management Market Shifts & Advancements
Acoustic liquid handling is displacing traditional pipetting robotics in high-throughput screening workflows. Cloud-native inventory platforms are enabling real-time compound tracking across geographically distributed biopharma networks. Regulatory data integrity mandates are forcing convergence between compound management software and enterprise quality systems.
Acoustic droplet ejection technology uses sound waves to transfer nanoliter-scale liquid volumes without physical contact. Large pharmaceutical firms in New Jersey and Basel are adopting acoustic dispensers for miniaturized screening assays. This approach is supplanting multi-channel pipetting robots in hit-to-lead optimization workflows, compressing compound consumption and plasticware waste.
EMA GMP Annex 11 revisions are tightening requirements for electronic signature integrity and audit trail completeness. Compound management software vendors must embed cryptographic timestamping and user access controls that satisfy both European and FDA inspectorates. Biologics developers with multi-continental manufacturing footprints face the steepest compliance burden as they harmonize quality systems across jurisdictions.
Service-based pricing models are displacing perpetual license structures for compound management software. Mid-tier biotechnology firms in South San Francisco and Cambridge prefer subscription access to cloud inventory platforms over capital-intensive on-premise deployments. This shift is most visible among gene therapy startups with variable funding cycles and unpredictable sample volume trajectories.
Global Compound Management Market Segmentation
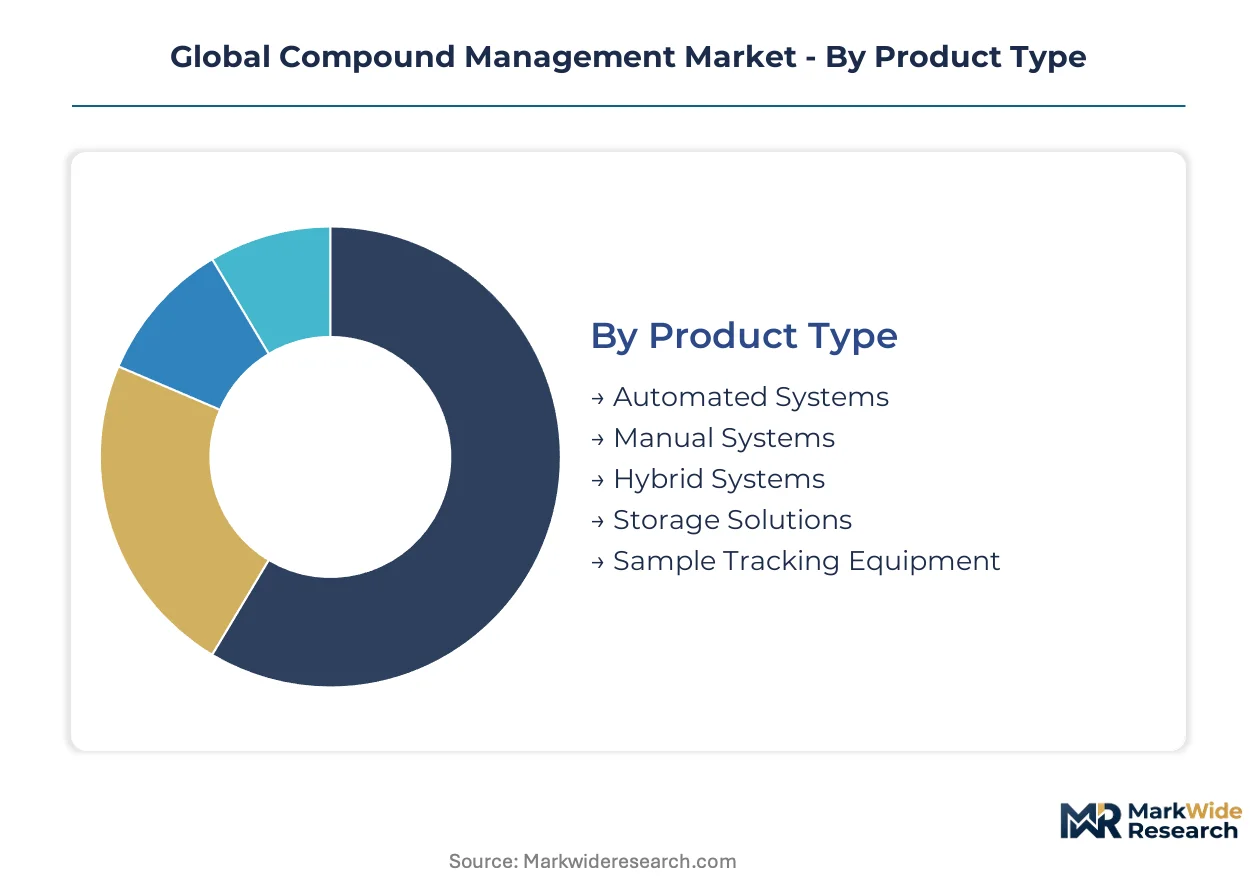
Segmentation in compound management reveals divergent technology adoption patterns between high-throughput pharmaceutical operations and resource-constrained academic settings. Procurement criteria vary sharply across end users, with regulatory compliance thresholds and sample volume throughput driving distinct equipment specifications.
Product Type:
Domestic installations dominate for manual and hybrid systems serving local biotech clusters, while automated platforms and cryogenic storage solutions flow through multinational vendor networks serving export-heavy pharmaceutical hubs.
- Automated Systems:Robotic liquid handling platforms integrate sample storage, retrieval, and preparation workflows. Large pharmaceutical firms in New Jersey and Basel deploy these systems to compress screening timelines and satisfy FDA 21 CFR Part 11 audit trail requirements. Labor cost pressures at contract research organizations accelerate replacement of manual workflows.
- Storage Solutions:Cryogenic infrastructure spans controlled-rate freezers, liquid nitrogen dewars, and automated retrieval systems maintaining -80°C to -196°C environments. Gene therapy developers in Boston and South San Francisco scale this capacity fastest as viral vector sample volumes multiply. EMA GMP Annex 11 temperature monitoring mandates tighten procurement specifications.
- Manual Systems:Benchtop storage and retrieval equipment persists in academic and early-stage biotech settings with limited sample volumes.
- Hybrid Systems:Semi-automated configurations bridge manual and fully robotic workflows for mid-tier research institutes.
- Sample Tracking Equipment:Handheld scanners and benchtop readers support barcode and RFID inventory verification at smaller facilities.
Automated Systems holds the largest share; momentum sits with Storage Solutions.
Technology:
Cost tier stratification separates capital-intensive robotics and cloud infrastructure from lower-barcode and RFID implementations accessible to budget-constrained end users.
- Cloud-Based Software:Real-time inventory synchronization platforms enable multi-site compound tracking across decentralized research networks. Biotechnology firms in Cambridge and South San Francisco adopt subscription pricing models to preserve capital for variable funding cycles. EMA data integrity mandates force cryptographic timestamping and user access control integration.
- Robotics:Articulated liquid handling arms and automated storage retrieval systems execute high-throughput screening workflows. Large pharmaceutical firms deploy these for hit-to-lead optimization at microscale volumes. Modular architectures from Tecan allow reconfiguration without full platform replacement.
- RFID:Radio-frequency identification tags enable wireless sample tracking without line-of-sight scanning requirements.
- Barcoding:Linear and 2D barcode systems remain the baseline for cost-sensitive academic and small biotech installations.
- Data Analytics:Predictive algorithms for sample degradation kinetics and inventory optimization integrate with automated storage platforms.
Cloud-Based Software is gaining share fastest; Robotics maintains the revenue base.
Application:
Volume concentration varies by therapeutic modality complexity, with gene therapy and biologics pipelines multiplying sample handling requirements faster than small-molecule chemical research.
- Biotechnology:Gene therapy, cell therapy, and biologics development demands cryogenic infrastructure for viral vectors, cell lines, and protein samples. Developers in Boston and Basel expand -196°C storage fastest as clinical pipelines mature. ISO 20387 biobanking quality requirements reshape vendor qualification criteria.
- Pharmaceutical R&D:Small-molecule drug discovery relies on automated compound libraries for high-throughput screening and lead optimization. Large firms in New Jersey and Germany sustain the installed base of liquid handling robotics. FDA 21 CFR Part 11 compliance drives validated system procurement cycles.
- Agrochemical Research:Crop protection compound screening employs adapted pharmaceutical workflows with lower regulatory validation thresholds.
- Chemical Research:Materials science and specialty chemical development utilizes compound management for catalyst and reagent libraries.
- Academic Research:University laboratories operate smaller-scale installations with manual systems and limited automation.
Pharmaceutical R&D holds the largest share; Biotechnology climbs the fastest.
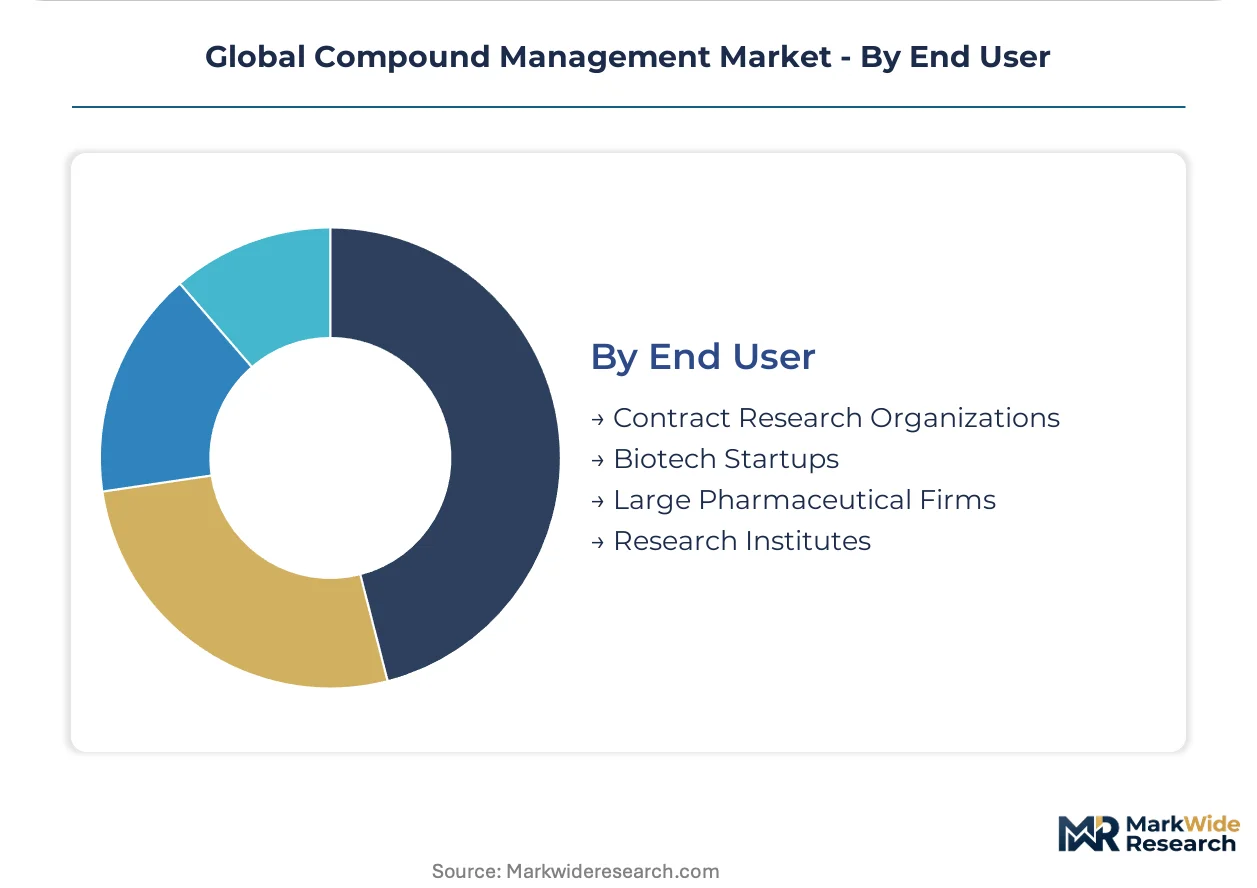
End User:
Customer type determines procurement sophistication, with large pharmaceutical firms demanding enterprise integration and contract research organizations prioritizing throughput flexibility.
- Large Pharmaceutical Firms:Enterprise-scale compound libraries integrate with global quality management systems and multi-site LIMS architectures. Firms in New Jersey, Basel, and Tokyo deploy validated automated platforms to harmonize screening operations across continents. Regulatory inspection readiness dictates 18-24 month validation timelines for system upgrades.
- Contract Research Organizations:Outsourced screening providers in India and Eastern Europe scale automated throughput to serve variable client demand. CDSCO pharmacovigilance expansion in India accelerates infrastructure investment. Modular automation configurations reduce capital risk during pipeline volatility.
- Biotech Startups:Venture-funded gene therapy developers in South San Francisco and Cambridge favor cloud-based subscription models over capital-intensive on-premise deployments.
- Research Institutes:Government and academic laboratories operate smaller-scale installations with manual and hybrid system predominance.
Large Pharmaceutical Firms holds the largest share; Contract Research Organizations shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 21 CFR Part 11 mandates in the United States and EMA data integrity guidelines in Europe are accelerating validated compound management system upgrades across pharmaceutical networks. Government biotech incentives in China and India are expanding cryogenic infrastructure for gene therapy pipelines. Procurement concentrates in clusters where regulatory inspection density intersects with high-throughput screening demand.
United States
Contract research organizations in New Jersey and Massachusetts are scaling automated compound libraries to serve pharmaceutical outsourcing demand. FDA 21 CFR Part 11 electronic records mandates force legacy system replacements before regulatory inspections. The Boston-Cambridge biotech corridor anchors North American gene therapy storage infrastructure for viral vector samples.
Germany
Pharmaceutical firms in Basel-proximate Baden-Württemberg and North Rhine-Westphalia sustain Europe's densest automated screening installations. EMA GMP Annex 11 revisions tighten audit trail requirements for multi-site quality systems. The Rhine-Neckar biopharma cluster drives demand for ISO 20387-compliant biobanking infrastructure.
China
NMPA pharmacovigilance expansion is forcing domestic pharmaceutical firms toward validated compound tracking systems. Government biotech park subsidies in Shanghai and Suzhou accelerate cryogenic storage deployment for cell therapy developers. The Yangtze River Delta concentration of CROs multiplies automated throughput requirements.
India
CDSCO pharmacovigilance expansion and export-oriented pharmaceutical manufacturing are driving compound management infrastructure investment. Hyderabad-Bengaluru biocluster growth outpaces local service density for ISO 20387-compliant biobanking. Contract research organizations in the Genome Valley corridor scale automated platforms to serve European and US client demand.
Japan
PMDA quality management directive revisions are compelling domestic generics manufacturers toward validated compound tracking replacement cycles. Pharmaceutical firms in the Kanto and Kansai regions harmonize quality systems with multi-continental manufacturing footprints. Tokyo-Osaka biopharma corridors sustain demand for enterprise-scale inventory synchronization platforms.
Global Compound Management Market Competitive Landscape
Player mix skews toward integrated automation specialists with liquid handling robotics capabilities and modular platform architects serving variable throughput demand. Market structure concentrates around vendors with cryogenic engineering competence and regulatory validation expertise. Two strategic archetypes dominate: robotics-integrated platform suppliers and cloud-native software specialists. Competitive moves center on modular architecture licensing and multi-site service network expansion.
Among Swiss-integrated automation specialists, Tecan Trading AG exemplifies modular platform architecture for pharmaceutical reconfiguration flexibility. Hamilton Company occupies a position within the robotics-integrated tier, representing North American high-throughput screening installation density. Azenta US, Inc. anchors the cryogenic storage and logistics integration archetype for North American service coverage. These three sit within distinct competitive vectors rather than direct overlap.
| Leading Market Players |
|---|
| Hamilton Company |
| Tecan Trading AG |
| Azenta US, Inc. |
| Brooks Automation |
| SPT Labtech |
| LiCONiC AG |
| Titian Software |
| Evotec |
| Biosero |
| Others |
Supply & Pricing Matrix
Long-term capacity reservation agreements with cryogenic gas suppliers lock in liquid nitrogen access and price visibility for biobanks operating -196°C storage infrastructure. These contracts insulate German and United States facilities from spot market volatility while binding capital to fixed cost structures that strain variable-revenue gene therapy startups.
Pricing Analysis
Certification level creates the primary spread between ISO 20387-validated biobanking platforms and standard laboratory storage systems. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 21 CFR Part 11 compliance depth, with validated audit-trail architectures commanding substantial premiums over basic inventory tracking. Cost compression in the mid-tier is intensifying because modular automation vendors are compressing implementation timelines. Academic research institutes exhibit the highest price sensitivity, while large pharmaceutical firms prioritize inspection readiness over procurement cost.
Supply Chain Analysis
Port congestion on trans-Pacific trade lanes elevates inbound logistics costs for stainless steel cold-storage hardware fabricated in China and South Korea. Cryogenic infrastructure draws from concentrated liquid nitrogen production in the United States, Germany, and China, with stainless steel and specialized insulation materials feeding from East Asian metalworking clusters. Single-source vulnerability in regional gas supplier oligopolies threatens operating budget predictability. Distribution runs through multinational vendor networks for automated platforms and domestic installation channels for manual systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward large pharmaceutical firms consolidating screening outsourcing across fewer contract research organizations. This concentration demands that vendors absorb compliance burden while compressing implementation timelines.
For Market Incumbents: Shield validated system margins by embedding cryptographic timestamping and user access controls that satisfy both FDA and EMA inspectorates. Expand service density in the India biotech corridor before local competitors achieve ISO 20387 certification depth. Prioritize backward integration into cryogenic engineering talent pipelines to offset hybrid skill scarcity in Boston-Cambridge and Basel-Rhine clusters.
For New Entrants and Emerging Players: FDA 21 CFR Part 11 fast-track validation services open immediate white-space at mid-tier generics manufacturers in Japan facing PMDA replacement cycles. Target the Hyderabad-Bengaluru biocluster where CDSCO pharmacovigilance expansion outpaces local service density. Lead with cloud-native subscription models that preserve capital for gene therapy startups with variable funding trajectories.
For Investors and Strategic Acquirers: Modular automation architects with reconfigurable liquid handling platforms represent the most defensible acquisition profile as pharmaceutical firms demand throughput flexibility without full platform replacement. Long-term viability hinges on regulatory validation expertise transferability across jurisdictions. Watch for acoustic liquid handling adoption inflection in New Jersey and Basel screening facilities as a signal of robotics displacement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Validation Pathway Acceleration | FDA 21 CFR Part 11 pre-submission programs compress 18-24 month timelines for contract research organizations. |
| Modular Platform Integration | Tecan's flexible configurations allow pharmaceutical firms to reconfigure screening throughput without capital replacement. |
| Cryogenic Service Network Expansion | Azenta's logistics integration captures North American gene therapy storage demand for viral vector samples. |
| Cloud-Native Inventory Synchronization | Real-time multi-site tracking satisfies EMA GMP Annex 11 data integrity mandates across decentralized networks. |
| AI-Assisted Predictive Maintenance | Machine learning algorithms for sample degradation kinetics integrate with automated storage at Boston biobanks. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EMA GMP inspection reports, and ISO 20387 certification databases. Interviews with compound management directors, regulatory affairs leads at biobanks, cryogenic engineering specialists, and pharmaceutical quality officers inform demand-side validation. Bottom-up triangulation across automated system installations, storage capacity expansions, and software subscription signings converges with top-down expenditure analysis at large pharmaceutical firms and contract research organizations.
Segmentation dimensions modeled span product type, technology architecture, application modality, and end-user sophistication across the projection horizon. Compound management CAGRs derive from pharmaceutical R&D budget trajectories, biologics pipeline maturation curves, and regulatory inspection frequency patterns. Analysis incorporates gene therapy viral vector volume forecasts and cloud migration timelines at multi-site research networks.
Decision-makers should treat outputs as directional under assumptions of sustained FDA and EMA enforcement intensity, stable liquid nitrogen supply concentration, and continued biologics pipeline expansion; material deviation would warrant model refresh. Specific risks include tariff disruption to stainless steel cold-storage hardware and accelerated acoustic liquid handling adoption displacing robotics demand. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Calcium Sulphite Market
Specialty Compounds
Global Specialty Polymer Market
Specialty Compounds
Joint Compound Market
Specialty Compounds
Carbon Black for Packaging Market
Specialty Compounds
Opacifiers Market
Specialty Compounds
Tosyl Chloride Market
Specialty Compounds
Film Dressing Market
Specialty Compounds
Dammar Gum Market
Specialty Compounds
Solketal Market
Specialty Compounds
Quinidine Sulfate Market
Specialty Compounds
Compounding Systems Market
Specialty Compounds
Potassium Hydrogen Sulphite Market
Specialty Compounds
Global Engineering Plastic Compounds Market
Specialty Compounds
Silicone Masterbatches Market
Specialty Compounds
Middle East and Africa Polypropylene Compounds Market
Specialty Compounds
Lauramidopropyl Betaine Market