
 France Food Colorants Market | 2026-2036
France Food Colorants Market Size, Share, and Industry Trends Forecast 2026-2036
France Food Colorants Market Foresight
The EU Green Deal's Farm to Fork strategy is repositioning French food colorant procurement toward botanical extracts and fermentation-derived pigments. BASF SE leverages its synthetic chemistry heritage while navigating clean-label transitions. Chr. Hansen A/S specializes in microbial pigment platforms that align with French dairy reformulation trends. Naturex anchors its position through Mediterranean-sourced anthocyanin supply chains.
Food colorants comprise dyes, pigments, and lakes that impart, restore, or enhance visual appeal in edible products, typically active at concentrations between 0.01% and 0.5% by weight depending on substrate and desired intensity. Their primary function spans identity preservation, flavor expectation management, and shelf-life visual monitoring across processed food systems. Natural colorants now command structural attention as French beverage bottlers reformulate around consumer rejection of azo compounds, while caramel color retains volume dominance in beer and sauce applications where thermal stability requirements exclude many plant alternatives. Synthetic colorants still occupy margin-protected niches in confectionery where vivid hue saturation and batch-to-batch consistency prove technically irreplaceable.
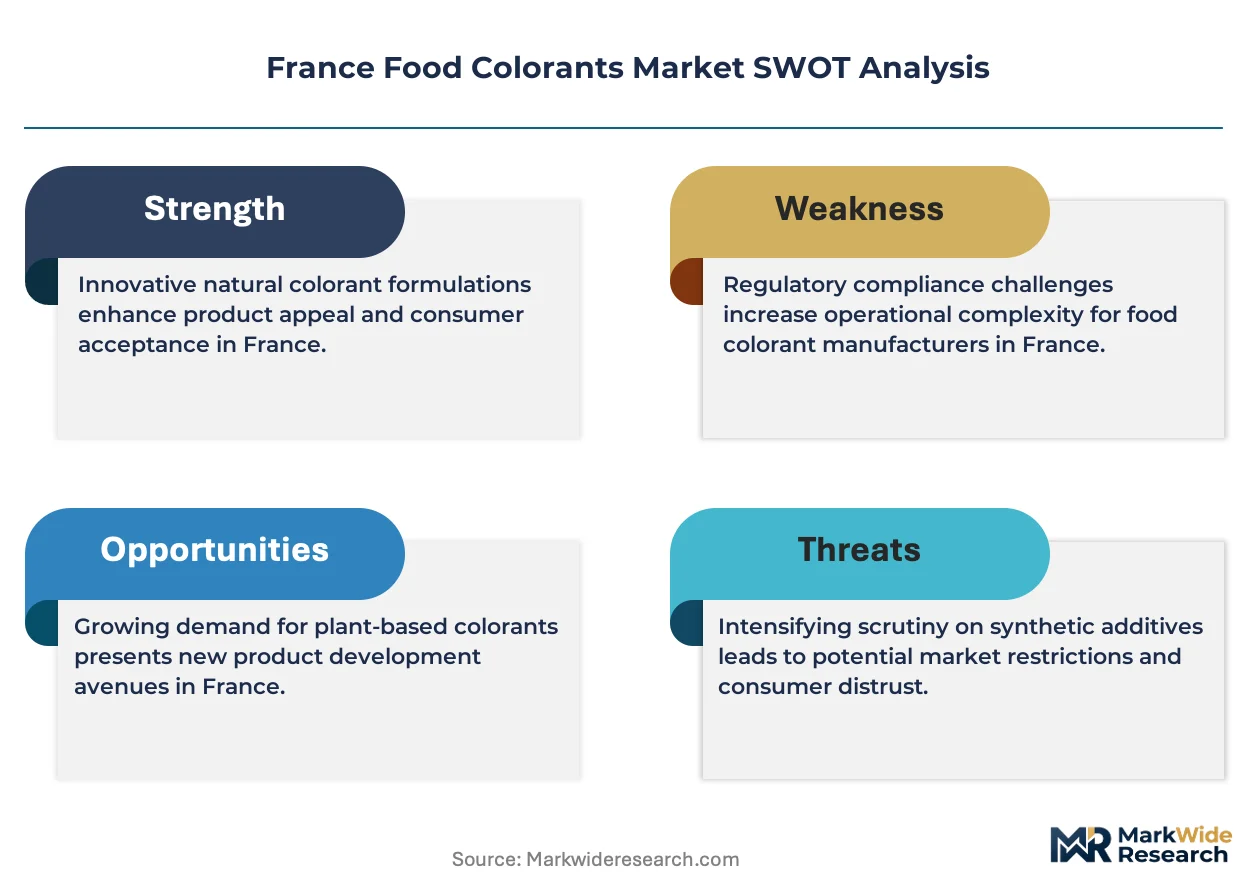
ANSM enforces additive authorization lists and purity specifications under transposed EU 1333/2008 framework, while EFSA re-evaluations periodically delist or restrict specific chromophores based on toxicological reassessment. BSI Group certification for natural extraction processes increasingly gates supply contracts with major French retail private labels. Stakeholders must monitor the interplay between EFSA timeline uncertainty and French processor reformulation lead times to avoid stranded inventory positions.
Market Dynamics
The EU Green Deal's Farm to Fork strategy is compressing reformulation timelines across French food processing, forcing simultaneous transitions from synthetic azo dyes to botanical extracts and fermentation-derived pigments while ANSM tightens purity enforcement.
Growth Catalysts
- EU Green Deal procurement mandates:Public sector food contracts now require clean-label colorant sourcing, redirecting institutional purchasing toward anthocyanin and betalain platforms.
- Confectionery vividness requirements:Premium chocolate and candy segments sustain demand for high-saturation natural pigments as carmine and spirulina replace cochineal in upscale formulations.
- Rhône-Alpes biotech clustering:Lyon-based fermentation facilities are scaling microbial pigment production, cutting lead times for dairy and beverage clients.
Market Restraints
- Anthocyanin thermal instability:Natural pigments degrade above 80°C, excluding them from UHT dairy and retort sauce applications where caramel color dominates.
- Beetroot supply concentration:Betalain extraction depends on seasonal French and Polish beet harvests, creating 40-60 day inventory coverage gaps during Q1 processing lulls.
- EFSA re-evaluation uncertainty:Pending toxicological reviews of titanium dioxide and certain aluminum lakes force processors to maintain dual formulation tracks.
Strategic Opportunities
- Provence-Alpes-Côte d'Azur wine byproduct valorization:Grape skin anthocyanin extraction from Côtes du Rhône press waste offers localized, cost-competitive red pigment supply.
- Precision fermentation scale-up:Microbial pigment platforms can achieve synthetic-grade batch consistency while retaining clean-label positioning for export markets.
- Direct-to-retail certification services:BSI Group natural extraction verification is becoming a contract gate for Carrefour and E.Leclerc private labels.
Industry Challenges
- Cross-functional reformulation expertise:Natural pigment integration requires simultaneous mastery of pH stability, lightfastness, and flavor masking—skill sets concentrated among senior Lyon and Paris food technologists.
- Legacy equipment retrofitting:Existing synthetic dye dosing systems lack precision for low-concentration natural colorants, requiring capital outlays for gravimetric feeders.
- Dual-track inventory management:EFSA timeline opacity forces processors to stockpile both legacy and replacement pigments, compressing working capital efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Food Colorants Market |
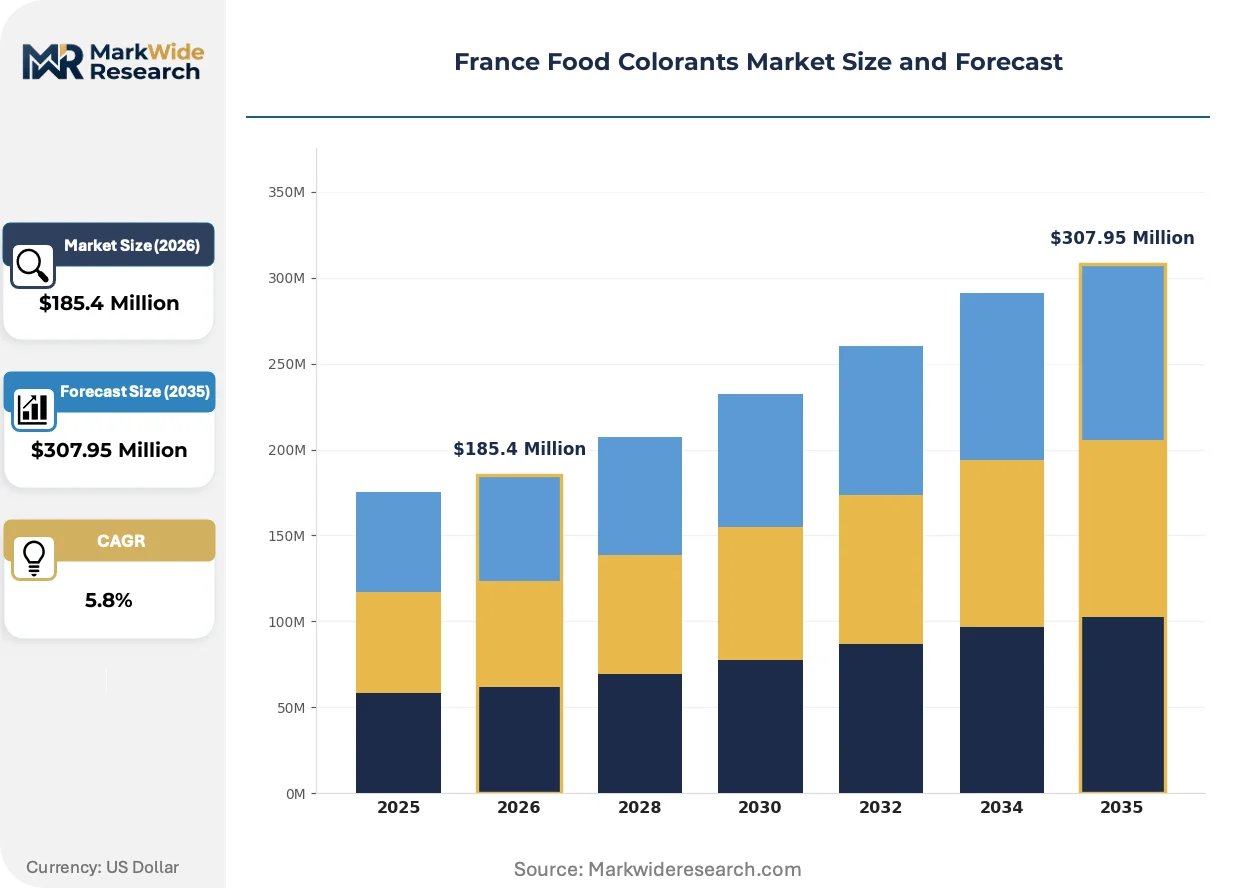
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $307.95 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Colorants, Synthetic Colorants, Caramel Color, Annatto Extract, Beetroot Red, Others Application: Baked Goods, Dairy Products, Confectionery, Snack Foods, Beverage Manufacturing, Sauces & Dressings End User: Food & Beverage Manufacturers, Ingredient Suppliers, Bakeries, Beverage Bottlers, Snack Producers Packaging Type: Pouches, Bottles, Powdered Packs, Liquid Containers, Bulk Bags |
| Companies Covered | Koninklijke DSM N.V., BASF SE, Chr. Hansen A/S, Sensient Technologies, Dohler Group, Givaudan SA, Archer Daniels Midland, Naturex, Roquette, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Food Colorants Market Shifts & Advancements
Clean-label momentum is fragmenting colorant procurement into specialty-grade botanical streams, while digital formulation tools compress development cycles and regulatory uncertainty sustains parallel synthetic tracks.
Encapsulation technology for anthocyanin stabilization is modularizing natural pigment applicability. French sauce manufacturers are adopting lipid-coated beetroot extracts for retort applications previously reserved for synthetic dyes. This modularization is collapsing the technical gap between natural and artificial performance ceilings.
EFSA's systematic re-evaluation of food additives under EU 1331/2008 is accelerating delisting risk for legacy chromophores. French processors face compressed reformulation windows as authorization withdrawals apply retroactively to existing inventory. The confectionery segment bears the highest exposure, with aluminum lake restrictions forcing immediate packaging and formulation overhauls.
Buyer concentration among Paris-region retail private labels is consolidating colorant procurement into multi-year framework agreements. Smaller Provence and Brittany processors are losing direct supplier access, forced instead through distributor intermediaries with certification bundling. This channel compression is most acute in organic and free-from product lines where documentation burdens favor scaled buyers.
France Food Colorants Market Segmentation
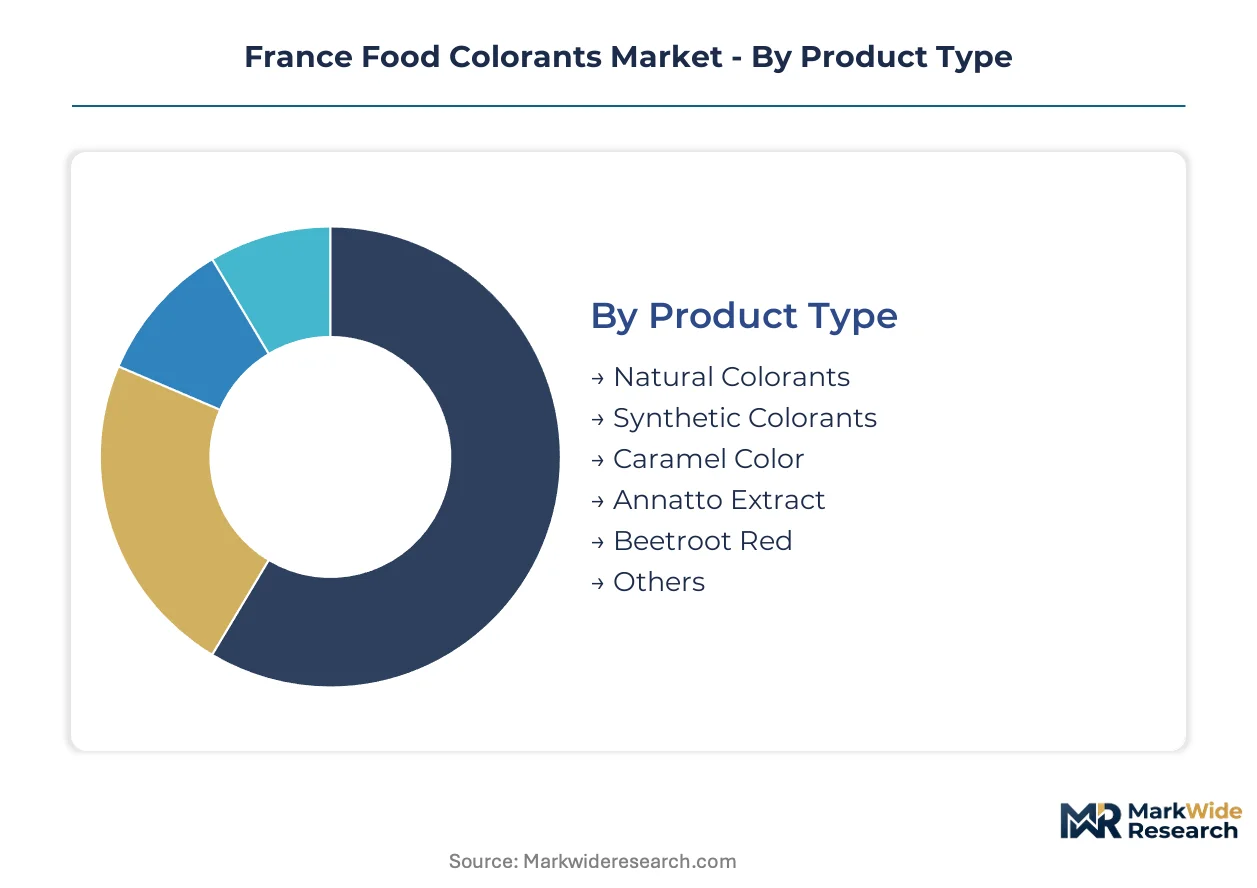
Segmentation reveals where capital deployment and regulatory compliance burdens concentrate across the French food colorants value chain. Product type and application splits determine which processors face the steepest reformulation costs under ANSM enforcement.
Product Type:
Natural colorant extraction demands the heaviest capital intensity, with fermentation vessels and botanical processing lines requiring multi-year depreciation schedules.
- Natural Colorants:Anthocyanin, betalain, and carotenoid platforms dominate Paris-region beverage reformulation. French dairy processors pay premiums for spirulina-derived blues that survive pasteurization without precipitation.
- Synthetic Colorants:Azo dyes and aluminum lakes retain footholds in Rhône-Alpes confectionery clusters where saturation benchmarks exceed natural pigment ceilings. EFSA re-evaluation risk forces dual-track inventory positions.
- Caramel Color:Thermal stability secures its lock on beer and UHT sauce applications across northern France.
- Annatto Extract:Provence dairy coloration relies on bixin and norbixin concentrates for cheese rind uniformity.
- Beetroot Red:Betalain extraction from French and Polish harvests supplies seasonal pink and red tones.
- Others:Turmeric and paprika oleoresins serve niche organic label requirements in Brittany processed foods.
Natural colorants absorb the bulk of installed capacity expansion; caramel color is expanding most quickly in beverage applications.
Application:
Volume concentration tilts toward liquid processing systems where dosing precision and thermal exposure profiles vary sharply.
- Baked Goods:Heat-stable carotenoids and encapsulated anthocyanins survive oven temperatures in croissant and macaron production. Parisian artisan bakeries drive spot demand for clean-label yellows and oranges.
- Dairy Products:Yogurt and fromage frais formulations require pH-stable pigments that resist protein interaction. Chr. Hansen's microbial platforms anchor supply relationships with French dairy cooperatives.
- Confectionery:Vivid hue requirements sustain synthetic dye use in high-saturation candy applications.
- Snack Foods:Seasoning adhesion challenges favor oil-dispersible paprika and annatto coatings.
- Beverage Manufacturing:Clear-label bottlers in Île-de-France reject azo compounds for grape-skin anthocyanins.
- Sauces & Dressings:Retort stability needs preserve caramel color dominance in tomato and brown sauce categories.
Dairy applications command the tightest specification windows; beverage manufacturing is climbing the fastest as clean-label bottlers scale.
End User:
Customer scale determines whether procurement flows direct to manufacturers or through distributor intermediaries with bundled certification.
- Food & Beverage Manufacturers:Integrated reformulation teams at Danone and Bel Group negotiate multi-year natural pigment frameworks with volume guarantees.
- Ingredient Suppliers:Lyon-based distributors aggregate demand from smaller processors lacking direct supplier access.
- Bakeries:Artisan producers in Bordeaux and Lille purchase powdered natural colorants through specialty ingredient channels.
- Beverage Bottlers:Paris-region private-label bottlers impose BSI Group certification as a contract gate.
- Snack Producers:Brittany and Alsace extrusion facilities source oil-dispersible pigments for coating drums.
Food and beverage manufacturers absorb the bulk of procurement volume; beverage bottlers are gaining share fastest on clean-label momentum.
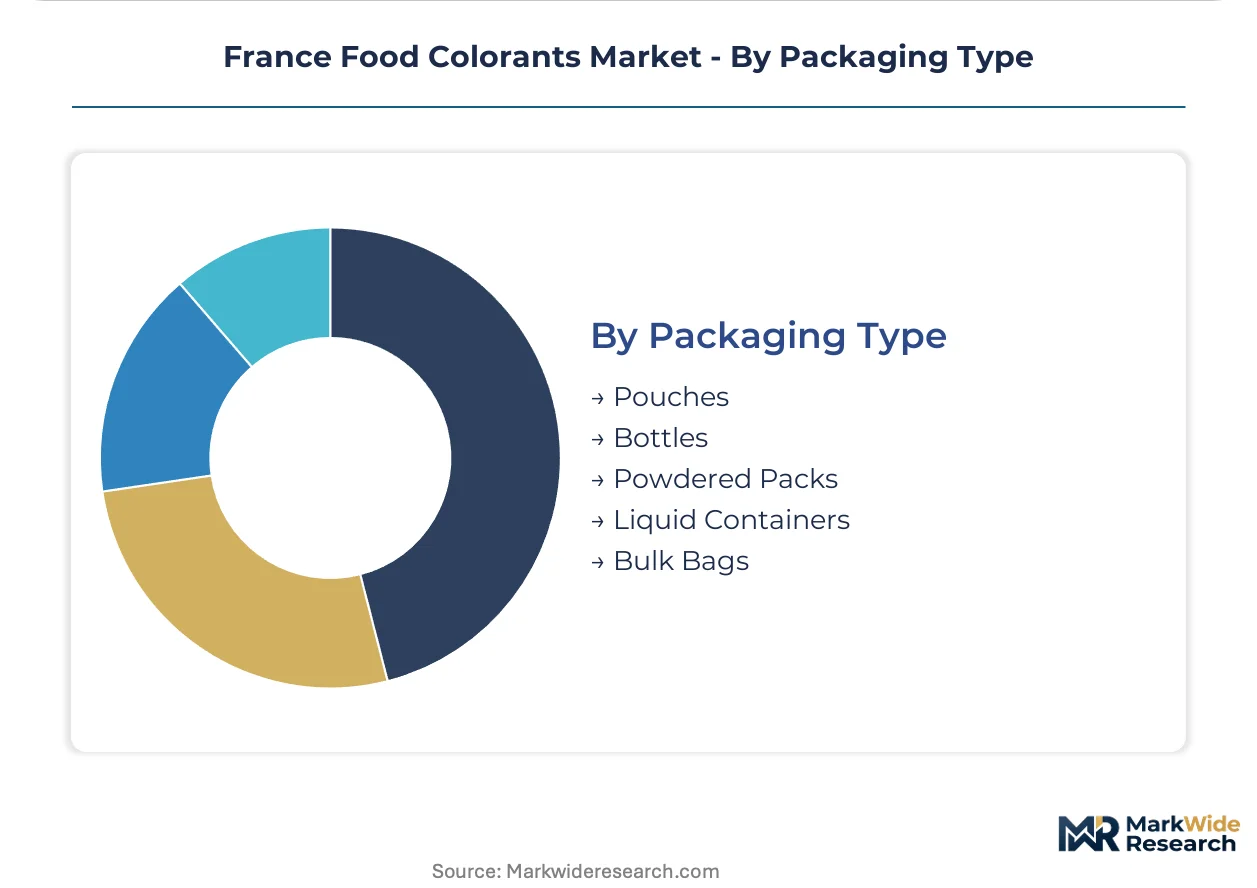
Packaging Type:
Packaging configuration tracks downstream customer scale and contamination risk tolerance.
- Pouches:Flexible packaging serves artisan bakeries and small-batch confectioners with moisture-sensitive powders.
- Bottles:Liquid anthocyanin and caramel color concentrates ship in amber glass for light protection.
- Powdered Packs:Single-use sachets target R&D laboratories and pilot-scale production lines.
- Liquid Containers:Intermediate bulk containers supply high-volume dairy and beverage plants with automated dosing compatibility.
- Bulk Bags:One-tonne FIBCs serve caramel color procurement for national sauce manufacturers.
Liquid containers hold the bulk of throughput infrastructure; pouches are expanding most quickly in artisan and organic segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Île-de-France anchors French food colorant demand through Paris-region beverage bottlers and retail private-label concentration. The ANSM enforces additive purity benchmarks that compress reformulation timelines across metropolitan processors. This analysis examines five sub-regions where procurement patterns, regulatory enforcement, and industrial clustering diverge sharply.
Île-de-France
Paris-region beverage manufacturers drive anthocyanin procurement volumes for clean-label bottling lines. ANSM inspection intensity peaks here due to proximity to national headquarters. Nanterre and Rungis distribution hubs consolidate inbound pigment shipments for redistribution to smaller processors lacking direct supplier contracts.
Auvergne-Rhône-Alpes
Lyon-based fermentation facilities scale microbial pigment platforms for dairy reformulation. The EU Green Deal's Farm to Fork procurement mandates redirect institutional purchasing toward these biotech-derived alternatives. Saint-Étienne and Grenoble satellite plants specialize in pH-stable spirulina extracts for yogurt applications.
Provence-Alpes-Côte d'Azur
Côtes du Rhône wine press waste feeds grape-skin anthocyanin extraction for cost-competitive red pigments. Seasonal harvest volatility creates Q1 inventory coverage gaps. Marseille port infrastructure handles imported beetroot concentrates from Polish suppliers during domestic harvest lulls.
Hauts-de-France
Lille and Roubaix bakeries generate spot demand for heat-stable carotenoids in artisan croissant production. Caramel color dominates beer applications across northern brewing clusters due to thermal stability requirements. Local processors face longer lead times for natural pigment certification through BSI Group channels.
Nouvelle-Aquitaine
Bordeaux-area dairy cooperatives source annatto extracts for cheese rind uniformity in traditional production. Brittany processed food manufacturers to the northwest purchase turmeric and paprika oleoresins through distributor intermediaries. Channel compression forces smaller buyers into bundled certification arrangements.
France Food Colorants Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tier and extraction technology sophistication. The vendor base stratifies into three tiers: multinational chemical conglomerates with synthetic heritage, specialized microbial pigment platforms, and regional botanical extractors. Strategic moves concentrate on fermentation capacity expansion and wine byproduct valorization partnerships.
Within the microbial platform tier, Chr. Hansen A/S and Koninklijke DSM N.V. exemplify fermentation-derived pigment specialists. BASF SE anchors the synthetic-to-natural transition archetype. These three entities occupy positions that reflect divergent responses to ANSM purity enforcement and EFSA re-evaluation timelines.
| Leading Market Players |
|---|
| Koninklijke DSM N.V. |
| BASF SE |
| Chr. Hansen A/S |
| Sensient Technologies |
| Dohler Group |
| Givaudan SA |
| Archer Daniels Midland |
| Naturex |
| Roquette |
| Others |
Supply & Pricing Matrix
The EU Green Deal's Farm to Fork strategy gates qualified supply access for French food colorant processors, compressing procurement timelines for botanical extracts while premium-tier pricing attaches to BSI Group-certified extraction batches. ANSM purity enforcement tightens the qualifying bottleneck, forcing smaller Provence and Brittany processors toward distributor intermediaries that bundle certification costs into marked-up pigment deliveries.
Pricing Analysis
Yield-based pricing anchors natural colorant contracts, with dairy processors paying premiums for spirulina-derived blues that survive pasteurization without precipitation. Certification grade and volume scale drive price differentiation across the three-tier structure separating premium organic extracts from standard technical grades and economy-tier synthetic alternatives. Cost compression in synthetic azo dyes is intensifying because EFSA re-evaluation uncertainty forces dual-track inventory positions. Artisan bakeries in Bordeaux and Lille exhibit highest price sensitivity, while integrated reformulation teams at Danone and Bel Group absorb premiums for multi-year framework guarantees.
Supply Chain Analysis
BSI Group natural extraction verification gates direct supplier contracts with Carrefour and E.Leclerc private labels, forcing channel consolidation around certified intermediaries. Pigment supply draws from France, Poland, and Mediterranean extraction hubs for anthocyanin and betalain platforms. Raw material dependencies center on seasonal beetroot harvests, grape-skin press waste from Côtes du Rhône vintners, and imported spirulina biomass. Single-source vulnerability concentrates in Q1 inventory coverage gaps when domestic beetroot processing lulls. Distribution runs through Nanterre and Rungis hubs for redistribution to smaller processors lacking direct contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The France food colorants market is consolidating around certification-bundled procurement and fermentation capacity scale, with ANSM enforcement timelines forcing weaker botanical extractors toward acquisition or exit.
For Market Incumbents: Extend microbial pigment platform coverage through precision fermentation scale-up in Lyon-based facilities, capturing dairy reformulation demand as Chr. Hansen anchors supply relationships with French cooperatives. Deepen backward integration into Provence wine byproduct valorization partnerships, securing cost-competitive anthocyanin feedstock against seasonal Polish beetroot volatility. Certification investment in BSI Group verification preserves direct retail access as channel compression accelerates. For New Entrants and Emerging Players: Encapsulation technology for anthocyanin stabilization offers entry wedge into retort sauce applications previously reserved for caramel color, collapsing the performance gap between natural and synthetic alternatives. Target artisan bakery clusters in Hauts-de-France with heat-stable carotenoid formulations for croissant and macaron production. Direct-to-retail certification services for organic private-label lines bypass distributor markups that disadvantage smaller Provence processors. For Investors and Strategic Acquirers: EFSA delisting announcements for titanium dioxide or aluminum lakes are the leading indicator that reformulation urgency will spike acquisition premiums for qualified natural pigment suppliers. Long-term viability centers on fermentation-derived platforms achieving synthetic-grade batch consistency while retaining clean-label positioning for export markets. Acquisition target archetype: Lyon-based biotech facilities with scalable microbial pigment production and existing dairy cooperative relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Lyon-based facilities cut lead times for Chr. Hansen's dairy pigment platforms. |
| Wine Byproduct Valorization Partnership | Côtes du Rhône grape-skin extraction localizes cost-competitive red pigment supply. |
| BSI Group Certification Investment | Verification gates Carrefour and E.Leclerc private-label contract access. |
| Encapsulation Technology Development | Lipid-coated beetroot extracts penetrate retort sauce applications. |
| Backward Integration into Beetroot Cultivation | Polish harvest partnerships close Q1 inventory coverage gaps. |
Research Methodology
Independent corroboration across ANSM regulatory filings, EFSA additive re-evaluation databases, and French customs trade records underwrites the qualitative findings in this study. Primary interviews with food technologists at Paris-region beverage bottlers, procurement leads at Rhône-Alpes dairy cooperatives, and Lyon-based fermentation facility managers combined with secondary validation from EU 1333/2008 framework documents and BSI Group certification registries. Bottom-up pigment volume estimates triangulated against top-down food processing sector consumption patterns.
Historical reference periods anchored the forecast window to pre-pandemic baseline procurement patterns and post-EU Green Deal implementation trajectories. The analytical framework segmented volume and value across natural, synthetic, and caramel color product types; dairy, beverage, confectionery, and baked goods applications; and Île-de-France, Auvergne-Rhône-Alpes, and Provence-Alpes-Côte d'Azur regional clusters. CAGRs derived from regression analysis of clean-label reformulation adoption curves and ANSM enforcement intensity proxies. Industry-specific inputs included EFSA timeline opacity coefficients and seasonal beetroot harvest yield volatility.
Several conditions sit outside the modeled scope, including abrupt EFSA authorization withdrawals without transition periods, catastrophic climate impacts on Mediterranean grape harvests, and trade disruption affecting Polish beetroot concentrate imports. Forecasts reflect assumptions about regulatory timeline continuity and fermentation scale-up execution rates. A model refresh is warranted upon material change in EFSA re-evaluation scheduling or ANSM purity benchmark revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Mandarin Oil Market
Flavorings and Food Additives
Flavor Oil Market
Flavorings and Food Additives
Royal Jelly Extract Market
Flavorings and Food Additives
Hops Essential Oil Market
Flavorings and Food Additives
Citrus Concentrate Market
Flavorings and Food Additives
Chicken Flavor Market
Flavorings and Food Additives
Betanin Food Color Market
Flavorings and Food Additives
Nature Identical Flavorings Market
Flavorings and Food Additives
Natural Acerola Cherry Extract Market
Flavorings and Food Additives
Seaweed Flavor Market
Flavorings and Food Additives
Keto Friendly Flavors Market
Flavorings and Food Additives
Italy Food Colorants Market
Flavorings and Food Additives
South America Flavors and Fragrances Market
Flavorings and Food Additives
Canola Lecithin Market
Flavorings and Food Additives
Licorice Extract Market
Flavorings and Food Additives
Feed Flavors and Sweeteners Market