
 Ingredients Market | 2026-2036
Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Ingredients Market Analysis
Modular ingredient bundling is pivoting procurement patterns across food and beverage supply chains. Cargill Incorporated leverages its grain-processing backbone to anchor bulk sweetener and texturizer supply contracts. Kerry Group plc differentiates through taste-and-nutrition integration, controlling formulation partnerships with multinational brands. DSM specializes in vitamin and enzyme premixes, sustaining R&D intensity that narrows substitution risk for buyers.
Ingredients comprise functional substances added to finished goods to enhance stability, sensory profile, nutritional value, or shelf life, typically dosed between 0.01% and 5% by weight depending on functional class and matrix compatibility. Their primary purpose spans preservation, flavor modulation, color standardization, and texture engineering across processed goods. Preservatives and flavors command the deepest margin pools in the product type dimension, reflecting formulation-critical status and limited supplier substitutability. Natural source claims are displacing synthetic alternatives fastest in the source dimension, though organic-certified supply remains bottlenecked by agricultural conversion timelines and certification lag.
FDA food additive regulations and EPA chemical safety assessments govern US market access, while REACH and EFSA evaluations shape European formulation portfolios through restricted substance lists and novel food approval pathways. These frameworks elevate compliance costs for synthetic color additive and preservative suppliers, redirecting R&D budgets toward natural extraction and fermentation-derived alternatives. Stakeholders must monitor regulatory divergence between jurisdictions, as misaligned approval timelines for novel ingredients threaten synchronized product rollouts and inventory pooling strategies.
Market Dynamics
Clean-label mandates from food and beverage manufacturers are compressing synthetic preservative demand while fermentation-derived alternatives capture formulation slots previously held by petrochemical inputs.
Growth Catalysts
- EU Green Deal chemical phase-downs:REACH restrictions on synthetic color additives redirect R&D budgets toward natural extraction pathways, expanding addressable market for botanical-derived stabilizers.
- India PLI scheme incentives:Domestic ingredient manufacturing subsidies under FSSAI-aligned mandates are reshoring supply chains previously dependent on Chinese fermentation capacity.
- Precision fermentation scale-up:Bioreactor productivity gains in enzyme and vitamin production are collapsing unit economics for traditional extraction methods.
Market Restraints
- Organic-certified supply bottlenecks:Agricultural conversion timelines and certification lag constrain natural source claims, capping volume growth in premium formulation tiers.
- Input volatility in agricultural feedstocks:Weather-driven supply swings in vanilla, citrus, and spice crops transmit price instability through natural flavor supply contracts.
- Technical substitution ceilings:Natural preservatives fail to match synthetic efficacy in high-moisture matrices, limiting clean-label penetration in ready-to-eat meat and dairy applications.
Strategic Opportunities
- Underpenetrated African markets:FSSAI-equivalent regulatory harmonization across East African Community states creates formulation standardization opportunities for regional brand owners.
- Personalized nutrition convergence:Microbiome-targeted ingredient premixes combining vitamins, prebiotics, and enzymes open white space beyond conventional fortification.
- Direct-to-manufacturer platform channels:B2B ingredient marketplaces disintermediate traditional distributor networks, compressing procurement cycles for mid-scale food processors.
Industry Challenges
- Formulation chemist scarcity:Cross-functional expertise spanning food science, regulatory compliance, and sensory evaluation commands premium compensation, constraining R&D team expansion.
- Novel food approval timelines:EFSA and FDA asynchronous evaluation schedules for fermentation-derived proteins threaten synchronized product rollouts across transatlantic markets.
- Legacy ERP integration friction:Batch-level traceability requirements for clean-label certification collide with outdated inventory management systems at tier-two manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ingredients Market |
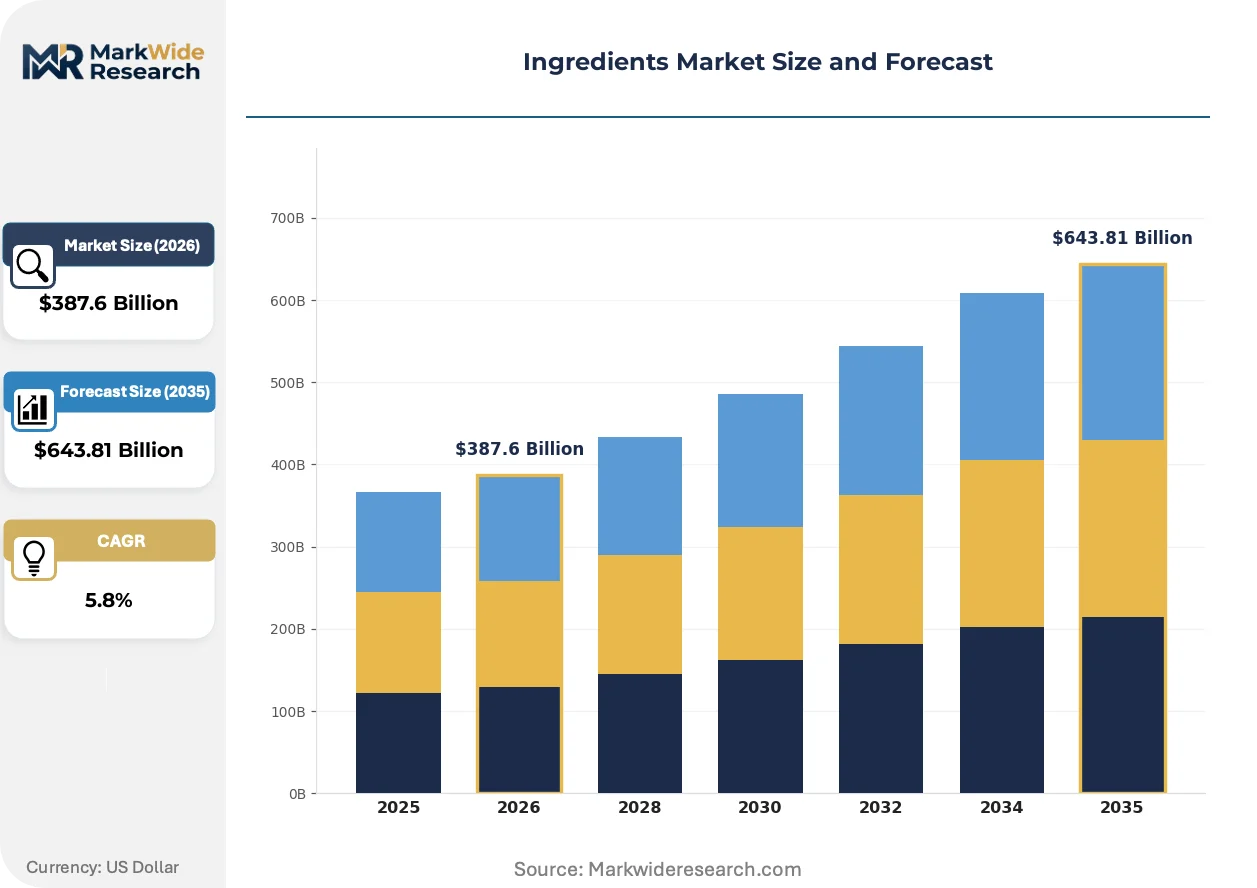
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $643.81 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Preservatives, Flavors, Color Additives, Emulsifiers End Use Industry: Food & Beverage, Personal Care, Pharmaceuticals, Nutraceuticals Form: Powder, Liquid, Granule, Paste Source: Natural, Synthetic, Organic, Inorganic |
| Companies Covered | Cargill Incorporated, Archer Daniels Midland Company, Ingredion Incorporated, BASF SE, Kerry Group plc, DSM, Tate & Lyle, International Flavors & Fragrances Inc., Givaudan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ingredients Market Emerging Trajectories
Bioprocessing advances and regulatory chemistry restrictions are converging to displace extraction-based supply with precision-manufactured alternatives across preservation and nutrition categories.
Cell-cultured fat and protein building blocks are rewriting ingredient sourcing economics for texturizers and emulsifiers. Plant-based meat formulators in North America and Europe are adopting these inputs at pilot scale now, with commercial volumes expected to follow bioreactor cost curves. This technology is rewriting the geographic map of supply, decoupling production from agricultural land and climate exposure.
REACH authorization requirements for persistent organic pollutants are forcing reformulation of long-chain emulsifiers and coating agents. European food manufacturers face substance sunset dates that compress substitution timelines to 24-36 months. Bakery and confectionery applications are most affected, with suppliers accelerating enzymatic interesterification and microbial wax development.
Long-term offtake agreements are displacing spot purchasing for strategic ingredients. Multinational food brands now contract directly with fermentation operators for three-to-five-year vitamin and enzyme supply, bypassing traditional chemical distributors. This pattern is most visible in Germany and the Netherlands, where processor consolidation has concentrated buyer power among a handful of pan-European operators.
Ingredients Market Segmentation
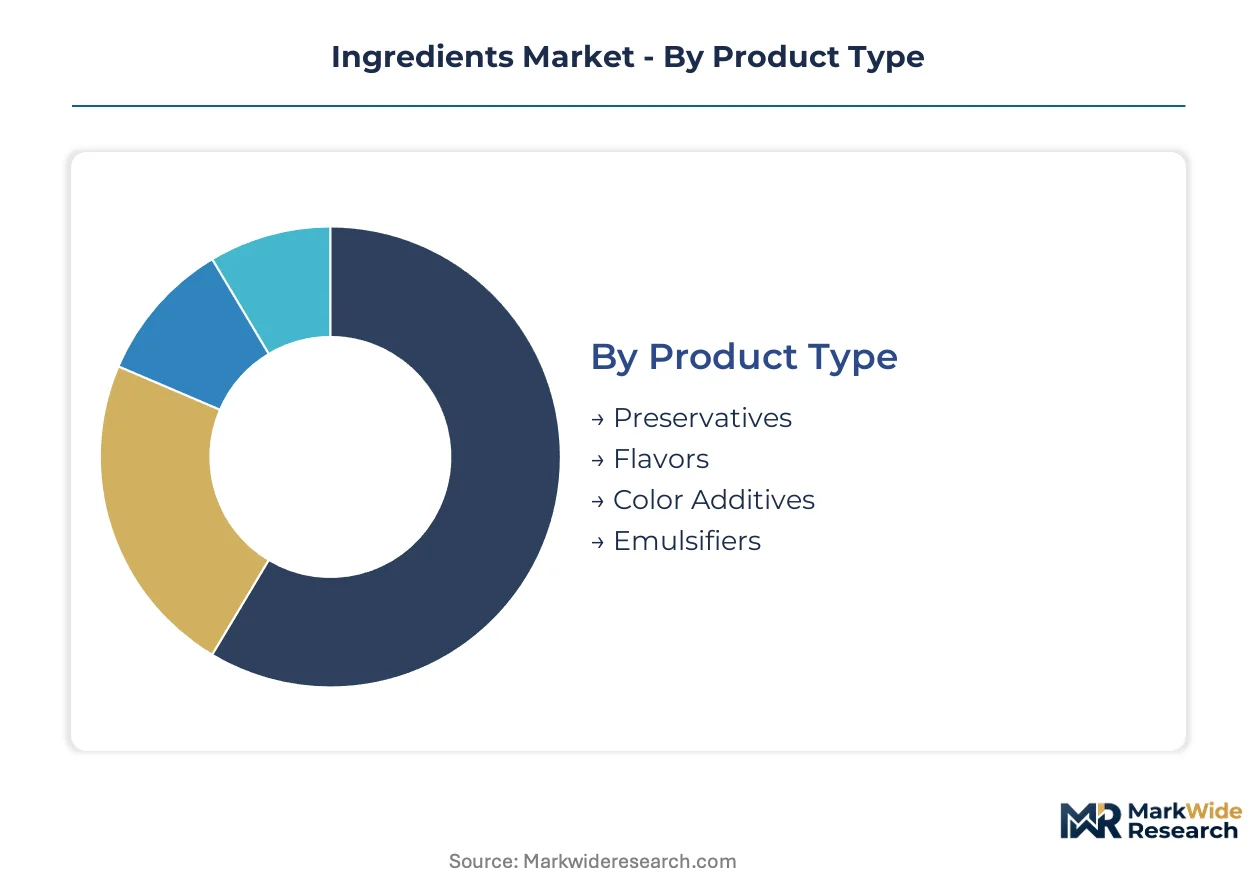
Ingredient segmentation dictates procurement strategies, formulation compatibility, and regulatory compliance pathways. Manufacturers prioritize segment-specific supply security over portfolio breadth. The report examines four critical dimensions shaping sourcing decisions.
Product Type:
Capital intensity varies sharply across this category, with fermentation infrastructure and extraction facilities requiring the heaviest upfront investment.
- Preservatives:Benzoates, sorbates, and natural extracts inhibit microbial growth in processed foods. Demand concentrates in ready-to-eat meat and dairy applications where clean-label mandates from Nestlé and Unilever are accelerating natural alternative adoption. REACH chemical phase-downs elevate compliance costs for synthetic suppliers.
- Flavors:Natural and nature-identical compounds deliver taste modulation across beverage and confectionery matrices. European and North American beverage manufacturers now specify botanical-derived profiles, though vanilla and citrus crop volatility transmits price instability through supply contracts.
- Color Additives:Carotenoids, anthocyanins, and caramel formulations standardize visual appeal. EU Green Deal restrictions on azo dyes redirect R&D budgets toward plant-extraction pathways.
- Emulsifiers:Lecithins, mono- and diglycerides stabilize oil-water interfaces in spreads and dressings. Enzymatic interesterification is displacing chemical processes in European bakery applications.
Preservatives absorb the bulk of installed capacity; flavors are expanding most quickly.
End Use Industry:
Application requirements determine purity grades, documentation depth, and supplier qualification protocols.
- Food & Beverage:The dominant consumption channel spanning bakery, dairy, beverages, and processed proteins. Clean-label formulation from CPG manufacturers compresses synthetic preservative slots while fermentation-derived alternatives capture volume.
- Personal Care:Preservatives and emulsifiers in topical formulations face stricter dermal safety thresholds than food applications. ECHA evaluations shape European formulation portfolios through restricted substance lists.
- Pharmaceuticals:Excipients and active pharmaceutical ingredients demand GMP certification and batch-level traceability. FDA and EMA asynchronous approval timelines threaten synchronized product rollouts.
- Nutraceuticals:Vitamin premixes, prebiotics, and enzyme blends target microbiome and metabolic health positioning. Precision fermentation scale-up collapses unit economics for traditional extraction methods.
Food and beverage commands the deepest volume base; nutraceuticals show the steepest expansion trajectory.
Form:
Physical state determines handling equipment, dissolution kinetics, and stability during storage and transport.
- Powder:Spray-dried and crystalline formats dominate high-volume fortification and dry-mix applications. Fluidized bed processing requires substantial capital deployment.
- Liquid:Solutions and suspensions enable precise dosing in continuous beverage manufacturing. Tank farm infrastructure locks in geographic supply placement.
- Granule:Agglomerated particles improve flowability and reduce dusting in industrial bakeries. Fluid bed granulation equipment carries moderate capital requirements.
- Paste:Concentrated semi-solids serve niche flavor and color applications requiring minimal moisture addition. Limited shelf stability constrains distribution radius.
Powder forms anchor global production capacity; liquid formats are climbing the fastest on beverage industry demand.
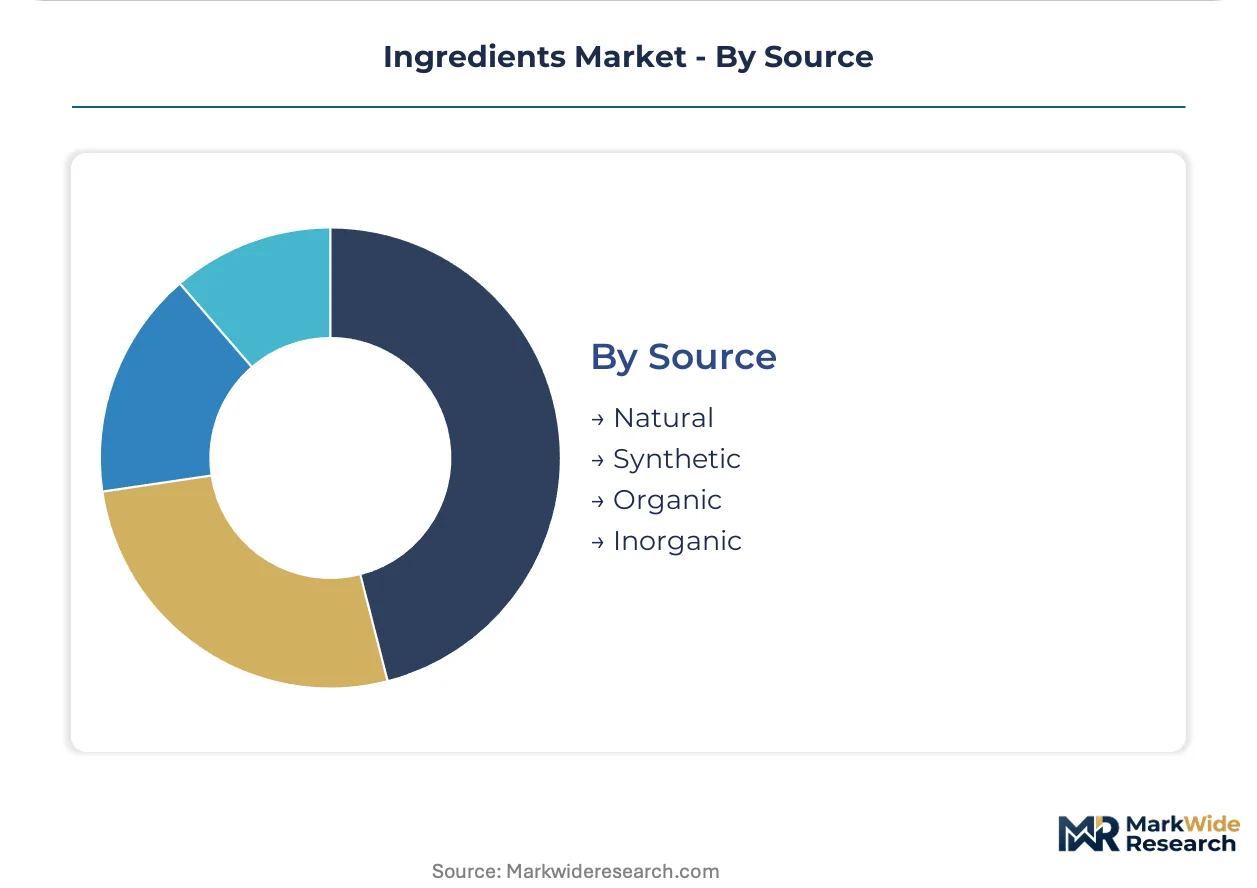
Source:
Provenance claims now function as primary purchase criteria, with certification lag and agricultural conversion timelines creating supply bottlenecks.
- Natural:Botanical extracts and fermentation-derived compounds satisfy clean-label procurement mandates. FSSAI-aligned sourcing requirements in India redirect domestic manufacturing priorities.
- Synthetic:Petrochemical-derived inputs retain cost advantage in high-volume, price-sensitive applications. REACH authorization requirements compress substitution timelines for persistent organic pollutants.
- Organic:Certified agricultural supply faces conversion period constraints and third-party audit backlogs. Premium pricing reflects constrained volume availability.
- Inorganic:Mineral salts and oxides serve color and texturizer functions where botanical alternatives lack stability. Limited growth exposure as natural substitution advances.
Natural sources capture the majority of new capacity investment; organic certification is gaining share fastest despite supply constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ingredient production clusters concentrate in agricultural heartlands and fermentation science hubs, while consumption tilts toward processed food manufacturing centers. China and India now rival traditional Western supply bases. Regulatory divergence between FDA, EFSA, and FSSAI timelines complicates synchronized product rollouts.
United States
Precision fermentation scale-up in the Midwest and biotechnology corridors drives enzyme and vitamin premix capacity expansion. FDA food additive regulations and EPA chemical safety assessments govern market access, elevating compliance costs for synthetic color and preservative suppliers. Chicago and Minneapolis-St. Paul anchor grain-processing and sweetener supply chains serving North American beverage and bakery manufacturers.
Germany
REACH authorization requirements for persistent organic pollutants force 24-36 month reformulation timelines for long-chain emulsifiers and coating agents. The EU Green Deal chemical phase-downs redirect R&D budgets toward natural extraction pathways. Frankfurt-Rhine-Main and Hamburg harbor clusters concentrate botanical-derived stabilizer development and pan-European distribution infrastructure.
China
Fermentation capacity for citric acid, amino acids, and vitamin intermediates dominates global intermediate supply. SAMR food safety standards and GB additive specifications govern domestic formulation approvals, with export certification lag creating inventory pooling challenges. Zhengzhou and Shandong Peninsula clusters integrate agricultural feedstock processing with industrial-scale bioreactor operations.
India
FSSAI mandates and PLI scheme incentives reshore supply chains previously dependent on Chinese fermentation capacity. Domestic ingredient manufacturing subsidies accelerate natural extract and spice oleoresin capacity in Kerala and Karnataka. Mumbai-Pune and Ahmedabad industrial corridors concentrate flavor and color additive formulation for regional brand owners.
Brazil
Agricultural commodity abundance supports natural extract and botanical supply for Latin American processed food manufacturers. ANVISA food additive regulations align gradually with Codex Alimentarius standards, though approval timeline gaps persist for novel fermentation-derived inputs. São Paulo state clusters integrate citrus, vanilla, and tropical fruit processing with regional beverage and confectionery supply chains.
Ingredients Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across ingredient supply tiers. The market structure stratifies into three layers: multinational agricultural processors with captive raw material bases, mid-scale fermentation and extraction specialists with regional density, and niche technology licensors with proprietary bioprocessing platforms. Dominant competitive moves include backward integration into agricultural supply and long-term offtake contracting that bypasses traditional distributor networks.
Within the diversified agricultural processor tier, Cargill Incorporated and Archer Daniels Midland Company exemplify scale-driven supply anchoring through grain-processing backbone integration. Kerry Group plc occupies a position bridging taste-and-nutrition formulation partnerships with multinational brand owners. Among biotechnology-focused specialists, DSM represents precision fermentation scale-up in enzyme and vitamin premix segments.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| BASF SE |
| Kerry Group plc |
| DSM |
| Tate & Lyle |
| International Flavors & Fragrances Inc. |
| Givaudan |
| Others |
Supply Flow & Price Mechanics
Vanilla bean futures and citrus concentrate indices transmit volatility directly into natural flavor contract pricing, cascading through three-tier supply arrangements that separate organic-certified premiums from conventional botanical grades and synthetic alternatives.
Pricing Analysis
Margin tightening in natural preservative tiers reflects agricultural feedstock instability and certification backlog delays. Three-tier pricing structure across premium, standard, and economy levels separates organic-certified botanical extracts from conventional natural sources and petrochemical synthetics. Price differentiation hinges on FSSAI compliance documentation and REACH registration status. Mid-scale food processors exhibit highest price sensitivity, while multinational CPG manufacturers prioritize supply security over unit cost.
Supply Chain Analysis
Fermentation capacity for citric acid and vitamin intermediates rests on Chinese bioreactor clusters, Indian PLI-subsidized greenfield sites, and Midwestern precision fermentation facilities. Key inputs span corn-derived dextrose, sugarcane molasses, and specialty enzyme inoculants. Single-source vulnerability concentrates in Shandong Peninsula amino acid production. Distribution runs through pan-European distributor networks and direct-to-manufacturer B2B platforms serving regional brand owners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation platforms are displacing solvent extraction methods across preservation and nutrition categories, compressing legacy capacity valuations and redirecting capital toward bioreactor infrastructure.
For Market Incumbents: Acquire precision fermentation technology licensors before unit economics collapse further. Anchor supply security through backward integration into agricultural feedstock processing in Kerala and Karnataka. Counter substitute threat from cell-cultured emulsifiers by accelerating enzymatic interesterification R&D partnerships with European bakery manufacturers. For New Entrants and Emerging Players: EU Green Deal chemical phase-downs in Germany open a window for botanical-derived stabilizer specialists with REACH pre-registration capabilities. Penetrate East African Community markets awaiting FSSAI-equivalent regulatory harmonization. Deploy direct-to-manufacturer platform channels to bypass entrenched distributor markups in mid-scale food processing segments. For Investors and Strategic Acquirers: Distressed-cycle entries favor fermentation specialists with stranded extraction assets in China and India. Five-to-ten-year viability hinges on bioreactor productivity gains outpacing agricultural yield improvements. Watch EFSA-FDA approval timeline convergence for novel fermentation-derived proteins as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Bioreactor productivity gains collapse vitamin and enzyme production costs versus extraction methods. |
| Backward Integration into Feedstock Supply | Corn and sugarcane processing captive supply buffers against agricultural commodity price swings. |
| Long-Term Offtake Contracting | Three-to-five-year direct agreements with Nestlé and Unilever bypass traditional chemical distributors. |
| Regulatory Pre-Registration Investment | REACH and FSSAI alignment accelerates market access for natural preservative alternatives. |
| Direct-to-Manufacturer Platform Launch | B2B marketplaces compress procurement cycles for mid-scale food processors in fragmented markets. |
Methodological Framework
Document review covered customs and trade databases, FSSAI additive approval registries, and SEC filings from publicly traded ingredient suppliers, complemented by interviews with fermentation plant managers, procurement leads at multinational CPG manufacturers, distribution channel partners, and technical R&D directors. Secondary validation drew from REACH substance registration databases, EFSA novel food evaluations, and Indian PLI scheme beneficiary disclosures. Bottom-up capacity assessments triangulated against top-down consumption estimates.
Output metrics span volume tonnage and value realization across product type, end-use industry, form, and source segmentation dimensions over the projection horizon. CAGRs derive from regression analysis against macroeconomic indicators and regulatory event timelines. Industry-specific inputs include bioreactor productivity curves, agricultural conversion lag estimates, and certification audit backlog projections.
The model assumes a particular technology adoption path; alternative pathways for cell-cultured fat and protein building blocks would alter the outlook for botanical extract demand. Forecasts reflect assumptions about REACH authorization timelines and FSSAI enforcement intensity. A small set of named triggers—EFSA-FDA approval synchronization, Indian PLI scheme expansion, and East African regulatory harmonization—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Licorice Root Market
Ingredients
Global Natural Gum Market
Ingredients
Commercial Flour Market
Ingredients
Asia-Pacific Protein Market
Ingredients
Sodium Alginate Market
Ingredients
United States Wheat Protein Market
Ingredients
Tryptose Market
Ingredients
High Protein Flour Market
Ingredients
Asia-Pacific Carrageenan Market
Ingredients
Home Baking Ingredients Market
Ingredients
Baking Ingredients Market
Ingredients
Protein Trends and Technologies Market
Ingredients
Europe Gelatin Market
Ingredients
Hydrolyzed Starch Market
Ingredients
Fermented Ingredients Market
Ingredients
Global Tomato Powder Market