
 Japan Food Enzymes Market | 2026-2036
Japan Food Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Food Enzymes Market Foresight
A capital-intensity divergence between integrated biotech platforms and commodity enzyme suppliers is unwinding competitive stability in the Japanese market. Amano Enzyme Inc. leverages proprietary fermentation technology to dominate specialty applications in traditional seasonings. Novozymes A/S anchors its position through global R&D scale adapted to Japanese beverage processing standards. Mitsubishi Chemical Corporation competes via backward integration into fine chemical precursors that feed captive enzyme production.
Food enzymes comprise protein-based biocatalysts, typically operating at temperatures between 30°C and 60°C and pH ranges of 4.0 to 8.0, that accelerate specific biochemical reactions in food matrices without becoming consumed in the process. These catalysts derive from microbial fermentation, plant extraction, or animal tissue recovery, and serve primarily to modify texture, enhance flavor development, extend shelf stability, or improve nutritional bioavailability in processed foods. Protease formulations command the deepest margin pools due to complexity in achieving precise peptide cleavage for umami enhancement in Japanese cuisine. Liquid formulations lead volume throughput among beverage and dairy processors seeking inline dosing integration, while powder formats sustain relevance in bakery premix applications where storage stability determines procurement decisions.
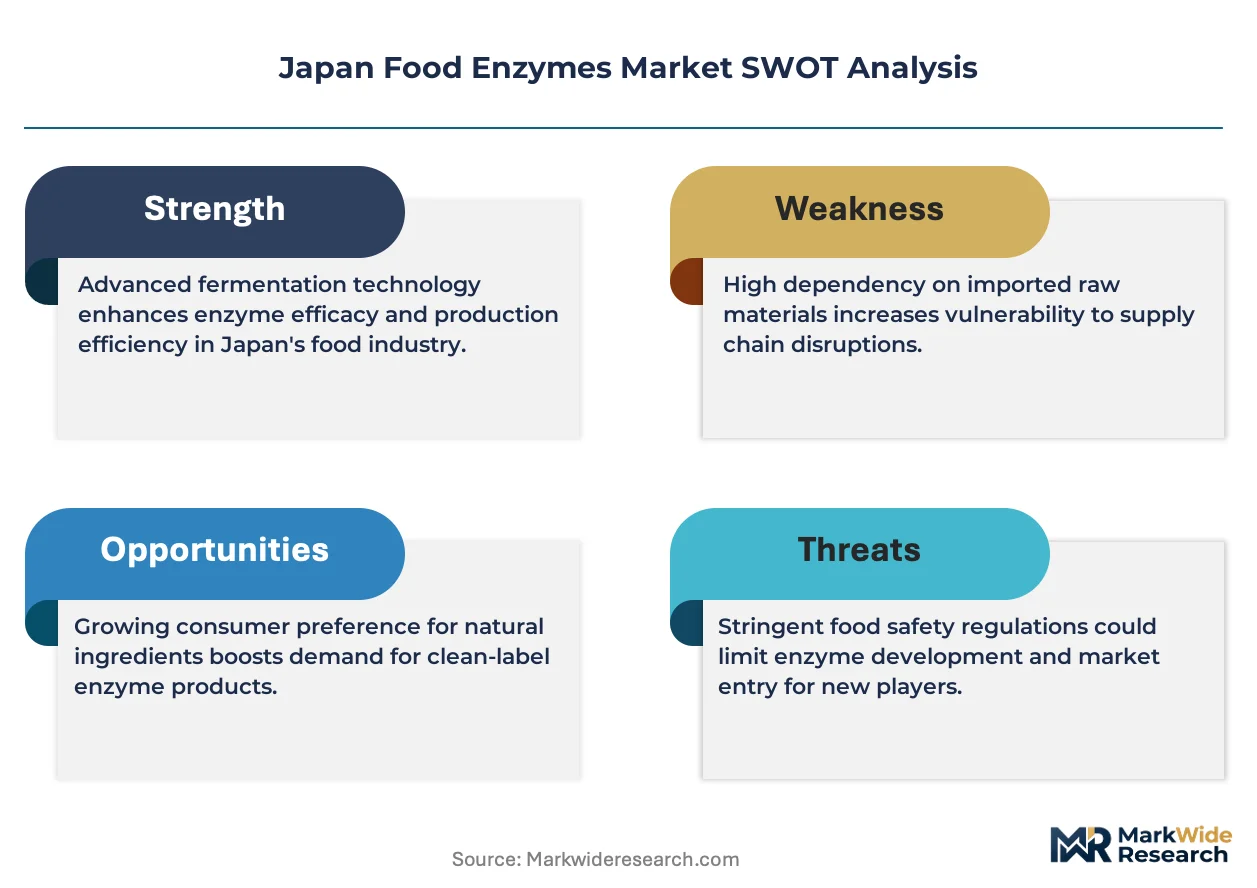
PMDA oversight of novel enzyme preparations and JIS standards for food-grade manufacturing inputs collectively elevate compliance costs for new market entrants. METI's biomanufacturing initiatives and the Ministry of Health, Labour and Welfare's food additive safety assessments further constrain formulation flexibility and approval timelines. Stakeholders must monitor regulatory convergence between Japan's enzyme classification system and evolving Codex Alimentarius guidelines to anticipate reformulation obligations.
Market Dynamics
Japanese food manufacturers face mounting pressure from METI's biomanufacturing mandates to replace petrochemical processing aids with enzymatic alternatives, forcing reformulation investments across traditional fermentation-dependent sectors.
Growth Catalysts
- Traditional seasoning revival:Premium shoyu and miso producers deploy protease blends to accelerate umami development while preserving artisanal labeling claims.
- Beverage clarification standards:Pectinase and cellulase adoption surges among Japanese fruit juice processors seeking clean-label alternatives to gelatin fining.
- Kanto corridor concentration:Dense clustering of dairy and bakery operations around Tokyo creates localized demand density for just-in-time enzyme logistics.
Market Restraints
- Fermentation substrate volatility:Corn and wheat bran price swings directly compress margins for domestic enzyme manufacturers reliant on agricultural feedstocks.
- Single-source supply risk:Critical lipase strains remain concentrated among three domestic fermentation houses, creating vulnerability to batch contamination events.
- PMDA novel food additive pathway:Extended safety review timelines for recombinant enzyme variants delay product launches by 18-36 months versus conventional preparations.
Strategic Opportunities
- Kansai underpenetration:Osaka-Kobe food manufacturing belt shows 40% lower enzyme adoption intensity than Kanto, presenting white-space expansion potential.
- Plant-based protein texturization:Emerging demand from Japanese alternative meat startups for transglutaminase and lipase combinations to replicate animal muscle structures.
- METI green innovation fund:Subsidized capital access for enzyme-based water and energy reduction projects in sake brewing and soy processing.
Industry Challenges
- Fermentation specialist scarcity:Japan's aging biochemical engineering workforce constrains scale-up capacity for next-generation enzyme production facilities.
- Legacy equipment retrofit costs:Inline dosing systems for liquid enzymes require $2-4 million per production line modifications at established dairies and beverage plants.
- JIS certification bottlenecks:Testing backlog at designated inspection bodies delays food-grade enzyme batch releases by 6-10 weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Food Enzymes Market |
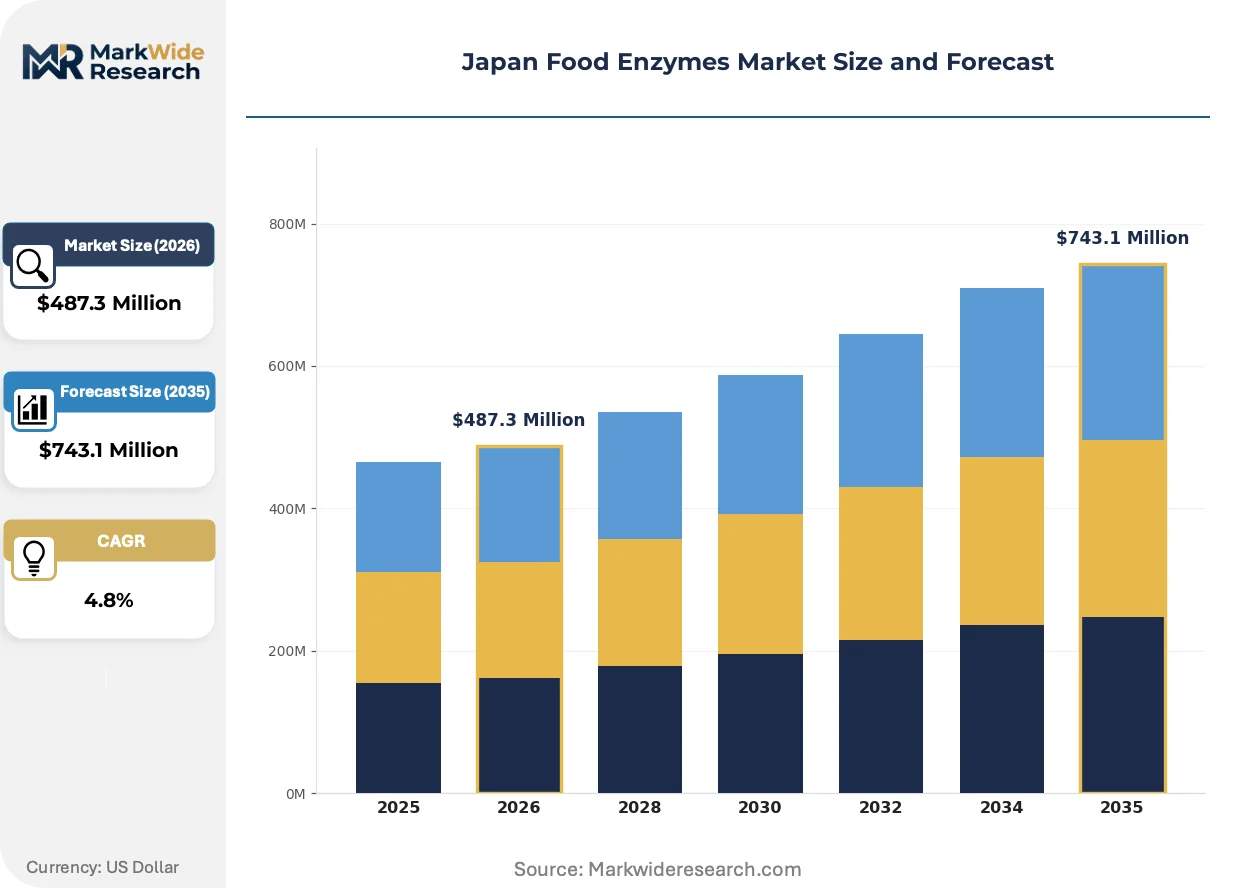
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $743.1 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amylase, Protease, Lipase, Cellulase Formulation: Liquid, Powder, Granular, Other Application: Beverages, Bakery, Dairy, Confectionery End User: Food Manufacturers, Restaurants, Retailers, Others |
| Companies Covered | Mitsubishi Chemical Corporation, Danisco A/S, Amano Enzyme Inc., Nagase ChemteX Corporation, Shin Nihon Chemical Co., Ltd., Novozymes A/S, Koninklijke DSM N.V., Sapporo Enzyme Co., Ltd., Nagase & Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Food Enzymes Market Shifts & Advancements
Enzyme engineering and delivery formats are diverging sharply between commodity scale and precision functionality, with Japanese manufacturers prioritizing application-specific performance over generic activity metrics.
Immobilized enzyme systems for continuous-flow bioreactors is bifurcating the processing equipment landscape. Sake breweries and amino acid manufacturers adopt fixed-bed configurations to reduce enzyme consumption by 60-70%. This technology is compressing batch processing economics and favoring capital-rich integrated producers over toll manufacturers.
METI's carbon neutrality roadmap for the food sector tightens energy efficiency standards for thermal processing. Enzymatic alternatives to heat-dependent reactions gain preferential treatment in green procurement guidelines. Low-temperature proteolysis and amylolysis applications expand most rapidly at mid-sized miso and mirin producers seeking compliance advantages.
Ingredient suppliers now bundle technical service with enzyme supply contracts, displacing transactional procurement at major Japanese food conglomerates. Dedicated application laboratories in Tsukuba and Nagoya troubleshoot formulation failures on-site. This service integration penetrates deepest among dairy processors lacking in-house enzymology expertise.
Japan Food Enzymes Market Segmentation
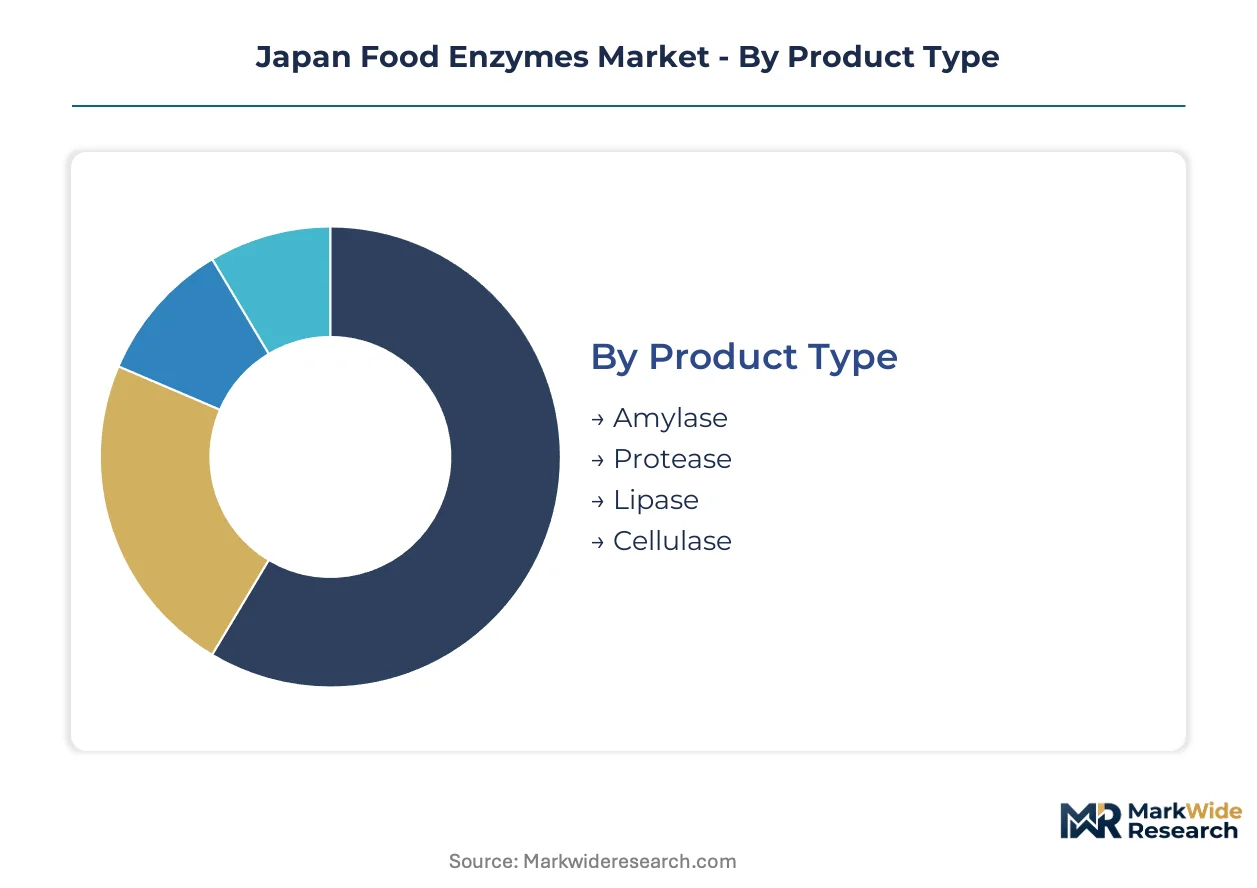
Enzyme procurement patterns in Japan diverge sharply across processing environments, with formulation format and application requirements dictating channel selection. Understanding these segment boundaries clarifies where technical service bundling commands premium positioning versus commodity supply relationships.
Product Type:
Liquid formulations dominate beverage and dairy channels, while powder grades flow through bakery premix distributors serving smaller manufacturers.
- Protease:These peptide-cleaving biocatalysts operate optimally at 45-60°C with pH tolerances of 5.5-7.5, enabling precise umami enhancement in shoyu and miso fermentation. Demand concentrates among Kanto-based traditional seasoning houses seeking to compress aging cycles while maintaining artisanal labeling claims. Premium positioning reflects complexity in achieving substrate-specific cleavage patterns without bitter off-notes.
- Amylase:Starch-hydrolyzing enzymes catalyze dextrinization and saccharification at 50-70°C across Japanese sake brewing and glucose syrup production. Sake breweries in the Kansai corridor represent the densest demand cluster, driven by METI energy efficiency mandates favoring low-temperature enzymatic conversion over thermal processing.
- Lipase:Triglyceride-modifying catalysts enable fat restructuring in dairy and confectionery applications.
- Cellulase:Cell wall-degrading enzymes facilitate juice clarification and plant fiber modification.
By volume, amylase leads through sake and starch processing scale. By growth pace, protease is ahead on premium seasoning revival and clean-label positioning.
Formulation:
Cost tiers separate automated inline dosing systems from manual handling formats, with capital investment thresholds determining customer access.
- Liquid:Pumpable enzyme concentrates with standardized activity units enable continuous-flow integration at beverage and dairy plants. Major Japanese conglomerates with automated CIP systems anchor demand, though retrofit costs of $2-4 million per line constrain mid-tier adoption.
- Powder:Spray-dried preparations with maltodextrin carriers deliver extended shelf stability for bakery premix and seasoning blend applications. Smaller miso and mirin producers in rural Honshu prefer this format for ambient storage compatibility and lower equipment requirements.
- Granular:Dust-free agglomerated particles reduce inhalation exposure in high-volume handling environments.
- Other:Encapsulated and immobilized formats for specialized bioreactor configurations.
By volume, liquid formulations dominate through beverage sector concentration. By margin contribution, granular formats command premium positioning on safety and handling efficiency.
Application:
Geographic clustering around Tokyo-Osaka industrial corridors creates distinct supply chain densities across end-use segments.
- Beverages:Fruit juice clarification and brewing optimization drive pectinase and amylase consumption. PMDA clean-label pressures are displacing gelatin fining agents, with Kanto processors leading adoption velocity.
- Bakery:Dough conditioning and shelf-life extension applications favor fungal amylase and xylanase blends. Regional bakery chains across Japan deploy these for consistent crumb structure in high-humidity distribution.
- Dairy:Cheese curd formation and flavor development applications concentrate lipase demand.
- Confectionery:Invertase and glucose oxidase enable texture control in chocolate and candy manufacturing.
By volume, beverages lead on processing scale and continuous-flow economics. By application expansion, bakery is climbing the fastest on convenience product proliferation.
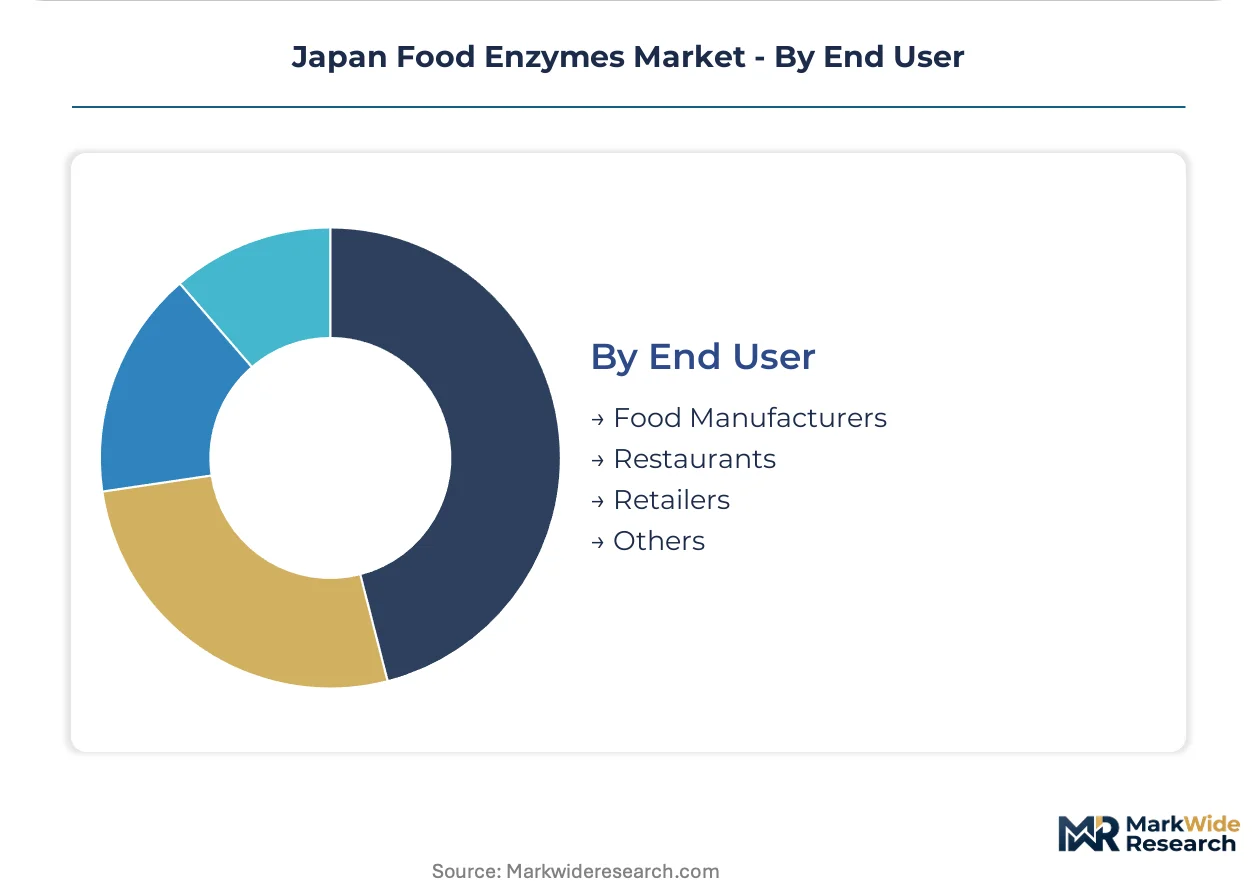
End User:
Customer capability tiers separate integrated enzymology operations from dependent buyers requiring technical service embedding.
- Food Manufacturers:Large-scale processors with dedicated R&D functions negotiate direct supply contracts with formulation customization. Tsukuba and Nagoya technical service laboratories maintain deepest penetration here.
- Restaurants:Chain operators and central kitchens deploy pre-blended enzyme preparations for consistency at scale. Procurement flows through specialized foodservice distributors with refrigerated logistics.
- Retailers:Private-label product development teams source enzyme-treated ingredients from contract manufacturers.
- Others:Institutional catering and specialty fermentation operations.
By procurement value, food manufacturers dominate through volume concentration. By service intensity requirements, restaurants are gaining share fastest on technical support dependency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's food enzymes trade balance tilts toward specialized imports for beverage clarification and premium seasoning applications, while domestic fermentation houses export protease formulations to Southeast Asian processed food sectors.
Kanto/Tokyo
Dense clustering of dairy processors and beverage conglomerates around the Tokyo industrial corridor sustains the nation's highest enzyme consumption intensity per square kilometer. METI's green innovation fund prioritizes this region for enzymatic water reduction projects in soy processing. Tsukuba's technical service laboratories anchor formulation support for just-in-time logistics to Yokohama and Chiba production facilities.
Kansai/Osaka
Sake breweries and traditional miso houses in the Osaka-Kobe belt operate at 40% lower enzyme adoption rates than Kanto counterparts, creating expansion headroom for suppliers. The Ministry of Health, Labour and Welfare's food additive safety assessments apply uniform standards here, though local processors lag in clean-label reformulation. Sakai City's fermentation equipment suppliers increasingly bundle enzyme dosing systems with legacy brewery retrofits.
Chubu/Nagoya
Central Japan's confectionery and starch processing sectors concentrate demand for amylase and invertase formulations. PMDA oversight of novel enzyme preparations creates compliance bottlenecks at Nagoya port inspection facilities, delaying batch releases. Toyota-adjacent industrial zones host mid-sized glucose syrup manufacturers migrating from thermal to enzymatic conversion under METI biomanufacturing mandates.
Kyushu
Southern Japan's shochu distilleries and sweet potato processors generate specialized demand for saccharification enzymes operating at elevated temperatures. Agricultural feedstock volatility hits harder here due to distance from Kanto distribution hubs. Fukuoka's emerging food tech startups pilot transglutaminase applications for plant-based protein texturization with METI subsidized capital access.
Hokkaido
Northern Japan's dairy cooperatives and wheat milling operations sustain powder-format enzyme procurement for ambient storage compatibility. JIS certification backlogs at Sapporo inspection bodies extend batch release timelines by 6-10 weeks versus Kanto benchmarks. Legacy equipment retrofit costs of $2-4 million per production line constrain inline liquid enzyme adoption at established butter and cheese facilities.
Japan Food Enzymes Market Competitive Landscape
Concentration sits with integrated biotech platforms that combine captive fermentation capacity with application-specific technical service. Three domestic specialists control critical lipase strain supply, while global enzyme houses anchor beverage and dairy channels through adapted R&D scale. The competitive landscape stratifies across proprietary fermentation technology holders, backward-integrated chemical conglomerates, and toll manufacturers serving seasonal seasoning producers. Dominant moves include strategic partnerships with sake breweries for immobilized enzyme bioreactors and geographic expansion into underpenetrated Kansai processing belts.
Within the domestic specialist tier, Amano Enzyme Inc. and Nagase ChemteX Corporation exemplify proprietary fermentation approaches to traditional Japanese applications. Novozymes A/S occupies a position among global scale players adapting international R&D to local beverage processing standards. Mitsubishi Chemical Corporation represents backward-integrated competition via captive fine chemical precursor supply. Sapporo Enzyme Co., Ltd. anchors regional service density in northern Japan's dairy and milling corridors.
| Leading Market Players |
|---|
| Mitsubishi Chemical Corporation |
| Danisco A/S |
| Amano Enzyme Inc. |
| Nagase ChemteX Corporation |
| Shin Nihon Chemical Co., Ltd. |
| Novozymes A/S |
| Koninklijke DSM N.V. |
| Sapporo Enzyme Co., Ltd. |
| Nagase & Co., Ltd. |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between Kanto-based beverage conglomerates and domestic fermentation houses lock in both lipase strain access and eighteen-month price visibility, insulating procurement teams from agricultural feedstock volatility while constraining formulation flexibility.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels. Premium tiers command positioning through JIS certification grade and dedicated Tsukuba technical service embedding, while economy tiers serve rural miso houses with powder formats and minimal support. Cost compression in standard grades intensifies as METI biomanufacturing mandates force petrochemical-to-enzyme conversions at mid-tier processors. Small-scale seasoning producers in rural Honshu exhibit highest price sensitivity, lacking capital for inline dosing retrofits.
Supply Chain Analysis
Just-in-time inventory preferences dominate Kanto beverage and dairy channels, while strategic stockpiling persists among Hokkaido dairy cooperatives facing six-to-ten-week JIS certification backlogs. Domestic fermentation houses in Aichi and Osaka prefectures draw from corn and wheat bran feedstocks anchored in North American and Australian agricultural supply. Single-source vulnerability concentrates around three domestic lipase strain holders. Distribution runs through specialized chemical distributors with temperature-controlled logistics for liquid concentrates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's food enzymes sector sits at a platform-economics inflection where METI's carbon neutrality roadmap and Codex Alimentarius convergence are forcing interoperability investments across formulation databases and technical service platforms.
For Market Incumbents: Consolidate proprietary fermentation capacity around immobilized enzyme bioreactor partnerships with sake breweries, locking in continuous-flow adoption before toll manufacturers achieve scale. Acquire regional technical service density in Kansai to preempt new entrant geographic expansion. METI green innovation fund access represents the critical lever for subsidized capacity additions. For New Entrants and Emerging Players: Differentiate on plant-based protein texturization applications for Osaka-Kobe alternative meat startups, where transglutaminase-lipase combinations face minimal incumbent technical service embedding. Target Kansai miso houses at forty percent lower enzyme adoption intensity than Kanto benchmarks. Lead with bundled fermentation equipment-enzyme packages through Sakai City equipment suppliers. For Investors and Strategic Acquirers: Regional specialists with captive strain libraries and backward-integrated fine chemical precursor supply offer durable positioning through regulatory tightening windows. Fermentation engineering capability scarcity in Japan's aging biochemical workforce underpins long-term viability. Watch PMDA novel food additive pathway acceleration as inflection signal for recombinant enzyme variant commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Immobilized Enzyme Bioreactor Deployment | Sake breweries reduce enzyme consumption sixty-to-seventy percent through fixed-bed configurations. |
| Kansai Technical Service Expansion | Osaka-Kobe underpenetration creates white-space capture opportunity for application laboratories. |
| Plant-Based Protein Texturization Partnerships | Fukuoka food tech startups pilot transglutaminase applications with METI subsidized capital. |
| JIS Certification Fast-Track Investment | Designated inspection body backlog compression accelerates batch release timelines at Sapporo. |
| Backward Integration into Fine Chemical Precursors | Mitsubishi Chemical's captive supply model feeds enzyme production margin protection. |
Research Methodology
Cross-validation between regulatory filing analysis and supply chain participant interviews anchors the qualitative findings. Primary fieldwork encompassed fermentation engineering directors at domestic enzyme houses, procurement leads at Kanto beverage conglomerates, technical service managers at Tsukuba application laboratories, and distribution channel partners specializing in temperature-controlled logistics. Secondary sources included METI biomanufacturing policy documents, PMDA novel food additive submission records, JIS standards publications, and customs trade data on fermentation substrate imports. Bottom-up segment sizing triangulated against top-down industry value chain estimates.
Sensitivity analysis across enzyme activity unit pricing scenarios and agricultural feedstock cost bands informed the projection framework. Segmentation dimensions modeled include product type, formulation format, application sector, and geographic demand cluster throughout the forecast period. CAGRs derived from elasticity-adjusted volume trajectories and value-per-unit trends across liquid, powder, and granular formats. Industry-specific inputs encompassed METI green innovation fund disbursement pacing and PMDA approval timeline distributions.
Material uncertainties — PMDA regulatory convergence timing, Codex Alimentarius guideline adoption, and lipase strain contamination events — sit outside the modeled envelope. Forecasts reflect documented assumptions on Kanto corridor demand density persistence and METI mandate enforcement intensity. Revision becomes warranted when JIS certification backlog durations cross twelve-week thresholds or METI biomanufacturing subsidy allocations shift significantly.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Octadecanedioic Acid (ODDA) Market
Food Additives and Ingredients
Erythorbic Acid Market
Food Additives and Ingredients
Microencapsulated Food Ingredient Market
Food Additives and Ingredients
Egypt Food Emulsifiers Market
Food Additives and Ingredients
Asia-Pacific Food Enzymes Market
Food Additives and Ingredients
Non-GMO Citric Acid Market
Food Additives and Ingredients
Feed Anti-Caking Agents Market
Food Additives and Ingredients
Japan Food Preservatives Market
Food Additives and Ingredients
Potassium Polymetaphosphate Food Additives Market
Food Additives and Ingredients
Lime Oil Market
Food Additives and Ingredients
Acetylated Distarch Adipate Market
Food Additives and Ingredients
Cake Enzyme Market
Food Additives and Ingredients
Nisin for Food Market
Food Additives and Ingredients
Africa Food Enzymes Market
Food Additives and Ingredients
Africa Anti Caking Agent Market
Food Additives and Ingredients
Bulking Agents Market