
 South America Plant Protein Ingredients Market | 2026-2036
South America Plant Protein Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
South America Plant Protein Ingredients Market Analytics
Market Context
A wide capital-intensity gap between integrated processors and commodity traders is reorganizing competitive tiers across the region. Cargill Incorporated leverages its Brazilian oilseed crushing network to secure upstream soy protein supply. Ingredion Incorporated anchors its position through specialty starch-protein hybrid investments in Argentina. Archer Daniels Midland Company competes via Panamax-scale logistics that lower unit costs for textured concentrates.
Technical Definition and Segment Structure
South America plant protein ingredients comprise extracted, concentrated, or isolated protein fractions derived from legumes, cereals, and oilseeds, typically achieving protein content ranging from 50% in flour grades to 90% in isolate forms through aqueous extraction or enzymatic separation, serving primarily as functional replacers for animal proteins in formulated foods and feed. Soy protein concentrate maintains mature volume leadership due to established crushing infrastructure, while pea protein isolate captures the fastest expansion as Brazilian and Argentine food manufacturers reformulate for allergen-free positioning. Margin pools concentrate in isolate production where spray-drying energy costs and cold precipitation yield management create technical barriers that textured flour grades cannot match.
Regulatory Environment and Outlook
ANVISA governs novel food ingredient approvals and protein content labeling claims in Brazil, while Argentina's national food code and MERCOSUR technical regulations coordinate cross-border standards that determine market access for imported isolates. Brazil's CONAB and MAPA jointly influence oilseed procurement through biofuel policy spillovers that redirect soy crush volumes between protein and biodiesel channels. Stakeholders must monitor how pending MERCOSUR harmonization on protein fortification thresholds reshapes formulation requirements and cross-border sourcing decisions.
Market Dynamics
Brazil's ANVISA food fortification revisions and Argentina's clean-label mandates are compressing formulation windows, forcing processors to requalify protein specifications faster than legacy supply contracts allow.
Growth Catalysts
- ANVISA Fortification Mandates:Brazil's updated protein content labeling rules compel food manufacturers to source higher-purity isolates, tightening ingredient specifications across the southeastern manufacturing corridor.
- Pea Protein Isolate Adoption:Allergen-free positioning in Brazilian meat alternatives and Argentine bakery reformulations accelerates demand for legume-derived fractions outside traditional soy dominance.
- MERCOSUR Harmonization:Pending technical regulations on cross-border protein fortification thresholds reduce compliance fragmentation, enabling Argentine processors to access Brazilian formulation contracts.
Market Restraints
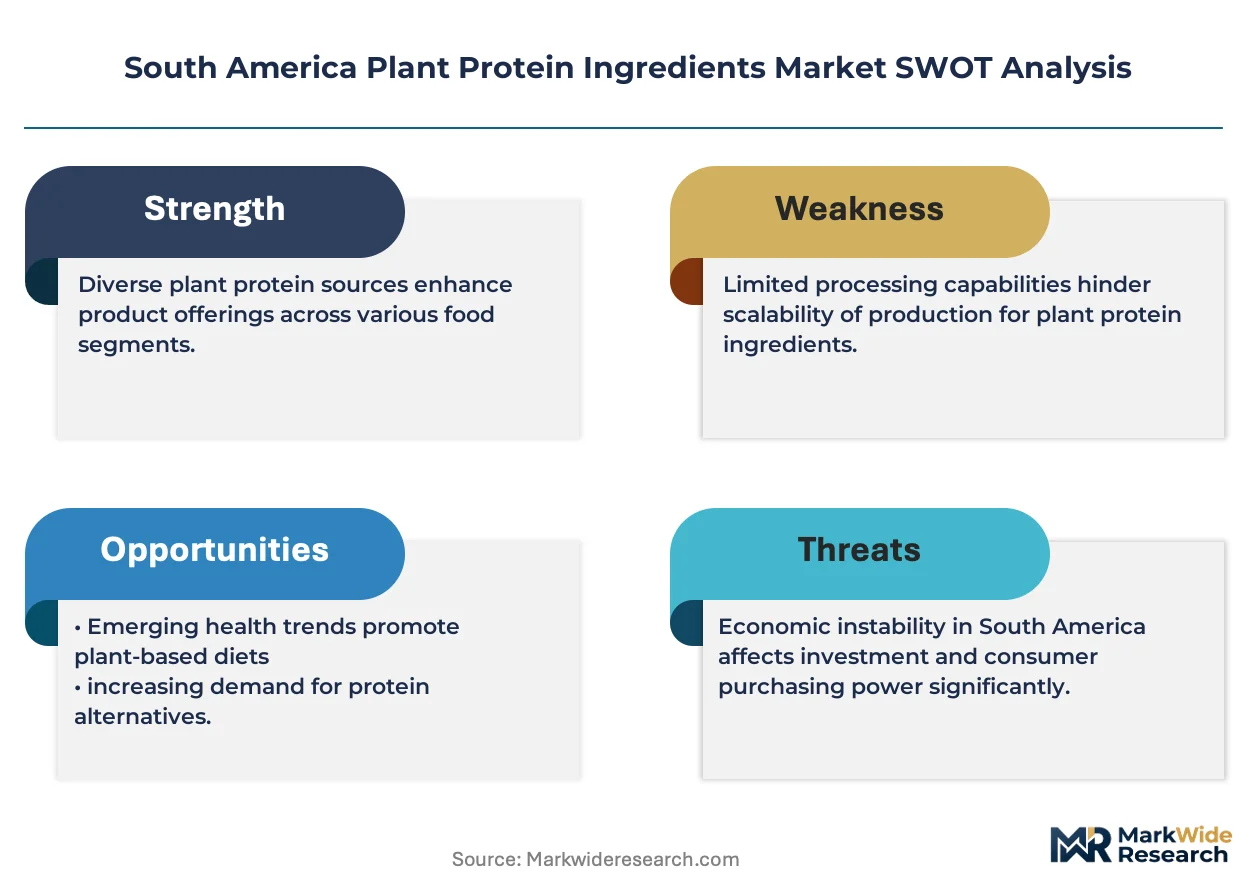
- Spray-Drying Energy Costs:Isolate production requires natural gas-intensive thermal processing, exposing margin pools to Argentine pipeline tariff volatility and Brazilian distributor fuel surcharge fluctuations.
- Soy Crush Concentration:Brazil's CONAB biofuel policy spillovers redirect oilseed volumes between protein and biodiesel channels, creating procurement uncertainty for concentrate buyers.
- Functional Limitations in Beverages:Pea protein's off-flavor profile and solubility gaps restrict penetration in Argentine ready-to-drink applications versus established dairy alternatives.
Strategic Opportunities
- Uruguayan Feed Protein Gap:Underdeveloped domestic crushing infrastructure creates import dependency for soy protein concentrate in Montevideo's aquaculture and poultry sectors.
- Enzymatic Fractionation Convergence:Cold precipitation yield management combined with membrane filtration upgrades enables Brazilian processors to capture premium isolate margins previously reserved to imported supply.
- Direct-to-Manufacturer Channels:Argentine specialty starch-protein hybrid producers bypass commodity traders, securing multi-year formulation partnerships with São Paulo-based CPG brands.
Industry Challenges
- Protein Chemist Scarcity:Brazilian universities produce insufficient formulation specialists trained in enzymatic separation, forcing processors to recruit from European ingredient firms at premium compensation.
- Isolate Certification Timelines:ANVISA novel food ingredient approvals average 18-24 months, delaying commercialization of emerging legume fractions from regional breeding programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Plant Protein Ingredients Market |
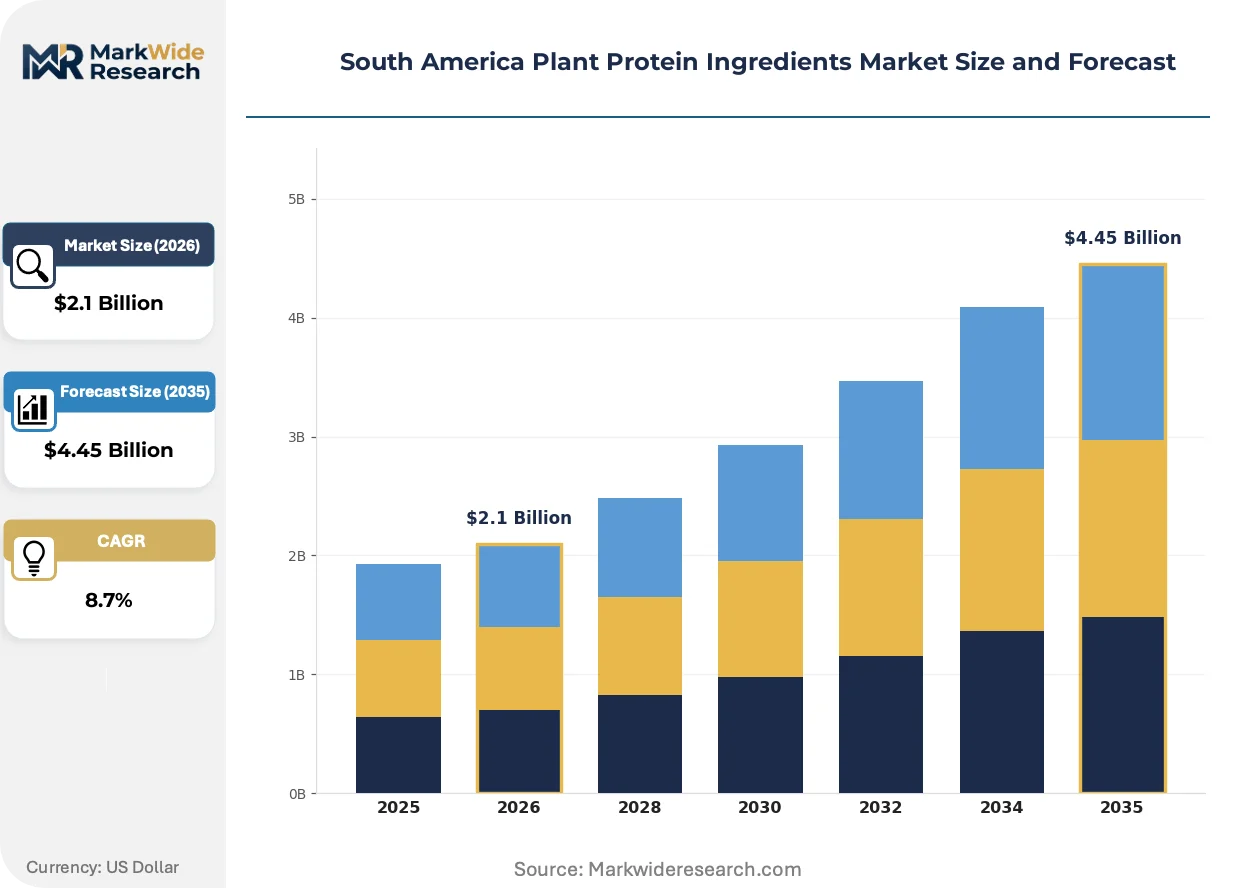
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pea Protein, Soy Protein, Rice Protein, Hemp Protein Application: Food & Beverage, Nutritional Supplements, Animal Feed, Personal Care Form: Isolate, Concentrate, Textured, Flour End User: Food Manufacturers, Fitness Enthusiasts, Vegans, Confectionery Producers |
| Companies Covered | Cargill Incorporated, Ingredion Incorporated, Kerry Group, Archer Daniels Midland Company, Roquette Frères, Tate & Lyle, DuPont de Nemours Inc., Bunge Limited, BRF S.A., Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Plant Protein Ingredients Market Evolving Landscape
Processing technology and procurement patterns are fragmenting established supply hierarchies, creating parallel tracks for commodity traders and integrated specialists serving distinct buyer risk appetites.
Enzymatic protein extraction is bifurcating the competitive landscape between legacy aqueous processors and precision-fractionation specialists. Brazilian meat alternative manufacturers adopt enzymatic isolates for superior gelation profiles, while Argentine bakery formulators retain flour-grade concentrates for cost-sensitive applications. This technology is bifurcating margin pools: spray-drying yield optimization now determines isolate profitability in ways commodity crushing cannot replicate.
ANVISA's pending protein fortification threshold harmonization with Argentina's national food code compresses cross-border compliance costs. Manufacturers sourcing across São Paulo and Buenos Aires face unified labeling requirements, reducing dual-certification overhead. Brazilian ready-to-drink brands and Argentine infant nutrition processors represent the most affected segments, accelerating regional sourcing consolidation.
Ingredient procurement contracts are shortening from multi-year commitments to 6-12 month rolling agreements with price-adjustment clauses. São Paulo-based CPG brands and Minas Gerais meat processors negotiate quarterly volume commitments indexed to oilseed futures, displacing fixed-price annual tenders. This compression is most visible in Brazil's southeastern manufacturing corridor, where logistics proximity enables just-in-time isolate delivery.
South America Plant Protein Ingredients Market Segmentation
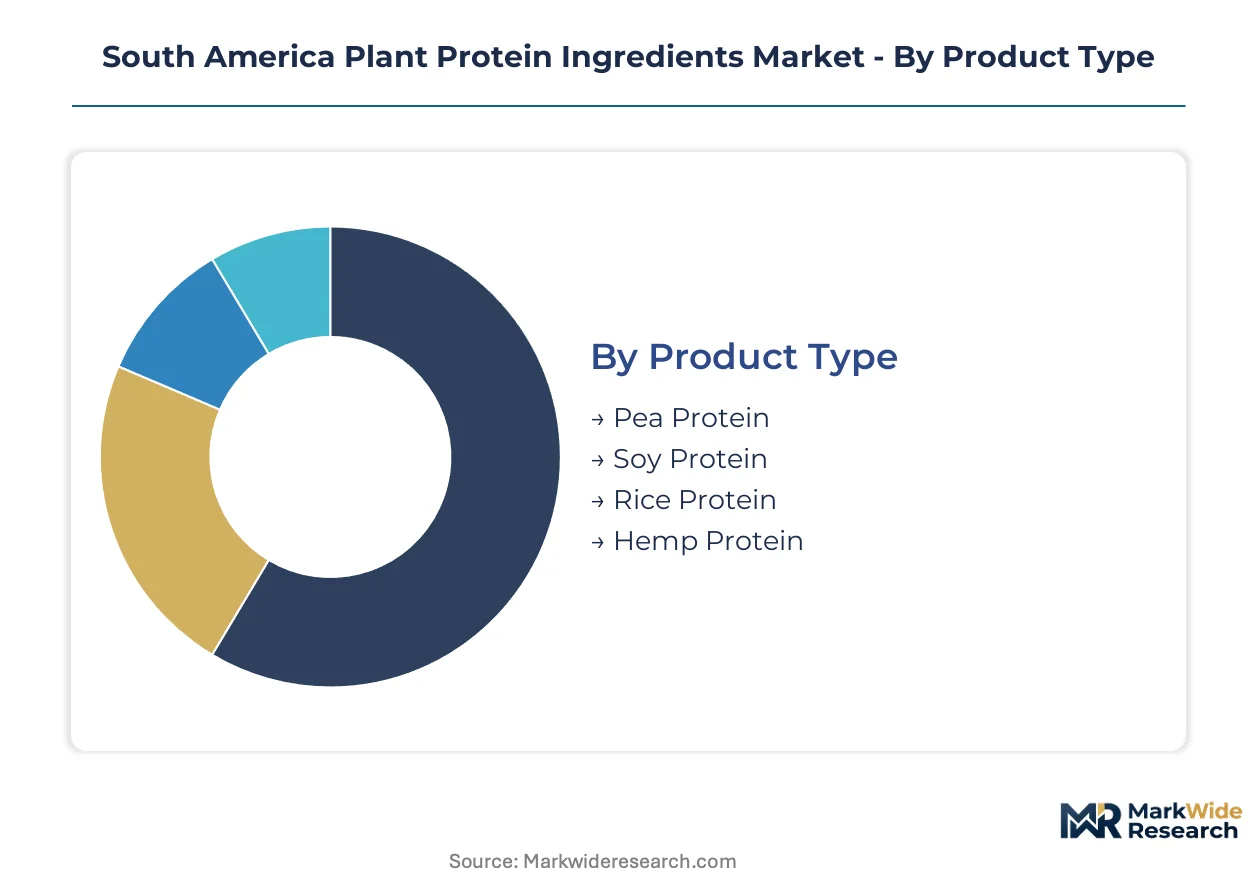
Segmentation in South America plant protein ingredients reveals distinct procurement patterns across Brazil's southeastern manufacturing corridor and Argentina's processing hubs. Channel strategies diverge sharply between commodity traders supplying flour grades and integrated specialists delivering isolate formulations to regulated food manufacturers.
Product Type:
Channel-mix patterns show soy and pea proteins flowing through established oilseed crushing networks, while rice and hemp fractions rely on specialized import distributors serving niche formulators.
- Soy Protein:Extracted from defatted soy flakes through aqueous or alcohol-wash processing, achieving 50-90% protein concentration depending on isolate versus concentrate grades. Brazilian crushers in São Paulo and Paraná states dominate supply, with ANVISA fortification mandates redirecting volumes toward higher-purity isolates for meat alternative manufacturers.
- Pea Protein:Yellow pea fractions processed through wet milling and air classification yield isolates with superior emulsification versus soy alternatives. Argentine processors in Buenos Aires province capture fastest expansion as allergen-free positioning penetrates Brazilian bakery and ready-to-drink channels.
- Rice Protein:Brown rice enzymatic extraction produces hypoallergenic isolates for infant nutrition formulators in Brazil's Minas Gerais corridor.
- Hemp Protein:Cold-pressed cake fractions retain fiber and omega profiles, serving Argentine natural products distributors and São Paulo-based specialty nutrition brands.
By volume, soy protein leads. By growth pace, pea protein is ahead.
Application:
Cost-tier stratification separates mass-market food and beverage formulations from premium-priced nutritional supplements and specialized feed applications.
- Food & Beverage:Meat alternatives, dairy replacers, and bakery applications in Brazil's southeastern corridor absorb concentrate and isolate volumes, with ANVISA protein labeling rules compelling reformulation toward higher-specification ingredients.
- Nutritional Supplements:Sports nutrition and clinical nutrition segments in Argentine metropolitan markets drive isolate demand for powder and ready-to-drink applications, constrained by pea protein solubility limitations in acidic beverages.
- Animal Feed:Aquaculture and poultry sectors in Uruguay and southern Brazil import soy protein concentrate where domestic crushing infrastructure remains underdeveloped.
- Personal Care:Cosmetic formulators in São Paulo utilize rice and hemp hydrolysates for hair and skin conditioning applications at small volume but premium pricing.
Food and beverage commands volume leadership. Nutritional supplements climb the fastest.
Form:
Margin concentration follows processing intensity, with spray-dried isolates capturing premium pools unavailable to flour-grade commodity traders.
- Isolate:Cold precipitation and membrane filtration achieve 90% protein content with minimal fiber and fat, serving Brazilian meat alternative manufacturers requiring gelation performance. Energy-intensive thermal processing exposes margins to Argentine natural gas tariff volatility.
- Concentrate:Defatted flake processing yields 65-70% protein fractions for cost-sensitive bakery and feed applications across Mercosur trade zones.
- Textured:Extruded concentrates mimic meat fibrous structure for Brazilian plant-based meat producers in São Paulo state.
- Flour:Full-fat or defatted milled seeds serve Argentine animal feed compounders and regional baking operations at lowest unit margins.
Concentrate leads by volume. Isolate expands most quickly.
End User:
Customer-type fragmentation separates large-scale food manufacturers negotiating quarterly contracts from specialty buyers prioritizing certification and provenance.
- Food Manufacturers:São Paulo-based CPG brands and Minas Gerais meat processors source isolates through shortened 6-12 month rolling agreements indexed to oilseed futures, displacing legacy annual tenders.
- Fitness Enthusiasts:Direct-to-consumer sports nutrition brands in Argentine urban centers drive pea and rice isolate demand for allergen-free positioning.
- Vegans:Ethical consumption segments in Brazilian metropolitan markets favor hemp and pea proteins with organic and non-GMO certifications.
- Confectionery Producers:Brazilian chocolate and snack manufacturers utilize soy and rice proteins for texture modification and protein fortification in premium product lines.
Food manufacturers dominate volume. Fitness enthusiasts gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics across South America favor Brazilian soy protein shipments to Mercosur partners while Argentine pea fraction exports penetrate Brazilian formulation channels. Uruguay and Paraguay remain net importers of concentrate grades where domestic crushing capacity lags feed sector demand.
Brazil
Southeastern manufacturing corridors in São Paulo and Minas Gerais states concentrate meat alternative and bakery formulation demand. ANVISA fortification mandates compel processors to source higher-purity isolates than legacy supply contracts specify. São Paulo-based CPG brands negotiate shortened procurement agreements indexed to oilseed futures.
Argentina
Buenos Aires province processors capture fastest pea protein isolate expansion through allergen-free positioning in Brazilian export channels. The national food code coordinates with pending Mercosur harmonization to reduce cross-border compliance overhead. Rosario's oilseed breeding programs face 18-24 month ANVISA novel ingredient approval delays.
Uruguay
Montevideo's aquaculture and poultry sectors import soy protein concentrate where underdeveloped domestic crushing infrastructure creates supply dependency. Feed compounders source Brazilian concentrates through riverine logistics corridors. Punta del Este specialty nutrition distributors serve premium hemp and rice protein niches.
Chile
Santiago metropolitan area sports nutrition brands drive isolate demand for powder and ready-to-drink applications. The country's national food regulator enforces protein content labeling alignment with Mercosur technical standards. Valparaíso port logistics enable Argentine pea protein transshipment to Pacific markets.
Paraguay
Asunción feed manufacturers rely on Brazilian soy concentrate imports where domestic oilseed processing remains insufficient for poultry sector scale. The central bank's trade financing facilities support commodity importer liquidity. Ciudad del Este distribution channels fragment across informal cross-border traders and formal distributor networks.
South America Plant Protein Ingredients Market Competitive Landscape
Concentration sits with integrated agribusiness conglomerates controlling upstream oilseed crushing and downstream protein fractionation. Brazilian and Argentine markets exhibit tiered competition between Panamax-scale logistics operators and specialty enzymatic fractionation specialists. Strategic archetypes span commodity traders, integrated processors, and hybrid starch-protein formulators. Dominant competitive moves include backward integration into captive oilseed supply and technology licensing for cold precipitation yield optimization.
Among North American-based agribusiness operators, Cargill Incorporated and Archer Daniels Midland Company exemplify scale-driven logistics archetypes leveraging Brazilian oilseed networks. Ingredion Incorporated represents the specialty hybrid tier through Argentine starch-protein investments. European specialists including Roquette Frères and Kerry Group occupy positions in premium isolate and formulation technology segments. Regional players such as BRF S.A. anchor domestic meat alternative supply chains.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Ingredion Incorporated |
| Kerry Group |
| Archer Daniels Midland Company |
| Roquette Frères |
| Tate & Lyle |
| DuPont de Nemours Inc. |
| Bunge Limited |
| BRF S.A. |
| Others |
Value Network & Pricing Analysis
Pea protein isolate substitution for soy concentrates is redrawing procurement geography across Mercosur trade zones while compressing margin pools previously anchored to Brazilian oilseed crushing networks. Argentine processors capture premium positioning through allergen-free certification tiers that São Paulo-based CPG brands now specify in shortened quarterly contracts.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in South American plant protein ingredients. Price differentiation rests on isolate purity grades and ANVISA novel food certification status, with spray-dried isolates commanding substantial premiums over flour-grade commodities. Cost compression in concentrate tiers is intensifying because Brazilian biofuel policy spillovers redirect soy crush volumes toward biodiesel channels. Feed compounders in Uruguay and Paraguay exhibit highest price sensitivity, while infant nutrition formulators in Minas Gerais tolerate premium tiers for hypoallergenic rice protein isolates.
Supply Chain Analysis
Port congestion at Santos and Paranaguá elevates inbound logistics costs for European enzymatic fractionation equipment and membrane filtration components essential to isolate production. Supply concentrates in Brazil, Argentina, and Uruguay, with Brazilian São Paulo and Paraná states anchoring soy protein concentrate output while Buenos Aires province processors lead pea fraction expansion. Raw material dependencies center on yellow pea imports from Canada, domestic soybeans from Mato Grosso, and natural gas for spray-drying thermal processing. Single-source vulnerability persists in Argentine pipeline gas supply that powers isolate yield optimization. Distribution runs through commodity traders for flour grades and direct-to-manufacturer channels for certified isolates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic extraction technology is disrupting established aqueous processing economics, creating asymmetric reward profiles for specialists versus legacy crushers as ANVISA fortification mandates tighten ingredient specifications.
For Market Incumbents: Consolidate backward integration into captive oilseed supply in Paraná and Mato Grosso to defend margin pools against Argentine pea protein entrants. Secure multi-year formulation partnerships with São Paulo CPG brands before contract durations compress further, and invest in cold precipitation yield optimization to preserve isolate profitability against energy cost volatility. For New Entrants and Emerging Players: Differentiate on allergen-free certification and organic provenance to penetrate Brazilian bakery and ready-to-drink channels where established soy suppliers carry legacy allergen exposure. Target Uruguayan aquaculture feed concentrate demand where domestic crushing infrastructure remains underdeveloped, and pursue direct-to-manufacturer channel strategies bypassing commodity trader markups. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors enzymatic fractionation specialists with proven ANVISA approval track records over legacy aqueous processors. Long-term viability across the analysis window hinges on isolate margin sustainability and regulatory certification moats. Acquisition candidates should demonstrate functional protein performance in meat alternative gelation applications. The signal to watch is MERCOSUR harmonization implementation timing, which would accelerate cross-border formulation contract consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Oilseed Supply | Secures upstream soy and pea volumes for Brazilian processors against Argentine competitor expansion. |
| Enzymatic Fractionation Technology Licensing | Enables precision isolate yield management that aqueous extraction cannot replicate for meat alternative manufacturers. |
| ANVISA Novel Food Certification Investment | Accelerates commercialization timelines for emerging legume fractions from regional breeding programs. |
| Direct-to-Manufacturer Channel Development | Bypasses commodity trader margins and secures multi-year partnerships with São Paulo CPG brands. |
| MERCOSUR Harmonization Compliance Preparation | Reduces dual-certification overhead for Argentine processors accessing Brazilian formulation contracts. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ANVISA regulatory filings, CONAB oilseed procurement statistics, MERCOSUR technical regulations, and trade customs data. Primary interviews engaged protein extraction plant managers, formulation chemists at Brazilian meat alternative manufacturers, procurement leads at Argentine bakery processors, and regulatory affairs specialists navigating novel food approvals. Secondary validation drew from SEC filings of North American agribusiness operators, Brazilian biofuel policy disclosures, and regional crushing capacity databases. Bottom-up volume modeling triangulated against top-down value estimates derived from isolate-concentrate price spreads.
Segmentation dimensions modeled include protein source type, application end-use, processing form grade, and customer archetype across the projection horizon. Value forecasts incorporate isolate premium tier expansion, concentrate commodity baseline erosion, and feed-grade import dependency in Uruguay and Paraguay. CAGRs were derived from volume trajectory analysis indexed to oilseed futures correlation and regulatory implementation schedules. Industry-specific inputs encompass spray-drying energy cost curves, enzymatic yield improvement coefficients, and ANVISA approval pipeline velocity.
The analysis sits within stated boundaries; outcomes outside sustained MERCOSUR regulatory harmonization, stable Argentine natural gas supply, and continued Brazilian biofuel policy spillover patterns would require recalibration. Forecasts reflect documented assumptions regarding protein fractionation technology adoption curves and certification timeline distributions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Halal and Kosher Empty Capsules Market
Ingredients
Cosmetic Bioactive Ingredients Market
Ingredients
Asia-Pacific Brewing Enzymes Market
Ingredients
Global Fresh Compressed Yeast Market
Ingredients
China Cane Sugar Market
Ingredients
Egg Phosphatidylcholine Market
Ingredients
Stock Cubes Market
Ingredients
Cheese Ripening Enzymes Market
Ingredients
Glucosylglycerol Market
Ingredients
Bulk Food Ingredients Market
Ingredients
Global Malt and Malt Extracts Market
Ingredients
Specialty Yeast Market
Ingredients
Blue Light Protection Ingredients Market
Ingredients
Spelt Flour Market
Ingredients
Global Alpha-Lactalbumin Market
Ingredients
Global Whey Protein Ingredients Market