
 Luxury Wines and Spirits Market | 2026-2036
Luxury Wines and Spirits Market Size, Share, and Industry Trends Forecast 2026-2036
Luxury Wines and Spirits Market Analysis
Single-serve luxury formats and curated tasting sets is hardening as the dominant packaging configuration for premium spirits. Pernod Ricard leverages its global distribution network to sustain volume leadership in ultra-premium segments. Diageo anchors its competitive position through backward integration into aged Scotch inventory. LVMH differentiates via vertical control across Champagne houses and cognac estates.
Luxury wines and spirits encompass alcoholic beverages produced from fermented grapes or distilled grains, subject to controlled-origin specifications, minimum aging protocols, and alcohol-by-volume thresholds typically exceeding 15% for spirits and 11% for still wines, serving ceremonial, gastronomic, and investment-grade collection purposes. Champagne and aged spirits occupy the deepest margin pools due to production scarcity and cellar-time requirements. Red wine competes most intensely for shelf space in specialty retail channels. Direct sales channels are capturing growing share among private collectors seeking provenance verification.
France's ANSM enforces strict appellation controls that limit Champagne production to designated terroirs, while the EU's REACH and CE marking frameworks govern bottle materials and import labeling. The US TTB and FDA jointly regulate alcohol content disclosures and additive permissions for imported luxury spirits. Stakeholders must monitor evolving e-commerce alcohol regulations across target markets to preserve channel access and pricing architecture.
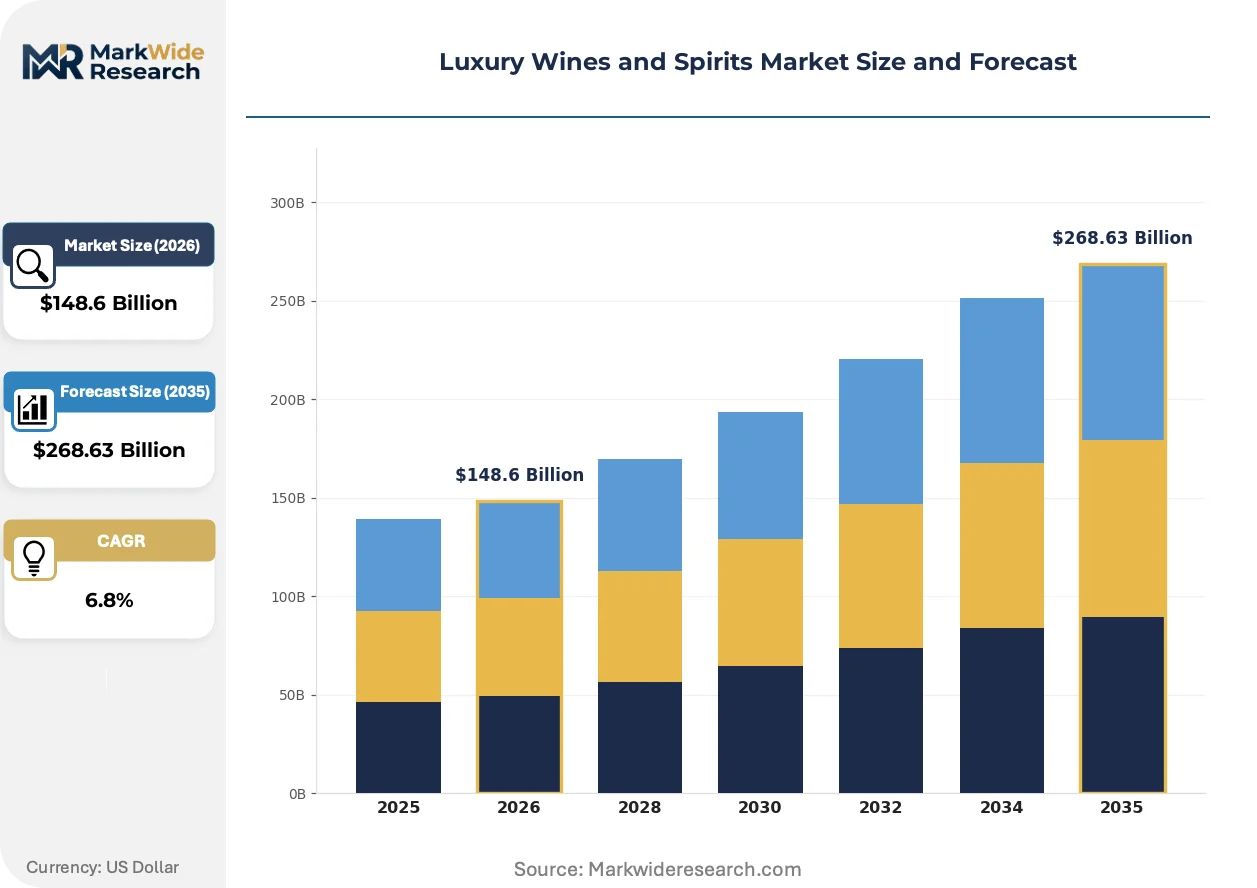
Market Dynamics
EU REACH compliance and France's ANSM appellation controls are tightening bottling material specifications and vineyard yield limits, compressing supply elasticity for Champagne and aged spirits while redirecting capital toward cellar automation and alternative closure systems.
Growth Catalysts
- High-net-worth millennial hospitality demand:Ultra-premium spirits consumption concentrates in private dining clubs and boutique hotel bars across London, New York, and Singapore, pulling aged inventory into experiential service formats.
- REACH material standards:EU-mandated glass and label composition rules are accelerating investment in recycled-content bottle molding and non-toxic adhesive alternatives for imported luxury spirits.
- Speyside whisky corridor concentration:Scotland's bonded warehouse infrastructure and water-source proximity continue to attract cask-financing vehicles and private collector storage facilities.
Market Restraints
- Barley and grape input volatility:Climate-induced harvest compression in Burgundy and the Scottish Highlands is elevating raw material cost uncertainty for single-estate producers.
- Champagne terroir supply ceiling:ANSM yield caps limit annual bottle production regardless of demand pull, creating structural scarcity that prices out emerging market entrants.
- TTB additive disclosure friction:US import labeling requirements for coloring agents and flavor modifiers delay product registration timelines by six to eighteen months for European entrants.
Strategic Opportunities
- Direct-to-collector e-commerce channels:Blockchain-verified provenance platforms are capturing private buyers in Hong Kong and Dubai who bypass traditional auction houses for cask and bottle acquisitions.
- Single-serve tasting set formats:Curated 50ml luxury spirit samplers are penetrating airline duty-free and corporate gifting segments previously unreachable through full-bottle distribution.
- EU F-Gas Regulation cellar incentives:Climate-controlled storage rebates for low-emission cooling systems are lowering operational costs for aged inventory facilities in France and Italy.
Industry Challenges
- Master distiller and cellar master scarcity:Generational talent gaps in Scotch whisky and Cognac production are extending apprenticeship pipelines and elevating compensation costs for heritage houses.
- Cask financing liquidity constraints:Whiskey and rum barrel investment vehicles face valuation opacity and exit-path uncertainty, complicating balance sheet management for inventory-heavy producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Luxury Wines and Spirits Market |
| Market Size in 2026 | $148.6 Billion |
| Market Size in 2035 | $268.63 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Red Wine, White Wine, Champagne, Spirits End User: Restaurants, Hotels, Retail Stores, Private Collectors Price Tier: Premium, Super Premium, Ultra Premium, Luxury Distribution Channel: Online Retail, Specialty Stores, Wholesale, Direct Sales |
| Companies Covered | Bacardi, Beam Suntory, Pernod Ricard, William Grant & Sons, Campari, Diageo, Brown Forman, Edrington Group, LVMH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Luxury Wines and Spirits Market Emerging Trajectories
Blockchain traceability systems and AI-driven climate control are compressing authentication timelines and cellar management costs, while regulatory material bans and shifting collector procurement patterns are redrawing competitive boundaries across the luxury spirits value chain.
NFC-enabled bottle authentication is expanding into high-value single-malt and vintage Champagne segments. Private collectors and auction houses in Hong Kong and Geneva are adopting chip-embedded closures at accelerating rates. This technology is expanding into secondary market verification, reducing fraud exposure and shortening due diligence cycles for cross-border transactions.
EU F-Gas Regulation phase-down schedules are mandating hydrocarbon and CO2-based cooling systems in bonded warehouses. French and Scottish storage facilities face retrofit deadlines that elevate capital deployment for climate-controlled aging environments. Champagne houses with extensive cellar networks are absorbing the steepest compliance costs while securing operating permits for extended vintage programs.
Collector procurement is fragmenting across direct-from-distillery allocation lists, specialized e-commerce platforms, and tokenized cask ownership structures. Traditional merchant and auction channels in London and New York are losing volume share to digitally native intermediaries offering fractional bottle exposure. This behavioral pivot is most pronounced among Asian ultra-high-net-worth buyers seeking provenance transparency without intermediary markups.
Luxury Wines and Spirits Market Segmentation
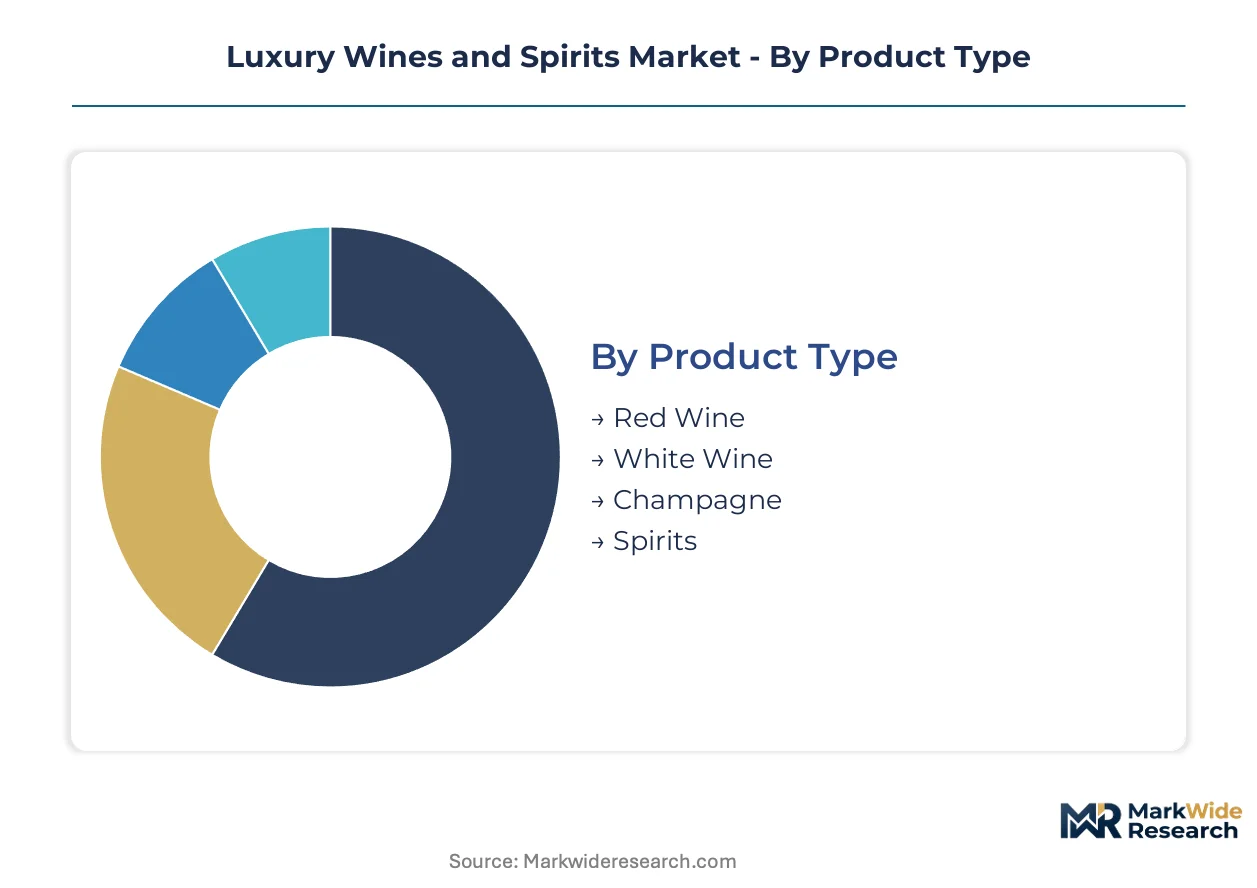
Segmentation in luxury wines and spirits reveals how capital deployment, regulatory exposure, and collector behavior fragment across product categories and channel structures. Producers align inventory aging protocols and distribution investments against specific buyer archetypes and margin profiles.
Product Type:
Champagne and aged spirits command the heaviest upfront cellar infrastructure investment, while still wines require less capital-intensive aging but greater vineyard land allocation.
- Red Wine:Cabernet Sauvignon and Pinot Noir bottlings from Bordeaux and Burgundy dominate auction turnover. Collector demand concentrates in Hong Kong and Geneva for first-growth classified growths, constrained by climate-induced harvest compression in French appellations.
- White Wine:Chablis grand cru and white Burgundy expressions attract gastronomic channel placement. Restaurant procurement in Paris and Tokyo favors these pairings for seafood-forward tasting menus, though oxidative stability limits extended cellar programs.
- Champagne:Vintage and prestige cuvee releases require minimum aging mandates under France's ANSM protocols. Production scarcity from yield-capped terroirs creates structural supply ceilings regardless of demand pull from private aviation and yachting segments.
- Spirits:Single-malt Scotch and Cognac carry the longest production cycles. Speyside bonded warehouse capacity and Limousin oak sourcing constraints concentrate investment in heritage houses with captive inventory pipelines.
Most installed capacity flows through Spirits. Expansion is steepest in Champagne.
End User:
Channel selection determines margin capture, with hospitality and direct collector access yielding superior returns against wholesale intermediation.
- Restaurants:Michelin-starred establishments in London and New York drive allocation-list access for limited releases. Sommelier relationships and by-the-glass pricing authority enable producers to bypass traditional merchant markups for marquee vintages.
- Hotels:Boutique properties and private dining clubs across Singapore and Dubai anchor ultra-premium spirits consumption in experiential formats. Mini-bar and in-room curated selections extend brand exposure to transient high-net-worth guests.
- Retail Stores:Specialist merchants in Paris, London, and Geneva maintain temperature-controlled storage and provenance documentation. These channels serve intermediary roles for collectors seeking auction alternatives with immediate physical inspection.
- Private Collectors:Direct-from-distillery allocation lists and blockchain-verified e-commerce platforms are displacing traditional merchant relationships. Asian ultra-high-net-worth buyers in Hong Kong prioritize provenance transparency without intermediary markups.
Volume concentrates in Retail Stores. Margin expansion is climbing the fastest in Private Collectors.
Price Tier:
Pricing stratification reflects production scarcity, aging duration, and origin certification rather than manufacturing cost differentials alone.
- Premium:Entry-level classified growths and aged spirit expressions with controlled-origin designation. Distribution concentrates in specialty retail and airline duty-free channels where brand education supports trial conversion.
- Super Premium:Single-vineyard wines and small-batch spirits with extended cellar aging. Collector demand in the US and UK favors these tiers for drinking-cellars versus pure investment holding.
- Ultra Premium:Limited releases and vintage-dated expressions with verified provenance chains. Private dining clubs and boutique hotel bars across London and Singapore pull aged inventory into service formats at substantial markup.
- Luxury:Auction-grade rarities and estate-direct allocations with multi-decade aging potential. Blockchain-verified authentication and single-cask bottlings dominate transaction structures at this tier.
Revenue contribution peaks in Ultra Premium. Collector attention is gathering fastest in Luxury.
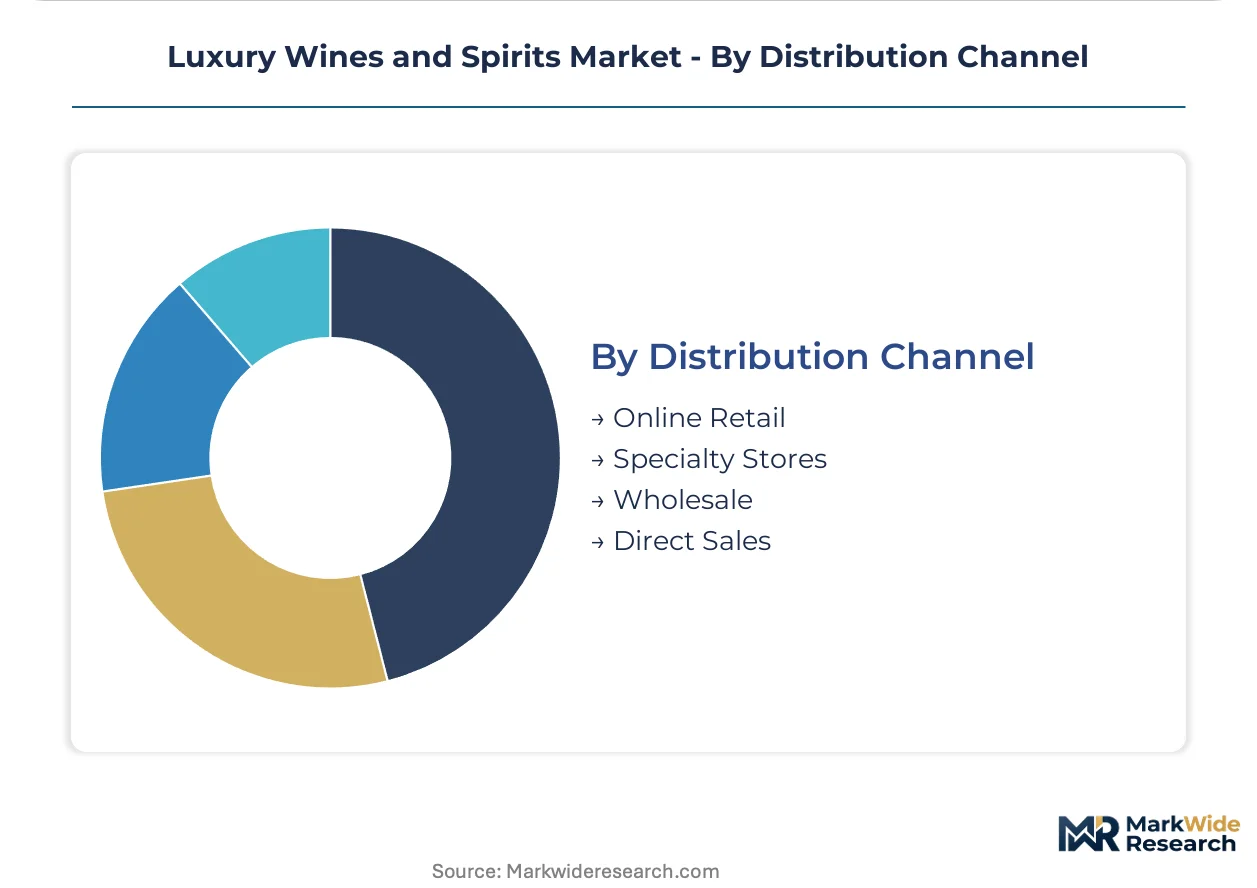
Distribution Channel:
Channel configuration determines regulatory compliance burden and pricing architecture preservation across import jurisdictions.
- Online Retail:Specialized e-commerce platforms with provenance verification are capturing volume from traditional auction houses. EU REACH labeling requirements and US TTB additive disclosures create registration friction for cross-border listings.
- Specialty Stores:Temperature-controlled merchants in Paris, London, and Geneva maintain physical inspection and immediate fulfillment advantages. These outlets absorb compliance costs for EU F-Gas Regulation cellar standards and CE marking requirements.
- Wholesale:Traditional import-distributor networks face margin compression from direct-to-collector alternatives. Three-tier system constraints in the US limit pricing flexibility for European entrants navigating TTB registration timelines.
- Direct Sales:Distillery allocation lists and tokenized cask ownership structures eliminate intermediary markups. This channel is expanding most quickly among Asian collectors seeking fractional exposure to aged inventory without auction-house fees.
Transaction volume still routes through Wholesale. Platform investment is accelerating most sharply in Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's Champagne region and Scotland's Speyside corridor established the foundational infrastructure for luxury spirits production centuries ago, creating terroir-linked scarcity that persists as the industry's geographic anchor. These origins continue to concentrate capital, talent, and regulatory attention in Western European production zones.
France
Private aviation and yachting segments pull vintage Champagne releases into experiential consumption formats, while ANSM yield caps enforce structural supply ceilings regardless of demand intensity. The EU's REACH framework governs bottle glass composition and adhesive specifications for export-bound inventory. Reims and Épernay host the densest concentration of prestige cuvée aging cellars, where houses are retrofitting climate systems to meet F-Gas Regulation phase-down timelines.
United Kingdom
London's private dining clubs and specialist merchants drive allocation-list access for limited Scotch releases, compressing traditional merchant markups. The UK's post-EU labeling requirements create friction for European import registrations, though the TTB parallel process for US-bound exports remains streamlined. Speyside's bonded warehouse infrastructure and water-source proximity attract cask-financing vehicles and collector storage facilities at accelerating rates.
United States
High-net-worth millennial hospitality demand concentrates in New York boutique hotel bars and Michelin-starred establishments, pulling aged inventory into by-the-glass service formats. TTB and FDA joint oversight of alcohol content disclosures and additive permissions extends product registration timelines for European entrants. California's Napa Valley and Sonoma County anchor domestic ultra-premium wine production, though climate-induced harvest compression elevates raw material cost uncertainty.
Singapore
Boutique properties and private dining clubs anchor ultra-premium spirits consumption among transient wealth, with mini-bar curated selections extending brand exposure. The city-state's strict import licensing framework governs alcohol distribution channels, preserving pricing architecture for heritage houses. Blockchain-verified e-commerce platforms are capturing private collectors seeking provenance transparency without intermediary markups.
China
Direct-from-distillery allocation lists and tokenized cask ownership structures are displacing traditional merchant relationships among ultra-high-net-worth buyers. SAMR and national standards bodies enforce labeling and additive disclosure requirements for imported luxury spirits. Shanghai and Beijing host the densest concentration of private collector procurement activity, with digital-native intermediaries gaining volume share from London and New York auction channels.
Luxury Wines and Spirits Market Vendor Landscape
The competitive structure tilts toward heritage houses with captive inventory pipelines and multi-decade aging programs. Consolidation concentrates among French and British entities controlling appellation-linked production zones, while fragmentation persists in specialty retail and digital intermediary layers. Three archetypes dominate: integrated luxury conglomerates with vertical estate control, standalone spirits specialists with bonded warehouse networks, and digital-native provenance platforms. M&A activity targets cask-financing vehicles and blockchain authentication technologies, while capacity expansion focuses on climate-compliant cellar retrofitting.
Among heritage spirits houses, Pernod Ricard and Diageo occupy positions exemplifying scale-driven distribution architecture and backward integration into aged inventory respectively. LVMH anchors the luxury-tier vector through estate control across Champagne houses and cognac producers. These three entities represent contrasting strategic postures: network leverage versus captive supply versus vertical terroir ownership.
| Leading Market Players |
|---|
| Bacardi |
| Beam Suntory |
| Pernod Ricard |
| William Grant & Sons |
| Campari |
| Diageo |
| Brown Forman |
| Edrington Group |
| LVMH |
| Others |
Supply Flow & Price Mechanics
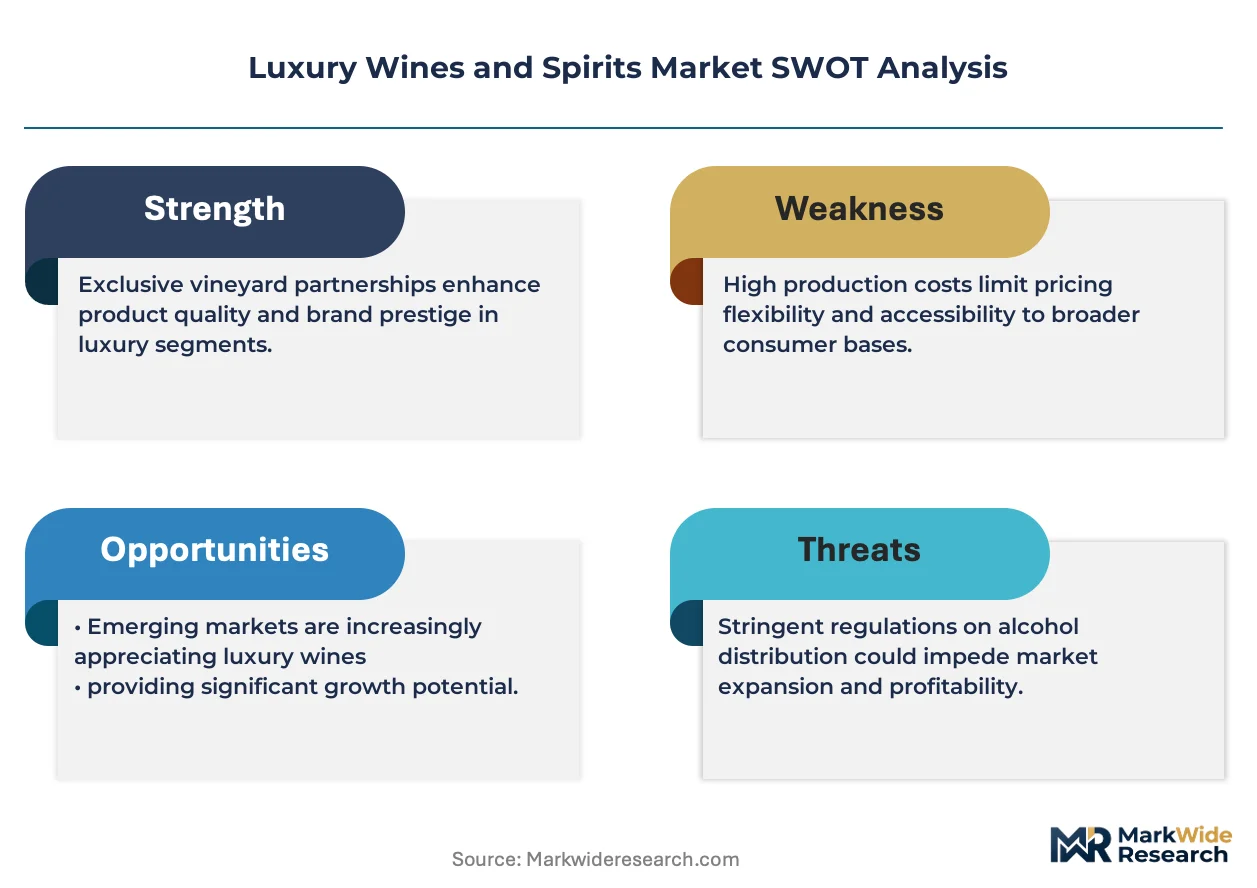
EU F-Gas Regulation phase-down schedules gate both climate-compliant bonded warehouse supply and premium-tier pricing access for aged inventory, compressing cellar infrastructure availability while elevating entry costs for producers seeking luxury-tier positioning.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies luxury wines and spirits by cellar aging duration and appellation certification. Price differentiation hinges on ANSM-controlled origin designation and verified provenance documentation. Cost compression in super-premium tiers is intensifying because climate-induced harvest volatility in Burgundy and the Scottish Highlands elevates raw material uncertainty. Emerging market collectors exhibit highest price sensitivity, while private aviation and yachting segments absorb luxury-tier markups without volume elasticity.
Supply Chain Analysis
Limousin oak sourcing rests on French forestry cooperatives and Scottish bonded warehouse capacity draws from Speyside water-source proximity. Raw material dependencies center on barley varietals from the Scottish Highlands, grand cru vineyard parcels in Champagne, and Cognac eaux-de-vie stocks. Single-source vulnerability concentrates in heritage houses with captive Limousin oak contracts. Distribution runs through specialist merchants in Paris, London, and Geneva maintaining temperature-controlled provenance documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in luxury wines and spirits derives from direct-to-collector channel capture and F-Gas Regulation cellar retrofit incentives lowering operational cost bases for aged inventory facilities.
For Market Incumbents: Cement cellar infrastructure dominance by accelerating climate-compliant bonded warehouse retrofitting ahead of EU F-Gas Regulation deadlines. Deepen backward integration into Limousin oak forestry partnerships to secure barrel supply against forestry cooperative consolidation. Blockchain-verified provenance platforms threaten authentication service margins—incumbents must control proprietary chip-embedded closure deployment.
For New Entrants and Emerging Players: SAMR labeling simplification in China opens a window for European entrants to bypass traditional merchant markups through direct-from-distillery allocation lists. Target Hong Kong and Dubai collector segments with tokenized cask ownership structures offering fractional exposure without auction-house fees. Lead with blockchain-native provenance verification as primary go-to-market differentiation against heritage house intermediation.
For Investors and Strategic Acquirers: Roll-up economics work for cask-financing vehicles because valuation opacity and exit-path uncertainty strand smaller inventory-heavy producers. Long-term viability centers on acquiring bonded warehouse networks with F-Gas Regulation-compliant climate systems already deployed. Watch for ANSM yield cap adjustments as inflection signal for Champagne production scarcity premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Cellar Climate Retrofitting | EU F-Gas Regulation compliance secures operating permits for extended vintage programs in Reims and Épernay. |
| Blockchain Provenance Integration | NFC-enabled authentication reduces fraud exposure for Hong Kong and Geneva auction channel transactions. |
| Direct-to-Collector Platform Launch | Eliminates intermediary markups for Asian ultra-high-net-worth buyers seeking allocation-list access. |
| Limousin Oak Backward Integration | Captive forestry partnerships insulate barrel supply against French cooperative consolidation pressures. |
| Single-Serve Format Expansion | 50ml tasting sets penetrate airline duty-free and corporate gifting segments unreachable through full-bottle distribution. |
Methodological Framework
Multiple input streams — primary interviews, trade customs data, regulatory filing repositories — were reconciled to construct segment-level demand estimates. Cellar masters at heritage Champagne houses, bonded warehouse operators in Speyside, and specialist merchant procurement heads in Paris and London provided operational validation. Secondary sources included ANSM production filings, EU REACH substance registrations, TTB label approvals, and customs records from Geneva and Hong Kong. Bottom-up inventory aging protocols and top-down channel revenue estimates were triangulated against bonded warehouse capacity disclosures.
Historical volume trajectories were cross-referenced against panel inputs from distillery allocation managers and collector platform operators across the analysis window. Segmentation modeling incorporated product type, price tier, end-user channel, and distribution format dimensions. CAGRs were derived from vintage release schedules, yield cap constraints, and cellar infrastructure investment pipelines. Forecast inputs centered on climate-induced harvest compression patterns and regulatory compliance cost curves for F-Gas Regulation retrofitting.
Revisions become necessary when ANSM adjusts Champagne yield ceilings, when SAMR modifies import labeling requirements, or when blockchain authentication achieves mass adoption in secondary markets. A small set of named triggers — regulatory yield adjustments, e-commerce alcohol liberalization, and climate system compliance deadlines — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Organic Alcoholic Beverages Market
Alcoholic Beverages
Wine Glass Market
Alcoholic Beverages
Ethyl Alcohol (Ethanol) Market
Alcoholic Beverages
Beer Line Cleaning Kit Market
Alcoholic Beverages
Chardonnay Market
Alcoholic Beverages
Japan Beer Market
Alcoholic Beverages
Europe Craft Spirits Market
Alcoholic Beverages
Alcoholic Ready-To-Drink (Rtds)/High Strength Premixes Market
Alcoholic Beverages
Gluten Free Alcoholic Drinks Market
Alcoholic Beverages
Oak Barrel Alternatives Market
Alcoholic Beverages
West Africa Alcoholic Beverages Market
Alcoholic Beverages
Premixed Margarita Market
Alcoholic Beverages
United States Spirits Market
Alcoholic Beverages
Beer Line Cooling System Market
Alcoholic Beverages
Black Beer Market
Alcoholic Beverages
Beer Processing Market