
 Honey Powder Market | 2026-2036
Honey Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Honey Powder Market Analysis
Market Context
The honey powder category is consolidating around a widening split between premium organic grades and commodity conventional offerings. Ingredion leverages its ingredient formulation expertise to serve large food manufacturers seeking consistent bulk supply, while Norevo anchors its position through specialized honey-derived ingredients for European confectionery clients. ADM competes across both tiers with integrated sweetener portfolios that span liquid and dried formats.
Technical Definition and Segment Structure
Honey powder consists of dehydrated liquid honey blended with carrier agents such as maltodextrin or starch, typically containing 50-70% honey solids by weight, and functions primarily as a free-flowing, non-sticky sweetener for industrial food processing and dry mix applications. Organic honey powder commands premium positioning within the product type dimension as brands pursue clean-label certification, while conventional honey powder retains volume leadership in cost-sensitive bakery and beverage applications. Within applications, food and beverage manufacturing dominates current offtake, though nutraceuticals represents the fastest-expanding consumption channel as functional food formulations proliferate.
Regulatory Environment
The FDA governs honey powder labeling and identity standards under 21 CFR, while USDA organic certification shapes premium tier access, and EU REACH frameworks influence carrier agent compliance for exports into European food manufacturing channels. Stakeholders must monitor evolving definitions of "natural" and "pure" across jurisdictions, as regulatory reinterpretation of these terms could force rapid reformulation of existing product lines or exclusion from key retail channels.
Market Dynamics
Clean-label regulations in the European Union and United States are tightening additive disclosure requirements for natural sweeteners, forcing ingredient processors to requalify carrier agents and certify supply chain traceability.
Growth Catalysts
- EU Clean-Label Mandates:REACH frameworks and EFSA guidance on natural claims are compelling bakery manufacturers to replace liquid honey with certified organic powder formats that simplify compliance documentation.
- Food and Beverage Manufacturing:Industrial buyers in the confectionery segment are accelerating adoption of honey powder as a shelf-stable alternative to liquid honey, reducing handling complexity and extending formulation windows.
- German Organic Supply Chains:Ingredient processors in Germany are prioritizing certified organic honey powder, creating concentrated demand that pulls premium-grade supply toward European food manufacturing channels.
Market Restraints
- Carrier Agent Cost Volatility:Maltodextrin and modified starch prices fluctuate with corn and tapioca feedstock markets, compressing margins for conventional honey powder producers.
- Supply Concentration Risk:Premium organic honey sourcing concentrates in specific apiary regions, exposing processors to climate-driven yield variability and regional pollination stress.
- Technical Limitation:Honey powder retains 50-70% honey solids by weight, limiting direct substitution ratios in formulations requiring pure honey flavor intensity without volume adjustment.
Strategic Opportunities
- Underpenetrated Nutraceuticals Channel:Functional food formulations in dietary supplements represent the fastest-expanding consumption channel for honey powder as a natural sweetener in probiotic and protein blends.
- USDA Organic Certification Tailwind:USDA organic certification shapes premium tier access, enabling processors to command price premiums through verified supply chain documentation.
- Spray-Drying Technology Convergence:Advances in low-temperature spray-drying are converging with encapsulation techniques to improve flavor retention and extend shelf stability beyond current 12-18 month benchmarks.
Industry Challenges
- Certification Timeline Compression:USDA organic and EU organic certification processes require 18-36 months for supply chain verification, delaying new product launches and locking out opportunistic market entrants.
- Integration Complexity with Legacy Dry-Mix Systems:Food manufacturers operating established pneumatic conveying and blending equipment face retrofit requirements to handle honey powder's hygroscopic properties without caking or flow interruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Honey Powder Market |
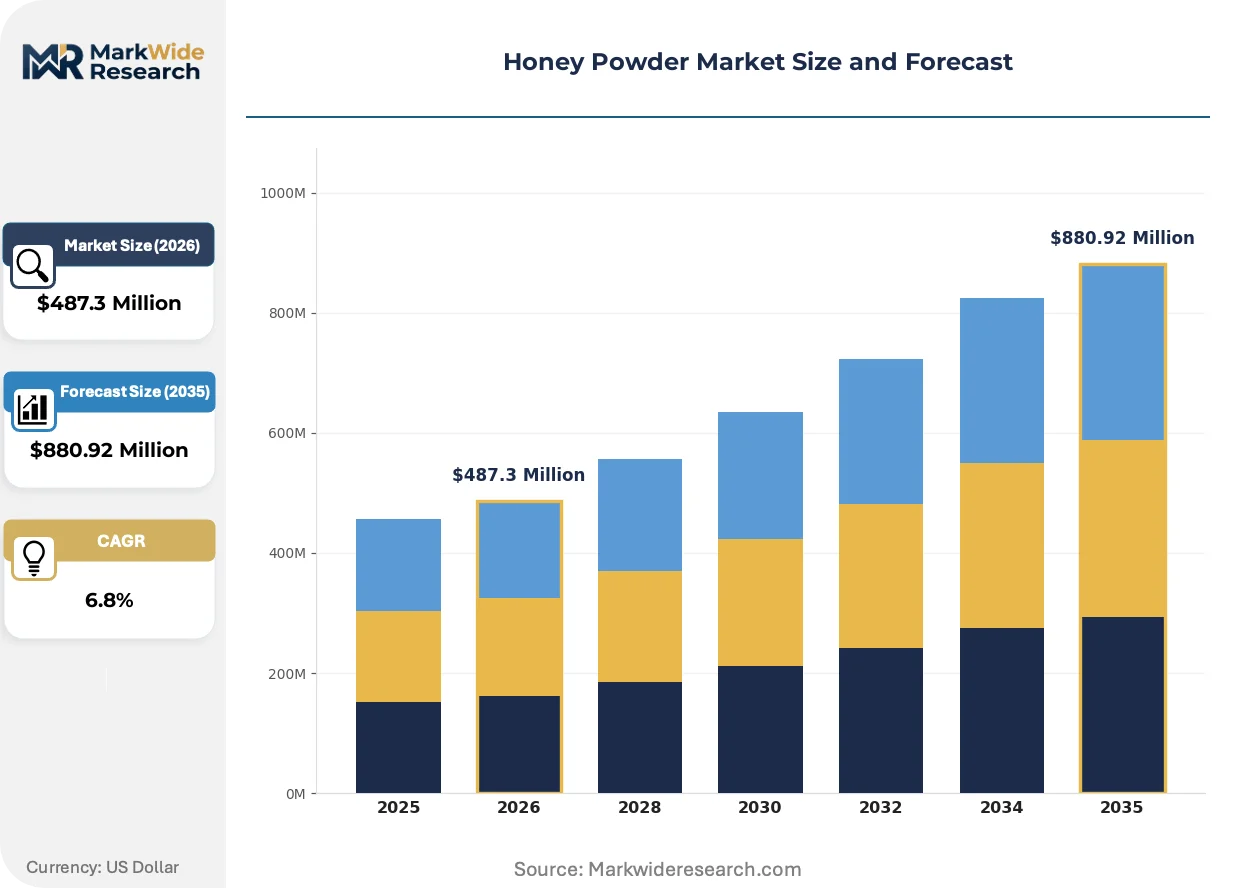
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Honey Powder, Conventional Honey Powder, Flavored Honey Powder, Instant Honey Powder Application: Food & Beverage, Nutraceuticals, Cosmetics, Pharmaceuticals Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale End User: Households, Food Manufacturers, Health Stores, Restaurants |
| Companies Covered | AmTech Ingredients, Ingredion, ADM, Augason Farms, Great American Spice Company, Norevo, G&S Foods, Whole Earth Brands, Cargill, Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Honey Powder Market Emerging Trajectories
Formulation science and regulatory reinterpretation are actively reshaping how honey powder is positioned, processed, and procured across industrial food channels.
Spray-drying technology with maltodextrin carriers is absorbing moisture-sensitive applications previously reserved for liquid honey or synthetic sweeteners. Bakery and dry-mix manufacturers are adopting these formats at accelerating pace to eliminate sticky handling equipment and reduce sanitation downtime. The technology is absorbing market share from liquid honey in shelf-stable cookie, cracker, and cereal coating applications where flowability determines production line efficiency.
REACH frameworks governing carrier agent compliance are tightening disclosure thresholds for exports into European food manufacturing channels. Industrial consequence includes mandatory requalification of maltodextrin and starch sources for residual solvent content and allergen cross-contact risk. German and French confectionery processors are responding by demanding batch-level certificates of analysis and third-party audited supply chain documentation from honey powder suppliers.
Buyer concentration among large food manufacturers is compressing supplier qualification cycles and unbundling technical service from commodity supply contracts. Mid-sized ingredient distributors are losing share to direct procurement relationships as Cargill, ADM, and Ingredion field dedicated account teams for honey powder formulations. This pattern is most visible in North American bakery channels where three national manufacturers now account for the majority of certified organic honey powder offtake.
Honey Powder Market Segmentation
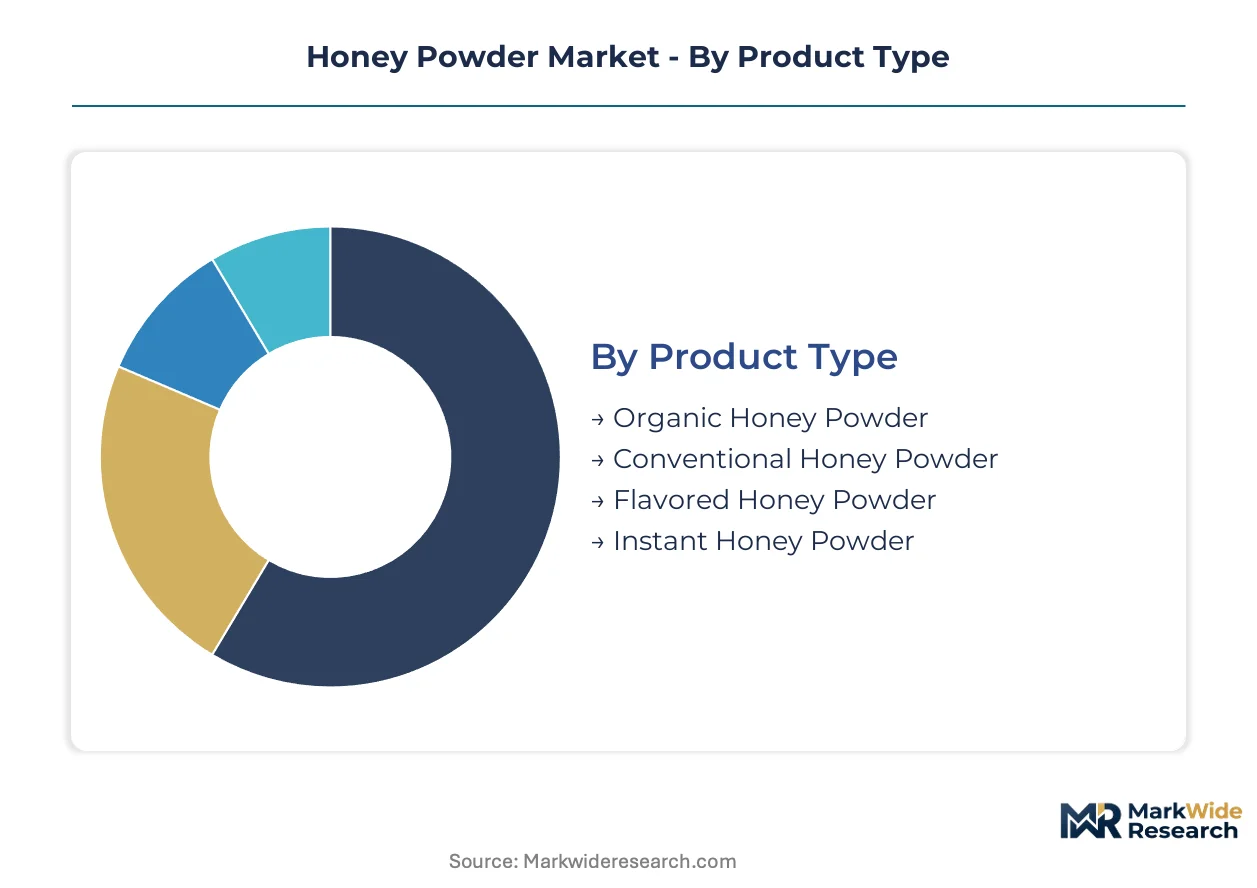
Honey powder procurement splits sharply across certification tiers, application requirements, and channel access protocols. Buyers prioritize organic certification for clean-label compliance, while industrial users optimize for handling efficiency and formulation stability.
Product Type:
Certification grade drives price premiums and regulatory access more than any other factor in honey powder selection.
- Organic Honey Powder:Contains certified organic honey solids with USDA or EU organic carrier agents, commanding 40-60% price premiums over conventional grades. German confectionery processors and North American natural food brands concentrate procurement here to satisfy EFSA and FDA disclosure mandates.
- Conventional Honey Powder:Standard maltodextrin or starch carriers with non-certified honey feedstock, retaining volume leadership in cost-sensitive bakery and beverage manufacturing. Price volatility in corn-derived carriers compresses margins for processors serving commodity cookie and cracker coatings.
- Flavored Honey Powder:Infused variants with vanilla, cinnamon, or fruit essences targeting specialty dry-mix and beverage applications.
- Instant Honey Powder:Agglomerated particles engineered for rapid cold-water solubility in instant tea and functional drink formulations.
Volume sits with Conventional Honey Powder; growth tilts toward Organic Honey Powder.
Application:
End-use functionality determines carrier selection, particle size specifications, and moisture sensitivity thresholds.
- Food & Beverage:Dominates current offtake across bakery coatings, cereal inclusions, dry dessert mixes, and shelf-stable beverage bases. Industrial buyers in cookie and cracker manufacturing prioritize free-flow properties that eliminate sticky handling equipment and reduce sanitation downtime.
- Nutraceuticals:Probiotic gummies, protein powders, and functional supplements are expanding most quickly as honey powder replaces synthetic sweeteners in clean-label formulations. Supplement manufacturers value batch-level organic certification for retail channel access.
- Cosmetics:Exfoliating scrubs, lip balms, and mask powders leverage honey powder's humectant properties without liquid phase instability.
- Pharmaceuticals:Excipient applications in chewable tablets and cough drop formulations require pharmacopeial-grade carrier documentation.
Food & Beverage captures current volume; Nutraceuticals shows the steepest expansion trajectory.
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and certification documentation needs.
- Online Retail:Direct-to-manufacturer portals and B2B platforms are gaining share fastest as mid-sized food processors bypass traditional distribution tiers for certified organic supply.
- Supermarkets:Retail-packaged honey powder for household baking remains limited to specialty and natural grocery chains.
- Specialty Stores:Health food retailers and organic cooperatives serve small-batch confectioners and artisan bakers with bagged organic grades.
- Wholesale:Industrial distributors with bulk pneumatic delivery capabilities retain lock on large food manufacturer accounts requiring just-in-time replenishment.
Wholesale holds established volume; Online Retail is climbing the fastest.
End User:
User scale determines packaging format, minimum order quantities, and technical support intensity.
- Food Manufacturers:National bakery and confectionery operations specify bulk tote quantities with dedicated account engineering support for pneumatic system integration.
- Households:Small-format retail canisters target home bakers seeking shelf-stable alternatives to sticky liquid honey.
- Health Stores:Private-label and branded organic honey powder for supplement compounding and natural food retail.
- Restaurants:Limited adoption in commercial kitchens due to reconstitution requirements; concentrated in bakery-café chains with centralized commissary production.
Food Manufacturers anchor procurement volume; Health Stores are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cologne anchors European honey powder procurement as German confectionery processors consolidate certified organic supply chains for clean-label compliance.
United States
Industrial bakers in Chicago and Minneapolis-St. Paul drive bulk demand for conventional honey powder in cookie and cracker coatings. FDA labeling requirements under 21 CFR tighten disclosure standards for natural sweetener claims. Pacific Northwest apiary networks supply organic feedstock to processors serving West Coast natural food brands.
Germany
REACH frameworks compel ingredient processors to requalify maltodextrin carriers for residual solvent documentation. EFSA guidance on natural claims accelerates replacement of liquid honey with certified organic powder formats. Bavarian and North Rhine-Westphalian confectionery clusters concentrate premium-grade procurement.
China
SAMR food additive standards shape carrier agent compliance for domestic and export-bound production. Yangtze River Delta processors scale spray-drying capacity to serve functional food manufacturers. Zhejiang and Jiangsu provinces concentrate equipment engineering and contract drying services.
India
FSSAI clean-label mandates push domestic brands toward honey-derived sweeteners in traditional confectionery. Maharashtra and Gujarat house ingredient distributors bridging imported organic supply with regional bakery chains. Karnataka's nutraceutical manufacturers trial honey powder in protein blend formulations.
Brazil
ANVISA pharmaceutical excipient standards create compliance pathways for honey powder in chewable tablet applications. São Paulo's dietary supplement manufacturers source certified organic grades for export to North American health channels. Minas Gerais apiary cooperatives expand organic honey collection to meet processor demand.
Honey Powder Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification tiers, with organic-certified supply commanding structural price premiums. The vendor base separates into three strategic archetypes: diversified ingredient conglomerates with integrated sweetener portfolios, specialized honey-derived ingredient processors, and regional distributors with pneumatic bulk-handling capabilities. Dominant competitive moves include backward integration into apiary supply networks and technology licensing for low-temperature spray-drying equipment.
Within the diversified conglomerate tier, Ingredion and ADM exemplify formulation-scale positioning across liquid and dried sweetener formats. Norevo occupies a specialist position among European honey-derived ingredient processors serving confectionery clients. Augason Farms and Great American Spice Company represent mid-scale domestic suppliers with retail and foodservice channel access. AmTech Ingredients anchors a position in carrier-agent optimization for industrial bakery applications.
| Leading Market Players |
|---|
| AmTech Ingredients |
| Ingredion |
| ADM |
| Augason Farms |
| Great American Spice Company |
| Norevo |
| G&S Foods |
| Whole Earth Brands |
| Cargill, Incorporated |
| Others |
Supply Flow & Price Mechanics
Low-temperature spray-drying technology convergence with encapsulation techniques simultaneously compresses production costs for processors and concentrates supply capacity among equipment-integrated manufacturers in Germany, China, and the United States. This production-method transition rewards capital-intensive operators with flavor-retention advantages while marginalizing smaller toll-drying facilities dependent on legacy high-heat systems.
Pricing Analysis
USDA organic certification anchors value-based pricing for honey powder, with verified supply chain documentation commanding substantial premiums over conventional grades. Three-tier pricing stratifies across organic-certified, conventional-industrial, and commodity-coating tiers, with price differentiation driven by certification level and volume scale. Cost compression in conventional maltodextrin-based grades is intensifying because corn feedstock volatility and carrier-agent requalification expenses squeeze processor margins. National bakery manufacturers with pneumatic bulk-handling infrastructure exhibit lowest price sensitivity, while mid-sized dry-mix processors without certification requirements drive hardest bargaining on conventional supply.
Supply Chain Analysis
Freight costs for hygroscopic honey powder constrain viable sourcing radii, favoring regional production clusters over intercontinental supply. Manufacturing concentrates in Germany, China, and the United States, with each hub serving adjacent food manufacturing corridors to minimize moisture-exposure transit risks. Raw material sourcing draws from Bavarian and North Rhine-Westphalian apiary networks for European organic feedstock, Yangtze River Delta maltodextrin suppliers for Asian carrier agents, and Pacific Northwest apiary cooperatives for North American organic grades. Single-source vulnerability in premium organic honey collection regions exposes processors to climate-driven yield variability. Distribution runs through industrial distributors with pneumatic bulk-handling capabilities for large food manufacturer accounts, supplemented by direct-procurement portals for mid-sized organic buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Low-temperature spray-drying equipment is displacing legacy high-heat systems as the dominant production technology, compressing qualification timelines and reshaping competitive positioning around flavor-retention performance.
For Market Incumbents: Deploy backward integration into apiary supply networks to secure captive organic honey feedstock against climate-driven yield variability and regional pollination stress. Accelerate certification investment in dual USDA-EU organic standards to maintain premium-tier access as EFSA disclosure mandates tighten. Consolidate technical service capabilities around pneumatic system integration to defend against direct-procurement disintermediation by Ingredion and ADM account teams. For New Entrants and Emerging Players: Enter via nutraceuticals channel white space in probiotic gummy and protein blend applications, where batch-level organic certification requirements create qualification barriers for commodity processors. Target German confectionery clusters with specialized honey-derived ingredient formulations that simplify REACH carrier-agent compliance documentation. Pursue equipment-leasing partnerships with Yangtze River Delta spray-drying facilities to bypass capital-intensive facility buildouts. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of regional distributors with pneumatic bulk-handling capabilities and established organic certification documentation systems. Long-term viability favors processors with integrated low-temperature spray-drying technology and verified multi-region apiary supply networks. Monitor EFSA and FDA reinterpretation of "natural" and "pure" claims as the critical inflection signal for forced reformulation cycles and supply chain requalification spending.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Apiary Networks | Captive organic honey supply from Minas Gerais and Pacific Northwest cooperatives insulates against climate-driven yield volatility. |
| Dual USDA-EU Organic Certification Investment | Simultaneous EFSA and FDA compliance documentation unlocks premium pricing in German confectionery and North American natural food channels. |
| Low-Temperature Spray-Drying Capacity Expansion | Flavor-retention performance beyond 12-18 month shelf stability benchmarks displaces legacy high-heat equipment operators. |
| Direct-to-Manufacturer Portal Development | Bypassing wholesale distribution tiers captures margin from mid-sized food processors seeking certified organic supply with batch-level traceability. |
| Nutraceuticals Formulation Partnership | Collaboration with Karnataka and São Paulo supplement manufacturers accelerates penetration of fastest-expanding honey powder consumption channel. |
Methodological Framework
Independent corroboration across ingredient procurement directors, spray-drying equipment engineers, and regulatory affairs specialists at honey powder processors underwrites the qualitative findings in this study. Primary fieldwork encompassed structured interviews with bakery manufacturing executives, confectionery R&D directors, and nutraceutical formulation scientists across Germany, the United States, China, and Brazil. Secondary validation drew from FDA 21 CFR filings, EFSA guidance documents on natural claims, USDA organic certification databases, and SAMR food additive standards. Bottom-up demand modeling from end-use consumption patterns was triangulated against top-down supply capacity assessments from spray-drying facility engineering specifications.
Rate-of-change decomposition across the projection horizon separates volume growth from price-mix effects and currency translation impacts. The analytical framework models segmentation dimensions spanning certification grade, application functionality, and distribution channel access protocols, with additional granularity on particle size specifications and carrier agent composition for industrial bakery versus nutraceutical end uses. CAGRs were derived from fitted trend extrapolation moderated by capacity constraint analysis and regulatory timeline assumptions. Forecast inputs incorporated REACH framework evolution for carrier-agent compliance and spray-drying technology adoption curves for flavor-retention performance thresholds.
Revisions become necessary when EFSA or FDA reinterpretation of "natural" and "pure" claims materializes, when climate-driven apiary yield failures disrupt organic honey feedstock availability, or when maltodextrin feedstock markets experience sustained volatility beyond historical bands. Forecasts reflect documented assumptions regarding certification timeline durations, equipment depreciation schedules, and regional regulatory harmonization progress. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Bouillon Market
Ingredients
South America Clean Ingredients Market
Ingredients
Pepsin Market
Ingredients
Murumuru Butter Market
Ingredients
Vegetable Fats Market
Ingredients
Ingredients Market
Ingredients
Cocoa Maker Market
Ingredients
Global Pregelatinized Starch Market
Ingredients
Soy Hydrolysates Market
Ingredients
Middle East and Africa Fermented Ingredients Market
Ingredients
Corn Oil Cake Market
Ingredients
Flaxseed Derivatives Market
Ingredients
Potato Peel Powder Market
Ingredients
Global Dairy Protein Ingredients Market
Ingredients
Biotech Ingredients Market
Ingredients
Dairy Ingredients Market