
 Airport Ground Support Vehicle Market | 2026-2036
Airport Ground Support Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Airport Ground Support Vehicle Market Analysis
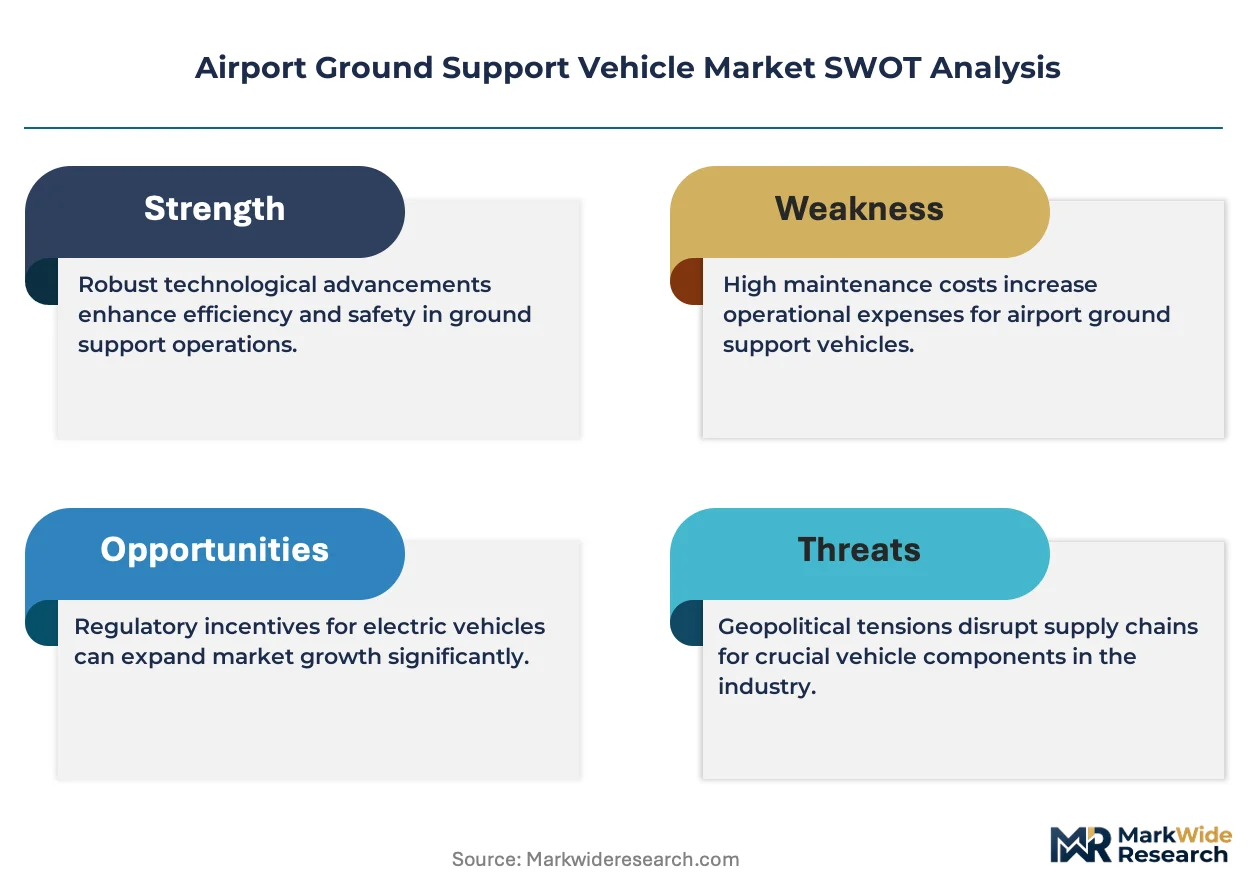
A certified aviation mechanic shortage is unwinding maintenance capacity at regional airports and forcing carriers to outsource ground handling. JBT Corporation leverages its vertical integration into electric drivetrain production to capture electrification contracts at tier-one hubs. TLD Group anchors its position through manufacturing scale across towbarless tractor and cargo loader lines. Weihai Guangtai Airport Equipment competes on cost-engineered diesel-to-electric conversions for emerging market airports.
Airport ground support vehicles are specialized mobile equipment designed to service aircraft during turnaround operations, typically featuring low-profile chassis, aircraft-compatible towing interfaces, and operating speeds below 25 mph to ensure tarmac safety. These vehicles perform critical functions including baggage transport, aircraft pushback, cargo loading, and passenger boarding bridge positioning. Towbarless tractors and electric power sources are gaining structural priority as airports phase out diesel equipment under emissions rules. Belt loaders and cargo loaders retain stable replacement demand from ground handling companies operating narrow-body fleets. Military bases represent a concentrated margin pool where specialized requirements and long procurement cycles limit vendor competition.
The FAA mandates ground support equipment emissions compliance under airport improvement program funding conditions, while the EU Green Deal drives F-Gas Regulation alignment for refrigerated cargo loaders. EPA Tier 4 Final standards and California Air Resources Board zero-emission airport regulations are accelerating electric powertrain adoption in the United States. Stakeholders must weigh battery energy density trade-offs against fast-charging infrastructure investments when specifying fleet replacement schedules.
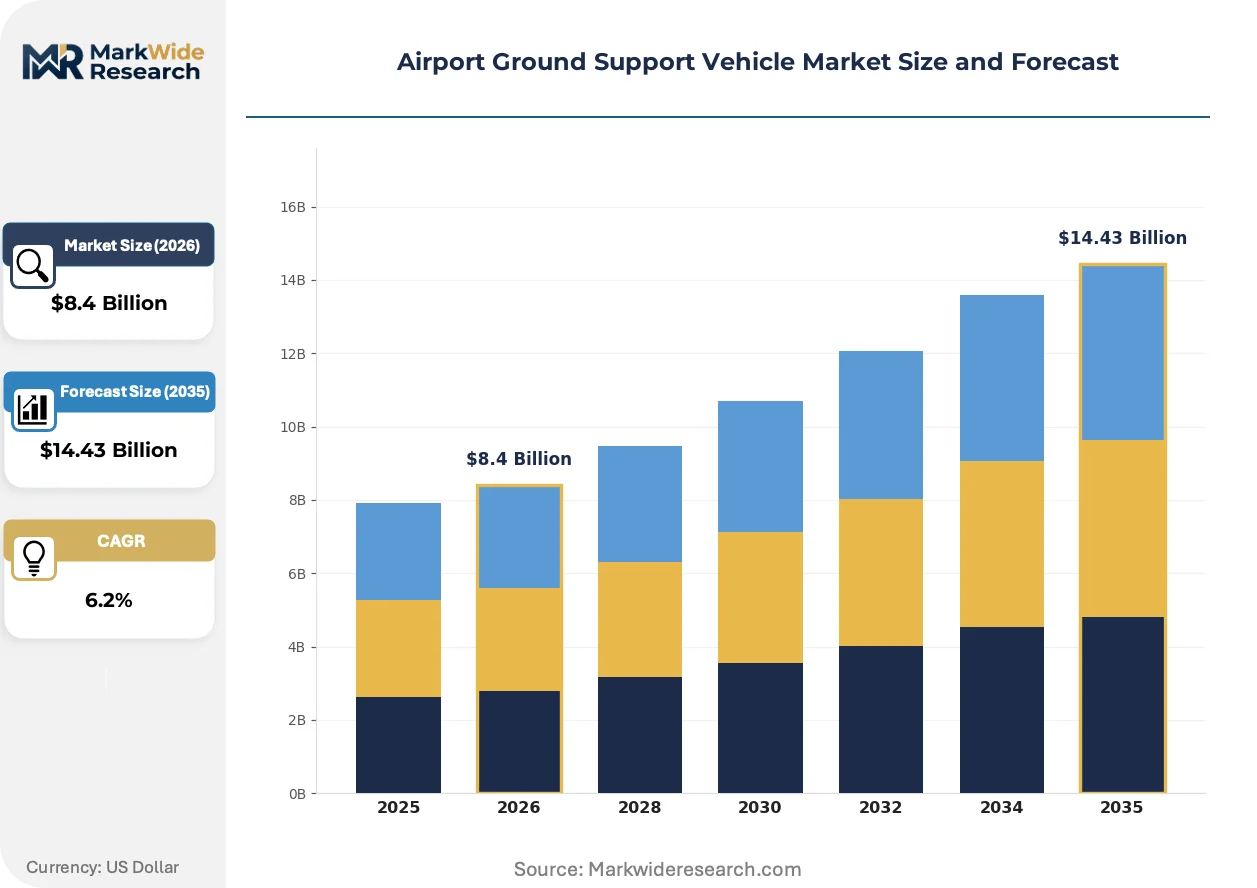
Market Dynamics
Fleet electrification mandates at Frankfurt, Munich, and Amsterdam Schiphol are compressing replacement cycles for diesel ground support equipment, forcing ground handlers to front-load capital expenditure on battery-electric towbarless tractors and belt loaders ahead of regulatory deadlines.
Growth Catalysts
- EU Green Deal F-Gas Regulation:Refrigerated cargo loader specifications now require low-global-warming-potential refrigerants, triggering equipment refresh programs at European cargo hubs.
- Ground handling outsourcing:Airlines divesting in-house operations to specialized handlers like Swissport and dnata concentrates procurement authority with fleet-scale buyers capable of volume electric vehicle commitments.
- Fast-charging infrastructure:350 kW opportunity charging systems at aircraft stands enable continuous-duty electric pushback tractors without battery swapping downtime.
Market Restraints
- Lithium-ion cell supply concentration:Cathode material processing and cell manufacturing cluster in China, exposing European and North American GSE assemblers to geopolitical supply risk and forced technology transfer requirements.
- Battery energy density ceiling:Current lithium iron phosphate packs deliver 160-180 Wh/kg, limiting electric cargo loader duty cycles below four hours on high-lift operations.
- Airport electrical infrastructure lead times:Utility interconnection queues for megawatt-scale charging depots at Heathrow and Charles de Gaulle now extend 18-24 months, delaying fleet commissioning.
Strategic Opportunities
- India airport privatization wave:The Airports Authority of India's asset monetization program creates greenfield GSE procurement at Bangalore, Hyderabad, and Chennai with no legacy diesel fleet to strand.
- Autonomous towing convergence:Lidar-based follow-me systems combined with electric drivetrains enable remote-operated pushback tractors, reducing tarmac personnel exposure and labor cost per turn.
- California CARB zero-emission airport regulations:The 2024 mandate for drayage and GSE electrification at LAX, SFO, and San Diego International creates first-mover pricing power for compliant equipment suppliers.
Industry Challenges
- Certified aviation mechanic shortage:FAA Airframe and Powerplant certificate holders are declining 4% annually, constraining maintenance capacity for both legacy diesel and new electric powertrain fleets at regional airports.
- Battery thermal runaway containment:Tarmac fire suppression systems must be reengineered for lithium-ion failure modes, adding engineering validation cycles and airport fire marshal approval delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airport Ground Support Vehicle Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $14.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Towbarless Tractors, Cargo Loaders, Seat Loaders, Belt Loaders Power Source: Diesel, Electric, Hybrid, Alternative Fuel End User: Airports, Ground Handling Companies, Airlines, Military Bases Application: Baggage Handling, Aircraft Maintenance, Passenger Boarding, Fueling |
| Companies Covered | JBT Corporation, TLD Group, Cavotec SA, Textron GSE, Oshkosh Aerotech, Weihai Guangtai Airport Equipment, Tronair, Mallaghan, MULAG Fahrzeugwerk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airport Ground Support Vehicle Market Emerging Trajectories
Solid-state battery chemistry and autonomous navigation systems are converging to redefine ground support vehicle architecture, compressing the historical trade-off between operational range and equipment payload capacity that has constrained electric adoption.
Solid-state battery packs with lithium-metal anodes are miniaturizing thermal management hardware requirements while doubling volumetric energy density versus conventional lithium-ion. Ground handlers at Singapore Changi and Dubai International are piloting these packs in belt loaders for narrow-body fleets, enabling all-day operation without midday charging interruptions that disrupt gate utilization.
The EU F-Gas Regulation's 2027 phase-down schedule for hydrofluorocarbon refrigerants is mandating CO2-based transcritical refrigeration systems in new cargo loaders. Equipment manufacturers serving Brussels Airport and Leipzig/Halle freight hubs are reengineering insulated compartments and compressor architectures to handle the 70-bar operating pressures, extending development timelines by 8-12 months.
Leasing structures are displacing outright purchase for electric GSE fleets at mid-size European airports. Ground handling companies at Milan Malpensa and Vienna International now contract equipment-as-a-service with charging infrastructure bundled, transferring battery degradation risk and residual value uncertainty to OEM captive finance arms while preserving balance sheet capacity for terminal concessions.
Airport Ground Support Vehicle Market Segmentation
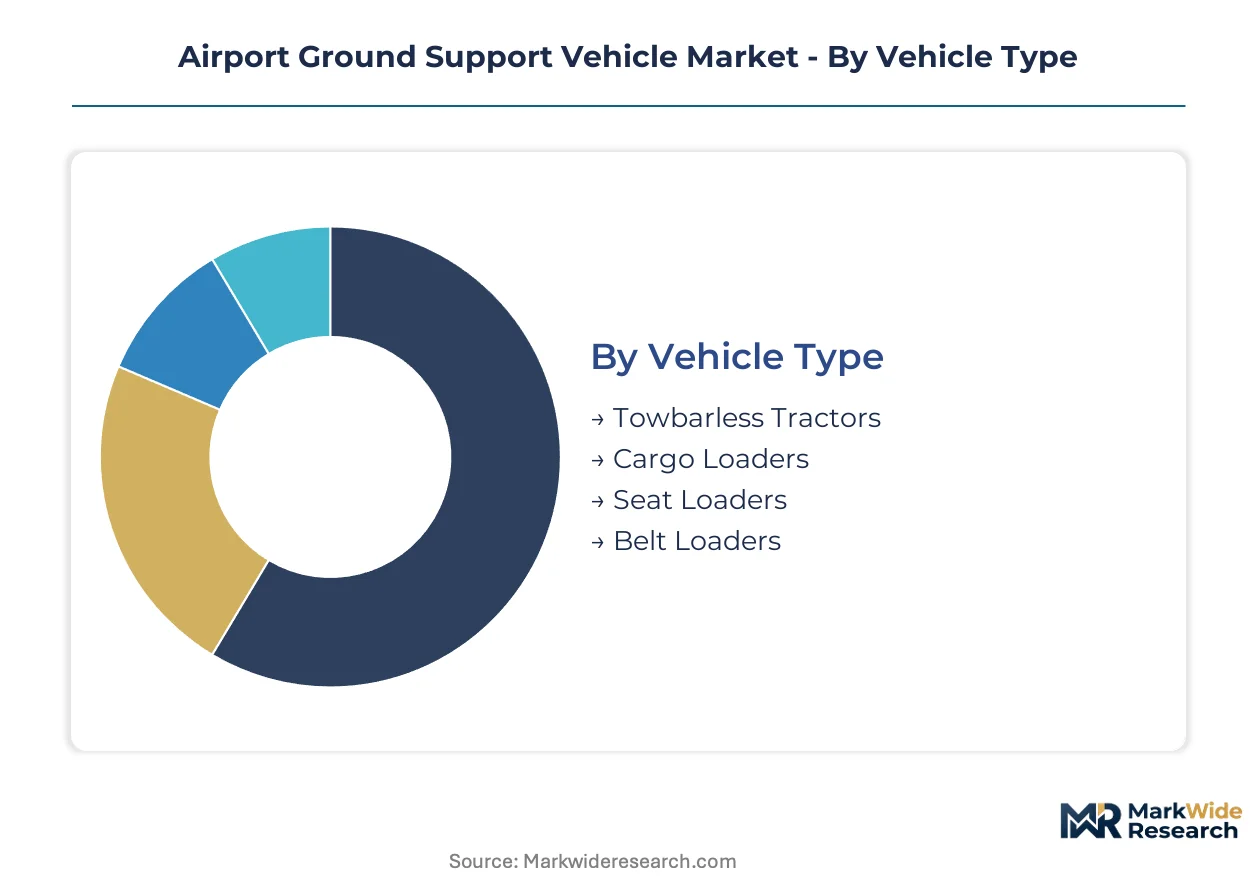
Airport ground support equipment procurement splits across operational function, energy compliance, and customer capital structure. Each segmentation axis carries distinct regulatory triggers and replacement cycle timing that reshape vendor go-to-market priorities.
Vehicle Type:
FAA airworthiness directives and EU ground handling safety mandates differentiate equipment categories through towing interface standards and collision avoidance requirements.
- Towbarless Tractors:Aircraft nose gear clamping systems eliminate towbar attachment time, cutting pushback duration by 40% versus conventional tugs. Frankfurt and Munich airports have standardized on electric variants for narrow-body fleets under fleet electrification mandates. Established volume favors towbarless tractors; emerging adoption favors seat loaders.
- Cargo Loaders:Scissor-lift platforms with 20-ton payload capacity service wide-body lower deck and main deck freight. Brussels Airport and Leipzig/Halle freight hubs drive demand for CO2-refrigerated variants under F-Gas Regulation compliance deadlines.
- Seat Loaders:Articulating boom platforms position passenger seats through cargo doors during cabin reconfiguration. Narrow-body fleet densification at low-cost carriers sustains replacement demand.
- Belt Loaders:Extendable conveyor systems transfer luggage to aircraft bulk holds. Singapore Changi pilots solid-state battery packs for continuous-duty narrow-body operations.
Operational criticality concentrates procurement authority on towbarless tractors; narrow-body fleet expansion sustains belt loader replacement cycles.
Power Source:
California CARB zero-emission airport regulations and EU Green Deal timelines compress diesel equipment residual value, accelerating capital redeployment toward electric powertrains.
- Electric:Lithium iron phosphate battery packs with 160-180 Wh/kg density power towbarless tractors and belt loaders at LAX, SFO, and San Diego International under 2024 mandates. Fast-charging infrastructure investments of 350 kW per aircraft stand enable continuous-duty deployment.
- Diesel:EPA Tier 4 Final compliant engines retain installed base at military bases and emerging market airports with limited grid interconnection. Replacement cycles extend as electrification capital constraints bite.
- Hybrid:Diesel-electric architectures bridge duty cycle gaps for cargo loaders requiring sustained high-lift operations beyond four-hour battery limits.
- Alternative Fuel:Hydrogen fuel cell prototypes undergo tarmac validation at Amsterdam Schiphol for heavy-lift applications beyond current battery economics.
Regulatory compliance investment favors electric powertrains; operational range constraints sustain hybrid adoption for cargo loader segments.
End User:
Ground handling outsourcing concentrates fleet-scale procurement authority with specialized operators capable of volume electric vehicle commitments and bundled charging infrastructure financing.
- Ground Handling Companies:Swissport and dnata aggregate equipment procurement across multiple airline contracts, enabling standardized electric fleet specifications at tier-one hubs. Equipment-as-a-service leasing structures transfer battery degradation risk to OEM captive finance arms.
- Airports:Frankfurt, Munich, and Amsterdam Schiphol operate direct procurement for common-use gate equipment, mandating compatibility standards across handling tenants.
- Airlines:Legacy carriers retaining in-house ground operations at fortress hubs specify specialized configurations matching narrow-body fleet profiles.
- Military Bases:Specialized requirements including air transportability and electromagnetic interference hardening limit vendor competition, sustaining margin premiums on qualified equipment.
Procurement scale concentration favors ground handling companies; specification autonomy favors airline direct procurement at fortress hubs.
Application:
Turnaround time pressure and passenger experience metrics differentiate equipment deployment across ramp functions, with baggage handling commanding highest fleet utilization rates.
- Baggage Handling:Belt loaders and baggage tractors operate at 85% fleet utilization during peak banks, driving replacement demand from ground handlers operating narrow-body fleets at slot-constrained airports.
- Aircraft Maintenance:Maintenance stands and engine change dollies require airworthiness certification extending procurement cycles. Certified aviation mechanic shortages constrain maintenance capacity deployment at regional airports.
- Passenger Boarding:Ambulift and passenger boarding bridge positioning equipment serves reduced mobility and remote stand operations.
- Fueling:Hydrant dispensers and refueler trucks operate under airport fuel farm safety protocols distinct from aircraft servicing equipment standards.
Utilization intensity favors baggage handling equipment; regulatory certification complexity favors maintenance application specialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FAA anchors regulatory momentum in the United States, where airport improvement program funding conditions now mandate ground support equipment emissions compliance. Frankfurt, Munich, and Amsterdam Schiphol compress replacement cycles for diesel equipment under parallel EU Green Deal timelines.
United States
California CARB zero-emission airport regulations mandate electrification at LAX, SFO, and San Diego International by 2024. The EPA Tier 4 Final standards accelerate electric powertrain adoption nationwide. Ground handlers at Dallas-Fort Worth and Atlanta Hartsfield-Jackson front-load capital expenditure on battery-electric towbarless tractors ahead of regulatory deadlines.
Germany
Frankfurt and Munich airports deploy large-scale electric GSE fleets under fleet electrification mandates. The EU Green Deal drives F-Gas Regulation alignment for refrigerated cargo loaders at Leipzig/Halle freight hubs. Equipment manufacturers reengineer insulated compartments for CO2-based transcritical refrigeration systems under 2027 phase-down schedules.
Netherlands
Amsterdam Schiphol mandates compatibility standards across handling tenants for common-use gate equipment. The EU Green Deal compresses diesel equipment residual value. Hydrogen fuel cell prototypes undergo tarmac validation for heavy-lift applications beyond current battery economics.
India
The Airports Authority of India's asset monetization program creates greenfield GSE procurement at Bangalore, Hyderabad, and Chennai. No legacy diesel fleet exists to strand at privatized airports. Weihai Guangtai Airport Equipment competes on cost-engineered diesel-to-electric conversions for emerging market deployment.
Singapore
Singapore Changi pilots solid-state battery packs in belt loaders for narrow-body fleets. 350 kW opportunity charging systems at aircraft stands enable continuous-duty electric pushback tractors. All-day operation proceeds without midday charging interruptions that disrupt gate utilization.
Airport Ground Support Vehicle Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier that competes on manufacturing scale and regional cost engineering. The market structure concentrates procurement authority with fleet-scale buyers capable of volume electric vehicle commitments. Two strategic archetypes dominate: vertically integrated drivetrain producers capturing electrification contracts, and scale manufacturers anchoring position across towbarless tractor and cargo loader lines. Competitive moves center on backward integration into battery supply and captive financing arms bundling charging infrastructure with equipment-as-a-service leases.
Within the integrated tier, JBT Corporation and TLD Group occupy positions reflecting upstream control over electric drivetrain production and manufacturing scale respectively. Weihai Guangtai Airport Equipment exemplifies the cost-engineering archetype serving emerging market conversions. These three entities represent the competitive spectrum from premium electrification specifications to diesel-to-electric retrofit economics.
| Leading Market Players |
|---|
| JBT Corporation |
| TLD Group |
| Cavotec SA |
| Textron GSE |
| Oshkosh Aerotech |
| Weihai Guangtai Airport Equipment |
| Tronair |
| Mallaghan |
| MULAG Fahrzeugwerk |
| Others |
Supply Flow & Price Mechanics
EU Green Deal emissions compliance gates both supplier qualification and price differentiation simultaneously, as ground support equipment vendors must certify electric powertrains and fast-charging compatibility before bidding on Frankfurt or Munich airport tenders, while uncertified competitors face exclusion from premium-tier procurement.
Pricing Analysis
European airports command 15-25% price premiums over Indian greenfield deployments for identical electric towbarless tractor specifications. Three-tier pricing structure across premium, standard, and economy levels separates OEM captive-finance bundled leases from bare-equipment transactions and emerging-market diesel conversions. Pricing pressure stems from Chinese cost-engineered entrants undercutting European manufacturers on belt loader contracts. Ground handling companies show highest price sensitivity due to fleet-scale volume commitments, while military bases accept premium pricing for electromagnetic interference hardening.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes inflate inbound logistics costs for lithium-ion cell deliveries to TLD Group and JBT Corporation assembly plants. Cathode material processing clusters in China, South Korea, and Japan; European and North American GSE assemblers draw from this concentrated base. Single-source vulnerability runs through Chinese lithium iron phosphate cell suppliers. Distribution runs through OEM direct sales for tier-one hub electrification contracts, with regional distributors serving emerging market retrofit demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Airport ground support vehicle electrification sits in early-cycle expansion, with California CARB mandates and EU Green Deal timelines forcing replacement waves ahead of natural equipment end-of-life.
For Market Incumbents: Fortify backward integration into battery pack assembly to offset Chinese cell supply risk and preserve margin on electric towbarless tractor contracts. Lock long-term cathode material offtake agreements before geopolitical restrictions harden. Certify thermal runaway containment systems ahead of airport fire marshal deadline compression. For New Entrants and Emerging Players: Lead with diesel-to-electric conversion kits for India's privatized airports, where no legacy fleet stranding risk exists and ground handlers seek capital-light electrification paths. Target Bangalore, Hyderabad, and Chennai greenfield procurement with equipment-as-a-service structures that bundle charging infrastructure and transfer battery degradation risk. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electric GSE manufacturing as fast-charging infrastructure deployment and solid-state battery R&D absorb cash. Five-to-ten-year viability favors vendors with captive finance arms capable of underwriting equipment-as-a-service leases. Monitor utility interconnection queue lengths at Heathrow and Charles de Gaulle as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Assembly | Reduces exposure to Chinese cell supply concentration for European GSE manufacturers. |
| Equipment-as-a-Service Launch | Transfers residual value risk to OEM finance arms at Milan Malpensa and Vienna International. |
| Fast-Charging Infrastructure Partnership | Enables 350 kW opportunity charging deployment at LAX, SFO, and San Diego International gates. |
| Solid-State Battery Pilot Program | Doubles volumetric energy density for Singapore Changi belt loader continuous-duty operations. |
| CO2 Refrigeration System Certification | Secures Brussels Airport and Leipzig/Halle cargo loader contracts under F-Gas Regulation deadlines. |
Methodological Framework
Cross-validation between primary interviews with ground handling fleet managers, airport procurement officers, and electric drivetrain engineers and secondary validation through FAA airworthiness directives, EU Green Deal policy documents, and CARB regulatory filings anchors the qualitative findings. Bottom-up equipment shipment tallies from tier-one hub deployments triangulate against top-down airport capital expenditure disclosures.
Sensitivity analysis on battery energy density assumptions and utility interconnection timelines frames the forecast uncertainty. Segmentation dimensions span vehicle type, power source architecture, end-user procurement structure, and regional regulatory cluster. CAGRs derive from replacement cycle compression under emissions mandates and fleet electrification penetration curves. Industry-specific inputs include certified aviation mechanic availability constraints and lithium-ion cell supply lead times.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement or accelerated FAA funding condition expansion would require recalibration. Forecasts reflect documented assumptions on battery cost decline trajectories and airport infrastructure investment schedules. Practitioners should keep alternative scenarios live as geopolitical supply restrictions and solid-state battery commercialization timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Global Automotive Carbon Fiber Composites Market
Vehicle Components
Trailer Brake Controllers Market
Vehicle Components
Locomotive Drive Shaft Market
Vehicle Components
Argentina Automotive Carbon Fiber Composites Market
Vehicle Components
Collapsible Jerry Can Market
Vehicle Components
Passenger Car Sensors Market
Vehicle Components
Electric Wheelchair Market
Vehicle Components
2 Wheeler Fuel Tank Market
Vehicle Components
Motorcycle Connectors Market
Vehicle Components
Russia Automotive Glass Fiber Composites Market
Vehicle Components
Mechanical Control Cables Market
Vehicle Components
High Precision Heavy Load Bearings Market
Vehicle Components
Canada Automotive Carbon Fiber Composites Market
Vehicle Components
Automotive and Transportation Connector Market
Vehicle Components
Towing Ropes Market
Vehicle Components
Europe Trailer Axle Market