
 Passenger Car Sensors Market | 2026-2036
Passenger Car Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Passenger Car Sensors Market Intelligence
Demand from automotive OEMs seeking fully integrated systems is rotating toward direct engagement with specialized semiconductor manufacturers. This shift alters the traditional value chain where Tier-1 suppliers held primary control. Robert Bosch GmbH leverages its system integration expertise to maintain its position. Continental AG competes by offering comprehensive ADAS solutions, while Infineon Technologies AG specializes in advanced sensor chipsets, supplying both OEMs and Tier-1 integrators.
Passenger car sensors are electromechanical devices that convert physical phenomena into electrical signals for vehicle control units. Many are built using MEMS technology, enabling miniaturization and cost reduction for mass-market applications. Their primary purpose is to provide real-time data for safety, performance, and comfort systems. While ultrasonic sensors remain standard for parking assistance, LiDAR and high-resolution radar sensors represent the fastest-growing types, essential for advanced collision avoidance systems.
Safety mandates from bodies like the US National Highway Traffic Safety Administration (NHTSA) and compliance with the EU's General Safety Regulation directly drive sensor content per vehicle. In China, GB standards for vehicle safety and emissions also dictate sensor specifications and market access. Consequently, navigating the complex landscape of sensor fusion and software integration becomes the critical challenge for all participants in the value chain.
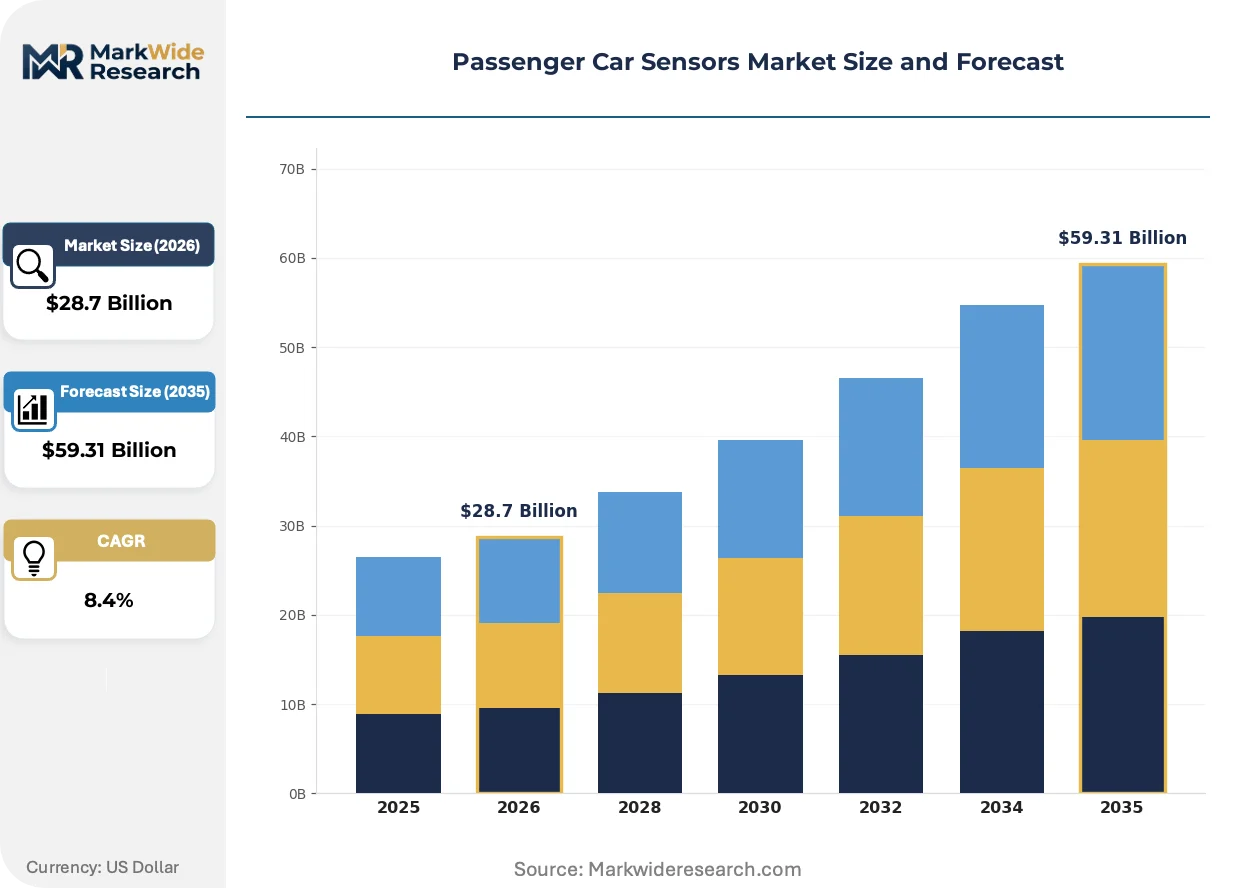
Market Dynamics
The convergence of stringent safety regulations and the architectural shift toward software-defined vehicles represents the central force shaping the passenger car sensor market. This dynamic compels a higher density of sensors per vehicle for data acquisition and processing.
Growth Catalysts
- Safety Mandates:The European Union's General Safety Regulation (GSR) directly requires features like intelligent speed assistance and advanced emergency braking, which depend on camera, radar, and ultrasonic sensors for their core functionality.
- ADAS Technology:The ongoing development of LiDAR and high-resolution radar sensors provides the detailed environmental perception necessary for Level 2+ and Level 3 autonomous driving systems, creating demand from OEMs developing these features.
- Chinese Market Demand:China's national strategy for intelligent connected vehicles (ICVs), supported by its GB standards, accelerates the adoption of advanced sensor suites as automakers compete on technological capabilities.
Market Restraints
- Software Complexity:The high cost and technical difficulty of developing and validating sensor fusion software, which combines data from multiple sensor types into a single world model, acts as a significant barrier.
- Semiconductor Bottlenecks:Reliance on a concentrated number of specialized semiconductor foundries for manufacturing advanced sensor chips creates supply chain vulnerabilities and potential production delays for the entire automotive industry.
- Validation Cycles:The extensive time and resources required for testing and validating safety-critical sensors to meet stringent automotive standards like ISO 26262 can slow the introduction of new technologies.
Strategic Opportunities
- In-Cabin Sensing:The development of sensors for driver monitoring systems (DMS) and occupant monitoring systems (OMS) opens a new application area focused on interior safety, comfort, and personalization.
- Sensor Data Monetization:The aggregation of anonymized data from vehicle sensor fleets presents an opportunity to create new revenue streams through services like real-time traffic mapping and road condition monitoring.
- Emerging Market Regulations:Anticipated safety mandates in markets such as India and Brazil, modeled after European and American standards, will create new volume demand for basic safety sensors like ABS and stability control sensors.
Industry Challenges
- Integration and Calibration:Ensuring that sensors sourced from different suppliers work together seamlessly within a vehicle's electronic architecture is a major engineering challenge, requiring complex calibration and software integration efforts.
- Cybersecurity Threats:As sensors become more connected and integral to vehicle control, protecting them and the data they generate from remote hacking and manipulation becomes a critical and ongoing operational challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Passenger Car Sensors Market |
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $59.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sensor Type: LiDAR, Ultrasonic, Radar, Infrared, Capacitive, Piezoelectric Technology: MEMS, CMOS, Optical, Magnetic, Electrochemical, Thermal Application: Collision Avoidance, Parking Assistance, Driver Monitoring, Blind Spot Detection, Emission Control, Cabin Environment Control End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Robert Bosch GmbH, Continental AG, DENSO Corporation, Infineon Technologies AG, NXP Semiconductors, STMicroelectronics, Allegro MicroSystems, ZF Friedrichshafen AG, TE Connectivity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Passenger Car Sensors Market Strategic Shifts & Innovations
Sensor data is evolving from a simple input for isolated functions into a central asset for the entire vehicle operating system. This transformation prioritizes software integration and high-speed data processing, defining the next generation of automotive electronics.
MEMS technology provides the foundation for inertial sensors like accelerometers and gyroscopes used in vehicle dynamics control. Automakers are adopting these components across all vehicle platforms due to their low cost and high reliability. Continuous improvement in semiconductor fabrication is miniaturizing the physical die size, enabling the integration of multiple sensing axes into a single, compact package.
The US National Highway Traffic Safety Administration (NHTSA) is advancing rulemaking for mandatory Automatic Emergency Braking (AEB) systems. This regulation directly compels the standard fitment of forward-facing camera or radar sensors capable of detecting pedestrians and other vehicles. Economy and mid-range vehicle segments are most impacted, as they must now incorporate ADAS sensor hardware that was previously optional or limited to premium trims.
A notable demand-side shift involves automotive OEMs building direct relationships with semiconductor designers for critical sensor chipsets. This model bypasses the traditional Tier-1 supplier for strategic sourcing, giving the OEM greater control over the technology roadmap and software stack. The trend is most pronounced in China, where electric vehicle manufacturers prioritize development speed and deep system integration.
Passenger Car Sensors Market Segmentation
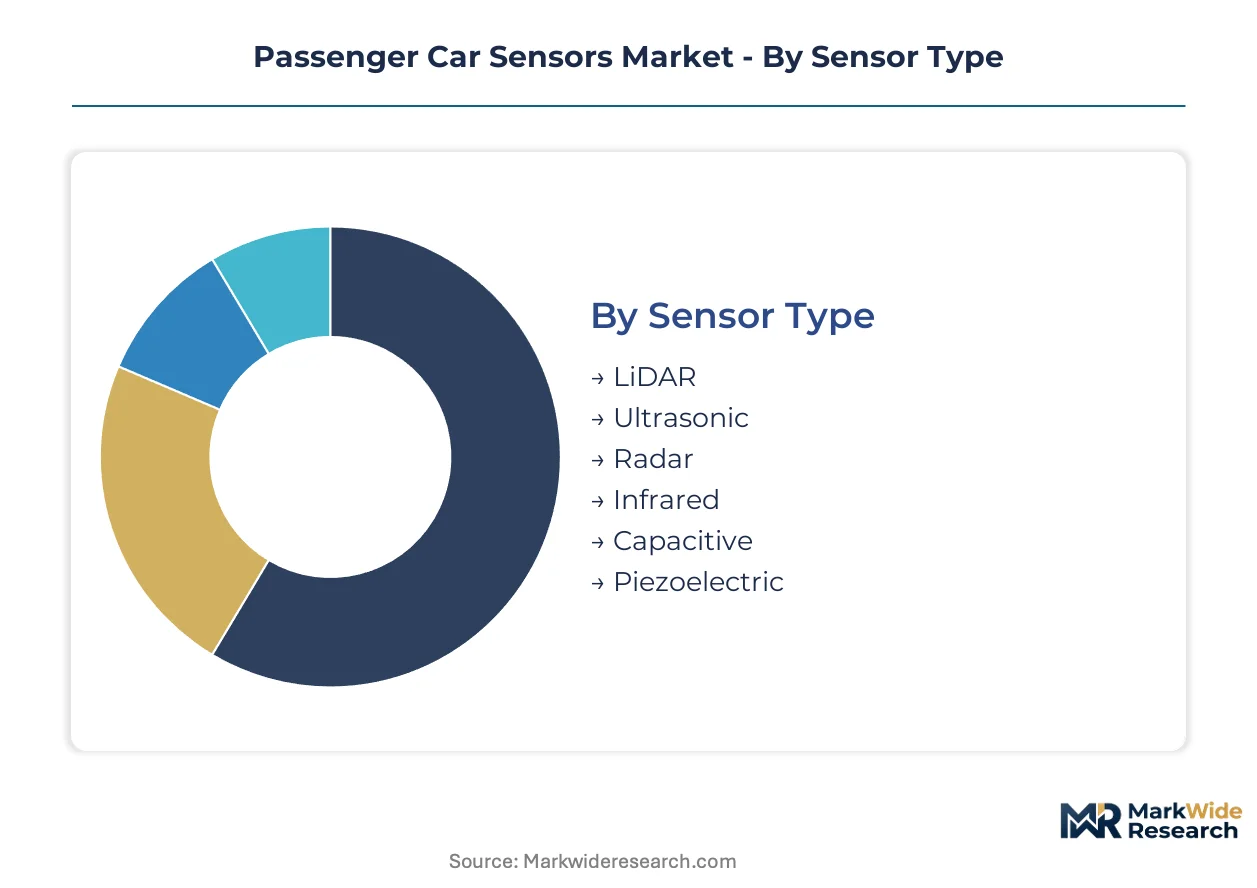
Segmentation analysis provides a granular understanding of the passenger car sensors market, highlighting the diverse components, technologies, applications, and end-users driving its evolution. This detailed view helps identify specific growth pockets, competitive landscapes, and strategic opportunities across the value chain. Understanding these segments is crucial for participants aiming to align product development and market strategies with emerging automotive trends.
Sensor Type:
The passenger car sensor market faces significant substitution pressure across various sensor types, as technological advancements offer alternative solutions for critical functions.
- LiDAR:These sensors generate detailed 3D point clouds of the vehicle's surroundings, offering superior spatial resolution for autonomous driving. Demand is concentrating in premium and Level 3+ autonomous vehicles, driven by the need for robust environmental perception in complex scenarios.
- Radar:Radar sensors emit radio waves to detect objects, measure distance, and velocity, operating reliably in adverse weather conditions. Their integration into advanced emergency braking and adaptive cruise control systems is mandated by safety regulations in Europe and the US.
- Ultrasonic:These sensors emit high-frequency sound waves to detect nearby obstacles, primarily used for parking assistance and low-speed maneuvering.
- Infrared:Infrared sensors detect heat signatures and are employed for night vision systems and in-cabin occupant detection.
- Capacitive:Capacitive sensors measure changes in electrical fields, finding use in occupant detection and touch-sensitive controls within the cabin.
- Piezoelectric:Piezoelectric sensors convert mechanical stress into electrical signals, commonly used in knock sensors and airbag deployment systems.
Ultrasonic sensors retain volume leadership; LiDAR sensors hold the steepest expansion curve.
Technology:
Technological advancements differentiate sensor capabilities, enabling specific applications from basic safety to advanced autonomy.
- MEMS:Micro-Electro-Mechanical Systems technology integrates mechanical and electrical components on a microchip, enabling miniaturization and cost-effective production of accelerometers and gyroscopes. Automakers are adopting MEMS across all vehicle platforms, enhancing vehicle dynamics control and safety.
- CMOS:Complementary Metal-Oxide-Semiconductor technology forms the basis for image sensors used in cameras, providing high-resolution visual data for ADAS and autonomous driving systems. Its demand is concentrating in forward-facing cameras for mandatory AEB systems across all vehicle segments.
- Optical:Optical technologies include LiDAR and camera systems, providing detailed environmental perception through light-based sensing principles.
- Magnetic:Magnetic sensors detect magnetic fields and are employed in wheel speed sensing for ABS and electronic stability control systems.
- Electrochemical:Electrochemical sensors measure chemical reactions, primarily used for exhaust gas monitoring and emission control systems.
- Thermal:Thermal sensors detect temperature changes, finding applications in engine management, climate control, and in-cabin occupant monitoring.
MEMS technology underpins a broad range of established safety functions; CMOS technology is expanding most quickly through camera-based ADAS.
Application:
The diverse applications of passenger car sensors directly influence vehicle safety, performance, and driver comfort.
- Collision Avoidance:These systems utilize radar, camera, and LiDAR sensors to detect potential impacts and initiate braking or steering interventions, directly mandated by safety regulations like the EU GSR. Demand is concentrating across all vehicle segments as AEB becomes standard fitment in key markets like the US.
- Driver Monitoring:Driver monitoring systems use cameras and infrared sensors to track driver attention, fatigue, and impairment, enhancing interior safety and supporting Level 2+ autonomous functions. This application represents a significant growth opportunity in new vehicle models in Europe and China.
- Parking Assistance:Parking assistance systems rely on ultrasonic sensors and cameras to aid drivers in maneuvering into parking spaces.
- Blind Spot Detection:Blind spot detection systems use radar sensors to alert drivers of vehicles in adjacent lanes, enhancing highway safety.
- Emission Control:Emission control applications utilize various sensors, including electrochemical, to monitor and regulate exhaust gases for regulatory compliance.
- Cabin Environment Control:Cabin environment control sensors manage temperature, humidity, and air quality, contributing to passenger comfort.
Collision Avoidance applications drive the largest sensor volumes; Driver Monitoring is gaining share fastest due to new safety mandates.
End User:
The distribution of passenger car sensors varies across different end-user segments, reflecting distinct procurement strategies and integration needs.
- OEMs:Original Equipment Manufacturers integrate sensors directly into their vehicle platforms, increasingly seeking direct relationships with semiconductor designers for strategic control over technology roadmaps. This shift is particularly pronounced among electric vehicle manufacturers in China.
- Tier-1 Suppliers:Tier-1 suppliers traditionally procure sensor components and integrate them into larger modules or systems for OEMs, leveraging their system integration expertise. Companies like Continental AG offer comprehensive ADAS solutions to maintain their market position.
- Aftermarket Providers:Aftermarket providers offer sensor-based solutions for vehicle upgrades or repairs, catering to existing vehicle fleets.
- Vehicle Assemblers:Vehicle assemblers integrate pre-assembled sensor modules and systems into the final vehicle during the manufacturing process.
OEMs are increasingly driving sensor technology specifications; Tier-1 Suppliers remain critical for complex system integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's robust automotive manufacturing base exports sensor-equipped vehicles globally, particularly to emerging markets. This export activity drives significant demand for advanced passenger car sensors within its domestic supply chain. European and North American markets also contribute substantially, focusing on high-value safety and autonomous driving features.
China
China's national strategy for intelligent connected vehicles (ICVs) creates strong demand for advanced sensor suites. The country's GB standards for vehicle safety and emissions strictly dictate sensor specifications and market access. Automotive manufacturing hubs in the Yangtze River Delta and Pearl River Delta drive significant sensor integration into new vehicle models.
United States
Mandatory Automatic Emergency Braking (AEB) systems accelerate sensor fitment in US vehicles. The US National Highway Traffic Safety Administration (NHTSA) advances rulemaking for AEB, compelling standard fitment of camera and radar sensors. Detroit's automotive industry and Silicon Valley's tech companies collaborate on advanced ADAS and autonomous driving systems.
Germany
Advanced research and development in automotive technology propels sensor innovation in Germany. The European Union's General Safety Regulation (GSR) mandates advanced safety features, directly impacting German vehicle production. Major automotive clusters in Bavaria and Baden-Württemberg lead sensor integration for premium and luxury car segments.
Japan
Technological leadership in automotive electronics supports high sensor content per vehicle in Japan. Japan's stringent vehicle safety standards encourage the adoption of advanced driver assistance systems. Automotive manufacturing centers in Aichi Prefecture and Kanagawa Prefecture focus on developing next-generation sensor technologies for global deployment.
India
Anticipated safety mandates create new volume demand for basic safety sensors in India. The country's evolving automotive regulations will likely mirror European and American standards for passive and active safety. Chennai and Pune, key automotive production hubs, are preparing for increased sensor fitment in locally manufactured vehicles.
Passenger Car Sensors Market Key Industry Players
Listed leaders compete with private specialists across the passenger car sensor value chain, particularly in semiconductor manufacturing and system integration. The market exhibits a tiered structure, with semiconductor manufacturers, Tier-1 suppliers, and automotive OEMs each vying for control. Strategic archetypes include specialized chip designers, comprehensive ADAS solution providers, and vehicle manufacturers seeking direct sourcing. Technology licensing and strategic partnerships represent dominant competitive moves among these participants.
Within the competitive landscape, Robert Bosch GmbH exemplifies the archetype of a diversified technology and service provider, leveraging its deep automotive systems integration capabilities. Continental AG occupies a strategic position as a comprehensive ADAS solution provider, delivering integrated sensor modules and software to global vehicle manufacturers. Infineon Technologies AG represents a specialized semiconductor manufacturer, anchoring the supply of advanced sensor chipsets that are critical for both direct OEM relationships and Tier-1 integrators. These companies collectively illustrate the shift towards more integrated and software-defined sensor solutions across the industry.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| DENSO Corporation |
| Infineon Technologies AG |
| NXP Semiconductors |
| STMicroelectronics |
| Allegro MicroSystems |
| ZF Friedrichshafen AG |
| TE Connectivity |
| Others |
Cost & Logistics Intelligence
LiDAR sensor substitution for traditional radar in advanced ADAS applications simultaneously reshapes the supply geography for specialized optical components and introduces new pricing tiers for environmental perception systems.
Pricing Analysis
Next-generation LiDAR and high-resolution radar sensors command premium pricing, reflecting their advanced capabilities compared to prior-generation ultrasonic or basic radar units. The dominant pricing structure remains per-unit transactional, often negotiated through long-term contracts with OEMs. Price differentiation stems from performance tier, such as sensor resolution and range, and adherence to stringent automotive safety certifications like ISO 26262. Pricing softness in established sensor types is intensifying due to MEMS miniaturization and mass production economies. Economy and mid-range vehicle segments exhibit the highest price sensitivity, while premium and luxury segments prioritize performance over cost.
Supply Chain Analysis
Just-in-time inventory strategies, common in automotive manufacturing, face challenges from the specialized nature of sensor components. Geographic supply concentration for advanced sensor chipsets centers on Taiwan, South Korea, and China, home to leading semiconductor foundries. The supply chain draws from specialized semiconductor wafers and optical components, creating dependencies on a concentrated vendor base. Semiconductor bottlenecks represent a significant structural risk, leading to potential production delays across the automotive industry. Distribution primarily runs through direct OEM relationships for strategic components and Tier-1 integrators for comprehensive module solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The passenger car sensor market presents a fragmentation opportunity, with the demand-side shift toward in-cabin sensing creating distinct new niches.
For Market Incumbents:Shield existing market share by deepening software integration expertise, particularly in sensor fusion algorithms. Secure long-term supply agreements for critical semiconductor components to mitigate supply chain vulnerabilities. Invest in next-generation LiDAR and radar technologies to counter the threat of specialized startups gaining traction with direct OEM sourcing. Focus R&D on robust validation processes to meet evolving safety mandates like the EU GSR.
For New Entrants and Emerging Players:Anchor in specialized application areas such as in-cabin sensing for driver and occupant monitoring systems. Target emerging markets like India and Brazil, which are preparing for new safety mandates, creating demand for basic safety sensors. Offer full-stack software-defined sensor solutions that simplify integration for OEMs. Develop highly integrated sensor modules that reduce engineering complexity for vehicle manufacturers.
For Investors and Strategic Acquirers:Secondary-cycle assets sit with specialized sensor technology firms and software developers in the current market. The long-term viability of the sector remains strong, driven by the irreversible trend toward autonomous driving and enhanced safety features. Identify acquisition targets with proprietary sensor fusion software or unique LiDAR/radar intellectual property. The acceleration of Level 3+ autonomous vehicle deployments serves as a critical signal to watch for inflection points.
| Strategic Initiative | Industry Significance |
|---|---|
| Deepen Sensor Fusion Software Expertise | Enhances system performance and differentiation as sensor integration complexity rises for OEMs. |
| Secure Long-Term Semiconductor Supply | Mitigates production risks and ensures component availability amid global supply chain volatility. |
| Invest in In-Cabin Sensing Technologies | Captures new revenue streams driven by evolving safety regulations and personalization trends. |
| Form Strategic Partnerships with OEMs | Ensures early design-in wins and alignment with future vehicle architecture development. |
| Expand Manufacturing Footprint in Asia | Leverages regional production advantages and addresses demand from key automotive hubs. |
Research Approach
A standing panel of automotive OEM engineers, Tier-1 procurement leads, semiconductor R&D specialists, and regulatory affairs experts provided ongoing calibration for market assumptions. Primary interviews were conducted with industry stakeholders, validated against extensive secondary research from vehicle production databases, safety regulation documents, semiconductor industry reports, and patent filings. The analysis employed both bottom-up and top-down triangulation to ensure data consistency and accuracy.
Outputs were validated for consistency against external benchmarks and industry association reports across the analysis window. The analytical framework modeled key segmentation dimensions, including sensor type, technology, application, end-user, vehicle class, and geographic region. Compound annual growth rates were derived from historical data extrapolation, factoring in future demand projections based on regulatory roadmaps. Safety mandate implementation schedules and ADAS feature roadmap adoption rates served as critical forecast inputs.
Decision-makers should treat outputs as directional under base assumptions of regulatory stability and continued semiconductor supply chain health; material deviation would warrant model refresh. Key risk factors include geopolitical disruptions and faster-than-anticipated technological obsolescence. Revision becomes warranted when significant shifts in autonomous driving adoption curves cross established thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Automotive Exhaust Gas Sensor Market
Vehicle Components
Advanced Driver Assistance System (ADAS) Sensor Market
Vehicle Components
Sideloaders Market
Vehicle Components
Portable Truck Access System Market
Vehicle Components
Global Car Accessories Market
Vehicle Components
Brake Hoses Market
Vehicle Components
North America Forklift Rental Market
Vehicle Components
Autonomous Trains Components Market
Vehicle Components
Global Automotive EGR Valves Market
Vehicle Components
Grille Guard Market
Vehicle Components
Bicycle Chain Device Market
Vehicle Components
Trailer Landing Gear Market
Vehicle Components
Towing Ropes Market
Vehicle Components
RV Battery Market
Vehicle Components
LAMEA Vehicle Exhaust Hose Market
Vehicle Components
CV Brake Controls Market